
 Semiconductor Wastewater Treatment Market | 2026-2036
Semiconductor Wastewater Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Wastewater Treatment Market Insights
Multi-source equipment procurement is restructuring how semiconductor fabs secure wastewater treatment capacity across their manufacturing networks. Veolia Water Technologies & Solutions SA leverages its integrated service portfolio to anchor long-term contracts with major foundry operators. Siemens competes through digital twin and automation platforms that optimize chemical dosing in real-time process control. SUEZ SA differentiates via advanced oxidation and membrane bioreactor combinations tailored to high-purity water recovery.
Semiconductor wastewater treatment encompasses physical, chemical, and biological processes engineered to remove heavy metals, fluorides, organic solvents, and nanoparticles from effluent streams generated during wafer fabrication, with typical systems achieving parts-per-billion contaminant removal to meet discharge or reuse standards. The primary industrial purpose centers on regulatory compliance and water recycling to sustain fab operations in water-stressed manufacturing locations. Membrane filtration leads technology adoption for ultrapure water pretreatment and final polishing stages, while zero liquid discharge commands premium system valuations due to its complete water recovery and crystallized waste output. Fabrication facilities represent the dominant end-user segment by installed base, though testing labs are expanding treatment footprints as advanced packaging processes generate more complex effluent chemistries.
EPA discharge standards under the Clean Water Act, REACH chemical restrictions administered by ECHA, and Taiwan's Industrial Park Sewerage Effluent Standards collectively determine treatment intensity and technology selection for semiconductor manufacturers operating across multiple jurisdictions. These frameworks mandate continuous monitoring of fluoride, copper, and total dissolved solids concentrations, directly driving demand for automated analytical instrumentation from suppliers like Horiba. Stakeholders must evaluate whether to build captive treatment expertise or rely on outsourced system integration and maintenance contracts as effluent complexity escalates with each process node advancement.
Market Dynamics
Zero liquid discharge mandates are compressing technology adoption timelines across advanced logic fabs, forcing simultaneous upgrades of precipitation, membrane, and crystallization stages within single capital cycles.
Growth Catalysts
- EPA Clean Water Act enforcement:Stricter fluoride and copper discharge limits in the United States are compelling fabs to replace conventional chemical precipitation with membrane-based treatment trains.
- Process node advancement:Each lithography shrink generates more complex effluent chemistries containing novel fluorinated compounds and nanoparticles that exceed legacy system capabilities.
- Taiwan cluster concentration:Hsinchu Science Park's dense fab footprint creates continuous demand for industrial-scale wastewater processing infrastructure with minimal redundancy tolerance.
Market Restraints
- Specialty membrane supply concentration:Polymeric ultrafiltration and reverse osmosis membranes rely on concentrated Asian manufacturing bases, exposing fabs to lead time volatility.
- Energy intensity of crystallization:Thermal zero liquid discharge systems consume substantial electricity, compressing operating margins in regions with high industrial power tariffs.
- REACH chemical restriction complexity:ECHA's evolving substance restrictions create compliance uncertainty for European fabs managing fluorinated effluent streams.
Strategic Opportunities
- Advanced packaging expansion:Testing and packaging facilities generate emerging effluent streams with distinct heavy metal profiles, opening adjacent equipment demand beyond wafer fabrication.
- Water-stressed manufacturing locations:Arizona and Texas fab investments create captive reuse opportunities where municipal supply constraints justify premium zero liquid discharge economics.
- Digital twin integration:Real-time chemical dosing optimization through automation platforms enables outcome-based service contracting that locks in long-term maintenance revenue.
Industry Challenges
- Cross-functional engineering scarcity:Treatment system design requires simultaneous expertise in semiconductor process chemistry, membrane materials science, and automation controls that few individual engineers possess.
- Legacy infrastructure retrofit complexity:Brownfield fabs face spatial constraints and production continuity requirements that complicate phased upgrades to membrane bioreactor configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Wastewater Treatment Market |
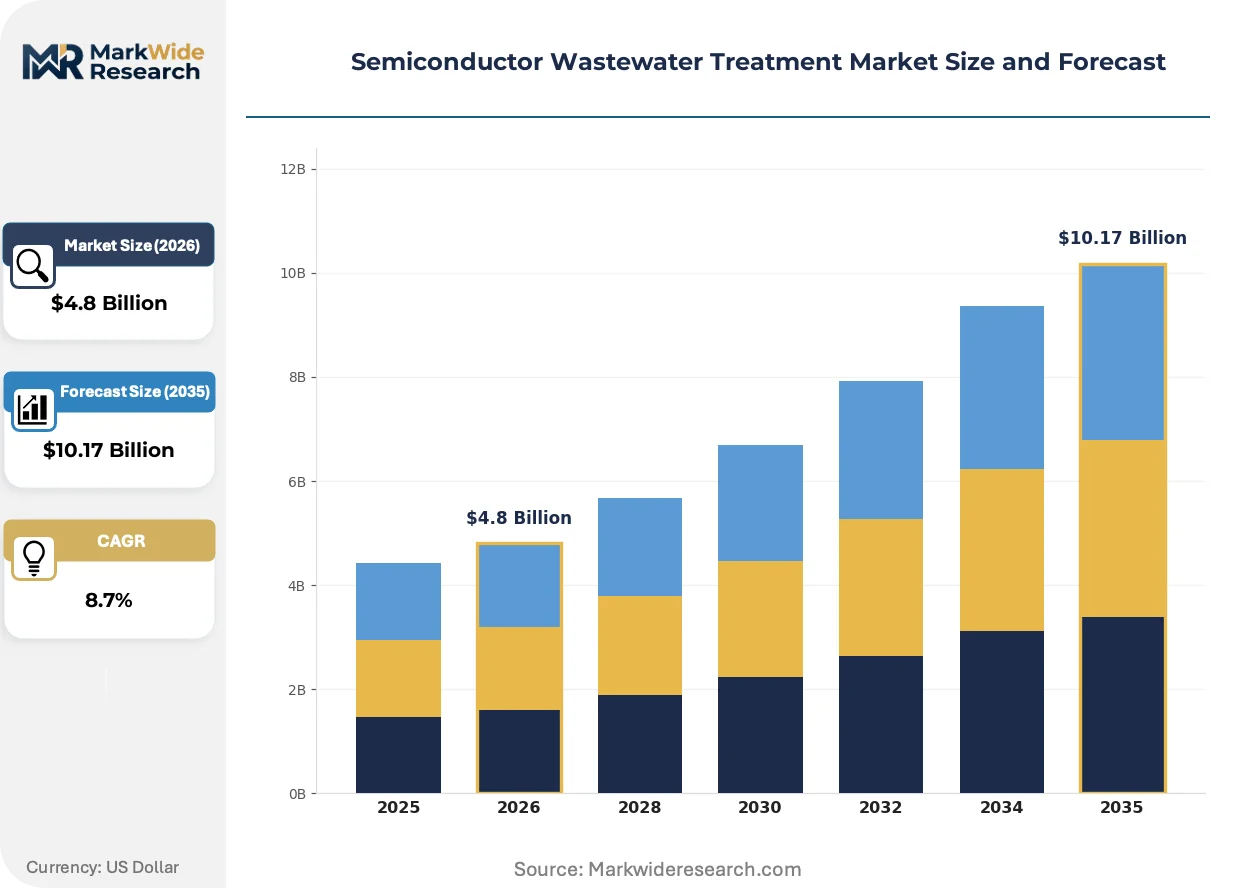
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Reverse Osmosis, Electrocoagulation, Ion Exchange, Membrane Filtration End User: Fabrication Facilities, Testing Labs, Research Institutes, Component Manufacturers Application: Process Water Treatment, Wastewater Reclamation, Chemical Neutralization, Zero Liquid Discharge Service Type: Consultation, Equipment Leasing, Maintenance, System Integration |
| Companies Covered | Arvia Technology, Organo Corporation, Siemens, SUEZ SA, Veolia Water Technologies & Solutions SA, DAS Environmental, Aquaporin, Xylem Inc., Horiba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Wastewater Treatment Market Trends and Innovations
Membrane technology evolution and regulatory stringency are converging to reshape competitive positioning across equipment categories and service delivery models.
Electrochemical oxidation systems are decentralizing fluoride destruction away from centralized chemical precipitation plants. Leading foundry operators in Taiwan and South Korea are piloting modular anodic oxidation units at individual process tool clusters rather than treating combined effluent streams. This distributed architecture is decentralizing capital deployment decisions from central engineering teams to individual fab module managers, compressing procurement cycles and enabling faster technology refresh.
REACH authorization requirements under ECHA oversight are tightening scrutiny of per- and polyfluoroalkyl substances used in etching and cleaning chemistries. European semiconductor manufacturers must now document substitution plans for legacy fluorinated compounds or secure time-limited authorizations. German and Dutch fabs are responding by accelerating partnerships with chemical suppliers to qualify next-generation etchants with improved biodegradability profiles before authorization deadlines crystallize.
Integrated service contracting is displacing equipment-only procurement across major foundry networks. TSMC and Samsung Foundry are bundling membrane replacement, chemical supply, and performance guarantees into multi-year agreements with single-source providers. This consolidation is most visible in Taiwan's Hsinchu and Tainan Science Parks, where fabs prioritize operational continuity over capital ownership and favor vendors with captive chemical production and field service density.
Semiconductor Wastewater Treatment Market Segmentation
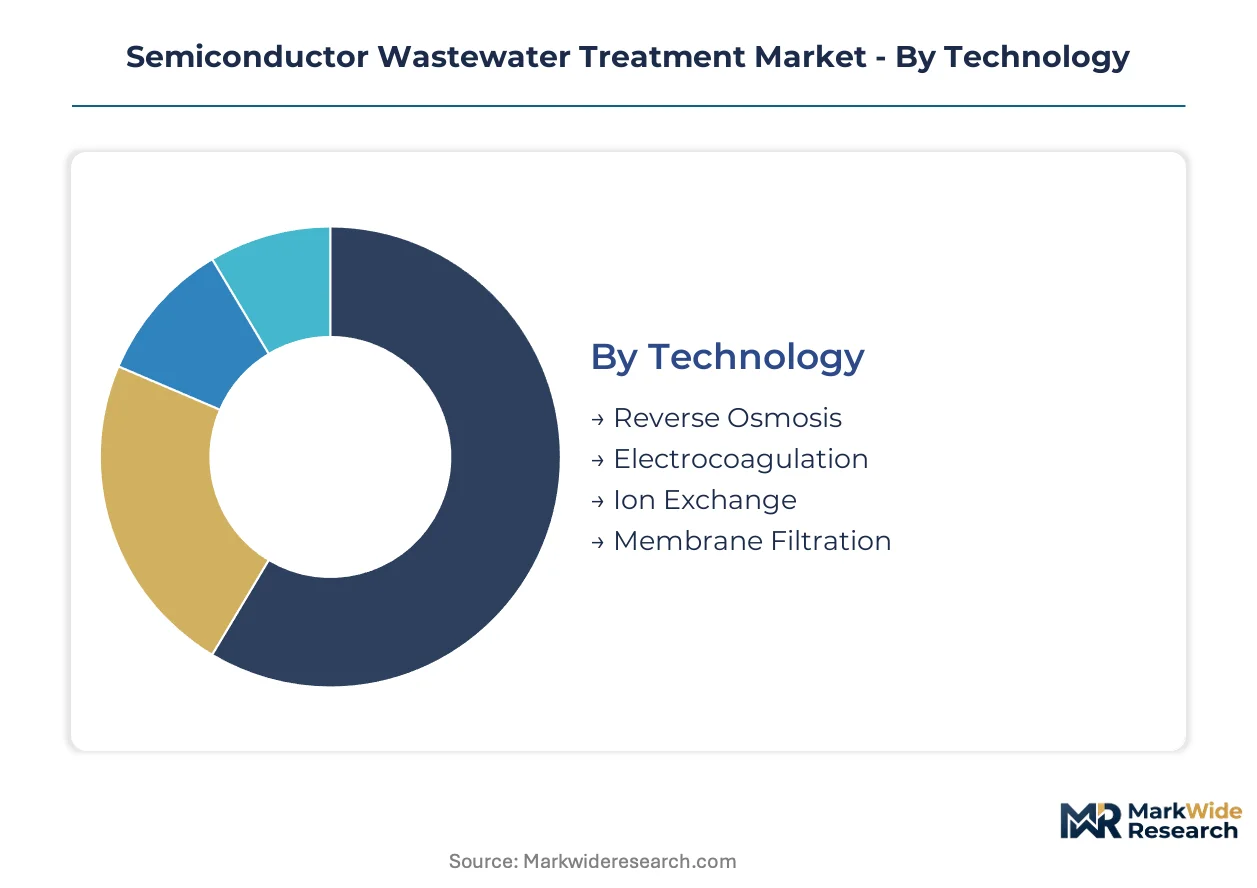
Technology selection in semiconductor wastewater treatment determines both capital intensity and operating compliance margins. Each segment category reflects distinct procurement logics—equipment performance, service relationships, or regulatory alignment—that shape how foundries structure their treatment investments.
Technology:
Membrane-based systems command premium valuations while electrochemical methods gain traction in retrofit-constrained brownfield sites.
- Reverse Osmosis:High-pressure membrane separation removes dissolved ions and organic contaminants to achieve ultrapure water standards for fab process loops. Demand concentrates in Taiwan's Hsinchu cluster where TSMC and United Microelectronics require continuous high-volume permeate output for 3nm and 2nm production ramps.
- Membrane Filtration:Ultrafiltration and microfiltration configurations target suspended solids and colloidal nanoparticles from chemical mechanical planarization effluent. South Korean fabs in Pyeongtaek are expanding microfiltration capacity to handle rising slurry volumes from advanced packaging integration.
- Electrocoagulation:Electrical current destabilizes heavy metal and fluoride complexes without chemical dosing, reducing sludge generation for facilities with limited waste disposal pathways.
- Ion Exchange:Selective resin beds capture trace metal contaminants including copper and nickel to meet EPA discharge thresholds for direct municipal sewer release.
Today's leader: Membrane Filtration. Tomorrow's challenger: Electrocoagulation.
End User:
Captive fab infrastructure absorbs the majority of installed capacity while testing and packaging facilities emerge as adjacent demand centers.
- Fabrication Facilities:Wafer fabs operate continuous treatment trains handling lithography, etch, and CMP effluent streams with zero redundancy tolerance. Arizona's emerging fab corridor—anchored by TSMC's Phoenix investment—is driving North American demand for integrated zero liquid discharge systems.
- Testing Labs:Advanced packaging and final test operations generate heavy metal-laden effluent from bumping and wire bonding processes. Facilities in Malaysia's Penang cluster are expanding treatment footprints as OSATs integrate 2.5D and 3D packaging capabilities.
- Research Institutes:Pilot line and R&D operations require flexible batch treatment systems accommodating experimental chemistries and lower throughput volumes.
- Component Manufacturers:Photomask, reticle, and specialty gas suppliers maintain smaller-scale treatment for process tool maintenance and cleanroom operations.
Fabrication Facilities anchor current procurement volumes; Testing Labs are climbing the fastest as packaging complexity escalates.
Application:
Water reclamation economics vary sharply by fab location, while zero liquid discharge commands the steepest capital commitments.
- Zero Liquid Discharge:Thermal crystallization and evaporator systems achieve complete water recovery with solid waste output, eliminating liquid discharge entirely. Texas fabs in water-stressed regions justify premium system economics through municipal supply risk mitigation and drought contingency planning.
- Process Water Treatment:Pretreatment and polishing stages protect downstream ultrapure water generation from organic and particulate contamination. Singapore's wafer fabs rely on advanced oxidation process trains to secure consistent feedwater quality despite variable reclaimed municipal supply.
- Wastewater Reclamation:Tertiary treatment enables direct reuse in cooling towers, scrubbers, and non-critical process steps to reduce freshwater withdrawal.
- Chemical Neutralization:pH adjustment and fluoride precipitation systems satisfy baseline discharge compliance for fabs without full water recovery mandates.
Process Water Treatment dominates current installation base; Zero Liquid Discharge represents the fastest-growing trajectory as water stress intensifies.
Service Type:
Outcome-based contracting is displacing equipment ownership across major foundry networks, restructuring vendor revenue models toward recurring service streams.
- System Integration:Turnkey engineering procurement and construction contracts bundle design, installation, and commissioning for greenfield fab projects. Japanese equipment suppliers are capturing EPC awards for Taiwan's Tainan Science Park expansions through technology transfer partnerships with local integrators.
- Maintenance:Predictive membrane replacement and chemical supply agreements lock in multi-year revenue with performance guarantees. Samsung Foundry's Gyeonggi facilities have consolidated maintenance contracts with single-source providers to minimize operational continuity risk.
- Consultation:Regulatory compliance auditing and treatment train optimization studies support brownfield upgrade planning and permit renewal.
- Equipment Leasing:Operating lease structures reduce capital deployment for packaging and testing facilities with uncertain production scaling timelines.
System Integration commands the largest contract values; Maintenance is expanding most quickly as installed membrane base matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors global demand for semiconductor wastewater treatment infrastructure, with concentrated fab operations in Taiwan, South Korea, and the United States driving capital deployment toward zero liquid discharge systems.
United States
EPA Clean Water Act enforcement tightens fluoride and copper discharge limits for fabs in Arizona and Texas. TSMC's Phoenix investment and Intel's Chandler expansion create captive treatment demand where municipal supply constraints justify premium system economics. Texas fabs deploy thermal crystallization units to eliminate liquid discharge entirely.
Taiwan
Industrial Park Sewerage Effluent Standards mandate continuous monitoring of heavy metals and fluorides across Hsinchu and Tainan Science Parks. TSMC and United Microelectronics operate concentrated manufacturing footprints requiring redundant membrane-based processing trains. Foundries bundle maintenance contracts into multi-year agreements with single-source providers.
South Korea
Samsung Foundry and SK Hynix drive demand in Pyeongtaek and Gyeonggi provinces where advanced packaging integration increases slurry volumes. Korean facilities expand microfiltration capacity for chemical mechanical planarization effluent. Regulatory alignment with REACH frameworks shapes chemical substitution timelines for fluorinated compounds.
Germany
ECHA authorization requirements tighten scrutiny of per- and polyfluoroalkyl substances used in etching chemistries. German fabs in Dresden and Saxony accelerate partnerships with chemical suppliers to qualify biodegradable etchants before authorization deadlines. European semiconductor manufacturers document substitution plans for legacy fluorinated compounds.
Japan
METI industrial water recycling guidelines push fabs in Kyushu and the Tohoku region toward membrane bioreactor configurations. Japanese equipment suppliers capture engineering procurement and construction awards for Taiwan expansions through technology transfer partnerships. Domestic foundries prioritize operational continuity through predictive membrane replacement agreements.
Semiconductor Wastewater Treatment Market Competitive Landscape
Global majors compete with regional champions across technology licensing and service density. The market structures around three tiers: integrated water utilities with captive chemical production, automation specialists with digital twin platforms, and membrane technology pure-plays. Consolidation pressures favor vendors with field service density in Taiwan and South Korea. Dominant competitive moves include multi-year integrated service contracting and backward integration into membrane manufacturing.
Within the integrated utility tier, Veolia Water Technologies & Solutions SA and SUEZ SA exemplify vendors bundling equipment, chemicals, and performance guarantees. Siemens occupies a position among automation-focused competitors through real-time process control platforms. Arvia Technology and Organo Corporation represent specialists in advanced oxidation and high-purity water recovery respectively. These archetypes illustrate how competitive positioning fragments across service integration, digital optimization, and technology specialization vectors.
| Leading Market Players |
|---|
| Arvia Technology |
| Organo Corporation |
| Siemens |
| SUEZ SA |
| Veolia Water Technologies & Solutions SA |
| DAS Environmental |
| Aquaporin |
| Xylem Inc. |
| Horiba |
| Others |
Pricing and Supply Chain Analysis
Foundry operators in Taiwan, South Korea, and the United States command substantial pricing leverage through consolidated procurement of zero liquid discharge systems, compressing vendor margins while rewarding performance-guaranteed service contracts. Their captive treatment investments favor long-term bundled agreements over equipment-only transactions.
Pricing Analysis
Specialty membrane cost pass-through dominates pricing structures for semiconductor wastewater treatment systems, with polymeric ultrafiltration and reverse osmosis modules anchoring project economics. Three-tier pricing structure across premium, standard, and economy levels separates membrane bioreactor configurations from conventional precipitation trains and basic neutralization skids. Price differentiation hinges on EPA discharge tier certification and after-sales chemical supply bundling. Cost compression in standard-tier equipment is intensifying because Asian membrane manufacturers are expanding capacity. Packaging and testing facilities exhibit highest price sensitivity due to uncertain production scaling, while Taiwan's Hsinchu cluster fabs prioritize operational continuity over capital expenditure minimization.
Supply Chain Analysis
Specialized automation engineers and membrane fabrication technicians concentrate in Taiwan, South Korea, and Japan, constraining system integrator expansion and extending project commissioning timelines. Polymeric membrane substrates, high-pressure pump assemblies, and precision analytical instrumentation feed from concentrated Asian manufacturing bases. Single-source vulnerability in fluoropolymer membrane supply exposes fabs to lead time volatility when geopolitical friction disrupts cross-strait logistics. Distribution runs through engineering-procurement-construction contractors with captive field service teams embedded in Taiwan's science park clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Clean Water Act enforcement and REACH authorization timelines continuously escalate treatment intensity requirements, embedding demand visibility into multi-year capital planning cycles.
For Market Incumbents: Hedge membrane supply exposure through backward integration into fluoropolymer manufacturing or strategic partnerships with Japanese materials suppliers. Diversify revenue toward predictive maintenance contracts as equipment ownership models fade. Chemical supply consolidation and field service density in Taiwan represent defensible moats against emerging automation specialists. For New Entrants and Emerging Players: Equipment leasing providers targeting Malaysia's Penang packaging cluster encounter lower competitive density than Taiwan's saturated fab infrastructure. Qualify electrochemical oxidation modules for brownfield retrofit applications where spatial constraints exclude membrane bioreactor deployment. Partner with regional system integrators lacking captive chemical production to accelerate market access. For Investors and Strategic Acquirers: Integrated water utilities with semiconductor field service density are the most active acquirers in this space, consolidating maintenance contract portfolios to deepen customer lock-in. Five-to-ten-year viability rests on membrane replacement recurring revenue streams rather than greenfield equipment sales cyclicality. Monitor EPA discharge limit revision announcements as inflection indicators for upgrade cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contracting | TSMC and Samsung Foundry are bundling membrane replacement, chemical supply, and performance guarantees into multi-year agreements. |
| Electrochemical Oxidation Deployment | Modular anodic oxidation units at individual process tool clusters decentralize capital deployment decisions to fab module managers. |
| Membrane Manufacturing Backward Integration | Veolia and SUEZ are securing captive fluoropolymer supply to reduce lead time volatility and protect margin structure. |
| Digital Twin Platform Integration | Siemens competes through real-time chemical dosing optimization that locks in long-term automation service revenue. |
| Water-Stressed Region Expansion | Arizona and Texas fab investments create captive reuse opportunities where municipal supply constraints justify premium system economics. |
Research Methodology
Bottom-up fabrication facility modeling reconciled against top-down membrane equipment supplier tracking forms the analytical core of this study. Primary interviews with fab engineering directors, EPC contractor procurement leads, water treatment plant managers, and regulatory compliance officers combined with secondary validation from EPA discharge filings, ECHA authorization databases, Taiwan EPA sewerage standards, and foundry capital expenditure disclosures. Triangulation across stakeholder perspectives and documentary sources ensures demand-side and supply-side estimates converge.
Historical trendline analysis of installed membrane base and replacement cycle patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include technology category, end-user facility type, application intensity, and service delivery model. CAGRs derive from regression-adjusted capacity expansion schedules and regulatory mandate implementation timelines. Foundry process node advancement trajectories and water stress indices for manufacturing locations serve as industry-specific forecast inputs.
Revisions become necessary when EPA discharge limit revisions, ECHA substance authorization withdrawals, or membrane supply disruptions materialize outside modeled scenarios. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and foundry capital commitment continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Global Municipal Water Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
CMP Slurry Blend and Delivery Systems Market
Water & Sludge Treatment
Global Sludge Treatment Chemicals Market
Water & Sludge Treatment
Industrial Water Treatment Chemicals Market
Water & Sludge Treatment
Nanotechnology in Water Treatment Market
Water & Sludge Treatment
Global Flocculant and Coagulant Market
Water & Sludge Treatment
Oil and Gas Water Treatment Chemicals Market
Water & Sludge Treatment
Germany Water Treatment Chemicals Market
Water & Sludge Treatment
Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market
Water & Sludge Treatment
Australia & New Zealand Water Treatment Chemicals Market
Water & Sludge Treatment
Global Mobile Water Treatment Market
Water & Sludge Treatment
Ultrapure Water Market
Water & Sludge Treatment
Enzymes for Water Treatment Market
Water & Sludge Treatment
Mexico Water Treatment Chemicals Market
Water & Sludge Treatment
Water and Wastewater Treatment Technologies Market