
 Sludge Heater Market | 2026-2036
Sludge Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Sludge Heater Market Analytics
Specialized welding and thermal engineering expertise is reorganizing competitive dynamics in sludge heater manufacturing. Andritz AG leverages its Austrian engineering base to dominate large-scale thermal hydrolysis integrations. Veolia Water Technologies sustains a service-led model across European municipal contracts. GEA Group anchors its position through captive supply of heat exchanger components.
A sludge heater is a thermal processing unit that raises the temperature of sewage sludge, typically to 160-180°C in thermal hydrolysis applications, to accelerate pathogen destruction and improve biogas yield in anaerobic digestion. The device operates by transferring thermal energy through direct steam injection, indirect tube-and-shell contact, or thermal oil circulation to reduce sludge viscosity and enhance dewaterability. Electric heaters currently occupy the premium tier for precision temperature control in smaller facilities, while steam heaters lead in capacity-installed terms across major municipal plants. Indirect heating technology is displacing direct steam methods where condensate recovery and energy efficiency targets are tightening.
The US EPA's Part 503 biosolids rule shapes pathogen-reduction technology selection, while the EU Urban Wastewater Treatment Directive drives nutrient recovery and energy neutrality mandates across member states. Germany's KBA and state-level environmental agencies enforce emission thresholds that favor low-NOx burner designs in gas-fired sludge heaters. Stakeholders must monitor how tightening carbon-accounting rules for Scope 1 emissions from digester gas combustion will reshape fuel choices in heater procurement decisions.
Market Dynamics
Municipal wastewater treatment plants are consolidating thermal hydrolysis investments to meet tightening pathogen-reduction mandates, while indirect heating technology gains ground over direct steam methods as energy recovery targets harden across regulatory jurisdictions.
Growth Catalysts
- Thermal Hydrolysis Expansion:Municipal facilities in Germany's Rhine-Ruhr corridor are scaling pre-digestion heating capacity to boost biogas yields and meet EU Urban Wastewater Treatment Directive energy-neutrality timelines.
- US EPA Part 503 Rule:Tighter Class A biosolids pathogen standards are forcing facility upgrades toward 160-180°C operating regimes that only specialized sludge heaters can sustain.
- Industrial Cluster Concentration:Chemical and food processing complexes in Belgium's Port of Antwerp are adding on-site sludge thermal treatment to reduce off-site disposal costs and carbon intensity.
Market Restraints
- Specialized Fabrication Bottlenecks:ASME-certified pressure vessel welding capacity concentrates in Austrian and German engineering shops, creating 14-18 month delivery backlogs for large tube-and-shell units.
- High-Alloy Steel Price Volatility:316L stainless steel and Inconel feedstock costs swing with nickel spot markets, compressing margins on fixed-price municipal contracts.
- Condensate Recovery Complexity:Direct steam injection systems face retrofit limitations where existing digester infrastructure lacks condensate handling capacity.
Strategic Opportunities
- Netherlands Nutrient Recovery Mandates:Struvite precipitation requirements at Rotterdam-area plants are creating demand for precise temperature control that electric sludge heaters uniquely provide.
- Biogas Upgrading Integration:Convergence of thermal hydrolysis with membrane biogas upgrading is opening bundled equipment procurement channels at Danish agricultural digesters.
- France's Circular Economy Roadmap:National organic waste diversion targets are accelerating greenfield anaerobic digestion projects in the Grand Est region without legacy steam infrastructure.
Industry Challenges
- Certified Welder Scarcity:TIG and orbital welding expertise for exotic alloy heat exchanger fabrication is concentrated among aging specialists in Central European engineering bases.
- Legacy Control System Integration:SCADA retrofitting for precision temperature modulation conflicts with 1990s-era municipal plant automation architectures.
- Scope 1 Emissions Accounting:Digester gas combustion in gas-fired heaters faces tightening carbon reporting rules that complicate fuel choice justification in public procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sludge Heater Market |
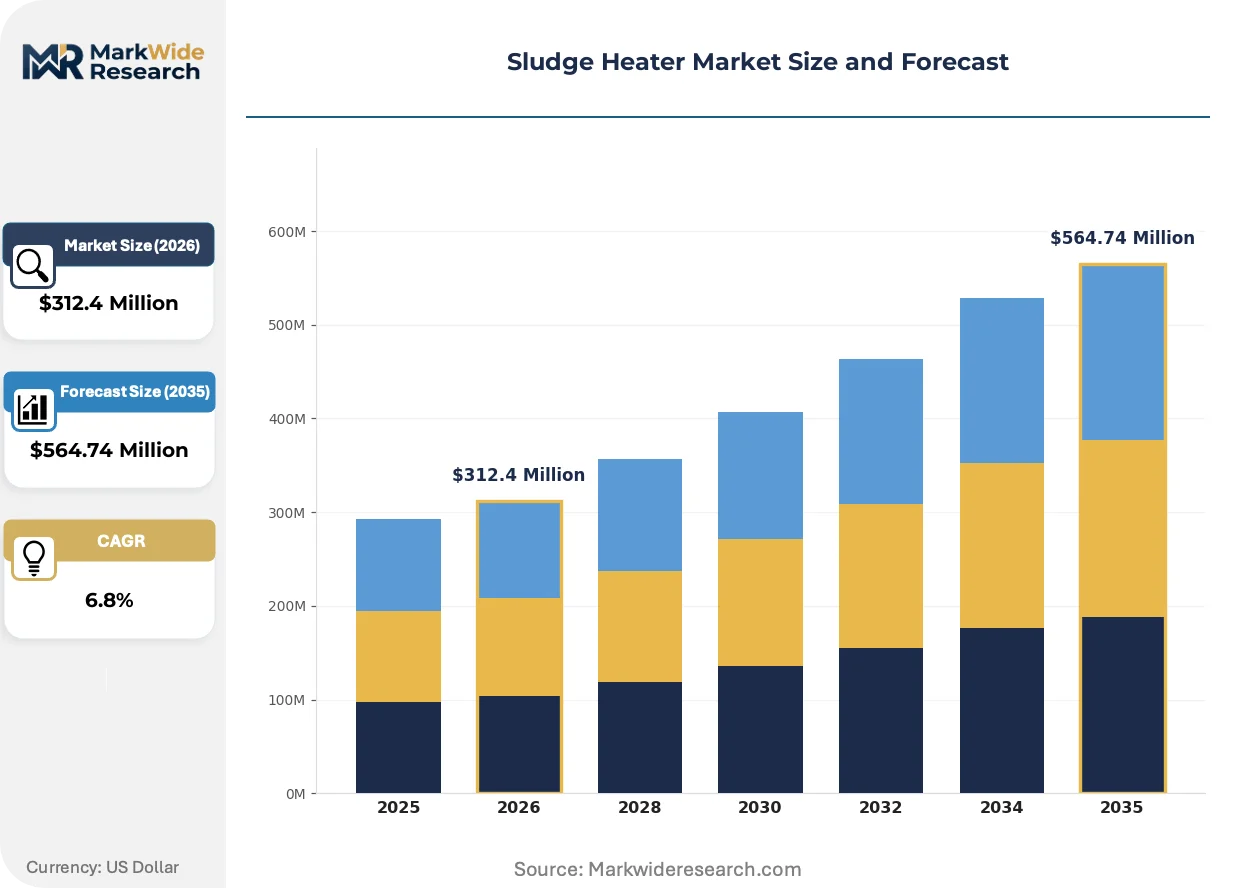
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Heater, Gas Heater, Steam Heater, Hybrid Heater End User: Municipal Wastewater Treatment, Industrial Wastewater Treatment, Agricultural Waste Management, Zoos & Aquariums Technology: Direct Heating, Indirect Heating, Thermal Oil Heating, Heat Exchanger Technology Application: Biogas Production, Sludge Drying, Odor Control, Energy Recovery |
| Companies Covered | Andritz AG, Veolia Water Technologies, GEA Group, Alfa Laval, Evoqua Water Technologies, HUBER SE, Flottweg SE, Xylem Inc., Komline-Sanderson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sludge Heater Market Evolving Landscape
Equipment design is pivoting toward modularity and energy recovery integration as operators seek to de-risk capital deployment and align with tightening carbon accounting frameworks.
Electric immersion heater arrays with silicon carbide elements are fragmenting the sub-500kW capacity tier. Small-to-midscale facilities in Denmark and Sweden are specifying these units for thermal hydrolysis pilot lines. The technology is fragmenting vendor competitive sets by enabling packaged skid deliveries that bypass traditional field-erected pressure vessel procurement cycles.
The EU F-Gas Regulation phase-down is accelerating adoption of ammonia and CO2 heat pump circuits for sludge pre-heating. Industrial boiler operators in Germany's chemical corridor are retrofitting absorption heat pumps to recover low-grade waste heat from existing processes. Food processing plants in northern Italy are most affected, replacing R-134A systems ahead of 2030 service ban deadlines.
Service unbundling is reshaping how municipal utilities contract thermal equipment. Dutch water authorities are separating heater hardware procurement from 10-year thermal performance guarantees, forcing OEMs to compete with third-party service integrators. The shift is most visible in the Randstad urban core, where regional water boards pool maintenance spend across multiple treatment sites.
Sludge Heater Market Segmentation
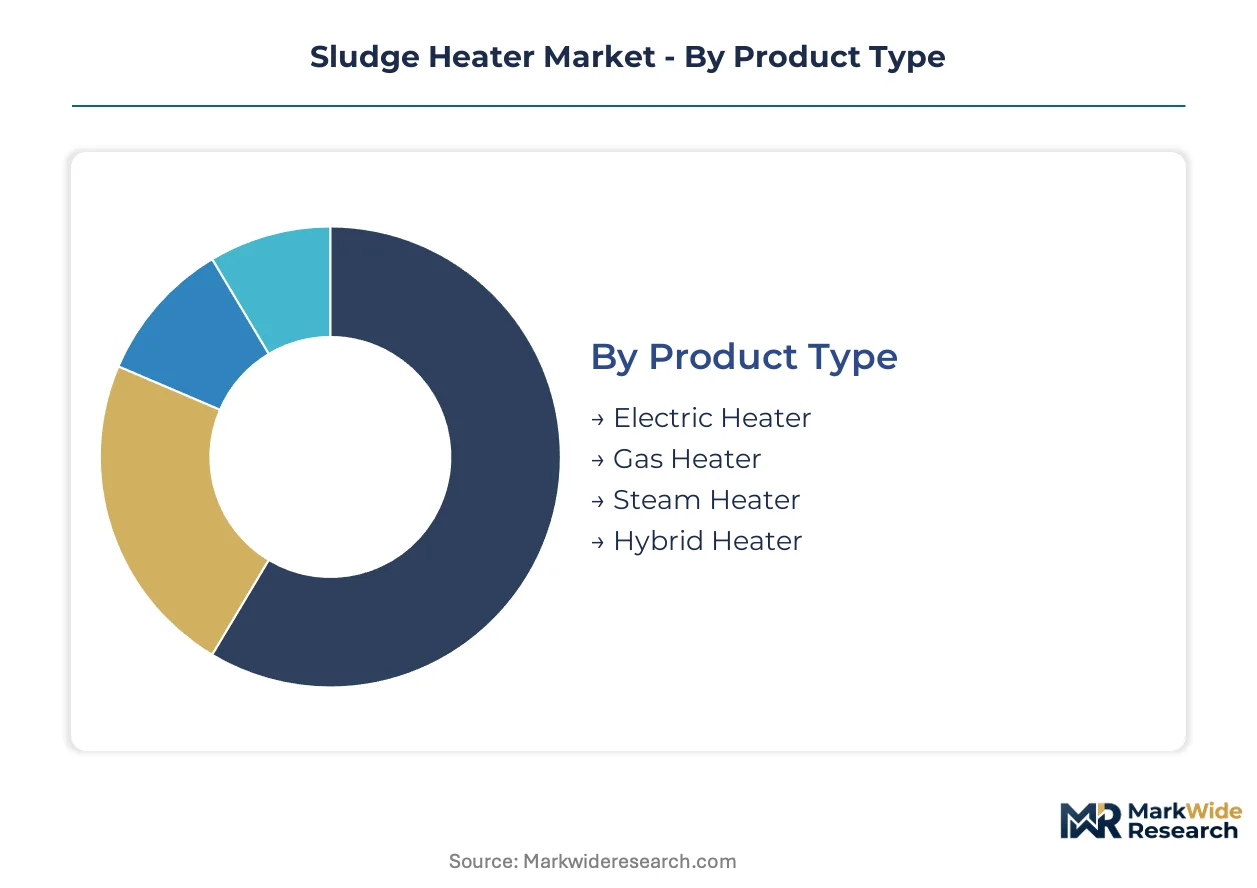
Sludge heater procurement decisions split across thermal performance requirements, regulatory compliance tiers, and integration complexity with existing anaerobic digestion infrastructure. Equipment specification varies sharply between municipal utilities seeking pathogen reduction certification and industrial operators prioritizing energy recovery economics.
Product Type:
EPA Part 503 Class A biosolids rules and EU Urban Wastewater Treatment Directive energy-neutrality mandates create divergent equipment specifications across thermal technologies.
- Electric Heater:Silicon carbide immersion elements deliver precision temperature control within ±2°C for thermal hydrolysis pilot lines. Dutch water authorities at Rotterdam-area plants specify these units for struvite precipitation processes where condensate recovery infrastructure is absent.
- Gas Heater:Low-NOx burner designs dominate large-scale municipal installations in Germany's Rhine-Ruhr corridor. KBA emission thresholds favor these units where digester gas combustion faces tightening Scope 1 carbon accounting rules in public procurement.
- Steam Heater:Direct injection systems retain cost advantage in legacy infrastructure.
- Hybrid Heater:Dual-fuel configurations bridge regulatory uncertainty.
Established volume favors gas-fired units in municipal scale; emerging adoption favors electric arrays in nutrient recovery applications.
End User:
Customer archetypes separate by capital deployment timelines and regulatory enforcement intensity rather than facility scale alone.
- Municipal Wastewater Treatment:Public utilities consolidate thermal hydrolysis investments to meet tightening pathogen standards. Germany's state environmental agencies enforce 160-180°C operating regimes that sustain specialized equipment procurement cycles.
- Industrial Wastewater Treatment:Chemical and food processing complexes in Belgium's Port of Antwerp add on-site thermal treatment to reduce off-site disposal costs.
- Agricultural Waste Management:Danish agricultural digesters drive bundled equipment procurement.
- Zoos & Aquariums:Niche demand concentrates in specialized biological waste handling.
Procurement concentration sits with municipal utilities; margin expansion favors industrial operators with carbon intensity targets.
Technology:
Heat transfer mechanisms differentiate by energy recovery potential and condensate handling requirements.
- Direct Heating:Steam injection systems face retrofit limitations where existing digesters lack condensate infrastructure. US facilities with 1990s-era SCADA architectures struggle to integrate precision temperature modulation.
- Indirect Heating:Tube-and-shell configurations gain share where energy efficiency targets harden. Austrian and German engineering shops concentrate ASME-certified welding capacity for these units.
- Thermal Oil Heating:Circulation systems suit high-viscosity sludge streams.
- Heat Exchanger Technology:Plate-and-frame designs enable modular deployment.
Direct methods retain installed base; indirect systems climb fastest on energy recovery mandates.
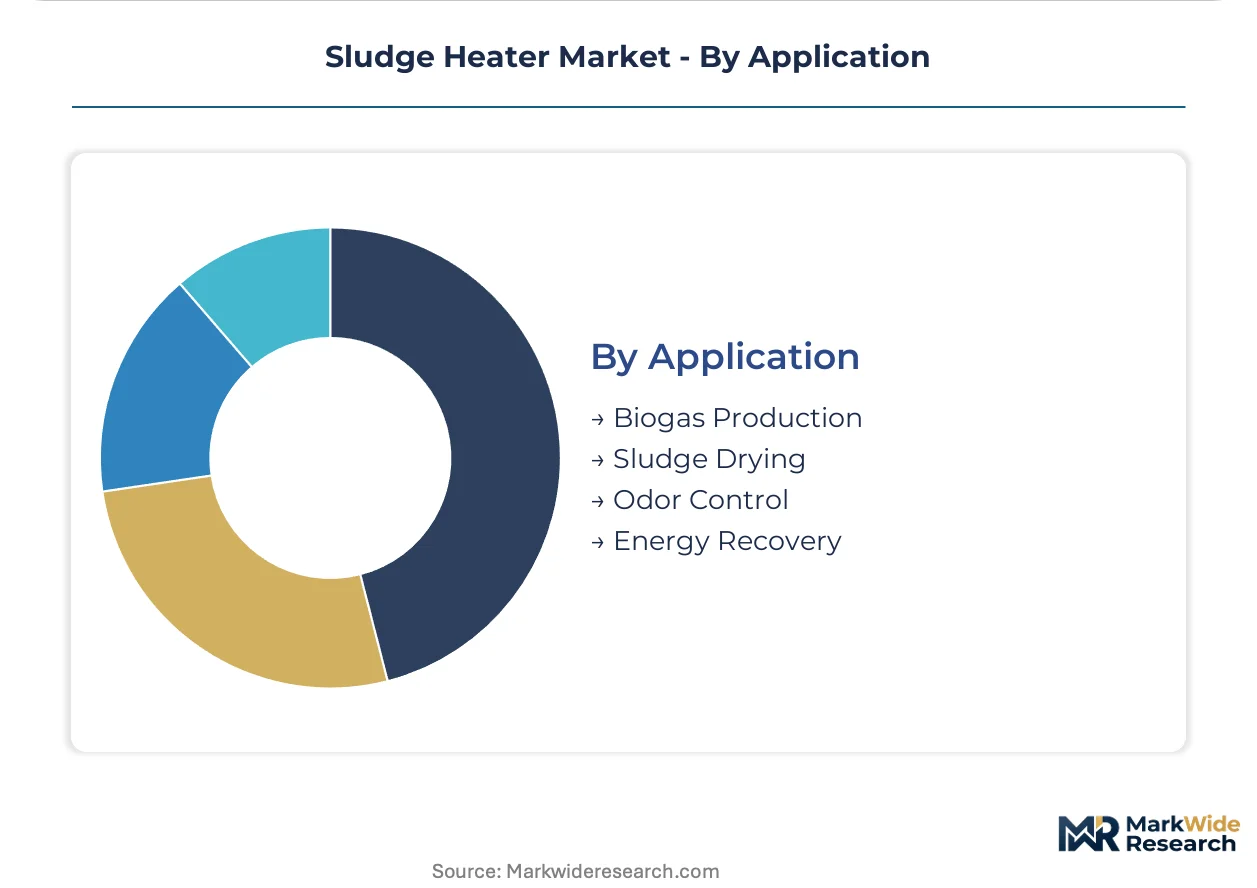
Application:
Downstream process integration determines temperature precision requirements and equipment lifecycle economics.
- Biogas Production:Thermal hydrolysis pre-treatment boosts methane yield 30-50% in anaerobic digestion. Pre-heating capacity expansions in Germany's Rhine-Ruhr corridor target EU energy-neutrality timelines.
- Sludge Drying:Evaporative load reduction improves transport economics.
- Odor Control:Pasteurization destroys volatile organic compound precursors.
- Energy Recovery:Waste heat capture from digester gas combustion tightens carbon intensity metrics.
Biogas yield optimization anchors capital deployment; energy recovery applications show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering shops command 30-40% price premiums over North American fabricators for ASME-certified thermal hydrolysis units. Austrian and Czech suppliers undercut both on standardized indirect heating systems.
Germany
North Rhine-Westphalia's Rhine-Ruhr corridor drives thermal hydrolysis capacity expansion at municipal utilities. KBA emission thresholds enforce low-NOx burner specifications in gas-fired installations. State environmental agencies in Düsseldorf and Cologne mandate 160-180°C operating regimes for Class A biosolids certification.
United States
Municipal utilities in the Great Lakes region retrofit 1990s-era digesters with precision temperature controls. EPA Part 503 rules tighten pathogen reduction standards for land-applied biosolids. Chicago and Milwaukee metropolitan plants consolidate pre-digestion heating investments.
Netherlands
Rotterdam-area water authorities separate heater procurement from long-term performance guarantees. EU Urban Wastewater Treatment Directive drives nutrient recovery mandates requiring precise temperature modulation. Randstad regional boards pool maintenance spend across multiple treatment sites.
Denmark
Agricultural digesters in Jutland and Zealand bundle thermal hydrolysis with membrane biogas upgrading. National biogas targets accelerate greenfield anaerobic digestion without legacy steam infrastructure. Copenhagen-area plants pilot electric immersion arrays for sub-500kW pilot lines.
Belgium
Port of Antwerp chemical complexes add on-site sludge thermal treatment to reduce off-site disposal costs. Flanders environmental regulations tighten carbon intensity metrics for industrial wastewater. Ghent and Liège food processing plants specify modular pre-heating skids.
Sludge Heater Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in sludge heater manufacturing. Specialized welding and thermal engineering expertise concentrates in Central European engineering bases, creating supply-side bottlenecks for large tube-and-shell units. Three archetypes dominate: Austrian-German integrated engineering conglomerates with captive pressure vessel fabrication, French-led water service multinationals with long-term municipal contracts, and Nordic-Baltic modular equipment specialists. Competitive moves center on separating hardware procurement from performance guarantees and bundling thermal hydrolysis with biogas upgrading systems.
Among the engineering conglomerates, Andritz AG and GEA Group exemplify the integrated fabrication model with in-house pressure vessel capacity. Veolia Water Technologies occupies a position within the service-led tier, anchoring municipal contract structures that unbundle equipment from long-term thermal performance guarantees. These three represent divergent strategic postures: captive manufacturing control versus service-based customer lock-in.
| Leading Market Players |
|---|
| Andritz AG |
| Veolia Water Technologies |
| GEA Group |
| Alfa Laval |
| Evoqua Water Technologies |
| HUBER SE |
| Flottweg SE |
| Xylem Inc. |
| Komline-Sanderson |
| Others |
Value Network & Pricing Analysis
Fourteen-to-eighteen-month delivery backlogs for ASME-certified tube-and-shell units concentrate pricing power in Austrian and German engineering shops, while municipal buyers face take-it-or-leave-it terms on fixed-price contracts. This lead-time compression feeds directly into cost pass-through dynamics for high-alloy steel inputs and specialized welding labor.
Pricing Analysis
Configured-to-order pricing for thermal hydrolysis-integrated sludge heaters commands substantial premiums over standardized indirect heating units, with customization depth tied to pathogen-reduction certification tiers and digester gas combustion specifications. Price differentiation rests on ASME pressure vessel certification status and captive heat exchanger component supply. Pricing pressure stems from nickel spot market volatility feeding 316L stainless steel and Inconel feedstock costs. Municipal utilities exhibit highest price sensitivity due to fixed-budget procurement cycles, while industrial operators in Belgium's Port of Antwerp absorb premiums for carbon intensity compliance.
Supply Chain Analysis
Austria and Germany anchor specialized pressure vessel fabrication for thermal hydrolysis applications, with Czech suppliers competing on standardized indirect heating systems. Raw material dependencies draw from nickel spot markets for high-alloy steels and silicon carbide for electric immersion elements. Single-source vulnerability concentrates in ASME-certified TIG and orbital welding expertise among aging specialist pools in Central European engineering bases. Distribution runs through direct OEM-municipal utility contracting and bundled equipment procurement channels at agricultural digester installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sludge heater demand sits in early-cycle expansion as thermal hydrolysis pre-treatment penetration accelerates across EU energy-neutrality timelines and US EPA Part 503 compliance deadlines.
For Market Incumbents: Shield installed base relationships by embedding 10-year thermal performance guarantees into municipal contract renewals before Dutch-style service unbundling spreads. Deepen backward integration into silicon carbide element supply to offset electric heater margin compression from Nordic-Baltic modular specialists. Prioritize ASME-certified welding capacity expansion in Austrian engineering bases to relieve 14-18 month delivery bottlenecks. For New Entrants and Emerging Players: CE marking fast-tracks for low-NOx burner designs open procurement channels at Germany's KBA-regulated municipal utilities. Target Netherlands nutrient recovery mandates where Rotterdam-area water authorities separate heater hardware from service contracts. Pursue packaged skid deliveries for Denmark's sub-500kW agricultural digester pilot lines to bypass field-erected pressure vessel procurement cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with orphaned thermal equipment divisions lacking municipal water sector focus. Five-to-ten-year viability hinges on regulatory enforcement intensity for pathogen-reduction standards and carbon accounting granularity. Watch for Scope 1 emissions reporting rule tightening in public procurement as inflection signal for gas-to-electric heater substitution trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Exchanger Components | GEA Group's captive supply model demonstrates margin protection against alloy steel volatility. |
| Service Unbundling Response | Veolia's performance-guarantee separation preempts Dutch water authority procurement restructuring. |
| Electric Immersion Array Development | Silicon carbide element adoption fragments sub-500kW tier away from steam heater incumbents. |
| Ammonia Heat Pump Circuit Adoption | EU F-Gas Regulation phase-down accelerates CO2 and ammonia pre-heating retrofits in Germany. |
| ASME Welding Capacity Expansion | Andritz AG's Austrian engineering base concentration risks delivery backlogs without capacity adds. |
Research Methodology
The analysis maps electric, gas-fired, steam, and hybrid heater sub-sectors, each validated through municipal utility procurement officers, industrial wastewater plant engineers, and thermal equipment aftermarket service heads. Primary interview intelligence triangulates against EPA Part 503 regulatory filings, EU Urban Wastewater Treatment Directive implementation reports, and ASME pressure vessel certification databases. Bottom-up equipment shipment tracking and top-down municipal capital expenditure surveys cross-validate volume estimates across the analysis window.
Consistency checks against external benchmarks anchored projections to observed thermal hydrolysis capacity expansions in Germany's Rhine-Ruhr corridor and Great Lakes municipal retrofit cycles. Segmentation modeling spans product type, end-user archetype, heat transfer technology, and downstream application integration. CAGRs derive from equipment replacement cycles, regulatory compliance deadlines, and biogas yield optimization economics. Forecast inputs incorporate KBA emission threshold enforcement trajectories and nickel spot market volatility assumptions.
Underlying assumptions cover EU energy-neutrality timeline adherence and US EPA biosolids rule enforcement intensity, with deviation risk concentrated in Scope 1 emissions accounting rule changes and high-alloy steel price swings. Forecasts reflect these conditions without claiming predictive certainty. Recalibration cycles align with material shifts in municipal procurement unbundling patterns and F-Gas Regulation implementation milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
South America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
South America Membrane Water and Wastewater (WWT) Treatment Market
Water & Sludge Treatment
Asia-Pacific Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Water Softening Systems Market
Water & Sludge Treatment
Global Water Clarifiers Market
Water & Sludge Treatment
Global Water Softeners Market
Water & Sludge Treatment
Sludge Treatment and Disposal Equipment Market
Water & Sludge Treatment
Process Water Treatment Market
Water & Sludge Treatment
Drinking Water Adsorbents Market
Water & Sludge Treatment
Water Treatment Market
Water & Sludge Treatment
Water Treatment Polymers Market
Water & Sludge Treatment
Germany Water Treatment Chemicals Market
Water & Sludge Treatment
Hazardous Waste Treatment System Market
Water & Sludge Treatment
North America Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Global Electrodeionization Market
Water & Sludge Treatment
Enzymes for Water Treatment Market