
 Global Multi-Turn Potentiometer Market | 2026-2036
Global Multi-Turn Potentiometer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Multi-Turn Potentiometer Market Outlook
Industrial automation buyers is rotating toward precision position-sensing systems that demand higher resolution and repeatability than single-turn alternatives. BOURNS leverages its vertical integration in resistive element manufacturing to control cost structures across volume tiers. Sensata Technologies anchors its position through magnetic technology leadership in harsh-environment applications. MENTOR specializes in compact form factors for space-constrained medical and aerospace instrumentation.
A multi-turn potentiometer is an electromechanical transducer that converts multiple full-shaft rotations into a proportional resistance change, typically achieving ten or more turns with linearity tolerances below one percent. Its primary purpose is to provide precise positional feedback in servo mechanisms, calibration equipment, and industrial process controls where fine adjustment range exceeds three hundred sixty degrees. Analog potentiometers dominate unit volume in cost-sensitive automotive throttle and climate control applications, while digital potentiometers capture margin pools in software-calibrated industrial networks. Optical technology segments lead precision instrumentation where contactless operation eliminates wear, and hybrid configurations are growing fastest in aerospace fly-by-wire systems that combine analog reliability with digital bus interfaces.
REACH and RoHS frameworks in Europe restrict hazardous substances in resistive element compositions, forcing reformulation of carbon and cermet materials. The EU AI Act and CE marking requirements for industrial machinery increasingly mandate traceable position-sensing components in autonomous production lines. FDA electromagnetic compatibility standards in the United States shape design verification protocols for medical device integrators. Stakeholders must monitor how IEC standard revisions for functional safety in process industries will redefine qualification thresholds for potentiometer feedback loops in safety-critical automation architectures.
Market Dynamics
Industrial automation architectures are reconfiguring around precision motion control, forcing potentiometer suppliers to align resolution specifications with servo-loop requirements in robotics and CNC systems. This structural pull is compressing development cycles and recalibrating qualification protocols across the supply base.
Growth Catalysts
- EU AI Act compliance mandates:Autonomous production lines in Germany and France now require traceable position-sensing components, expanding demand for certified feedback devices in safety-critical loops.
- Optical sensing technology:Contactless operation eliminates mechanical wear in precision instrumentation, opening replacement cycles in laboratory calibration equipment and semiconductor metrology.
- Stuttgart-Munich industrial corridor concentration:Germany's machine tool and automotive automation cluster generates sustained demand for high-linearity multi-turn devices in servo positioning applications.
Market Restraints
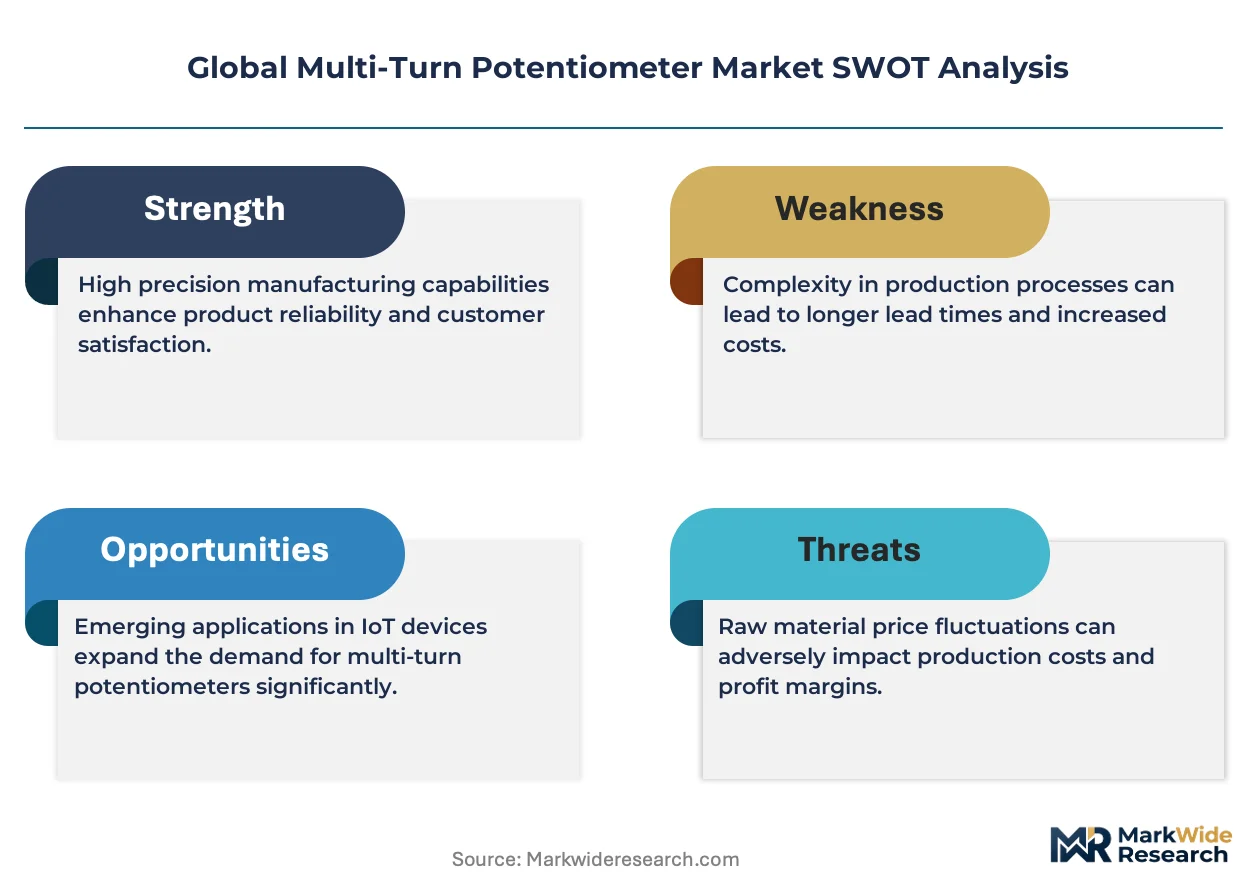
- Rare earth magnet supply concentration:Magnetic encoder alternatives depend on neodymium supply chains centered in China, creating input cost volatility and geopolitical exposure for hybrid potentiometer manufacturers.
- REACH substance restrictions:ECHA reformulation mandates for carbon and cermet resistive elements force costly material requalification and supply chain revalidation.
- Digital potentiometer substitution:Software-calibrated networks in industrial automation displace analog units in non-safety-critical feedback loops, compressing addressable volume in cost-sensitive tiers.
Strategic Opportunities
- Aerospace fly-by-wire hybridization:Combining analog reliability with digital bus interfaces creates specification white space in commercial aviation and defense platforms requiring MIL-STD-810 qualification.
- Medical device miniaturization:Compact form factors for surgical robotics and imaging systems open premium positioning in FDA-regulated applications where electromagnetic compatibility is mandatory.
- India PLI scheme for industrial automation:Production-linked incentives for advanced manufacturing equipment create localized demand pull in Pune and Bangalore automation clusters.
Industry Challenges
- IEC 61508 functional safety certification timelines:Process industry qualification for safety instrumented systems extends development cycles by 18-24 months, straining smaller suppliers' capital reserves.
- Legacy system integration complexity:Retrofitting precision position feedback into existing analog control architectures requires custom signal conditioning, fragmenting engineering resources.
- Electromagnetic compatibility test protocol proliferation:Divergent FDA, CE marking, and ISO 11452 verification requirements multiply pre-market compliance costs for multi-region product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Multi-Turn Potentiometer Market |
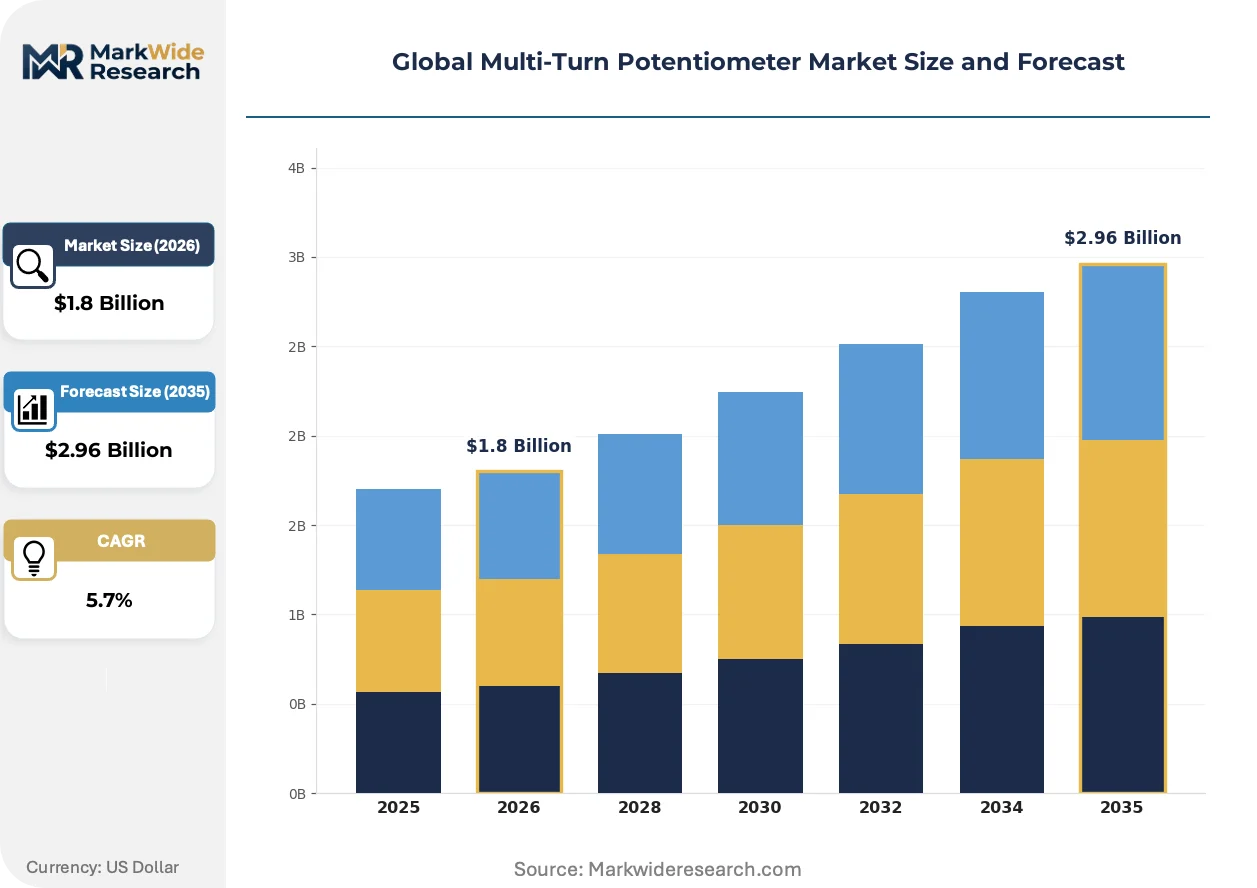
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Potentiometers, Digital Potentiometers, Hybrid Potentiometers, Precision Potentiometers Application: Automotive Controls, Industrial Automation, Consumer Electronics, Audio Devices End User: Manufacturers, OEMs, Retailers, Distributors Technology: Resistance Technology, Optical Technology, Magnetic Technology, Capacitive Technology |
| Companies Covered | MENTOR, Celesco, BOURNS, MCB industrie, On Line Controls, MURRELEKTRONIK, Sensata Technologies, Iskra d.d., Althen Sensors & Controls, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Multi-Turn Potentiometer Market Strategic Shifts
Component architectures are fragmenting as end-users demand configurable sensing platforms that bridge analog reliability with digital connectivity. This recombination is driving material science investment and reshaping supplier capability requirements.
Optical encoding technology is decomposing the traditional electromechanical potentiometer value chain. Photodiode arrays and LED-based position detection eliminate brush contact wear, extending operational life beyond ten million cycles. Medical imaging OEMs in Switzerland and semiconductor equipment builders in Japan are adopting these devices for sub-micron repeatability requirements. The technology is decomposing established price-performance tiers by collapsing the premium segment into a single contactless category.
REACH and RoHS frameworks in Europe are forcing systematic reformulation of resistive element compositions. ECHA substance restrictions now cover cadmium-free cermet alternatives and halogen-free carbon track materials, compelling suppliers to revalidate temperature coefficient stability. German automotive Tier-1 suppliers are accelerating qualification of compliant materials to maintain CE marking access for industrial machinery exports.
Specification consolidation among industrial automation buyers is compressing vendor qualification cycles. Large robotics OEMs in Bavaria and Baden-Württemberg now mandate integrated digital output interfaces and predictive maintenance telemetry as standard requirements. Distributors in the DACH region are responding by pre-certifying sensor platforms against multiple industry standards, reducing procurement friction for mid-size system integrators.
Global Multi-Turn Potentiometer Market Segmentation
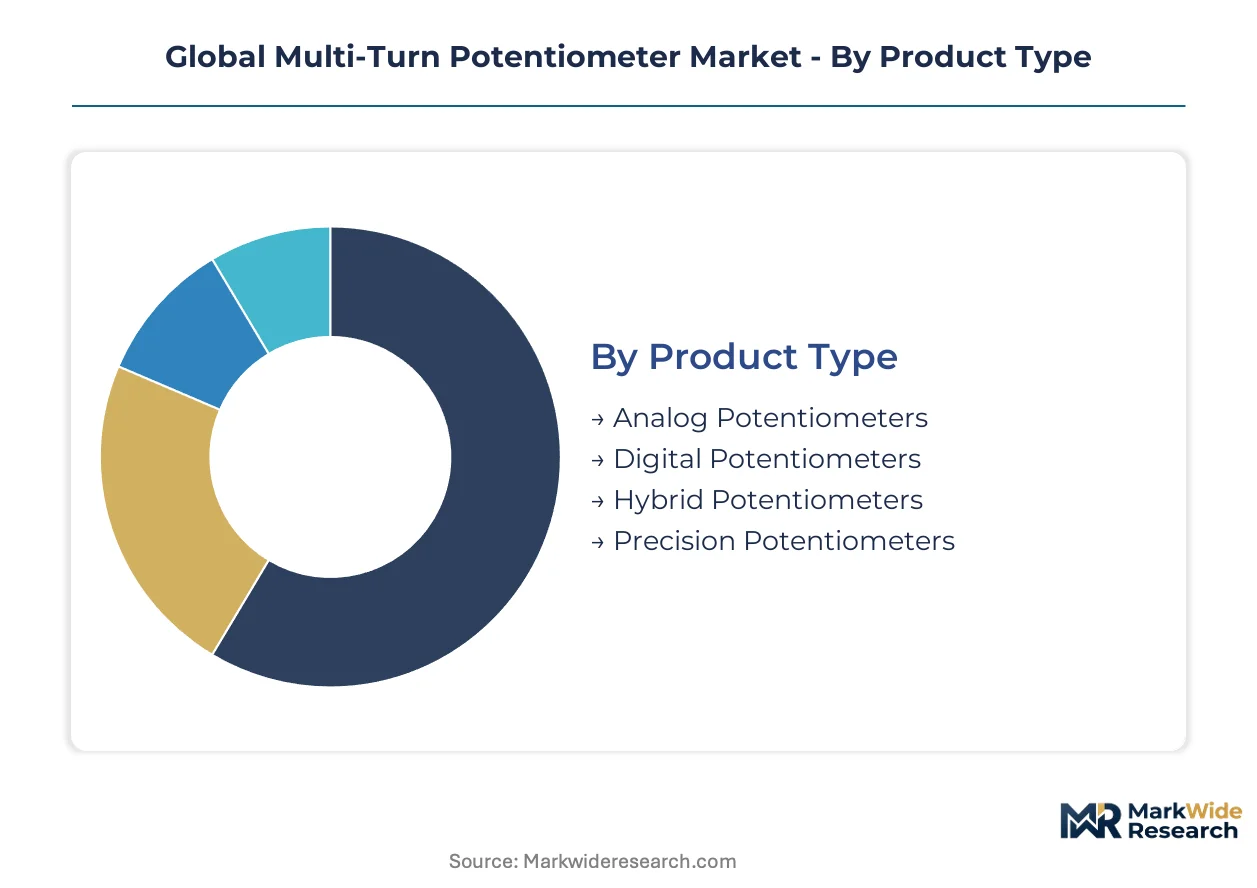
Multi-turn potentiometer procurement channels diverge sharply by performance tier and certification burden. Industrial buyers route high-specification devices through authorized distributors with IEC 61508 documentation, while automotive volume contracts flow direct to Tier-1 suppliers.
Product Type:
Distributor stocking patterns split between commodity analog units and digitally calibrated variants requiring technical support infrastructure.
- Analog Potentiometers:Carbon and cermet resistive elements deliver continuous resistance change across ten or more shaft rotations with sub-one-percent linearity. Automotive throttle position sensors in Stuttgart's manufacturing corridor consume volume production from BOURNS and Vishay.
- Digital Potentiometers:Solid-state resistor arrays with SPI or I2C interfaces enable software-calibrated gain stages without mechanical wear. Industrial automation networks in Bavaria specify these for remote recalibration of servo loops.
- Hybrid Potentiometers:Combine analog sensing reliability with digital output stages for aerospace fly-by-wire architectures.
- Precision Potentiometers:Wirewound or conductive plastic elements achieve ten-turn resolution below 0.1 percent for laboratory calibration equipment.
By volume, analog variants lead. By growth pace, hybrid configurations are expanding most quickly.
Application:
End-use concentration determines margin structure, with medical and aerospace commanding certification premiums over consumer tiers.
- Automotive Controls:Climate control panels and throttle-by-wire systems specify multi-turn devices for fine adjustment range exceeding 360 degrees. KBA type-approval requirements in Germany mandate electromagnetic compatibility verification.
- Industrial Automation:CNC machine tools and robotic positioning systems demand repeatability below 0.05 percent. Stuttgart-Munich automation clusters specify integrated digital interfaces as standard.
- Consumer Electronics:Audio mixing consoles and professional video equipment use cost-optimized ten-turn units.
- Audio Devices:High-fidelity amplifiers specify conductive plastic elements for low noise floor.
Industrial automation generates the highest unit values. Automotive controls dominate shipment volumes.
End User:
Procurement authority sits differently across contract types, with OEMs driving specification and distributors managing fulfillment friction.
- Manufacturers:Captive production of resistive elements and final assembly for vertical integration.
- OEMs:System integrators in medical imaging and semiconductor equipment specify custom form factors.
- Retailers:Component distributors in the DACH region pre-certify platforms against multiple standards.
- Distributors:Arrow and Avnet maintain inventory for mid-size automation integrators.
OEMs command specification authority. Distributors capture logistics value.
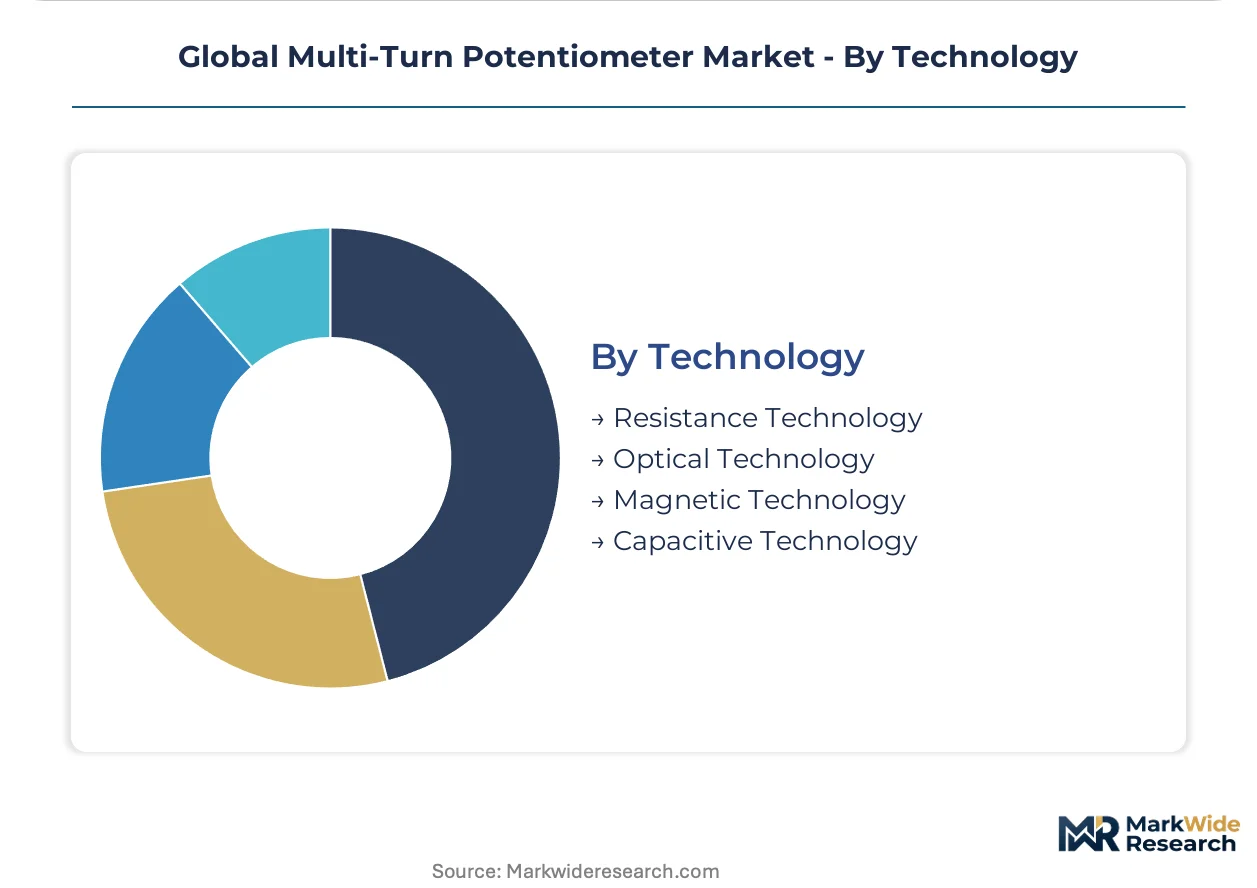
Technology:
Material science investment is fragmenting supplier capabilities between contact and contactless sensing architectures.
- Resistance Technology:Wirewound, cermet, and conductive plastic elements dominate established cost-performance tiers. REACH substance restrictions force reformulation of carbon track compositions.
- Optical Technology:Photodiode arrays and LED-based detection eliminate mechanical wear. Semiconductor metrology OEMs in Japan adopt these for sub-micron repeatability.
- Magnetic Technology:Hall-effect and magnetoresistive sensing for harsh-environment applications.
- Capacitive Technology:Contactless position detection for hermetically sealed aerospace systems.
Resistance technology retains volume leadership. Optical sensing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's dominance in precision electromechanical component manufacturing, connecting Stuttgart's machine tool clusters to Black Sea export routes.
Germany
Stuttgart-Munich industrial corridor generates sustained demand for high-linearity multi-turn devices in servo positioning applications. KBA type-approval requirements mandate electromagnetic compatibility verification for automotive throttle systems. Bavarian robotics OEMs now specify integrated digital output interfaces as standard procurement requirements.
United States
Medical device manufacturers in Greater Boston and semiconductor equipment builders in Silicon Valley drive precision potentiometer demand for sub-micron repeatability. FDA electromagnetic compatibility standards shape design verification protocols for surgical robotics integrators. Minneapolis automation clusters specify hybrid configurations for aerospace fly-by-wire applications.
Japan
Semiconductor metrology OEMs in Tokyo-Yokohama corridor adopt optical encoding technology for contactless position detection. METI industrial standards accelerate qualification of REACH-compliant resistive materials. Nagoya automotive suppliers integrate multi-turn feedback devices into CNC machine tool retrofits.
China
MIIT GB standards for industrial machinery safety reshape certification requirements for position-sensing components in autonomous production lines. Yangtze River Delta automation clusters absorb volume production of analog units for cost-sensitive climate control applications. Shenzhen electronics manufacturers source digital potentiometers for software-calibrated industrial networks.
India
Pune and Bangalore automation clusters generate localized demand pull under PLI scheme incentives for advanced manufacturing equipment. BIS certification requirements for industrial electronics extend qualification timelines for imported feedback devices. Gujarat automotive suppliers specify multi-turn potentiometers for electric vehicle throttle-by-wire systems.
Global Multi-Turn Potentiometer Market Competitive Environment
Concentration sits with vertically integrated specialists controlling resistive element manufacturing and diversified electromechanical conglomerates serving harsh-environment applications. Three archetypes define competitive positioning: precision instrumentation specialists, automotive volume suppliers, and hybrid technology integrators. Strategic moves center on backward integration into resistive material production and pre-certification of sensor platforms against multiple regional standards.
Among European-based fabricators, MENTOR and MCB industrie exemplify compact form factor specialization for space-constrained medical and aerospace instrumentation. BOURNS anchors the volume supplier archetype with in-house production of carbon and cermet resistive elements. Sensata Technologies occupies a position within the harsh-environment tier, leveraging magnetic technology leadership for industrial automation applications requiring MIL-STD-810 qualification.
| Leading Market Players |
|---|
| MENTOR |
| Celesco |
| BOURNS |
| MCB industrie |
| On Line Controls |
| MURRELEKTRONIK |
| Sensata Technologies |
| Iskra d.d. |
| Althen Sensors & Controls |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Stuttgart automation OEMs and resistive element suppliers lock in neodymium pricing visibility while insulating volume buyers from REACH-driven material reformulation cost spikes. These arrangements concentrate procurement leverage among Bavarian robotics integrators who bundle multi-turn potentiometer orders with servo system contracts.
Pricing Analysis
Volume-discount tiering separates IEC 61508-certified precision units from uncertified analog variants across the German industrial corridor. Price differentiation rests on electromagnetic compatibility verification grade and cermet material compliance status. Cost compression in standard analog tiers intensifies as digital potentiometer substitution accelerates in non-safety-critical loops. Automotive Tier-1 suppliers in Stuttgart exhibit highest price sensitivity, while aerospace fly-by-wire integrators absorb certification premiums.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp trade lanes elevates inbound logistics costs for carbon track materials sourced from East Asian chemical processors. Manufacturing concentrates in Germany, China, and Japan, with cermet resistive elements drawing from Austrian and Chinese ceramic powder suppliers. Single-source vulnerability sits with neodymium magnet feedstock for hybrid encoder configurations. Distribution runs through Arrow and Avnet hubs serving mid-size DACH region automation integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Component specification fragmentation creates niche entry points as optical encoding technology decomposes traditional electromechanical value chains across laboratory calibration and semiconductor metrology applications.
For Market Incumbents: Secure backward integration into halogen-free carbon track material production to deflect ECHA reformulation cost shocks. Anchor channel control through pre-certified sensor platforms against FDA electromagnetic compatibility and CE marking requirements. Digital potentiometer substitution in industrial automation networks threatens analog volume tiers. For New Entrants and Emerging Players: Lead with compact form factor specialization for surgical robotics OEMs in Greater Boston and Swiss medical imaging clusters. The most penetrable white space sits in hybrid configurations combining analog reliability with SPI/I2C digital interfaces for aerospace fly-by-wire retrofits. Pursue direct technical sales to Bavarian robotics OEMs bypassing distributor certification markups. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with in-house resistive element production and established MIL-STD-810 qualification pathways. Long-term viability over the analysis window favors suppliers controlling cermet material formulations amid REACH substance restrictions. Monitor IEC 61508 revision timelines as inflection indicators for safety instrumented system qualification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resistive Materials | Captive cermet production insulates BOURNS from ECHA reformulation cost volatility. |
| Pre-Certification Against Multiple Standards | Distributors in the DACH region reduce procurement friction for mid-size integrators. |
| Optical Encoding Technology Transition | Contactless photodiode arrays extend operational life beyond ten million cycles. |
| Hybrid Configuration Development | Combining analog sensing with digital bus interfaces opens aerospace specification white space. |
| Compact Form Factor Miniaturization | MENTOR targets space-constrained FDA-regulated surgical robotics applications. |
Study Parameters
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings. Conversations with automation OEM procurement teams, resistive element plant managers, distributor technical sales directors, and aerospace qualification engineers combined with ECHA substance restriction databases, IEC standard revision drafts, FDA electromagnetic compatibility guidance documents, and KBA type-approval records. Bottom-up shipment estimates from German automotive Tier-1 suppliers triangulate against top-down industrial automation capex forecasts.
Sensitivity analysis around neodymium price volatility and REACH compliance cost trajectories shapes the projection framework. Segmentation dimensions span product architecture, application criticality, end-user procurement authority, and sensing technology material base. CAGRs derive from installed base replacement cycles and autonomous production line adoption curves across the modeling period. Forecast inputs incorporate Stuttgart-Munich machine tool cluster demand patterns and India PLI scheme localization incentives.
The analysis sits within stated boundaries; outcomes outside sustained industrial automation capex growth and stable ECHA regulatory timelines would require recalibration. Forecasts reflect assumptions around optical encoding cost parity achievement and hybrid potentiometer aerospace qualification velocity. Semiconductor metrology capital expenditure softness or magnetic encoder technology breakthroughs could revise trajectory projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Electric Pipette Controllers Market
Sensors and Controls
Global Ultrasonic Gas Leak Detector Market
Sensors and Controls
Asia-Pacific MEMS and Sensors Market
Sensors and Controls
Global Pyrometer Market
Sensors and Controls
Europe Sensors Market
Sensors and Controls
MEMS Microphones Market
Sensors and Controls
Body Worn Temperature Sensors Market
Sensors and Controls
Wired Occupancy Sensors Market
Sensors and Controls
UV Sensors Market
Sensors and Controls
Water Cut Monitor Market
Sensors and Controls
Piezoelectric Sensor Market
Sensors and Controls
Ambient Light Sensor Market
Sensors and Controls
2D Gesture Recognition Market
Sensors and Controls
Collision Sensors Market
Sensors and Controls
Global Hall Effect Current Sensor Market
Sensors and Controls
PID Controller Market