
 Fibert Market | 2026-2036
Fibert Market Size, Share, and Industry Trends Forecast 2026-2036
Fibert Market Foresight
The gap between premium optical fiber and commodity plastic fiber is repositioning procurement patterns across telecom and industrial verticals. Corning Incorporated leverages its fused silica manufacturing depth to command premium pricing in data center interconnects. Prysmian Group anchors European supply through submarine and terrestrial cable integration. Sumitomo Electric Industries dominates specialty fiber for medical and sensing applications with proprietary pure-glass preform technology.
Fibert encompasses engineered filament structures—glass optical fiber with core diameters of 8-10 microns for single-mode transmission, or plastic optical fiber with 1 mm cores for short-reach flexibility—manufactured via modified chemical vapor deposition or extrusion processes to guide light across telecommunications, sensing, and illumination systems. Optical fiber leads value generation as submarine and long-haul networks require ultra-low attenuation below 0.2 dB per kilometer, while fiber optic cables for data centers represent the fastest-expanding margin pool driven by hyperscaler buildouts. Plastic fiber occupies a mature niche in automotive and consumer electronics where cost tolerance overrides performance thresholds.
FCC broadband equity programs in the United States, the EU Green Deal digital infrastructure targets, and China's MIIT gigabit city mandates collectively shape deployment timelines and product certification requirements across three continents. ISO/IEC 11801 and ITU-T G.652 standards constrain interoperability and limit vendor switching for network operators. Stakeholders must monitor regulatory divergence between EU CE marking for environmental compliance and FCC Part 68 terminal equipment rules as procurement specifications fragment across jurisdictions.
Market Dynamics
AI workload density in hyperscale data centers is compressing fiber deployment cycles from multi-year infrastructure projects to 18-month capacity expansions, forcing suppliers to synchronize manufacturing with cloud capital expenditure waves rather than traditional telecom buildouts.
Growth Catalysts
- EU Green Deal digital infrastructure targets:Mandated fiber-to-the-home rollouts across Germany, France, and Italy are accelerating municipal procurement timelines and standardizing open-access network architectures.
- Hyperscaler data center interconnect demand:Amazon Web Services, Microsoft Azure, and Google Cloud are deploying multi-terabit coherent optical systems requiring ultra-low-loss single-mode fiber between facilities.
- China MIIT gigabit city mandates:Provincial governments in Jiangsu and Guangdong are subsidizing fiber drops to residential complexes, anchoring volume consumption for domestic preform manufacturers.
Market Restraints
- High-purity silicon tetrachloride feedstock volatility:Semiconductor-grade chemical supply constraints in Japan and Germany are inflating preform production costs for specialty fiber grades.
- Submarine cable supply concentration:Only three cable-lay vessel operators control deep-water installation capacity, creating 24-month order backlogs for transoceanic routes.
- Plastic optical fiber performance ceiling:1 mm core diameter limits transmission to 100 meters at gigabit speeds, blocking entry into enterprise backbone applications.
Strategic Opportunities
- Rural broadband underpenetration in India:BharatNet Phase III targets 100,000 gram panchayats with optical fiber, opening tender volumes for cable integrators willing to localize assembly.
- Fiber sensing convergence with structural health monitoring:Distributed acoustic sensing for oil pipelines and railway tracks is merging telecom fiber expertise with industrial IoT deployment models.
- US FCC Broadband Equity, Access, and Deployment program:USD 42.5 billion in competitive grants is redirecting procurement toward open-access middle-mile networks in underserved counties.
Industry Challenges
- Specialized fusion splicer technician scarcity:Single-mode alignment tolerances below 0.1 degrees require certified operators, and training pipelines lag deployment schedules by 18-24 months.
- Multi-jurisdiction certification fragmentation:EU CE marking for environmental compliance diverges from FCC Part 68 terminal equipment rules, forcing dual testing protocols for transatlantic suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fibert Market |
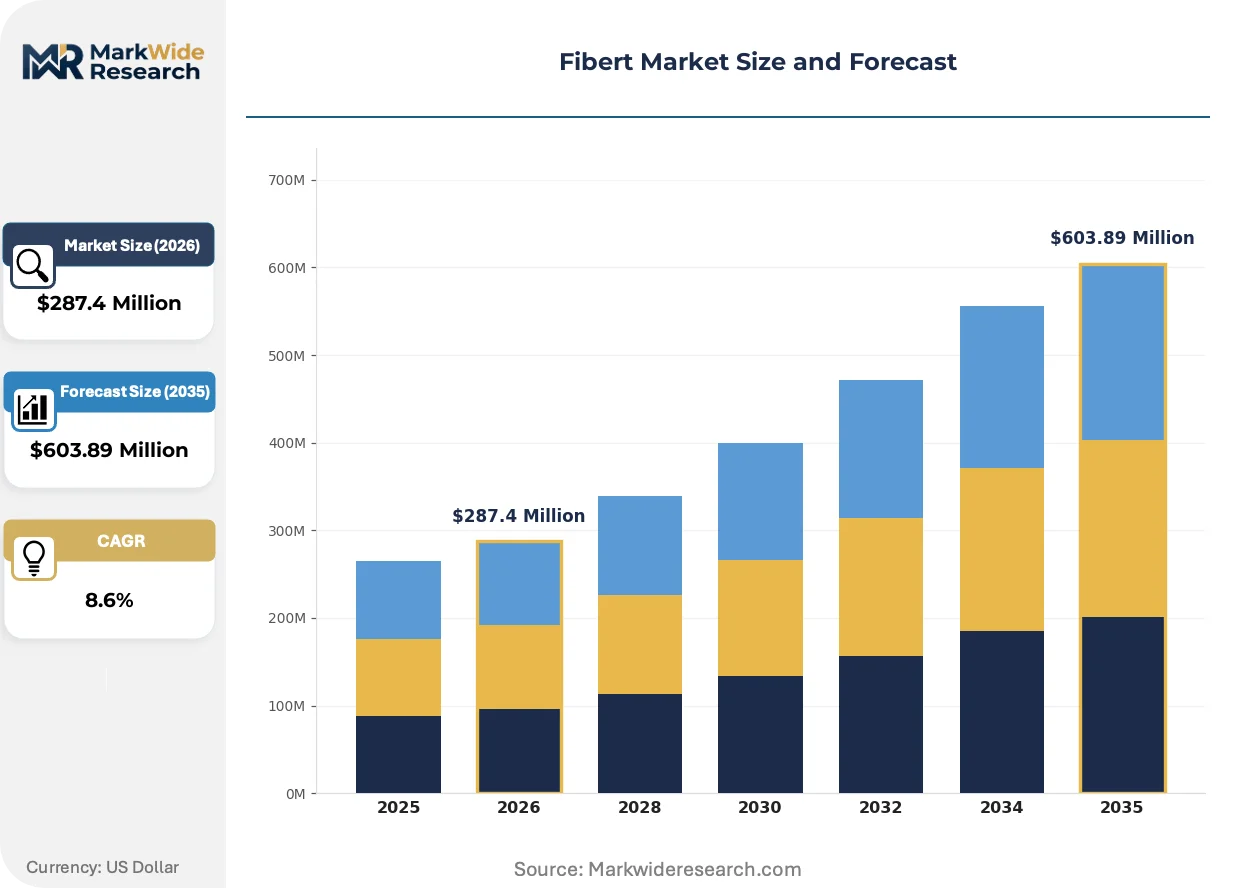
| Market Size in 2026 | $287.4 Million |
| Market Size in 2035 | $603.89 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Fiber, Fiber Optic Cables, Plastic Fiber, Specialty Cables Application: Telecommunication, Data Centers, Medical Devices, Industrial Automation End User: Telecom Providers, Healthcare Facilities, Manufacturing Plants, IT Companies Material: Glass, Plastic, Carbon Fiber, Synthetic Polymers |
| Companies Covered | Corning Incorporated, Prysmian Group, Sumitomo Electric Industries, Yangtze Optical Fibre and Cable, Fujikura, Furukawa Electric, LS Cable & System, Hengtong Group, LEONI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fibert Market Shifts & Advancements
Hollow-core fiber architecture is collapsing latency benchmarks for financial trading and high-performance computing, while regulatory pressure on embodied carbon is rewriting material specifications for cable sheathing and deployment practices.
Photonic-bandgap hollow-core fiber is electrifying latency-sensitive applications by guiding light through air rather than glass, reducing signal delay by 30% compared to conventional silica. Chicago Mercantile Exchange and Frankfurt Stock Exchange co-location facilities are piloting installations for algorithmic trading. This architecture is electrifying competitive positioning among specialty fiber houses capable of manufacturing kilometer-length segments with sub-decibel loss.
The EU F-Gas Regulation phase-down on fluorinated greenhouse gases is banning sulfur hexafluoride use in medium-voltage cable terminations, forcing manufacturers to redesign gas-insulated switchgear for fiber-powered grid monitoring. Prysmian and Nexans are accelerating dry-cable designs with synthetic insulation. Submarine cable projects in the North Sea and Baltic are most affected, with environmental impact assessments now mandatory for landing permits.
Hyperscalers are consolidating optical transceiver procurement through direct sourcing agreements with fiber preform suppliers, bypassing traditional cable distributor networks. Amazon and Microsoft now specify fiber attenuation and dispersion parameters in master service agreements rather than accepting standard product catalogs. This pattern is most visible in Northern Virginia and Frankfurt data center clusters, where direct contracting has compressed distributor margins by 40% in three years.
Fibert Market Segmentation
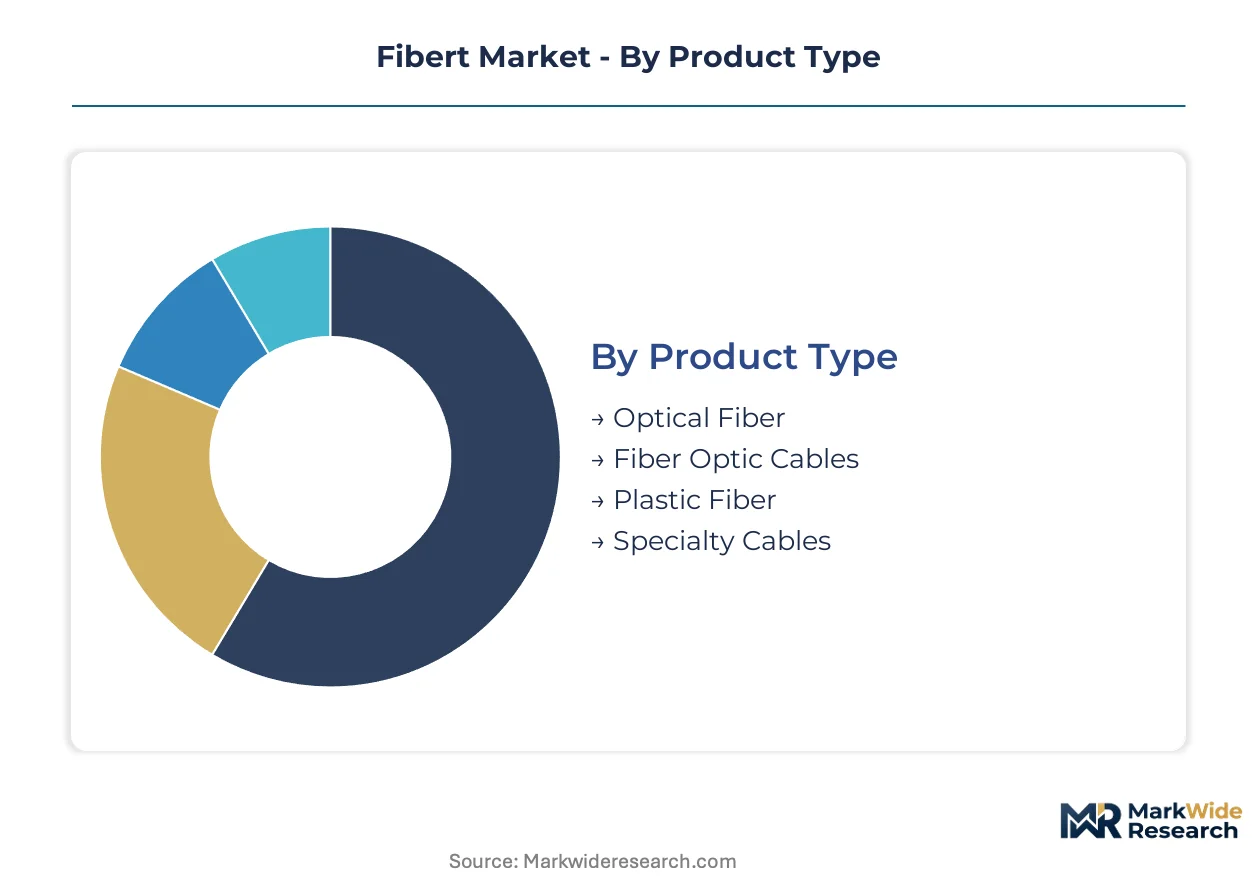
Segmentation in the Fibert Market reveals divergent margin structures across material purity grades and deployment environments. Procurement specifications from hyperscalers, healthcare regulators, and industrial automation integrators fragment demand into distinct technical tiers with incompatible certification requirements.
Product Type:
Technology specifications define performance ceilings and deployment economics across filament architectures.
- Optical Fiber:Fused silica cores with germanium-doped cladding achieve attenuation below 0.2 dB per kilometer for submarine and long-haul networks. Demand concentrates in China where MIIT gigabit city mandates subsidize residential fiber drops, anchoring volume consumption for domestic preform manufacturers.
- Fiber Optic Cables:Bundled fiber assemblies with protective sheathing and strength members for terrestrial and subsea installation. Hyperscaler data center interconnects in Northern Virginia and Frankfurt clusters are expanding multi-terabit coherent optical systems, compressing deployment cycles to 18-month capacity expansions.
- Plastic Fiber:Polymethyl methacrylate cores with 1 mm diameter enable short-reach flexibility at cost points incompatible with glass alternatives. Automotive interior lighting and consumer electronics remain mature niches where performance thresholds are secondary to manufacturing simplicity.
- Specialty Cables:Custom-engineered assemblies for radiation-hardened, high-temperature, or chemically resistant environments. Nuclear power instrumentation and downhole oil sensing drive specification complexity.
Optical Fiber leads on scale; Fiber Optic Cables lead on momentum.
Application:
End-use environments impose distinct mechanical, thermal, and regulatory constraints on filament selection.
- Telecommunication:Metropolitan and access networks requiring ITU-T G.652 standard compliance for interoperability. EU Green Deal digital infrastructure targets in Germany, France, and Italy are accelerating municipal procurement timelines for fiber-to-the-home rollouts.
- Data Centers:Hyperscale facilities demand ultra-low-loss single-mode fiber for spine-leaf architectures and campus interconnects. Amazon Web Services, Microsoft Azure, and Google Cloud direct sourcing agreements now specify attenuation and dispersion parameters in master service agreements.
- Medical Devices:Biocompatible fiber for endoscopic illumination and laser surgical systems. ISO 10993 and US FDA 510(k) pathways constrain material selection and sterilization compatibility.
- Industrial Automation:Ruggedized fiber for electromagnetic interference immunity in robotic control and process monitoring. Factory floor vibration tolerance and chemical exposure resistance differentiate specifications from commercial telecom grades.
Telecommunication dominates installed base; Data Centers exhibit the steepest expansion trajectory.
End User:
Procurement sophistication and technical specification authority vary sharply across customer categories.
- Telecom Providers:Incumbent operators and competitive local exchange carriers with network engineering teams capable of specifying preform purity and cable tensile strength. Open-access network mandates in EU member states are standardizing wholesale procurement frameworks.
- Healthcare Facilities:Hospital systems and outpatient surgical centers prioritizing single-use disposability and sterilization validation. Reimbursement coding for minimally invasive procedures shapes volume forecasts.
- Manufacturing Plants:Automotive, chemical, and electronics producers deploying fiber for machine vision and distributed sensing. Operational technology teams specify ingress protection ratings and connector ruggedization.
- IT Companies:Cloud service providers and colocation operators with capital expenditure cycles synchronized to AI workload density. Direct contracting with preform suppliers has compressed traditional distributor margins by 40% in three years.
Telecom Providers anchor volume commitments; IT Companies are gaining share fastest in value terms.
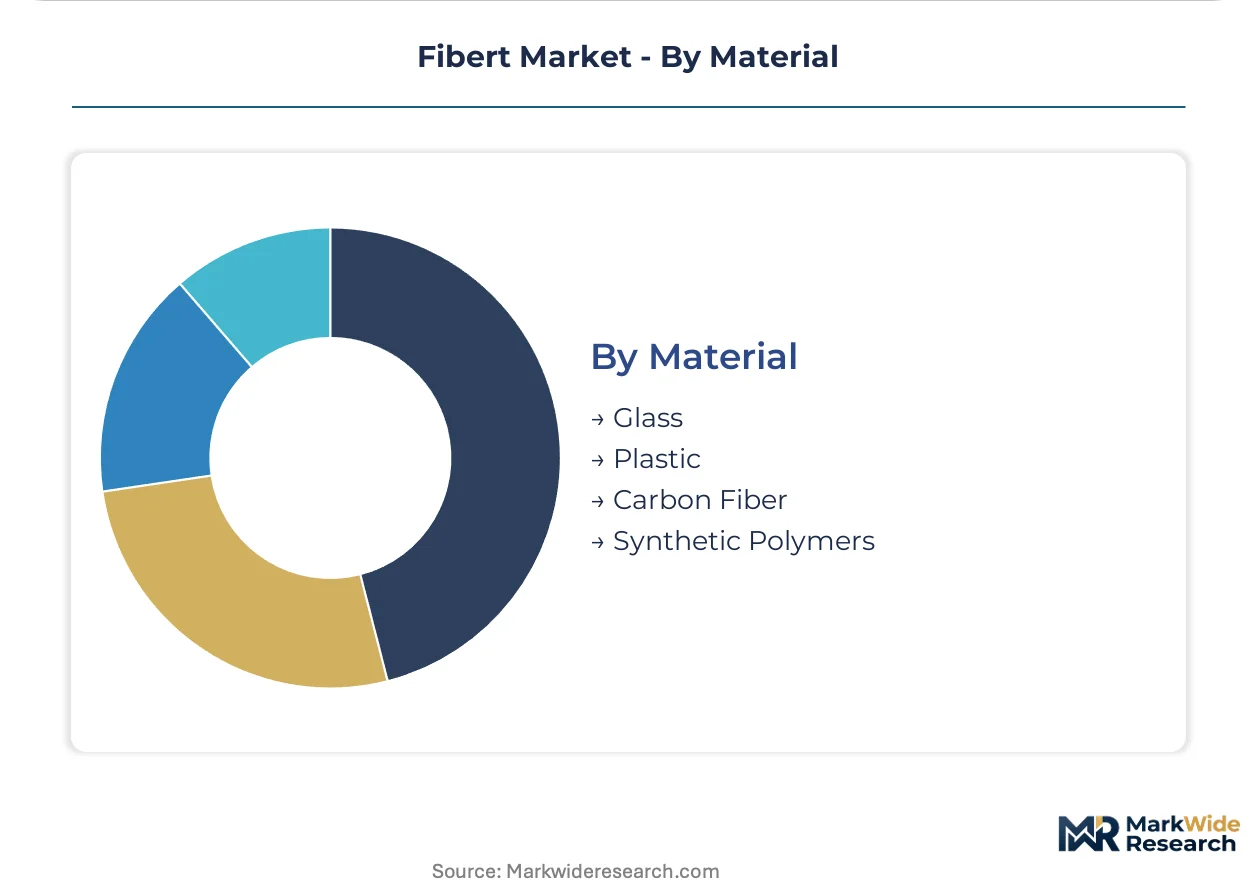
Material:
Substrate chemistry determines optical performance, mechanical durability, and environmental compliance profiles.
- Glass:High-purity silicon dioxide with controlled dopant profiles for refractive index engineering. Semiconductor-grade silicon tetrachloride feedstock constraints in Japan and Germany are inflating preform production costs for specialty grades.
- Plastic:Polymer matrices enabling large-core diameters and bend tolerance at transmission distance penalties below 100 meters. EU F-Gas Regulation phase-down on fluorinated greenhouse gases is forcing redesign of gas-insulated switchgear for fiber-powered grid monitoring.
- Carbon Fiber:Reinforcement elements for strength members and composite cable structures rather than optical transmission. Submarine cable armoring and aerial messenger wires exploit tensile strength-to-weight ratios.
- Synthetic Polymers:Jacketing and buffer materials including polyethylene, polyvinyl chloride, and low-smoke zero-halogen compounds. CE marking environmental compliance diverges from FCC Part 68 terminal equipment rules, forcing dual testing protocols for transatlantic suppliers.
Glass commands premium positioning; Synthetic Polymers face regulatory-driven specification churn.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fusion splicer technicians cluster in Germany, Japan, and the United States, creating regional bottlenecks as deployment schedules outpace training pipelines by 18-24 months.
United States
Hyperscaler data center interconnects in Northern Virginia and Dallas-Fort Worth are compressing fiber deployment cycles to 18-month capacity expansions. The FCC Broadband Equity, Access, and Deployment program directs USD 42.5 billion toward open-access middle-mile networks in underserved counties. Chicago Mercantile Exchange co-location facilities are piloting hollow-core fiber installations for algorithmic trading latency reduction.
China
Provincial governments in Jiangsu and Guangdong are subsidizing fiber drops to residential complexes under MIIT gigabit city mandates. Yangtze Optical Fibre and Cable and Hengtong Group anchor domestic preform manufacturing capacity. The Yangtze River Delta concentration of cable integrators is synchronizing output with cloud capital expenditure waves from Alibaba Cloud and Tencent.
Germany
EU Green Deal digital infrastructure targets are accelerating municipal procurement timelines for fiber-to-the-home rollouts across Bavaria and North Rhine-Westphalia. CE marking environmental compliance requirements are diverging from FCC Part 68 terminal equipment rules. Prysmian Group's submarine and terrestrial cable integration anchors European supply from its Milan headquarters with German manufacturing depth.
Japan
Semiconductor-grade silicon tetrachloride feedstock constraints are inflating preform production costs for specialty fiber grades. METI industrial policy supports domestic pure-glass preform technology development. Sumitomo Electric Industries dominates specialty fiber for medical and sensing applications from its Osaka-Kobe manufacturing cluster.
India
BharatNet Phase III targets 100,000 gram panchayats with optical fiber backbone infrastructure. TRAI open-access framework mandates are standardizing wholesale procurement for rural broadband underpenetration. Cable integrators in Gujarat and Maharashtra are localizing assembly to capture tender volumes from the Department of Telecommunications.
Fibert Market Competitive Landscape
Top-tier vendors anchor premium single-mode fiber for submarine and data center interconnects, while mid-tier fabricators compete on volume for terrestrial telecom and access networks. The vendor base stratifies across fused silica manufacturing depth, submarine cable integration capability, and specialty fiber pure-glass preform technology. Three archetypes dominate: integrated preform-to-cable operators, specialty fiber houses, and regional volume suppliers. Capacity expansion and direct hyperscaler contracting represent the dominant competitive moves.
Within the integrated preform-to-cable tier, Corning Incorporated, Prysmian Group, and Yangtze Optical Fibre and Cable exemplify scale-driven positioning. Corning occupies a position representing North American fused silica manufacturing depth. Prysmian exemplifies European submarine and terrestrial integration. Yangtze Optical Fibre and Cable anchors Chinese domestic volume consumption under MIIT policy alignment.
| Leading Market Players |
|---|
| Corning Incorporated |
| Prysmian Group |
| Sumitomo Electric Industries |
| Yangtze Optical Fibre and Cable |
| Fujikura |
| Furukawa Electric |
| LS Cable & System |
| Hengtong Group |
| LEONI |
| Others |
Supply & Pricing Matrix
Hollow-core fiber manufacturing scale-up is compressing cost curves for latency-sensitive applications while concentrating preform supply among fused silica specialists with vapor deposition mastery. This technology transition simultaneously elevates premium-tier pricing power for specialty fiber houses and squeezes commodity-grade margins as hyperscalers consolidate procurement through direct preform contracts.
Pricing Analysis
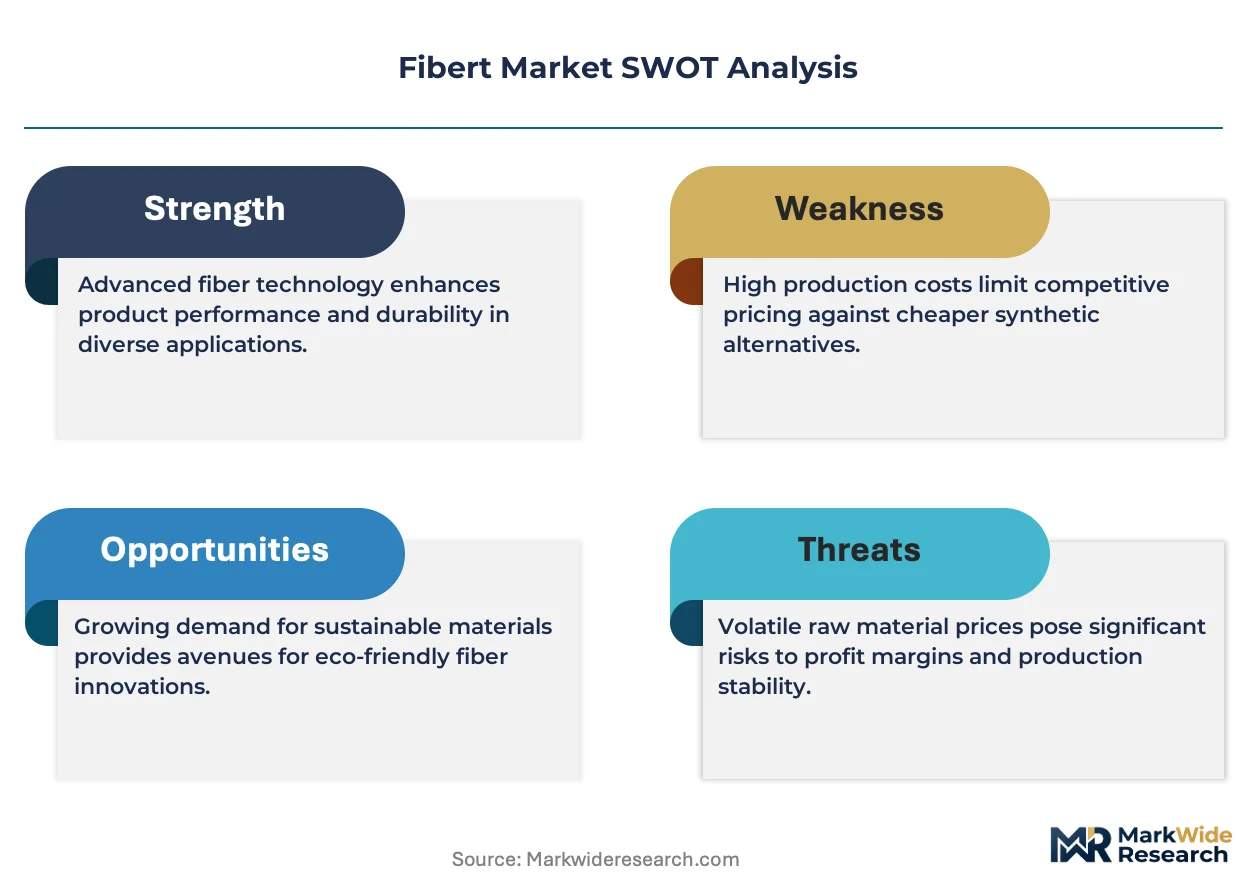
Bundled cable-and-installation services command substantial premiums over unbundled fiber strand transactions, particularly in submarine and data center interconnect deployments. Three-tier pricing structure across premium low-attenuation single-mode, standard ITU-T G.652 compliant, and economy plastic fiber grades reflects certification level and volume scale differentiation. Pricing pressure stems from hyperscaler direct sourcing agreements that have compressed distributor margins significantly. Telecom providers exhibit highest price sensitivity due to open-access network mandates, while IT companies prioritize performance specifications over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from hyperscalers and submarine cable consortiums mandate multi-supplier qualification for preform and cable-lay capacity, fragmenting procurement across qualified vendors. Geographic supply concentration centers on China, Japan, and Germany for semiconductor-grade silicon tetrachloride feedstock and pure-glass preform manufacturing. Raw material dependencies rest on high-purity silicon dioxide, germanium tetrachloride dopants, and synthetic polymer jacketing compounds. Single-source vulnerability in deep-water cable-lay vessel capacity creates structural bottlenecks for transoceanic routes. Distribution runs through integrated preform-to-cable operators for premium tiers and regional volume suppliers for terrestrial access networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on hollow-core fiber premium-tier adoption displacing conventional silica in latency-sensitive applications, coupled with feedstock cost compression as Chinese preform manufacturers achieve vapor deposition scale.
For Market Incumbents: Cement data center interconnect market share through captive supply of ultra-low-loss single-mode fiber to hyperscaler direct sourcing programs. Prysmian and Corning must defend against Chinese preform manufacturers achieving ITU-T G.652.D certification equivalence by accelerating hollow-core fiber commercialization and locking multi-year submarine cable installation contracts before vessel capacity constraints ease. For New Entrants and Emerging Players: FCC Broadband Equity, Access, and Deployment program in the United States opens a window for regional cable integrators to capture open-access middle-mile tender volumes in underserved counties. Target rural broadband deployment in India under BharatNet Phase III through localized assembly partnerships in Gujarat and Maharashtra. Enter through fiber sensing convergence with structural health monitoring for oil pipelines and railway tracks, leveraging telecom fiber expertise without competing head-to-head with incumbent preform suppliers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier cable assemblers lacking preform manufacturing depth but possessing established hyperscaler relationships and regional installation capabilities. Long-term viability favors integrated preform-to-cable operators with hollow-core fiber R&D pipelines and submarine cable-lay vessel access. Monitor hyperscaler capital expenditure cycle inflections as the primary demand signal, with direct contracting patterns indicating pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Preform Manufacturing | Captive silicon tetrachloride supply secures margin control against Japanese and German feedstock volatility. |
| Hollow-Core Fiber Commercialization | Photonic-bandgap architecture commands 30% latency reduction premiums from Chicago Mercantile Exchange and Frankfurt Stock Exchange co-location facilities. |
| Submarine Cable-Lay Vessel Acquisition | Deep-water installation capacity ownership breaks 24-month order backlogs controlled by three global operators. |
| Direct Hyperscaler Master Service Agreements | Amazon Web Services and Microsoft Azure procurement bypasses distributor networks and locks multi-terabit coherent optical specifications. |
| Fiber Sensing Industrial IoT Partnerships | Distributed acoustic sensing for oil pipelines merges telecom fiber expertise with structural health monitoring deployment models. |
Research Methodology
Multiple input streams — hyperscaler capital expenditure disclosures, submarine cable consortium procurement records, and MIIT gigabit city subsidy filings — were reconciled against primary interviews with fiber preform manufacturing executives, data center network engineering directors, and submarine cable-lay vessel operators. Secondary validation drew from ITU-T standards documentation, EU Green Deal digital infrastructure target announcements, and FCC Broadband Equity program grant allocations. Bottom-up fiber strand volume estimates and top-down cable assembly value projections were triangulated to constrain forecast variance.
Historical hyperscaler deployment cycles were cross-referenced against panel input from cloud infrastructure procurement specialists to model capacity expansion timing. Segmentation dimensions across the modeling period included material purity grade, deployment environment, and end-user procurement sophistication tier. CAGRs were derived from fiber-to-the-home rollout velocity in EU member states, MIIT gigabit city mandate progressions, and AI workload density trajectories in hyperscale facilities. Industry-specific forecast inputs incorporated silicon tetrachloride feedstock availability constraints and hollow-core fiber manufacturing yield improvements.
Revisions become necessary when semiconductor-grade chemical supply disruptions in Japan or Germany materialize, or when hyperscaler direct sourcing patterns accelerate beyond historical distributor displacement rates. Forecasts reflect assumptions regarding EU Green Deal implementation timelines, FCC grant disbursement velocities, and Chinese provincial subsidy continuity. Deviation in cable-lay vessel capacity expansion or hollow-core fiber kilometer-length loss specifications would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Agitation System Market
Others
Language Translation Device Market
Others
Global Injectable Nanomedicine Market
Others
Exosome Technologies Market
Others
Rotary Dial Machine Market
Others
North America 3D Printing Construction Market
Others
Magnesite Market
Others
Digital Thermal Plates Market
Others
Tanned Fish Skin Leather Market
Others
Global Animal Feed Protein Ingredients Market
Others
Africa Smart Card Market
Others
Bio-Based Leather Market
Others
Mini Pcs Market
Others
Paraffin Physical Therapy Market
Others
Spain Feed Additives Market
Others
Enterprise Video Content Management Market