
 Live IP Broadcast Equipment Market | 2026-2036
Live IP Broadcast Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Live IP Broadcast Equipment Market Outlook
Software-defined feature licensing is pivoting vendor economics away from hardware-centric sales toward recurring revenue models. Cisco Systems leverages its networking infrastructure dominance to bundle IP transport with broadcast control layers. Grass Valley sustains R&D intensity in edge-processing cameras and production switchers. Harmonic differentiates through cloud-native media processing platforms that compress distribution costs for streaming platforms.
Live IP broadcast equipment comprises networked hardware and software systems that transmit uncompressed or lightly compressed video, audio, and metadata over Internet Protocol infrastructure rather than traditional baseband coaxial or fiber circuits. These systems typically operate at 10Gbps to 100Gbps Ethernet speeds with precision timing via PTP IEEE 1588 to maintain frame-accurate synchronization across distributed production environments. Encoders represent the fastest-expanding product category as broadcasters migrate MPEG-2 and H.264 workflows toward HEVC and AV1 compression for bandwidth efficiency. NDI technology captures growing share among content creators and corporate video departments seeking low-latency contribution over standard IT networks without dedicated broadcast infrastructure.
The Federal Communications Commission shapes US market access through spectrum allocation and ATSC 3.0 next-generation broadcast standards, while the European Telecommunications Standards Institute and EBU drive interoperability frameworks across European deployments. China's Ministry of Industry and Information Technology governs GB standards for ultra-high-definition transmission over IP networks, creating compliance thresholds for imported equipment. Stakeholders must monitor which regulatory bodies adopt ST 2110 versus proprietary IP protocols, as this determination locks in supplier ecosystems and replacement cycles across major broadcast infrastructure investments.
Market Dynamics
The migration from SDI baseband to SMPTE ST 2110 IP workflows is compressing replacement cycles and forcing broadcast infrastructure buyers to requalify entire supplier ecosystems simultaneously.
Growth Catalysts
- ATSC 3.0 Next-Gen TV Mandates:The FCC's spectrum repack and next-generation broadcast standard is compelling US station groups to rebuild transmission chains around IP-native architectures rather than hybrid SDI-IP bridges.
- Remote Production Architectures:Sports leagues and live entertainment producers are distributing camera and switching operations across geographic nodes to reduce on-site crew footprints and venue costs.
- HEVC and AV1 Codecs:Streaming platforms are upgrading contribution and distribution encoders to advanced compression formats, triggering hardware refresh cycles in master control and playout facilities.
Market Restraints
- Precision Timing Hardware Costs:IEEE 1588 PTP grandmaster clocks and boundary switches add 15-25% to infrastructure budgets versus genlocked SDI equivalents, slowing mid-market station upgrades.
- Single-Source Silicon Dependencies:Merchant switch ASICs and FPGA supply for 25G/100G Ethernet interfaces concentrate among three US and Taiwanese semiconductor suppliers, creating allocation risk during demand spikes.
- Proprietary Protocol Lock-In:Several camera and intercom vendors maintain closed IP transport implementations that fragment interoperability and extend integration timelines.
Strategic Opportunities
- Cloud-Native Playout in India:TRAI's infrastructure sharing guidelines and the country's expanding fiber backbone create entry points for virtualized master control and disaster recovery services.
- 5G Network Slicing:Broadcasters in Germany and South Korea are testing guaranteed-bandwidth slices for wireless camera backhaul and field contribution, bypassing satellite truck economics.
- Edge Processing Cameras:Cameras with onboard HEVC encoding and AI-driven metadata extraction reduce backhaul bandwidth requirements for live remote productions.
Industry Challenges
- PTP Timing Expertise Scarcity:Broadcast engineering teams lack depth in IEEE 1588 network design, forcing reliance on systems integrators for IP facility builds and slowing in-house troubleshooting.
- Hybrid Facility Complexity:Stations operating parallel SDI and IP routing layers during transition periods face doubled maintenance overhead and signal monitoring fragmentation.
- ST 2110 Certification Bottlenecks:Equipment validation against SMPTE compliance test suites creates 6-12 month product launch delays for smaller vendors.
Report Scope
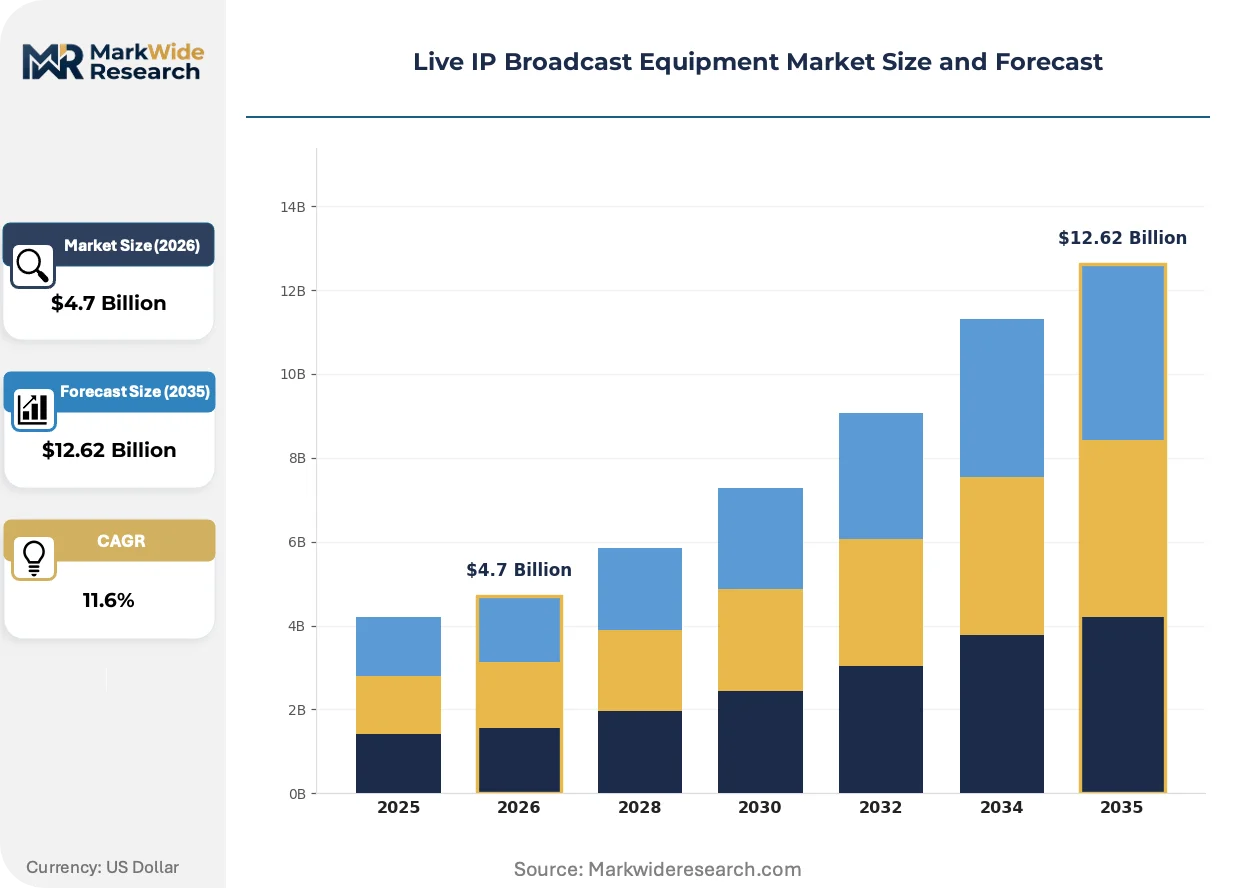
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Live IP Broadcast Equipment Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.62 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switchers, Routers, Video Servers, Encoders Technology: HDMI, SDI, NDI, RTP End User: Television Broadcasters, Streaming Platforms, Event Organizers, Content Creators Application: Live Streaming, Sports Broadcasting, News Coverage, Remote Production |
| Companies Covered | Cisco Systems, Grass Valley, Harmonic, Evertz Microsystems, Sony, EVS Broadcast Equipment, AJA Video Systems, Ross Video, NewTek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Live IP Broadcast Equipment Market Strategic Shifts
Compression efficiency gains, regulatory mandates for next-generation broadcasting, and disaggregated procurement models are restructuring how live IP infrastructure is specified, financed, and deployed.
Software-defined media processing is converging with commodity server hardware to displace purpose-built broadcast appliances. Major streaming platforms and national broadcasters in the United States and United Kingdom are deploying GPU-accelerated encoding farms on standard x86 infrastructure. This convergence is collapsing the historical premium between broadcast-grade and IT-grade equipment procurement.
The European Union's CSRD sustainability disclosure requirements are forcing equipment manufacturers to document supply chain carbon intensity and design for modularity. Broadcast infrastructure OEMs serving EBU member organizations must now provide replaceable sub-assemblies rather than monolithic chassis replacements. German and French public broadcasters are inserting circular economy clauses into technical tenders.
Buyers are unbundling hardware acquisition from software licensing and maintenance contracts. Large station groups in the United States are negotiating enterprise-wide codec licenses separate from encoder box purchases, then sourcing white-label hardware through distribution. This behavior is most visible among Nexstar and Sinclair-scale operators consolidating vendor management across dozens of local markets.
Live IP Broadcast Equipment Market Segmentation
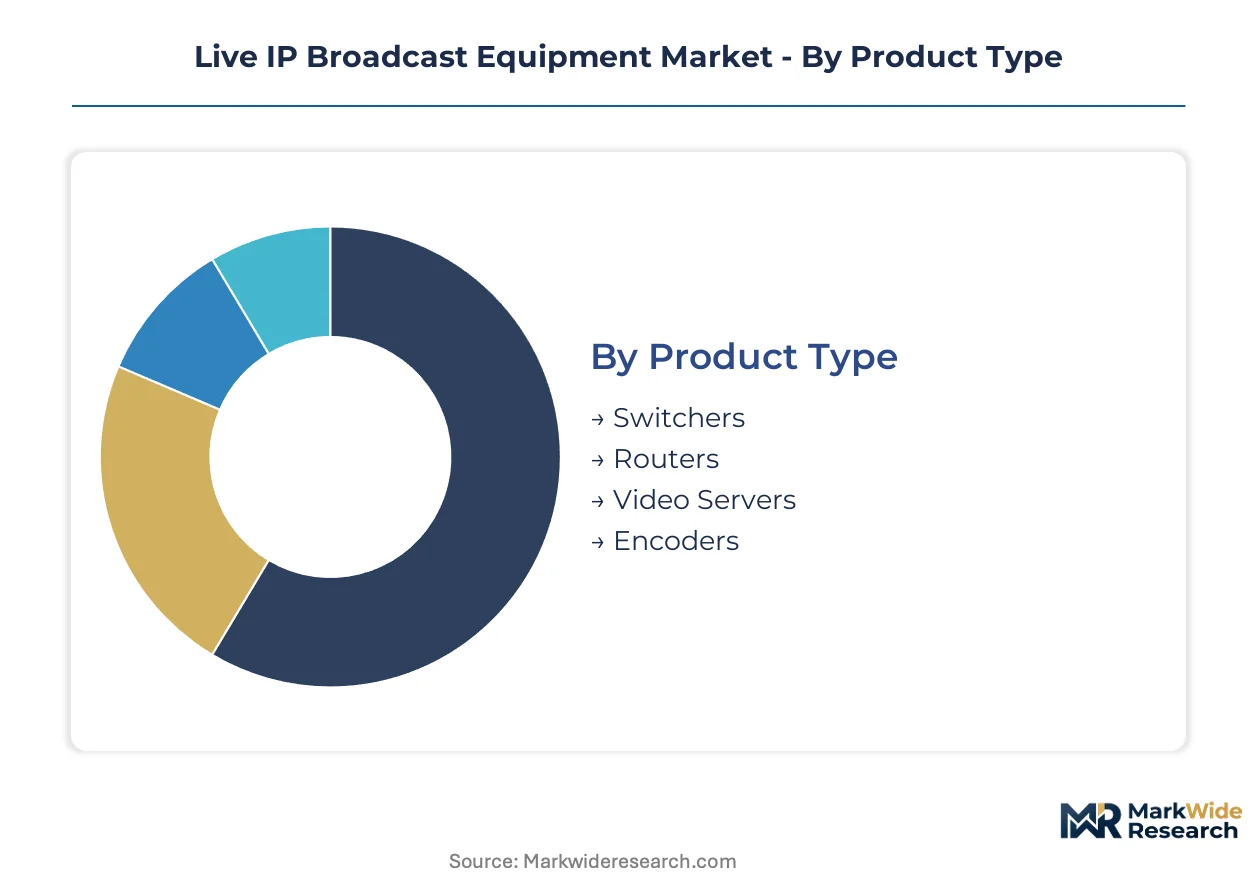
Live IP broadcast equipment procurement patterns diver sharply by integration depth. Standalone systems serve facility rebuilds while embedded modules slip into existing IT infrastructure, reshaping vendor sales cycles and support obligations across each segment category.
Product Type:
Standalone chassis dominate facility builds; blade-based modules integrate into data center racks for cloud-adjacent workflows.
- Switchers:Production switchers combine video mixing, keying, and graphics layering in 1-5 M/E configurations. Demand clusters with ESPN-scale sports networks and national broadcasters in the United States rebuilding master control around ST 2110. These buyers prioritize frame-accurate transitions over density.
- Encoders:Hardware encoding appliances compress baseband signals into HEVC or AV1 streams for contribution and distribution. Streaming platforms in China and Germany are refreshing encoder farms to reduce bandwidth costs per subscriber. The shift from MPEG-2 to advanced codecs accelerates replacement timelines.
- Routers:IP routing fabrics manage signal distribution across 10Gbps to 100Gbps Ethernet backbones with PTP timing.
- Video Servers:Playout servers store and retrieve compressed or uncompressed content for frame-accurate broadcast output.
Volume placements concentrate in Encoders; the faster expansion belongs to Switchers.
Technology:
Legacy interfaces persist in retrofit budgets; native IP protocols capture greenfield spend.
- NDI:Network Device Interface transmits compressed video over standard Gigabit Ethernet without dedicated broadcast infrastructure. Corporate video departments and houses of worship in Germany adopt NDI for multi-camera live production without SDI cabling. Low cost and software ecosystem breadth drive penetration.
- RTP:Real-time Transport Protocol carries uncompressed or lightly compressed streams with precision timing via PTP. Broadcasters in China deploying 4K/8K channels favor RTP for its deterministic latency and SMPTE compliance. Regulatory pressure for ultra-high-definition transmission favors this stack.
- HDMI:Consumer-grade interface persists in prosumer and entry-level live production kits.
- SDI:Serial Digital Interface remains entrenched in hybrid facilities bridging baseband and IP layers.
SDI still commands the largest installed base; NDI is climbing the fastest among new deployments.
End User:
Capital intensity separates facility owners from rental-dependent operators.
- Streaming Platforms:Subscription video services operate hyperscale encoding and packaging farms with continuous refresh cycles. Netflix-scale operators in the United States and China deploy software-defined transcoding on commodity servers. Their procurement favors OPEX-heavy licensing over CAPEX-heavy hardware.
- Television Broadcasters:Station groups and national networks maintain transmission chains with 15-20 year asset lifecycles. Public broadcasters in Germany and commercial groups in the United States are rebuilding for ATSC 3.0 and DVB-T2. Regulatory mandates compress their decision timelines.
- Event Organizers:Rental houses and live production companies favor portable flypack systems for temporary deployments.
- Content Creators:Individual producers and small studios prioritize NDI-enabled software workflows over dedicated hardware.
Television Broadcasters anchor volume demand; Streaming Platforms show the steepest expansion trajectory.
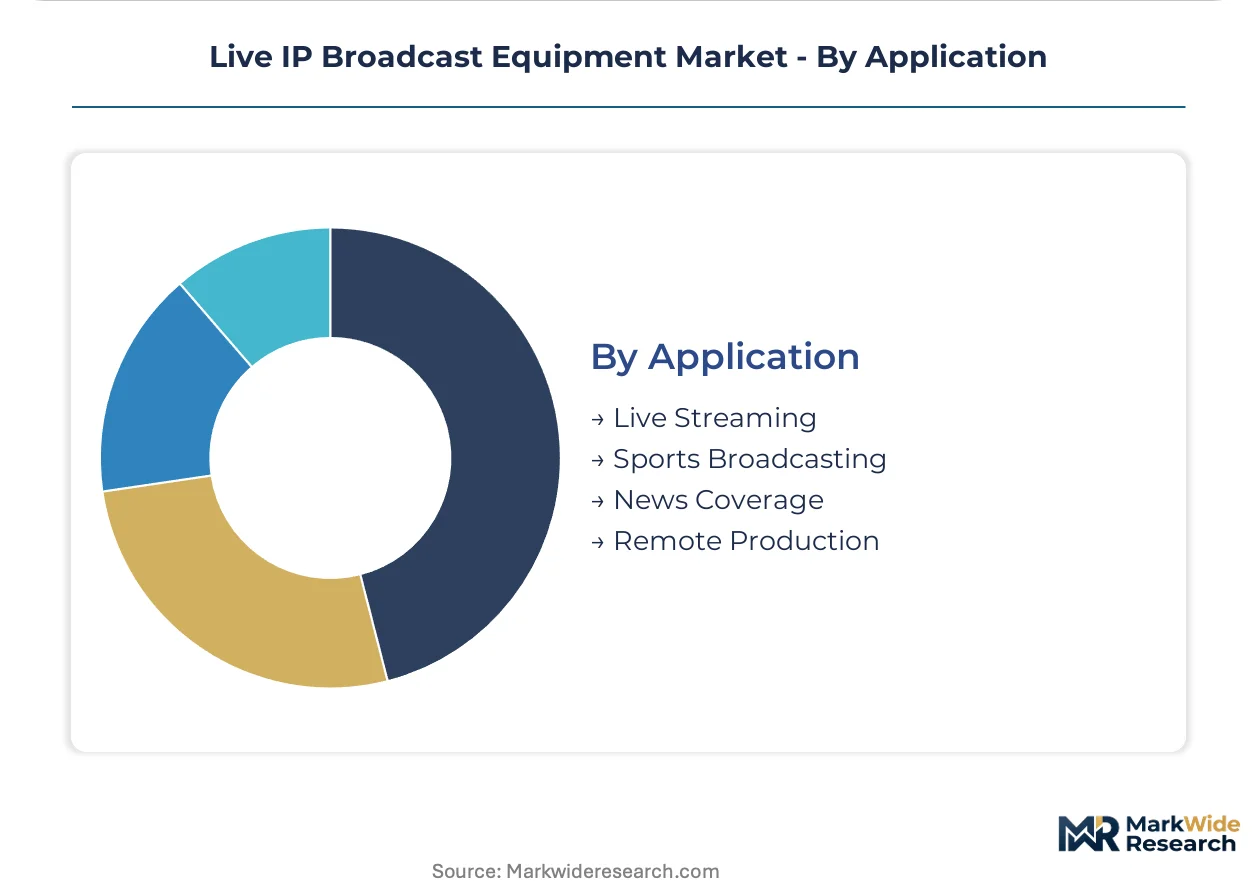
Application:
Latency tolerance and crew mobility requirements dictate architecture choices.
- Remote Production:Distributed workflows separate camera operators from technical directors across geographic nodes. Sports leagues in the United States and Germany are centralizing production for multiple venue events to reduce travel costs. Fiber and 5G backhaul enable this model.
- Sports Broadcasting:High-frame-rate capture and instant replay impose stringent timing and bandwidth requirements. Olympic-scale productions in China and FIFA-tier events in Germany demand uncompressed IP transport with sub-frame latency. Premium rights fees justify infrastructure investment.
- Live Streaming:Social platforms and corporate webinars prioritize reach over production polish.
- News Coverage:Field crews require rapid deployment and satellite/ cellular hybrid connectivity.
Sports Broadcasting captures the premium tier; Remote Production is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Burbank and Los Angeles anchor North American broadcast infrastructure procurement as major studio groups rebuild master control facilities for streaming-first distribution. Station clusters in Dallas and Atlanta follow similar upgrade cycles.
United States
ESPN-scale sports networks and station groups like Nexstar drive encoder and switcher demand for ATSC 3.0 compliance. The FCC's spectrum repack mandates compress decision timelines for IP-native rebuilds versus hybrid bridges. Production gravity concentrates in Los Angeles, Burbank, and New York Metro where streaming platforms operate hyperscale encoding farms.
Germany
ARD and ZDF public broadcasters deploy ST 2110 infrastructure for UHD channel expansion while commercial groups modernize playout. The EBU and ETSI interoperability frameworks shape procurement specifications across member organizations. Munich and Cologne host the densest vendor integration activity for remote production hubs serving Bundesliga sports rights.
China
State broadcasters CCTV and provincial satellite channels build 4K/8K transmission chains over IP networks for major event coverage. The MIIT governs GB standards compliance for ultra-high-definition equipment imports. Beijing and Shanghai clusters concentrate system integration expertise for Olympic-scale productions.
South Korea
KBS and MBC test 5G network slicing for wireless camera backhaul in live entertainment venues. The MSIT spectrum policies enable guaranteed-bandwidth slices that bypass traditional satellite truck economics. Seoul Capital Area broadcasters lead APAC deployment of edge-processing cameras with onboard HEVC encoding.
United Kingdom
BBC Studios and ITV rebuild playout infrastructure around cloud-native architectures with software-defined licensing models. Ofcom's spectrum management and the EU CSRD sustainability disclosure requirements insert circular economy clauses into technical tenders. London and Salford MediaCityUK concentrate vendor engineering resources for EMEA deployment support.
Live IP Broadcast Equipment Market Competitive Environment
Capital-heavy networking infrastructure producers compete with asset-light broadcast software designers for control of the live IP stack. The vendor base separates into three tiers: integrated networking-broadcast hybrids, pure-play production equipment specialists, and cloud-native media processing platforms. Strategic archetypes include ST 2110 compliance leaders, NDI ecosystem builders, and GPU-accelerated encoding farm operators. Competitive moves concentrate on enterprise-wide codec licensing unbundled from hardware, plus vertical integration into precision timing silicon for PTP grandmaster clocks.
Within the networking-broadcast hybrid tier, Cisco Systems exemplifies infrastructure bundling that collapses transport and control layers into single procurement decisions. Grass Valley and Harmonic occupy positions at opposite ends of the hardware-software spectrum, with the former anchoring traditional production switcher and camera markets while the latter represents cloud-native displacement of purpose-built appliances. Evertz Microsystems sits within the timing and synchronization specialist archetype that IEEE 1588 PTP deployment complexity sustains.
| Leading Market Players |
|---|
| Cisco Systems |
| Grass Valley |
| Harmonic |
| Evertz Microsystems |
| Sony |
| EVS Broadcast Equipment |
| AJA Video Systems |
| Ross Video |
| NewTek |
| Others |
Value Chain & Pricing Dynamics
Performance-tier divergence between ST 2110-certified broadcast infrastructure and uncertified IP transport gear manifests in both pricing premiums and supply chain sourcing patterns, with precision timing silicon commanding dedicated procurement channels distinct from commodity Ethernet components.
Pricing Analysis
Margin tightening in mid-market encoder tiers reflects unbundled software licensing models that separate codec royalties from hardware acquisition. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and PTP timing precision, with hyperscale streaming platforms showing lowest price sensitivity due to bandwidth cost savings from advanced compression, while regional broadcasters face acute budget constraints on IEEE 1588 grandmaster clock investments.
Supply Chain Analysis
Refurbishment flows for production switchers and camera control units concentrate in Germany and the United Kingdom, where EBU circular economy mandates drive modular redesign. Merchant switch ASICs draw from Taiwan and US semiconductor foundries, while precision oscillator components rest on Japanese and Swiss suppliers. Single-source vulnerability in 25G/100G FPGA allocation creates exposure during demand spikes. Distribution runs through systems integrators serving national broadcasters and direct OEM relationships with streaming platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
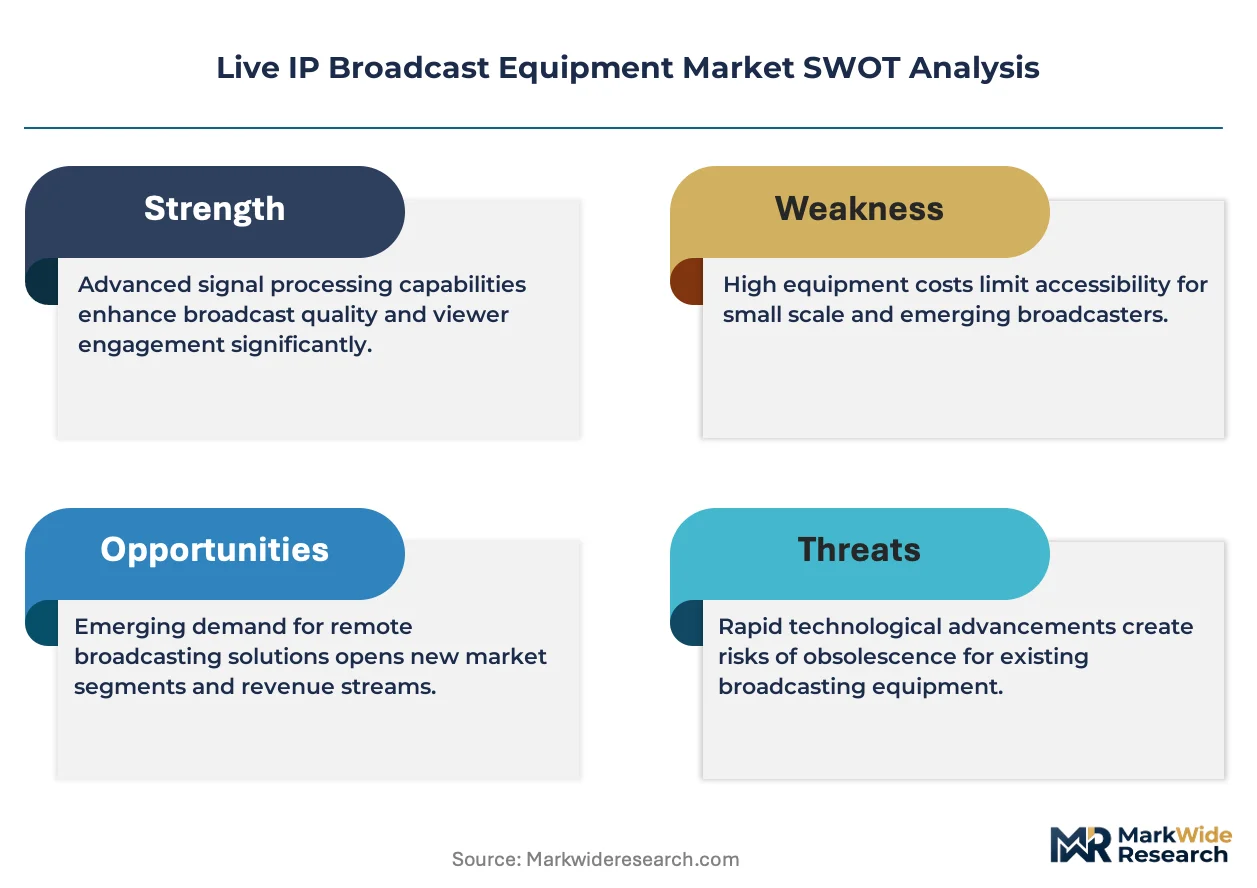
This market operates as a vertical-integration race where control over PTP timing silicon and edge-processing camera modules determines margin capture across the live production stack.
For Market Incumbents: Cement ST 2110 compliance leadership through captive supply of IEEE 1588 boundary clock silicon, insulating against merchant semiconductor allocation risk. Acquire cloud-native encoding specialists before hyperscale streaming platforms bring transcoding infrastructure in-house, eroding appliance vendor relevance. For New Entrants and Emerging Players: ATSC 3.0 mandates in the United States open a window for virtualized master control software targeting mid-market station groups bypassing legacy vendor relationships. Enter through NDI-enabled corporate video workflows in Germany, where houses of worship and education sectors show lowest switching costs from SDI infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with timing and synchronization specialists given IEEE 1588 deployment complexity that sustains systems integrator dependency. Target 5-10 year viability through acquisition of edge-processing camera OEMs with onboard HEVC encoding. Monitor TRAI infrastructure sharing guideline enforcement in India as inflection signal for cloud-native playout demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PTP Silicon | Captive supply of IEEE 1588 grandmaster clock components reduces exposure to Taiwan-US semiconductor allocation bottlenecks. |
| Cloud-Native Encoding Farm Deployment | GPU-accelerated transcoding on x86 infrastructure collapses the broadcast-grade versus IT-grade equipment procurement premium. |
| 5G Network Slicing Partnership | Guaranteed-bandwidth slices with Korean and German carriers bypass satellite truck economics for wireless camera backhaul. |
| Modular Hardware Design Certification | EU CSRD compliance enables replaceable sub-assembly procurement preferred by ARD and ZDF public broadcasters. |
| Enterprise-Wide Codec Licensing Unbundling | Nexstar-scale station groups negotiate software licenses separate from encoder hardware, shifting vendor economics toward recurring revenue. |
Study Parameters
Independent corroboration across broadcast engineering directors, IP facility systems integrators, and streaming platform CTOs underwrites the qualitative findings. Primary fieldwork with SMPTE standards committee participants, EBU technical working group members, and procurement leads at ESPN-scale sports networks combined with secondary validation from FCC spectrum allocation filings, ETSI interoperability specifications, and MIIT GB standard disclosures. Bottom-up encoder shipment tallies and top-down infrastructure capex estimates triangulate market sizing.
Rate-of-change decomposition separates replacement cycle compression from greenfield build contributions across the projection horizon. Segmentation dimensions include product type, technology protocol, end-user capital intensity, and application latency requirements. CAGRs derive from installed base turnover modeling and codec transition timelines. Industry-specific inputs capture ATSC 3.0 mandate compliance deadlines and TRAI infrastructure sharing guideline adoption curves.
The model assumes a particular technology adoption path; alternative pathways for AV1 versus HEVC codec deployment would alter the outlook. Forecasts incorporate assumptions regarding IEEE 1588 PTP expertise scarcity resolution and merchant silicon supply stability. Practitioners should monitor FCC spectrum repack completion rates and EBU circular economy tender clause penetration for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Augmented Reality in Retail Market
Others
Global Magnetic Flow Meters Market
Others
Trusted Platform Module (TPM) Market
Others
Automotive Smart Lighting Market
Others
France Smart Home Market
Others
South Korea Automotive LED Lighting Market
Others
8K Technology Market
Others
Fresh Apples Market
Others
Global Digital Market
Others
Calcined Petroleum Coke Market
Others
Moveable Water Tap Market
Others
Egg Market
Others
Europe Meditation Market
Others
Android STB and TV Market
Others
ISO Cylinder Market
Others
Global on-Demand Laundry Service Market