
 Motor Monitoring Market | 2026-2036
Motor Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Motor Monitoring Market Intelligence
A widening capability gap between integrated hardware-software providers and component-only vendors is unwinding competitive stability in motor monitoring. ABB leverages its installed base of variable frequency drives to bundle predictive maintenance subscriptions, while Rockwell Automation sustains factory-floor dominance through its Logix platform integration. Schneider Electric differentiates by embedding motor monitoring into broader building-and-industrial energy management architectures.
Motor monitoring encompasses the continuous measurement and analysis of electrical, mechanical, and thermal parameters from rotating machinery to preempt failures and optimize operational lifespan. Systems typically sample vibration at 10 kHz or higher, process stator current signatures for rotor bar fault detection, and stream data through edge gateways to cloud analytics platforms. Vibration sensors and current sensors anchor the hardware layer, though data analytics and cloud-based monitoring are capturing expanding margin pools as buyers shift from capital expenditure to subscription-based outcomes. Wireless monitoring is displacing wired installations in retrofit-heavy environments where conduit costs exceed sensor hardware by multiples.
OSHA electrical safety standards and the EU's F-Gas Regulation are tightening requirements for motor efficiency and leak detection in hermetically sealed compressor motors, directly expanding sensor deployment scope. ISO 17359 condition monitoring standards and IEEE 841 severe-duty motor specifications are becoming procurement gatekeepers for multinational industrial buyers. Stakeholders must weigh captive sensor manufacturing against modular interoperability as regulatory fragmentation across North American and European compliance regimes deepens.
Market Dynamics
Wireless retrofit installations are compressing project timelines from months to weeks, eroding the installed-base advantage of legacy wired-system incumbents and forcing pricing recalibration across hardware tiers.
Growth Catalysts
- EU F-Gas Regulation:Mandatory leak detection in hermetically sealed compressor motors expands sensor deployment scope across refrigeration and HVAC fleets.
- Automotive OEM retrofits:Germany's manufacturing belt is accelerating IoT-enabled condition monitoring deployment to reduce unplanned downtime in stamping and paint operations.
- Cloud-native analytics platforms:Edge-to-cloud data pipelines enable subscription-based predictive maintenance, converting capital expenditure into recurring revenue streams for industrial buyers.
Market Restraints
- Semiconductor input volatility:MEMS accelerometer and ADC chip supply concentration in East Asian foundries creates procurement risk for vibration sensor module vendors.
- Conduit cost economics:Retrofit environments with extensive cable tray infrastructure face sunk-cost resistance against wireless displacement.
- Regulatory fragmentation:Divergent IEEE 841 and IEC 60034 compliance testing requirements increase certification overhead for multinational hardware suppliers.
Strategic Opportunities
- India's PLI scheme for manufacturing:Greenfield automotive and textile plants present first-mover advantage for integrated motor monitoring system deployments.
- Digital twin convergence:Physics-based motor models fused with real-time sensor streams enable simulation-driven maintenance scheduling in process industries.
- Utility demand response programs:FERC Order 2222 compliance creates revenue streams for motor monitoring data aggregated into virtual power plants.
Industry Challenges
- Vibration analysis skill scarcity:Interpretation of frequency spectra for bearing fault diagnosis requires specialized training that outpaces workforce development programs.
- Legacy SCADA integration friction:Proprietary protocols in brownfield industrial sites complicate edge gateway deployment and data normalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motor Monitoring Market |
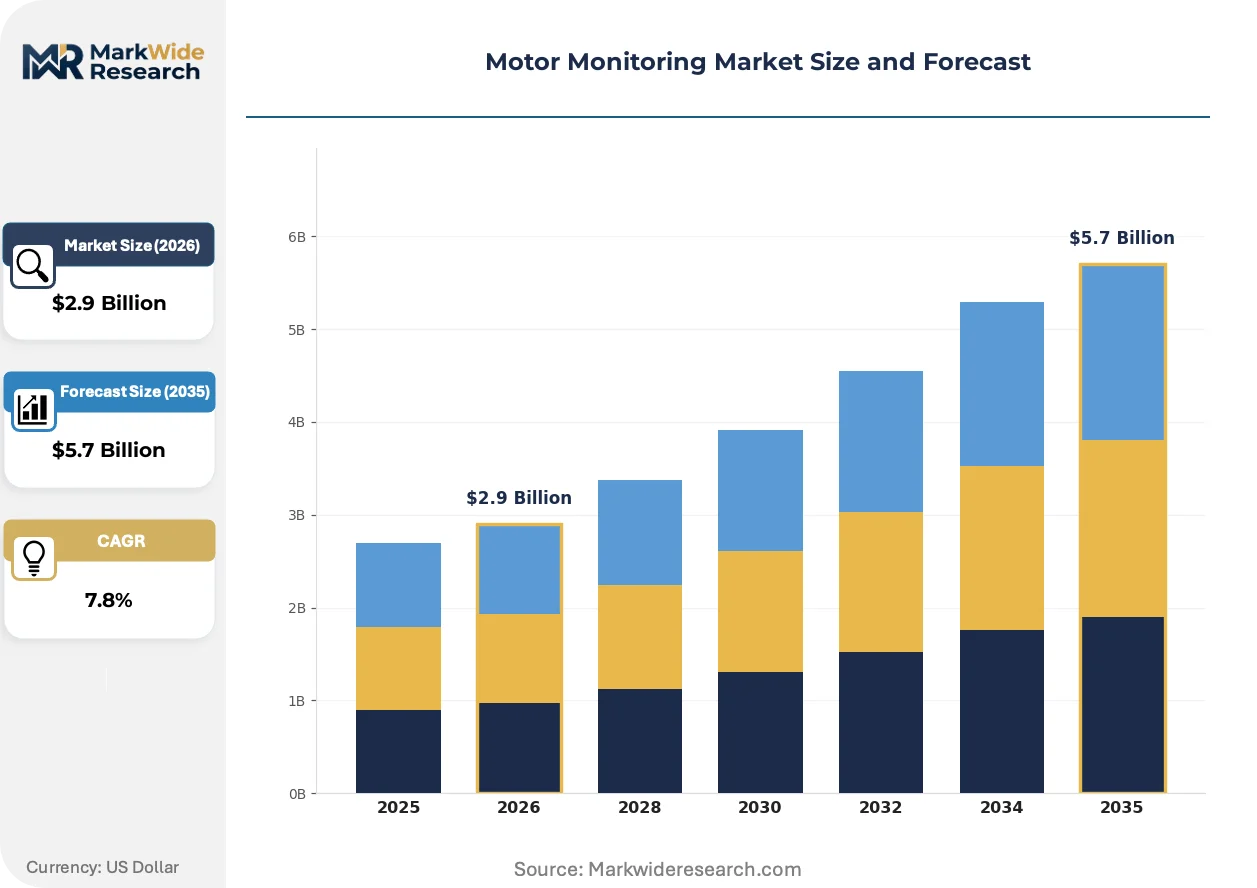
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vibration Sensors, Current Sensors, Temperature Sensors, Proximity Sensors End User: Manufacturing, Automotive, Aerospace, Marine Technology: Wireless Monitoring, IoT Solutions, Cloud-based Monitoring, Data Analytics Application: Predictive Maintenance, Condition Monitoring, Performance Optimization, Fault Detection |
| Companies Covered | ABB, Siemens, General Electric, Emerson Electric, Honeywell International, Schneider Electric, Rockwell Automation, Mitsubishi Electric, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motor Monitoring Market Strategic Shifts & Innovations
Sensor hardware and analytics software are decoupling into separate procurement decisions, fragmenting vendor relationships and compressing margins at the component layer while expanding them in platform services.
MEMS-based vibration sensors with integrated edge processing are bifurcating the hardware tier. Automotive tier-one suppliers are adopting these units for high-volume deployment in stamping press lines. This compression of sensor-plus-processor into single-package modules is eroding the traditional separation between data acquisition hardware and signal conditioning equipment.
REACH substance restrictions on heavy metals in electronic components are accelerating lead-free solder and conformal coating reformulation across European supply chains. Motor monitoring hardware destined for EU member states now requires full material disclosure documentation. Severe-duty motor OEMs in Germany and Italy are prioritizing suppliers with pre-certified RoHS-compliant sensor portfolios to compress procurement cycles.
Buying committees are unbundling hardware specification from software platform selection, treating vibration sensors as commodity inputs while competing on analytics dashboard capabilities. System integrators in North American oil and gas are consolidating sensor procurement under MRO contracts while negotiating separate SaaS agreements for diagnostic algorithms. This bifurcation is most pronounced in Permian Basin operations where drilling contractors rotate equipment across multiple operator sites.
Motor Monitoring Market Segmentation
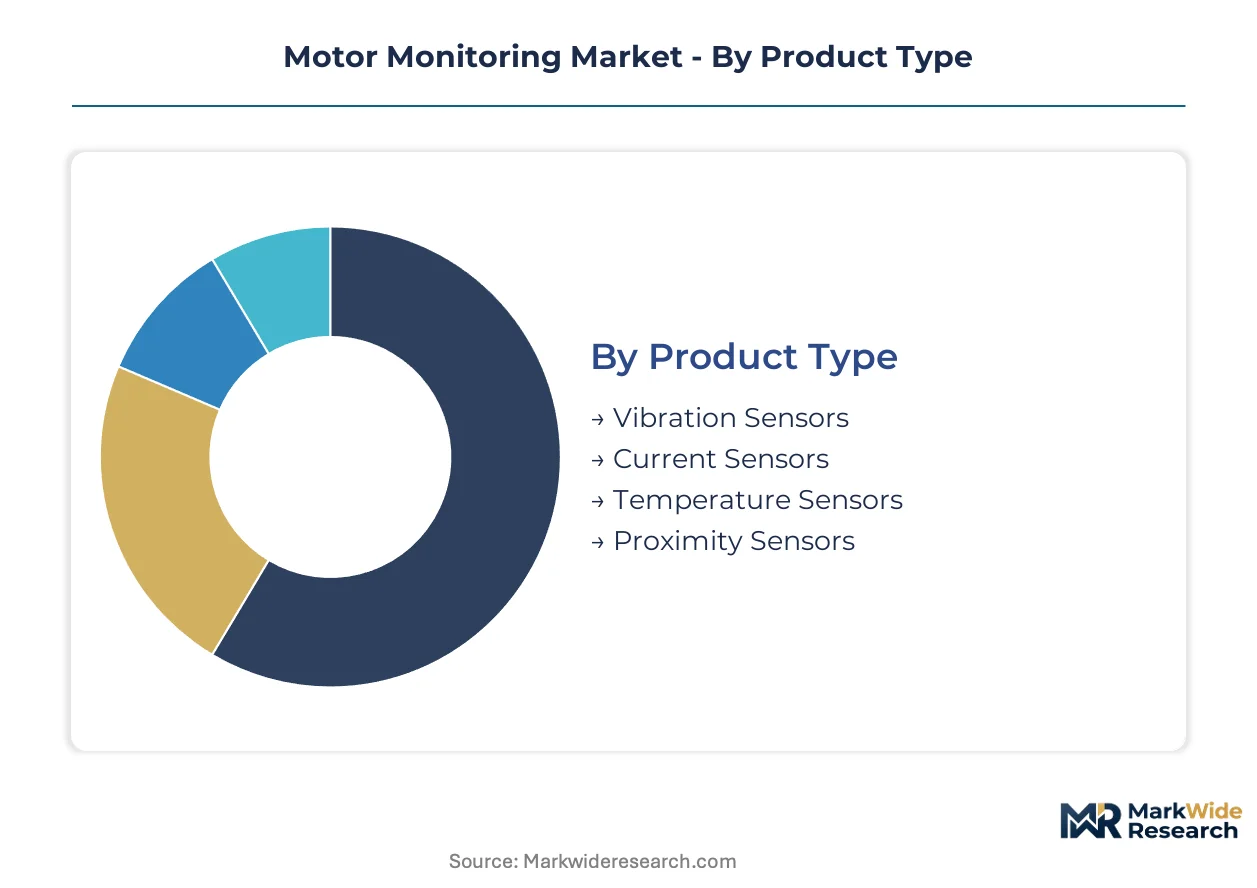
Motor monitoring procurement splits across hardware commoditization and platform premiumization. Buyers now source sensors and analytics through separate channels, fragmenting vendor relationships and margin capture across the value chain.
Product Type:
Vibration sensors flow through industrial distributors and MRO contracts, while current and temperature variants increasingly ship direct to OEM motor manufacturers.
- Vibration Sensors:MEMS accelerometers sampling at 10 kHz or higher anchor predictive maintenance deployments. Demand clusters in Germany's automotive belt where stamping press retrofits require high-frequency bearing fault detection.
- Current Sensors:Stator current signature analysis enables rotor bar fault detection without mechanical intrusion. Manufacturing plants in the US Midwest specify these for legacy motor fleets where vibration sensor installation proves invasive.
- Temperature Sensors:Thermocouple and RTD-based units monitor bearing and winding thermal stress. REACH-compliant variants dominate EU procurement.
- Proximity Sensors:Eddy-current and capacitive designs measure shaft displacement and air gap variation. Marine applications specify corrosion-resistant housings.
Vibration sensors dominate installed base. Current sensors are where expansion concentrates.
End User:
Cost tier segmentation separates premium-specification aerospace buyers from price-sensitive manufacturing procurement committees.
- Manufacturing:Discrete and process plants deploy mixed sensor portfolios across conveyor, pump, and compressor assets. India's PLI scheme beneficiaries specify integrated monitoring for greenfield textile and automotive facilities.
- Automotive:OEMs and tier-one suppliers mandate IoT-enabled condition monitoring for stamping, paint, and powertrain operations. Germany's manufacturing belt leads retrofit intensity.
- Aerospace:MRO providers and airframe manufacturers require DO-160G-qualified sensors for auxiliary power units and fuel pumps. Certification overhead limits supplier pools.
- Marine:Classification society rules from Lloyd's Register and DNV drive sensor specification for propulsion and auxiliary systems. Offshore vessels prioritize intrinsically safe designs.
Manufacturing captures volume. Automotive is climbing the fastest.
Technology:
Volume concentration sits with wireless retrofit installations displacing wired legacy infrastructure.
- Wireless Monitoring:Battery-powered and energy-harvesting sensor nodes eliminate conduit costs. Brownfield sites with extensive cable tray infrastructure face sunk-cost resistance.
- IoT Solutions:Edge gateways normalize proprietary protocols for cloud transmission. Legacy SCADA integration friction complicates deployment in North American oil and gas.
- Cloud-based Monitoring:Subscription platforms convert capital expenditure to recurring operational budgets. System integrators negotiate SaaS agreements separate from hardware procurement.
- Data Analytics:Physics-based models and machine learning algorithms interpret frequency spectra for fault classification. Vibration analysis skill scarcity constrains adoption.
Wireless monitoring dominates retrofit activity. Cloud-based monitoring is gaining share fastest.
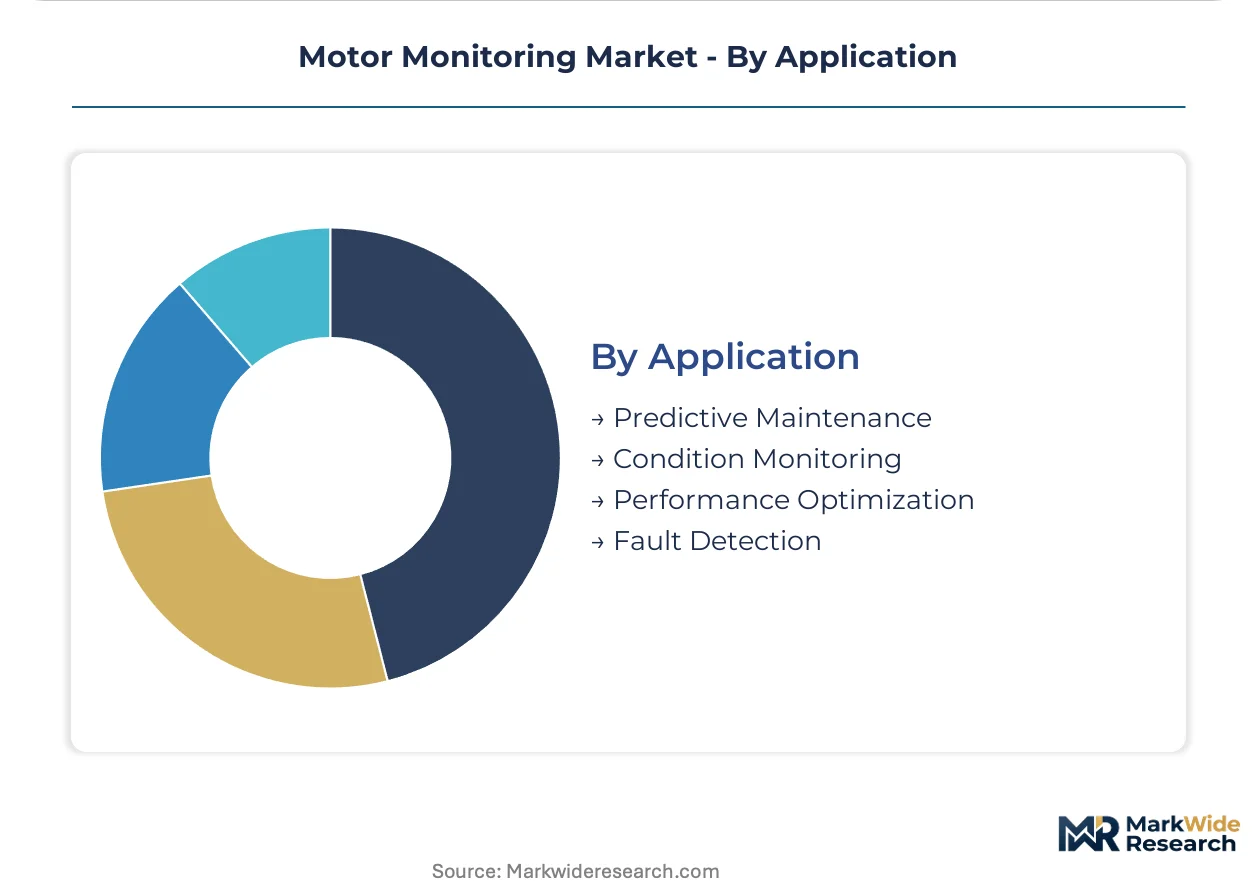
Application:
Customer type segmentation separates outcome-based predictive maintenance contracts from compliance-driven condition monitoring mandates.
- Predictive Maintenance:Subscription-based services schedule interventions before functional failure. ABB bundles these with variable frequency drive installed bases.
- Condition Monitoring:Continuous parameter tracking satisfies ISO 17359 procurement gatekeepers. Multinational industrial buyers mandate certification for supplier qualification.
- Performance Optimization:Efficiency analytics align motor loading with process demand. EU Green Deal industrial decarbonization mandates tighten efficiency requirements.
- Fault Detection:Automated alerts trigger maintenance workflows for bearing degradation and rotor asymmetry. F-Gas Regulation leak detection expands sensor scope in hermetically sealed compressor motors.
Condition monitoring dominates regulatory compliance. Predictive maintenance shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German automotive belt procurement committees, while Indian greenfield manufacturing sites operate on compressed hardware margins under PLI scheme volume commitments.
United States
Midwest manufacturing plants specify current sensors for legacy motor fleets where vibration installation proves invasive. FERC Order 2222 compliance creates revenue streams for motor monitoring data aggregated into virtual power plants. Permian Basin drilling contractors rotate equipment across operator sites, unbundling hardware from SaaS procurement.
Germany
Automotive OEMs mandate IoT-enabled condition monitoring for stamping and paint operations to reduce unplanned downtime. EU Green Deal industrial decarbonization mandates tighten efficiency requirements for rotating equipment across member states. Baden-Württemberg's manufacturing belt leads retrofit intensity for legacy motor fleets.
China
Dual carbon goals accelerate deployment of wireless sensor networks in heavy industrial clusters. GB standards for motor efficiency create compliance-driven replacement cycles across state-owned enterprises. Yangtze River Delta textile and automotive plants specify integrated monitoring for greenfield facilities.
India
PLI scheme beneficiaries specify integrated motor monitoring for greenfield textile and automotive facilities. Central Electricity Authority guidelines push efficiency monitoring for industrial motor fleets above specified horsepower thresholds. Gujarat and Maharashtra manufacturing corridors attract first-mover deployments from integrated system vendors.
Japan
Automotive tier-one suppliers adopt MEMS-based vibration sensors with integrated edge processing for high-volume stamping press lines. METI energy efficiency standards mandate monitoring for motors above designated capacity thresholds. Kansai industrial belt prioritizes predictive maintenance subscriptions bundled with drive systems.
Motor Monitoring Market Key Industry Players
Concentration sits with integrated hardware-software providers possessing installed bases of complementary industrial equipment. Three structural tiers define competitive positioning: diversified industrial conglomerates bundling motor monitoring into broader automation portfolios, pure-play condition monitoring specialists competing on analytics capabilities, and component vendors supplying commodity sensors through distribution channels. Dominant competitive moves include strategic partnerships between sensor manufacturers and cloud analytics platforms, plus backward integration into MEMS fabrication to secure accelerometer supply.
Among diversified industrial conglomerates, ABB leverages its installed base of variable frequency drives to bundle predictive maintenance subscriptions, while Rockwell Automation sustains factory-floor dominance through its Logix platform integration. Schneider Electric occupies a position embedding motor monitoring into broader building-and-industrial energy management architectures.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| General Electric |
| Emerson Electric |
| Honeywell International |
| Schneider Electric |
| Rockwell Automation |
| Mitsubishi Electric |
| Eaton |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day MEMS accelerometer lead times from East Asian foundries compress pricing power for vibration sensor module vendors while amplifying margin capture for integrated platform providers with captive inventory buffers. This inventory asymmetry separates hardware commoditization from software premiumization across procurement committees.
Pricing Analysis
The configured-to-order premium for ISO 17359-certified sensor packages runs three to five multiples above standard MRO catalog pricing. Three-tier pricing structure across premium, standard, and economy levels dominates: premium tiers bundle edge processing and cloud analytics subscriptions; standard tiers ship through industrial distributors on volume contracts; economy variants serve price-sensitive Indian PLI scheme greenfield sites. Cost compression in the standard tier intensifies as MEMS integration erodes signal conditioning equipment margins. Manufacturing procurement committees in Germany's automotive belt exhibit lowest price sensitivity due to unplanned downtime costs; Indian textile plant operators under PLI volume commitments show highest sensitivity.
Supply Chain Analysis
Just-in-time inventory strategies prevail among North American system integrators, while European OEMs maintain strategic stockpiles of REACH-compliant sensor portfolios to compress procurement cycles. MEMS fabrication concentrates in Taiwan and South Korea; final assembly and calibration cluster in China and Mexico; distribution runs through industrial distributors and direct OEM channels. Raw material dependencies span silicon wafers, lead-free solder alloys, and conformal coating formulations. Single-source vulnerability in ADC chip supply creates procurement risk for vibration sensor vendors. Downstream distribution favors consolidated MRO contracts unbundled from separate SaaS agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Motor monitoring sits in early-cycle expansion as wireless retrofit installations displace wired legacy infrastructure and subscription-based predictive maintenance converts capital expenditure to recurring operational budgets.
For Market Incumbents: Secure backward integration into MEMS fabrication to insulate against East Asian foundry concentration, and lock in exclusive distribution terms with Baden-Württemberg automotive OEMs before pure-play analytics specialists capture retrofit mindshare. Threat from cloud-native platform entrants with AI-driven fault classification algorithms intensifies. Certification investment in EU F-Gas Regulation compliance for hermetically sealed compressor motors anchors channel control. For New Entrants and Emerging Players: Vibration analysis skill scarcity among maintenance workforces creates service-layer white space for training-coupled analytics subscriptions. Target India's Gujarat and Maharashtra manufacturing corridors for greenfield integrated system deployments where PLI scheme beneficiaries lack incumbent relationships. Go-to-market through system integrators in Permian Basin oil and gas operations, where equipment rotation across operator sites fragments vendor loyalty. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core condition monitoring divisions amid portfolio rationalization. Long-term viability hinges on recurring revenue share from predictive maintenance subscriptions exceeding hardware transactional exposure. Watch for inflection when cloud-native analytics platforms achieve ISO 17359 certification parity with incumbent hardware-software bundles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Fabrication | Captive accelerometer supply insulates against Taiwan and South Korea foundry concentration risks. |
| ISO 17359 Certification Investment | Procurement gatekeeper status secures multinational industrial buyer qualification mandates. |
| Cloud-Native Analytics Platform Launch | Subscription revenue conversion captures margin expansion as hardware commoditizes. |
| Strategic Partnership with Automotive OEMs | Baden-Württemberg stamping press retrofits anchor installed base for predictive maintenance bundling. |
| Geographic Expansion into India PLI Corridors | Gujarat and Maharashtra greenfield textile and automotive sites lack entrenched incumbent relationships. |
Research Approach
Cross-validation between primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads and secondary validation through SEC filings, customs and trade data, industrial automation association reports, and ISO certification registries anchors the qualitative findings. Bottom-up sensor shipment estimates triangulate against top-down predictive maintenance subscription revenue analysis.
Sensitivity analysis around wireless adoption velocity and cloud platform penetration rates shapes the analytical framework across the projection horizon. Segmentation dimensions span product type, end user industry, technology deployment mode, and application purpose. CAGRs derive from installed base growth, replacement cycle compression, and subscription attach rate assumptions. Industry-specific inputs include EU F-Gas Regulation compliance timelines and Indian PLI scheme capacity commissioning schedules.
Material uncertainties — semiconductor supply disruptions, regulatory fragmentation between IEEE 841 and IEC 60034 testing regimes, and workforce skill scarcity constraining vibration analysis adoption — sit outside the modeled envelope. Forecasts reflect documented assumptions about wireless retrofit economics and cloud platform interoperability. Revision becomes warranted when MEMS accelerometer lead times exceed strategic inventory buffers or when REACH substance restrictions expand beyond current heavy metal limitations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Hydrostatic Transmission Market
Vehicle Components
Vehicle Cargo Box Market
Vehicle Components
Motorcycle Side Box Market
Vehicle Components
Intelligent Rubber Tracks Market
Vehicle Components
Collapsible Jerry Can Market
Vehicle Components
Digital Tire Inflator Market
Vehicle Components
Snowplows Market
Vehicle Components
Wheel Seals Market
Vehicle Components
Vehicle Air Deflector Market
Vehicle Components
Global Automotive Rain, Light, Humidity Sensor Market
Vehicle Components
Europe Automotive Lightweight Car Market
Vehicle Components
Automotive Pyrofuse Market
Vehicle Components
Mobile Liquid Tanks Market
Vehicle Components
Self Loading Trailer Market
Vehicle Components
Car Modification Market
Vehicle Components
Trailer Terminal Tractor Market