
 Cement Consistency Meter Market | 2026-2036
Cement Consistency Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Cement Consistency Meter Market Insights
China is tilting toward domestic manufacturing of precision cement testing equipment as infrastructure standardization intensifies. Fann Instrument Company leverages its deep specialization in oilfield and construction fluid testing to sustain technical credibility across multiple geographies. Chandler Engineering anchors its position through rigorous product engineering for laboratory and field environments. AMETEK competes by extending its instrumentation portfolio into materials characterization with controlled distribution channels.
A cement consistency meter measures the penetration resistance or flow characteristics of cement paste to determine water content requirements and setting behavior, typically operating with a standardized plunger or Vicat needle apparatus under defined load conditions. The device ensures batch uniformity in concrete production by quantifying consistency against ASTM C187, EN 196, or equivalent national protocols. Digital meters are capturing preference where electromagnetic sensing enables real-time data logging and reduced operator variance. Laboratory instruments retain the dominant margin pool due to certification requirements and higher unit values, while portable meters are expanding fastest among contractors performing field quality control. Mechanical meters occupy a shrinking but defended niche in budget-constrained public works procurement.
ASTM International governs product calibration protocols in the United States, while the European Committee for Standardization enforces EN 196 conformity across EU member states and aligned markets. China's State Administration for Market Regulation implements GB standards that increasingly reference automated consistency measurement for large-scale infrastructure projects. Stakeholders must monitor how national standards bodies integrate digital traceability requirements into cement testing protocols, as this will determine which technology platforms achieve regulatory acceptance and procurement eligibility across priority construction markets.
Market Dynamics
ASTM C187 and EN 196 calibration tightening is forcing equipment replacement cycles across construction testing laboratories, compressing the window between certification audits and accelerating capital expenditure decisions for consistency meter procurement.
Growth Catalysts
- Infrastructure build-outs:India's National Infrastructure Pipeline is driving cement testing laboratory expansion in Mumbai, Delhi, and Bangalore. State-level quality mandates require Vicat apparatus deployment at commercial batching plants.
- EN 196-3 automation requirements:The European Committee for Standardization's updated protocols mandate digital data logging for cement paste testing, eliminating manual needle penetration documentation.
- Electromagnetic sensing:Real-time penetration resistance measurement with reduced operator variance is displacing mechanical dial gauges in commercial concrete production facilities.
Market Restraints
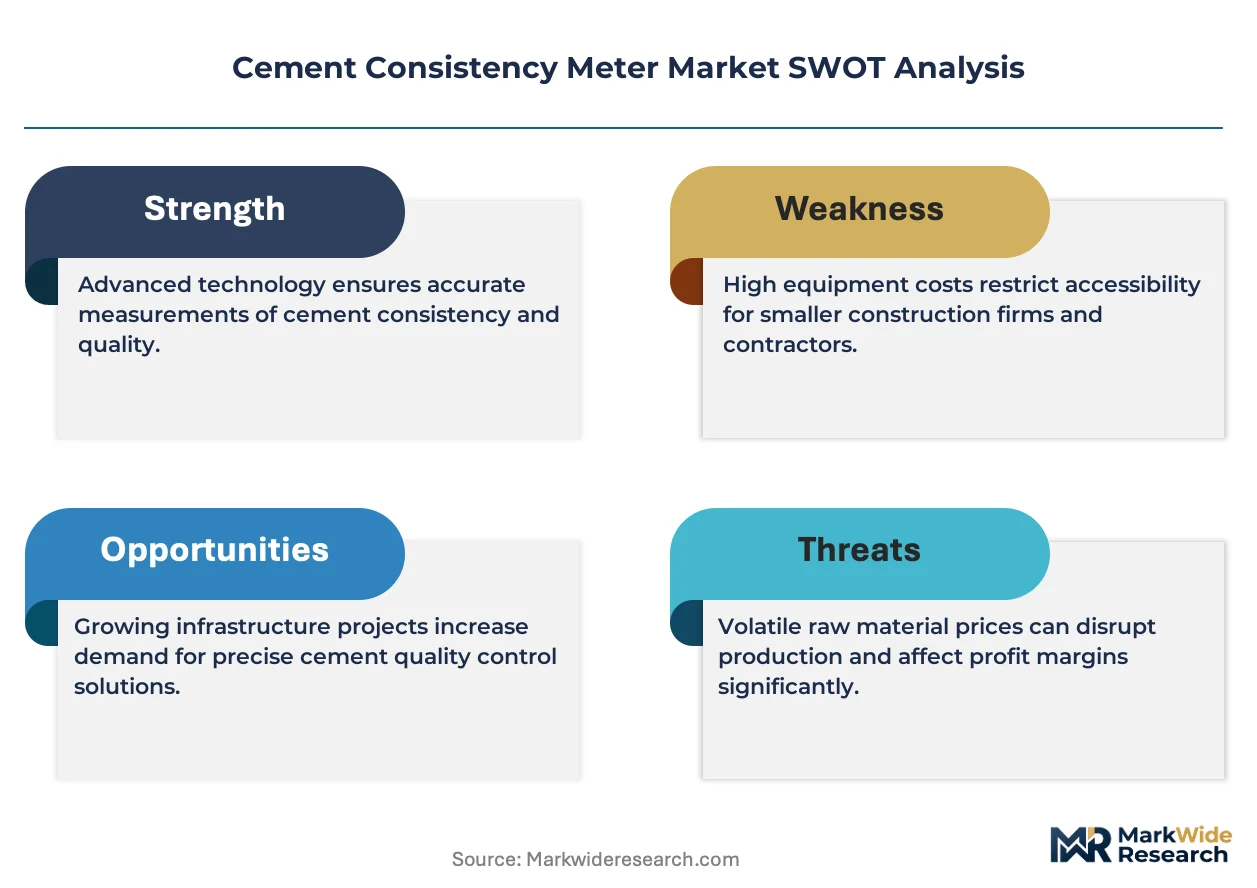
- Precision sensor supply concentration:Load cell and LVDT component manufacturing clusters in Germany and Japan create procurement vulnerability for meter assemblers outside these regions.
- Calibration infrastructure gaps:Developing economies lack accredited metrology laboratories capable of certifying consistency meters to ISO 17025 standards, extending commissioning timelines.
- Portable unit durability limits:Field-deployed meters face accelerated wear from dust ingress and vibration, compressing replacement cycles versus laboratory equipment.
Strategic Opportunities
- Southeast Asia laboratory build-outs:Vietnam and Indonesia are constructing provincial construction materials testing centers with standardized cement paste analysis capabilities.
- Cloud-connected calibration:Remote diagnostic platforms enable predictive maintenance alerts and automated certification renewal notifications for distributed equipment fleets.
- GB/T 1346 alignment:China's State Administration for Market Regulation is referencing automated Vicat measurement in large-scale infrastructure project specifications, creating procurement preference for digital platforms.
Industry Challenges
- Metrology technician scarcity:Certified calibration specialists capable of servicing electromagnetic consistency meters remain concentrated in major urban testing hubs, limiting field service coverage.
- Legacy mechanical meter installed base:Budget-constrained public works departments resist digital platform migration despite tightening accuracy requirements, fragmenting supplier service obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cement Consistency Meter Market |
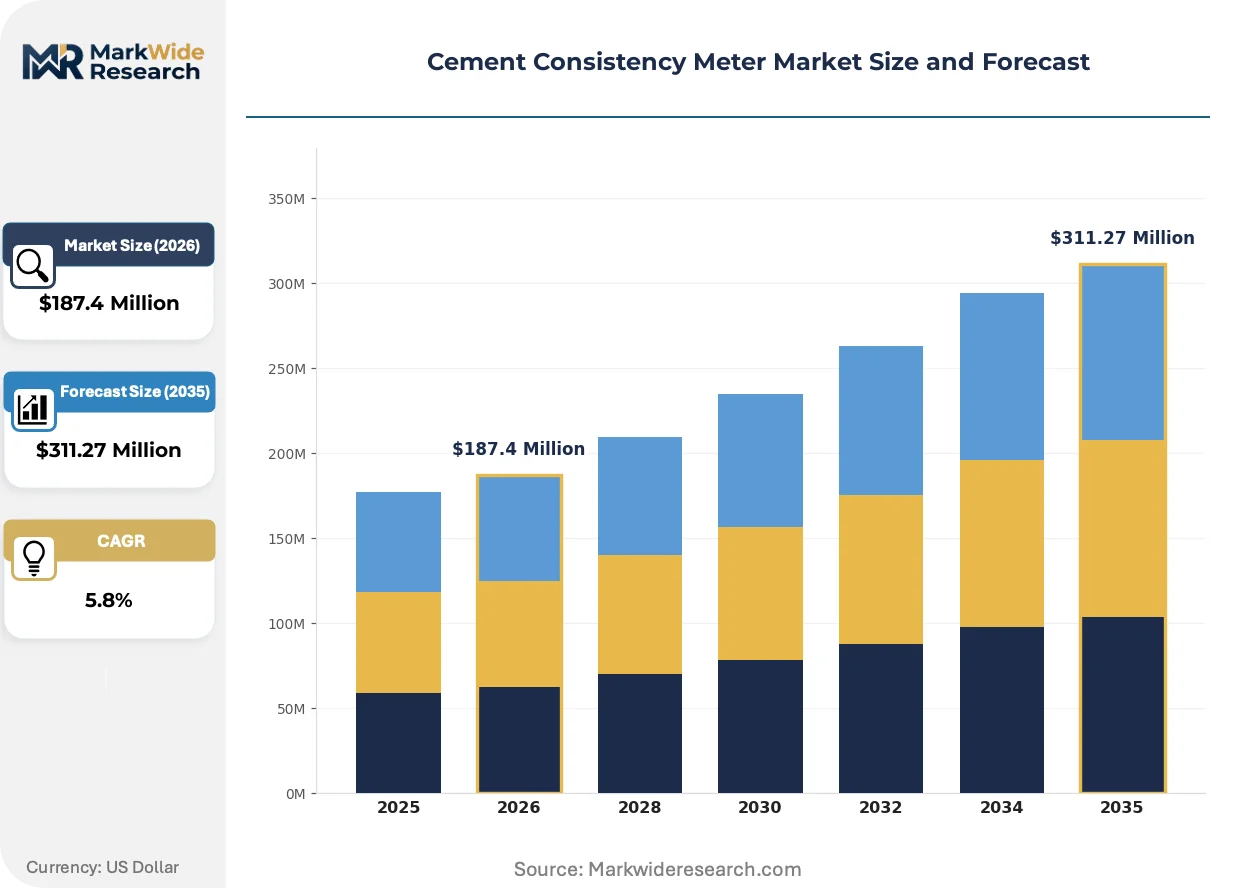
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Meters, Laboratory Instruments, Digital Meters, Mechanical Meters End User: Construction Companies, Material Testing Labs, Research Institutions, Contractors Technology: Electromagnetic, Ultrasonic, Mechanical, Optical Application: Quality Control, Field Testing, Laboratory Testing, Research & Development |
| Companies Covered | Fann Instrument Company, Chandler Engineering, OFI Testing Equipment, Grace Instrument Company, AMETEK, Cooper Research Technology, Tianjin Nithons Technology, Rigchina Group Company, Humboldt Mfg. Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cement Consistency Meter Market Trends and Innovations
Digital traceability requirements are compressing the acceptable latency between measurement and documentation, forcing convergence between sensing hardware and data architecture in cement testing workflows.
Wireless data transmission modules embedded in Vicat apparatus are virtualizing the documentation layer that previously required manual transcription and paper-based record retention. Commercial concrete producers in Germany and France are adopting these platforms to satisfy EN 196 audit requirements with timestamped, tamper-resistant measurement logs. This architecture is virtualizing the role of laboratory technicians from data recorders to calibration auditors, compressing headcount at high-throughput testing facilities.
REACH compliance deadlines for electronic component substance restrictions are accelerating redesign cycles for consistency meter circuit assemblies. Manufacturers serving EU member states must validate solder compositions and housing polymers against updated candidate substance lists before placing equipment on the market. Laboratory instrument suppliers with established EU-notified body relationships are capturing certification timeline advantages over Asian competitors without established European regulatory infrastructure.
Equipment-as-a-service contracting is displacing capital purchase models among mid-sized ready-mix concrete operators seeking to convert fixed testing equipment expenditure into variable per-batch costs. German and Austrian construction material distributors are bundling consistency meter access with consumables and calibration services under multi-year agreements. This model concentrates most visibly in Central European markets where construction sector financing constraints favor operational expenditure treatment of quality control assets.
Cement Consistency Meter Market Segmentation
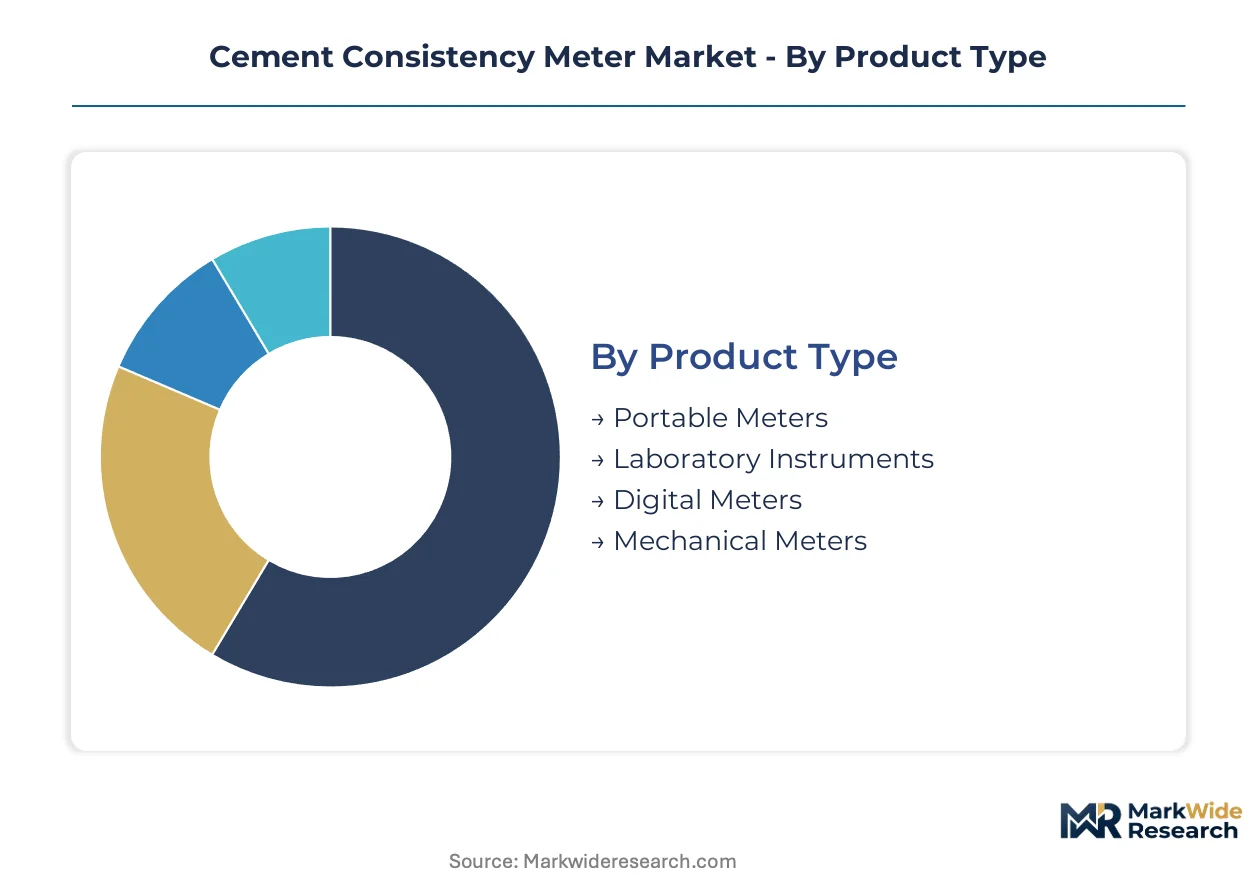
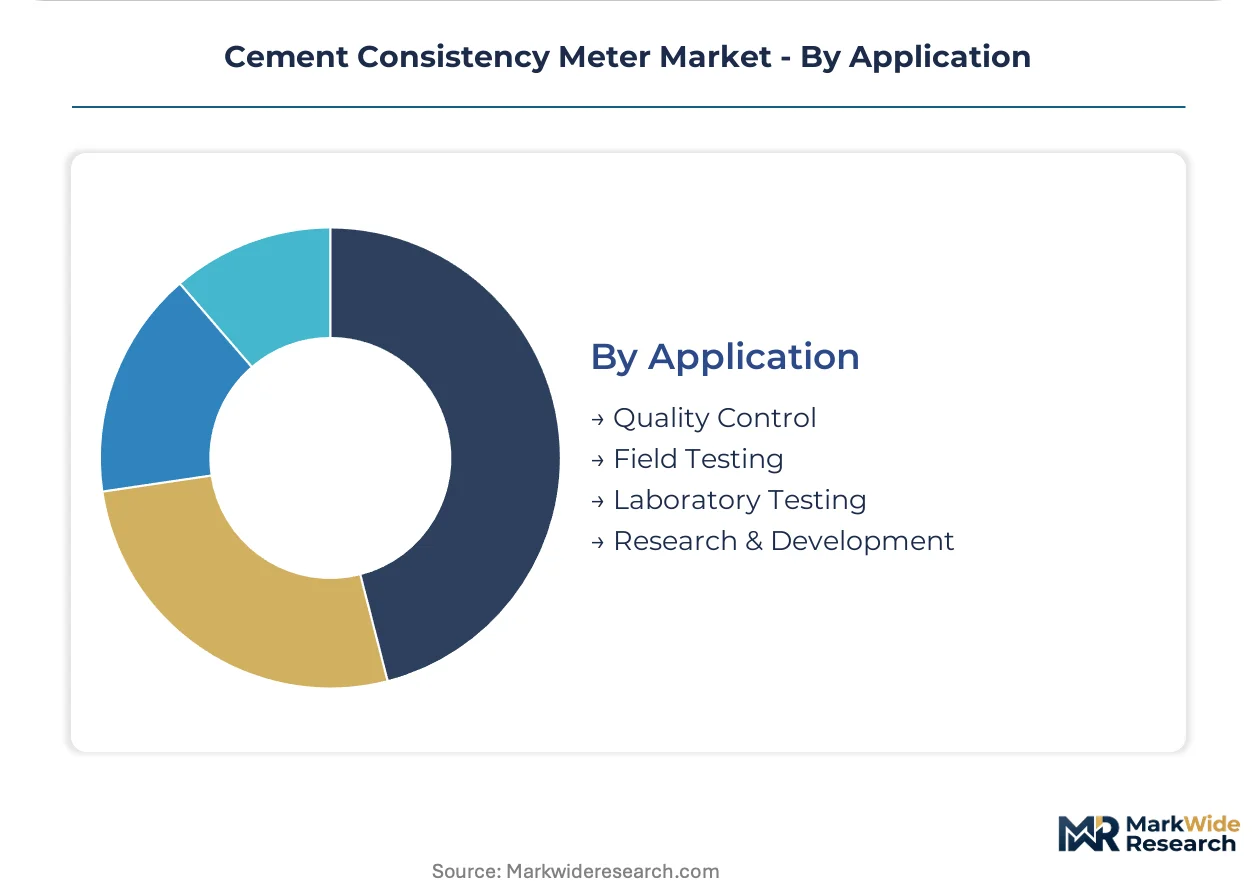
Segmentation in the cement consistency meter market reveals distinct service intensity patterns across equipment tiers. Digital and laboratory platforms demand intensive calibration support, while portable mechanical units require rapid field replacement logistics. Procurement behavior diverges sharply between certified testing facilities and contractor fleets.
Product Type:
After-sales service intensity varies dramatically across product tiers, with laboratory instruments requiring ISO 17025 traceability maintenance and portable units demanding rapid turnaround on vibration-damaged components.
- Portable Meters:Compact, battery-operated units with hardened enclosures for dust and shock resistance. Demand concentrates among Indian and Indonesian contractors performing field quality control at remote infrastructure sites where laboratory access is limited. Replacement cycles compress under tropical humidity and haul-road vibration.
- Laboratory Instruments:Precision-engineered platforms with electromagnetic load cells and automated penetration logging. European commercial batching plants in Germany and France are upgrading to satisfy EN 196-3 digital documentation mandates, driving premium procurement.
- Digital Meters:Microprocessor-controlled systems with real-time data transmission and cloud connectivity. These platforms are gaining share in Chinese state infrastructure projects referencing GB/T 1346 automated measurement protocols.
- Mechanical Meters:Spring-loaded dial gauge apparatus with minimal electronic components. Budget-constrained public works departments in Southeast Asia retain these for basic Vicat testing despite tightening accuracy standards.
By volume, mechanical meters lead. By growth pace, digital meters are expanding most quickly.
End User:
Customer type determines procurement authority structure, with material testing labs holding technical specification power and construction companies controlling capital allocation timelines.
- Construction Companies:Large-scale concrete producers integrating consistency testing into batching plant workflows. India's National Infrastructure Pipeline is accelerating laboratory build-outs at commercial facilities in Mumbai and Delhi.
- Material Testing Labs:Accredited facilities performing third-party certification to ASTM C187 and EN 196 protocols. These operators prioritize electromagnetic platforms with automated calibration logging and audit trail generation.
- Research Institutions:Universities and national standards bodies conducting cement chemistry and additive development. Procurement emphasizes precision instrumentation with programmable test sequences.
- Contractors:Small and mid-sized operators performing field acceptance testing. These users favor portable units with simplified operation and minimal training requirements.
Material testing labs command the highest unit values. Contractors represent the steepest expansion trajectory for portable equipment.
Technology:
Technology selection tracks regulatory digitization pressure, with electromagnetic platforms capturing preference where standards bodies mandate automated data capture.
- Electromagnetic:Load cell and LVDT-based penetration resistance measurement with microsecond response times. Real-time sensing eliminates operator reading variance and enables timestamped documentation for EN 196 compliance.
- Ultrasonic:Non-contact velocity measurement through cement paste samples. Research applications in Japan and South Korea are exploring these platforms for early-age setting monitoring.
- Mechanical:Calibrated spring and dial gauge assemblies with manual needle penetration. Legacy installed base in developing economies sustains demand for replacement parts and recalibration services.
- Optical:Laser displacement tracking of Vicat needle position. Emerging platforms target high-throughput laboratory environments seeking reduced mechanical wear.
Mechanical technology retains the largest installed base. Electromagnetic platforms are climbing the fastest as standards digitize.
Application:
Application context determines equipment specification rigor, with quality control mandates driving laboratory-grade procurement and field conditions demanding ruggedized portability.
- Quality Control:Continuous batch monitoring at commercial concrete production facilities. Chinese state-owned construction groups are deploying automated Vicat systems at megaproject sites under SAMR quality directives.
- Field Testing:On-site verification of delivered concrete consistency. Southeast Asian contractors in Vietnam and Indonesia require portable meters with rapid setup and battery operation.
- Laboratory Testing:Accredited analysis for certification and compliance documentation. European facilities prioritize platforms with EN 196-3 data logging and tamper-resistant record retention.
- Research & Development:Experimental cement formulation and additive evaluation. Academic and institutional users demand programmable test parameters and raw data export capabilities.
Laboratory testing captures the dominant margin pool. Field testing is gaining share fastest among distributed contractor networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ASTM International governs equipment calibration protocols in the United States, while parallel standards bodies across major construction economies enforce divergent conformity requirements that shape regional procurement patterns.
United States
Commercial batching plants in Texas and Florida are upgrading testing infrastructure under ASTM C187 tightening. The Federal Highway Administration's quality mandates for federally aided projects require accredited laboratory equipment at state-level facilities. Houston and Miami construction material distributors report accelerating replacement cycles for mechanical dial gauges.
Germany
EN 196-3 digital documentation mandates are eliminating manual needle penetration recording across commercial concrete production. The country's national metrology institute enforces ISO 17025 traceability for laboratory-grade consistency meters. Bavarian and North Rhine-Westphalian testing facilities prioritize electromagnetic platforms with automated calibration logging.
China
State Administration for Market Regulation directives for large-scale infrastructure reference automated Vicat measurement under GB/T 1346. Provincial construction bureaus in Jiangsu and Guangdong mandate digital consistency testing at megaproject sites. Yangtze River Delta equipment assemblers are capturing domestic procurement preference through localized sensor supply chains.
India
The National Infrastructure Pipeline accelerates laboratory build-outs in Mumbai, Delhi, and Bangalore. State-level quality mandates require Vicat apparatus deployment at commercial batching plants. Bureau of Indian Standards certification timelines compress procurement decisions for electromagnetic platforms with reduced operator variance.
Indonesia
Provincial construction materials testing centers in Java and Sumatra require standardized cement paste analysis capabilities. The national standards body references EN 196 protocols for imported equipment qualification. Jakarta-based contractors favor portable meters with rapid setup for remote infrastructure site verification.
Cement Consistency Meter Market Competitive Landscape
Capability concentration sits with laboratory-grade specialists; scale advantage sits with diversified instrumentation conglomerates. The vendor base stratifies across precision-engineering boutiques, construction-fluid testing specialists, and broad-line metrology platforms. Three archetypes dominate: oilfield-testing heritage players, materials-characterization generalists, and regional fabrication houses. Competitive moves center on calibration service bundling and electromagnetic platform migration to capture EN 196-3 compliance demand.
Within the oilfield-testing heritage tier, Fann Instrument Company and Chandler Engineering exemplify technical credibility sustained across multiple geographies. AMETEK occupies a position among diversified instrumentation conglomerates extending materials characterization portfolios. Among Asia-Pacific fabricators, Tianjin Nithons Technology and Rigchina Group Company represent regional scale advantages in domestic procurement environments. These anchors illustrate how competitive positioning diverges between specification-driven laboratory markets and cost-sensitive field deployment segments.
| Leading Market Players |
|---|
| Fann Instrument Company |
| Chandler Engineering |
| OFI Testing Equipment |
| Grace Instrument Company |
| AMETEK |
| Cooper Research Technology |
| Tianjin Nithons Technology |
| Rigchina Group Company |
| Humboldt Mfg. Co. |
| Others |
Pricing and Supply Chain Analysis
Shanghai-Rotterdam container freight corridors transmit cost volatility from precision sensor manufacturing clusters directly into European laboratory instrument pricing, while Indian procurement teams exploit domestic assembly capabilities to compress landed costs for electromagnetic platforms.
Pricing Analysis
Price spreads between German-manufactured laboratory instruments and Chinese-assembled portable units exceed threefold across equivalent performance tiers. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales bundling intensity. Cost compression in economy mechanical meters intensifies as Southeast Asian public works departments consolidate procurement under national tender frameworks. Contractors exhibit acute price sensitivity; accredited material testing laboratories prioritize calibration service reliability over unit acquisition cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days dominate procurement negotiations between meter assemblers and load cell suppliers, straining working capital for mid-tier manufacturers. Component manufacturing concentrates in Germany, Japan, and coastal China provinces. Electromagnetic sensors, LVDT position transducers, and hardened field enclosures constitute critical input dependencies. Single-source vulnerability in precision load cell supply creates procurement risk for European instrument builders. Distribution runs through construction material distributors in Central Europe and direct OEM relationships in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Chinese state-owned construction groups and Indian National Infrastructure Pipeline contractors, compressing supplier margins and accelerating equipment standardization demands.
For Market Incumbents: Harden defensive positions by securing ISO 17025-accredited calibration service networks in secondary Indian cities before electromagnetic platform commoditization accelerates. Deepen backward integration into LVDT sensor production to offset procurement vulnerability from Japanese component suppliers. Channel control through exclusive distributor arrangements in Germany and Austria protects premium positioning against Asian cost competitors. For New Entrants and Emerging Players: Indonesian provincial laboratory build-outs represent the most penetrable white-space opportunity, with state-mandated EN 196 alignment creating qualification pathways for electromagnetic platforms. Vietnam's infrastructure acceleration lacks established calibration infrastructure, enabling service-bundled entry. Go-to-market through Jakarta-based construction material distributors with localized technical support teams bypasses incumbent field service advantages. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors laboratory-grade specialists with established EU-notified body relationships over diversified instrumentation conglomerates. Long-term viability hinges on regulatory digitization tailwinds persisting across ASTM, EN, and GB standard convergence. Acquisition targets should demonstrate embedded calibration service revenue streams exceeding thirty percent of equipment sales. Watch for SAMR automation mandates accelerating beyond current GB/T 1346 scope as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | ISO 17025 accreditation in Indian secondary cities captures National Infrastructure Pipeline contractor demand. |
| Electromagnetic Platform Migration | EN 196-3 digital documentation mandates eliminate mechanical dial gauge procurement eligibility in Germany. |
| Cloud-Connected Diagnostic Integration | Remote certification renewal alerts reduce technician dispatch costs for distributed Southeast Asian fleets. |
| Regional Component Assembly | Yangtze River Delta sensor supply chains satisfy SAMR domestic procurement preferences for Chinese megaprojects. |
| Equipment-as-a-Service Contracting | Per-batch pricing models convert fixed capital expenditure for mid-sized ready-mix operators in Austria. |
Research Methodology
Operator-level perspectives from laboratory calibration technicians, construction material procurement managers, and electromagnetic sensor manufacturing engineers anchored the qualitative base. Primary interviews combined with secondary validation against ASTM International technical committee minutes, EN 196-3 protocol revision drafts, and Bureau of Indian Standards certification timelines. Customs records for load cell and LVDT component trade flows, SEC filings from diversified instrumentation conglomerates, and provincial construction bureau procurement announcements supplied quantitative grounding. Bottom-up equipment shipment estimates triangulated against top-down infrastructure investment forecasts.
Scenario-bracketing framed volume and value outputs across conservative, baseline, and accelerated digitization pathways throughout the forecast period. Segmentation dimensions modeled include product tier, end-user archetype, technology platform, and application context. CAGRs derived from regression analysis against historical replacement cycle data and standards-mandated upgrade timelines. Industry-specific inputs incorporated EN 196-3 implementation schedules and SAMR infrastructure quality directive enforcement intensity.
Practitioners should monitor ASTM C187 calibration interval tightening proposals and REACH substance restriction updates for early signals of equipment redesign cycles. Forecasts reflect assumptions regarding electromagnetic platform cost curves and metrology technician availability trajectories. Macroeconomic infrastructure investment freezes, regulatory harmonization failures, or ultrasonic sensing technology breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Southern Africa Construction Equipment Rental Market
Construction Equipment
Derinding Machines Market
Construction Equipment
Hand Push Trencher Market
Construction Equipment
Hybrid Excavator Market
Construction Equipment
Shotcrete Sprayer Market
Construction Equipment
Hammer Unions Market
Construction Equipment
Europe Construction Machinery Rental Market
Construction Equipment
Concrete Mixer Market
Construction Equipment
Horizontal Machining Center Market
Construction Equipment
Soil Compaction Equipment Market
Construction Equipment
US Waterjet Cutting Machines Market
Construction Equipment
Roadheaders Market
Construction Equipment
CNC Machine Market
Construction Equipment
(AWP) Aerial Work Platform Rental Market
Construction Equipment
Field Marking Equipment Market
Construction Equipment
Stud Welding Machine Market