
 Global Water-Based Coatings Market | 2026-2036
Global Water-Based Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Water-Based Coatings Market Foresight
Color-matching software subscriptions and tinting service contracts is pivoting how coatings are specified and sold, embedding recurring revenue into historically transactional relationships. PPG Industries leverages digital color platforms to anchor specification decisions with large architectural clients. BASF SE differentiates through polymer R&D intensity, sustaining patent positions in high-performance acrylic emulsions. AkzoNobel N.V. dominates marine and protective segments through controlled distribution networks in Northern Europe and East Asia.
Water-based coatings are aqueous dispersions of resin binders, pigments, and additives with volatile organic compound content typically below regulatory thresholds, applied through spray, dip, or roll processes to form protective and decorative films on substrates. Acrylic formulations lead architectural applications due to weatherability and cost positioning, while polyurethane segments capture premium margin pools in automotive and industrial machinery where abrasion resistance commands specification priority. Emulsion polymerization technology anchors volume manufacturing, though radiation curing is gaining traction in wood products and furniture manufacturing for accelerated line speeds and reduced energy curing.
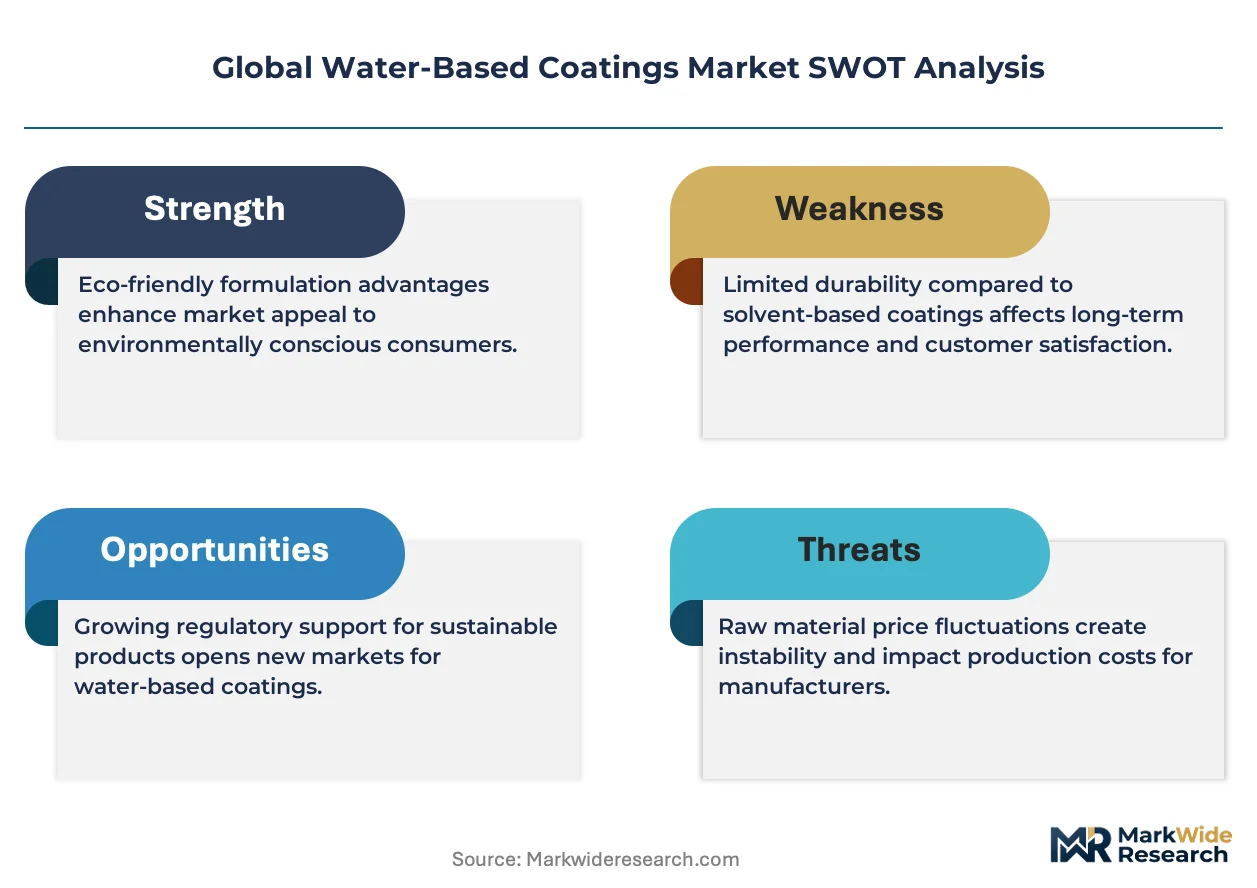
EPA standards under the National Emission Standards for Hazardous Air Pollutants and REACH registration requirements in Europe are eliminating solvent-based alternatives from specification lists in regulated end uses. China's MEE enforcement of GB standards on industrial coatings and India's BIS certification for architectural products are tightening market access for non-compliant imports. Stakeholders must monitor regulatory divergence across these three jurisdictions, as compliance cost asymmetries will reshape competitive positioning in traded product segments.
Market Dynamics
Emulsion polymerization scale economics and REACH-driven solvent displacement are compressing specification windows, forcing formulators to recalibrate binder portfolios around aqueous systems with equivalent performance envelopes.
Growth Catalysts
- REACH Phase-Down:ECHA enforcement is eliminating high-VOC solvent systems from EU specification lists, redirecting architectural and automotive procurement toward compliant water-borne alternatives.
- Acrylic Emulsion Advances:Hybrid core-shell polymer architectures now deliver polyurethane-grade abrasion resistance at emulsion price points, penetrating industrial machinery and transportation coatings.
- China Infrastructure Buildout:Coastal manufacturing clusters in Jiangsu and Zhejiang provinces sustain large-volume offtake for protective and decorative applications.
Market Restraints
- Petrochemical Feedstock Volatility:Acrylic acid and styrene monomer prices swing with naphtha-cracker economics, compressing formulation margins during upstream spikes.
- Water Sensitivity Limitations:Aqueous systems require extended flash-off periods and controlled humidity conditions, restricting deployment in tropical climates and uncontrolled field applications.
- Specialty Additive Concentration:High-performance rheology modifiers and dispersants concentrate among German and Japanese chemical suppliers, creating procurement bottlenecks.
Strategic Opportunities
- India BIS Certification Expansion:Mandatory IS 15489 compliance for architectural coatings is displacing unorganized supply, creating structured entry for compliant multinationals.
- Radiation Curing Convergence:UV-LED curing integration with water-borne wood coatings is enabling 3-second line speeds in furniture manufacturing.
- Digital Color Platforms:Cloud-based tinting systems and spectrophotometer-linked software are embedding specification loyalty through subscription-based color-matching services.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Polymer synthesis expertise for high-solids emulsions concentrates among aging technical workforces in Western Europe and Japan.
- Multi-Jurisdiction Certification Burden:Simultaneous EPA NESHAP, REACH SVHC, and China GB standard compliance requires parallel testing protocols, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Water-Based Coatings Market |
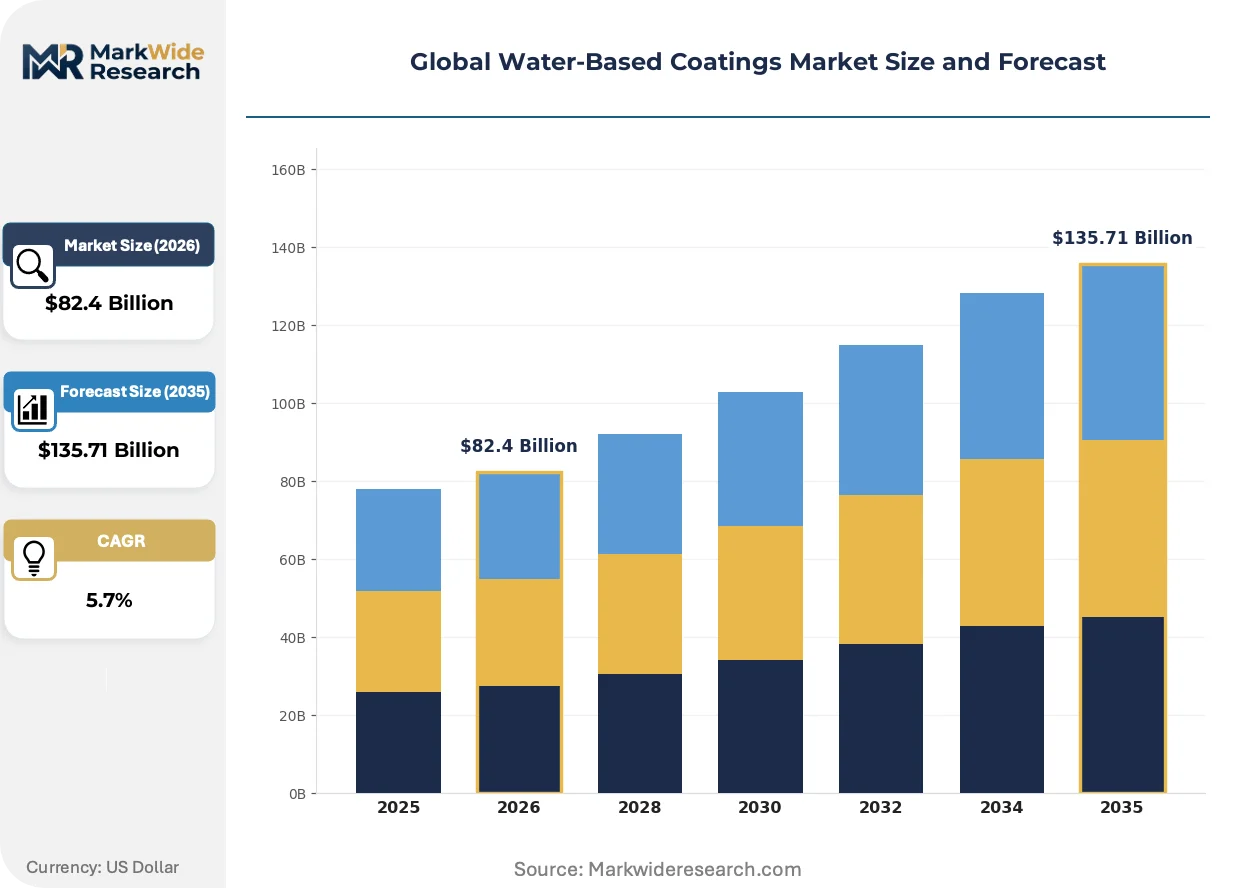
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $135.71 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Polyurethane, Alkyd, Latex, Vinyl Technology: Emulsion Polymerization, Solvent-Free Polymer, Sol-Gel, Pressure Sensitive Adhesive, Radiation Curing, Powder Coating Application: Architectural Surfaces, Marine Vessels, Wood Products, Metal Fabrication, Automotive Components, Industrial Machinery End User: Construction Contractors, Shipbuilders, Furniture Manufacturers, Equipment Producers, Vehicle Assemblers, Machinery Suppliers |
| Companies Covered | AkzoNobel N.V., PPG Industries, Inc., The Sherwin-Williams Company, BASF SE, Axalta Coating Systems Ltd., Dow Inc., Jotun A/S, Hempel A/S, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Water-Based Coatings Market Shifts & Advancements
Digital specification tools and accelerated curing chemistries are compressing traditional coating procurement and application cycles, embedding software-defined performance into physical product categories.
Self-crosslinking acrylic emulsion technology is consolidating architectural and light industrial applications under unified binder platforms. Large-scale housing developers in North America and Northern Europe are specifying these systems for combined interior-exterior programs. The technology is consolidating previously separate procurement categories into single-source supply relationships, reducing supplier count per project.
EPA National Emission Standards for Hazardous Air Pollutants are tightening permissible VOC thresholds in industrial maintenance coatings. Metal fabrication and infrastructure refurbishment sectors face compliance deadlines that invalidate legacy solvent-based inventories. Marine and protective segments in the US Gulf Coast are responding with accelerated water-borne system qualification programs.
Specification authority is migrating from general contractors to architectural software platforms with embedded performance databases. PPG's digital color tools and comparable platforms are capturing decision rights upstream of traditional distribution channels. This shift concentrates most visibly in commercial construction across Germany, the United Kingdom, and urban Australia.
Global Water-Based Coatings Market Segmentation
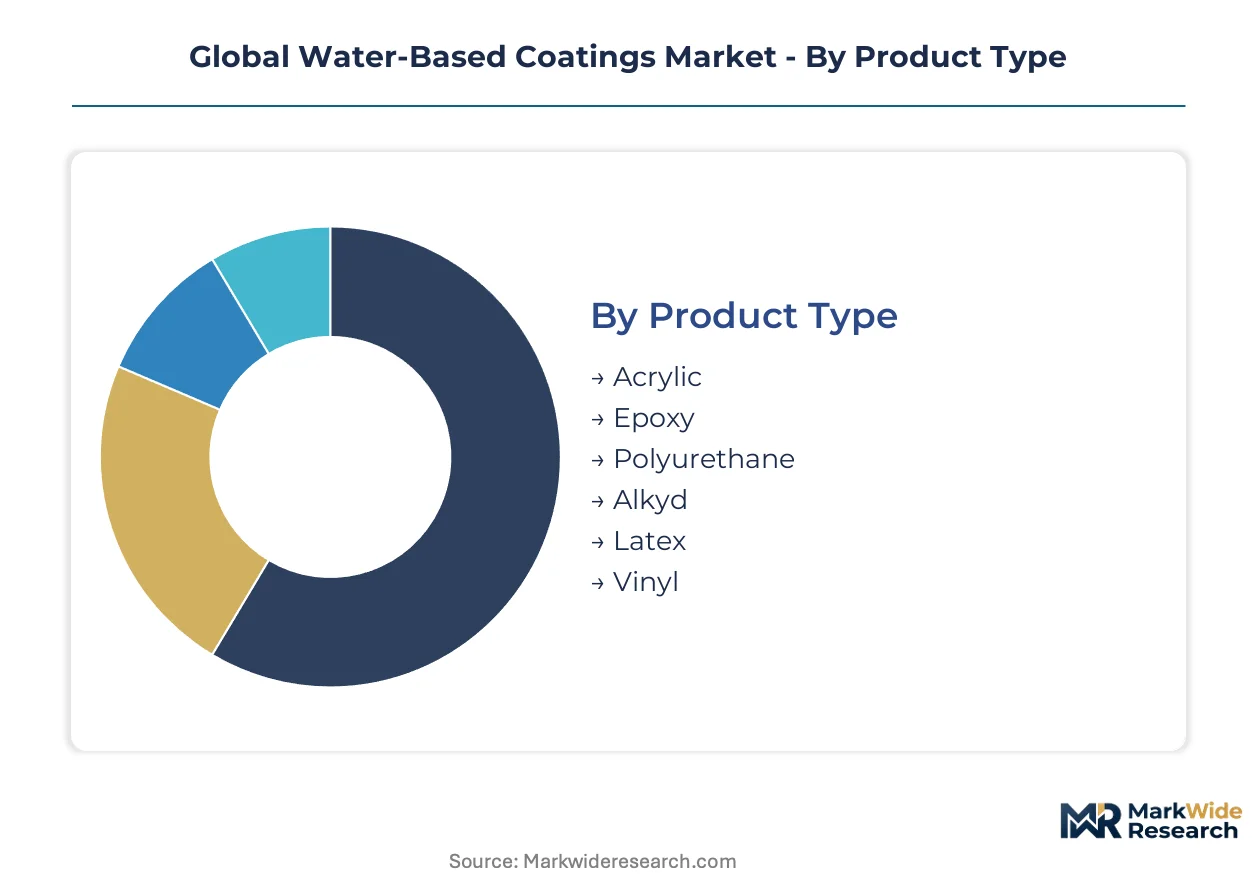
Water-based coatings segment along four distinct axes that determine capital deployment, technical specification, and margin capture. Product type and technology choices lock in raw material exposure and manufacturing scale requirements. Application and end-user dimensions dictate compliance burdens and specification authority.
Product Type:
Capital intensity varies sharply across resin chemistries, with polyurethane systems requiring specialized reactor trains and acrylic emulsions scaling through continuous polymerization infrastructure.
- Acrylic:Aqueous dispersions of acrylate and methacrylate monomers deliver weatherability and UV resistance. Housing developers in Germany and the United Kingdom specify these systems for combined interior-exterior programs, consolidating procurement under single-source relationships. Self-crosslinking variants now penetrate light industrial applications previously served by solvent-borne alternatives.
- Polyurethane:Two-component water-borne urethane systems achieve abrasion resistance and chemical tolerance for premium segments. Automotive component suppliers in Stuttgart and Wolfsburg specify these for underhood applications where thermal cycling demands exceed acrylic capabilities. The chemistry requires isocyanate handling infrastructure that elevates fixed costs above emulsion alternatives.
- Epoxy:Water-dispersed epoxy resins serve protective coatings for metal substrates in marine and infrastructure applications.
- Alkyd:Modified oil-based resins adapted for aqueous delivery retain gloss retention in decorative architectural segments.
- Latex:Styrene-acrylic copolymer emulsions dominate volume architectural markets through cost positioning.
- Vinyl:Polyvinyl acetate and vinyl-acrylic hybrids capture economy-tier interior wall coatings.
Most installed capacity flows through acrylic emulsion systems. Expansion is steepest in polyurethane water-borne technologies.
Technology:
Manufacturing process selection determines energy intensity, cure speed, and regulatory compliance pathways across coating production.
- Emulsion Polymerization:Continuous stirred-tank reactors produce acrylic and vinyl emulsions at scale. Jiangsu and Zhejiang manufacturing clusters in China anchor global volume output for this technology. The process achieves sub-50 g/L VOC content without downstream solvent recovery, satisfying EPA NESHAP and REACH thresholds.
- Radiation Curing:UV-LED and electron-beam systems integrated with water-borne wood coatings enable sub-10-second cure cycles. Furniture manufacturers in High Point, North Carolina and Dongguan, China deploy these systems for accelerated line speeds and reduced thermal energy. Capital requirements for UV lamp arrays and nitrogen inerting exceed conventional convection ovens.
- Solvent-Free Polymer:High-solids water-borne systems minimize volatile content through advanced dispersant technology.
- Sol-Gel:Inorganic-organic hybrid coatings deliver ceramic-like hardness for specialty glass and metal applications.
- Pressure Sensitive Adhesive:Water-borne PSA coatings serve tape and label markets through controlled tack and peel properties.
- Powder Coating:Water-borne powder slurries combine zero-VOC powder attributes with liquid application convenience.
Emulsion polymerization commands the largest installed base. Radiation curing is gaining share fastest in wood products manufacturing.
Application:
Specification authority migrates differently across end-use segments, with architectural decisions concentrating in software platforms and industrial choices remaining with equipment OEMs.
- Architectural Surfaces:Interior and exterior wall, trim, and specialty coatings for residential and commercial construction. Digital color platforms in Germany, the United Kingdom, and urban Australia are capturing specification decisions upstream of traditional distribution. Cloud-based tinting systems embed recurring revenue through subscription-based color-matching services.
- Automotive Components:OEM and refinish coatings for vehicle bodies, underhood components, and plastic substrates. Tier-1 suppliers in Stuttgart, Wolfsburg, and Detroit specify water-borne basecoats and clearcoats to meet EPA and REACH VOC limits. The segment demands crash repair compatibility and chip resistance that historically favored solvent-borne systems.
- Marine Vessels:Protective coatings for ship hulls, decks, and cargo holds in saltwater environments.
- Wood Products:Furniture, cabinetry, and flooring finishes where radiation curing integration accelerates production cycles.
- Metal Fabrication:Industrial maintenance and OEM coatings for structural steel and equipment.
- Industrial Machinery:Protective and decorative finishes for manufacturing equipment and agricultural machinery.
Architectural surfaces absorb the largest coating volume. Automotive components are expanding most quickly as OEMs phase out solvent-borne systems.
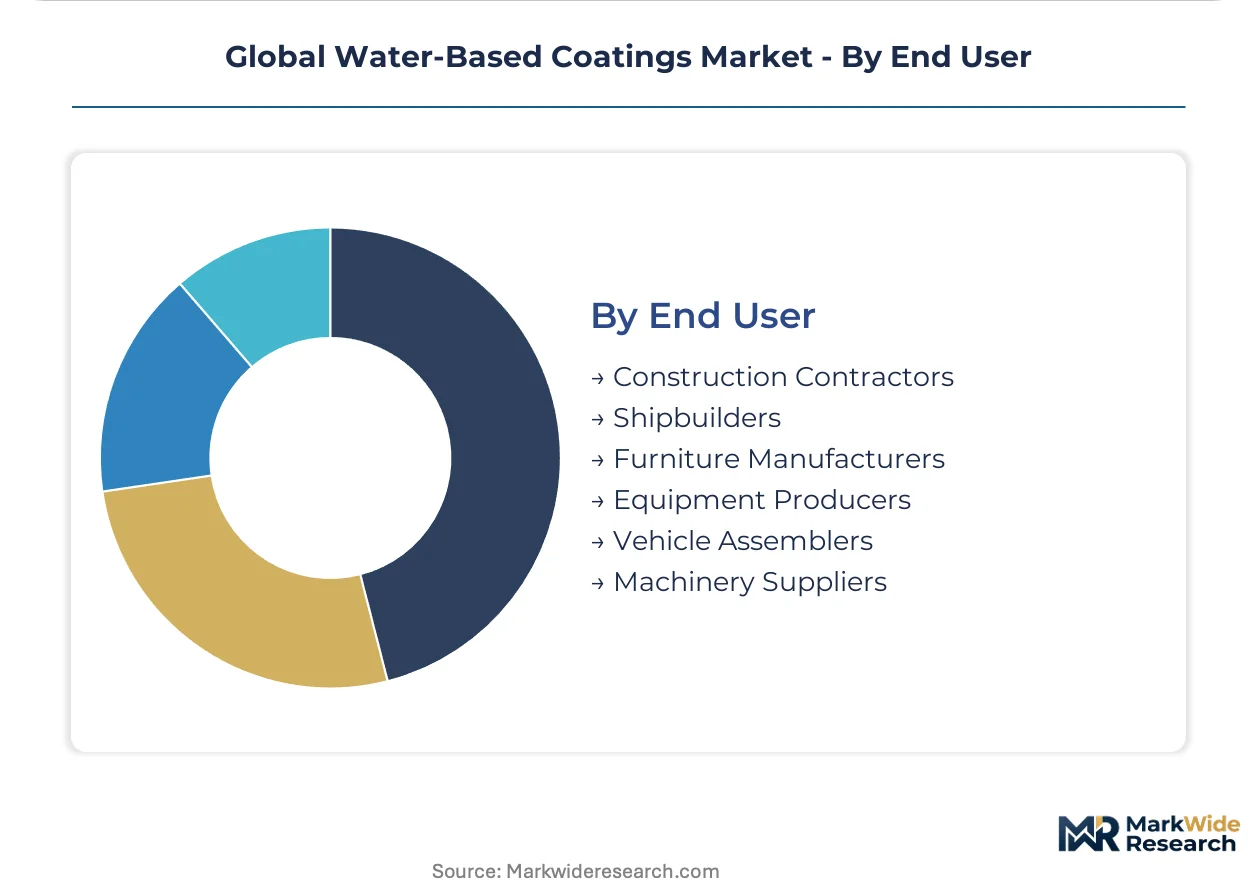
End User:
Procurement sophistication and compliance enforcement intensity vary across customer categories, determining margin capture and contract structure.
- Construction Contractors:Commercial and residential builders procuring architectural coatings through specification-driven processes. Large housing developers in North America and Northern Europe are consolidating supplier counts through unified interior-exterior programs. Digital platforms are embedding specification loyalty through integrated color-matching subscriptions.
- Vehicle Assemblers:OEMs and tier suppliers with integrated paint shops and stringent quality protocols. Stuttgart and Detroit-based manufacturers enforce water-borne system qualification through parallel testing against solvent-borne benchmarks. The transition requires line modification and technician retraining that extends over multiple model years.
- Shipbuilders:Yards in Northern Europe and East Asia specifying protective systems for newbuild and maintenance programs.
- Furniture Manufacturers:Producers in High Point and Dongguan adopting radiation-cured water-borne systems for throughput gains.
- Equipment Producers:Industrial machinery OEMs specifying coatings for corrosion protection and brand identity.
- Machinery Suppliers:Aftermarket and refurbishment providers serving installed equipment bases.
Construction contractors represent the largest customer category by volume. Vehicle assemblers are driving the fastest specification migration toward compliant water-borne systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal manufacturing clusters consume water-based coatings at volumes exceeding Germany and the United States combined, yet regulatory enforcement intensity diverges sharply between these jurisdictions. Construction buildout and automotive production concentrate demand in distinct geographic patterns.
China
Jiangsu and Zhejiang province clusters drive architectural and industrial offtake through state-led infrastructure programs. MEE enforcement of GB standards on industrial coatings tightens market access for non-compliant imports. Shanghai and Ningbo manufacturing hubs sustain emulsion polymerization capacity serving domestic and export markets.
Germany
Automotive OEM paint shops in Stuttgart and Wolfsburg mandate water-borne basecoat qualification for tier suppliers. ECHA REACH enforcement eliminates high-VOC solvent systems from EU specification lists. Bavarian and North Rhine-Westphalian chemical parks anchor acrylic emulsion R&D for architectural and automotive segments.
United States
Metal fabrication and infrastructure refurbishment sectors face EPA NESHAP compliance deadlines invalidating legacy solvent inventories. Gulf Coast marine yards accelerate water-borne system qualification for protective applications. High Point furniture manufacturers deploy radiation-cured water-borne systems for throughput gains.
India
Mandatory BIS IS 15489 compliance for architectural coatings displaces unorganized supply in Maharashtra and Gujarat. Central government infrastructure programs concentrate procurement authority with large housing developers. Mumbai and Ahmedabad construction markets consolidate supplier counts through unified interior-exterior programs.
Japan
Automotive component suppliers in Nagoya and Tokyo metro areas specify water-borne systems for underhood thermal cycling applications. METI industrial standards align with REACH-equivalent chemical management protocols. Osaka-Kobe chemical corridor maintains specialty additive production for rheology modifiers and dispersants.
Global Water-Based Coatings Market Competitive Landscape
Top-tier vendors anchor specification authority with automotive OEMs and large architectural clients, while mid-tier regional formulators compete on price in unregulated construction segments. The vendor base stratifies across three tiers: multinational chemical conglomerates with integrated resin production, specialized coatings companies with controlled distribution networks, and regional emulsion suppliers serving price-sensitive markets. Dominant competitive moves include digital platform integration for color-matching services and backward integration into acrylic monomer production.
Within the multinational chemical conglomerate tier, BASF SE and Dow Inc. exemplify integrated resin-to-coating architectures that control raw material cost exposure. Among specialized coatings companies, AkzoNobel N.V. and PPG Industries occupy positions where controlled distribution networks in Northern Europe and digital color platforms respectively embed specification loyalty. These named entities represent archetypes rather than exhaustive enumeration of market participants.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| BASF SE |
| Axalta Coating Systems Ltd. |
| Dow Inc. |
| Jotun A/S |
| Hempel A/S |
| Arkema |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up regional formulators in North America and Western Europe now control substantial acrylic emulsion capacity, disciplining spot-market volatility through long-term offtake contracts with housing developers and automotive tier suppliers. This ownership concentration tightens pricing coordination across architectural segments while compressing margin pools for unintegrated distributors caught between consolidated resin supply and specification-driven procurement.
Pricing Analysis
Capacity additions in China's Jiangsu and Zhejiang provinces are reshaping price floors for standard-grade acrylic emulsions, forcing European and North American producers toward premium polyurethane and self-crosslinking formulations. Three-tier pricing structure across premium, standard, and economy levels separates certified low-VOC architectural coatings from commodity interior latex. Price differentiation hinges on REACH and EPA compliance tier and volume scale commitments from large housing developers. Cost compression in economy-tier latex is intensifying because of naphtha-cracker volatility and Chinese export pricing. Construction contractors in unregulated South Asian markets exhibit highest price sensitivity; automotive OEMs in Stuttgart and Detroit show least.
Supply Chain Analysis
Acrylic acid and styrene monomer supply rests on naphtha-cracker economics concentrated in China, South Korea, and Germany. Specialty rheology modifiers and dispersants draw from Japanese and German chemical producers, creating procurement bottlenecks for high-performance formulations. Single-source vulnerability in isocyanate precursors for water-borne polyurethane threatens automotive coating supply continuity. Distribution runs through controlled specification networks anchored by digital color platforms in Northern Europe and direct sales teams serving Gulf Coast marine yards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Water-Based Coatings Market functions as a stable compounder, with regulatory displacement of solvent systems providing durable volume tailwinds across construction and automotive end uses.
For Market Incumbents: To counter feedstock volatility and margin compression in standard-grade emulsions, deepen backward integration into acrylic monomer production and anchor specification loyalty through captive digital color platform subscriptions with large architectural clients. For New Entrants and Emerging Players: Regional distributors in India's Maharashtra and Gujarat construction markets offer the most penetrable channel structure, as mandatory BIS IS 15489 compliance displaces unorganized supply and creates structured entry for certified multinationals willing to invest in local tinting infrastructure and technician training programs. For Investors and Strategic Acquirers: Specialty chemicals conglomerates with adjacent polymer portfolios are the most active acquirers in this space, targeting mid-cap formulators with controlled distribution in marine and protective segments. The long-term viability window favors assets with REACH and EPA certification infrastructure already deployed. Watch MEE enforcement intensity in China's coastal provinces as the critical inflection signal for competitive repositioning in traded product segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Production | Captive supply of styrene and acrylate precursors insulates margin pools from naphtha-cracker volatility in Northeast Asia. |
| Digital Color Platform Deployment | Cloud-based tinting systems with PPG Industries' architecture embed recurring revenue and specification lock-in with German housing developers. |
| Radiation Curing Technology Adoption | UV-LED integration with water-borne wood coatings enables 3-second line speeds for High Point furniture manufacturers. |
| BIS Certification Infrastructure Investment | IS 15489 compliance capability opens structured access to India's Maharashtra and Gujarat construction markets displacing unorganized supply. |
| Hybrid Core-Shell Polymer R&D Expansion | Self-crosslinking acrylic emulsions with polyurethane-grade abrasion resistance consolidate procurement categories for North American housing developers. |
Research Methodology
Bottom-up architectural and automotive coatings modeling reconciled against top-down emulsion polymerization capacity tracking forms the analytical core of this study. Primary interviews with plant managers at Jiangsu and Zhejiang manufacturing clusters, procurement leads at Stuttgart and Detroit automotive tier suppliers, distribution channel partners in Northern Europe, and technical R&D directors at German chemical parks were validated against secondary sources including customs and trade data from China and India, Cefic and ACC industry reports, SEC 10-K filings from listed coatings companies, and EPA NESHAP regulatory filings.
Historical trendline analysis across resin chemistry, technology, application, and end-user dimensions established baseline growth patterns. Segmentation models incorporated grade tier, end-use industry, regional production hub, and compliance certification level. CAGRs were derived from regression-adjusted trend extrapolation incorporating feedstock cost trajectories and regulatory phase-down schedules. Forecast inputs included MEE enforcement intensity projections for China GB standards and BIS certification expansion timelines for Indian architectural markets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to naphtha-cracker economics, REACH SVHC list expansions, and automotive OEM water-borne system qualification rates. Forecasts reflect documented assumptions about regulatory enforcement continuity and polymer synthesis technology diffusion. A small set of triggers—MEE inspection intensity in coastal China, BIS inspectorate staffing in Maharashtra, and EPA NESHAP compliance deadline adherence—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Metallic Powder Coating Market
Coatings
US Concrete Floor Coatings Market
Coatings
Saudi Arabia Floor Coatings Market
Coatings
South Korea Marine Coatings Market
Coatings
Phosphate Conversion Coatings Market
Coatings
Waterborne Wood Coatings Market
Coatings
Global Automotive Specialty Coatings Market
Coatings
Japan Protective Coatings Market
Coatings
Coating Auxiliaries Market
Coatings
OEM Coatings Market
Coatings
Vacuum Coating Machine Market
Coatings
Perfluoroalkoxy (PFA) Coatings Market
Coatings
Egyptian Protective Coatings Market
Coatings
Energy Efficient Powder Coatings Market
Coatings
Leisure Boat Marine Coatings Market
Coatings
Gelcoat Market