
 Automotive OEM Coatings Market | 2026-2036
Automotive OEM Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive OEM Coatings Market Intelligence
The European Union's REACH regulation is recalibrating the cost-of-entry calculus for automotive OEM coatings, demanding significant investment in compliant chemistry. BASF SE leverages its global R&D network to develop low-VOC formulations that meet these standards. PPG Industries Inc. sustains its market position through large-scale supply agreements with major automakers in North America and Europe. Axalta Coating Systems LLC specializes in high-performance clearcoats for premium vehicle lines, navigating complex customer specifications.
Automotive OEM coatings are multi-layered systems applied sequentially during vehicle manufacturing. These systems, including an electrocoat, primer, basecoat, and clearcoat, provide crucial corrosion protection and a high-quality aesthetic finish. Waterborne technologies are displacing traditional solvent-borne systems to meet environmental mandates. Within product types, advanced clearcoats offering scratch resistance command premium pricing, while the basecoat segment determines the vehicle's final color and appearance.
Compliance frameworks, including the US EPA's rules on hazardous air pollutants and China's GB standards, dictate permissible VOC levels in coatings. The European Chemicals Agency (ECHA) further governs market access by restricting specific substances under REACH. A coating supplier's competitive advantage will depend on its ability to navigate these complex and often divergent international chemical regulations.
Market Dynamics
The central dynamic shaping the automotive OEM coatings market is the intense pressure from global environmental regulations. This forces a rapid technological pivot towards waterborne systems, especially as EV production introduces new substrate and performance requirements.
Growth Catalysts
- Electric Vehicle Expansion:Demand for specialized coatings for electric vehicle battery casings and lightweight composite exterior panels creates new, high-value application segments for coating suppliers.
- Regulatory Mandates:Stringent VOC emission standards, including the EU Green Deal and China's GB standards, accelerate the industry-wide transition from solvent-borne to compliant waterborne technologies.
- Production Geography:New automotive manufacturing investments in Mexico and continued production scale in China solidify these countries as central consumption hubs for high-volume OEM coatings.
Market Restraints
- Raw Material Volatility:Price fluctuations in key feedstocks, particularly titanium dioxide and specialized epoxy resins, directly impact the cost structure and margin stability for coating manufacturers.
- Divergent Regulations:Navigating conflicting chemical inventories and substance restrictions between the EU's REACH and the US EPA's rules on hazardous air pollutants increases compliance complexity and cost.
- Processing Bottlenecks:Waterborne coatings typically require longer curing times and more sophisticated climate control in paint shops compared to solvent-borne systems, posing a challenge to vehicle production throughput.
Strategic Opportunities
- Functional Clearcoats:Developing advanced clearcoats with integrated functionalities like enhanced scratch resistance or self-healing properties opens a premium-priced market segment beyond standard aesthetic finishes.
- Bio-Based Formulations:The integration of bio-based resins and solvents into coating formulations provides a distinct sustainability advantage, aligning with automakers' corporate environmental goals.
- Indian Automotive Sector:The expanding automotive manufacturing base in India represents a significant volume growth opportunity for coating suppliers able to establish local production and supply chains.
Industry Challenges
- Application Skills Gap:A shortage of technicians with the expertise to operate and maintain the sophisticated application and curing equipment required for modern waterborne and high-solids coating systems.
- Substrate Adhesion Complexity:Ensuring consistent adhesion and color harmony across the diverse mix of substrates on a single vehicle, including steel, aluminum, and carbon fiber composites, is a major technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive OEM Coatings Market |
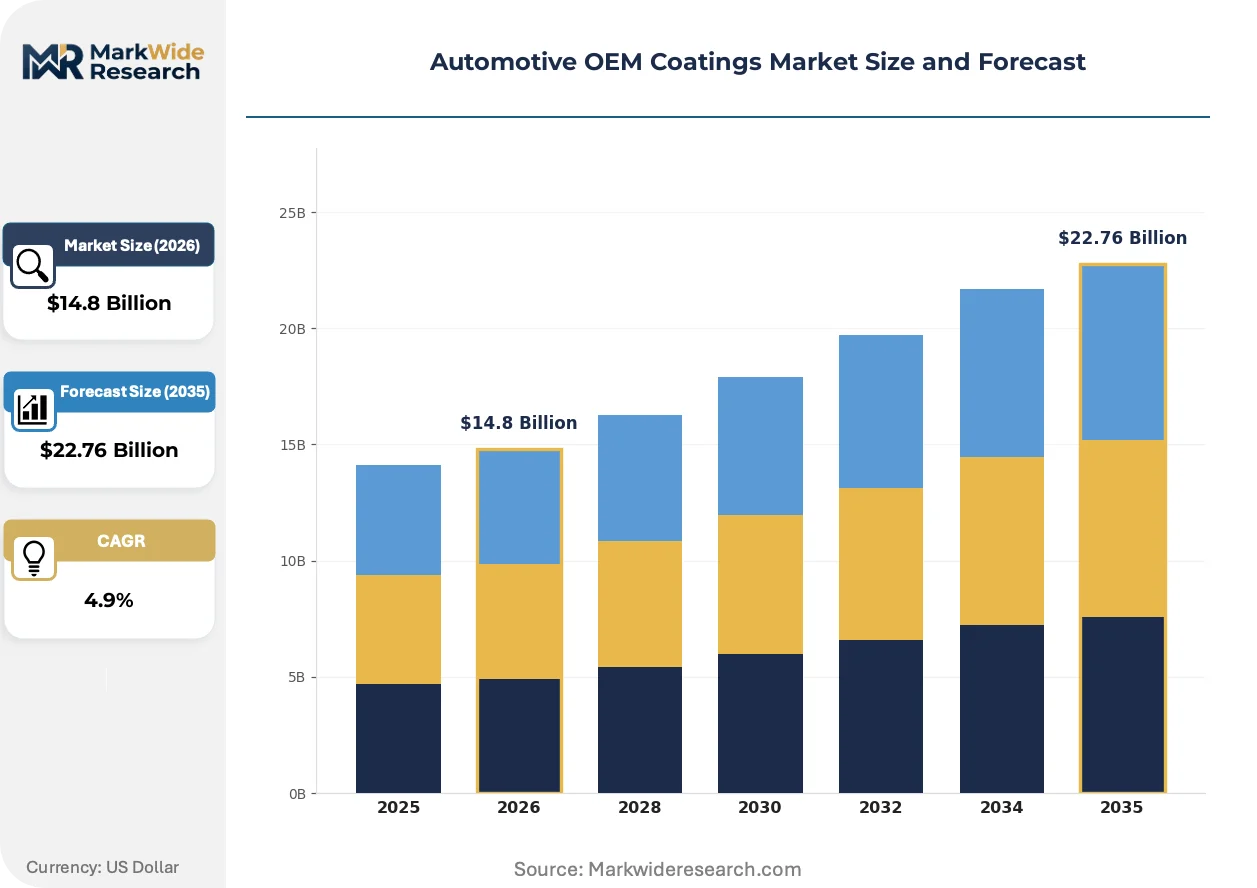
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.76 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primer, Basecoat, Clearcoat, Electrocoating Technology: Waterborne, Solvent-borne, Powder, UV-cured Application: Exterior Panels, Interior Components, Engine Parts, Chassis End User: Vehicle Assemblers, Tier-1 Suppliers, Dealerships, Aftermarket Providers |
| Companies Covered | BASF SE, PPG Industries Inc., Nippon Paint Holdings Co., Ltd., Akzo Nobel N.V., Axalta Coating Systems LLC, The Sherwin-Williams Company, Kansai Paint Co., Ltd., KCC Corporation, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive OEM Coatings Market Strategic Shifts & Innovations
Material science innovation and stringent environmental mandates are converging to fundamentally re-engineer coating systems. This shift prioritizes functional performance and regulatory compliance alongside traditional aesthetics, altering product development cycles for all suppliers.
Digital color matching software provides precise formulation using cloud-based spectrophotometer data. OEM paint shops are adopting this technology to ensure global color consistency. This software is decentralizing color expertise, embedding it within a replicable digital process instead of relying on individual technician skill.
The European Union's REACH regulation governs the chemical composition of coatings sold within the bloc. This framework restricts specific substances like certain isocyanates, compelling complete product reformulation. The electrocoat and primer segments are most impacted, accelerating R&D into alternative, compliant chemistries to maintain market access.
Automaker procurement is evolving to specify coatings based on functional performance, such as infrared reflectivity for thermal management. This shifts the purchasing decision from design studios to engineering departments. The trend is most prominent in the electric vehicle sector for battery casing coatings.
Automotive OEM Coatings Market Segmentation
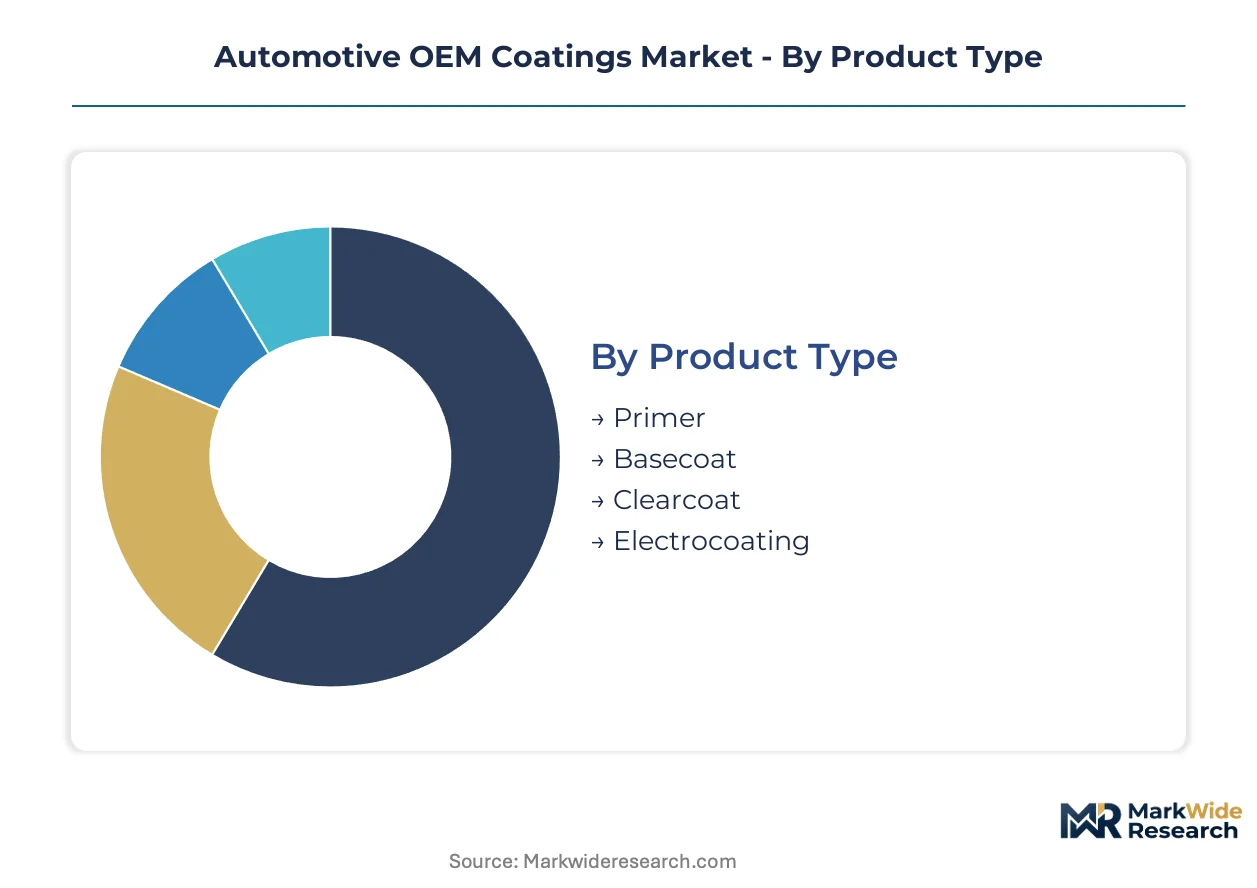
The automotive OEM coatings market segments based on the diverse functional and aesthetic requirements of vehicle manufacturing. Understanding these distinctions helps suppliers align product development with specific automaker needs. Each segment addresses unique performance criteria, from corrosion resistance to exterior finish quality. This granular view clarifies where technological innovation and regulatory compliance exert the most pressure.
Product Type:
Automaker purchasing decisions for coating systems hinge on the specific layer's functional contribution to the vehicle's overall durability and appearance.
- Primer:Primers create a smooth surface for subsequent layers and enhance chip resistance for the overall coating system.
- Basecoat:Basecoats deliver the vehicle's primary color and aesthetic effects, containing pigments and metallic flakes. This segment sees high demand in all automotive production hubs, including China and Mexico, as it defines the final visual appeal.
- Clearcoat:Clearcoats form the outermost layer, providing UV protection, gloss, and scratch resistance to the underlying basecoat. Demand concentrates in premium vehicle lines, where advanced clearcoats with self-healing properties command higher pricing.
- Electrocoating:Electrocoating provides the initial corrosion protection and adhesion layer directly onto the vehicle body.
Electrocoating leads on scale due to its universal application; Clearcoat leads on momentum with its advanced functional properties.
Technology:
The maturity of coating technologies influences their adoption rates and compliance with environmental mandates across global markets.
- Waterborne:Waterborne coatings use water as the primary solvent, significantly reducing volatile organic compound (VOC) emissions. Demand is accelerating in the European Union and China due to stringent VOC emission standards like the EU Green Deal.
- Solvent-borne:Solvent-borne systems rely on organic solvents for pigment dispersion and resin dissolution, offering robust performance. While still used in some regions, this technology faces displacement by compliant alternatives under global environmental regulations.
- Powder:Powder coatings provide durable, chip-resistant finishes without solvents, often used for chassis and underbody components.
- UV-cured:UV-cured coatings offer rapid curing times and high hardness, finding niche applications in specialized component finishing.
Waterborne technologies are expanding most quickly, driven by regulatory compliance and sustainability goals.
Application:
Application-specific performance requirements dictate the type and formulation of coatings used across different vehicle parts.
- Exterior Panels:Exterior panel coatings provide the primary aesthetic finish, UV protection, and corrosion resistance for visible body parts. This segment demands high-quality basecoats and clearcoats, especially for electric vehicles requiring specialized finishes for composite panels.
- Interior Components:Interior component coatings focus on tactile feel, scratch resistance, and aesthetic integration with cabin designs.
- Engine Parts:Coatings for engine parts require high heat resistance, chemical inertness, and protection against fluids and corrosion. Specialized coatings are critical for thermal management and durability in both internal combustion and electric vehicle powertrains.
- Chassis:Chassis coatings provide robust corrosion protection and impact resistance for the underbody and structural components.
Exterior Panels represent the largest volume segment, while Engine Parts coatings show the steepest expansion trajectory due to EV demands.
End User:
The type of end-user determines the scale of supply agreements and the technical support required from coating manufacturers.
- Vehicle Assemblers:Vehicle assemblers integrate multi-layered coating systems directly onto vehicle bodies in their paint shops. This segment represents the largest volume consumption, with major automakers in China and North America driving significant procurement.
- Tier-1 Suppliers:Tier-1 suppliers apply coatings to various components like plastic bumpers, wheels, and interior parts before assembly. Demand here focuses on specialized coatings for specific substrates and high-volume component finishing for automakers.
- Dealerships:Dealerships use coatings for minor repairs, touch-ups, and protective film applications on new or used vehicles.
- Aftermarket Providers:Aftermarket providers supply coatings for collision repair, custom paint jobs, and restoration projects for older vehicles.
Vehicle Assemblers account for the bulk of OEM coating consumption, with Tier-1 Suppliers gaining share fastest through specialized component work.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A highly skilled automotive manufacturing workforce anchors global demand for OEM coatings, particularly in regions with established production capabilities. These specialized coatings are crucial for vehicle durability and aesthetic appeal across diverse markets. Environmental regulations significantly influence technological shifts in these manufacturing hubs.
China
Demand for advanced coatings for electric vehicle production drives the Chinese market. China's GB standards enforce strict VOC limits, accelerating waterborne technology adoption. Major automotive clusters in the Yangtze River Delta, like Shanghai, are seeing significant investment in compliant paint shop infrastructure.
Germany
German automakers prioritize high-performance clearcoats and corrosion protection for premium vehicle lines. The EU Green Deal and ECHA regulations compel continuous innovation in low-VOC formulations. The Stuttgart region, home to several major OEMs, focuses on developing sustainable coating solutions.
Mexico
New automotive manufacturing investments in Mexico solidify its role as a central consumption hub for OEM coatings. The country's environmental regulations, aligned with North American standards, promote efficient application processes. Production facilities in states like Nuevo León are expanding to meet export demands for finished vehicles.
India
India's expanding automotive manufacturing base represents a significant volume growth opportunity for coating suppliers. The Bureau of Indian Standards (BIS) sets quality and environmental norms for automotive components. Chennai, a major automotive production center, is attracting new investments in coating supply chains.
United States
United States vehicle assemblers require high-volume coating systems for diverse vehicle segments. The US EPA's rules on hazardous air pollutants influence coating formulations and application technologies. The Detroit automotive cluster continues to drive innovation in multi-substrate adhesion and aesthetic finishes.
Automotive OEM Coatings Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists within the automotive OEM coatings market. The market structure is moderately consolidated at the top tier, with several large chemical companies holding significant market share. Strategic archetypes include global chemical giants offering broad portfolios and specialized coating providers focusing on niche applications. Competitive moves center on R&D investment in compliant chemistries and securing long-term supply agreements with major automakers.
Global chemical giants like BASF SE and PPG Industries Inc. represent the scale-driven end of the market, leveraging extensive R&D networks and established supply chains across multiple continents. BASF SE leverages its global R&D network to develop low-VOC formulations that meet stringent environmental standards. PPG Industries Inc. sustains its market position through large-scale supply agreements with major automakers in North America and Europe. Axalta Coating Systems LLC exemplifies a specialized player, focusing on high-performance clearcoats for premium vehicle lines and navigating complex customer specifications. These companies anchor market stability while driving technological advancements in waterborne and functional coatings.
| Leading Market Players |
|---|
| BASF SE |
| PPG Industries Inc. |
| Nippon Paint Holdings Co., Ltd. |
| Akzo Nobel N.V. |
| Axalta Coating Systems LLC |
| The Sherwin-Williams Company |
| Kansai Paint Co., Ltd. |
| KCC Corporation |
| Covestro AG |
| Others |
Cost & Logistics Intelligence
Captive supply arrangements, common for major automotive OEMs, anchor both the long-term supply position and the pricing power for specialized coatings. This integration ensures material availability and cost predictability amidst volatile raw material markets.
Pricing Analysis
Bundled service offerings, including technical support and application expertise, often influence pricing structures in automotive OEM coatings. Contract-based long-term offtake agreements dominate, with price differentiation driven by coating quality grade for performance-critical layers and customization levels for specialized finishes. Automaker procurement's focus on cost efficiencies exerts consistent pricing pressure across standard segments. Vehicle assemblers show less price sensitivity for high-performance clearcoats, while aftermarket providers are highly price-sensitive for basic repair coatings.
Supply Chain Analysis
Domestic content mandates in regions like China and Mexico are reshaping sourcing strategies for automotive OEM coatings. Supply concentrates heavily in established automotive manufacturing hubs such as Germany, China, and Mexico. The industry draws from key raw materials like titanium dioxide and specialized epoxy resins. Commodity price volatility, particularly for these feedstocks, represents a significant structural supply chain risk. Distribution runs primarily through direct supply agreements with vehicle assemblers and Tier-1 suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive OEM coatings market presents a late-cycle quality story, driven by automakers' demand-shift towards premium specifications for durability and aesthetics. This evolution prioritizes advanced functional performance over basic cost considerations.
For Market Incumbents: Lock in long-term supply agreements with major vehicle assemblers to secure volume and market share. Invest heavily in global R&D networks to develop advanced low-VOC formulations, mitigating the threat of stringent environmental regulations like the EU Green Deal. Diversify raw material sourcing to buffer against commodity price volatility. Offer integrated technical support to deepen customer relationships and counter emerging niche competitors. For New Entrants and Emerging Players: Capture niche opportunities in specialized coatings for electric vehicle battery casings and lightweight composite panels. The expanding automotive manufacturing base in India represents a highly penetrable volume growth opportunity. Focus on developing advanced functional clearcoats with self-healing properties, offering a distinct value proposition. Leverage bio-based formulations to provide a sustainability advantage, aligning with automaker environmental goals. For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory compliance demands significant R&D investment and specialized manufacturing capabilities. The market offers sustained long-term viability over the next decade due to continuous demand for high-performance, compliant coatings. Target specialized players with proven expertise in waterborne technologies or advanced functional clearcoats. Increased R&D spending by smaller firms on alternative chemistries serves as a key inflection indicator for potential M&A activity.| Strategic Initiative | Industry Significance |
|---|---|
| Develop Bio-Based Formulations | Aligns with automakers' corporate environmental goals and sustainability mandates. |
| Expand Waterborne Production Capacity | Meets stringent VOC emission standards, particularly in the European Union and China. |
| Secure EV Battery Casing Coating Contracts | Addresses new, high-value application segments within electric vehicle manufacturing. |
| Invest in Digital Color Matching Software | Ensures global color consistency and decentralizes color expertise across OEM paint shops. |
| Establish Local Production in Emerging Markets | Capitalizes on volume growth opportunities in countries like India and Mexico. |
Research Approach
Coverage spans China, Germany, Mexico, India, and the United States, with primary inputs from each key region. This analysis integrates in-depth interviews with OEM procurement managers, Tier-1 R&D directors, coating formulation chemists, and environmental compliance officers. Secondary validation draws from automotive production databases, environmental agency reports, industry association publications, and company financial filings. A rigorous bottom-up and top-down triangulation approach ensures data accuracy.
Rate-of-change decomposition underpins the analytical framework applied across the analysis window. The model segments the market by product type, technology, application, end-user, and regional automotive production clusters. Compound Annual Growth Rates (CAGRs) are derived from historical trends, market drivers, and expert projections. Key forecast inputs include electric vehicle production forecasts and regulatory compliance timelines for VOC emissions.
Raw material price volatility, geopolitical trade policies, and unexpected shifts in automotive production are the dominant revision risks. Forecasts reflect a specific set of macroeconomic and technological assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Fire Resistant Paints Market
Paints & Coatings
Refinish Paint Market
Paints & Coatings
Low VOC Paint Market
Paints & Coatings
Europe Paints and Coatings Additives Market
Paints & Coatings
Asia-Pacific Paints and Coatings Market
Paints & Coatings
Industrial Paint Booth Market
Paints & Coatings
Nano Paints and Coatings Market
Paints & Coatings
Middle East and Africa Floor Coatings Market
Paints & Coatings
Global Decorative Paints and Coatings Market
Paints & Coatings
Global Texture Paint Market
Paints & Coatings
Middle-East and Africa Wood Coatings Market
Paints & Coatings
Paints and Coatings Additives Market
Paints & Coatings
India Architectural Coatings Market
Paints & Coatings
India Floor Coatings Market
Paints & Coatings
India Paints and Coatings Market
Paints & Coatings
Middle East & Africa Corrosion Protection Coating Market