
 Industrial Solid Waste Management Market | 2026-2036
Industrial Solid Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Solid Waste Management Market Analysis
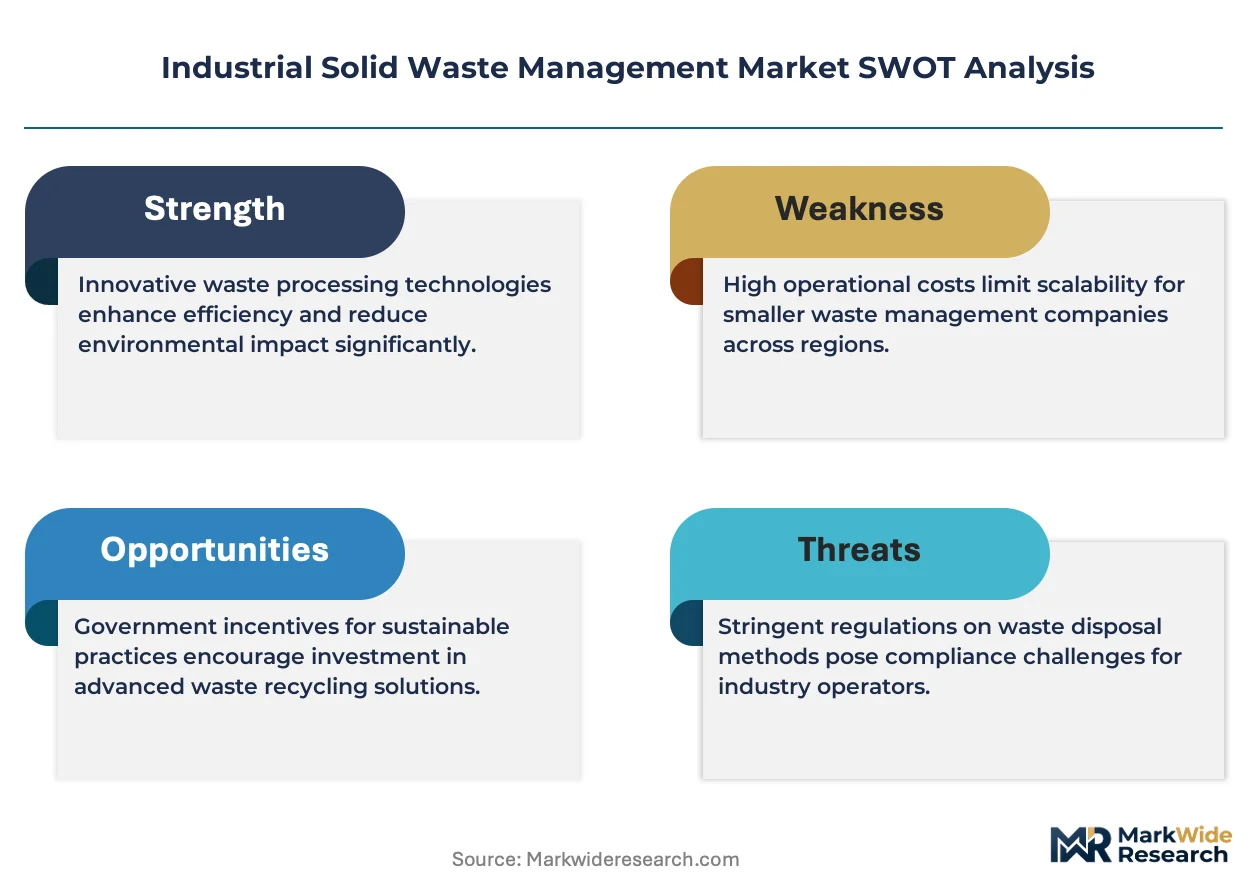
Landfill tipping fee revenue is fragmenting across regional markets as treatment-based alternatives capture margin pools. Waste Management Inc leverages its North American network density to sustain collection profitability. Veolia Environnement SA anchors European market access through multi-service municipal contracts. Republic Services Inc competes on post-collection vertical integration, controlling transfer station-to-landfill throughput.
Industrial solid waste management encompasses the systematic handling of non-liquid discarded materials from manufacturing, construction, and institutional sources through collection, transportation, treatment, and final disposal or recovery processes. Operations typically manage waste streams with calorific values ranging from 8-15 MJ/kg for municipal-industrial blends, requiring thermal treatment systems operating at 850-1,100°C for complete combustion. Non-hazardous waste services dominate volume throughput due to manufacturing and construction sector scale. Recycling margins concentrate in electronic waste fractions where precious metal recovery justifies capital-intensive sorting infrastructure. Hazardous waste treatment commands premium pricing through specialized incineration and stabilization requirements.
EPA Subtitle D standards shape US landfill design and leachate management, while the EU Waste Framework Directive mandates hierarchical preference for prevention, reuse, and recycling over disposal. China's MEE enforces dual carbon-aligned waste reduction targets that redirect industrial slag and ash toward construction material substitution. India's CPCB landfill remediation directives and extended producer responsibility frameworks are tightening compliance timelines for bulk waste generators. Stakeholders must monitor regulatory divergence between jurisdictions where carbon border adjustments could revalue domestic recycling capacity against imported secondary raw materials.
Market Dynamics
Landfill diversion mandates across Asia-Pacific manufacturing corridors are compressing collection-to-disposal margins and forcing capital redeployment toward thermal treatment and anaerobic digestion infrastructure. China's dual carbon targets and India's Swachh Bharat compliance timelines are accelerating this structural pivot.
Growth Catalysts
- Waste-to-Energy Mandates:China's MEE enforces carbon-aligned reduction targets that redirect industrial slag toward construction material substitution, creating captive demand for thermal processing capacity.
- EU Waste Framework Directive:Hierarchical preference for prevention, reuse, and recycling over disposal is tightening landfill access and elevating treatment-based alternatives.
- India's Industrial Corridor Development:Bulk waste generator obligations under CPCB remediation directives are driving integrated infrastructure investment across manufacturing zones.
Market Restraints
- Capital Intensity for Sorting Infrastructure:Precious metal recovery from electronic waste fractions requires capital-intensive automated sorting systems that strain mid-tier operator balance sheets.
- Regulatory Divergence Risk:Carbon border adjustment mechanisms under EU Green Deal implementation could revalue domestic recycling capacity against imported secondary raw materials, creating compliance friction for exporters.
- Calorific Variability:Municipal-industrial blend streams ranging 8-15 MJ/kg require flexible thermal system design that increases operational complexity and maintenance cycles.
Strategic Opportunities
- India's Underpenetrated Treatment Market:Swachh Bharat Mission Phase II funding gaps in secondary cities present white space for anaerobic digestion and composting facility development.
- Advanced Sorting Convergence:Integration of near-infrared spectroscopy with robotics is enabling higher-purity fraction recovery from complex industrial mixed waste streams.
- Extended Producer Responsibility Expansion:India's EPR frameworks for bulk waste generators are mandating producer-funded collection infrastructure that shifts capex burden upstream.
Industry Challenges
- Specialized Incineration Expertise Gap:Hazardous waste treatment at 850-1,100°C requires certified operators and maintenance technicians that outpace vocational training pipeline capacity.
- Legacy Landfill Remediation Timelines:India's CPCB directives for legacy site closure impose parallel compliance obligations that divert management attention from greenfield treatment investments.
- Leachate Management Complexity:EPA Subtitle D standards for landfill design impose ongoing monitoring and treatment costs that compress residual site economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Solid Waste Management Market |
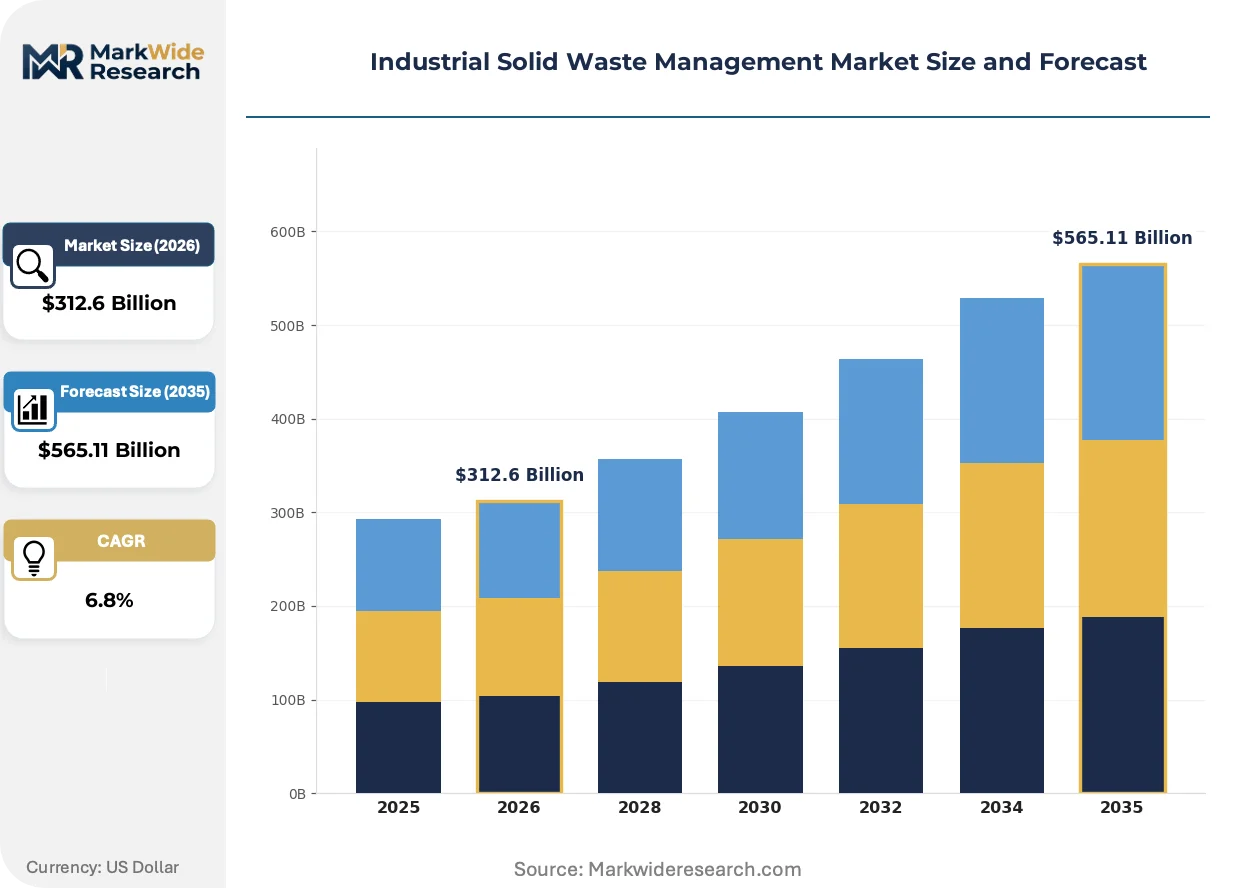
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Waste Type: Hazardous Waste, Non-Hazardous Waste, Biomedical Waste, Electronic Waste Service Type: Collection, Transportation, Treatment, Recycling End User: Manufacturing, Construction, Healthcare, Retail Treatment Method: Landfilling, Incineration, Composting, Anaerobic Digestion |
| Companies Covered | Waste Management Inc, Veolia Environnement SA, Republic Services Inc, SUEZ SA, Clean Harbors Inc, Covanta Holding Corporation, Stericycle Inc, GFL Environmental Inc, Remondis SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Solid Waste Management Market Emerging Trajectories
Anaerobic digestion and advanced thermal treatment systems are displacing conventional landfill-dependent models across Asia-Pacific industrial zones. Technology convergence with carbon capture and digital monitoring is reshaping facility economics and compliance architectures.
Plasma gasification technology converts industrial waste streams into synthetic gas and vitrified slag at temperatures exceeding 3,000°C. Steel and cement manufacturers in China and South Korea are piloting integrated installations to displace fossil feedstocks. Conventional grate combustion for low-calorific industrial waste is rendering obsolete as gasification yields superior energy recovery rates and residual material valorization.
China's MEE dual carbon targets mandate industrial waste reduction quotas that redirect slag and ash toward construction material certification. GB standards alignment for recycled aggregate quality is forcing batching plant operators to source from licensed treatment facilities rather than uncontrolled landfill extraction. Cement producers in the Yangtze River Delta are responding by securing long-term offtake agreements with gasification operators.
Service unbundling is fragmenting traditional collection-treatment-disposal contracts into discrete performance-based modules. Manufacturing facilities in India's Pune and Chennai industrial belts are procuring waste characterization, transportation, and thermal treatment from separate specialized providers rather than integrated municipal concessionaires. This procurement pattern is most visible in automotive and electronics assembly verticals where EPR compliance requires documented chain-of-custody verification.
Industrial Solid Waste Management Market Segmentation
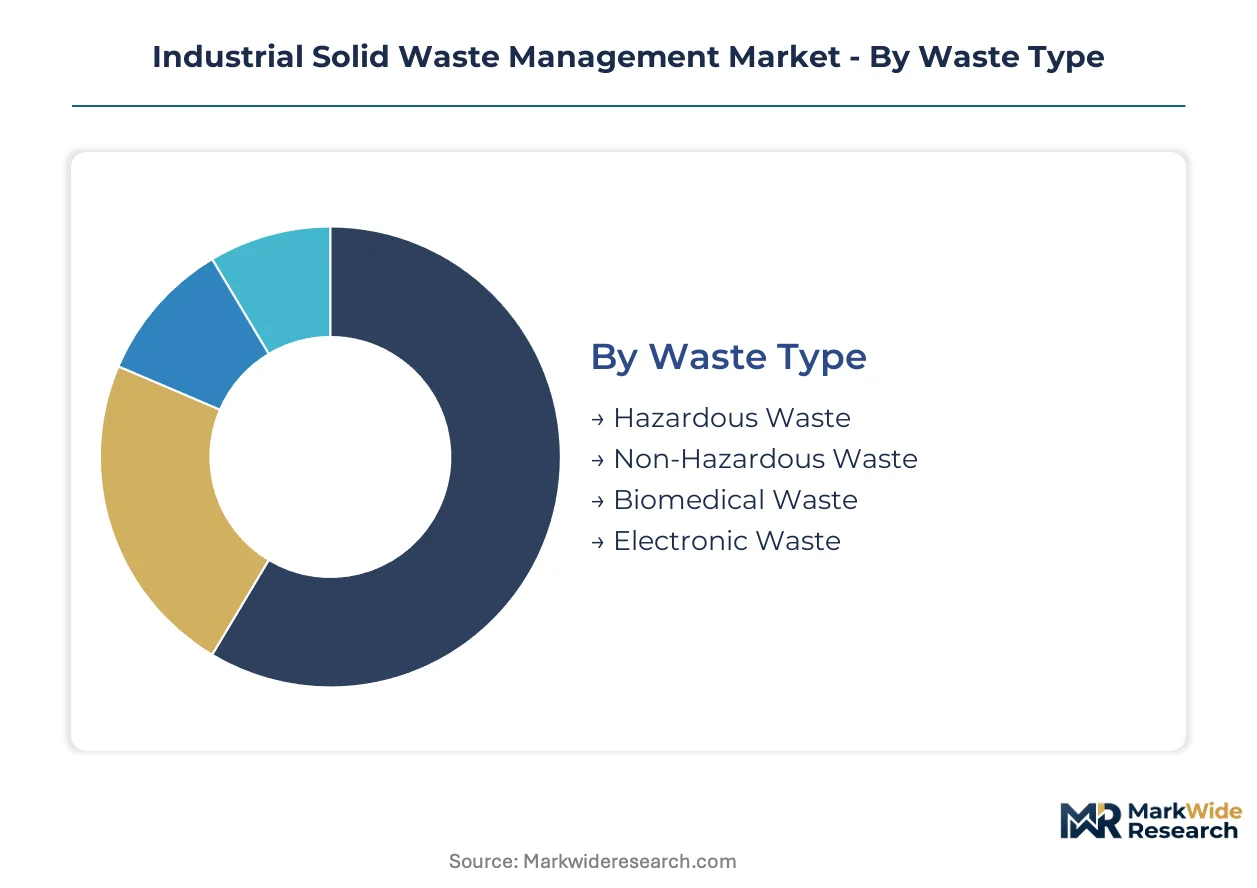
Segmentation in industrial solid waste management determines capital deployment cycles and margin capture. Treatment method selection locks in decade-long infrastructure commitments, while waste type classification triggers distinct regulatory compliance architectures.
Waste Type:
Cycle times vary dramatically: non-hazardous waste streams turn weekly through collection networks, while hazardous waste treatment stretches across quarter-long stabilization and manifest documentation cycles.
- Non-Hazardous Waste:Manufacturing slag, packaging debris, and construction debris dominate volume throughput. India's CPCB bulk waste generator mandates and China's MEE dual carbon targets are redirecting these streams from landfill toward construction aggregate certification and thermal recovery.
- Hazardous Waste:Sludges, solvents, and contaminated soils require specialized incineration at 850-1,100°C or chemical stabilization. Treatment capacity concentrates in China's Yangtze River Delta and India's Gujarat industrial corridor where EPA-aligned technical standards apply to export-oriented facilities.
- Biomedical Waste:Sharps, pathological specimens, and infectious materials demand autoclave or incinerator destruction with chain-of-custody documentation. Healthcare facility clusters in Chennai and Pune drive localized collection network density.
- Electronic Waste:Circuit boards and battery fractions contain recoverable precious metals requiring automated dismantling and hydrometallurgical processing. China's GB standards for recycled content mandate producer-funded collection infrastructure.
Non-hazardous waste dominates installed base. Electronic waste is where expansion concentrates.
Service Type:
Cost tier stratification separates commodity collection from premium treatment services. Collection and transportation operate on thin margins with asset-heavy vehicle fleets, while treatment and recycling capture value through technical differentiation.
- Collection:Scheduled pickup from manufacturing facilities using compactor trucks and roll-off containers. India's Swachh Bharat Mission Phase II is formalizing informal sector participation through municipal concession contracts in secondary cities.
- Transportation:Long-haul transfer from collection points to treatment facilities via tippers and walking floor trailers. China's NMPA-aligned hazardous waste manifest systems mandate GPS-tracked vehicles for cross-province movements.
- Treatment:Thermal processing, biological stabilization, and physical separation at centralized facilities. Plasma gasification pilots in South Korea and China are displacing conventional grate combustion for industrial mixed waste.
- Recycling:Fraction recovery and secondary raw material production. Near-infrared spectroscopy integration with robotics is enabling higher-purity output from complex mixed streams in European sorting facilities.
Treatment commands the steepest margin expansion. Recycling is climbing the fastest as EPR frameworks shift capex burden upstream.
End User:
Application intensity drives service customization. Manufacturing generates predictable high-volume streams suitable for long-term contracts, while construction and retail produce episodic, geographically dispersed loads.
- Manufacturing:Automotive, electronics, and steel plants generate metal-rich slag and packaging waste. China's GB standards for recycled aggregate quality force batching plants to source from licensed treatment facilities.
- Construction:Demolition debris and excavation spoil require mobile crushing and soil remediation. India's industrial corridor development is concentrating demand in Delhi-Mumbai and Chennai-Bengaluru freight corridors.
- Healthcare:Hospitals and clinics produce regulated biomedical fractions. CPCB color-coded segregation mandates in India are expanding specialized collection vehicle fleets.
- Retail:Distribution centers generate cardboard, plastic film, and damaged goods. Reverse logistics integration with e-commerce platforms is reshaping collection scheduling in urban India.
Manufacturing anchors contract volume. Construction is gaining share fastest as infrastructure investment accelerates.
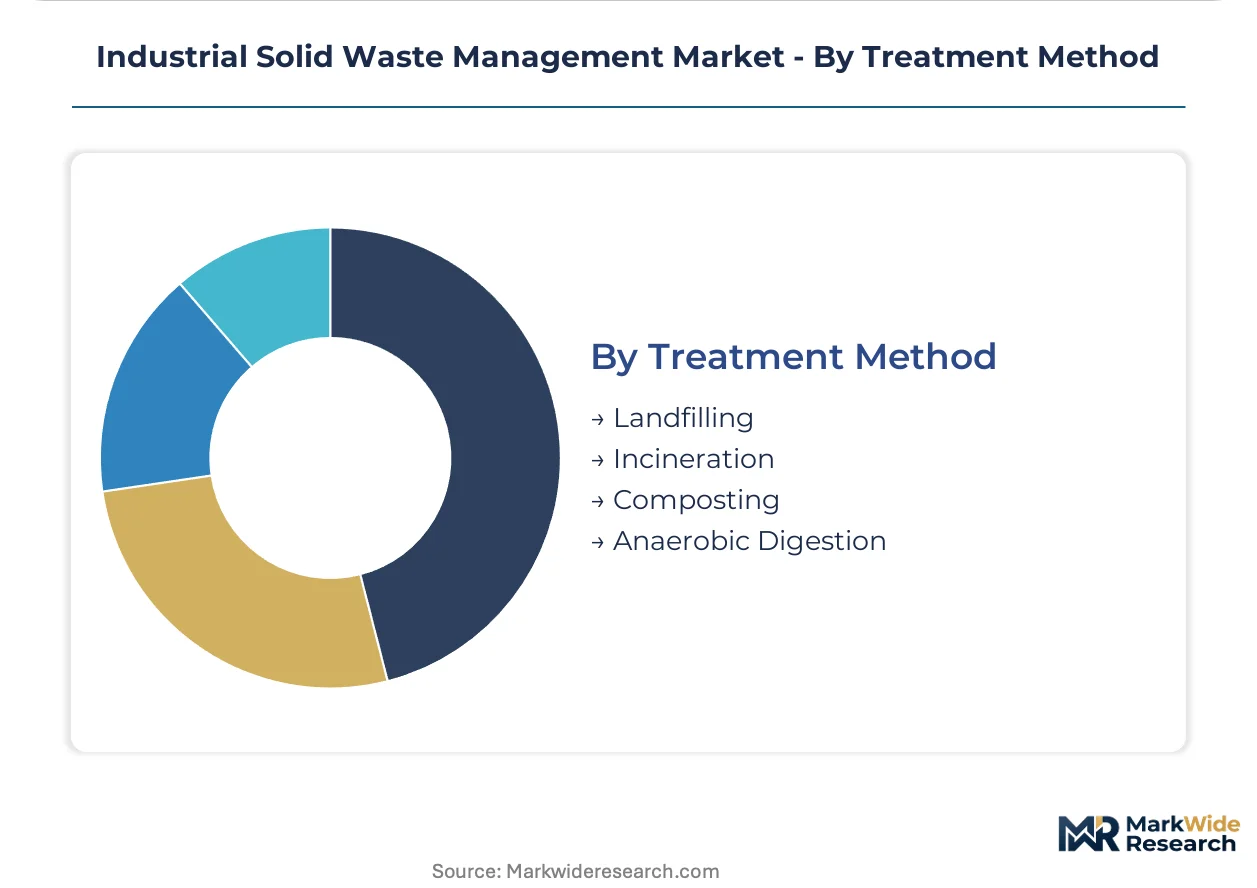
Treatment Method:
Maturity curves separate legacy landfill dependence from emerging biological and thermal recovery. Incineration and landfilling represent depreciated asset bases, while anaerobic digestion and advanced composting attract greenfield capital.
- Incineration:Grate combustion and rotary kiln systems operating at 850-1,100°C for complete destruction. China's MEE carbon-aligned quotas redirect industrial slag toward construction material substitution rather than thermal disposal.
- Landfilling:Engineered cell construction with leachate collection and gas recovery. EPA Subtitle D standards in the US and EU Landfill Directive constraints are compressing new site approvals.
- Composting:Aerobic decomposition of organic industrial fractions into soil amendments. India's Swachh Bharat Mission is funding mechanized composting facilities in secondary cities with <100,000 population.
- Anaerobic Digestion:Oxygen-free biogas generation from food processing and agricultural residues. EU Waste Framework Directive hierarchical preference is elevating this method above incineration for biodegradable fractions.
Landfilling dominates installed base. Anaerobic digestion is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys thermal processing at industrial scale while India concentrates on biological treatment expansion; Germany and the United States emphasize circular economy compliance with divergent regulatory architectures.
China
Steel and cement manufacturers in the Yangtze River Delta pilot plasma gasification installations to displace fossil feedstocks. MEE dual carbon targets mandate industrial waste reduction quotas that redirect slag toward construction material certification. Guangdong province batching plants now source recycled aggregate exclusively from licensed treatment facilities under GB standards alignment.
India
Automotive and electronics assembly clusters in Pune and Chennai drive demand for documented chain-of-custody verification. Swachh Bharat Mission Phase II funds mechanized composting facilities in secondary cities below 100,000 population. CPCB bulk waste generator obligations concentrate infrastructure investment across the Delhi-Mumbai and Chennai-Bengaluru freight corridors.
Germany
Multi-service municipal contracts anchor European market access for integrated waste operators. EU Waste Framework Directive hierarchical preference for prevention, reuse, and recycling tightens landfill access and elevates treatment-based alternatives. Industrial zones in North Rhine-Westphalia deploy anaerobic digestion capacity for food processing residues under federal circular economy implementation.
United States
Network density across metropolitan collection routes sustains post-collection profitability for major operators. EPA Subtitle D standards shape landfill design and leachate management requirements in Texas and California markets. Transfer station-to-landfill throughput control dominates competitive positioning in the Southeast and Midwest industrial corridors.
Japan
METI industrial efficiency mandates drive waste heat recovery integration at manufacturing facilities. JIS standards for recycled material quality certification redirect construction debris toward licensed processing rather than uncontrolled extraction. Osaka-Kobe manufacturing belt operators secure long-term offtake agreements with advanced thermal treatment providers.
Industrial Solid Waste Management Market Vendor Landscape
Capability concentration sits with specialized hazardous treatment operators; scale advantage sits with integrated collection-to-disposal networks. The market structures around three tiers: municipal concession holders with density-driven collection economics, technology-anchored thermal treatment specialists, and vertically integrated hazardous waste processors. Dominant competitive moves include strategic partnerships for anaerobic digestion capacity and geographic expansion through transfer station acquisitions.
Among North American integrated operators, Waste Management Inc and Republic Services Inc exemplify scale-driven network economics, while Veolia Environnement SA represents the European multi-service concession model. These three occupy positions across distinct competitive vectors—collection density, post-collection vertical control, and municipal contract anchoring—without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Waste Management Inc |
| Veolia Environnement SA |
| Republic Services Inc |
| SUEZ SA |
| Clean Harbors Inc |
| Covanta Holding Corporation |
| Stericycle Inc |
| GFL Environmental Inc |
| Remondis SE & Co. KG |
| Others |
Supply Flow & Price Mechanics
China's licensed treatment facility network for construction aggregate certification anchors upstream supply concentration, directing margin pools toward thermal processing operators with long-term offtake agreements in the Yangtze River Delta and Guangdong province.
Pricing Analysis
Long-term offtake contracts dominate hazardous waste treatment, while spot markets govern non-hazardous collection services. Price differentiation rests on EPA-aligned technical certification and volume scale, with premium tiers capturing hazardous incineration at 850-1,100°C. Cost compression in municipal collection runs through fuel and labor inputs. Small-scale generators exhibit highest price sensitivity; steel and cement manufacturers with dual carbon compliance obligations show lowest.
Supply Chain Analysis
Industrial slag and construction debris feedstocks concentrate in China, India, and South Korea where manufacturing corridor density is highest. Supply chains draw from demolition contractors, automotive assembly plants, and steel foundries for metal-rich fractions. Single-source vulnerability sits with plasma gasification technology licensors. Distribution runs through transfer station networks controlled by integrated operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as landfill diversion mandates across Asia-Pacific manufacturing corridors accelerate treatment infrastructure deployment.
For Market Incumbents: Build regulatory certification moats through EPA-aligned hazardous waste permits and MEE dual carbon quota compliance. Secure transfer station acquisitions in India's Delhi-Mumbai freight corridor to defend collection density. Add anaerobic digestion capacity in secondary cities under Swachh Bharat Mission Phase II funding to counter emerging biological treatment specialists. For New Entrants and Emerging Players: India's secondary cities below 100,000 population represent the most penetrable entry point for mechanized composting and anaerobic digestion facilities. Electronic waste fractions in Pune and Chennai automotive clusters offer precious metal recovery opportunities with lower capital barriers than thermal processing. Pursue EPR-mandated producer-funded collection contracts to bypass upfront vehicle fleet investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed hazardous waste specialists in China's Yangtze River Delta and India's Gujarat industrial corridor. Five-to-ten year viability hinges on regulatory enforcement consistency for landfill diversion. Watch CPCB remediation directive compliance timelines as inflection signal for greenfield treatment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Gasification Capacity Buildout | Steel manufacturers in South Korea displace fossil feedstocks through synthetic gas offtake agreements. |
| Backward Integration into Collection Networks | Thermal treatment operators secure feedstock supply certainty through municipal concession participation. |
| Extended Producer Responsibility Partnership | Electronics assemblers in Chennai fund dedicated collection infrastructure for documented chain-of-custody. |
| Near-Infrared Spectroscopy Deployment | European sorting facilities achieve higher-purity fraction recovery from complex industrial mixed waste. |
| Joint Venture for Anaerobic Digestion | Food processing residues in North Rhine-Westphalia generate biogas under EU Waste Framework Directive preference. |
Methodological Framework
Initial hypotheses were tested against primary input from thermal treatment facility operators, hazardous waste manifest coordinators, municipal procurement officers, and cement plant sourcing managers and refined through secondary validation. Bottom-up triangulation combined EPA enforcement records, MEE carbon quota disclosures, CPCB bulk waste generator registries, and EU landfill diversion statistics with top-down macroeconomic indicators.
Demand-supply balance modeling across the analysis window segmented by waste type, service tier, treatment method, and end-use intensity. CAGRs were derived from facility capacity expansion pipelines and regulatory compliance timeline assumptions. Forecast inputs included MEE dual carbon target enforcement probability and Swachh Bharat Mission Phase II allocation trajectories.
Practitioners should monitor carbon border adjustment mechanism implementation and GB standards alignment pace for early signals of forecast revision. Cross-checking against EU Waste Framework Directive landfill diversion rate benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Singapore Waste Management Market
Waste Management & Pollution Control
Reusable Oil Absorbents Market
Waste Management & Pollution Control
India Waste-To-Energy Market
Waste Management & Pollution Control
Asia-Pacific Municipal Solid Waste Management Market
Waste Management & Pollution Control
Biomedical Waste Management Market
Waste Management & Pollution Control
Metal Recycling Equipment Market
Waste Management & Pollution Control
Saudi Arabia Medical Waste Management Market
Waste Management & Pollution Control
Reusable Sediment Control Wattles Market
Waste Management & Pollution Control
Global Waste Management Software Market
Waste Management & Pollution Control
Trash Rakes Market
Waste Management & Pollution Control
Sharp Waste Disposal Market
Waste Management & Pollution Control
India Plastic Waste Management Market
Waste Management & Pollution Control
North America Industrial Waste Management Market
Waste Management & Pollution Control
Household Composters Market
Waste Management & Pollution Control
Paper Recycling Market
Waste Management & Pollution Control
Asia-Pacific Industrial Waste Management Market