
 Europe Municipal Solid Waste Management Market | 2026-2036
Europe Municipal Solid Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Municipal Solid Waste Management Market Insights
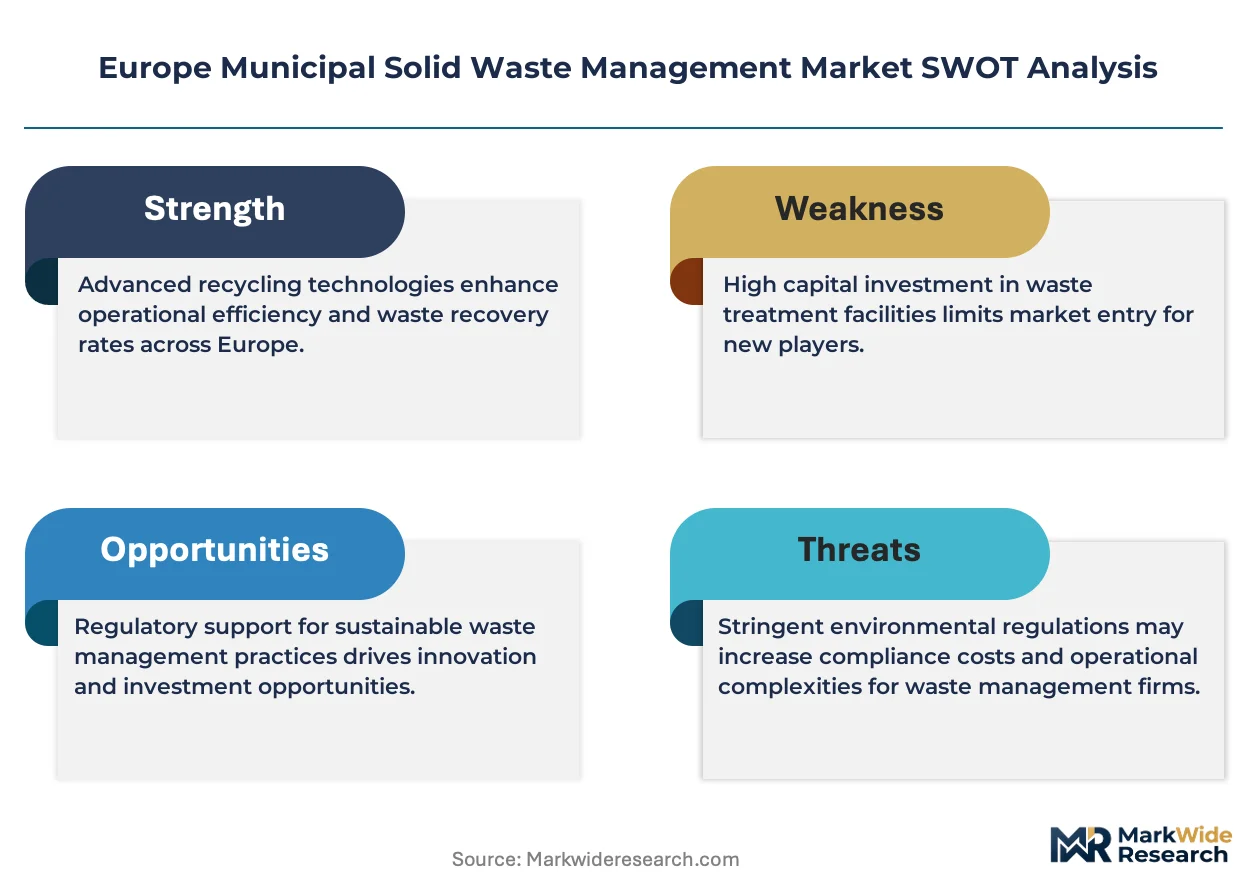
Recycled plastic feedstock is rebalancing sorting economics across European material recovery facilities. Veolia Environnement leverages its integrated collection-to-treatment network across France and Benelux. SUEZ anchors its competitiveness through advanced optical sorting technology deployed at scale. FCC Environment dominates Iberian municipal contracts with long-term concession structures.
Europe municipal solid waste management encompasses the systematic collection, transport, processing, and disposal of refuse generated by households, commerce, and industry, with modern facilities achieving energy recovery rates exceeding 60% through controlled thermal treatment. The primary purpose centers on minimizing environmental externalities while extracting secondary materials and energy vectors from discarded resources. Collection services command the largest revenue share due to their labor-intensive, route-dense operational requirements across fragmented municipal geographies. Anaerobic digestion represents the fastest-expanding technology segment as member states divert organic waste from landfill under tightening EU directives. Industrial end users generate the highest-margin waste streams because their homogeneous, high-volume outputs enable efficient single-stream processing.
The EU Green Deal and the Waste Framework Directive, enforced by the European Commission and national environmental agencies, mandate progressive landfill diversion targets that directly determine investment timelines for treatment capacity. ECHA's REACH restrictions on hazardous substance content in recovered materials shape sorting purity standards and downstream market access for recyclers. Stakeholders must monitor Germany's Packaging Act amendments and France's extended producer responsibility expansions as these will reset gate fee structures and collection financing models.
Market Dynamics
The EU Green Deal's landfill reduction mandates are compressing investment timelines across member states, forcing municipal governments to accelerate anaerobic digestion and mechanical biological treatment deployments before directive deadlines.
Growth Catalysts
- Organic Waste Diversion Mandates:The EU Waste Framework Directive requires member states to cut landfill deposits of biodegradable waste by 65 percent. Municipalities in Germany and France are expanding source-separated collection programs to capture food and garden waste streams.
- Industrial Corridor Density:Manufacturing clusters in Germany's Ruhr region and northern Italy generate homogeneous, high-volume waste streams. These outputs enable efficient single-stream processing and energy recovery economics.
- Mechanical Biological Treatment:MBT facilities achieve landfill diversion while extracting refuse-derived fuel. Spain and Portugal are deploying this technology to meet circular economy targets without full incineration infrastructure.
Market Restraints
- Capital Intensity Barriers:Waste-to-energy plants require EUR 200-400 million per facility. Smaller municipalities in eastern Europe lack balance-sheet capacity to finance anaerobic digestion infrastructure.
- Feedstock Contamination:Mixed plastic streams from households degrade sorting economics. Optical sorting purity requirements under ECHA REACH restrictions limit market access for lower-grade recyclers.
- Landfill Tipping Fee Volatility:Gate fees in southern Europe remain below northern European levels. This price gap slows technology migration and preserves legacy disposal capacity.
Strategic Opportunities
- Extended Producer Responsibility Expansion:France's EPR amendments will reset collection financing models. Packaging producers will assume direct cost responsibility for post-consumer waste streams.
- Digital Route Optimization:Fleet telematics and dynamic routing algorithms are reducing collection costs. Municipal operators in the Netherlands are piloting AI-driven bin-level sensors to cut unnecessary truck rolls.
- Biogas Grid Injection:Upgraded biomethane from anaerobic digestion qualifies for renewable energy certificates. Denmark and Sweden are building injection infrastructure to serve industrial heat users.
Industry Challenges
- Technical Workforce Scarcity:Plant operators with combined mechanical and biological process expertise are concentrated in Germany and Austria. Training pipelines in southern and eastern Europe lag deployment schedules.
- Legacy Contract Rigidities:Long-term municipal concessions signed in the 2000s lock in gate fee structures. Renegotiation friction delays technology refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Municipal Solid Waste Management Market |
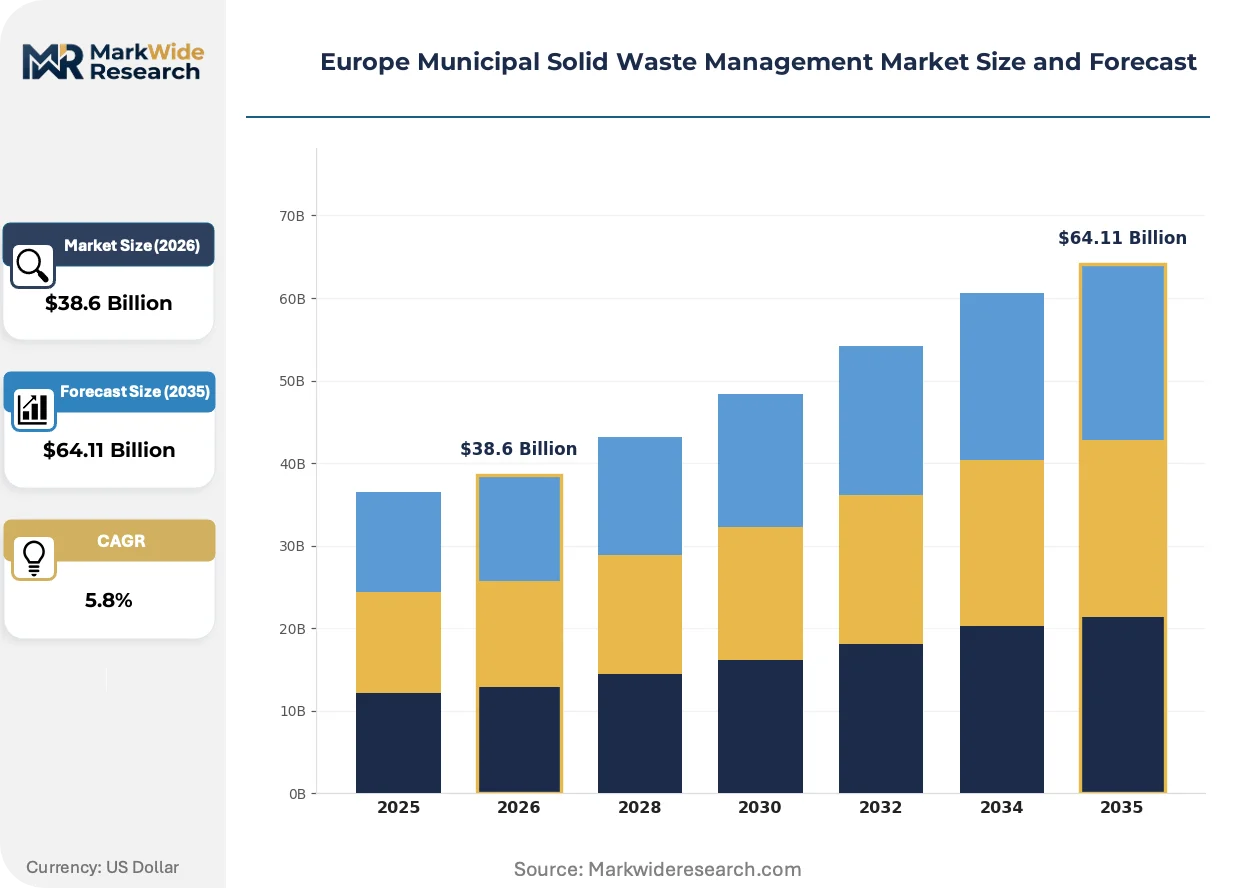
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Recycling, Composting, Landfilling Technology: Incineration, Anaerobic Digestion, Mechanical Biological Treatment, Sorting End User: Residential, Commercial, Industrial, Government Waste Type: Organic Waste, Plastics, Metal, Paper, Glass |
| Companies Covered | Veolia Environnement, SUEZ, FCC Environment, Remondis, Renewi, Biffa, Paprec, PreZero, Urbaser, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Municipal Solid Waste Management Market Trends and Innovations
Digital sensing and advanced sorting technologies are compressing operational costs while regulatory pressure on landfill diversion accelerates capital redeployment toward biological treatment pathways.
Near-infrared optical sorting is overtaking manual and magnetic separation in European material recovery facilities. The technology identifies polymer types at conveyor speeds exceeding five meters per second. Sorting plant operators in Belgium and the Netherlands are retrofitting existing lines to capture food-grade PET streams. This capability is enabling bottle-to-bottle recycling economics that mechanical methods cannot match.
REACH restrictions on hazardous substance content in recovered materials are tightening purity standards for plastic recyclers. ECHA's enforcement of SVHC thresholds limits downstream market access for mixed polymer outputs. Automotive and electronics manufacturers are responding by specifying certified recycled content quotas in supplier contracts.
Pay-as-you-throw tariff structures are displacing flat-rate municipal waste charges in urban France and Italy. Households face variable pricing tied to residual waste bin weights or bag tags. Cities including Milan and Lyon report 15-25 percent reductions in landfill-bound volumes within two years of implementation.
Europe Municipal Solid Waste Management Market Segmentation
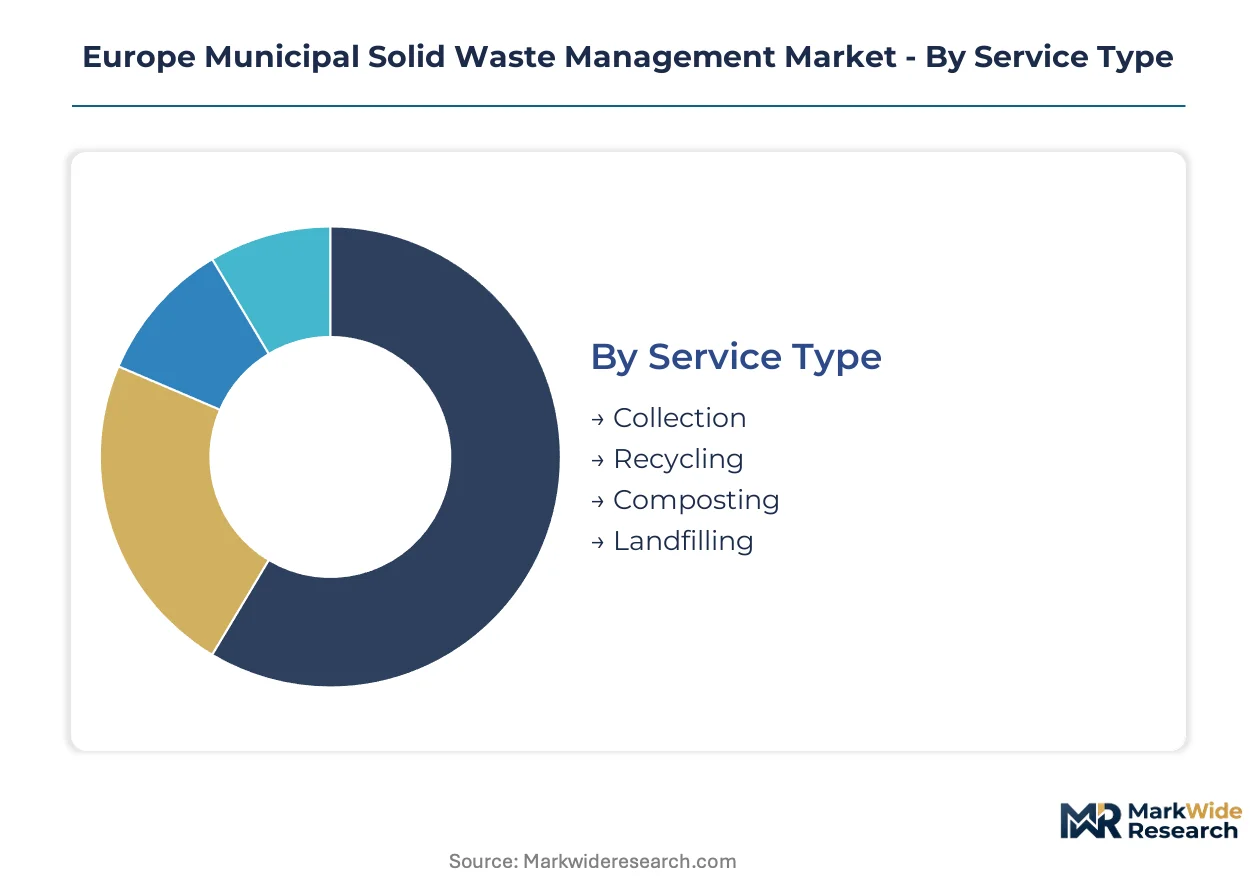
Europe's municipal solid waste management market segments along operational, technological, and material dimensions that determine capital deployment and margin structures. Each category carries distinct regulatory exposure and integration complexity that shapes competitive positioning across member states.
Service Type:
Standalone collection services operate independently of downstream processing, while recycling and composting functions embed into integrated treatment chains with tighter margin interdependencies.
- Collection:Labor-intensive route operations dominate revenue composition across fragmented municipal geographies. Dense urban corridors in Germany's Ruhr region and northern Italy generate the highest truck-roll efficiency, though driver shortages constrain expansion in eastern Europe.
- Recycling:Material recovery facilities process source-separated streams into commodity-grade outputs. Belgium and the Netherlands concentrate optical sorting investments, driven by ECHA REACH purity mandates that limit market access for lower-grade processors.
- Composting:Aerobic decomposition of garden and food waste produces soil amendments. France and Italy expand centralized composting capacity under EU landfill diversion deadlines.
- Landfilling:Residual disposal for non-recoverable fractions faces tightening capacity restrictions. Southern Europe retains higher landfill dependency due to capital constraints on alternative infrastructure.
Volume placements concentrate in Collection; the faster expansion belongs to Recycling.
Technology:
Cost tiers separate mature thermal processes from emerging biological pathways, with mechanical sorting bridging both investment categories through retrofit economics.
- Incineration:Controlled thermal treatment achieves energy recovery rates exceeding 60 percent in modern European plants. Germany and Denmark operate the densest waste-to-energy networks, serving industrial heat demand clusters.
- Anaerobic Digestion:Biological breakdown of organic waste yields biogas and digestate. Sweden and Denmark lead biomethane grid injection infrastructure buildout, qualifying output for renewable energy certificates.
- Mechanical Biological Treatment:Combined sorting and biological processing extracts refuse-derived fuel while diverting biodegradable fractions from landfill. Spain and Portugal deploy MBT to meet circular economy targets without full incineration investment.
- Sorting:Near-infrared optical systems identify polymer types at conveyor speeds exceeding five meters per second. Belgian and Dutch operators retrofit existing lines to capture food-grade PET streams that mechanical methods cannot recover.
Capital deployment tilts toward Anaerobic Digestion; installed base dominance remains with Incineration.
End User:
Customer type determines waste stream homogeneity and collection economics, with industrial generators offering the most predictable volumes and residential sources requiring dense route infrastructure.
- Residential:Household waste streams mix organics, packaging, and residuals requiring complex separation systems. Milan and Lyon implement pay-as-you-throw tariffs that reduce landfill-bound volumes through variable pricing.
- Commercial:Retail and office generators produce moderate volumes with higher recyclables concentration. France's extended producer responsibility expansions shift collection financing onto packaging supply chains.
- Industrial:Manufacturing clusters generate homogeneous, high-volume outputs enabling efficient single-stream processing. Germany's automotive and chemical corridors anchor waste-to-energy feedstock contracts.
- Government:Public sector facilities including hospitals and schools operate under distinct procurement frameworks. Municipal concession structures lock in long-term service relationships with limited technology refresh flexibility.
Revenue concentration sits with Residential contracts; margin expansion follows Industrial accounts.
Waste Type:
Material composition dictates processing pathway selection and downstream market access under tightening purity standards.
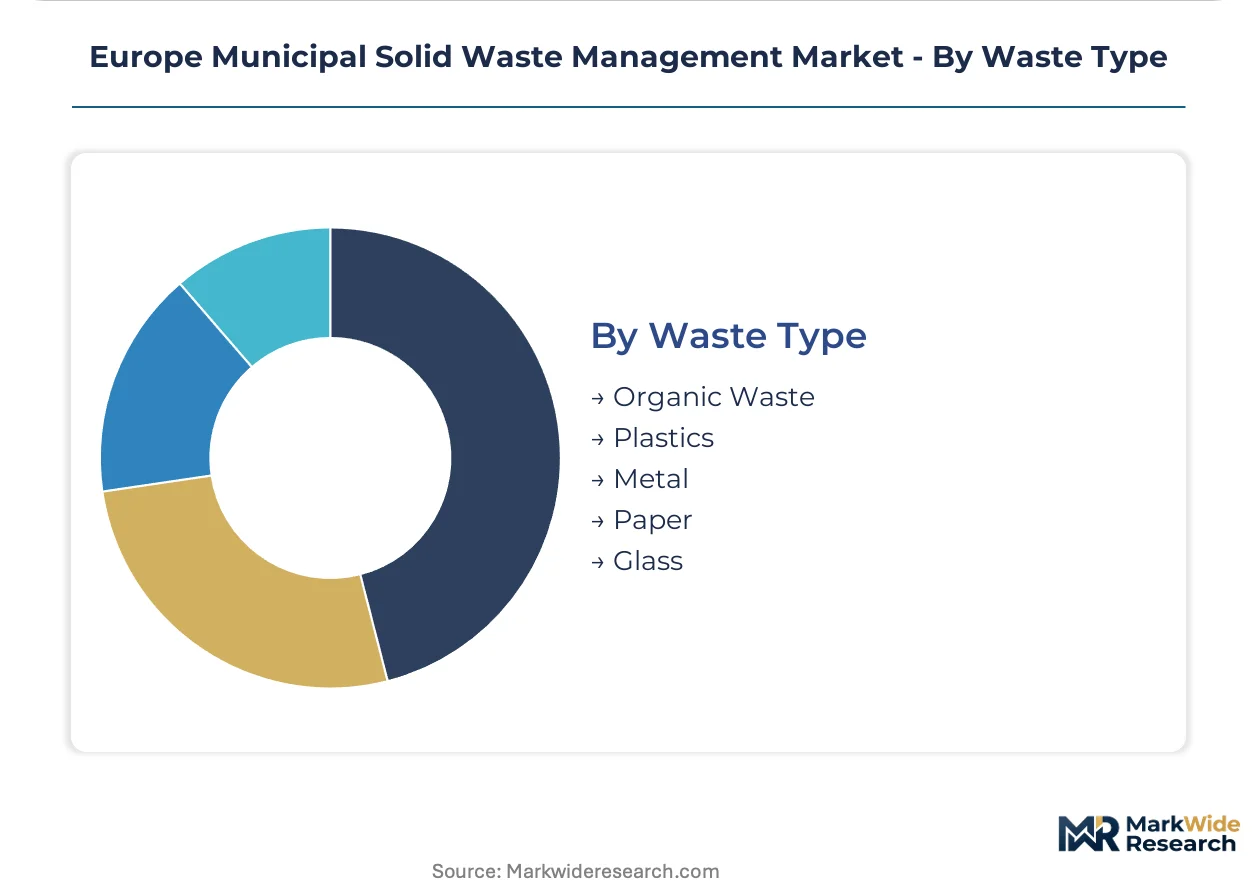
- Organic Waste:Food and garden fractions face mandatory diversion from landfill under EU Waste Framework Directive targets. Germany and France expand source-separated collection programs to capture biodegradable streams for anaerobic digestion.
- Plastics:Polymer recovery requires optical sorting to meet ECHA REACH restrictions on hazardous substance content. Automotive and electronics manufacturers specify certified recycled content quotas that reshape supplier economics.
- Metal:Ferrous and non-ferrous fractions retain strong commodity value through magnetic separation. Scrap metal networks operate established collection-to-smelter pathways across Benelux and northern Germany.
- Paper:Cardboard and fiber streams sustain mature recycling infrastructure with stable end-market demand. Packaging Act amendments in Germany reset collection financing models for post-consumer paper.
- Glass:Container recycling achieves closed-loop recovery through color-separated collection. Iberian markets maintain higher refillable bottle shares that reduce single-use container generation.
Processing volumes concentrate in Organic Waste; regulatory pressure is stiffening most rapidly for Plastics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's waste-to-energy tax incentives and feed-in tariff zones for biomethane have concentrated investment in the Ruhr industrial corridor and Bavarian organic processing clusters.
Germany
Ruhr manufacturing clusters generate homogeneous industrial waste streams feeding dedicated energy recovery plants. The Packaging Act amendments reset collection financing models for post-consumer materials. Bavaria's anaerobic digestion facilities serve Munich's dense metropolitan demand while exporting upgraded biomethane to industrial heat users.
France
Paris and Lyon implement pay-as-you-throw tariffs that reduce residual waste volumes through variable household pricing. Extended producer responsibility expansions shift collection costs onto packaging supply chains. The Grand Est region anchors Veolia's integrated collection-to-treatment network across municipal concessions.
Italy
Milan's door-to-door organic waste separation achieves diversion rates exceeding northern European benchmarks. The EU Waste Framework Directive deadlines compress investment timelines for Lombardy's composting capacity. Emilia-Romagna's agricultural corridor absorbs digestate outputs from anaerobic facilities serving Bologna and Modena.
Spain
Barcelona and Madrid deploy mechanical biological treatment to meet circular economy targets without full incineration infrastructure. Lower landfill gate fees in southern provinces preserve legacy disposal capacity. FCC Environment's Iberian concession structures lock in long-term service relationships across Catalonia and Andalusia.
Netherlands
Amsterdam and Rotterdam pilot AI-driven bin-level sensors that cut unnecessary collection truck rolls. ECHA REACH purity mandates drive optical sorting investments at Belgian-Dutch border facilities. The Randstad's dense urban geography generates route efficiency advantages for automated fleet telematics deployment.
Europe Municipal Solid Waste Management Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated operators commanding municipal concessions while technology vendors supply sorting equipment to independent facilities. The vendor base organizes around three archetypes: full-service concessionaires with collection-to-disposal networks, equipment specialists focused on optical sorting and anaerobic digestion technology, and regional contractors securing single-municipality contracts. Dominant competitive moves include concession renegotiation to reset legacy gate fee structures and geographic expansion through acquisition of distressed municipal contracts in southern and eastern Europe.
Within the full-service concessionaire tier, Veolia Environnement, SUEZ, and FCC Environment exemplify divergent geographic anchoring strategies. Veolia leverages its French and Benelux integrated network to capture source-separated organic streams under tightening EU diversion mandates. SUEZ occupies a position defined by advanced sorting technology deployment at scale across its operational footprint. FCC Environment anchors its competitiveness through long-term Iberian municipal structures that resist competitive entry despite technology refresh pressures.
| Leading Market Players |
|---|
| Veolia Environnement |
| SUEZ |
| FCC Environment |
| Remondis |
| Renewi |
| Biffa |
| Paprec |
| PreZero |
| Urbaser |
| Others |
Pricing and Supply Chain Analysis
Gate fee divergence between northern and southern European markets manifests in both municipal contract structures and treatment technology deployment patterns. Northern European operators command premium pricing through energy recovery certifications and biomethane grid injection capabilities, while southern markets retain landfill-dependent cost basins that compress margins across collection and processing tiers.
Pricing Analysis
Volume concentration in residential collection services generates thin margins that scale through route density, while industrial waste streams yield premium pricing through homogeneous feedstock quality and long-term offtake security. Price differentiation rests on ECHA REACH certification tiers for recovered plastics and renewable energy certificate eligibility for biomethane outputs. Pricing pressure stems from legacy municipal concessions signed under pre-2015 gate fee structures that resist renegotiation. Municipal governments in eastern Europe exhibit highest price sensitivity due to constrained fiscal capacity, whereas German industrial clusters demonstrate lowest sensitivity given waste-to-energy integration with manufacturing heat demand.
Supply Chain Analysis
Biogas upgrading equipment supply rests on German and Austrian engineering specialists, while optical sorting technology draws from Belgian and Dutch precision manufacturing clusters. Raw material dependencies include food-grade polymer feedstocks, specialized anaerobic digestion inoculants, and high-purity steel for incineration grate systems. Single-source vulnerability concentrates in proprietary biogas membrane upgrading systems where two European vendors dominate. Distribution runs through municipal concession networks that lock in decade-long service relationships, with equipment sales flowing through EPC contractors serving national infrastructure programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated operators capable of financing anaerobic digestion infrastructure under compressed EU directive timelines. Capital intensity barriers are forcing smaller municipal contractors into distressed asset sales.
For Market Incumbents: Deploy concession renegotiation levers to reset legacy gate fee structures before technology refresh cycles. Anchor defensive positioning through backward integration into biomethane grid injection infrastructure in Denmark and Sweden. Acquire distressed municipal contracts in Portugal and Greece where local operators lack balance-sheet capacity for MBT deployment.
For New Entrants and Emerging Players: Begin with digital route optimization services targeting mid-sized Dutch and Belgian municipalities piloting AI-driven bin sensors. White-space concentration sits in pay-as-you-throw tariff implementation support for French and Italian urban governments. Go-to-market traction follows software-as-a-service pricing that avoids capital-intensive treatment asset ownership.
For Investors and Strategic Acquirers: Re-rating potential sits with Iberian concession holders given FCC Environment's demonstrated ability to lock in long-term municipal structures despite technology refresh pressures. Long-term viability favors operators with exposure to industrial corridor feedstock contracts in Germany's Ruhr region. Monitor France's extended producer responsibility implementation pace as the inflection signal for packaging supply chain financing shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Biomethane Grid Injection Infrastructure | Upgraded biogas qualifies for renewable energy certificates under EU Green Deal frameworks. |
| Optical Sorting Technology Retrofit | Near-infrared systems capture food-grade PET streams that mechanical methods cannot recover. |
| Pay-as-you-Throw Tariff Implementation | Milan and Lyon achieved 15-25 percent landfill volume reductions within two years. |
| Anaerobic Digestion Capacity Buildout | Germany and France expand source-separated collection to meet EU Waste Framework Directive targets. |
| Extended Producer Responsibility Expansion | France's EPR amendments reset collection financing onto packaging supply chains. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Europe municipal solid waste management assessment. Primary interviews with municipal procurement officers, anaerobic digestion plant operators, optical sorting equipment vendors, and EPC contractors combined with bottom-up and top-down triangulation. Secondary validation drew from EU Waste Framework Directive implementation reports, ECHA REACH enforcement databases, national environmental agency filings, and European waste-to-energy operator disclosures.
Data-stream reconciliation across service type, technology, end user, and waste type segmentation dimensions shaped the analytical framework across the projection horizon. CAGRs derived from treatment capacity deployment pipelines, organic waste diversion mandate compliance schedules, and municipal concession renewal cycles. Industry-specific forecast inputs included biomethane grid injection infrastructure buildout timelines and pay-as-you-throw tariff adoption curves in urban France and Italy.
Regulatory deadline delays, feedstock contamination rate volatility, and municipal fiscal constraint intensification are the dominant revision risks. Forecasts reflect documented assumptions regarding EU directive enforcement consistency and technology cost reduction trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Metal Recycling Equipment Market
Waste Management & Pollution Control
Singapore Waste Management Market
Waste Management & Pollution Control
Animal Waste Incinerator Market
Waste Management & Pollution Control
Waste Paper Management Market
Waste Management & Pollution Control
Landfill Gas Market
Waste Management & Pollution Control
North America Bio-Medical Waste Management Market
Waste Management & Pollution Control
Global Waste Management Equipment Market
Waste Management & Pollution Control
Waste Recycling Services Market
Waste Management & Pollution Control
Wheeled Bins Market
Waste Management & Pollution Control
India Municipal Solid Waste Management Market
Waste Management & Pollution Control
Qatar Waste Management Market
Waste Management & Pollution Control
South American Waste Management Market
Waste Management & Pollution Control
Global Oil Spill Management Market
Waste Management & Pollution Control
ASEAN Waste Management Market
Waste Management & Pollution Control
GCC Industrial Waste Management Market
Waste Management & Pollution Control
India Commercial Food Waste Decomposer Market