
 Household Composters Market | 2026-2036
Household Composters Market Size, Share, and Industry Trends Forecast 2026-2036
Household Composters Market Outlook
Fragmentation among urban apartment dwellers and suburban homeowners is realigning procurement patterns across the household composters landscape. Mill leverages its subscription-based filter replenishment model to sustain recurring revenue beyond hardware sales. Vitamix anchors its FoodCycler line through established kitchen-appliance retail channels and brand recognition among premium home cooks. Lomi differentiates via app-connected carbon-filter monitoring and odor-neutralization technology that competes with conventional outdoor tumblers.
A household composter is a contained decomposition system engineered to accelerate organic matter breakdown through controlled aeration, temperature management, and moisture regulation, typically processing 1–5 kilograms of food scraps weekly into humus-like output. Electric countertop variants employ thermophilic heating elements and grinding mechanisms to achieve 24-hour cycle completion, while aerobic tumblers rely on manual rotation to maintain 55–65°C thermophilic zones. Plastic dominates material selection for entry-price electric units, though metal construction commands margin pools in premium outdoor tumblers where weather resistance extends product lifespan. Small-capacity countertop installations lead unit volume in dense urban markets, yet medium-capacity outdoor fixed systems capture higher per-unit economics in single-family suburban applications.
The EPA's food waste reduction targets and EU Green Deal organic diversion mandates shape product certification requirements and market access conditions for manufacturers seeking transatlantic distribution. California's SB 1383 statewide organic waste regulations and France's AGEC anti-waste law create enforcement templates that other jurisdictions emulate, directly stimulating household-level composter procurement. Stakeholders must monitor evolving municipal collection infrastructure investments versus household self-processing subsidies to anticipate whether electric countertop or outdoor tumbler formats capture the next wave of policy-driven demand.
Market Dynamics
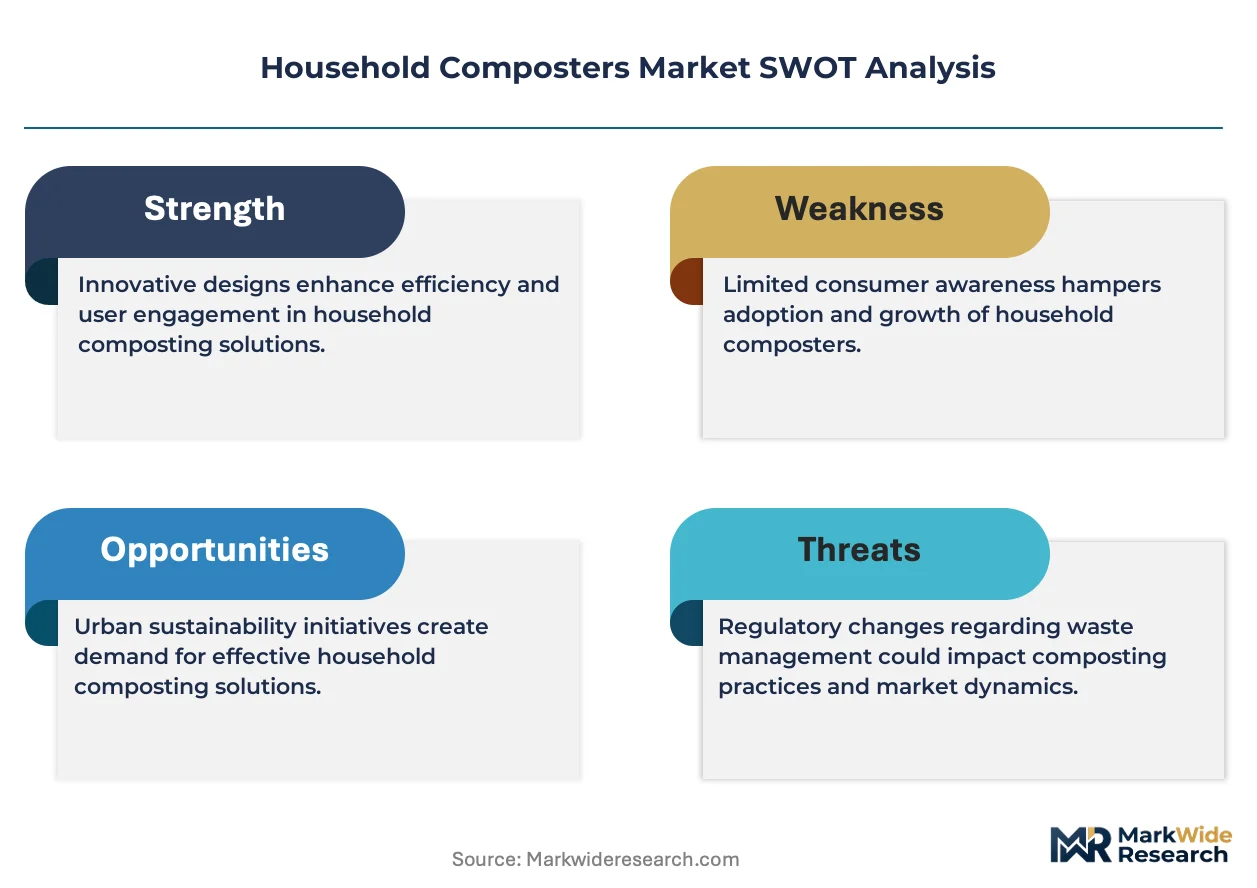
Municipal organic waste mandates are fragmenting procurement patterns between electric countertop units for apartment dwellers and outdoor tumblers for suburban homeowners, creating parallel demand channels with divergent margin structures.
Growth Catalysts
- California's SB 1383 enforcement:Statewide organic waste regulations mandate household-level diversion, directly stimulating composter procurement in jurisdictions with uneven curbside infrastructure.
- EU Green Deal organic diversion mandates:Cross-border certification requirements harmonize product standards, enabling manufacturers to scale distribution across member states with unified compliance.
- Countertop electric technology:Thermophilic heating elements and grinding mechanisms compress decomposition cycles to 24 hours, unlocking adoption among urban apartment dwellers lacking outdoor space.
Market Restraints
- Plastic resin input volatility:Entry-price electric units rely heavily on petroleum-derived polymers, exposing margin pools to petrochemical price swings.
- Curbside collection substitution:Municipal infrastructure investments in dense metropolitan areas threaten household self-processing demand where collection services achieve scale.
- Metal supply concentration:Premium outdoor tumblers requiring weather-resistant alloys face sourcing constraints from concentrated specialty steel producers.
Strategic Opportunities
- France's AGEC anti-waste law template:Extended producer responsibility frameworks emerging across EU member states create enforcement models that stimulate household procurement through penalty structures.
- Subscription filter replenishment models:Recurring revenue streams from carbon-filter replacements sustain manufacturer economics beyond one-time hardware sales.
- App-connected monitoring convergence:Integration of IoT sensors with odor-neutralization systems enables predictive maintenance and differentiated positioning against passive tumblers.
Industry Challenges
- Composting microbiology expertise gap:Manufacturers struggle to staff thermophilic process optimization roles, slowing product development cycles for temperature-controlled electric variants.
- Multi-jurisdiction certification complexity:Divergent electrical safety standards across North American and EU markets extend product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Composters Market |
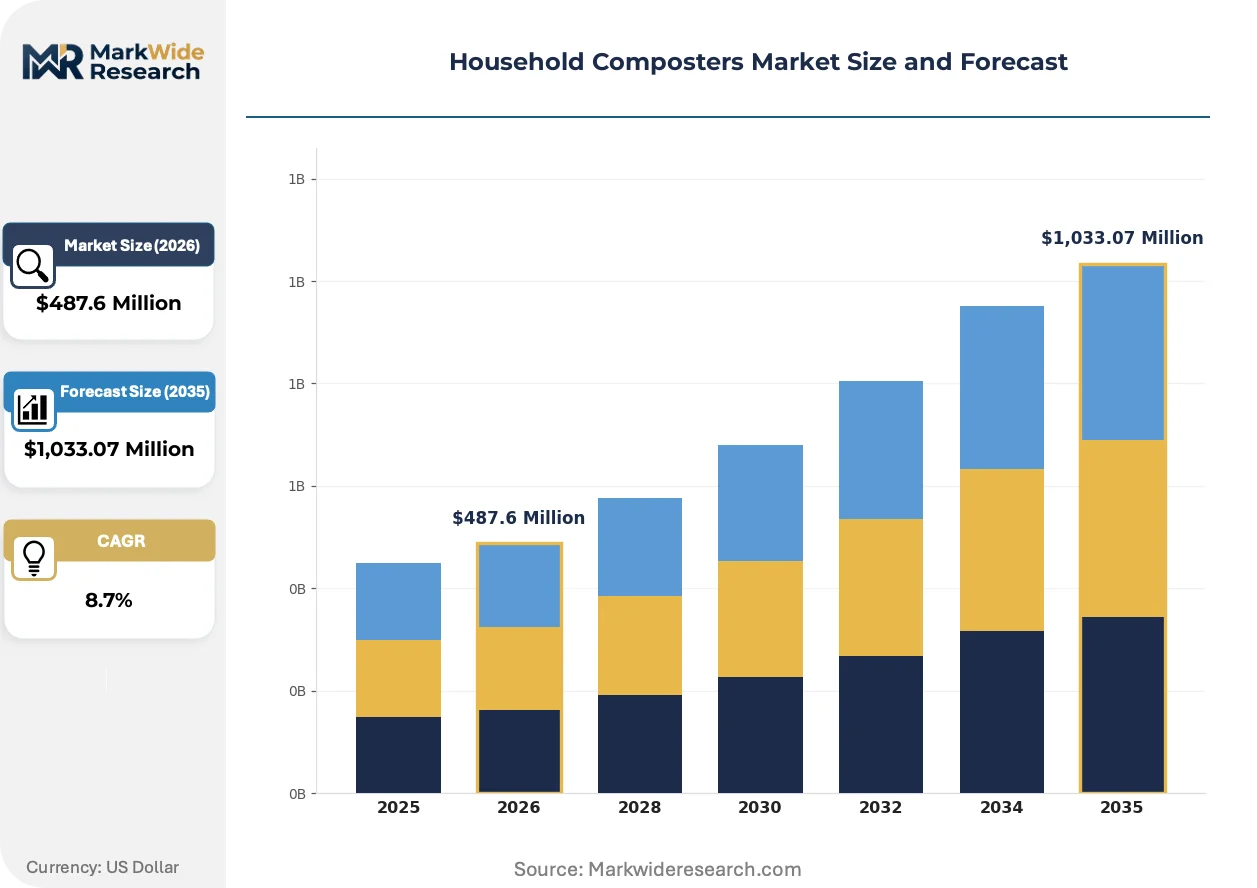
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Tumbler, Electric, Aerobic Material: Plastic, Metal, Wood, Bamboo Capacity: Small, Medium, Large, Extra Large Installation: Indoor, Outdoor, Portable, Fixed |
| Companies Covered | Mill, Algreen Products, GEME (Terra 2), VermiHut, Joraform, Reencle, Vitamix (FoodCycler), Airthereal, Lomi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Composters Market Strategic Shifts
Active unification of hardware and digital service layers is compressing traditional boundaries between appliance manufacturing and subscription software, while regulatory enforcement templates accelerate cross-border standardization.
Carbon-filter monitoring systems with smartphone connectivity are unifying odor control and maintenance scheduling into single-platform experiences. Urban apartment dwellers in California and New York metropolitan areas adopt these integrated units fastest, collapsing the distinction between hardware purchase and ongoing service relationship as manufacturers capture lifetime value through filter replenishment.
The EPA's food waste reduction targets are tightening certification requirements for electrical safety and compost quality claims. Manufacturers seeking transatlantic distribution must now synchronize testing protocols with EU Green Deal organic diversion standards, compressing product development timelines as dual-compliance becomes table stakes for market access.
Leasing and rental models for electric countertop units are displacing outright purchase in dense urban markets. Property management companies in San Francisco and Seattle bundle composters with tenant amenities, shifting procurement authority from individual consumers to institutional buyers who negotiate fleet pricing and centralized maintenance contracts.
Household Composters Market Segmentation
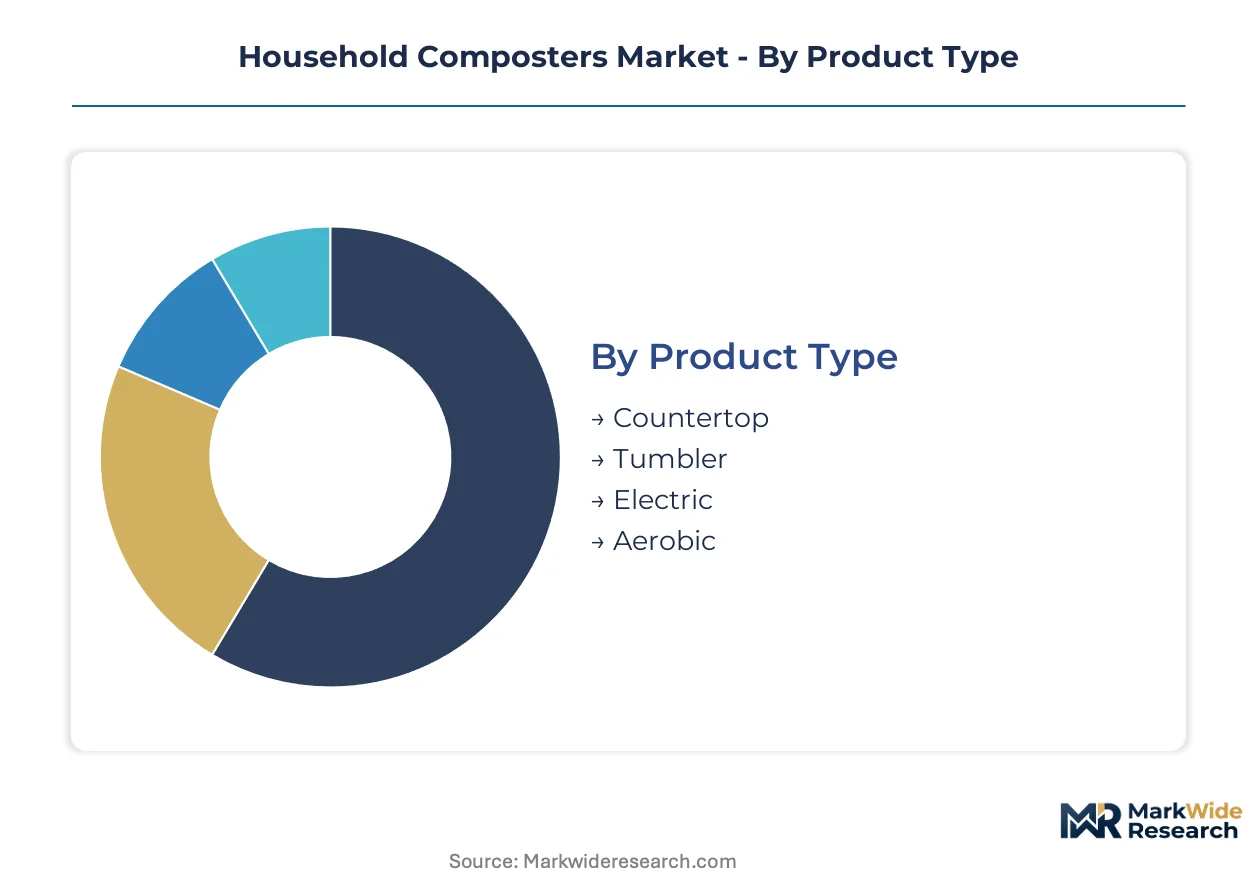
Household composter procurement fragments sharply across living contexts and waste volumes. Product format, material durability, and spatial constraints determine which configurations capture demand in dense urban versus suburban environments.
Product Type:
Supply concentration in thermophilic electric systems is reshaping manufacturer R&D allocation toward compact, temperature-controlled units.
- Countertop:Compact electric units with thermophilic heating elements and grinding mechanisms process 1-3 kilograms weekly into dehydrated output within 24-hour cycles. Demand concentrates in California and New York metropolitan areas where apartment dwellers face municipal organic waste diversion mandates without outdoor space.
- Tumbler:Rotating aerobic bins with dual-chamber designs maintain thermophilic zones through manual rotation, typically processing 100-300 liters. Suburban homeowners in jurisdictions with uneven curbside infrastructure drive procurement as self-sufficient alternatives to municipal collection gaps.
- Electric:Plug-in units with automated aeration and carbon filtration neutralize odors for indoor operation. EPA food waste reduction targets tighten electrical safety certification requirements for transatlantic distribution.
- Aerobic:Passive ventilation systems relying on natural airflow and microbial activity require no electricity but longer decomposition cycles. Price-sensitive buyers in rural areas with ample outdoor space favor this format.
Countertop units absorb the bulk of installed capacity in dense metropolitan markets; electric variants are expanding most quickly through subscription filter replenishment models.
Material:
Cost tier stratification across petroleum-derived and weather-resistant inputs determines margin pools and replacement frequency.
- Plastic:Recycled polyethylene and polypropylene dominate entry-price electric units, offering moldability for complex aeration channel geometries. Petrochemical price volatility exposes margin pools to supply shocks.
- Metal:Galvanized steel and aluminum alloys command premium positioning in outdoor tumblers requiring weather resistance across freeze-thaw cycles. Specialty steel sourcing constraints from concentrated European producers limit capacity scaling.
- Wood:Cedar and redwood constructions appeal to aesthetic-conscious suburban homeowners seeking landscape integration. Rot susceptibility shortens functional lifespan versus synthetic alternatives.
- Bamboo:Rapid-renewable biomass feedstock targets sustainability-positioned buyers in EU Green Deal jurisdictions with extended producer responsibility frameworks. Moisture absorption limits structural durability in humid climates.
Plastic captures the highest unit volume through entry-price electric penetration; metal formats sustain premium per-unit economics in outdoor applications.
Capacity:
Volume segmentation directly tracks household size and weekly organic waste generation patterns across single-person apartments to multi-generational homes.
- Small:Under-5-liter countertop units serve single-person households generating minimal food scraps. Urban apartment dwellers in San Francisco and Seattle metropolitan areas drive adoption through property management amenity bundles.
- Medium:20-100 liter tumblers accommodate 2-4 person households with moderate garden waste. Suburban jurisdictions with SB 1383 enforcement and patchwork curbside coverage stimulate replacement demand.
- Large:100-300 liter fixed systems process substantial yard debris alongside kitchen waste. Single-family homeowners with established composting routines sustain this segment.
- Extra Large:300+ liter commercial-grade units adapted for multi-unit residential compounds. Institutional buyers in France's AGEC enforcement zones negotiate fleet pricing for centralized processing.
Small-capacity units dominate urban unit shipments; medium formats claim the steepest expansion trajectory through suburban policy enforcement.
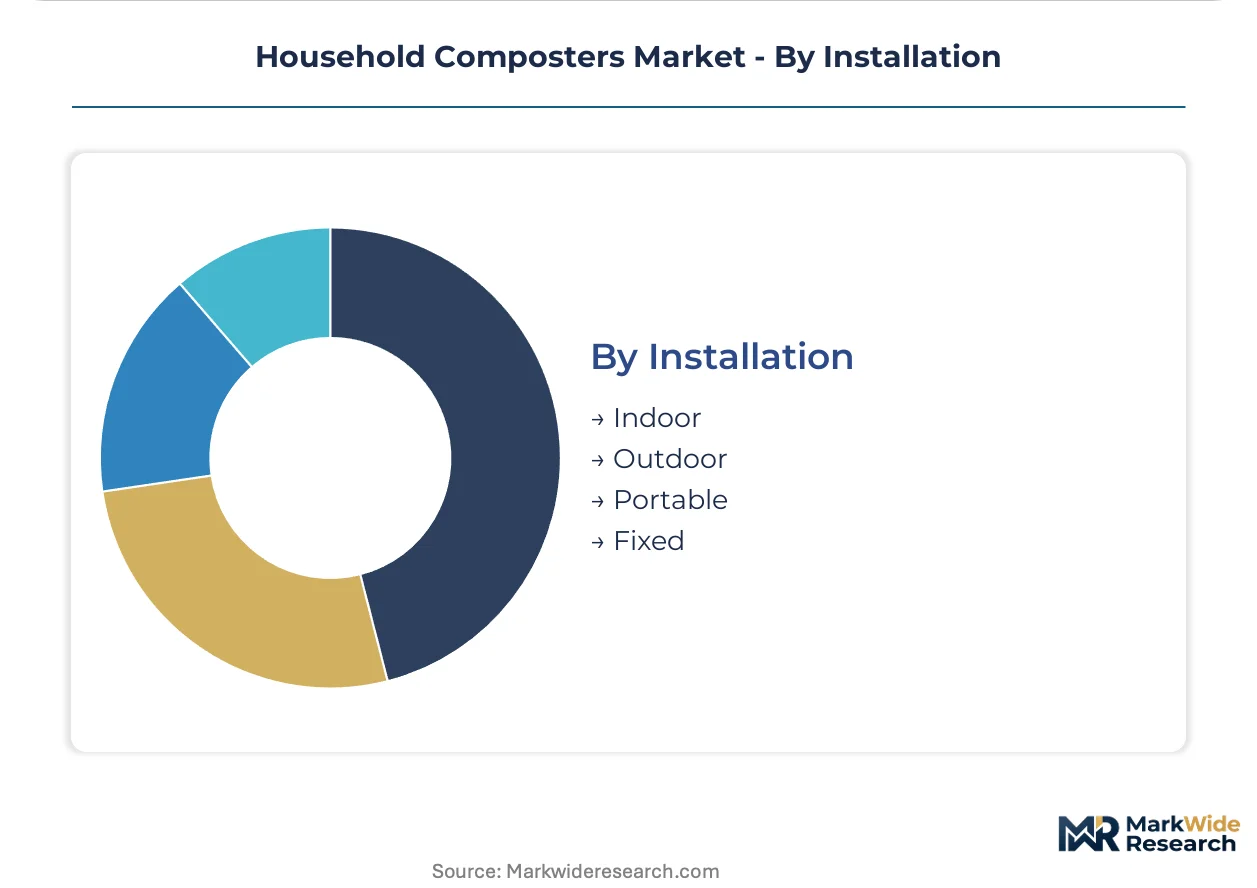
Installation:
Customer type bifurcation between renters and owners determines mobility requirements and permanent infrastructure investment tolerance.
- Indoor:Sealed electric units with carbon filtration enable kitchen-counter operation without odor leakage. California's statewide organic waste regulations accelerate adoption where outdoor space is unavailable.
- Outdoor:Exposed tumblers and fixed bins leverage ambient temperature fluctuations for thermophilic processing. Seasonal weather exposure limits operational windows in northern climates.
- Portable:Lightweight plastic constructions with collapsible designs serve renters and seasonal users. Transient urban populations in Seattle and Portland favor flexibility over permanence.
- Fixed:Permanent installations with concrete anchoring or integrated garden beds target established homeowners. Longer replacement cycles compress recurring revenue opportunities for manufacturers.
Indoor installations command the majority of new unit sales; portable formats are gaining share fastest among younger, mobility-oriented demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty steel feedstock from concentrated European producers anchors premium outdoor tumbler manufacturing, while petroleum-derived polymer clusters in the US Gulf Coast supply entry-price electric unit casings.
United States
California's SB 1383 enforcement and patchwork municipal infrastructure drive countertop electric adoption among urban apartment dwellers. The EPA's food waste reduction targets tighten electrical safety certification requirements for interstate distribution. San Francisco and Seattle metropolitan areas concentrate property management fleet procurement of small-capacity indoor units.
Germany
EU Green Deal organic diversion mandates harmonize cross-border product standards for manufacturers seeking transatlantic distribution. REACH and RoHS compliance frameworks extend product launch timelines but enable unified market access across member states. The North Rhine-Westphalia industrial cluster hosts specialty steel sourcing for weather-resistant outdoor tumblers.
France
AGEC anti-waste law enforcement templates stimulate household procurement through extended producer responsibility penalty structures. Municipal organic waste collection gaps in dense metropolitan areas sustain demand for self-processing alternatives. The Île-de-France region concentrates institutional buyer negotiations for multi-unit residential fleet deployments.
United Kingdom
Post-Brexit regulatory divergence from EU standards creates parallel certification requirements for manufacturers. London metropolitan area renters drive portable format adoption through property management amenity bundles. The Midlands manufacturing base supplies plastic resin components for entry-price electric variants.
Japan
METI energy efficiency standards shape thermophilic heating element specifications for countertop electric units. Dense urban housing stock in Tokyo and Osaka metropolitan areas limits outdoor space availability. JIS certification requirements filter market entry for foreign manufacturers seeking distribution partnerships.
Household Composters Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue subscription-based service layers and IoT integration. The vendor base splits between kitchen-appliance incumbents leveraging retail channel relationships and venture-backed specialists commercializing thermophilic electric technology. Three archetypes dominate: hardware-plus-subscription platforms, traditional outdoor equipment fabricators, and diversified small-appliance manufacturers. Competitive moves concentrate on filter replenishment model scaling and carbon-filter monitoring technology licensing.
Within the hardware-plus-subscription tier, Mill and Lomi exemplify recurring revenue architectures through carbon-filter replenishment programs. Vitamix anchors the diversified small-appliance archetype through established kitchen retail channel presence. Among specialized electric variants, GEME and Reencle occupy positions in the thermophilic acceleration segment, while Joraform and VermiHut represent traditional aerobic tumbler fabrication. Algreen Products and Airthereal sit within the mid-market accessibility tier.
| Leading Market Players |
|---|
| Mill |
| Algreen Products |
| GEME (Terra 2) |
| VermiHut |
| Joraform |
| Reencle |
| Vitamix (FoodCycler) |
| Airthereal |
| Lomi |
| Others |
Value Chain & Pricing Dynamics
Thermophilic electric heating elements and grinding mechanisms are compressing decomposition cycles from weeks to hours while simultaneously concentrating manufacturing expertise among specialty component suppliers in China, South Korea, and Japan. This production-method transition rewards early movers with carbon-filter replenishment subscription architectures that capture lifetime value beyond hardware margins.
Pricing Analysis
Warranty and service-bundling architectures separate hardware-plus-subscription platforms from transactional outdoor tumbler vendors. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service intensity. Price differentiation hinges on UL/CE electrical safety tiers and geographic delivery cost differentials. Pricing pressure stems from petrochemical resin volatility in entry-price electric units. Urban apartment dwellers exhibit highest price sensitivity; suburban homeowners with established composting routines show lowest.
Supply Chain Analysis
Regional distribution centers in California, Texas, and New Jersey anchor hub-and-spoke fulfillment patterns for countertop electric units. Manufacturing concentrates in China, Vietnam, and Mexico for plastic resin casings and thermophilic heating element assembly. Raw material dependencies include petroleum-derived polymers, galvanized steel alloys, and activated carbon filtration media. Single-source vulnerability from concentrated European specialty steel producers threatens premium outdoor tumbler capacity scaling. Distribution runs through kitchen-appliance retail channels and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The household composters market sits in a technology-transition phase where thermophilic electric systems displace passive aerobic tumblers as the default urban solution. App-connected carbon-filter monitoring and predictive maintenance algorithms are replacing odor-neutralization as the primary differentiation vector.
For Market Incumbents: Extend subscription filter replenishment models to capture recurring revenue streams beyond one-time hardware sales. Invest in thermophilic process optimization R&D to defend against venture-backed specialists commercializing faster cycle times. Backward integration into carbon filtration media production mitigates raw material cost volatility from activated carbon suppliers. For New Entrants and Emerging Players: IoT-enabled odor monitoring systems offer a technology-first wedge into property management fleet procurement channels. Target dense metropolitan rental markets in California and New York where municipal organic waste mandates create immediate procurement urgency. Pursue direct-to-consumer launch architectures with trial periods that reduce adoption friction for skeptical urban apartment dwellers. For Investors and Strategic Acquirers: Exit pathways concentrate in hardware-plus-subscription platforms with demonstrated filter replenishment retention rates. The five-to-ten year viability window favors manufacturers with dual UL/CE certification enabling transatlantic distribution scale. Watch municipal curbside collection infrastructure investment announcements as the critical inflection signal for household self-processing demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Filter Replenishment Scaling | Recurring revenue from carbon-filter replacements sustains manufacturer economics beyond hardware margins in California enforcement zones. |
| Dual Certification Investment (UL/CE) | Unified electrical safety compliance compresses product launch timelines for transatlantic distribution across EU Green Deal jurisdictions. |
| Property Management Fleet Partnerships | Institutional buyer negotiations in San Francisco and Seattle metropolitan areas shift procurement authority from individual consumers to amenity bundlers. |
| App-Connected Monitoring Integration | Predictive maintenance algorithms differentiate electric countertop units against passive tumblers in odor-sensitive urban installations. |
| Backward Integration into Filtration Media | In-house activated carbon production mitigates supply chain risk from concentrated specialty material suppliers. |
Study Parameters
Independent corroboration across primary interviews with product development executives, municipal waste management officers, retail category buyers, and channel distribution partners underwrites the qualitative findings. Secondary validation draws from EPA food waste reduction documentation, EU Green Deal organic diversion filings, California SB 1383 enforcement records, and kitchen-appliance retail audit data. Bottom-up unit shipment modeling triangulates against top-down market sizing across product format, material durability, and installation type segments.
Comparable-period anchoring to historical organic waste mandate enforcement phases in France and California calibrated the projection horizon. The analytical framework models demand across thermophilic electric, aerobic tumbler, and passive ventilation product types; plastic, metal, wood, and bamboo material tiers; and indoor, outdoor, portable, and fixed installation configurations. CAGRs derive from policy-driven procurement elasticity estimates and household penetration rate trajectories. Forecast inputs include municipal collection infrastructure investment schedules and petrochemical price volatility assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt curbside collection scaling or extended producer responsibility penalty structure delays. Outputs reflect documented assumptions regarding SB 1383 enforcement consistency and EU Green Deal harmonization timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Europe Medical Waste Management Market
Waste Management & Pollution Control
Global Pharmaceutical Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Industrial Waste Management Market
Waste Management & Pollution Control
Construction Waste Management Market
Waste Management & Pollution Control
India E-Waste Management Market
Waste Management & Pollution Control
Wood Recycling Market
Waste Management & Pollution Control
North America Industrial Waste Management Market
Waste Management & Pollution Control
South American Waste Management Market
Waste Management & Pollution Control
US Municipal Solid Waste Management Market
Waste Management & Pollution Control
Solid Waste Management Market
Waste Management & Pollution Control
Europe Waste Management Market
Waste Management & Pollution Control
Rare Earth Recycling Market
Waste Management & Pollution Control
India Recycling Market
Waste Management & Pollution Control
Asia-Pacific Waste Management Market
Waste Management & Pollution Control
Waste Paper Recycling Market
Waste Management & Pollution Control
Africa Waste Management Market