
 Sugar Beet Market | 2026-2036
Sugar Beet Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Beet Market Outlook
European sugar beet processing is restructuring around energy-intensive refining consolidation. Südzucker AG leverages its integrated starch-sugar platform to control biogas co-generation assets across Germany and Poland. Nordzucker AG anchors Baltic Sea logistics through specialized bulk terminals in Denmark and Sweden. Tereos Group competes on beet-to-ethanol conversion efficiency at its French and Brazilian facilities.
Sugar beet is a root crop containing sucrose concentrations of 15-20% by fresh weight, harvested mechanically and processed through diffusion extraction to yield crystalline sugar and molasses co-products. Sliced sugar beets dominate fresh industrial intake due to lower transport moisture penalties versus whole root delivery. Sugar beet pulp captures expanding animal feed demand as dairy operations substitute imported soy protein with regional fiber sources. Dried sugar beet chips sustain niche export flows to Middle Eastern equine feed markets where dust-controlled rations command premium positioning.
The EPA administers Renewable Fuel Standard compliance pathways that determine beet ethanol eligibility for credit generation. REACH and EFSA frameworks govern molasses residue thresholds in food-grade versus feed-grade output streams. Stakeholders must monitor carbon border adjustment mechanisms as these reshape the cost calculus for imported versus domestic beet sugar.
Market Dynamics
Biofuel refineries are accelerating beet ethanol offtake as ethanol blending mandates tighten across North America, Europe, and Asia-Pacific, restructuring long-term contracting patterns away from food-grade sugar toward fuel pathway certification.
Growth Catalysts
- EU F-Gas Regulation:Carbon accounting protocols for crop-to-fuel certification are expanding beet ethanol eligibility in European renewable fuel pools, pulling additional acreage into energy crop rotations.
- Dairy feed substitution:Sugar beet pulp is displacing imported soy protein in regional dairy operations across the Upper Midwest, creating co-product demand that improves processor crush economics.
- Mechanical harvesting automation:Six-row self-propelled harvesters are reducing per-ton labor inputs in the Red River Valley, compressing harvest windows and reducing field losses.
Market Restraints
- Natural gas price volatility:Energy-intensive diffusion extraction and crystallization stages expose processors to input cost swings that compress margin visibility on multi-year supply contracts.
- Processor concentration in the Red River Valley:Three dominant cooperatives control rail-loading infrastructure, creating single-point logistics vulnerability for contracted growers.
- Sucrose yield ceiling:Genetic and agronomic limits on root sucrose concentration (15-20% fresh weight) constrain unit economics against tropical cane sugar in unprotected markets.
Strategic Opportunities
- Baltic Sea corridor expansion:Nordzucker AG's specialized bulk terminals in Denmark and Sweden enable Ukrainian and Polish beet sugar exports to Middle Eastern markets with limited cane competition.
- Biogas co-generation integration:Molasses and pulp residue streams can anchor anaerobic digestion assets that generate renewable natural gas certificates under EU Green Deal methane reduction frameworks.
- Equine feed premium channels:Dust-controlled dried sugar beet chips command positioning advantages in Gulf State markets where import substitution policies favor processed feed over raw grain.
Industry Challenges
- Carbon intensity accounting expertise:Fuel pathway certification under EPA Renewable Fuel Standard and EU delegated acts requires specialized lifecycle analysis capabilities that most regional cooperatives lack in-house.
- REACH molasses residue compliance:Food-grade versus feed-grade output stream separation demands analytical infrastructure upgrades that strain mid-scale processor capex cycles.
- Railcar fleet reconfiguration:Transitioning from whole root to sliced beet delivery requires specialized hopper investments that lock in transport mode decisions for decade-long depreciation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Beet Market |
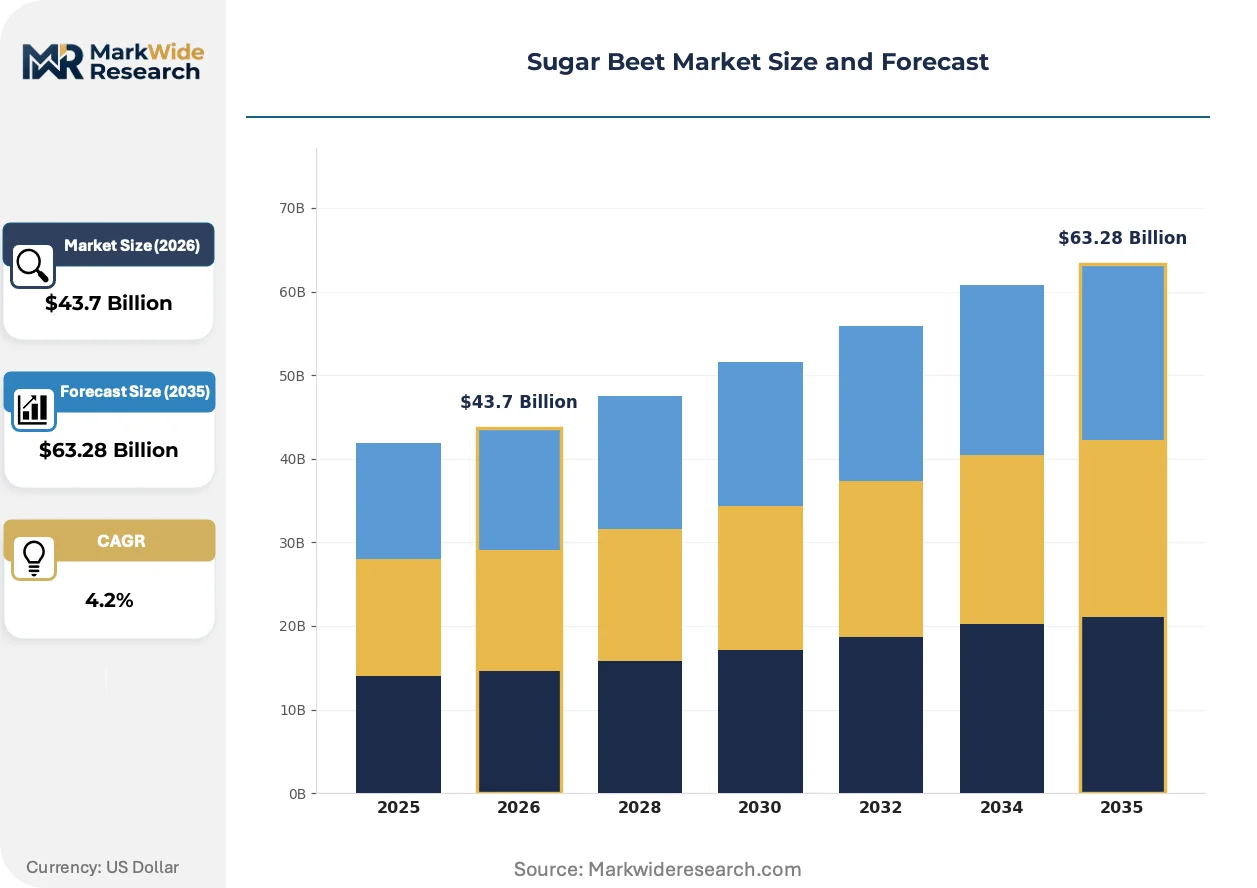
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $63.28 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliced Sugar Beets, Dried Sugar Beet Chips, Sugar Beet Pulp, Sugar Beet Powder End Use Industry: Food & Beverage, Animal Feed, Biofuels, Pharmaceuticals Application: Baking, Sweetening Agents, Feed Supplements, Ethanol Production Distribution Channel: Direct Sales, Wholesale Distributors, Online Retail, Export |
| Companies Covered | Südzucker AG, Nordzucker AG, British Sugar, Tereos Group, Cosun Beet Company, American Crystal Sugar Company, Michigan Sugar Company, Amalgamated Sugar Company, Western Sugar Cooperative, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Beet Market Strategic Shifts
Diffusion extraction technology and residue valorization systems are compressing the capital intensity gap between beet and cane processing, while carbon border mechanisms restructure geographic competitive advantage.
Continuous counter-current diffusion technology is overtaking batch extraction systems in new processor installations across Germany and Poland. Biofuel refineries in France and Brazil are specifying this equipment for its water and energy efficiency advantages in beet-to-ethanol conversion. The technology is overtaking older extraction methods by enabling real-time sucrose recovery monitoring that reduces molasses sugar loss penalties.
EPA Renewable Fuel Standard compliance pathways are tightening lifecycle carbon intensity thresholds for beet ethanol credit generation. This regulatory pressure is forcing processors to document cultivation inputs, fertilizer sources, and transport modes with granular traceability systems. French and German facilities are responding fastest, leveraging existing farm-level data infrastructure from CAP subsidy compliance to meet emerging certification requirements.
Long-term offtake contracting is displacing spot market sales for industrial sugar buyers in North American and European food manufacturing. Cereal and confectionery processors in Minnesota and Illinois are locking in three-to-five-year supply agreements that embed price collars and volume flexibility clauses. This pattern is most visible in the Red River Valley processor catchment, where buyer concentration and rail logistics density enable bilateral negotiation structures that bypass traditional commodity exchange price discovery.
Sugar Beet Market Segmentation
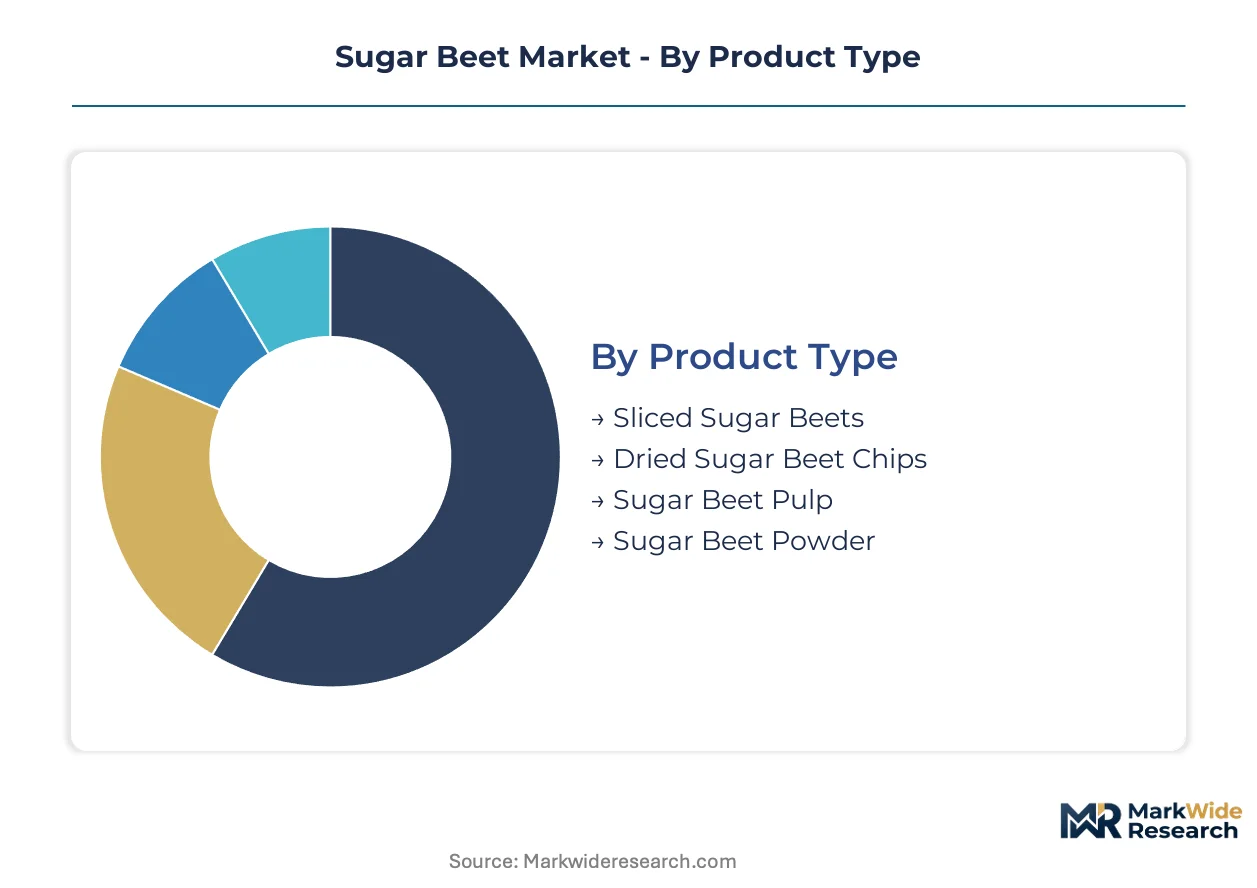
Sugar beet processing generates distinct product streams with divergent margin profiles and certification requirements. Segment boundaries harden around moisture content specifications, end-use purity standards, and transport economics that favor regional processing concentration over long-haul raw material movement.
Product Type:
Standardization dominates sliced beet formats for industrial diffusion extraction, while customization intensifies in dehydrated and milled products serving niche feed and pharmaceutical specifications.
- Sliced Sugar Beets:Fresh-cut cossettes with 75-78% moisture content optimize sucrose diffusion rates in counter-current extraction systems. Red River Valley processors in North Dakota and Minnesota contract 90% of North American supply through dedicated rail-loading terminals. Mechanical harvesting automation compresses field-to-factory windows to 48 hours, limiting spoilage penalties.
- Sugar Beet Pulp:Pressed and dried residue from diffusion extraction contains 8-10% protein and 20-25% fiber by dry weight. Upper Midwest dairy operations in Wisconsin and South Dakota substitute this regional protein source for imported soy meal, creating co-product demand that improves processor crush economics. EPA Renewable Fuel Standard documentation requirements now extend to pulp-derived biogas pathways.
- Dried Sugar Beet Chips:Low-dust pelleted formats command premium positioning in Gulf State equine feed markets.
- Sugar Beet Powder:Spray-dried sucrose concentrates serve pharmaceutical excipient and specialized food applications.
Most installed capacity flows through Sliced Sugar Beets. Expansion is steepest in Sugar Beet Pulp as dairy feed substitution accelerates.
End Use Industry:
Volume concentration sits with food-grade sugar extraction, while regulatory complexity and margin expansion concentrate in fuel pathway certification and pharmaceutical-grade output streams.
- Food & Beverage:Crystalline sugar and liquid sucrose serve cereal, confectionery, and beverage manufacturing with established purity specifications. Minnesota and Illinois processors lock in three-to-five-year supply agreements that embed price collars and volume flexibility clauses, bypassing traditional commodity exchange price discovery. REACH and EFSA frameworks govern molasses residue thresholds in food-grade versus feed-grade separation.
- Biofuels:Beet-to-ethanol conversion efficiency determines credit generation under EPA Renewable Fuel Standard and EU delegated acts. French and Brazilian facilities specify continuous counter-current diffusion technology for water and energy efficiency advantages. Carbon intensity accounting requires granular traceability of cultivation inputs, fertilizer sources, and transport modes.
- Animal Feed:Pulp and molasses residue streams displace imported protein in regional livestock operations.
- Pharmaceuticals:High-purity sucrose excipients demand analytical infrastructure upgrades that strain mid-scale processor capex cycles.
Contracted volume concentrates in Food & Beverage. Regulatory-driven expansion is climbing the fastest in Biofuels as ethanol blending mandates tighten.
Application:
Cost tier separation distinguishes commodity sweetening from premium feed and fuel pathway applications with divergent certification burdens.
- Ethanol Production:Fuel pathway certification under EPA Renewable Fuel Standard and EU F-Gas Regulation requires specialized lifecycle analysis capabilities. French and German facilities leverage existing farm-level data infrastructure from CAP subsidy compliance to meet emerging requirements. Beet ethanol eligibility for credit generation hinges on documented carbon intensity below tightening thresholds.
- Feed Supplements:Regional fiber and protein sources reduce dairy operation dependence on imported soy. Sugar beet pulp captures expanding demand as processors invest in anaerobic digestion assets that generate renewable natural gas certificates under EU Green Deal methane reduction frameworks.
- Baking:Crystalline sugar with specific granulation profiles serves industrial bakery and confectionery formulations.
- Sweetening Agents:Liquid and crystalline sucrose formats compete with cane sugar and high-fructose corn syrup in price-sensitive applications.
Processing infrastructure dedicates the largest share to Sweetening Agents. Capital deployment is expanding most quickly in Ethanol Production as biorefinery offtake contracts lengthen.
Distribution Channel:
Supply concentration in processor-dominated rail corridors shapes channel economics, with export flows requiring specialized bulk terminal investments.
- Direct Sales:Processor-to-manufacturer contracts bypass intermediary margins and enable bilateral price negotiation. Red River Valley cooperatives control loading infrastructure that locks in transport mode decisions for decade-long depreciation periods. Long-term offtake agreements now embed sustainability certification requirements.
- Export:Nordzucker AG's specialized bulk terminals in Denmark and Sweden enable Ukrainian and Polish beet sugar flows to Middle Eastern markets with limited cane competition. Dust-controlled dried sugar beet chips sustain niche flows to Gulf State equine feed markets.
- Wholesale Distributors:Regional aggregators serve smaller food manufacturers without rail siding access.
- Online Retail:Direct-to-consumer channels capture specialty and organic beet sugar segments.
Railcar fleet investment concentrates in Direct Sales. Geographic diversification is gaining share fastest in Export as Baltic Sea corridor capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting beet processing investment toward jurisdictions with streamlined carbon-accounting protocols and integrated biogas incentive structures. Producers migrate capacity where compliance costs compress margins less severely.
United States
EPA Renewable Fuel Standard credit generation pulls acreage toward fuel-pathway certification in Minnesota and North Dakota. The Red River Valley processor concentration enables dedicated rail-loading infrastructure that locks in transport economics. Six-row mechanical harvesters compress field-to-factory windows below 48 hours.
Germany
EU F-Gas Regulation and delegated acts on crop-to-fuel certification expand beet ethanol eligibility in renewable fuel pools. CAP subsidy compliance infrastructure supplies farm-level traceability data for carbon intensity documentation. Saxony-Anhalt and Lower Saxony host integrated starch-sugar platforms with anaerobic digestion assets.
France
Beet-to-ethanol conversion efficiency targets drive continuous counter-current diffusion technology adoption. EFSA frameworks govern molasses residue thresholds separating food-grade from feed-grade streams. Picardy and Champagne-Ardenne processing clusters leverage existing sugar beet cooperatives for biorefinery feedstock contracts.
Poland
EU Green Deal methane reduction frameworks incentivize renewable natural gas certificates from pulp residue digestion. REACH compliance demands analytical infrastructure upgrades that strain mid-scale processor capex. Greater Poland and Kuyavian-Pomeranian Voivodeships concentrate beet sugar output with Baltic Sea export corridor access.
Brazil
Sugar-ethanol platform economics favor cane dominance, yet beet ethanol imports qualify under national biofuel blending mandates. ANVISA pharmaceutical-grade excipient standards create niche demand for spray-dried sucrose concentrates. São Paulo state processors evaluate beet supplementation to diversify feedstock risk.
Sugar Beet Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue integrated biogas and pharmaceutical-grade specialization. Three dominant cooperatives control North American rail-loading infrastructure, creating bilateral contracting power versus commodity exchange price discovery. Strategic archetypes separate into integrated agribusiness conglomerates, regional cooperative processors, and specialty feed ingredient specialists. Competitive moves concentrate on anaerobic digestion asset integration and long-term offtake contracting with carbon-certification clauses.
Among European-based integrated processors, Südzucker AG, Nordzucker AG, and Tereos Group exemplify divergent geographic and technological positioning. Südzucker anchors German and Polish operations around starch-sugar platform control. Nordzucker occupies Baltic Sea logistics specialization through Danish and Swedish bulk terminal assets. Tereos represents beet-to-ethanol conversion efficiency focus at French and Brazilian facilities. These three entities illustrate how scale, corridor access, and fuel-pathway certification capability define competitive separation.
| Leading Market Players |
|---|
| Südzucker AG |
| Nordzucker AG |
| British Sugar |
| Tereos Group |
| Cosun Beet Company |
| American Crystal Sugar Company |
| Michigan Sugar Company |
| Amalgamated Sugar Company |
| Western Sugar Cooperative |
| Others |
Value Chain & Pricing Dynamics
Six-row self-propelled harvester operators in the Red River Valley command wage premiums that compress labor-cost differentials between premium food-grade and standard fuel-pathway beet sugar tiers. This workforce concentration tightens pricing spreads as mechanical harvesting automation diffuses across North Dakota and Minnesota processor catchments.
Pricing Analysis
Distributor margins on wholesale beet sugar flows absorb transport moisture penalties that separate sliced beet premiums from whole root discounts. Three-tier pricing structure across pharmaceutical-grade excipients, food-grade crystalline, and fuel-pathway ethanol separates purity certification tiers with widening spreads as EPA Renewable Fuel Standard documentation burdens intensify. Cost compression in fuel-grade streams is intensifying because carbon intensity accounting expertise scarcity forces processors to outsource compliance analytics. Biofuel refineries exhibit lowest price sensitivity due to mandated blending floors, while small confectionery manufacturers in Illinois and Minnesota face acute margin pressure from locked-in supply agreements.
Supply Chain Analysis
Seasonal harvest labor availability in Saxony-Anhalt and Lower Saxony constrains German processor throughput expansion despite continuous counter-current diffusion technology deployment. Geographic supply concentration centers on the United States, Germany, and France for beet processing infrastructure, with Poland and Brazil as secondary hubs. Raw material flows draw from Red River Valley grower cooperatives, CAP-subsidized French beet farms, and Ukrainian acreage feeding Baltic Sea export corridors. Single-source vulnerability concentrates in rail-loading infrastructure controlled by three North American cooperatives. Distribution runs through processor-direct contracts with food manufacturers and biofuel refineries, bypassing commodity exchange price discovery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sugar beet market represents a late-cycle quality story as dairy feed substitution and pharmaceutical excipient specifications pull demand toward premium-grade pulp and powder segments. Buyers now prioritize documented carbon intensity thresholds over commodity spot pricing.
For Market Incumbents: Acquire anaerobic digestion assets adjacent to existing diffusion extraction facilities to capture renewable natural gas certificates under EU Green Deal frameworks. Consolidate rail-loading terminal control in the Red River Valley to defend against logistics arbitrage by emerging cooperative formations. Vertical integration into farm-level data infrastructure counters carbon intensity accounting expertise scarcity that threatens EPA Renewable Fuel Standard credit generation.
For New Entrants and Emerging Players: Continuous counter-current diffusion technology retrofit services offer entry wedge into mid-scale Polish and Ukrainian processor upgrade cycles. White-space concentration sits with REACH-compliant molasses residue separation infrastructure serving food-grade versus feed-grade stream bifurcation. Gulf State equine feed markets present penetrable premium channel for dust-controlled dried chip formats with limited incumbent presence.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional cooperative processors lacking in-house lifecycle analysis capabilities for fuel pathway certification. Long-term viability hinges on biogas co-generation integration and pharmaceutical-grade excipient analytical infrastructure deployment. Watch Baltic Sea bulk terminal utilization rates as inflection signal for Ukrainian and Polish export corridor expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm-Level Data Infrastructure | CAP subsidy compliance systems supply traceability data for EU F-Gas Regulation carbon intensity documentation. |
| Anaerobic Digestion Asset Deployment | Molasses and pulp residue streams generate renewable natural gas certificates under EU Green Deal methane reduction frameworks. |
| Continuous Counter-Current Diffusion Technology Adoption | French and Brazilian biorefineries specify this equipment for water and energy efficiency in beet-to-ethanol conversion. |
| Baltic Sea Bulk Terminal Expansion | Nordzucker AG's Danish and Swedish terminals enable Ukrainian beet sugar flows to Middle Eastern markets with limited cane competition. |
| Long-Term Offtake Contracting with Certification Clauses | Minnesota and Illinois cereal processors lock in three-to-five-year agreements embedding sustainability requirements and price collars. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with sugar beet processor operations directors, biofuel refinery procurement managers, dairy nutritionists specifying pulp feed rations, and rail logistics coordinators informed demand-side calibration. Secondary validation drew from EPA Renewable Fuel Standard compliance filings, EU ECHA REACH registration data, USDA crop production reports, and customs records of Baltic Sea beet sugar export flows. Triangulation across these sources anchored volume and value estimates.
Historical trendline analysis of beet acreage, processor capacity utilization, and ethanol blending mandate trajectories established baseline growth patterns. Segmentation modeling spanned product type, end-use industry, application, and distribution channel dimensions, with geographic regulatory cluster as an additional cross-cutting variable. CAGRs were derived from fitted trend projections across the analysis window, incorporating sucrose yield ceilings and mechanical harvesting diffusion curves as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU F-Gas Regulation delegated act revisions and carbon border adjustment mechanism implementation timing. Forecasts reflect documented assumptions regarding ethanol blending mandate tightening trajectories and rail infrastructure investment continuity. Material deviation in EPA Renewable Fuel Standard lifecycle threshold tightening or natural gas price volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
India Compound Feed Market
Agriculture and Agri Products
Asia-Pacific Poultry Meat Market
Agriculture and Agri Products
Prunus Africana Market
Agriculture and Agri Products
GCC Poultry Meat Market
Agriculture and Agri Products
Thailand Compound Feed Market
Agriculture and Agri Products
Saudi Arabia Poultry Meat Market
Agriculture and Agri Products
Mexico Compound Feed Market
Agriculture and Agri Products
Lucerne Market
Agriculture and Agri Products
Asia Pacific Animal Feed Market
Agriculture and Agri Products
Taro Market
Agriculture and Agri Products
Europe Alfalfa Hay Market
Agriculture and Agri Products
Australia Floriculture Market
Agriculture and Agri Products
Global Quail Eggs Market
Agriculture and Agri Products
Brazil Compound Feed Market
Agriculture and Agri Products
Flower Pot Market
Agriculture and Agri Products
Netherlands Commercial Greenhouse Market