
 Africa Orange Market | 2026-2036
Africa Orange Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Orange Market Outlook
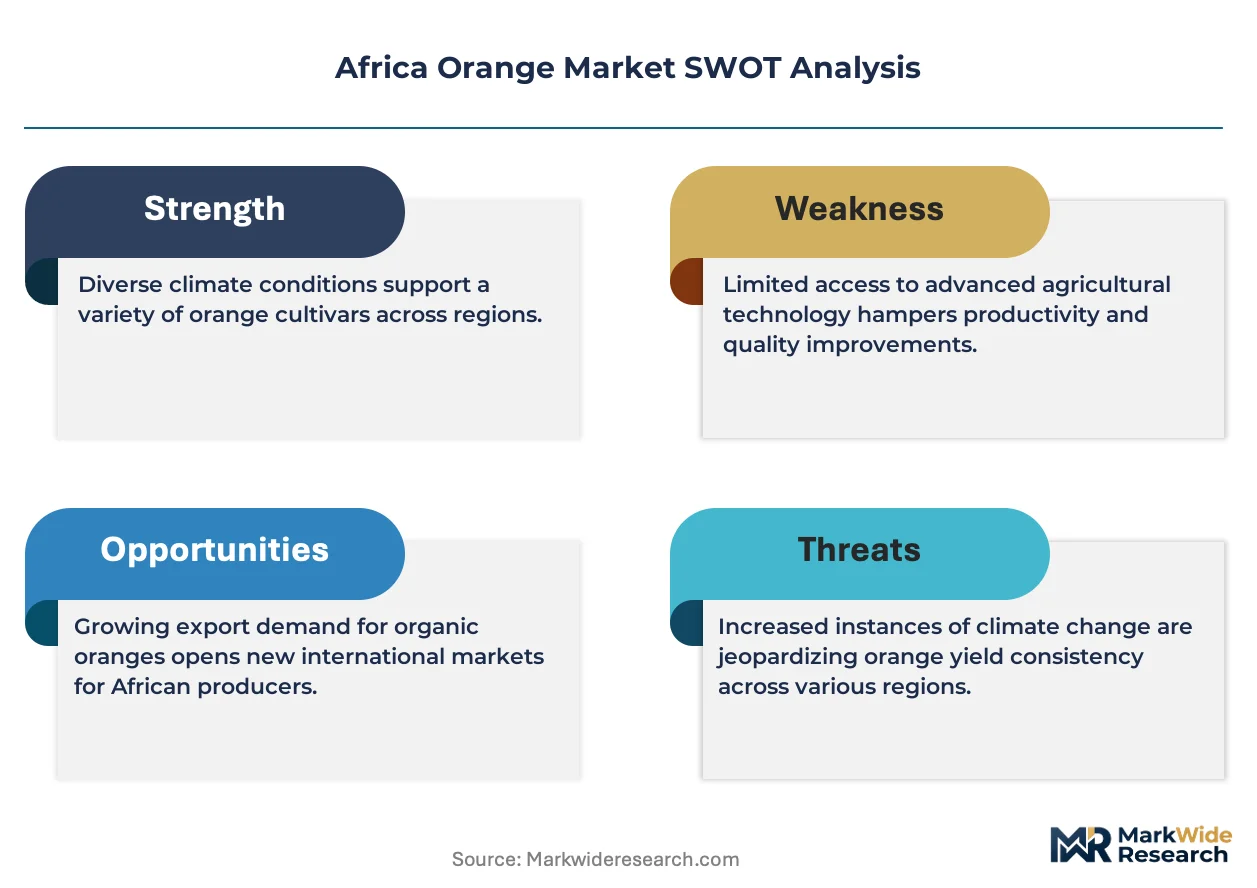
Synthetic packaging films are recalibrating post-harvest economics for African orange exporters. Egypt leverages integrated Nile Delta cold-chain corridors to dominate Middle Eastern wholesale channels. South Africa anchors premium Valencia supply through Western Cape orchard consolidation. Morocco competes via certified organic Navel segments targeting European retail buyers.
Africa oranges comprise Citrus sinensis cultivars with Brix levels of 10-14 degrees, peel oil content of 1.5-2.5 percent, and juice yields of 40-50 percent by mass, serving fresh consumption, concentrate production, and essential oil extraction. Valencia varieties sustain the largest volume pool across wholesale and export channels due to extended harvest windows and superior processing recovery. Nutraceutical applications represent the fastest-growing end-user segment as peel-derived flavonoid extraction scales in Tunisia and Algeria. Carton packaging controls premium retail positioning while bulk formats occupy processor procurement at origin.
Egypt's agricultural quarantine authority enforces EU-aligned phytosanitary standards that determine market access for Navel and Blood orange consignments. South Africa's Department of Agriculture applies PPECB inspection protocols that shape cold-chain investment and export timing decisions. Algeria's national standardization body maintains citrus grading rules affecting price realization for smallholder cooperatives. Stakeholders must monitor evolving SPS certification reciprocity between North African suppliers and Gulf Cooperation Council import regimes.
Market Dynamics
Cold-pressed extraction technology is compressing processing margins across Nigerian juice plants while Egypt's Nile Delta corridor consolidates premium Navel supply for European export channels. This dual technological and geographic concentration is restructuring procurement hierarchies continent-wide.
Growth Catalysts
- EU F-Gas Regulation alignment:South Africa's PPECB certification protocols now synchronize with EU transit standards, unlocking premium cold-chain access for Western Cape Valencia exporters.
- Nutraceutical peel extraction:Flavonoid recovery from orange waste streams is scaling in Tunisia and Algeria, creating parallel revenue pools from previously discarded biomass.
- Cold-pressed juice technology:Nigerian processors are retrofitting extraction lines to capture higher Brix recovery and extend shelf-life credentials for domestic retail placement.
Market Restraints
- Phytosanitary certification bottlenecks:Egypt's agricultural quarantine authority enforces EU-aligned inspection protocols that delay consignment release and compress export windows for smallholder cooperatives.
- Input cost volatility:Synthetic packaging film prices fluctuate with petrochemical feedstock indices, squeezing post-harvest margin buffers for exporters lacking backward integration into material supply.
- Water scarcity in Nile Delta:Irrigation constraints during extended dry cycles limit orchard yield consistency and force quality downgrades for Navel grades destined for European retail.
Strategic Opportunities
- Gulf Cooperation Council SPS reciprocity:Evolving certification mutual recognition between North African suppliers and Saudi SFDA protocols opens direct air-freight channels for Blood orange premium segments.
- Organic certification arbitrage:Morocco's certified organic Navel production qualifies for EU Green Deal import preferences, commanding price premiums in German and Dutch retail chains.
- Integrated cold-chain corridors:Nile Delta infrastructure investments linking orchard consolidation to port-side pre-cooling are compressing transit time to Middle Eastern wholesale hubs.
Industry Challenges
- Phytosanitary compliance timelines:Smallholder cooperatives in Algeria face extended certification delays under national standardization body grading rules, forcing cash-flow gaps between harvest and export realization.
- Extraction technology retrofit costs:Nigerian juice processors confront capital intensity in cold-press line installation, with payback periods stretching across multiple harvest cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Orange Market |
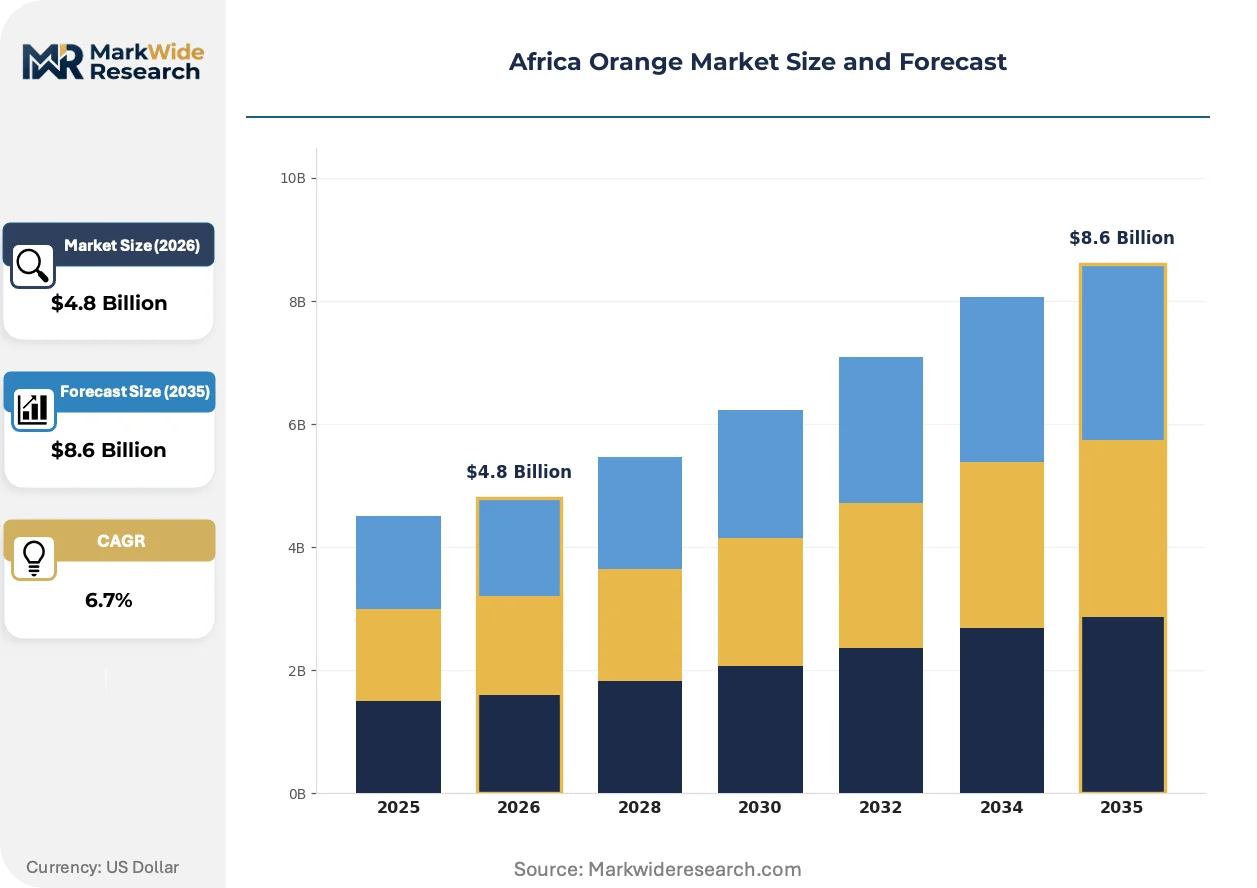
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Navel, Valencia, Blood, Tangerine Distribution Channel: Wholesale, Retail, Online, Export End User: Food Industry, Beverage Industry, Nutraceuticals, Retail Consumers Packaging Type: Carton, Bag, Clamshell, Bulk |
| Companies Covered | Egypt, South Africa, Morocco, Tunisia, Zimbabwe, Libya, Algeria, Turkey, Sudan, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Orange Market Strategic Shifts
Technology adoption and regulatory synchronization are compressing traditional supply hierarchies across African orange channels. Three distinct vectors are restructuring how value is captured from orchard to retail shelf.
Cold-pressed extraction systems are overtaking traditional reaming methods in Nigerian juice processing plants. These systems operate at lower temperatures, preserving volatile aromatic compounds and extending finished product shelf stability. Large-scale processors in Lagos and Ibadan are retrofitting lines to meet retail buyer specifications for non-thermal processing claims.
South Africa's PPECB inspection protocols are tightening alignment with EU F-Gas Regulation transit requirements for controlled-atmosphere shipping. This regulatory convergence forces cold-chain infrastructure upgrades at Western Cape export terminals. Premium Valencia consignments now require continuous temperature logging from orchard gate to European port discharge.
Retail procurement patterns in European destination markets are compressing supplier qualification cycles. German and Dutch supermarket chains now mandate dual organic-phytosanitary certification for Navel and Blood orange shelf placement. Moroccan exporters with pre-existing EU organic accreditation are capturing expanded listing opportunities as compliance thresholds rise.
Africa Orange Market Segmentation
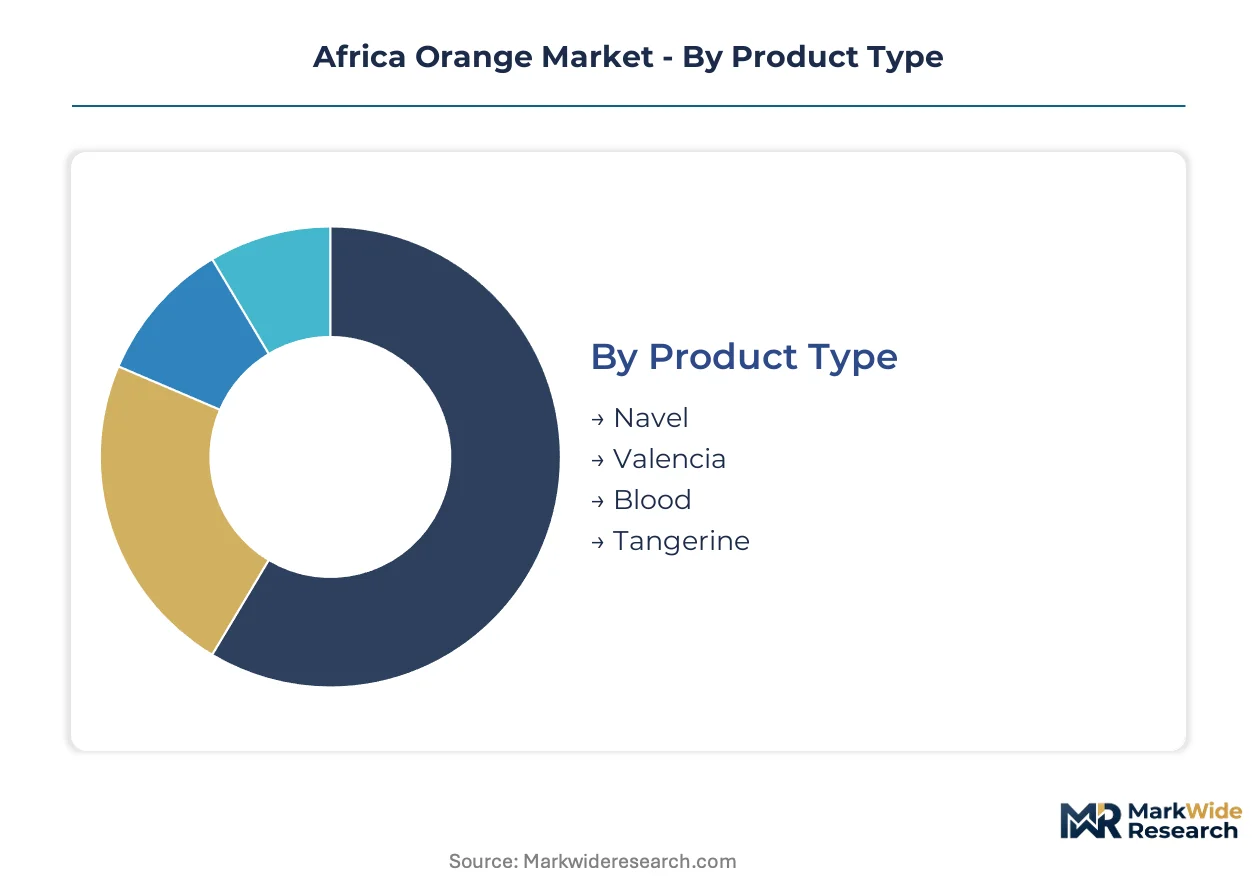
Orange market segmentation across Africa reveals how cultivar selection, channel configuration, and end-use specifications determine value capture. Procurement patterns diverge sharply between fresh export corridors and domestic processing clusters.
Product Type:
Standalone fresh consumption varieties dominate premium export economics while embedded processing cultivars anchor industrial procurement.
- Navel:Seedless Citrus sinensis with thick rind and easy-peel characteristics. Egypt's Nile Delta belt concentrates supply for European retail channels where EU phytosanitary certification gates market access. Water scarcity during extended dry cycles forces quality downgrades.
- Valencia:Late-season cultivar with thin skin, high juice yield of 40-50 percent by mass, and Brix levels of 10-14 degrees. South Africa's Western Cape orchards supply wholesale and concentrate processors; extended harvest windows sustain year-round processor procurement.
- Blood:Anthocyanin-pigmented flesh variant commanding premium positioning in Middle Eastern air-freight channels.
- Tangerine:Mandarina hybrid with loose rind and sweeter profile serving fresh snack segments in North African domestic markets.
Valencia leads volumes today; Blood orange is gaining share fastest through Gulf Cooperation Council premium retail placement.
Distribution Channel:
Channel selection determines margin structure through cold-chain investment intensity and certification burden.
- Wholesale:Aggregator-dominated procurement at origin markets with minimal packaging overhead. Nigerian juice processors source Valencia through Lagos and Ibadan trading hubs where cold-pressed extraction technology is displacing traditional reaming methods.
- Retail:Supermarket and independent grocer placement requiring graded sizing and phytosanitary documentation. Moroccan organic Navel suppliers access German and Dutch chains through EU Green Deal import preferences.
- Online:Direct-to-consumer platforms with last-mile cold-chain gaps limiting penetration outside urban centers.
- Export:Port-integrated logistics with PPECB inspection protocols in South Africa and EU-aligned quarantine standards in Egypt shaping timing decisions.
Export channels capture highest unit margins; retail is expanding most quickly through supermarket consolidation in North African cities.
End User:
Application requirements split procurement between fresh consumption specifications and industrial processing tolerances.
- Food Industry:Fresh segment and ingredient supply for confectionery and bakery applications. Peel oil extraction at 1.5-2.5 percent content serves flavoring compound manufacturers.
- Beverage Industry:Concentrate production and not-from-orange juice bottling. Nigerian processors retrofitting extraction lines to capture higher Brix recovery and extend shelf-life credentials.
- Nutraceuticals:Flavonoid recovery from orange waste streams scaling in Tunisia and Algeria, creating parallel revenue pools from previously discarded biomass.
- Retail Consumers:Fresh consumption with quality grading determining price realization at point of sale.
Beverage industry leads volumes today; nutraceuticals is climbing the fastest as peel-derived extraction scales across North Africa.
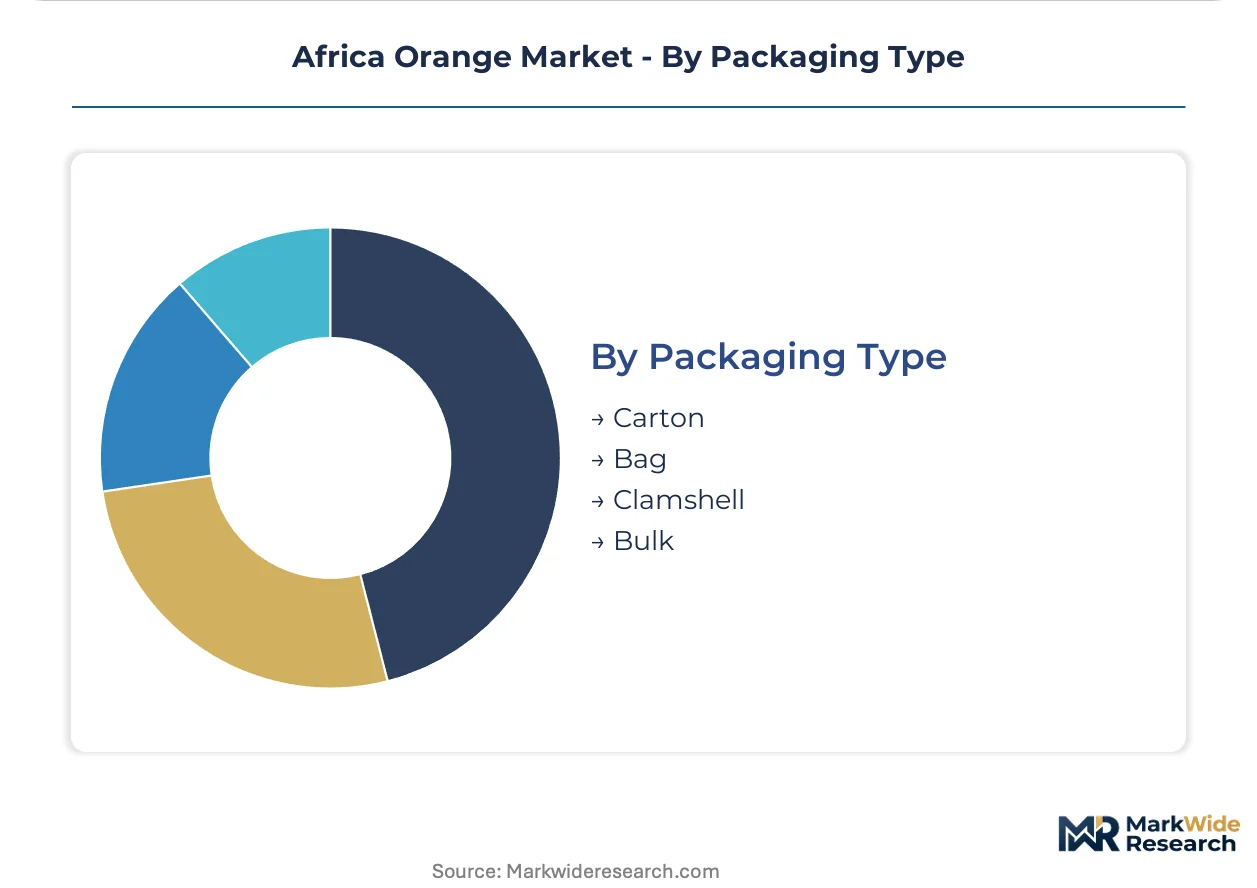
Packaging Type:
Format selection signals market tier and determines post-harvest loss exposure through supply chain length.
- Carton:Premium retail positioning with printed branding and standardized counts. European destination markets mandate dual organic-phytosanitary certification for shelf placement.
- Bag:Economy fresh consumption with mesh or plastic film construction. Synthetic packaging film prices fluctuate with petrochemical feedstock indices, squeezing margin buffers for exporters lacking backward integration into material supply.
- Clamshell:Protected presentation for delicate Blood orange segments in premium retail.
- Bulk:Processor procurement at origin with minimal handling overhead. Nile Delta infrastructure investments linking orchard consolidation to port-side pre-cooling compress transit time to Middle Eastern wholesale hubs.
Bulk leads volumes today; carton is gaining share fastest through supermarket certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Nile Delta farming belt concentrates premium-grade Navel output for European export channels, while South Africa's Western Cape orchards anchor Valencia supply through controlled-atmosphere shipping corridors. Egypt's agricultural quarantine authority enforces EU-aligned phytosanitary standards that determine market access for Blood orange consignments.
Egypt
Phytosanitary certification bottlenecks compress export windows for smallholder cooperatives supplying European retail. The agricultural quarantine authority applies EU-aligned inspection protocols that delay consignment release during peak harvest. Nile Delta infrastructure investments linking orchard consolidation to port-side pre-cooling compress transit time to Middle Eastern wholesale hubs.
South Africa
PPECB inspection protocols synchronize with EU F-Gas Regulation transit standards, unlocking premium cold-chain access for Western Cape Valencia exporters. The Department of Agriculture mandates continuous temperature logging from orchard gate to European port discharge. Cape Town port terminals anchor controlled-atmosphere shipping infrastructure serving concentrate processors and fresh wholesale channels.
Morocco
Certified organic Navel production qualifies for EU Green Deal import preferences, commanding price premiums in German and Dutch retail chains. The national food safety authority maintains citrus grading rules affecting smallholder cooperative price realization. Souss-Massa farming clusters concentrate certified organic supply targeting European supermarket procurement.
Tunisia
Flavonoid recovery from orange waste streams scales across peel-derived nutraceutical extraction facilities. The national standardization body enforces citrus quality grades determining export eligibility for Blood orange air-freight segments. Cap Bon peninsula orchards supply anthocyanin-pigmented variants through direct Gulf Cooperation Council channels.
Nigeria
Cold-pressed extraction technology retrofits compress processing margins across Lagos and Ibadan juice plants. The national food and drug regulator applies local manufacturing standards for not-from-concentrate retail placement. Wholesale aggregator networks at origin markets supply Valencia cultivars to processors displacing traditional reaming methods.
Africa Orange Market Competitive Environment
Capacity expansion dominates the current landscape as Nigerian processors retrofit extraction lines and Egyptian exporters consolidate Nile Delta cold-chain infrastructure. The vendor base spans state-linked agricultural authorities, private orchard consolidators, and integrated juice processors with captive supply arrangements. Three archetypes define competitive positioning: phytosanitary-certified exporters, technology-integrated processors, and organic-accredited specialty growers. M&A activity concentrates among mid-scale orchard operators seeking backward integration into cold-chain assets, while strategic partnerships link North African suppliers to Saudi SFDA protocol alignment.
Among country-based supply authorities, Egypt, South Africa, and Morocco exemplify distinct competitive vectors. Egypt represents the phytosanitary-certified export archetype through its agricultural quarantine authority's EU alignment. South Africa occupies the technology-integrated processor position via PPECB-synchronized cold-chain infrastructure. Morocco anchors the organic-accredited specialty tier through certified Navel production qualifying for EU Green Deal preferences.
| Leading Market Players |
|---|
| Egypt |
| South Africa |
| Morocco |
| Tunisia |
| Zimbabwe |
| Libya |
| Algeria |
| Turkey |
| Sudan |
| Others |
Value Chain & Pricing Dynamics
European retail buyers concentrate procurement power through consolidated supermarket chains, forcing three-tier pricing structure across premium, standard, and economy levels for Navel and Valencia grades. Their volume commitments and dual organic-phytosanitary certification demands compress margin buffers for Egyptian and Moroccan exporters lacking backward integration into cold-chain assets.
Pricing Analysis
Input-cost pass-through from synthetic packaging films and petrochemical feedstock indices squeezes post-harvest economics for exporters without in-house material production. Price differentiation hinges on EU phytosanitary certification tier and organic accreditation status, with Moroccan certified organic Navels commanding premiums in German and Dutch retail. Pricing pressure stems from cold-pressed extraction technology retrofits in Nigerian processing plants. Smallholder cooperatives in Algeria exhibit highest price sensitivity due to extended certification delays; integrated Nile Delta exporters show lowest sensitivity through captive cold-chain infrastructure.
Supply Chain Analysis
Seasonal labor availability in Egypt's Nile Delta, South Africa's Western Cape, and Morocco's Souss-Massa clusters shapes harvest timing and export window compression. Raw material flows draw from Valencia orchards for juice processors, Navel consolidation for European retail, and Blood orange anthocyanin variants for Gulf air-freight. Single-source vulnerability concentrates in Egyptian quarantine authority certification bottlenecks. Distribution runs through port-integrated cold-chain corridors with PPECB inspection protocols at Cape Town terminals and EU-aligned quarantine standards at Alexandria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Africa Orange Market compounds steadily as nutraceutical peel extraction scales waste-stream valorization across North Africa. This structural demand expansion anchors long-term value capture for positioned suppliers.
For Market Incumbents: To counter cold-pressed extraction margin compression, Egyptian exporters should deepen backward integration into Nile Delta pre-cooling infrastructure and secure dual organic-phytosanitary certification lock-in with German retail chains. South African operators must synchronize PPECB protocols with EU F-Gas Regulation transit standards to defend Western Cape Valencia positioning. For New Entrants and Emerging Players: Gulf Cooperation Council supermarket procurement managers represent the most accessible channel partners for Blood orange air-freight segments. Tunisia's flavonoid extraction facilities offer white-space entry through nutraceutical waste-stream partnerships. Algerian smallholder cooperatives present aggregation plays for processors seeking origin-proximate Valencia supply. For Investors and Strategic Acquirers: Integrated juice processors with captive orchard networks are the most active acquirer in this space, consolidating mid-scale Western Cape and Souss-Massa operators. Long-term viability frames around 5-10 year nutraceutical demand expansion. Watch for Saudi SFDA protocol reciprocity announcements as inflection signals for North African export channel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Nile Delta port-side pre-cooling investments compress transit time to Middle Eastern wholesale hubs. |
| Organic Certification Investment | Morocco's EU Green Deal qualification unlocks premium shelf placement in German and Dutch retail chains. |
| Extraction Technology Retrofit | Nigerian processors adopting cold-pressed systems capture higher Brix recovery for domestic retail placement. |
| Phytosanitary Protocol Alignment | South Africa's PPECB synchronization with EU F-Gas Regulation unlocks controlled-atmosphere shipping access. |
| Nutraceutical Waste-Stream Partnership | Tunisia's flavonoid recovery facilities create parallel revenue pools from previously discarded orange biomass. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Egyptian agricultural quarantine officials, South African PPECB inspectors, Nigerian juice plant operations managers, and Moroccan organic certification auditors with secondary validation from customs export records, EU phytosanitary inspection databases, and FAO citrus production statistics. Bottom-up orchard yield modeling and top-down regional consumption estimates were triangulated for convergence.
Segment-weighting approaches applied differential growth assumptions across cultivar types, distribution channels, and end-use applications throughout the forecast period. CAGRs were derived from historical volume trajectories and projected demand elasticity for fresh consumption, concentrate production, and nutraceutical extraction. Modeling incorporated irrigation constraint scenarios for Nile Delta water scarcity and cold-chain infrastructure buildout timelines for Western Cape export terminals.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Saudi SFDA protocol reciprocity negotiations and EU F-Gas Regulation enforcement intensity. Projections reflect assumptions around phytosanitary certification throughput rates and synthetic packaging film price stability. Material deviation in Gulf Cooperation Council import regime alignment or extended Nile Delta drought cycles warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Greenhouse Market
Agriculture and Agri Products
Brazil Cashew Market
Agriculture and Agri Products
Global Guayusa Market
Agriculture and Agri Products
Australia Organic Farming Market
Agriculture and Agri Products
Europe Poultry Feed Market
Agriculture and Agri Products
India Palm Oil Market
Agriculture and Agri Products
Japan Animal Protein Market
Agriculture and Agri Products
Global Medicated Feed Market
Agriculture and Agri Products
North America Bonsai Market
Agriculture and Agri Products
Poultry and Eggs Market
Agriculture and Agri Products
Asia-Pacific Artificial Humus Market
Agriculture and Agri Products
Europe Eggs Market
Agriculture and Agri Products
Uncaria Tomentosa Market
Agriculture and Agri Products
Global Vermicompost Market
Agriculture and Agri Products
South America Swine Feed Premix Market
Agriculture and Agri Products
Africa Cashew Market