
 South America Compound Feed Market | 2026-2036
South America Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
South America Compound Feed Market Analytics
Consolidation among Brazil's integrated poultry processors is expanding the compound feed buyer base toward fewer, larger contracts. JBS S.A. leverages captive feed mills to secure supply chain margins across its Brazilian protein operations. Cargill Inc anchors grain origination networks that supply compound feed manufacturers throughout the Mercosur region. Nutreco N.V. specializes in premix and nutritional solutions that differentiate performance for large-scale swine and poultry producers.
South America compound feed comprises scientifically formulated mixtures of grains, protein meals, vitamins, and minerals designed to deliver precise nutritional profiles for livestock species, with typical formulations containing 40-60% corn and 15-25% soybean meal depending on target animal. The product serves commercial animal agriculture by optimizing feed conversion ratios, reducing mortality, and standardizing output quality across industrial farming operations. Poultry feed dominates volume given Brazil's position as the world's largest chicken exporter, while aquafeed represents the fastest-growing category as Chilean and Brazilian salmon and tilapia producers expand marine and freshwater cage operations. Ingredient composition tilts heavily toward corn and soybean meal, reflecting regional crop production advantages, though barley gains traction in southern Brazil and Argentine feed formulations where climate and rotation patterns support cultivation.
Brazil's Ministry of Agriculture (MAPA) enforces feed safety regulations under IN 15/2014, mandating Good Manufacturing Practices and traceability systems that elevate compliance costs for smaller regional blenders. Argentina's SENASA oversees equivalent feed control standards, while Chile's SERNAMEGTA aligns with OECD agricultural quality frameworks for salmon feed exports. Stakeholders must monitor evolving residue limits and sustainability certification requirements that increasingly determine market access for South American protein exports to European and North American buyers.
Market Dynamics
Brazil's MAPA enforcement of IN 15/2014 feed safety protocols is compressing formulation standards across South America, forcing smaller regional blenders toward consolidation or exit while integrated protein producers capture procurement volume through captive milling capacity.
Growth Catalysts
- Integrated protein processing:Brazil's southeastern poultry and swine clusters are consolidating procurement around fewer, larger compound feed contracts that favor manufacturers with traceable supply chains and volume-scale logistics.
- IN 15/2014 compliance infrastructure:Mandatory Good Manufacturing Practices and ingredient traceability systems are elevating barriers to entry, redirecting demand toward certified suppliers with established quality management protocols.
- Aquaculture cage expansion:Chilean salmon producers and Brazilian tilapia operations are scaling marine and freshwater feed volumes, creating specialized demand for high-performance aquafeed formulations with precise amino acid profiles.
Market Restraints
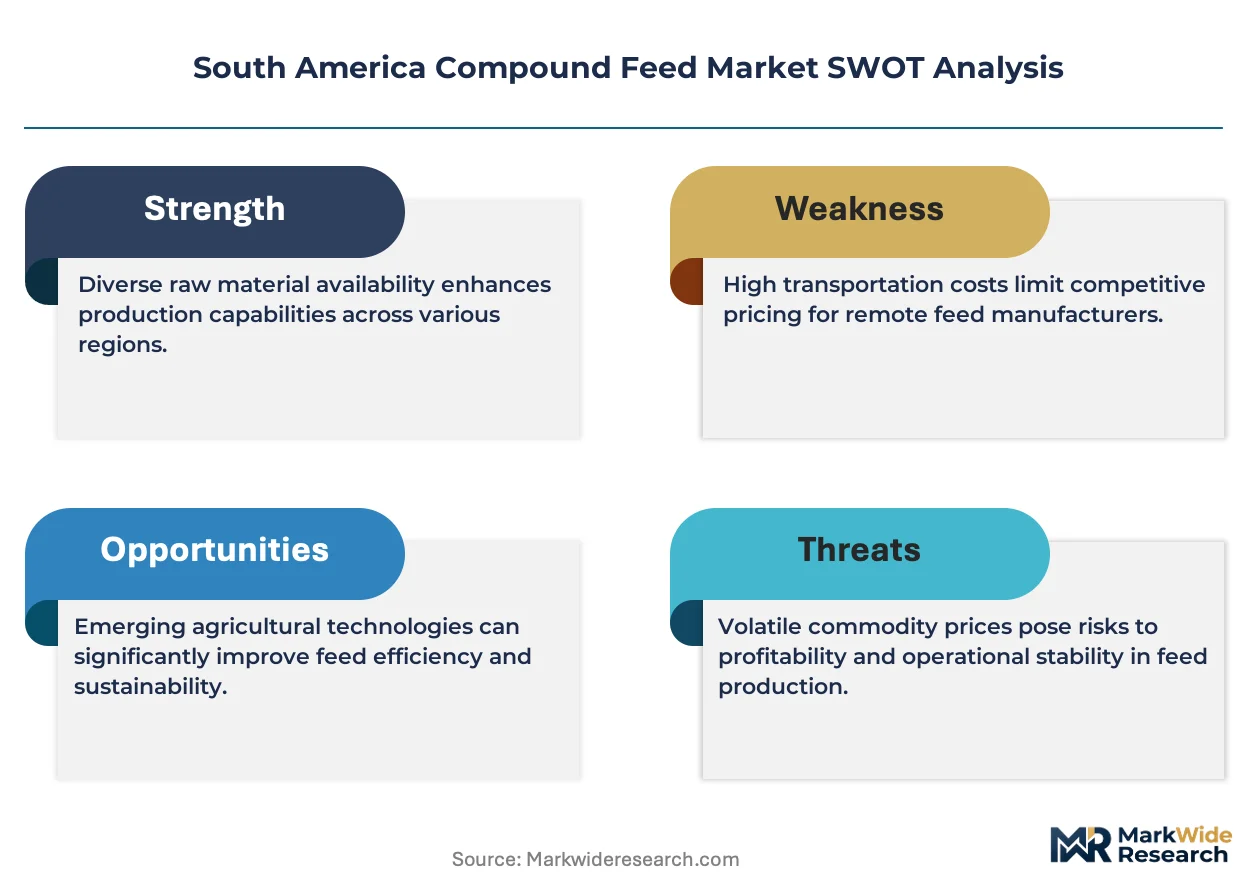
- Corn-soybean meal input concentration:Regional feed formulations depend on 40-60% corn and 15-25% soybean meal, exposing margins to commodity price volatility in Brazil's Center-West grain belt and Argentine Pampas production zones.
- Regional blender fragmentation:Argentina's SENASA-registered facilities and Chile's SERNAMEGTA-certified plants face capacity constraints against MAPA-compliant Brazilian competitors, limiting cross-border supply flexibility.
- Residue limit stringency:European Union and North American import standards for antibiotic-free and mycotoxin-controlled feed outputs are disqualifying non-compliant South American batches from premium export channels.
Strategic Opportunities
- Barley rotation adoption:Southern Brazilian and Argentine feed formulators are diversifying grain bases beyond corn through barley cultivation in cooler climate zones, reducing seasonal input cost spikes.
- Chilean salmon feed specialization:SERNAMEGTA-aligned OECD quality frameworks are enabling Chilean manufacturers to capture premium positioning in marine protein export markets with certified sustainable aquafeed.
- Digital traceability platforms:Blockchain-enabled ingredient tracking systems are emerging as competitive differentiators for MAPA-compliant suppliers seeking to demonstrate chain-of-custody integrity to European buyers.
Industry Challenges
- Formulation chemist scarcity:Brazil's expanding industrial feed sector faces acute shortages of nutritionists capable of optimizing amino acid matrices for high-density poultry and swine operations under IN 15/2014 documentation requirements.
- Legacy mill retrofit costs:Regional blenders in Argentina and Paraguay must deploy capital for automated batching systems and HACCP-compliant infrastructure to maintain market access against Brazilian integrated competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Compound Feed Market |
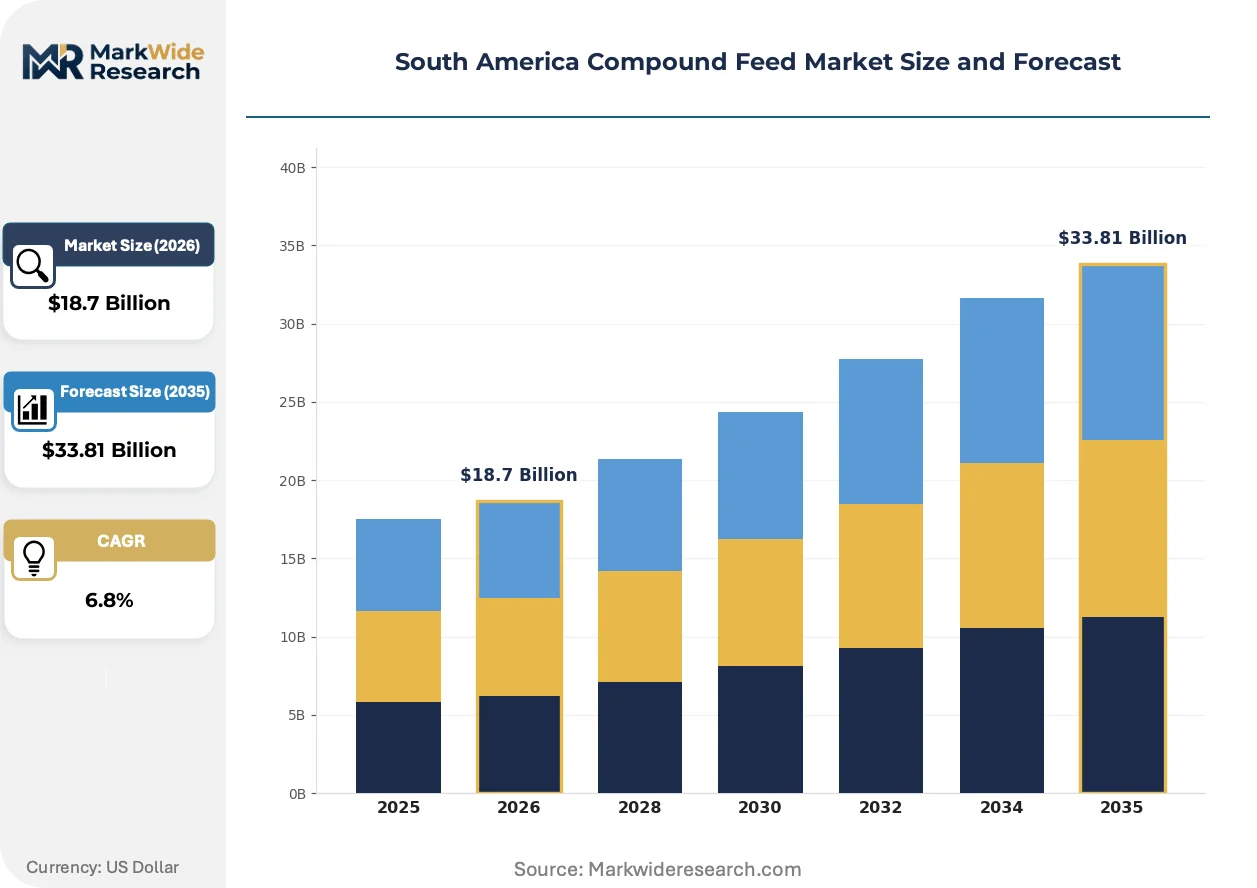
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry Feed, Ruminant Feed, Aquafeed, Swine Feed Ingredient Type: Corn, Soybean Meal, Wheat, Barley End User: Commercial Farms, Feed Manufacturers, Livestock Producers, Aquaculture Distribution Channel: Direct Sales, Retail, E-commerce, Wholesalers |
| Companies Covered | Cargill Inc, BRF, JBS S.A., Land O'Lakes Purina, Alltech Inc, Kemin Industries Inc, Nutreco N.V., Aurora Alimentos, Archer Daniels Midland Company, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Compound Feed Market Evolving Landscape
Precision nutrition platforms and alternative protein ingredients are restructuring how South American feed manufacturers formulate for species-specific performance targets, with digital tools compressing the gap between laboratory optimization and commercial-scale production.
Enzyme-supplemented feed matrices are consolidating cost-efficiency gains across Brazil's commercial broiler operations. Phytase and protease additives reduce phosphorus and crude protein requirements without compromising feed conversion ratios. Large-scale poultry integrators in São Paulo and Minas Gerais are adopting these platforms fastest, compressing the cost advantage gap between technologically equipped formulators and conventional blenders.
SERNAMEGTA's alignment with OECD agricultural quality frameworks is reshaping certification requirements for Chilean salmon feed exports. The regulatory convergence mandates documented sustainability metrics and residue-controlled ingredient sourcing for market access to European retail channels. Chilean aquafeed manufacturers are responding by restructuring supplier qualification protocols and investing in marine-origin raw material traceability systems.
Contracting patterns among Brazil's protein processors are compressing supplier rosters toward integrated feed mill operators with captive grain origination networks. JBS S.A. and similar consolidators are internalizing formulation capacity to capture margin pools previously allocated to third-party manufacturers. This concentration is most visible in Brazil's southeastern states, where procurement committees now prioritize supply security and price predictability over multi-source bidding flexibility.
South America Compound Feed Market Segmentation
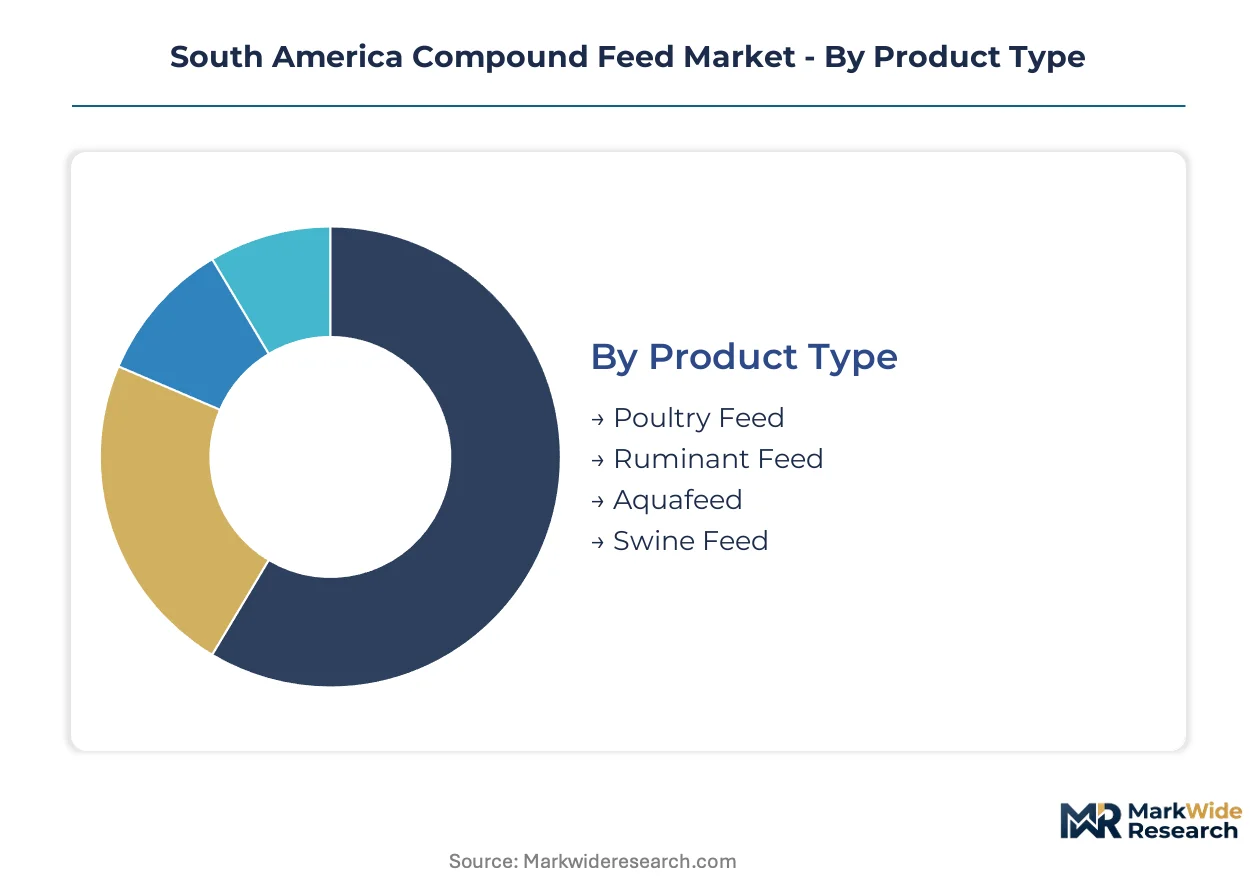
Compound feed segmentation in South America reflects the region's agricultural specialization, with poultry and aquaculture driving distinct formulation requirements. Understanding these divisions clarifies how procurement concentrates among integrated processors versus independent livestock operations.
Product Type:
Poultry feed dominates volume throughput while aquafeed commands premium formulation margins across Brazilian and Chilean production zones.
- Poultry Feed:Formulations contain 40-60% corn and 15-25% soybean meal optimized for broiler feed conversion ratios in São Paulo and Minas Gerais integrated operations. Brazil's position as the world's largest chicken exporter sustains massive procurement contracts from processors like JBS S.A. with captive milling capacity.
- Aquafeed:High-performance matrices with precise amino acid profiles serve Chilean salmon cages and Brazilian tilapia operations. SERNAMEGTA-aligned OECD quality frameworks enable premium positioning in European retail channels for residue-controlled marine protein exports.
- Ruminant Feed:Corn-silage based formulations support cattle finishing operations in Brazil's Center-West and Argentine Pampas grazing systems.
- Swine Feed:Lysine-supplemented diets address genetic improvement trends in Santa Catarina and Paraná sow operations under IN 15/2014 traceability mandates.
Poultry feed absorbs the bulk of installed capacity; aquafeed is expanding most quickly.
Ingredient Type:
Regional crop advantages concentrate sourcing around Brazil's Center-West grain belt, with climate-driven alternatives gaining traction in southern latitudes.
- Corn:The dominant energy source comprising 40-60% of typical formulations, sourced from Mato Grosso and Goiás production zones. MAPA-compliant traceability systems track batches from farm gate to feed mill for export-bound protein operations.
- Soybean Meal:Primary protein component at 15-25% inclusion rates, crushing capacity concentrates near Santos port logistics corridors. Argentine meal competes for cross-border supply into southern Brazilian formulations.
- Barley:Rotation crop expanding in Rio Grande do Sul and Argentine feed zones where cooler climates reduce seasonal corn price spikes.
- Wheat:Secondary energy source in southern Brazilian and Uruguayan formulations where milling byproducts integrate into ruminant rations.
Corn and soybean meal together command the majority of ingredient procurement spend; barley is gaining share fastest among alternative grains.
End User:
Procurement patterns diverge sharply between vertically integrated protein processors and independent livestock operators with fragmented purchasing power.
- Commercial Farms:Large-scale poultry and swine integrators in Brazil's southeastern states negotiate volume contracts with price predictability clauses. These operators prioritize supply security over multi-source bidding flexibility.
- Aquaculture:Chilean salmon producers and Brazilian tilapia cage operators demand certified sustainable feed with documented chain-of-custody for European market access.
- Feed Manufacturers:Third-party blenders serving independent livestock producers face MAPA compliance cost pressures and consolidation toward certified suppliers.
- Livestock Producers:Cattle ranchers in Argentina's Pampas and Brazil's Pantanal purchase bulk rations through cooperative purchasing arrangements.
Commercial farms absorb the bulk of compound feed volume; aquaculture is climbing the fastest among end-user categories.
Distribution Channel:
Logistics infrastructure and contract scale determine channel selection, with direct sales capturing integrated processor volume and retail serving dispersed independent operations.
- Direct Sales:Long-term supply agreements link major protein processors to compound feed manufacturers with dedicated logistics corridors. JBS S.A. and similar consolidators internalize this channel through captive mill networks.
- Wholesalers:Regional distributors aggregate demand from mid-scale livestock operations across Paraguay, Uruguay, and Argentina's interior provinces.
- Retail:Farm supply stores serve smallholder poultry and swine producers with bagged feed products in Brazil's northeastern and Amazonian states.
- E-commerce:Digital platforms emerge for premix and nutritional supplement ordering among technically sophisticated independent producers.
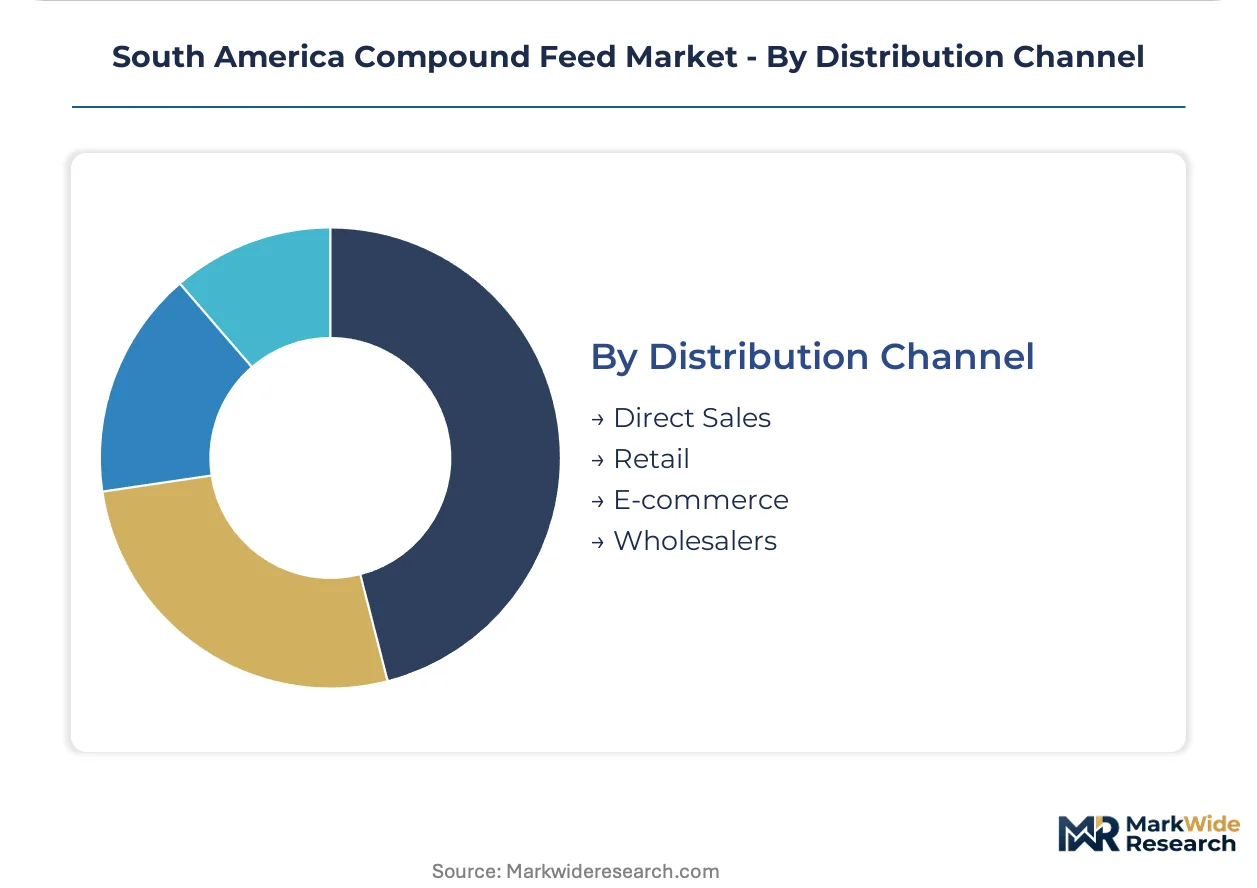
Direct sales captures the bulk of transaction value; e-commerce is expanding most quickly among channel alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial livestock farms concentrate compound feed procurement in Brazil's southeastern states, where integrated poultry and swine operations generate the region's dominant demand pull. Argentina and Chile follow as specialized suppliers with distinct regulatory frameworks shaping their competitive positioning.
Brazil
Integrated protein processors in São Paulo and Minas Gerais are consolidating procurement around fewer, larger compound feed contracts that favor manufacturers with traceable supply chains. MAPA enforces IN 15/2014 feed safety protocols mandating Good Manufacturing Practices and ingredient traceability systems. JBS S.A. leverages captive feed mills across its Brazilian protein operations to secure supply chain margins.
Argentina
Cattle finishing operations in the Pampas grazing zones sustain demand for corn-silage based ruminant formulations alongside poultry and swine feed production. SENASA oversees feed control standards equivalent to Brazilian MAPA requirements, elevating compliance costs for regional blenders. Crushing capacity near Rosario port logistics corridors supplies soybean meal for cross-border formulations into southern Brazil.
Chile
Salmon producers scaling marine cage operations generate specialized demand for high-performance aquafeed with precise amino acid profiles. SERNAMEGTA aligns with OECD agricultural quality frameworks, enabling premium positioning in European retail channels for residue-controlled marine protein exports. Manufacturers in the Los Lagos Region are restructuring supplier qualification protocols to meet documented sustainability metrics.
Colombia
Poultry integrators in the Cundinamarca and Antioquia departments are expanding commercial broiler operations, driving procurement of corn-soybean meal formulations. The country's national agricultural regulator enforces feed safety protocols that elevate barriers to entry for smaller regional blenders. Feed manufacturers near Bogotá are investing in automated batching systems to maintain market access against Brazilian integrated competitors.
Paraguay
Mid-scale livestock operations across the Eastern Region purchase compound feed through cooperative purchasing arrangements and regional distributors. The country's agricultural quality framework requires legacy mill retrofits for automated systems and HACCP-compliant infrastructure. Processing clusters near Asunción face capacity constraints against MAPA-compliant Brazilian competitors, limiting cross-border supply flexibility.
South America Compound Feed Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized aquafeed and precision nutrition platforms. The market structure tilts toward consolidation as integrated protein processors internalize milling capacity through captive operations. Three archetypes dominate: grain-origination conglomerates with logistics networks, premix specialists with nutritional solutions, and integrated protein processors with backward control over feed supply. Competitive moves center on M&A-driven consolidation and geographic expansion into adjacent Mercosur markets.
Within the grain-origination tier, Cargill Inc anchors supply networks throughout the Mercosur region. Nutreco N.V. exemplifies the premix and nutritional solutions archetype, occupying a position differentiated by performance optimization for large-scale operations. JBS S.A. represents integrated processor verticalization, sitting within the captive milling tier that is compressing third-party manufacturer margins across Brazil's southeastern states.
| Leading Market Players |
|---|
| Cargill Inc |
| BRF |
| JBS S.A. |
| Land O'Lakes Purina |
| Alltech Inc |
| Kemin Industries Inc |
| Nutreco N.V. |
| Aurora Alimentos |
| Archer Daniels Midland Company |
| Others |
Value Network & Pricing Analysis
Family-owned regional blenders across Argentina and Paraguay face capital constraints that limit MAPA-equivalent compliance investment, compressing their pricing power against Brazilian integrated processors with captive grain origination networks and volume-scale logistics corridors. This ownership-structure divergence concentrates margin capture among consolidators while forcing smaller competitors toward exit or acquisition.
Pricing Analysis
Volume-scale poultry feed contracts absorb procurement spend while aquafeed commands formulation premiums. Pricing stratifies across MAPA-certified premium tiers, SERNAMEGTA-aligned OECD standard tiers, and non-certified economy batches serving domestic-only channels. Cost compression in economy-tier rations intensifies as Brazilian integrated processors internalize milling capacity. Independent livestock producers in Brazil's northeastern states exhibit highest price sensitivity; Chilean salmon exporters demonstrate lowest sensitivity due to residue-controlled certification requirements.
Supply Chain Analysis
Compound feed formulation rests on Brazilian Center-West corn production, Argentine Pampas soybean meal crushing capacity, and southern Brazilian barley cultivation zones. MAPA-compliant traceability systems, SENASA-registered facility standards, and SERNAMEGTA-aligned OECD frameworks constitute critical regulatory infrastructure. Commodity price volatility in Brazil's grain belt presents persistent supply risk. Distribution runs through direct sales agreements linking integrated processors to captive mill networks, with wholesalers aggregating fragmented independent demand across Mercosur border zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MAPA enforcement of IN 15/2014 feed safety protocols functions as a consolidation mechanism, elevating compliance costs that force smaller regional blenders toward exit while integrated protein processors capture procurement volume through backward integration into captive milling capacity.
For Market Incumbents: To counter margin compression from JBS S.A.-style captive feed mill networks, third-party manufacturers should deepen backward integration into grain origination corridors near Santos port logistics hubs and accelerate MAPA certification investment to disqualify non-compliant competitors from export-bound protein contracts. For New Entrants and Emerging Players: Mid-scale tilapia cage operators in Brazil's northeastern states represent an underserved buyer archetype requiring residue-controlled but lower-volume aquafeed formulations than Chilean salmon producers demand. Entry should leverage digital traceability platforms as competitive differentiators for European market access. For Investors and Strategic Acquirers: Accelerating acquisition activity among Argentine SENASA-registered facilities is the leading indicator that regional blender consolidation is reaching terminal velocity. The analysis frames this as a 5-to-10-year roll-up opportunity targeting mid-cap formulators with automated batching infrastructure and cross-border logistics capabilities. Watch for SERNAMEGTA-OECD alignment investments as certification-premium capture signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Cargill-style supply networks secure corn-soybean meal cost advantages against spot-market volatility. |
| MAPA Certification Investment | IN 15/2014 compliance unlocks export-bound poultry processor contracts disqualifying regional competitors. |
| Digital Traceability Platform Deployment | Blockchain-enabled chain-of-custody systems differentiate suppliers for European antibiotic-free import standards. |
| Aquafeed Specialization | SERNAMEGTA-aligned OECD frameworks enable premium positioning in Chilean salmon export channels. |
| Automated Batching System Retrofit | HACCP-compliant infrastructure preserves market access against Brazilian integrated competitor expansion. |
Research Methodology
Multi-period observation of MAPA enforcement patterns, IN 15/2014 compliance adoption curves, and integrated processor procurement consolidation anchored the trend analysis, supplemented by interviews with feed formulation chemists, grain origination traders, poultry processor procurement committees, and SENASA regulatory affairs officers. Secondary validation drew from Brazilian Ministry of Agriculture enforcement bulletins, Argentine SENASA facility registration databases, Chilean SERNAMEGTA export certification records, and Mercosur customs trade data. Bottom-up volume modeling triangulated against top-down protein production forecasts.
Input-output matrices mapped corn-soybean meal price elasticity against poultry feed conversion ratios across the projection horizon. Segmentation dimensions modeled include species-specific formulation requirements, ingredient type concentration, end-user procurement scale, and distribution channel logistics structure. CAGRs derived from trend extrapolation of enforcement-driven compliance cost trajectories and aquaculture cage expansion rates. Industry-specific inputs incorporated phytase adoption curves and barley rotation penetration in southern latitudes.
Revisions become necessary when MAPA enforcement intensity shifts, SERNAMEGTA-OECD alignment requirements tighten, or Brazilian integrated processors accelerate captive mill construction beyond current trajectories. Forecasts reflect documented assumptions regarding regulatory stability and commodity price band persistence. A small set of named triggers—enforcement escalation, certification framework convergence, and grain belt climate disruption—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
United States Alfalfa Market
Agriculture and Agri Products
Beet Pulp Market
Agriculture and Agri Products
Indonesia Animal Feed Market
Agriculture and Agri Products
LAMEA Artificial Humus Market
Agriculture and Agri Products
Mushroom Cultivation Market
Agriculture and Agri Products
Organic Quinoa Market
Agriculture and Agri Products
Alfalfa Market
Agriculture and Agri Products
Russia Compound Feed Market
Agriculture and Agri Products
Residential Organic Compost Market
Agriculture and Agri Products
China Compound Feed Market
Agriculture and Agri Products
South America Swine Feed Premix Market
Agriculture and Agri Products
LAMEA Rapeseed Oil Market
Agriculture and Agri Products
Primary Feed Materials Market
Agriculture and Agri Products
Colombia Hemp Market
Agriculture and Agri Products
Colombia Agriculture Market
Agriculture and Agri Products
Organic Soymeal Market