
 Argentina Agriculture Market | 2026-2036
Argentina Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Agriculture Market Insights
Argentina's National Agri-Food Health and Quality Service (SENASA) phytosanitary certification overhaul is shifting procurement priorities toward traceable supply chains. Cargill Argentina S.A. leverages its integrated grain elevator network to sustain origination volumes across the Pampas region. Adecoagro S.A. anchors its competitiveness through direct farmland management and ethanol processing assets. Bunge Argentina S.A. dominates port terminal logistics at Rosario, controlling the critical export corridor to Paraná River deep-water terminals.
Argentina agriculture encompasses crop cultivation, livestock husbandry, and agro-industrial processing across temperate grasslands and subtropical zones, with soybean protein content typically ranging from 38% to 42% and wheat milling yields calibrated to 75% extraction rates for domestic consumption and export. The sector serves food processing, animal feed formulation, biofuel feedstock supply, and textile fiber production as primary commercial endpoints. Oilseeds command the dominant value pool within product type segmentation due to crushing margin capture and biodiesel mandate pull-through. Wholesale channels retain structural primacy in distribution, though cooperative aggregation is gaining volume share as smaller producers seek collective bargaining power against trader oligopsony.
SENASA enforces phytosanitary border controls and export certification that dictate market access timing and compliance costs for grain and oilseed shipments. The Secretariat of Agriculture, Livestock and Fisheries administers export duty structures and registration requirements that directly alter farmer selling incentives and trader hedging strategies. The Central Bank of Argentina's foreign exchange regulations constrain dollar repatriation timelines, injecting working capital friction into commodity trading operations. Stakeholders must monitor regulatory volatility around export policy and currency convertibility as determinants of investment recovery horizons and farmgate price transmission.
Market Dynamics
SENASA's phytosanitary certification overhaul is compressing origination timelines and forcing traders to restructure supply chain documentation systems ahead of the 2024 export season.
Growth Catalysts
- Brazilian Food Processing Demand:Crushing capacity expansion in São Paulo and Paraná states pulls Argentine soybean protein across the border through simplified MERCOSUR sanitary protocols.
- Biodiesel Blend Mandates:Argentina's domestic biofuel law sustains crush margins even when export parity weakens, anchoring farmer selling liquidity.
- Traceability Technology Adoption:Blockchain-enabled grain tracking from farm to port terminal satisfies EU deforestation regulation documentation requirements for premium market access.
Market Restraints
- Input Cost Volatility:Urea and diammonium phosphate pricing swings, tied to natural gas feedstock fluctuations, compress planting margin predictability for wheat and corn rotations.
- Port Terminal Concentration:Rosario-San Lorenzo corridor handles over 80 percent of grain exports, creating weather and labor stoppage vulnerability.
- Foreign Exchange Friction:Central Bank of Argentina repatriation timelines and parallel exchange rate spreads distort farmgate price signals and working capital cycles.
Strategic Opportunities
- Northwest Region Expansion:Santiago del Estero and Tucumán provinces offer untapped irrigation potential for specialty crops with lower SENASA inspection queue congestion.
- Organic Certification Premiums:EU organic import quotas and US NOP equivalence agreements create price arbitrage for Pampas producers completing three-year transition protocols.
- Cooperative Aggregation Platforms:Digital silo receipt tokenization enables smaller producers to pool volumes and access Rosario terminal direct shipping, bypassing trader oligopsony.
Industry Challenges
- Agronomic Data Integration:Fragmented farm management software systems resist interoperability with SENASA's electronic phytosanitary certificate platform, delaying export clearance.
- Certified Seed Multiplication:Intacta RR2 Pro and Enlist E3 trait approval timelines lag North American introduction by multiple growing seasons, constraining varietal competitiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Agriculture Market |
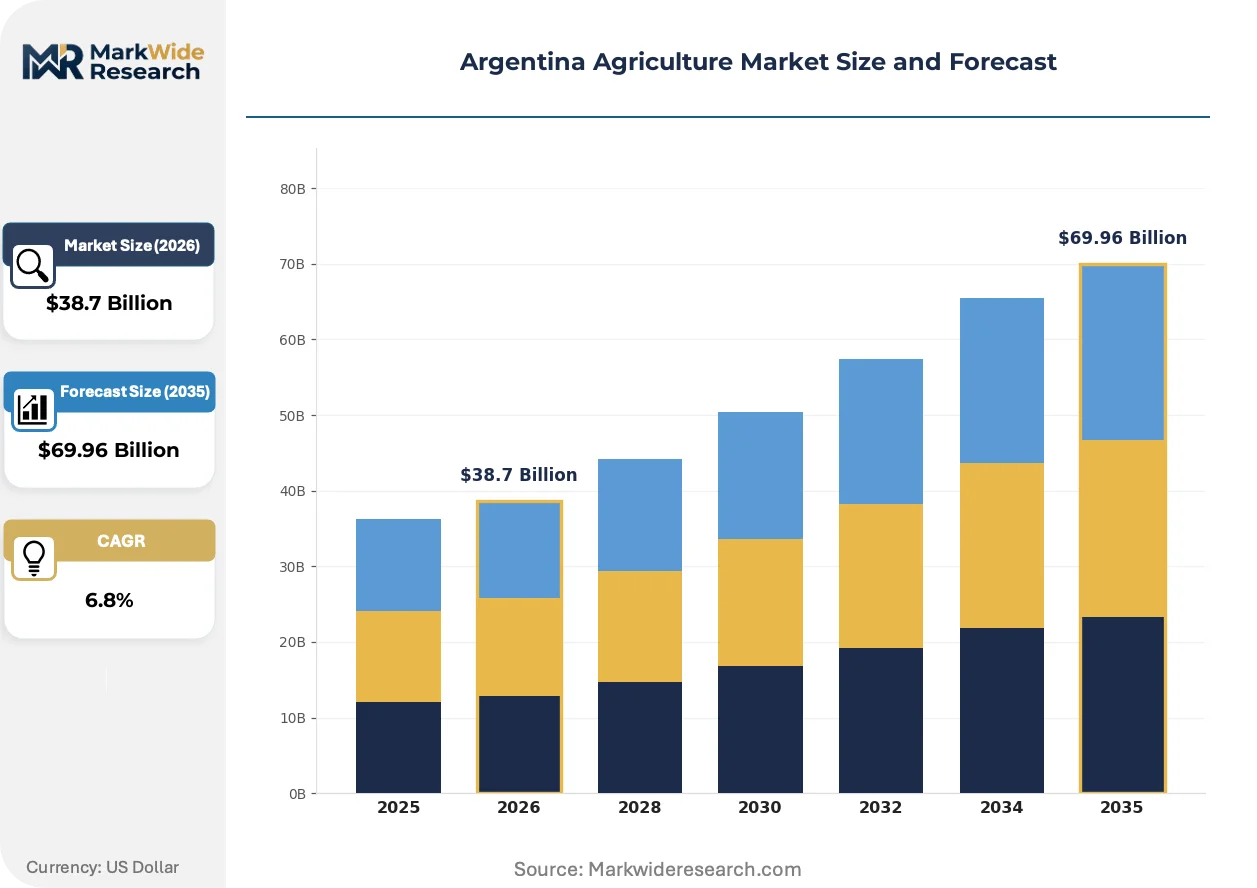
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereals, Oilseeds, Fruits, Vegetables End Use Industry: Food Processing, Animal Feed, Biofuels, Textile Distribution Channel: Wholesale, Retail, Export, Cooperative Packaging Type: Bags, Boxes, Bulk, Other |
| Companies Covered | Cargill Argentina S.A., Bunge Argentina S.A., COFCO International Argentina S.A., Adecoagro S.A., Los Grobo Agropecuaria S.A., Aceitera General Deheza, Lartirigoyen, MSU Agro, LIPSA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Agriculture Market Trends and Innovations
Digital infrastructure and regulatory compliance requirements are compressing decision cycles across origination, logistics, and export certification workflows in Argentine agriculture.
Variable-rate input application hardware is unifying soil sampling data with prescription planting algorithms across the Pampas. Large-scale mixed-crop operations in Buenos Aires province deploy these systems at accelerating replacement cycles for legacy spreading equipment. The technology is unifying agronomic precision with SENASA-mandated field activity records, satisfying traceability audits without duplicate documentation.
SENASA's electronic phytosanitary certificate platform mandates real-time lot tracking from elevator intake to vessel loading. Export traders must reconfigure grain flow documentation to capture GPS-tagged origin coordinates and pesticide application histories. Soybean shipments destined for European Union ports face the tightest compliance windows, with rejection risk for incomplete digital certificates.
Buyer consortiums among domestic feed millers are consolidating procurement volumes and demanding direct farmgate contracting with price transparency clauses. Traditional cooperative and trader intermediaries lose volume share as these aggregators build captive supply relationships. The pattern concentrates in Córdoba province, where poultry and dairy integration density supports dedicated corn and soybean meal supply agreements.
Argentina Agriculture Market Segmentation
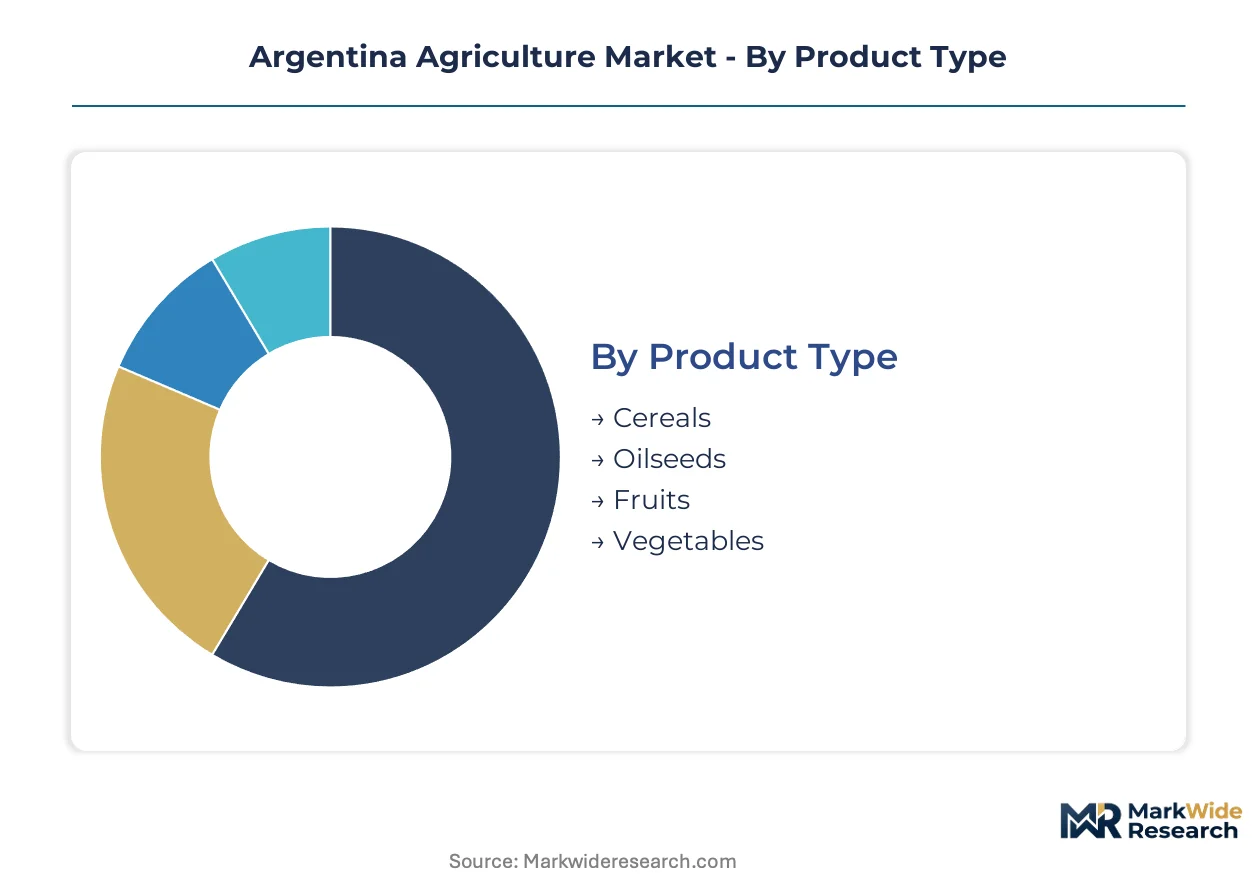
Segmentation in Argentine agriculture reveals how SENASA compliance requirements and export corridor logistics reshape commercial flows across product categories and channel structures. Understanding these divisions clarifies where traceability investments concentrate and which buyer configurations command pricing power.
Product Type:
Integration depth varies sharply: oilseeds and cereals flow through vertically coordinated crushing and export systems, while fruits and vegetables operate in fragmented spot markets with minimal embedded processing.
- Oilseeds:Soybean dominates planted area with protein content between 38% and 42%, feeding crushing margins that biodiesel mandates sustain. Demand concentrates in Buenos Aires province elevators serving Rosario export terminals, with SENASA phytosanitary certificates now requiring GPS-tagged origin documentation.
- Cereals:Wheat and corn rotations anchor the Pampas grain belt, with milling yields calibrated to 75% extraction rates for domestic consumption. Wheat shipments face the tightest EU deforestation regulation compliance windows, forcing blockchain-enabled field activity records.
- Fruits:Citrus and stone fruit production clusters in Tucumán and Entre Ríos provinces, supplying fresh export markets with shorter value chains than bulk grains.
- Vegetables:Tomato and onion cultivation serves domestic processing and fresh retail channels, bypassing the Rosario terminal concentration that constrains grain logistics.
Oilseeds leads volumes today; fruits is gaining share fastest through organic certification premiums and EU quota access.
End Use Industry:
Cost tier differentiation separates commodity-scale buyers with captive supply agreements from specialty processors paying traceability premiums.
- Food Processing:Soybean crushing and wheat milling dominate value capture, with Brazilian food processors in São Paulo and Paraná pulling Argentine protein across MERCOSUR borders. SENASA sanitary protocols enable simplified cross-border flows relative to extra-regional exports.
- Animal Feed:Poultry and dairy integration density in Córdoba province drives dedicated corn and soybean meal procurement, with buyer consortiums consolidating volumes and demanding direct farmgate contracting.
- Biofuels:Argentina's domestic biofuel law sustains crush margins and farmer selling liquidity even when export parity weakens, anchoring ethanol processing assets.
- Textile:Cotton fiber production serves domestic textile mills with limited export orientation, operating outside the grain-centric SENASA certification overhaul.
Food processing commands the largest value pool; biofuels demonstrates the steepest expansion trajectory through mandate-driven demand.
Distribution Channel:
Customer type determines channel selection: large traders control wholesale and export flows, while cooperative aggregation gains traction among smaller producers seeking collective bargaining power.
- Wholesale:Cargill, Bunge, and ADM origination networks retain structural primacy, leveraging integrated grain elevators across the Pampas to sustain volume capture.
- Export:Rosario-San Lorenzo corridor handles the majority of grain shipments, with port terminal concentration creating weather and labor stoppage vulnerability.
- Cooperative:Digital silo receipt tokenization enables smaller producers to pool volumes and access Rosario terminal direct shipping, bypassing trader oligopsony.
- Retail:Fresh produce and packaged goods serve domestic supermarket chains with localized logistics requirements distinct from bulk commodity flows.
Wholesale channels dominate transaction volumes; cooperative platforms are expanding most quickly through producer aggregation technology.
Packaging Type:
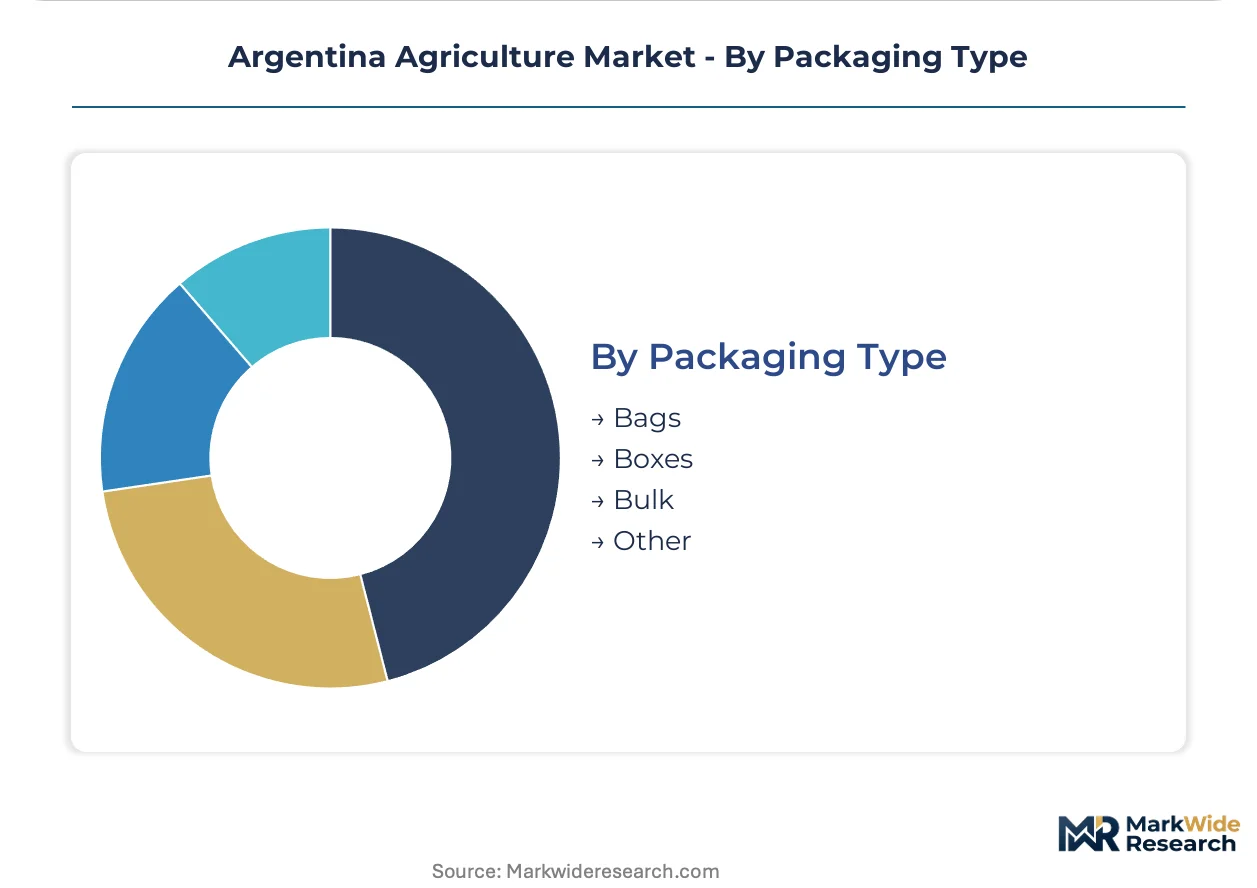
Volume scale dictates packaging economics: bulk shipment minimizes unit costs for export grain, while bagged and boxed formats serve differentiated domestic and specialty markets.
- Bulk:Unpacked grain flows dominate oilseed and cereal exports through Paraná River deep-water terminals, minimizing handling costs but requiring precise moisture management.
- Bags:Polypropylene and paper bags serve domestic milling and retail distribution, with SENASA lot tracking requirements now extending to packaged goods documentation.
- Boxes:Corrugated containers protect fresh fruit and vegetable shipments for export quality preservation, particularly for EU-bound citrus.
- Other:Flexible intermediate bulk containers and reusable totes serve specialty seed and organic product segments with higher per-unit value.
Bulk packaging leads volumes today; bagged formats are climbing the fastest through domestic food security stockpiling requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina's agricultural industry traces its modern scale to late 19th-century European settlement and the expansion of rail networks across the Pampas, transforming the region into a dominant soybean and wheat exporter by the late 20th century.
Buenos Aires Province
Soybean crushing demand from Rosario export terminals drives elevator origination volumes across the Pampas grain belt. SENASA phytosanitary certification requirements now mandate GPS-tagged field documentation for EU-bound shipments. The Azul and Tandil clusters host precision agriculture equipment deployment for variable-rate input application.
Córdoba Province
Poultry and dairy integration density sustains dedicated corn and soybean meal procurement through direct farmgate contracting. The Secretariat of Agriculture administers export duty structures that alter farmer selling incentives during harvest windows. The Marcos Juárez and Río Cuarto corridors concentrate feed miller buyer consortiums consolidating procurement volumes.
Santa Fe Province
Rosario-San Lorenzo port terminal logistics anchor the critical export corridor to Paraná River deep-water terminals. Central Bank foreign exchange regulations inject working capital friction into commodity trading operations through dollar repatriation timeline constraints. The San Lorenzo crushing complex handles the majority of soybean protein shipments destined for Brazilian food processors.
Entre Ríos Province
Citrus and rice cultivation supplies fresh export markets with distinct logistics requirements from bulk grain flows. MERCOSUR sanitary protocols enable simplified cross-border shipments to Brazilian processors relative to extra-regional exports. The Concordia and Gualeguaychú clusters specialize in early-season citrus varieties capturing premium EU quota windows.
Santiago del Estero Province
Untapped irrigation potential for specialty crops attracts investment amid lower SENASA inspection queue congestion at northwest border crossings. Biodiesel blend mandates sustain crush margins and farmer selling liquidity even when export parity weakens. The Quimilí and Añatuya sub-regions pilot center-pivot expansion for corn and sorghum rotations.
Argentina Agriculture Market Competitive Landscape
Premium-margin players sit above commodity-margin players across origination network density and port terminal control. The market structure consolidates around three to four dominant traders with integrated elevator systems, while mid-scale operators compete through cooperative aggregation platforms. Strategic archetypes include vertically integrated crushing-export houses, farmland management specialists with ethanol assets, and digital cooperative platforms enabling small-producer volume pooling. Dominant competitive moves center on supply chain documentation system upgrades for SENASA compliance and cooperative platform technology licensing.
Within the integrated crushing-export tier, Cargill Argentina S.A. and Bunge Argentina S.A. exemplify archetypes defined by grain elevator network scale and port terminal positioning. Adecoagro S.A. occupies a distinct position as a farmland management specialist with captive ethanol processing infrastructure. COFCO International Argentina S.A. represents the state-linked trading house archetype with origination capabilities across the Pampas. Los Grobo Agropecuaria S.A. anchors the cooperative-aggregation vector, enabling smaller producers to bypass trader oligopsony through collective volume pooling.
| Leading Market Players |
|---|
| Cargill Argentina S.A. |
| Bunge Argentina S.A. |
| COFCO International Argentina S.A. |
| Adecoagro S.A. |
| Los Grobo Agropecuaria S.A. |
| Aceitera General Deheza |
| Lartirigoyen |
| MSU Agro |
| LIPSA |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap cooperatives and sovereign-backed trading houses anchor origination pricing discipline across the Pampas, linking elevator consolidation to farmgate premium capture. Their capital structures buffer working capital cycles against Central Bank repatriation delays, compressing price volatility transmission to smaller producers.
Pricing Analysis
Commodity spot pricing with contract-based long-term offtake overlays dominates Argentine grain transactions, with SENASA-certified traceability commanding premium-mid-economy pricing differentiation. Price differentiation hinges on EU deforestation regulation compliance grade and volume scale at Rosario terminal intake. Pricing pressure stems from urea and diammonium phosphate input cost swings tied to natural gas feedstock volatility. Smallholder cooperatives exhibit highest price sensitivity due to working capital constraints, while integrated crushing-export houses absorb margin compression through biodiesel mandate arbitrage.
Supply Chain Analysis
Freight cost concentration at the Rosario-San Lorenzo corridor elevates logistics economics above farmgate pricing in total delivered cost structures. Supply concentrates in Argentina, Brazil, and Paraguay as the MERCOSUR grain belt, with crushing capacity expansion in São Paulo pulling Argentine soybean protein across simplified sanitary protocols. Raw material dependencies center on glyphosate formulations, certified seed multiplication, and phosphate fertilizer imports. Single-source vulnerability at Paraná River deep-water terminals exposes export flows to weather and labor stoppage risk. Distribution runs through wholesale trader networks with cooperative aggregation platforms gaining volume share via digital silo receipt tokenization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in SENASA-compliant traceability premiums and cooperative platform technology licensing, with cost compression in input procurement digitization enabling tier upgrade capture.
For Market Incumbents: To counter cooperative aggregation platforms eroding origination share, deepen elevator network density in Córdoba province feed mill corridors and accelerate blockchain-enabled field activity record integration for EU deforestation regulation compliance windows. Certification investment in organic transition protocols unlocks quota-constrained premium access. For New Entrants and Emerging Players: Begin with northwest region irrigation infrastructure in Santiago del Estero and Tucumán provinces, where SENASA inspection queue congestion remains lowest. Specialty crop segments with direct-to-processor contracting bypass Rosario terminal concentration. Digital farm management software interoperability with SENASA's electronic phytosanitary certificate platform constitutes the critical go-to-market wedge. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale operators lacking integrated crushing or ethanol processing assets, presenting consolidation targets for backward integration plays. Long-term viability frames around biodiesel mandate durability and MERCOSUR sanitary protocol expansion. Watch Central Bank foreign exchange regulation liberalization as the inflection signal for working capital cycle normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Integration | SENASA electronic phytosanitary compliance satisfies EU deforestation regulation documentation requirements. |
| Northwest Irrigation Expansion | Santiago del Estero center-pivot development unlocks specialty crop production with lower inspection congestion. |
| Cooperative Platform Licensing | Digital silo receipt tokenization enables small-producer volume pooling against trader oligopsony. |
| Organic Certification Transition | Three-year protocol completion captures EU organic import quota premiums. |
| Crushing-Export Vertical Coordination | Integrated elevator-to-terminal grain flow secures biodiesel mandate margin arbitrage. |
Research Methodology
Coverage spans Argentina, Brazil, and Paraguay, with primary inputs from each MERCOSUR member state combining interviews with grain elevator operations managers, SENASA regulatory affairs officers, cooperative procurement directors, and Brazilian food processor supply chain leads. Secondary validation draws from SENASA export certification databases, Central Bank of Argentina foreign exchange regulation circulars, and MERCOSUR sanitary protocol amendments. Bottom-up origination volume modeling triangulates against top-down sectoral GDP contribution estimates.
Rate-of-change decomposition isolates area expansion, yield improvement, and price trajectory drivers across the analysis window. Segmentation dimensions span product type, end-use industry, distribution channel, and packaging format, with provincial regulatory cluster and SENASA compliance tier as Argentina-specific overlays. CAGRs derive from trend extrapolation of planted area, crushing capacity utilization, and export parity spreads. Biodiesel blend mandate revisions and EU deforestation regulation enforcement timelines constitute key forecast sensitivity inputs.
Caveats apply where Central Bank foreign exchange regulation shifts or SENASA phytosanitary protocol modifications could materially shift the outlook. Forecasts reflect assumptions around MERCOSUR trade integration continuity and EU market access durability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Japan Compound Feed Market
Agriculture and Agri Products
Tissue Cultured Date Palm Market
Agriculture and Agri Products
Cashew Market
Agriculture and Agri Products
Cambodia Agriculture Market
Agriculture and Agri Products
Organic Farming Market
Agriculture and Agri Products
Corn Gluten Feed Concentrates Market
Agriculture and Agri Products
Asia Pacific Poultry Feed Market
Agriculture and Agri Products
Ethiopia Agriculture Sector Market
Agriculture and Agri Products
Faba Beans Flour Market
Agriculture and Agri Products
Philippines Feed Industry Market
Agriculture and Agri Products
Genetically Modified Feed Market
Agriculture and Agri Products
Poultry Processing Product Market
Agriculture and Agri Products
Taro Market
Agriculture and Agri Products
Asia-Pacific Alfalfa Market
Agriculture and Agri Products
Asia-Pacific Animal Protein Market
Agriculture and Agri Products
Australia Animal Protein Market