
 Tunisia Agriculture Market | 2026-2036
Tunisia Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Tunisia Agriculture Market Insights
Food processing demand is rebalancing toward higher-value crop derivatives as export-oriented buyers tighten quality specifications. ECOFEED leverages backward integration into feedstock cultivation to secure raw material consistency. CAPRIGEN anchors its position through specialized dairy genetics services that support herd improvement programs. Groupe Alfa dominates industrial tomato processing with captive sourcing from contracted growers in the Cap Bon peninsula.
Tunisia agriculture encompasses crop cultivation, livestock management, and agro-industrial processing across rain-fed and irrigated systems, with olive orchards covering approximately one-third of arable land and serving as the dominant perennial crop. The sector functions as both a domestic food security pillar and a foreign exchange generator through olive oil, dates, and citrus exports. Cereals occupy the largest planted area but face structural margin pressure from import dependency and climatic variability. Olives command premium export pricing and concentrate value-added processing investment. Distribution through wholesale markets retains dominance for fresh produce, while retail chains and online platforms capture expanding packaged goods volumes.
Tunisia's Ministry of Agriculture enforces phytosanitary certification and geographic indication protections that shape export market access, particularly for olive oil destined to EU buyers under preferential trade arrangements. The national quality regulator applies CODEX-aligned standards for processed agricultural exports, while the central bank's trade finance facilities influence working capital availability across seasonal procurement cycles. Stakeholders must monitor water allocation policy shifts under the national drought response framework and assess irrigation infrastructure investment timelines against crop expansion plans.
Market Dynamics
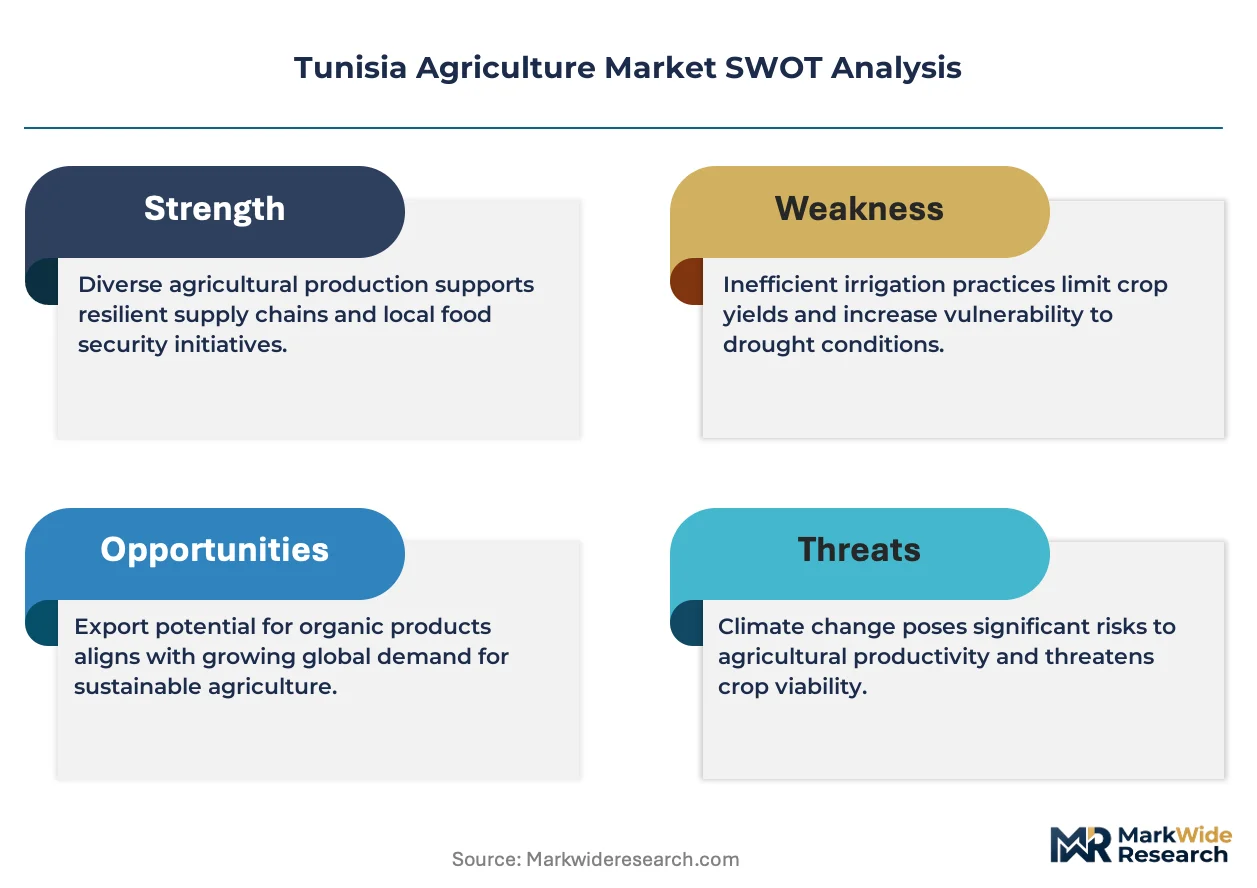
Water scarcity and the national drought response framework are forcing a structural pivot from rain-fed cereals to drip-irrigated high-value crops across Tunisia's coastal agricultural belt. This reallocation of productive capacity is compressing traditional farming systems while concentrating investment in precision irrigation infrastructure.
Growth Catalysts
- EU preferential trade arrangements:Duty-free access for Tunisian olive oil under the Association Agreement is pulling export-oriented cultivation toward certified organic orchards in the Sahel corridor.
- Drip irrigation technology:Expanded adoption of subsurface drip systems is lifting water-use efficiency in tomato and pepper cultivation across Cap Bon peninsula contract farms.
- Food processing buyers:Export-oriented date derivative and olive oil processors are tightening quality specifications that reward backward integration into controlled cultivation.
Market Restraints
- Cereal import dependency:Structural deficit in domestic wheat production ties farm-gate margins to Black Sea supply volatility and foreign exchange fluctuations.
- Phytosanitary certification friction:CODEX-aligned standards enforced by the national quality regulator create documentation bottlenecks for smallholder exporters targeting EU retail channels.
- Groundwater depletion:Over-extraction in the Jeffara aquifer is accelerating salinization that degrades citrus rootstock viability in southeastern governorates.
Strategic Opportunities
- Geographic indication expansion:Tunisia's Ministry of Agriculture is extending protected designation protocols beyond olive oil into date varieties from Kebili and Deglet Nour sub-regions.
- Retail chain procurement:Modern grocery formats in Greater Tunis and Sfax are creating dedicated shelf space for packaged organic produce that bypasses traditional wholesale markets.
- Climate-smart agriculture incentives:National agricultural modernization program subsidies for solar-powered pumping are reducing energy costs for isolated farms in Kairouan and Sidi Bouzid.
Industry Challenges
- Agronomic technician shortage:Limited training capacity in precision irrigation system design is slowing deployment timelines for commercial expansion projects.
- Certification compliance costs:Smallholder aggregation into export-compliant lots requires traceability infrastructure that strains working capital during seasonal procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tunisia Agriculture Market |
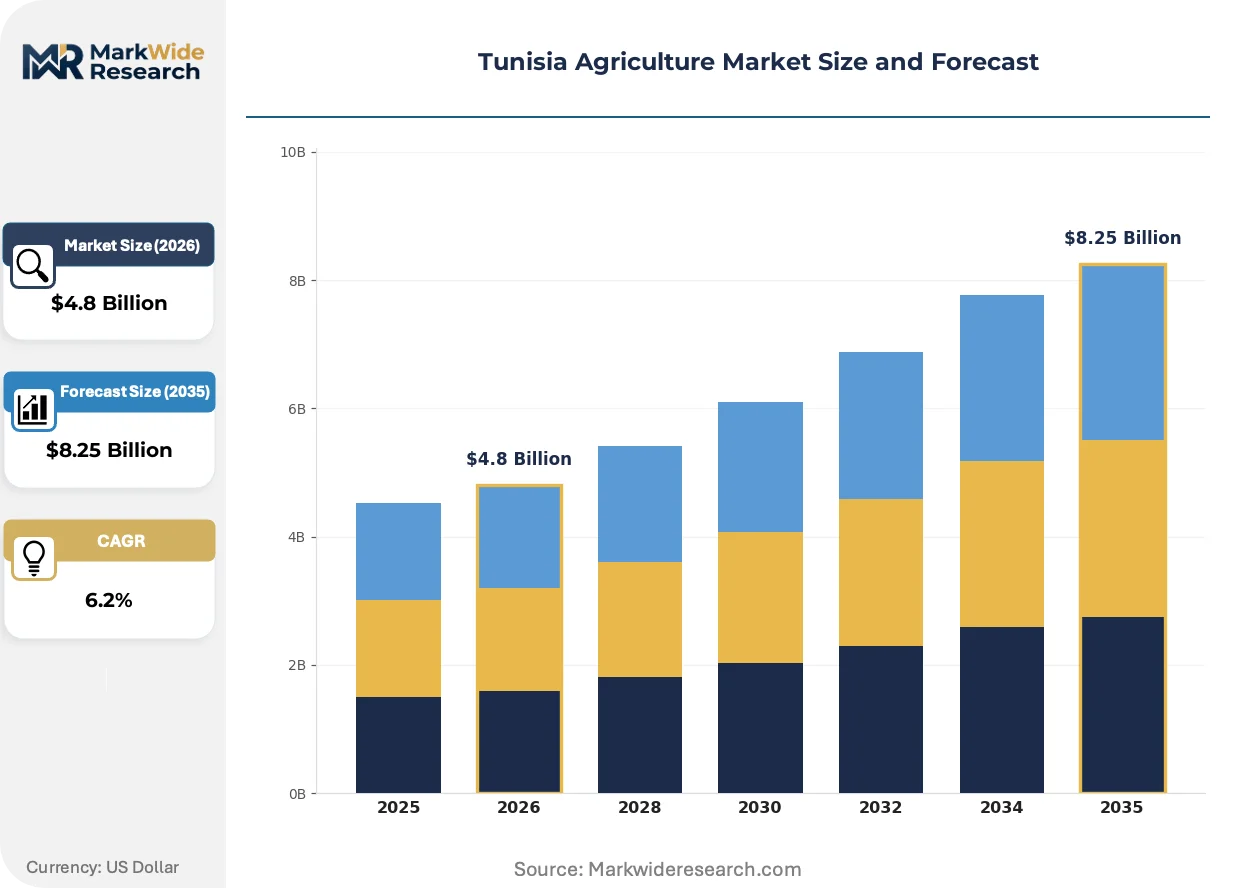
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereals, Fruits, Vegetables, Olives End Use Industry: Food Processing, Export, Local Consumption, Biofuels Distribution Channel: Direct Sales, Wholesale Markets, Retail Chains, Online Platforms Packaging Type: Bags, Boxes, Bulk Containers, Bottles |
| Companies Covered | Esca'Rome Holding Company, ECOFEED, Dooda, Grown in Town, INSTAWARE, TerraSens, CAPRIGEN, Emballage Creation Tunisie, Groupe Alfa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tunisia Agriculture Market Trends and Innovations
Digital agriculture platforms and climate-adaptive cultivation systems are restructuring how Tunisian farms manage water, labor, and market access. These innovations are compressing traditional extension service models while opening direct channels between producers and export buyers.
Subsurface drip irrigation combined with soil moisture sensor networks is consolidating farm-level water management across the Sahel coastal corridor. Large tomato and pepper contract growers in Cap Bon are deploying these integrated systems to meet processor volume commitments under tighter delivery windows. The technology is consolidating control over irrigation scheduling away from traditional cooperative-managed distribution toward processor-directed precision agriculture protocols.
Tunisia's national drought response framework is mandating volumetric water allocation permits that restrict new well drilling in over-extracted basins. The policy is forcing citrus and stone fruit operations in Nabeul and Zaghouan governorates to retrofit existing flood irrigation to micro-sprinkler systems or abandon marginal hectares. Processors dependent on these supply basins are responding by consolidating sourcing contracts onto farms with verified renewable water access.
Export buyers are unbundling after-sales technical support from input supply contracts and purchasing agronomic advisory as standalone subscription services. Large olive oil bottlers targeting EU retail channels are deploying their own field teams to monitor pesticide application records across contracted orchards. This disintermediation of traditional cooperative extension is most visible in Sfax and Sousse governorates where processor-producer vertical coordination is deepest.
Tunisia Agriculture Market Segmentation
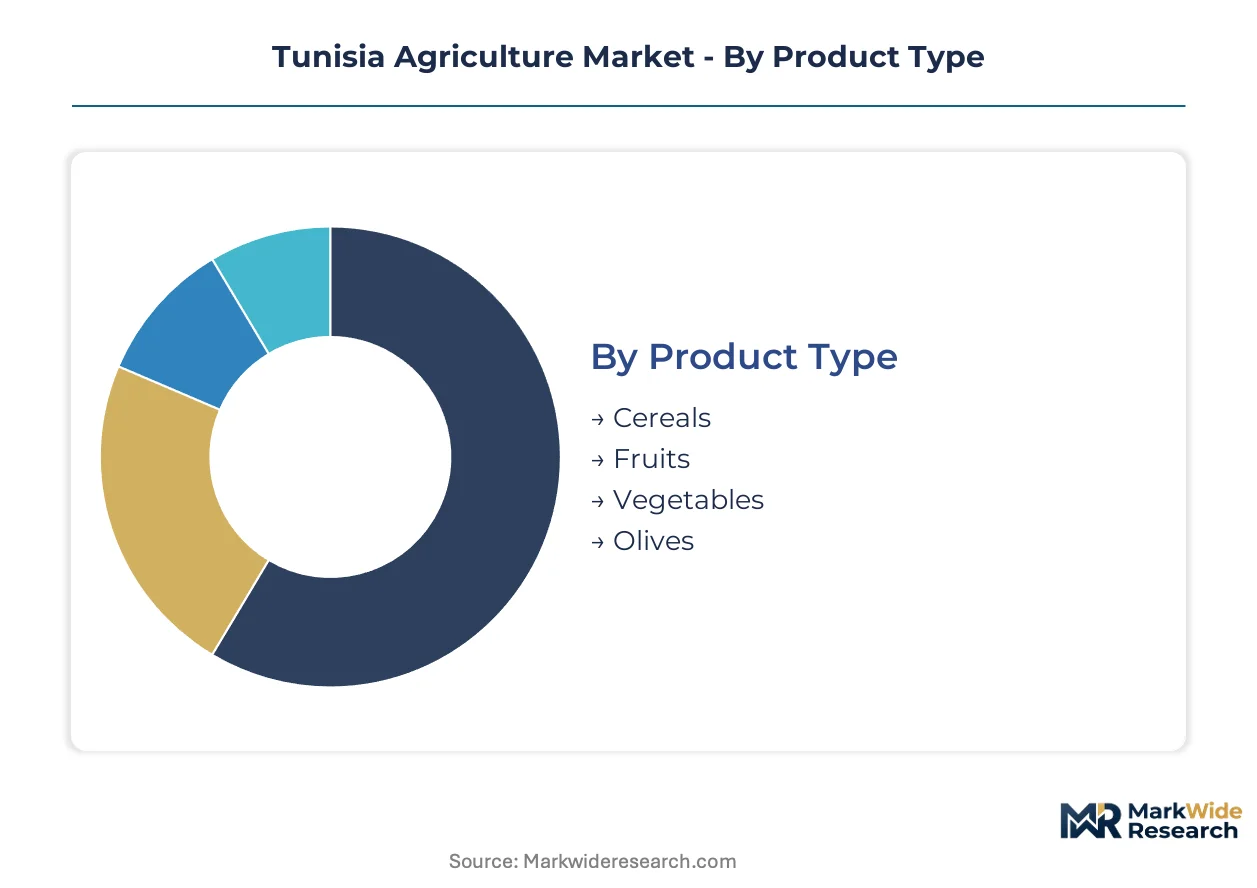
Tunisia's agricultural output fragments across distinct commercial pathways where product perishability, export certification requirements, and buyer consolidation patterns reshape how each segment captures value. Understanding these divisions clarifies where infrastructure investment and regulatory compliance concentrate.
Product Type:
Standalone commodity crops operate through spot-market mechanisms while integrated orchard systems embed directly into processor supply chains with multi-year contracting.
- Olives:Perennial orchards covering roughly one-third of national arable land deliver fruit for both table olive and virgin oil extraction. Demand concentrates in the Sahel coastal corridor from Sousse to Sfax, where EU-bound exporters under the Association Agreement drive certified organic cultivation.
- Cereals:Rain-fed wheat and barley dominate planted area but face compressed margins from import dependency and climatic variability. The sector functions primarily for domestic food security rather than export revenue generation.
- Fruits:Citrus from Cap Bon and dates from Kebili serve dual markets—fresh export through wholesale channels and derivative processing for industrial buyers.
- Vegetables:Tomato and pepper contract farming under drip irrigation supplies industrial processors, with volume commitments tightening delivery windows.
Olives lead volumes today; vegetables are gaining share fastest.
End Use Industry:
Cost-tier stratification separates commodity-grade flows from premium-certified channels, with traceability infrastructure determining access to upper price bands.
- Food Processing:Industrial buyers of olive oil, date derivatives, and tomato paste enforce backward integration into controlled cultivation to secure raw material consistency. CODEX-aligned standards from the national quality regulator shape documentation requirements.
- Export:EU retail channels demand phytosanitary certification and geographic indication protections enforced by the Ministry of Agriculture. Duty-free access under preferential trade arrangements pulls cultivation toward certified orchards.
- Local Consumption:Wholesale market distribution retains dominance for fresh produce serving domestic households and food service operators.
- Biofuels:Emerging demand for agricultural feedstock in renewable energy applications remains nascent relative to food and export channels.
Food processing leads volumes today; export is gaining share fastest.
Distribution Channel:
Customer-type concentration distinguishes traditional cooperative-managed flows from processor-directed procurement and modern retail formats.
- Wholesale Markets:Centralized fresh produce trading in Tunis, Sfax, and Sousse handles the majority of domestic fruit and vegetable volumes. These markets retain dominance despite modern format expansion.
- Direct Sales:Large processors contract dedicated acreage for tomato, pepper, and olive supply, bypassing spot-market intermediaries.
- Retail Chains:Modern grocery formats in Greater Tunis and Sfax create dedicated shelf space for packaged organic produce with traceability documentation.
- Online Platforms:Digital channels capture expanding packaged goods volumes, particularly for premium olive oil and date products targeting urban consumers.
Wholesale markets lead volumes today; retail chains are climbing the fastest.
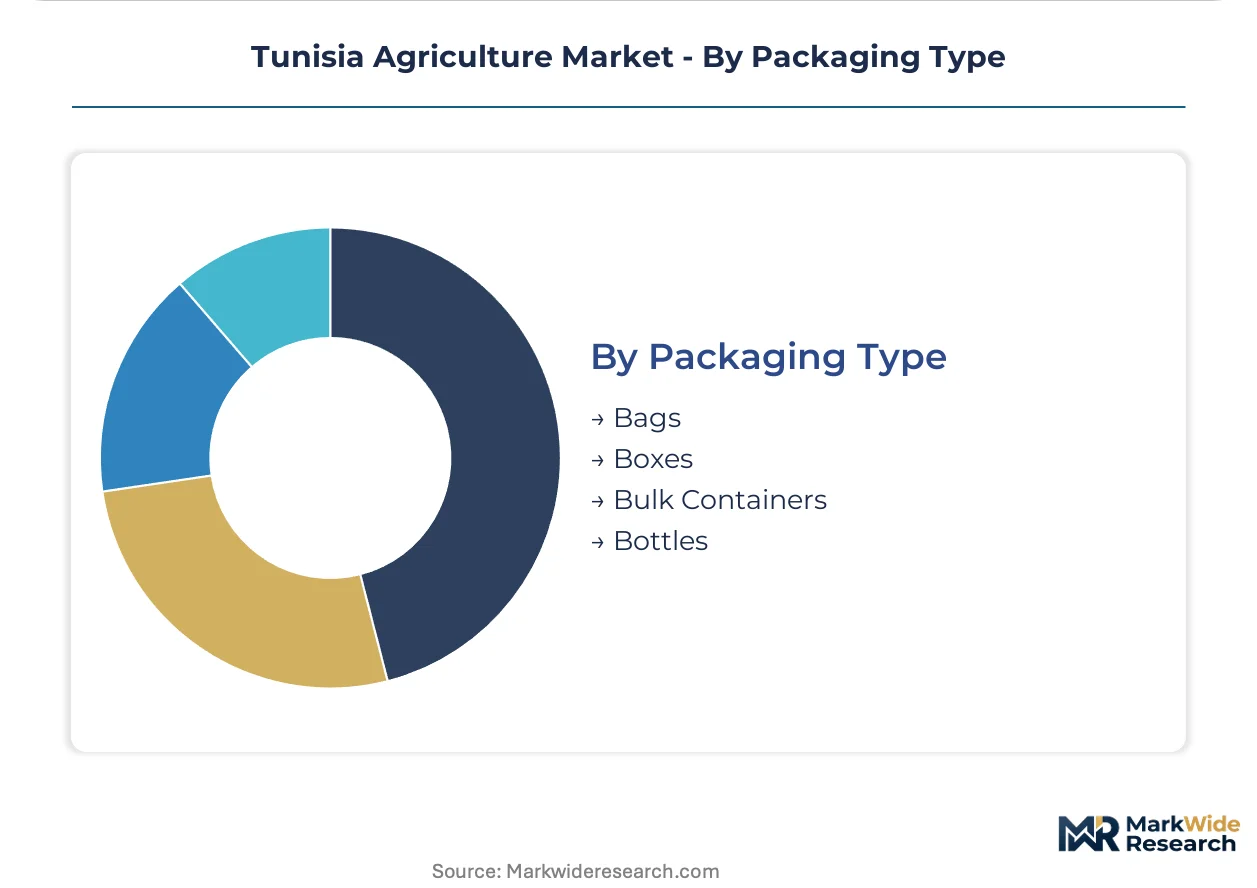
Packaging Type:
Application-specific requirements drive format selection, with export-grade specifications diverging sharply from bulk commodity handling.
- Bottles:Dark glass containers for virgin olive oil destined to EU retail channels require compliance with packaging material regulations and labeling standards.
- Bulk Containers:Stainless steel tanks and flexitanks handle industrial-scale oil and date derivative shipments to food processors.
- Bags:Woven polypropylene sacks serve cereal and feed grain distribution through wholesale channels.
- Boxes:Corrugated packaging for fresh citrus and table grapes balances ventilation with protection for export shipment.
Bulk containers lead volumes today; bottles are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting agricultural investment toward governorates with streamlined water permitting and subsidized drip irrigation infrastructure, compressing activity in rain-fed interior zones where compliance costs for drought-response protocols run higher.
Sahel Coastal Corridor
EU-bound olive oil exporters under the Association Agreement are clustering certified organic orchards between Sousse and Sfax. The Ministry of Agriculture's geographic indication protections for Chemlali and Chetoui varieties are pulling cultivation toward documented traceability systems. Processing capacity concentrates in Sfax port zones where bulk flexitank loading meets tighter delivery windows.
Cap Bon Peninsula
Industrial tomato and pepper contract farming is displacing traditional citrus in Nabeul governorate as processors enforce backward integration into drip-irrigated supply basins. The national agricultural modernization program subsidizes subsurface irrigation retrofits that reduce water-use intensity. Groupe Alfa's contracted grower networks anchor processing volume commitments here.
Kairouan and Sidi Bouzid
Solar-powered pumping subsidies under climate-smart agriculture incentives are reducing energy costs for isolated cereal and livestock operations transitioning to fodder crop cultivation. The central bank's seasonal trade finance facilities influence working capital availability during procurement windows. CAPRIGEN's dairy genetics services support herd improvement programs across these central governorates.
Kebili and Southern Oases
Deglet Nour date export certification is concentrating in Kebili sub-regions where protected designation protocols are extending beyond olive oil into date varieties. Phytosanitary documentation bottlenecks for smallholder exporters are forcing aggregation into processor-managed traceability systems. ECOFEED leverages feedstock cultivation integration to secure raw material consistency here.
Greater Tunis and Sfax Metro
Modern grocery retail formats are creating dedicated shelf space for packaged organic produce that bypasses traditional wholesale markets. Online platform distribution captures expanding premium olive oil and date product volumes targeting urban consumers. INSTAWARE and TerraSens anchor digital agriculture platform deployment serving these metropolitan demand centers.
Tunisia Agriculture Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with export-oriented processors commanding tighter vertical coordination than domestic wholesale suppliers. The vendor base clusters around three strategic archetypes: genetics and advisory specialists, integrated processor-grower networks, and digital agriculture platform operators. Competitive moves center on backward integration into controlled cultivation and multi-year contracting that locks in processor-directed precision agriculture protocols.
Among Tunisia-based agricultural enterprises, ECOFEED exemplifies the feedstock-integrated processor archetype through its backward integration model, while CAPRIGEN occupies a position within the specialized genetics and herd improvement tier. Groupe Alfa anchors the industrial tomato processing segment with its contracted grower network structure. These three represent distinct competitive positioning vectors that other market participants are emulating or avoiding based on capital intensity and regulatory compliance capacity.
| Leading Market Players |
|---|
| Esca'Rome Holding Company |
| ECOFEED |
| Dooda |
| Grown in Town |
| INSTAWARE |
| TerraSens |
| CAPRIGEN |
| Emballage Creation Tunisie |
| Groupe Alfa |
| Others |
Pricing and Supply Chain Analysis
EU-bound olive oil exporters under the Association Agreement concentrate procurement power across the Sahel coastal corridor, compressing farm-gate margins into certified organic premiums that reward documented traceability. This buyer consolidation enforces backward integration into controlled cultivation, restructuring how value distributes across processor-directed supply chains versus spot-market intermediaries.
Pricing Analysis
Processor-direct contracting eliminates distributor margin layers that traditionally absorbed 12-18 percent in cooperative-managed channels. Price differentiation hinges on organic certification tier and volume scale, with Chemlali and Chetoui geographic indication premiums widening spreads between certified and conventional lots. Cost compression in rain-fed cereal tiers is intensifying because import parity pricing ties domestic wheat to Black Sea supply volatility. Smallholder aggregators face the sharpest price sensitivity, while integrated processor-grower networks with renewable water access command negotiating leverage.
Supply Chain Analysis
Single-source vulnerability sits with groundwater-dependent citrus operations in Nabeul and Zaghouan governorates where Jeffara aquifer depletion accelerates salinization. Supply draws from three concentrated basins: Cap Bon peninsula for contract vegetables, Sahel corridor for certified olives, and Kebili oases for Deglet Nour dates. Regulatory restriction risk looms as volumetric water allocation permits tighten under the national drought response framework. Distribution runs through Sfax port zones where bulk flexitank loading consolidates export volumes, bypassing traditional wholesale market intermediaries for processor-direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Tunisia agriculture market functions as a stable compounder anchored by EU preferential trade arrangements that lock in duty-free access for certified olive oil exports. This structural demand driver insulates premium-tier producers from commodity cycle volatility while concentrating investment in drip-irrigated high-value crop systems.
For Market Incumbents: Deploy precision irrigation infrastructure retrofits to defend processor volume commitments as volumetric water permits tighten. ECOFEED's backward integration model demonstrates how captive feedstock cultivation secures raw material consistency against smallholder aggregation bottlenecks. CAPRIGEN's specialized dairy genetics services illustrate defensive positioning through technical advisory lock-in that deepens producer dependency. For New Entrants and Emerging Players: Digital agriculture platforms offer the most penetrable entry vector, with INSTAWARE and TerraSens establishing deployment templates in Greater Tunis and Sfax metro zones. White-space concentrates in solar-powered pumping advisory for isolated Kairouan and Sidi Bouzid operations transitioning to fodder crops. A subscription-based agronomic monitoring service targeting processor-contracted orchards bypasses capital-intensive cultivation assets entirely. For Investors and Strategic Acquirers: Food processing conglomerates with EU retail channel access are the most active acquirer in this space, seeking traceability-compliant cultivation assets. Long-term viability centers on water-rights-secured land positions with verified renewable access. The signal to monitor is Ministry of Agriculture geographic indication expansion beyond olive oil into date varieties, which would revalue Kebili sub-region assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled Cultivation | ECOFEED's feedstock cultivation model secures processor supply consistency against smallholder aggregation friction. |
| Geographic Indication Certification Investment | Ministry of Agriculture protections for Chemlali and Chetoui varieties command EU retail channel premiums. |
| Precision Irrigation Infrastructure Deployment | Subsurface drip retrofits in Cap Bon meet processor volume commitments under tighter water allocation permits. |
| Dairy Genetics Service Expansion | CAPRIGEN's herd improvement programs lock in producer dependency across Kairouan and Sidi Bouzid governorates. |
| Digital Agriculture Platform Scaling | INSTAWARE and TerraSens deployment in metropolitan demand centers compress traditional extension service models. |
Research Methodology
Bottom-up farm-gate production modeling reconciled against top-down processor intake tracking forms the analytical core of this study. Primary interviews with olive oil export managers, drip irrigation system installers, cooperative aggregation officers, and Ministry of Agriculture certification auditors combined with secondary validation from customs export records, central bank trade finance disclosures, and national agricultural modernization program subsidy allocations. This dual approach triangulates volume estimates against documented procurement flows.
Historical trendline analysis of certified organic orchard expansion and drip irrigation adoption rates established baseline growth parameters across the projection horizon. Segmentation modeling incorporated product type, end-use industry, distribution channel, and packaging format dimensions, with water access tier and certification status as industry-specific forecast inputs. CAGRs were derived from regression analysis of planted area shifts and processor capacity expansion timelines.
The model assumes a particular technology adoption path for subsurface drip irrigation; alternative pathways for solar-powered pumping retrofits would alter the outlook. Forecasts reflect assumptions about EU trade arrangement continuity and drought response framework enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Saudi Arabia Eggs Market
Agriculture and Agri Products
Canada Backyard Poultry Feed Market
Agriculture and Agri Products
Japan Compound Feed Market
Agriculture and Agri Products
Animal Feed and Feed Additives Market
Agriculture and Agri Products
North America Shiitake Mushroom Market
Agriculture and Agri Products
Asia-Pacific Compound Feed Market
Agriculture and Agri Products
Compound Feed Market
Agriculture and Agri Products
Marine Algae Market
Agriculture and Agri Products
India Palm Oil Market
Agriculture and Agri Products
Asia Pacific Animal Feed Market
Agriculture and Agri Products
Africa Compound Feed Market
Agriculture and Agri Products
Asia-Pacific Swine Feed Market
Agriculture and Agri Products
South Africa Compound Feed Market
Agriculture and Agri Products
North America Swine Feed Premix Market
Agriculture and Agri Products
Middle East and Africa Bonsai Market
Agriculture and Agri Products
Seaweed Market