
 Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems (RAS) Market | 2026-2036
Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems (RAS) Market Size, Share, and Industry Trends Forecast 2026-2036
Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems (RAS) Market Insights
Direct equipment sales to commercial farms is fragmenting as leasing models and service-based contracts gain traction among capital-constrained operators. Pentair leverages its fluid treatment portfolio to anchor recurring revenue streams in North American salmon RAS projects. Veolia competes through integrated water-energy contracts that bundle biological filtration with energy recovery. AKVA Group specializes in feeding and farm infrastructure systems that extend into water treatment modules for Atlantic salmon producers.
Aquaculture water treatment systems and recirculating aquaculture systems (RAS) comprise closed-loop configurations that recycle over 90 percent of culture water through mechanical solids removal, biofiltration for ammonia conversion, and gas exchange for oxygen replenishment and carbon dioxide stripping. These systems serve commercial farms seeking to decouple production from coastal water quality constraints and seasonal temperature fluctuations. Recirculating systems dominate capital deployment due to their superior water reuse rates and biosecurity advantages over flow-through alternatives. Biological filtration occupies the largest share of operational expenditure as nitrifying biofilm maintenance determines system carrying capacity and fish health outcomes. Commercial farms represent the primary end user segment, with research institutions driving pilot-scale demand for species diversification trials.
EPA discharge permits under the Clean Water Act shape system design standards for US inland aquaculture facilities, while the EU Water Framework Directive and F-Gas Regulation constrain cooling and aeration equipment choices in European installations. Norway's national polluter-pays framework for salmon aquaculture accelerates land-based RAS investment as coastal license access tightens. Stakeholders must monitor how evolving effluent nutrient limits in Denmark and the Netherlands redirect technology procurement toward integrated multi-trophic systems that capture waste streams for secondary biomass production.
Market Dynamics
The EU Green Deal's tightening discharge limits for coastal aquaculture are accelerating capital migration from open-net pens to land-based closed-containment facilities, restructuring equipment procurement priorities across Atlantic salmon value chains.
Growth Catalysts
- Norway's polluter-pays framework:Coastal license scarcity for traditional salmon farming redirects investment toward inland RAS installations with zero direct discharge.
- Biological filtration advancement:Enhanced nitrifying biofilm management protocols extend system carrying capacity and reduce mortality events in high-density culture.
- Denmark and Netherlands effluent rules:Nutrient limit tightening stimulates demand for integrated multi-trophic aquaculture systems that convert waste streams into secondary biomass.
Market Restraints
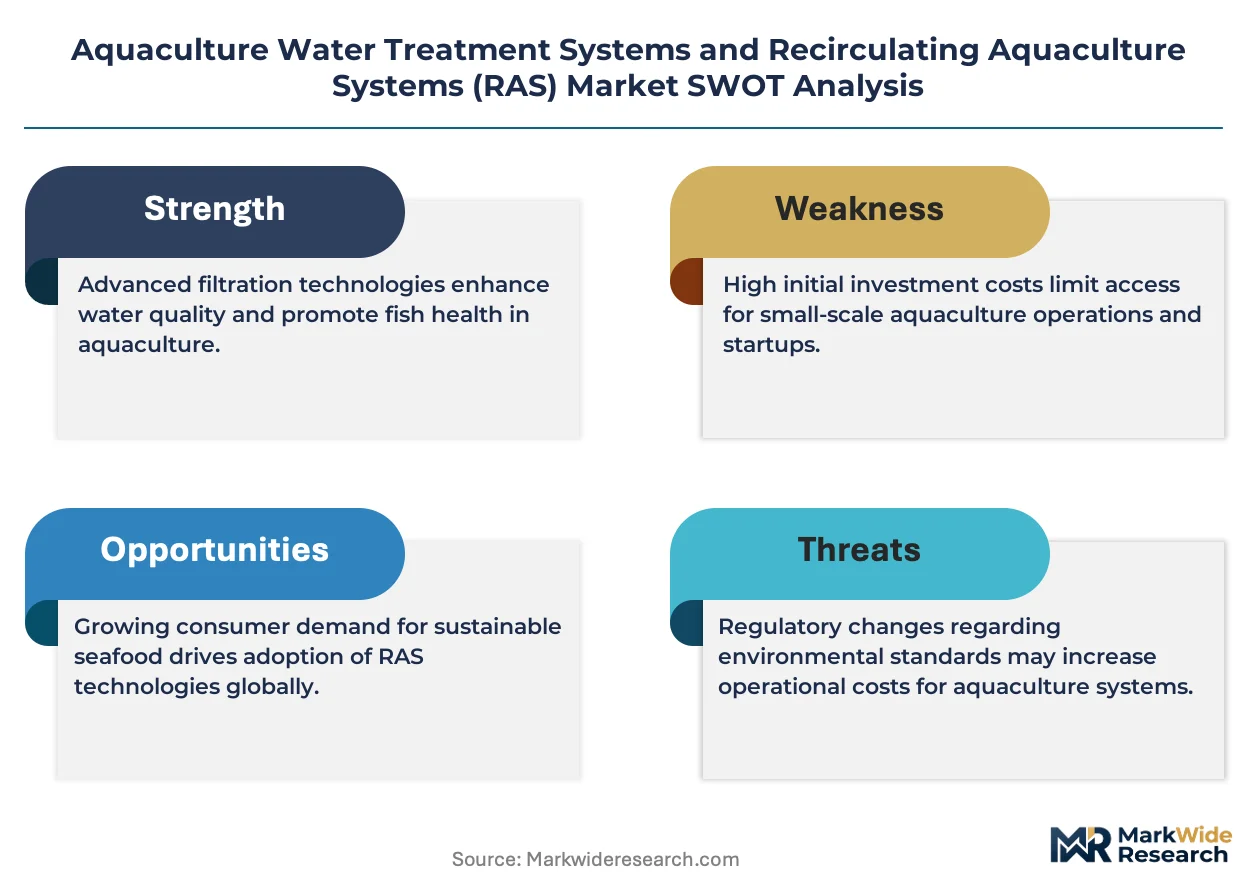
- Energy cost volatility:Aeration and temperature control systems account for disproportionate operational expenditure in temperate-zone RAS facilities.
- Component supply concentration:Specialized biofilter media and high-efficiency oxygen transfer equipment originate from limited European and North American manufacturing bases.
- Technical scale thresholds:Minimum viable unit economics for Atlantic salmon RAS require production volumes that exceed most regional market absorption capacity.
Strategic Opportunities
- United States inland expansion:EPA discharge permit requirements under the Clean Water Act create compliant-site scarcity that rewards early-mover RAS developers.
- Leasing model penetration:Capital-constrained operators in China and Southeast Asia are adopting service-based contracts that bundle equipment with biological support.
- Species diversification trials:Research institutions drive pilot-scale demand for water treatment systems adapted to yellowtail, kingfish, and grouper culture protocols.
Industry Challenges
- Biofilm management expertise:Shortage of technicians trained in nitrifying bacteria colony maintenance creates operational risk during system startup and shock events.
- Legacy flow-through integration:Existing coastal farms face complex retrofit economics when adapting partial recirculation to meet new discharge standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems (RAS) Market |
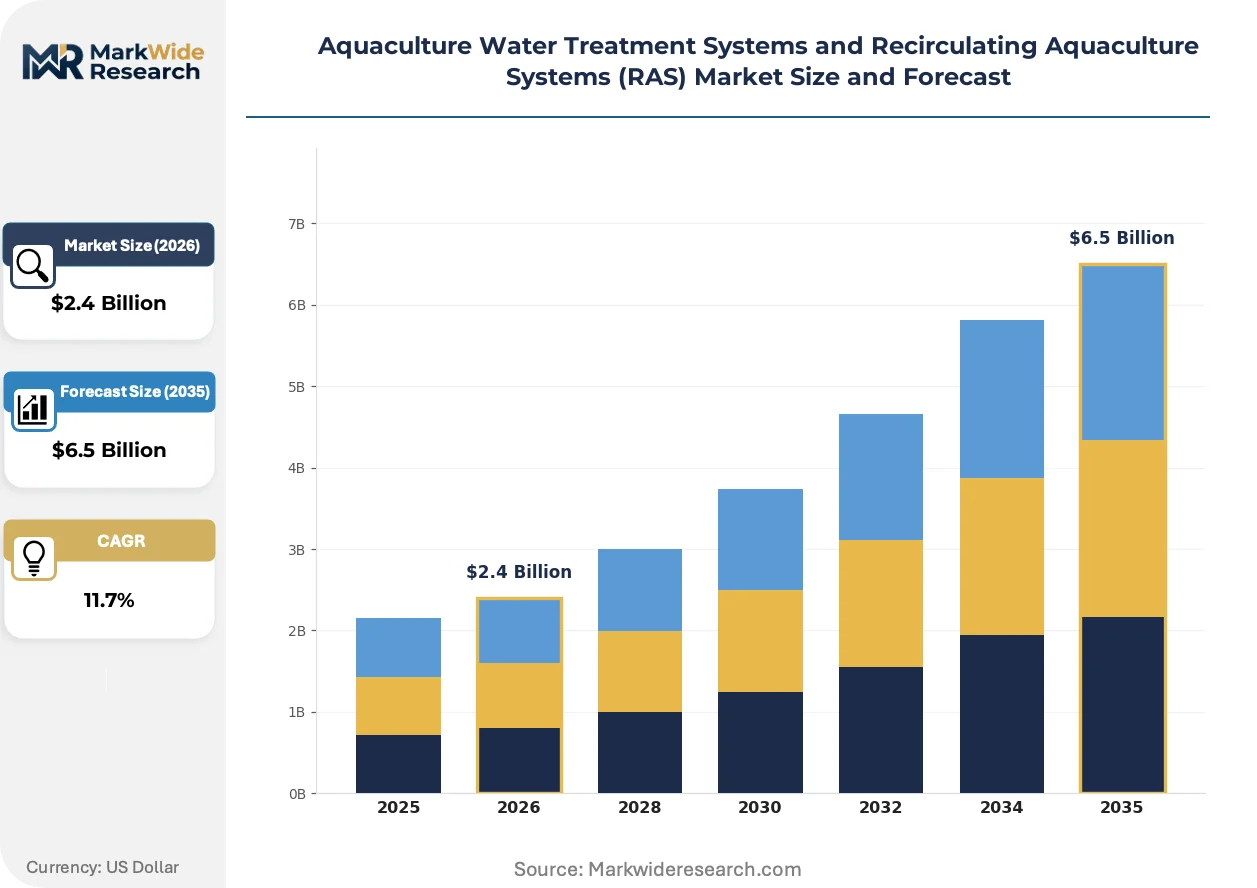
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Recirculating Systems, Flow-Through Systems, Integrated Systems, Multi-Trophic Systems Filtration Method: Mechanical Filtration, Biological Filtration, Chemical Filtration, UV Filtration Treatment Technology: Ozone Treatment, Reverse Osmosis, Membrane Filtration, Sedimentation End User: Commercial Farms, Research Institutions, Educational Organizations, Small-Scale Producers |
| Companies Covered | AKVA Group, Pentair, Veolia, Xylem, Skretting, AquaMaof, RADAQUA, Billund Aquaculture, PR Aqua, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems (RAS) Market Trends and Innovations
Real-time water quality monitoring and automated feedback loops are compressing response times to ammonia spikes and oxygen depletion events, shifting competitive advantage toward digitally integrated system architectures.
Sensor-integrated biofiltration control is digitizing ammonia conversion management in commercial Atlantic salmon RAS facilities. Norwegian and North American producers are deploying continuous dissolved oxygen and nitrite monitoring arrays that adjust backwash frequency and hydraulic retention time without human intervention. This capability is digitizing operational decision-making and reducing biological filtration failure rates.
The EU F-Gas Regulation constrains refrigerant choices for temperature control systems in European RAS installations. Equipment manufacturers are redesigning heat pump and chiller architectures to accommodate lower-global-warming-potential working fluids. Danish and Dutch salmon producers face accelerated equipment replacement cycles as legacy cooling systems phase out of compliance.
After-sales service unbundling is fragmenting traditional equipment supply relationships in the Chinese market. Domestic operators are purchasing core mechanical and biological filtration hardware while contracting specialized firms for biofilm seeding, startup support, and ongoing nitrification performance guarantees. This pattern concentrates in Shandong and Fujian provinces where rapid RAS deployment outpaces in-house technical capacity formation.
Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems (RAS) Market Segmentation
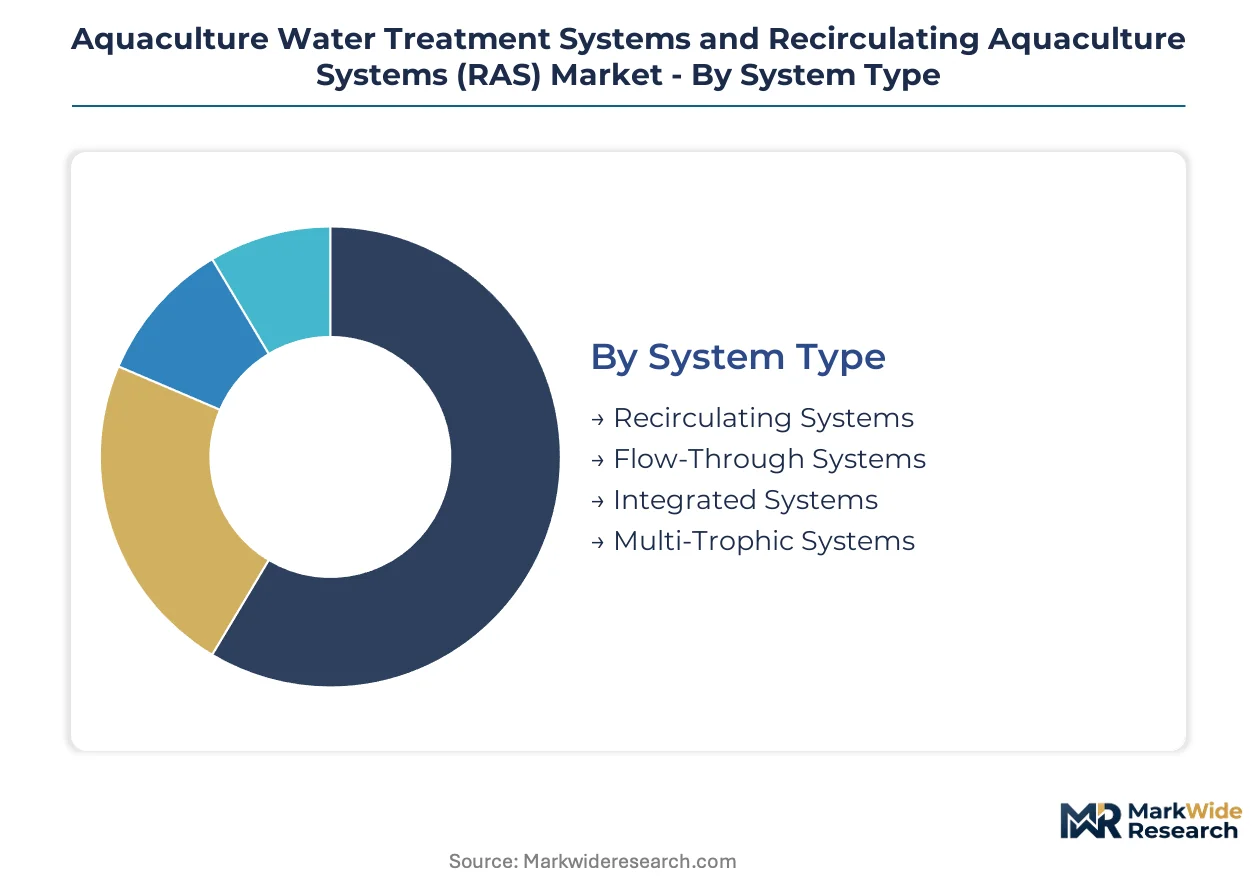
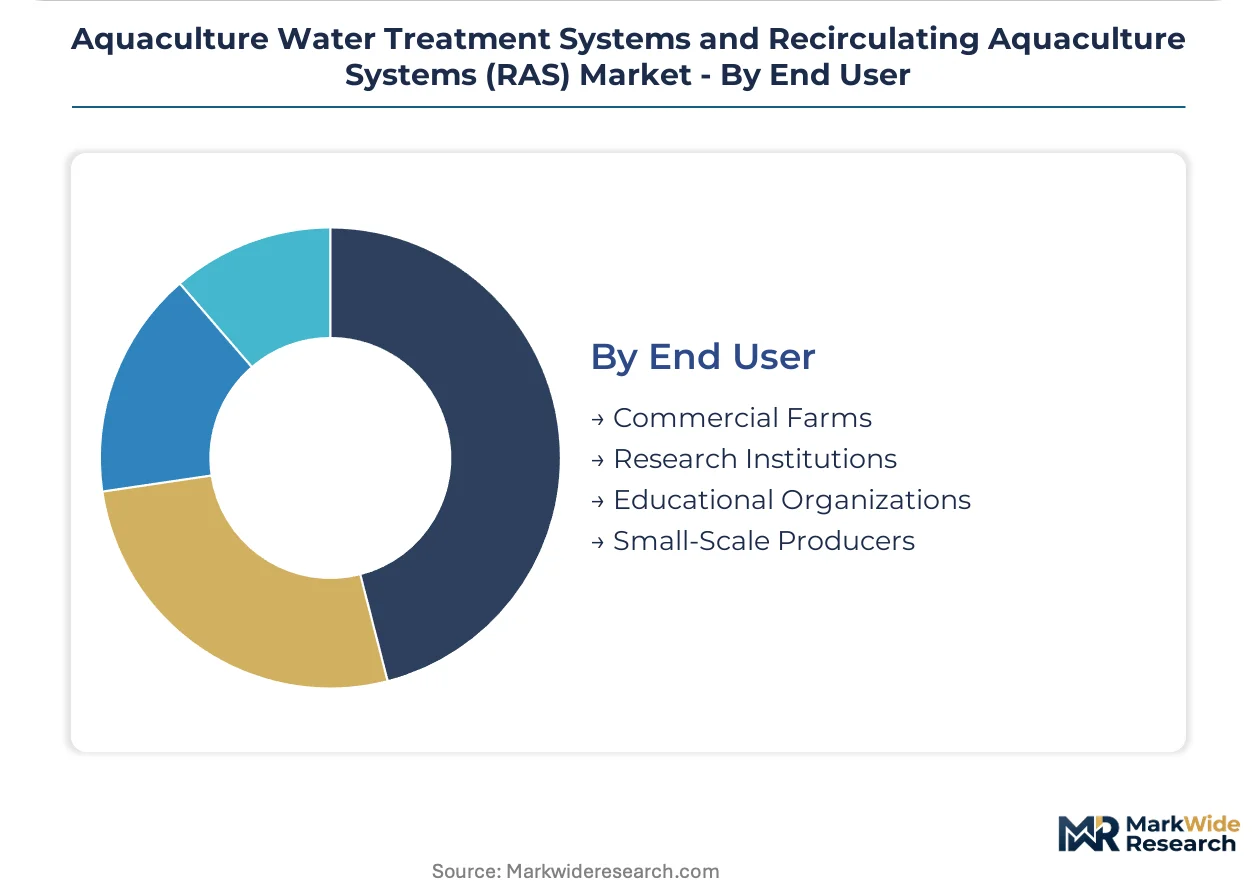
Segmentation in aquaculture water treatment reveals how capital allocation and regulatory pressure concentrate across system architectures and operational scales. Equipment suppliers calibrate their portfolios differently for high-volume Atlantic salmon producers versus pilot-scale research facilities.
System Type:
Mature configurations dominate commercial deployment while emerging hybrid architectures gain traction in constrained geographies.
- Recirculating Systems:Closed-loop configurations recycle over 90 percent of culture water through mechanical solids removal, biofiltration, and gas exchange. Norwegian land-based salmon producers deploy these systems to bypass coastal license scarcity under the national polluter-pays framework.
- Flow-Through Systems:Single-pass water architectures discharge directly to receiving waters after limited treatment. Denmark and Netherlands operators face accelerated retrofit pressure as EU Water Framework Directive nutrient limits tighten on effluent discharge.
- Integrated Systems:Hybrid designs combine partial recirculation with controlled discharge for legacy farm retrofits.
- Multi-Trophic Systems:Waste stream capture configurations convert effluent nutrients into secondary biomass production.
Recirculating Systems handle the majority of throughput; Multi-Trophic Systems are expanding most quickly on share.
Filtration Method:
Cost tier separation distinguishes capital-intensive biological infrastructure from operational expenditure-heavy mechanical alternatives.
- Mechanical Filtration:Solids removal through drum screens, sand filters, and microscreen architectures protects downstream biological components. US inland facilities under EPA Clean Water Act discharge permits prioritize robust mechanical stages to maintain permit compliance.
- Biological Filtration:Nitrifying biofilm colonies convert toxic ammonia to nitrate through fixed-film or suspended-growth reactors. Norwegian and North American Atlantic salmon RAS operators concentrate technical staffing here due to biofilm maintenance expertise scarcity.
- Chemical Filtration:Activated carbon and foam fractionation address dissolved organics and color.
- UV Filtration:Pathogen inactivation through ultraviolet irradiation supports biosecurity protocols.
Biological Filtration commands the largest operational expenditure allocation; UV Filtration is climbing the fastest on share.
Treatment Technology:
Application specificity drives technology selection between intensive species culture and water source conditioning.
- Ozone Treatment:Powerful oxidation reduces dissolved organics, color, and bacterial load while boosting oxygen saturation. Danish salmon producers face accelerated equipment replacement cycles as EU F-Gas Regulation constrains legacy cooling system refrigerants, redirecting capital toward ozone-integrated architectures.
- Reverse Osmosis:Membrane-based desalination and ion removal enables inland production of marine species in brackish water zones. Chinese operators in Shandong province deploy reverse osmosis for yellowtail and kingfish pilot trials.
- Membrane Filtration:Ultrafiltration and microfiltration separate fine solids and pathogens.
- Sedimentation:Gravity-based solids settling provides low-energy pre-treatment for high-load waste streams.
Ozone Treatment handles the majority of intensive culture throughput; Reverse Osmosis is gaining share fastest.
End User:
Customer type determines contract structure, with service-based models penetrating capital-constrained segments.
- Commercial Farms:Industrial-scale operators seeking biosecurity isolation and year-round production control. Norwegian and US salmon producers drive equipment procurement volume as coastal license access tightens and EPA discharge permit scarcity rewards compliant-site development.
- Research Institutions:Pilot-scale demand centers on species diversification trials for yellowtail, kingfish, and grouper protocols. Chinese and Southeast Asian leasing model penetration concentrates here as service-based contracts bundle equipment with biological support.
- Educational Organizations:Training and demonstration facilities require simplified operational interfaces.
- Small-Scale Producers:Regional operators in China and Southeast Asia adopt unbundled after-sales service arrangements.
Commercial Farms handle the majority of throughput; Research Institutions are the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian producers command pricing power through coastal license scarcity, while Chinese operators absorb cost pressure from rapid capacity scaling. This asymmetry redistributes equipment procurement budgets across Atlantic salmon and Asian diversified aquaculture value chains.
Norway
Land-based Atlantic salmon producers drive closed-containment investment as coastal license access tightens under the national polluter-pays framework. The EU Green Deal's discharge limit trajectory accelerates capital migration from open-net pens to inland RAS installations. Bergen and Trøndelag clusters concentrate engineering expertise for zero-direct-discharge system design.
United States
EPA discharge permit scarcity under the Clean Water Act rewards early-mover RAS developers with compliant inland sites. Maine and Washington State producers face intensifying regulatory scrutiny on effluent nutrient loading. Pacific Northwest engineering clusters specialize in salmonid temperature control and biosecurity isolation protocols.
China
Shandong and Fujian provinces dominate domestic RAS contract volume as yellowtail and kingfish pilot trials expand. The Ministry of Ecology and Environment tightens coastal aquaculture discharge standards, redirecting investment toward closed-loop configurations. Domestic operators adopt unbundled after-sales service arrangements as rapid deployment outpaces technical capacity formation.
Denmark
EU Water Framework Directive nutrient limits stimulate demand for integrated multi-trophic systems that convert waste streams into secondary biomass. Danish salmon producers face accelerated equipment replacement cycles as F-Gas Regulation constraints phase out legacy cooling system refrigerants. Jutland engineering clusters specialize in ozone-integrated heat pump architectures.
Netherlands
Effluent rule tightening redirects technology procurement toward waste-capture configurations for secondary production. Dutch producers concentrate pilot-scale deployment of hybrid recirculation systems that balance water reuse with controlled discharge. Zeeland and Noord-Brabant clusters develop integrated water-energy contracts bundling biological filtration with energy recovery.
Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems (RAS) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in biofilter media and oxygen transfer equipment. The vendor base separates between consolidated fluid treatment conglomerates and fragmented regional fabricators. Three archetypes dominate: full-system integrators, biological filtration specialists, and water-energy bundlers. Competitive moves concentrate on service-based contract penetration and geographic expansion through leasing models.
Among full-system integrators, AKVA Group exemplifies the infrastructure-to-treatment extension archetype, while Pentair occupies a position bridging fluid treatment portfolios with recurring revenue streams. Veolia anchors the water-energy bundler tier through integrated contracts. These three represent divergent strategic postures: equipment-centric platform building, component-to-system vertical extension, and service-based operational integration.
| Leading Market Players |
|---|
| AKVA Group |
| Pentair |
| Veolia |
| Xylem |
| Skretting |
| AquaMaof |
| RADAQUA |
| Billund Aquaculture |
| PR Aqua |
| Others |
Pricing and Supply Chain Analysis
Bergen's engineering cluster concentrates biofilter media and oxygen transfer equipment manufacturing, concentrating upstream pricing power among Norwegian and Danish component specialists who supply Atlantic salmon RAS developers worldwide. This geographic concentration enables configured-to-order premiums for zero-discharge system architectures while standard mechanical filtration hardware faces cost compression from Chinese fabricators.
Pricing Analysis
The customization-premium spread separates standard drum screen and sand filter configurations from engineered biological filtration systems with automated nitrification monitoring. Project-based contracting dominates, with price differentiation driven by biofilm management certification tiers and after-sales service bundling. Pricing pressure stems from Chinese domestic operators adopting unbundled service arrangements that fragment traditional equipment-plus-support packages. Research institutions exhibit highest price sensitivity due to capital constraints, while Norwegian land-based salmon producers absorb premiums for compliant-site zero-discharge architectures.
Supply Chain Analysis
Supplier-financing facilities from Danish and Dutch equipment manufacturers extend payment terms for biofilter seeding and startup support services, easing capital constraints for Southeast Asian operators. Specialized biofilter media and high-efficiency oxygen transfer equipment originate from Norway, Denmark, and the United States, with raw material dependencies on engineered plastics, titanium alloys for aeration components, and nitrifying bacteria cultures. Single-source vulnerability concentrates in European biofilm media formulations. Distribution runs through direct equipment sales fragmenting toward leasing models and service-based contracts in China and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across coastal discharge limits creates specialized niches for zero-discharge engineering, biological filtration expertise, and integrated multi-trophic system design. Equipment suppliers, new entrants, and investors each face distinct structural opportunities.
For Market Incumbents: Entrench through backward integration into biofilter media manufacturing and captive nitrifying bacteria culture production, securing supply continuity against single-source vulnerabilities. Expand service-based contract penetration in China's Shandong and Fujian provinces where rapid RAS deployment outpaces technical capacity formation. Counter emerging domestic Chinese fabricators by embedding proprietary monitoring software into biological filtration hardware, creating switching costs through digitized operational decision-making. For New Entrants and Emerging Players: Southeast Asia's yellowtail and kingfish pilot trials present underpenetrated demand for species-adapted water treatment protocols. Target research institutions with bundled equipment-leasing arrangements that include biofilm seeding and nitrification performance guarantees, mirroring successful penetration patterns in Chinese provinces. Differentiate through ozone-integrated architectures that anticipate EU F-Gas Regulation compliance requirements for temperature control system replacements. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because discharge limit tightening across the EU, Norway, and the United States structurally expands addressable market for closed-containment alternatives to open-net pen aquaculture. Acquisition candidates include biological filtration specialists with proprietary nitrifying biofilm management protocols and regional fabricators with established EPA or EU permit-compliant reference installations. Monitor EU Water Framework Directive enforcement intensity in Denmark and the Netherlands as early signal for integrated multi-trophic system demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biofilter Media | Captive supply of engineered nitrifying substrates reduces single-source vulnerability for Norwegian salmon RAS developers. |
| Leasing Model Penetration | Service-based contracts unlock capital-constrained operators in China's Shandong and Fujian provinces. |
| Ozone-Integrated System Development | Anticipates EU F-Gas Regulation compliance requirements for Danish and Dutch cooling system replacements. |
| Species Diversification R&D Partnerships | Pilot-scale demand from research institutions validates yellowtail and kingfish protocol adaptations. |
| Integrated Multi-Trophic System Design | Converts waste streams into secondary biomass, addressing tightening Netherlands and Denmark effluent limits. |
Research Methodology
The analysis maps recirculating systems, flow-through configurations, biological filtration methods, and treatment technologies, each validated through RAS engineering directors, aquaculture farm operations managers, biological filtration technicians, and regulatory compliance officers. Primary interviews with Norwegian land-based salmon producers, Chinese yellowtail pilot operators, and Danish equipment manufacturers combined with secondary validation from EPA discharge permit databases, EU Water Framework Directive implementation reports, Norwegian coastal licensing authority filings, and Chinese Ministry of Ecology and Environment standards. Bottom-up installation contract tracking and top-down aquaculture production capacity estimates provided triangulation across data sources.
The assumption-set framing held fixed the EU Green Deal discharge limit trajectory and Norway's polluter-pays framework while varying energy cost volatility scenarios and Chinese domestic technical capacity formation rates across the projection horizon. Segmentation dimensions modeled include system architecture, filtration method, treatment technology, and end-user type with regional regulatory cluster differentiation. CAGRs derived from equipment procurement pipeline analysis and production capacity expansion announcements, with specific inputs from biological filtration operational expenditure ratios and leasing model penetration rates in Asian markets.
Practitioners should monitor EU F-Gas Regulation enforcement timelines, Chinese coastal discharge standard revisions, and nitrifying biofilm technician training program expansion for early signals of demand inflection or supply constraint. Forecasts reflect documented assumptions regarding regulatory compliance cost trajectories and capital availability for land-based aquaculture investment. Macroeconomic energy price shocks, accelerated refrigerant phase-out schedules, or breakthroughs in flow-through retrofit economics would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
North America Aqua Feed Market
Aquaculture Innovations
Ornamental Tropical Fish Feed Market
Aquaculture Innovations
GCC Fish Farming Market
Aquaculture Innovations
Tilapia Market
Aquaculture Innovations
South Korea Aquaculture Market
Aquaculture Innovations
Fish Oil for Aquafeed Market
Aquaculture Innovations
Aquaculture Additives Market
Aquaculture Innovations
Clams, Cockles, Ark Shells Market
Aquaculture Innovations
Fish Farming Market
Aquaculture Innovations
Global Plant Based Fish Feed Market
Aquaculture Innovations
Aquaculture Healthcare Market
Aquaculture Innovations
Microalgae-Based Aquafeed Market
Aquaculture Innovations
Salmon Feed Market
Aquaculture Innovations
Seaweed Cultivation Market
Aquaculture Innovations
Aquaculture Pumps Market
Aquaculture Innovations
Shrimp Feed Market