
 Temporary Storage Buildings Market | 2026-2036
Temporary Storage Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
Temporary Storage Buildings Market Analytics
The capability gap between engineered-tension membrane specialists and commodity shed assemblers is collapsing as rental fleets demand certified wind-load and snow-load ratings across all price tiers. Sprung Structures leverages its aluminum subframe architecture to sustain premium positioning in military and aviation contracts. Heritage Building Systems anchors its competitiveness through controlled distribution networks spanning rural agricultural counties. ClearSpan Fabric Structures differentiates via in-house polyethylene membrane extrusion that shortens lead times for disaster-relief procurement cycles.
Temporary storage buildings are relocatable enclosures engineered with galvanized steel arches or aluminum frames tensioned over woven polyethylene or PVC-coated fabric membranes, designed for rapid assembly without permanent foundations and engineered to specified live loads, wind speeds, and snow ratings for industrial material protection. Fabric buildings dominate current deployment volumes due to lower capital outlay and faster permitting, while modular units capture expanding margin pools as construction firms seek reusable, code-compliant alternatives to conventional site trailers. Military use applications are accelerating fastest among end-user segments, driven by NATO mobility requirements and contingency base standardization protocols.
OSHA workplace safety standards govern temporary structure egress and anchorage on US construction sites, while the EU Construction Products Regulation mandates CE marking for structural stability and fire reaction performance of membrane materials. Germany's KBA building code adaptations for temporary structures and France's ANSM oversight of public-venue safety certifications collectively shape product design requirements and market access conditions across European procurement channels. Stakeholders must monitor evolving national interpretations of ISO 10977 wind-resistance testing as procurement specifications harden from guideline-based to prescriptive compliance frameworks.
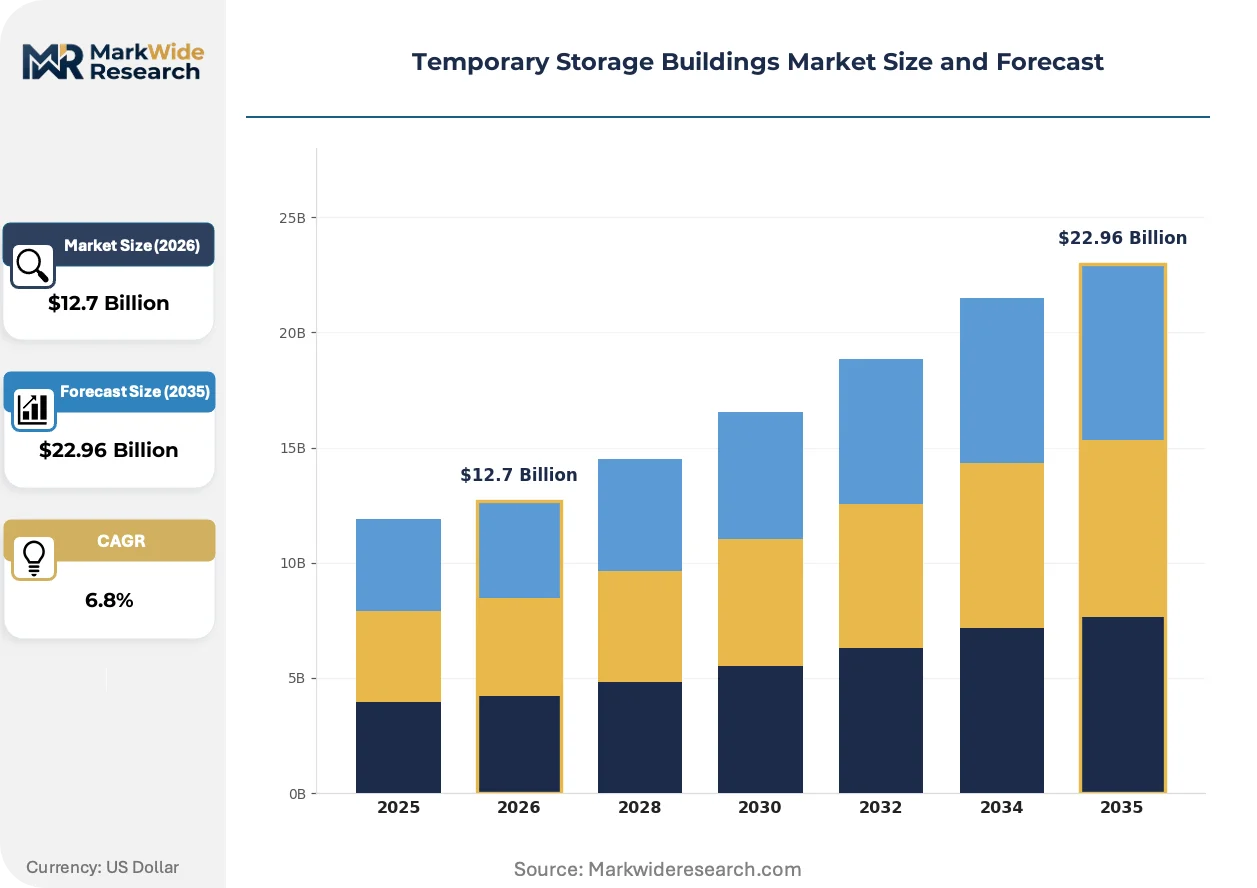
Market Dynamics
The EU Green Deal's embodied carbon thresholds are compressing supplier margins while forcing rapid material substitution across membrane and frame supply chains, fundamentally restructuring how manufacturers compete on certification rather than price alone.
Growth Catalysts
- NATO Mobility Requirements:Military contingency base standardization protocols are accelerating procurement of certified wind-load and snow-load rated structures across allied defense ministries.
- Germany's KBA Code Adaptations:Building code modifications for temporary structures enable faster permitting of demountable storage solutions in warehouse-constrained urban zones.
- Recycled Steel Frame Adoption:Fabricators integrating post-consumer aluminum and galvanized steel subframes capture premium positioning in EU public procurement channels.
Market Restraints
- PVC Membrane Phase-Out Costs:The EU Green Deal's polymer restrictions force capital-intensive retooling of extrusion lines toward polyethylene and bio-based alternatives.
- Galvanized Steel Tariff Volatility:Import duties on Chinese steel coil disrupt frame production economics for mid-tier assemblers dependent on spot-market sourcing.
- Foundation Engineering Gaps:Site-specific geotechnical assessments for tensioned membrane anchorage extend project timelines and inflate soft costs beyond commodity shed budgets.
Strategic Opportunities
- France's ANSM Public-Venue Certification:Safety oversight expansion creates entry paths for fire-rated membrane suppliers into festival, exhibition, and emergency shelter markets.
- Aviation MRO Hangar Conversion:Airlines retiring wide-body fleets are repurposing certified tension structures for parts storage and line maintenance bays.
- Disaster-Relief Procurement Cycles:FEMA and UNHCR framework agreements reward manufacturers with in-house membrane extrusion and sub-30-day lead time capabilities.
Industry Challenges
- ISO 10977 Testing Capacity Bottlenecks:Wind-resistance certification backlogs delay product launches as third-party laboratories struggle with prescriptive compliance framework transitions.
- Membrane Welding Technician Scarcity:RF and hot-air seaming specialists command premium wages, constraining output scaling for rental fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temporary Storage Buildings Market |
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $22.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable Structures, Fabric Buildings, Modular Units, Canopy Tents Application: Construction Sites, Event Venues, Military Use, Disaster Relief End User: Construction Companies, Event Organizers, NGOs, Government Agencies Installation Type: On-Site Deployment, Off-Site Deployment, Permanent Installation, Mobile Units |
| Companies Covered | Premier Portable Buildings, General Steel, Sprung Structures, SteelMaster Buildings, Heritage Building Systems, Trachte Building Systems, Sheds Unlimited, ClearSpan Fabric Structures, Big Top Fabric Structures, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temporary Storage Buildings Market Evolving Landscape
Material science advances and procurement digitization are compressing traditional competitive moats between engineered-tension specialists and commodity assemblers, while regulatory compliance hardens from voluntary to mandatory specifications.
Aluminum subframe architecture is bifurcating the premium segment from galvanized steel alternatives. Military and aviation buyers specify 6061-T6 extruded profiles for rapid redeployment cycles. This structural preference is compressing steel-frame margins in price-sensitive agricultural and construction verticals while elevating certified aluminum suppliers into long-term service contracts.
REACH annex restrictions on phthalate plasticizers are forcing PVC membrane reformulation across European supply chains. Manufacturers substituting bio-based plasticizers or pivoting entirely to polyethylene extrusion face 18-24 month requalification timelines. German and French public-venue procurement channels are most affected, with buyers now requiring ECHA-compliant material declarations prior to tender submission.
Rental fleet operators are consolidating procurement through digital tender platforms that automate compliance verification against ISO 10977 and national building codes. Construction firms and disaster-relief agencies bypass traditional distributor networks for direct manufacturer relationships. This channel compression is most visible in North American markets, where Sprung Structures and Heritage Building Systems have established captive portal procurement for repeat national accounts.
Temporary Storage Buildings Market Segmentation
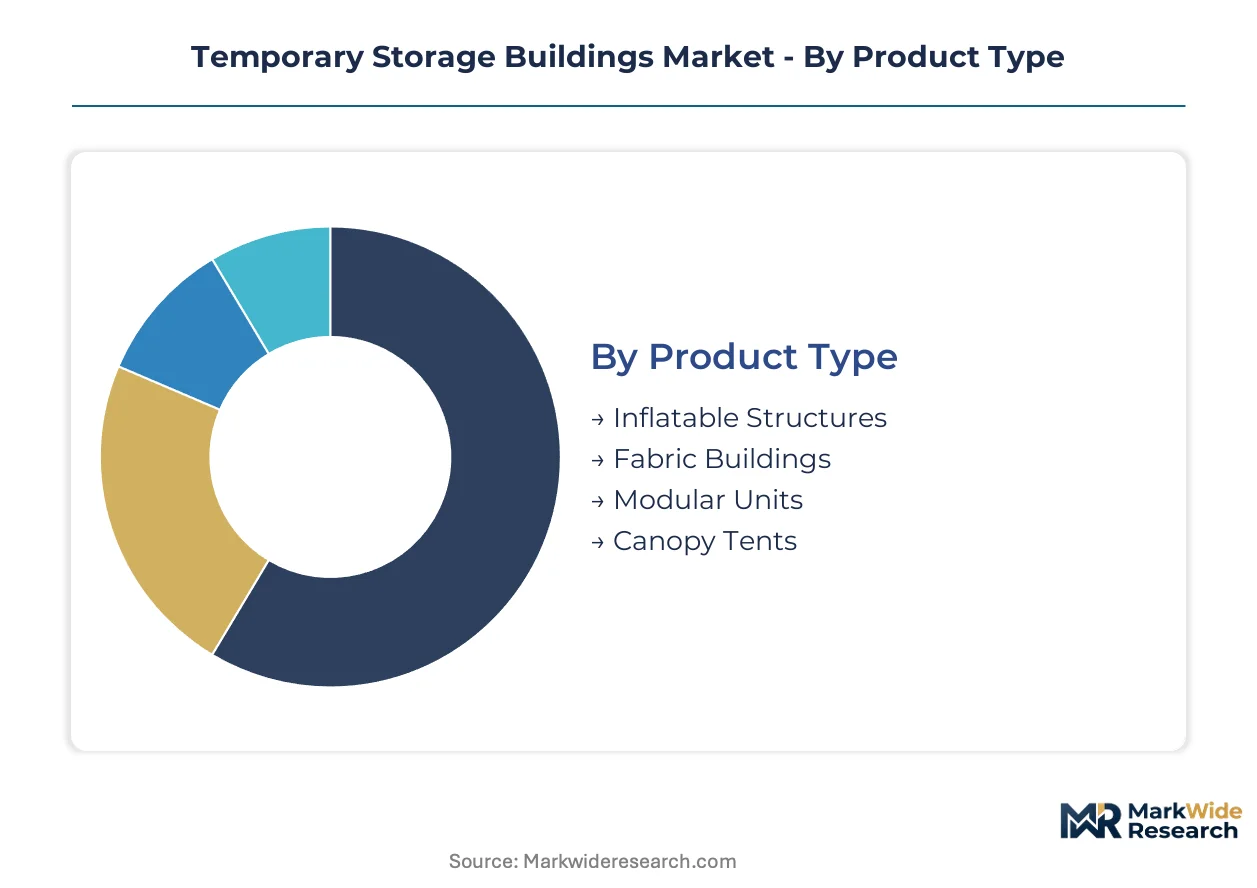
Segmentation in temporary storage buildings reveals how procurement specifications diverge across regulatory environments and end-use risk profiles. Product architecture, deployment location, and buyer category each impose distinct compliance burdens that reshape supplier economics.
Product Type:
CE marking under the EU Construction Products Regulation and ISO 10977 wind-resistance testing create tiered entry barriers that separate certified engineered solutions from commodity alternatives.
- Fabric Buildings:Galvanized steel or aluminum frames tensioned over woven polyethylene or PVC-coated membranes dominate current procurement volumes. German warehouse operators facing KBA code restrictions and France's ANSM public-venue safety mandates are accelerating orders for certified wind-load and snow-load rated structures.
- Modular Units:Reusable, code-compliant panelized systems capture expanding margin pools as construction firms seek alternatives to conventional site trailers. EU Green Deal embodied carbon thresholds are pushing manufacturers toward recycled steel frames and bio-based insulation cores.
- Inflatable Structures:Rapid-deployment air-beam architecture serves military contingency base protocols and disaster-relief staging.
- Canopy Tents:Light-duty framed shelters address agricultural equipment coverage and retail seasonal storage with minimal foundation requirements.
Established volume favors fabric buildings; emerging adoption favors modular units.
Application:
End-use risk tiers dictate foundation engineering intensity and membrane fire-rating specifications.
- Military Use:NATO mobility requirements and contingency base standardization protocols demand certified tension structures with rapid redeployment cycles. Aluminum subframe architecture specified for 6061-T6 extruded profiles commands premium positioning in allied defense procurement channels.
- Construction Sites:OSHA workplace safety standards govern egress and anchorage on US job sites, while material staging requirements concentrate demand for demountable solutions with sub-30-day lead times.
- Disaster Relief:FEMA and UNHCR framework agreements reward manufacturers with in-house membrane extrusion capabilities.
- Event Venues:France's ANSM oversight and Germany's public-assembly codes drive fire-rated membrane specifications for festival and exhibition deployments.
Military and disaster-relief applications are climbing the fastest; construction sites anchor current revenue concentration.
End User:
Procurement sophistication separates institutional buyers with compliance verification systems from price-sensitive spot purchasers.
- Government Agencies:Defense ministries and emergency management authorities mandate ISO 10977 certification and national building code adherence prior to tender award. Digital procurement portals automate verification, compressing traditional distributor margins.
- Construction Companies:Rental fleet operators and general contractors prioritize rapid assembly and relocation economics over permanent foundation investments.
- NGOs:Humanitarian logistics coordinators balance unit cost against deployment speed in remote-access environments.
- Event Organizers:Seasonal demand patterns favor short-term rental structures with minimal site preparation requirements.
Institutional procurement favors government agencies; volume scaling favors construction companies.
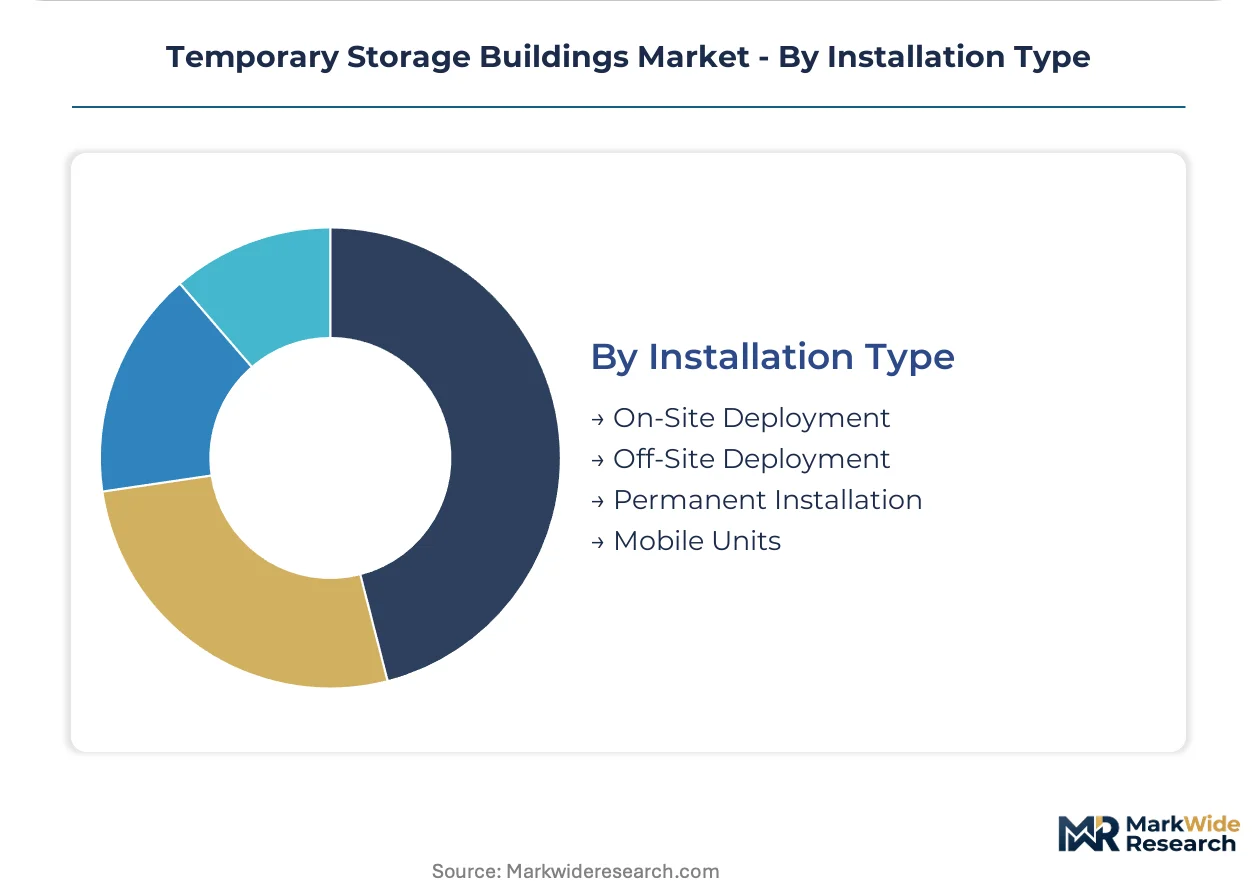
Installation Type:
Foundation permanence determines geotechnical assessment obligations and project timeline elasticity.
- On-Site Deployment:Tensioned membrane structures assembled without permanent foundations serve material staging and equipment shelter applications. Site-specific anchorage engineering extends soft costs beyond commodity shed budgets.
- Mobile Units:Trailer-mounted or skid-based systems enable rapid repositioning across construction phases and military forward operating locations.
- Off-Site Deployment:Factory-integrated modular units reduce field assembly labor for remote or labor-constrained environments.
- Permanent Installation:Concrete-pier or slab-mounted structures approach conventional building code compliance for long-term industrial storage.
Flexibility premiums favor mobile units; current procurement volume concentrates in on-site deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German procurement premiums for CE-marked tension structures exceed US spot-market pricing by 40-60%, reflecting divergent compliance burdens and foundation engineering standards across Atlantic procurement channels.
Germany
Warehouse capacity shortages in Hamburg and Rhine-Ruhr logistics corridors accelerate demountable storage deployment. KBA building code adaptations for temporary structures compress permitting timelines below conventional construction cycles. Bavarian fabricators near Munich specialize in aluminum subframe systems for defense and aviation contracts requiring rapid redeployment certification.
United States
Construction material staging demand concentrates in Texas Permian Basin energy corridors and Southeast manufacturing reshoring zones. OSHA workplace safety standards govern egress and anchorage specifications on active job sites. FEMA disaster-relief procurement cycles reward manufacturers with sub-30-day lead time capabilities through direct federal framework agreements.
France
Public-venue safety mandates from ANSM reshape festival and exhibition shelter specifications toward fire-rated membrane materials. REACH annex restrictions on phthalate plasticizers force PVC reformulation across membrane supply chains. Île-de-France logistics operators facing warehouse constraints adopt demountable solutions for urban last-mile staging facilities.
Canada
Remote resource extraction camps in Alberta oil sands and Northern Territories drive demand for rapid-assembly tension structures with extreme-climate wind ratings. Health Canada building code harmonization with provincial standards creates unified procurement specifications across Prairie Provinces. Vancouver-area port operators deploy modular units for trans-Pacific container staging amid terminal capacity bottlenecks.
United Kingdom
Post-Brexit customs inspection backlogs at Dover and Felixstowe ports inflate demand for on-site temporary storage near ferry terminals. UKCA marking transition from CE certification creates compliance recertification windows for membrane suppliers. Midlands manufacturing clusters near Birmingham adopt relocatable enclosures for just-in-time component buffering against supply chain volatility.
Temporary Storage Buildings Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with engineered-tension membrane specialists commanding premium positioning in institutional procurement while commodity assemblers compete on rental fleet scale and distributor network density. The vendor base spans three strategic tiers: aluminum subframe architects serving military-aviation contracts, galvanized steel fabricators anchored in agricultural and construction verticals, and rental fleet operators consolidating through digital tender platforms. Dominant competitive moves include backward integration into in-house membrane extrusion and geographic expansion through controlled distribution networks in rural counties.
Among North American fabricators, Sprung Structures and Heritage Building Systems exemplify divergent archetype positioning. Sprung Structures occupies the premium-tier vector through aluminum subframe specialization, while Heritage Building Systems anchors the scale-driven end via controlled distribution spanning agricultural counties. ClearSpan Fabric Structures represents the vertically integrated model with captive membrane production capabilities.
| Leading Market Players |
|---|
| Premier Portable Buildings |
| General Steel |
| Sprung Structures |
| SteelMaster Buildings |
| Heritage Building Systems |
| Trachte Building Systems |
| Sheds Unlimited |
| ClearSpan Fabric Structures |
| Big Top Fabric Structures |
| Others |
Value Network & Pricing Analysis
Aluminum extrusion capacity utilization above 85% in German and Bavarian fabrication clusters concentrates supply-side leverage among certified subframe specialists, compressing margins for galvanized steel assemblers while elevating price floors for military-aviation procurement tiers.
Pricing Analysis
The configured-to-order premium over standard fabric shelters spans 40-60% in German public procurement channels. Project-based contract pricing dominates institutional segments, with ISO 10977 certification tier and aluminum subframe specification serving as primary differentiation drivers. Cost compression in commodity steel-frame tiers intensifies due to spot-market galvanized coil exposure, while government agencies exhibit lowest price sensitivity given mandate-driven compliance requirements.
Supply Chain Analysis
Strait of Hormuz transit vulnerability for petrochemical feedstocks underwrites membrane material cost volatility across European extrusion operations. China, Germany, and the United States anchor global supply concentration for woven polyethylene substrates and aluminum 6061-T6 profiles. Raw material dependencies rest on PVC resin, bio-based plasticizers, and galvanized steel coil. Single-source vulnerability in phthalate-free additive formulations creates regulatory compliance risk. Distribution runs through manufacturer-direct digital portals and controlled rural distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Temporary storage buildings constitute a regulatory-entrenchment defensive moat where ISO 10977 certification backlog and national building code interpretation create switching costs that institutional buyers cannot readily circumvent.
For Market Incumbents: Secure aluminum subframe capacity expansion in German defense-corridor fabrication clusters to preempt NATO mobility requirement procurement waves. Deepen backward integration into in-house membrane extrusion to capture disaster-relief framework agreement margins threatened by ClearSpan's captive supply advantages. For New Entrants and Emerging Players: Lead with bio-based membrane formulations targeting France's ANSM public-venue certification channel where REACH plasticizer restrictions have disqualified incumbent PVC suppliers. Penetrate aviation MRO hangar conversion segments through rapid-deployment inflatable architecture absent from established tension-structure portfolios. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among rental fleet operators with captive portal procurement relationships; these assets warrant premium multiples against project-dependent fabricators. Long-term viability centers on regulatory compliance automation capabilities. Acquisition targets should demonstrate in-house ISO 10977 testing partnerships or captive laboratory relationships. Monitor ECHA material declaration expansion as inflection signal for membrane supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Extrusion | Captive polyethylene production shortens FEMA and UNHCR disaster-relief lead times against competitors. |
| Aluminum Subframe Capacity Expansion | 6061-T6 extrusion investments capture NATO defense procurement migrating from galvanized steel alternatives. |
| Digital Procurement Portal Development | Automated ISO 10977 compliance verification compresses distributor margins and locks national account relationships. |
| REACH-Compliant Material Reformulation | Phthalate-free PVC or bio-based polyethylene pivots open ANSM-certified public-venue channels in France. |
| Controlled Distribution Network Extension | Rural county coverage density anchors agricultural and construction segment volume scaling against rental consolidators. |
Research Methodology
A standing panel of rental fleet procurement directors, defense ministry contingency base planners, membrane welding technicians, and KBA code compliance officers provided ongoing calibration against secondary validation from EU Construction Products Regulation filings, ECHA substance restriction updates, FEMA framework agreement disclosures, and customs trade data on aluminum extrusion and steel coil imports. Bottom-up project pipeline analysis triangulated with top-down procurement budget forecasting across institutional buyer segments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated product architecture, installation type, end-use risk tier, and regional regulatory cluster dimensions. CAGRs derived from unit deployment trajectories and average contract value evolution, with specific inputs including NATO mobility requirement procurement cycles and German warehouse capacity utilization rates.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or NATO contingency base standardization timelines would require recalibration. Forecasts reflect documented assumptions regarding membrane material substitution timelines and aluminum capacity expansion schedules. Practitioners should keep alternative scenarios live as ECHA plasticizer restriction scope and KBA code interpretation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Formwork Market
Building & Construction Materials
Europe Oriented Strand Board Market
Building & Construction Materials
US Exterior Wall Systems Market
Building & Construction Materials
Residential and Commercial Smart Glass Market
Building & Construction Materials
Acoustic Ceiling Tiles Market
Building & Construction Materials
Middle-East and Africa Industrial Flooring Market
Building & Construction Materials
Insulating Glass Window Market
Building & Construction Materials
Softwood Lumber Market
Building & Construction Materials
Finishing Lines Market
Building & Construction Materials
Sheet Piling Market
Building & Construction Materials
Architectural Window Films Market
Building & Construction Materials
Moisture Resistant Plaster Boards Market
Building & Construction Materials
Travertine Market
Building & Construction Materials
Modular Commercial Building System Market
Building & Construction Materials
Saudi Arabia Concealed Cistern Market
Building & Construction Materials
Insulated Metal Panels Market