
 Asia-Pacific Online Grocery Delivery Market | 2026-2036
Asia-Pacific Online Grocery Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Online Grocery Delivery Market Outlook
The shift from marketplace-reliant sourcing to captive fulfillment networks is hardening across the Asia-Pacific online grocery delivery sector. Meituan leverages its super-app infrastructure to control last-mile density in Chinese megacities. Blinkit anchors rapid commerce through dark-store proliferation in Indian urban corridors. Amazon.com Inc. competes via integrated logistics spanning Australia, Japan, and Singapore.
Asia-Pacific online grocery delivery denotes digitally ordered perishable and packaged food fulfillment through temperature-monitored supply chains, typically requiring cold-chain integrity below four degrees Celsius for dairy and protein categories. Its commercial purpose centers on replacing traditional wet-market and supermarket trips with algorithmically routed doorstep fulfillment. Same-day delivery and express delivery command premium positioning where urban density supports sub-thirty-minute promises, while scheduled delivery and subscription service models capture recurring household baskets with higher retention economics. Direct delivery and marketplace models diverge sharply in margin structure, with captive logistics sustaining tighter quality control against asset-light partner networks.
India's FSSAI enforces packaged food labeling and hygiene protocols that elevate warehouse compliance costs for cross-border sellers. China's SAMR and Australia's ACCC monitor platform pricing transparency and vendor contract terms, constraining exclusivity arrangements that once locked merchants to single platforms. Japan's METI guidelines on food traceability add serialization requirements for imported fresh produce. Stakeholders must track how divergent national enforcement calendars reshape capital deployment timing across multi-country footprints.
Market Dynamics
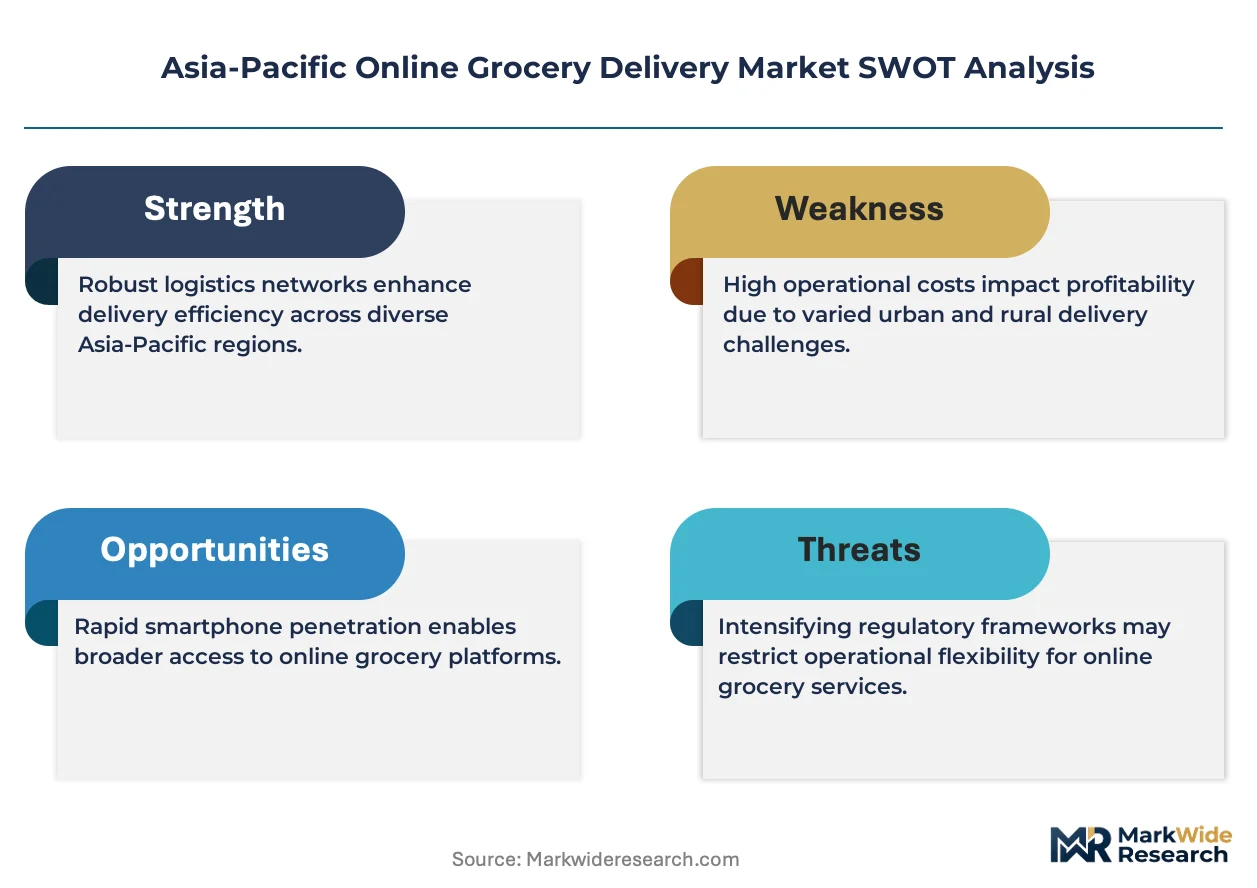
The migration from asset-light marketplace models to captive fulfillment infrastructure constitutes the dominant structural force across Asia-Pacific online grocery delivery. Platform operators now prioritize cold-chain density over geographic breadth, reshaping capital allocation toward warehouse automation and fleet electrification.
Growth Catalysts
- Scheduled Subscription Models:Working parents in metro India and Southeast Asia lock in recurring delivery slots, generating predictable demand density that justifies dedicated dark-store placement.
- FSSAI Labeling Mandates:India's packaged food hygiene protocols compel platform investment in temperature-verified warehousing, inadvertently raising barriers for cross-border sellers unable to meet serialization requirements.
- Super-App Ecosystems:Integrated payment, loyalty, and delivery interfaces in Chinese megacities collapse customer acquisition costs while embedding grocery within broader lifestyle spending patterns.
Market Restraints
- Perishability-Driven Inventory Risk:Protein and dairy categories demand sub-four-degree Celsius integrity throughout the chain, elevating spoilage losses for operators lacking predictive demand algorithms.
- Last-Mile Labor Concentration:Gig-worker availability clusters disproportionately in tier-one Indian and Chinese cities, constraining service expansion into secondary urban corridors.
- Interstate Cold-Chain Gaps:India's fragmented national highway refrigeration infrastructure forces platform operators to rebuild temperature-controlled capacity rather than leverage existing third-party networks.
Strategic Opportunities
- Vietnam and Indonesia Penetration:Smartphone penetration in Ho Chi Minh City and Jakarta outpaces organized grocery infrastructure, creating first-mover terrain for platform operators willing to absorb initial fulfillment losses.
- SAMR Data Localization Rules:China's e-commerce transparency mandates generate compliance-service demand for foreign entrants seeking market access without building captive logistics.
- IoT-Converged Fleet Monitoring:Real-time temperature and location telemetry from delivery vehicles enables dynamic route optimization while generating audit trails for regulator submissions.
Industry Challenges
- Cold-Chain Engineer Scarcity:Platform operators compete with pharmaceutical distributors for technicians capable of maintaining multi-zone refrigeration across distributed warehouse networks.
- Legacy Wet-Market Integration:Established fresh produce procurement relationships in Chinese and Indian wholesale markets resist digitization, forcing hybrid sourcing models that dilute margin capture.
- Multi-Jurisdiction Compliance Timelines:Divergent enforcement calendars across India's FSSAI, China's SAMR, and Australia's ACCC fragment capital deployment sequencing for regional operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Online Grocery Delivery Market |
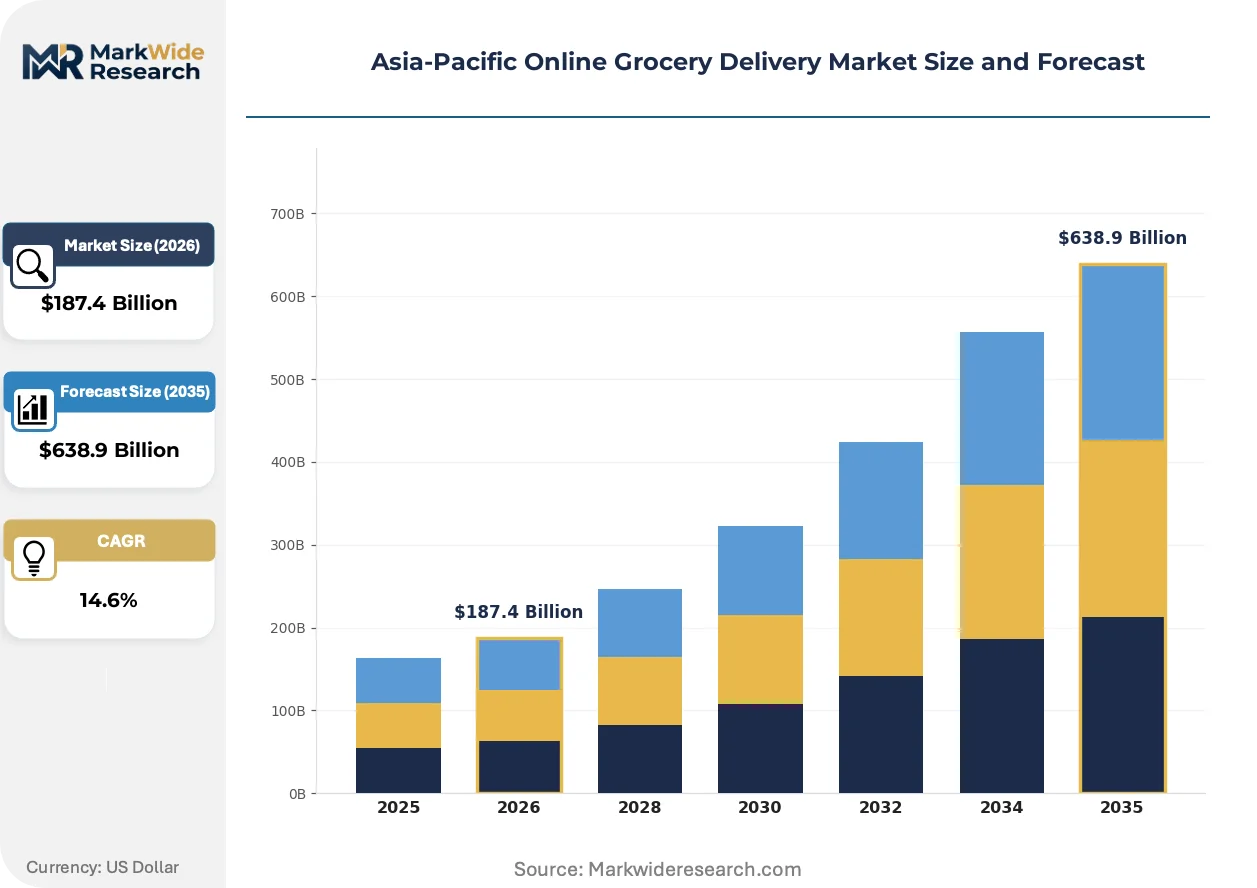
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $638.9 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Scheduled Delivery, Subscription Service, Express Delivery Product Type: Fruits & Vegetables, Dairy Products, Beverages, Packaged Foods Customer Type: Households, Restaurants, Offices, Retailers Delivery Model: Direct Delivery, Click & Collect, Partner Delivery, Marketplace |
| Companies Covered | Swiggy Instamart, Costco Wholesale Corp., Amazon.com Inc., Walmart Inc., SPAR International, Blinkit, Coles Group Ltd., Meituan, Flipkart Internet Pvt. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Online Grocery Delivery Market Strategic Shifts
Algorithmic demand prediction and automated micro-fulfillment are compressing delivery windows while reshaping warehouse location strategy across the region. Platform operators now optimize for sub-thirty-minute radius coverage rather than citywide presence.
AI-powered demand forecasting is rewriting inventory positioning logic across Asia-Pacific grocery platforms. Meituan and comparable operators deploy machine learning models that predict neighborhood-level consumption patterns from weather, calendar, and social event data. Dark-store stocking decisions now refresh hourly rather than daily. This compression is eliminating buffer inventory while raising service-level expectations for perishable availability.
China's SAMR e-commerce transparency rules are mandating real-time pricing disclosure and vendor contract standardization. Platform exclusivity arrangements that once locked merchants to single operators now face mandatory cooling-off periods and termination rights. Cross-border sellers into the Chinese market must restructure partner agreements to accommodate audit-ready documentation. Australian operators under ACCC scrutiny are preemptively adopting similar transparency architectures to avoid enforcement action.
Household procurement patterns in India's tier-one cities are fragmenting across multiple platform relationships rather than consolidating with single providers. Consumers maintain subscriptions for staple replenishment while reserving express slots for impulse categories from competing apps. This behavior is forcing platform operators to unbundle service tiers and compete on category-specific reliability rather than aggregate convenience. Mumbai and Delhi NCR households demonstrate the highest switching frequency, with loyalty programs showing diminished retention power against promotional discounting.
Asia-Pacific Online Grocery Delivery Market Segmentation
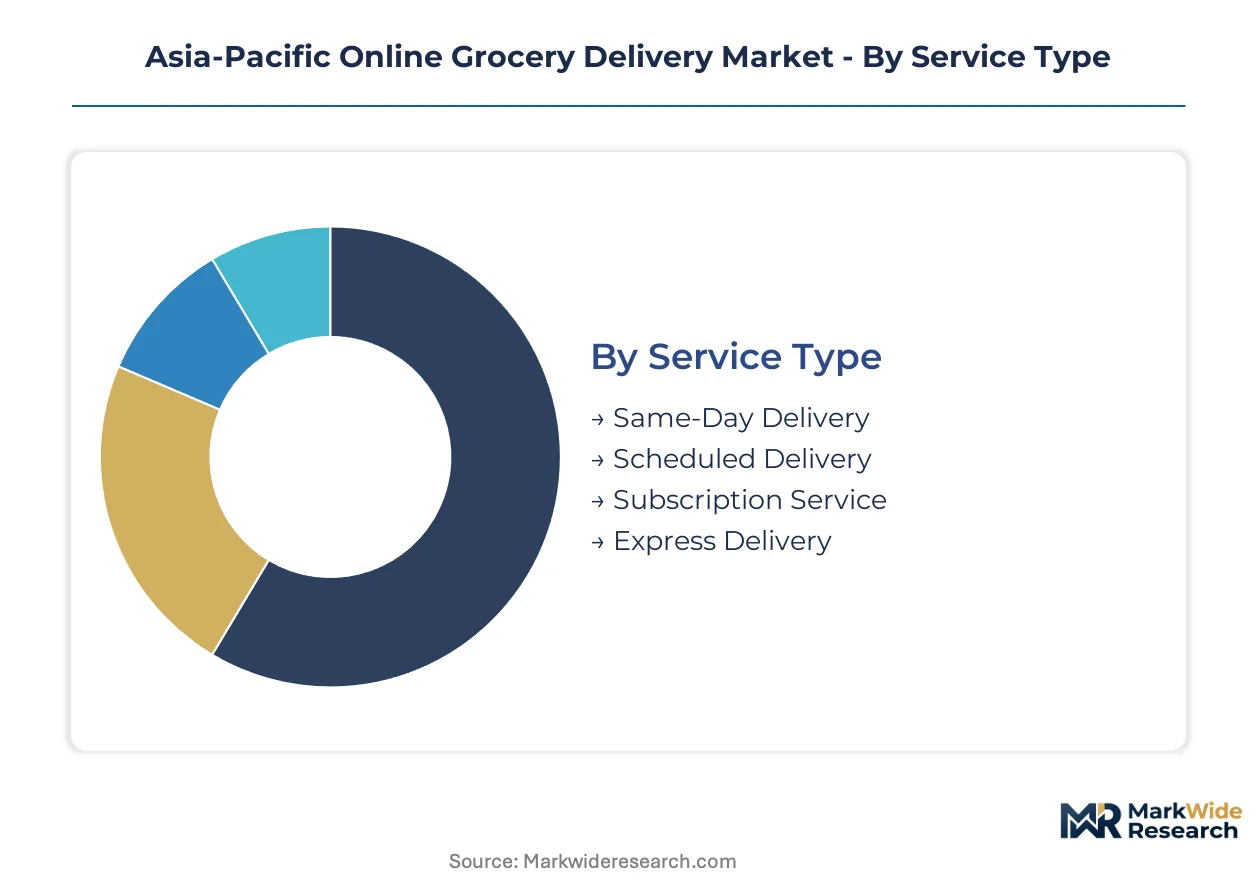
Segmentation in Asia-Pacific online grocery delivery reveals how platform operators allocate capital across fulfillment modalities and customer cohorts. Each dimension carries distinct margin profiles and infrastructure requirements that shape competitive positioning in this capital-intensive sector.
Service Type:
Customization intensity varies sharply across this spectrum, from rigid subscription slots to on-demand express windows requiring dynamic fleet deployment.
- Same-Day Delivery:Temperature-controlled fulfillment completing within 24 hours through hub-and-spoke warehouse networks. Demand concentrates in China's Yangtze River Delta cluster where urban density supports route consolidation and working parents prioritize weekend stock-up missions.
- Scheduled Delivery:Pre-booked time slots enabling predictive demand aggregation and dark-store pre-positioning. Metro India households lock recurring slots for staple replenishment, generating the retention economics that justify dedicated cold-chain infrastructure.
- Subscription Service:Recurring basket fulfillment with automated replenishment algorithms.
- Express Delivery:Sub-thirty-minute fulfillment through micro-fulfillment nodes.
Leading the category by volume: Scheduled Delivery. Expanding most quickly: Express Delivery.
Product Type:
Margin structure diverges across temperature requirements, with ambient packaged goods subsidizing loss-leading fresh categories that drive frequency.
- Fruits & Vegetables:Fresh produce requiring rapid inventory turnover and quality-grading protocols. Procurement relationships in India's wholesale mandis and China's wet markets resist digitization, forcing hybrid sourcing that dilutes platform margin capture.
- Dairy Products:Temperature-sensitive SKUs demanding sub-four-degree Celsius integrity throughout the chain. China's SAMR traceability mandates and India's FSSAI labeling requirements elevate compliance costs for cross-border sellers.
- Beverages:High-weight, low-margin category with ambient and chilled variants.
- Packaged Foods:Shelf-stable inventory with longest fulfillment windows and lowest spoilage risk.
Packaged Foods anchors revenue contribution. Dairy Products shows steepest expansion trajectory as cold-chain density improves.
Customer Type:
Order frequency and basket composition vary dramatically across end-use segments, from high-velocity household replenishment to bulk institutional procurement.
- Households:Individual consumers with fragmented platform relationships and high switching frequency. Mumbai and Delhi NCR households maintain multiple app subscriptions, unbundling staple replenishment from impulse express orders.
- Restaurants:Commercial buyers requiring consistent quality and volume reliability for menu continuity.
- Offices:Corporate procurement with scheduled bulk delivery and consolidated billing requirements.
- Retailers:Small-format stores sourcing inventory through platform marketplaces.
Households dominate transaction volume. Restaurants gain share fastest as platform B2B capabilities mature.
Delivery Model:
Asset intensity separates captive logistics operators from marketplace intermediaries, with margin and quality control implications.
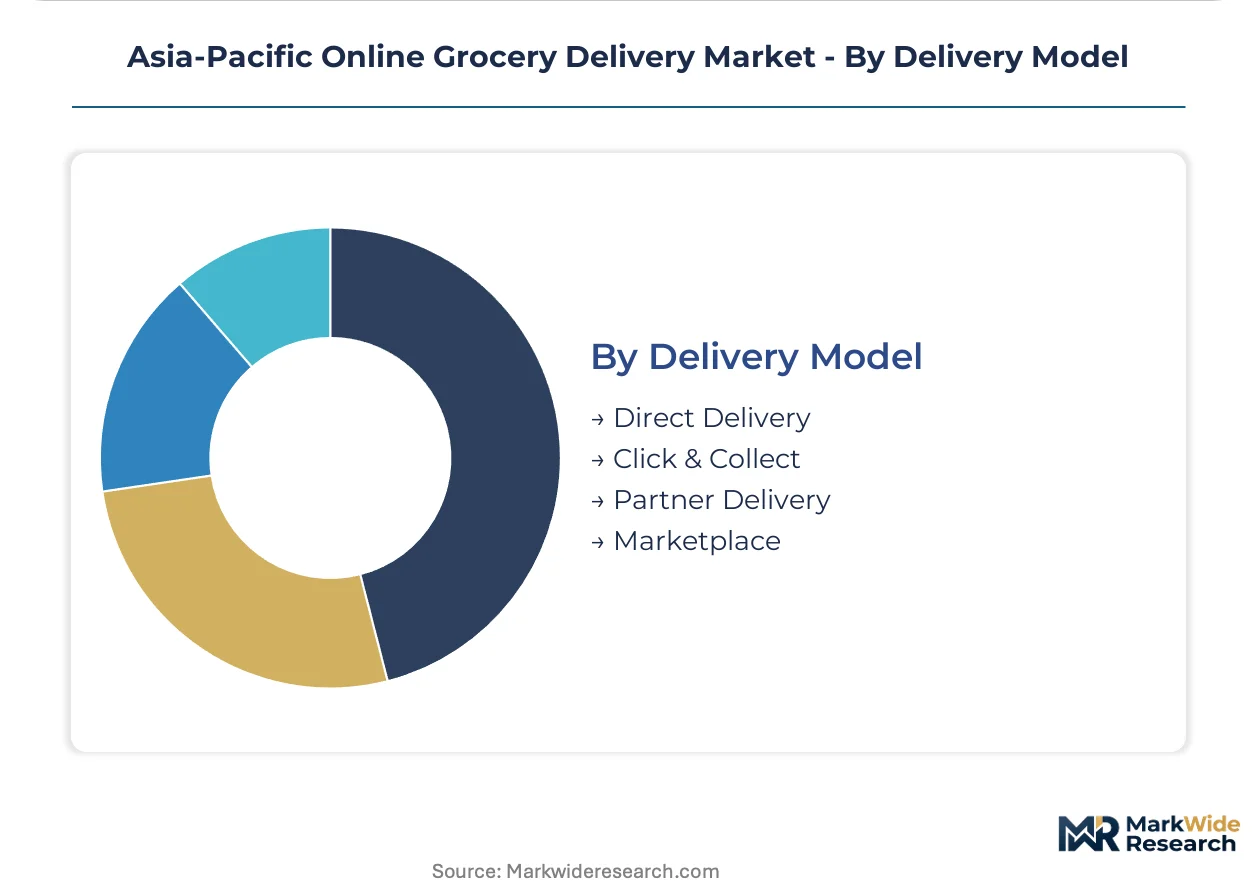
- Direct Delivery:Platform-operated fleets with full cold-chain custody. Meituan's super-app infrastructure and Blinkit's dark-store networks exemplify this model, enabling sub-thirty-minute promises through last-mile density.
- Click & Collect:Customer pickup from designated fulfillment points reducing last-mile cost.
- Partner Delivery:Third-party logistics integration with variable service-level agreements.
- Marketplace:Asset-light model connecting buyers with independent sellers bearing fulfillment responsibility.
Direct Delivery leads by revenue concentration. Click & Collect climbs fastest as urban real estate constraints intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Working parents in metro India and Southeast Asia drive adoption through scheduled delivery subscriptions, while China's Yangtze River Delta cluster anchors fulfillment density. India's FSSAI labeling mandates and China's SAMR e-commerce rules reshape compliance requirements across national footprints. Demand concentrates in tier-one Indian cities and Chinese megacity corridors where cold-chain infrastructure justifies capital deployment.
China
Meituan's super-app infrastructure controls last-mile density in megacities where urban population concentration supports sub-thirty-minute delivery promises. SAMR e-commerce transparency rules mandate real-time pricing disclosure and vendor contract standardization that constrain exclusivity arrangements. The Yangtze River Delta cluster generates the route consolidation economics that justify dedicated dark-store placement and fleet electrification investments.
India
Blinkit anchors rapid commerce through dark-store proliferation in Mumbai and Delhi NCR urban corridors where household switching frequency runs highest. FSSAI packaged food labeling and hygiene protocols compel platform investment in temperature-verified warehousing that elevates barriers for cross-border sellers. Interstate cold-chain gaps force operators to rebuild temperature-controlled capacity rather than leverage existing third-party networks.
Japan
Amazon.com Inc. competes via integrated logistics spanning Australia, Japan, and Singapore where METI guidelines on food traceability add serialization requirements for imported fresh produce. Working households in Greater Tokyo maintain fragmented platform relationships that unbundle staple replenishment from impulse express orders. The Kanto region's established retail infrastructure constrains pure-play grocery platform penetration relative to other Asia-Pacific markets.
Australia
Coles Group Ltd. operates within ACCC scrutiny of platform pricing transparency and vendor contract terms that preemptively shape competitive behavior. Suburban sprawl around Sydney and Melbourne generates delivery radius challenges that favor click-and-collect models over pure doorstep fulfillment. The country's dispersed population density produces unit economics that diverge sharply from Asian megacity corridors.
Vietnam
Smartphone penetration in Ho Chi Minh City outpaces organized grocery infrastructure, creating first-mover terrain for platform operators willing to absorb initial fulfillment losses. Working households in the Mekong Delta corridor demonstrate subscription appetite for staple replenishment that mirrors Indian metro patterns. Legacy wet-market procurement relationships resist digitization, forcing hybrid sourcing models that dilute margin capture for new entrants.
Asia-Pacific Online Grocery Delivery Market Competitive Environment
Dark-store network expansion dominates the current landscape as operators prioritize cold-chain density over geographic breadth. The vendor base stratifies across super-app ecosystems, dedicated rapid-commerce specialists, and integrated retail conglomerates with captive logistics. Three archetypes define competitive positioning: algorithmic demand predictors with hourly inventory refresh, hybrid marketplace-logistics operators balancing asset-light and captive models, and legacy retailers retrofitting store networks for fulfillment. M&A activity and warehouse automation capex represent the dominant competitive moves reshaping capital allocation.
Among Asia-Pacific-based rapid-commerce specialists, Blinkit and Meituan occupy positions that exemplify divergent infrastructure strategies. Blinkit represents the dark-store proliferation archetype anchoring sub-thirty-minute promises through distributed micro-fulfillment nodes. Meituan sits within the super-app ecosystem tier where integrated payment, loyalty, and delivery interfaces collapse customer acquisition costs. Amazon.com Inc. anchors the multinational integrated logistics archetype spanning Australia, Japan, and Singapore with temperature-monitored supply chain custody.
| Leading Market Players |
|---|
| Swiggy Instamart |
| Costco Wholesale Corp. |
| Amazon.com Inc. |
| Walmart Inc. |
| SPAR International |
| Blinkit |
| Coles Group Ltd. |
| Meituan |
| Flipkart Internet Pvt. Ltd. |
| Others |
Value Chain & Pricing Dynamics
China's dual carbon goals and fleet electrification mandates gate access to premium-tier pricing corridors for operators with compliant cold-chain infrastructure, while excluding asset-light marketplace intermediaries from temperature-verified fulfillment contracts. India's FSSAI serialization requirements and Japan's METI traceability protocols similarly partition supplier qualification tiers, concentrating margin capture among platform operators with captive warehouse networks.
Pricing Analysis
Volume concentration in scheduled subscription tiers subsidizes razor-thin margins in express delivery segments. Three-tier pricing structure across premium, standard, and economy levels stratifies by delivery speed promise and cold-chain custody grade. Cost compression in economy tiers intensifies because gig-worker wage floors in Chinese and Indian megacities are rising faster than route density improvements. Working parents in metro India demonstrate lowest price sensitivity for subscription slots, while impulse-driven express buyers in Jakarta and Ho Chi Minh City exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from China's SAMR and India's FSSAI compel platform operators to qualify multiple cold-chain warehouse providers per metropolitan zone. Geographic supply concentration centers on China, India, and Vietnam for dark-store construction materials and refrigeration equipment. Raw material dependencies span lithium-ion battery cells for electric delivery fleets, polyurethane insulation panels, and IoT temperature sensors. Single-source vulnerability runs through specialized cold-chain engineering talent pools shared with pharmaceutical distributors. Distribution runs through hub-and-spoke warehouse networks feeding micro-fulfillment nodes in urban cores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold-chain engineer scarcity props pricing power for qualified operators, as platform competition for technical talent outstrips graduating pipeline capacity from regional vocational institutes.
For Market Incumbents: Hedge against interstate cold-chain infrastructure gaps by securing captive warehouse footprints in Indian tier-one corridors before land cost escalation accelerates. Prioritize backward integration into temperature-controlled fleet operations to offset rising third-party logistics rates. Defensive consolidation around dark-store density in Chinese Yangtze River Delta cities blunts Meituan's super-app ecosystem lock-in threat. For New Entrants and Emerging Players: The price-point gap between premium subscription tiers and economy on-demand slots offers white-space terrain for hybrid service bundles. Vietnam's Ho Chi Minh City and Indonesia's Jakarta present most penetrable geographies where smartphone penetration outpaces organized grocery infrastructure. Go-to-market angle should anchor scheduled delivery subscriptions for working households, mirroring Indian metro adoption patterns. For Investors and Strategic Acquirers: Dark-store network expansion announcements from regional operators is the leading indicator that capital allocation is shifting toward captive fulfillment infrastructure. Long-term viability favors platform operators with algorithmic demand prediction capabilities and hourly inventory refresh systems. Acquisition target archetype: rapid-commerce specialists with established cold-chain custody in tier-one Indian or Southeast Asian corridors. Signal to watch is FSSAI compliance certification velocity as barrier-to-entry proxy.| Strategic Initiative | Industry Significance |
|---|---|
| Dark-Store Network Expansion | Enables sub-thirty-minute delivery promises through distributed micro-fulfillment nodes in dense urban corridors. |
| Fleet Electrification Program | Aligns with China's dual carbon goals while reducing last-mile fuel cost volatility for route-dense operators. |
| IoT Temperature Monitoring Integration | Generates real-time audit trails for India's FSSAI and China's SAMR compliance submissions. |
| Subscription Service Tier Launch | Captures recurring household demand density that justifies dedicated cold-chain infrastructure investment. |
| Warehouse Automation Deployment | Compresses order fulfillment cycle times to support hourly inventory refresh in perishable categories. |
Study Parameters
Multi-period observation of dark-store placement velocity, fleet electrification capex, and regulatory enforcement calendars anchored the trend analysis, supplemented by interviews with cold-chain logistics directors, platform operations executives, FSSAI compliance officers, and grocery category managers. Secondary validation drew from SAMR e-commerce transparency filings, India's FSSAI packaged food labeling directives, METI food traceability guidelines, and customs records for refrigeration equipment imports. Bottom-up demand modeling triangulated against top-down market sizing across service type, product category, and customer segment dimensions.
Segment-weighting approach applied differential growth assumptions to scheduled delivery, express delivery, and subscription service tiers based on urban density thresholds and cold-chain infrastructure maturity. Modeled dimensions spanned service modality, temperature requirement tier, customer archetype, and metropolitan zone classification. CAGRs were derived from regression analysis of historical fulfillment volume against smartphone penetration, working household density, and regulatory compliance cost indices. Forecast inputs incorporated route consolidation economics and perishability-driven spoilage loss rates.
Inputs from platform operator disclosures and national regulator guidance documents were available through the study window; gaps in real-time dark-store utilization rates and gig-worker wage trajectory data introduce uncertainty bands around fulfillment cost assumptions. Deviation in China's SAMR enforcement intensity or India's interstate cold-chain infrastructure buildout pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
India Retail Bubble Tea Kits Market
Food Service
Catering Food Warmers Market
Food Service
Latin America Airport Quick Service Restaurant Market
Food Service
Germany Foodservice Market
Food Service
United States Food Truck Market
Food Service
South Africa Fast Food Market
Food Service
Ice Cream Carts Market
Food Service
Food Service Gloves Market
Food Service
GCC Food Service Market
Food Service
South America Free from Food Market
Food Service
Beverage Napkins Market
Food Service
North America Food Service Disposable Market
Food Service
Saudi Arabia Pizza Restaurants Market
Food Service
Canada Food Service Market
Food Service
Integrated Stove Market
Food Service
Commercial Air Fryer Market