
 Commercial Cutlery Market | 2026-2036
Commercial Cutlery Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Cutlery Market Outlook
Modular knife sets bundled with magnetic storage blocks and interchangeable blade systems is expanding buyer choice across commercial kitchens. Zwilling J.A. Henckels leverages its Solingen heritage to sustain premium positioning in European foodservice channels. Wüsthof competes through precision-forged manufacturing scale that anchors supply relationships with major restaurant groups. Mercer Tool Corp. specializes in value-tier offerings that dominate culinary school procurement across North America.
Commercial cutlery encompasses knives, shears, and sharpening tools engineered from high-carbon stainless steel alloys with Rockwell hardness ratings between 55 and 66 HRC, designed for repetitive food preparation in professional environments. Chef knives command the largest product-type position due to universal kitchen necessity, while ceramic blades represent the fastest-growing material segment as kitchens seek lightweight, corrosion-resistant alternatives for specialized slicing tasks. Stainless steel retains mature, high-volume status in food processing applications where durability requirements outweigh weight considerations.
FDA food-contact surface regulations and NSF International certification standards govern blade materials and handle sanitation design in US commercial kitchens, directly shaping product development requirements for market access. EU REACH compliance and CE marking obligations constrain alloy compositions and manufacturing chemistries for European-bound inventory. Stakeholders must monitor evolving food safety audits and sustainability disclosure frameworks to align procurement specifications with tightening operator compliance obligations.
Market Dynamics
Restaurants deploying open-kitchen concepts are recalibrating procurement specifications toward visually distinctive blade finishes and ergonomic handle designs that withstand continuous guest visibility.
Growth Catalysts
- EU F-Gas Regulation:Heat treatment facilities across Germany and Italy are retrofitting furnaces with hydrogen-based atmospheres to meet fluorinated gas phase-down mandates, accelerating capital deployment in energy-efficient metallurgy.
- Ceramic blade advancement:Zirconium dioxide formulations achieving Rockwell 85+ hardness are displacing steel in specialized slicing stations within Japanese sushi operations and plant-based protein processing lines.
- Solingen craft cluster:Concentrated blade-making heritage in this German city sustains premium positioning through apprenticeship pipelines and localized supply of cobalt-alloyed steels.
Market Restraints
- Alloy cost volatility:Molybdenum and vanadium price swings from South African and Chinese concentrate suppliers compress margin predictability for forged-blade manufacturers.
- REACH compliance friction:ECHA substance restrictions on chromium VI surface treatments force reformulation of passivation chemistries, extending qualification timelines for European-bound inventory.
- Ceramic brittleness ceiling:Fracture toughness limitations below 5 MPa·m½ restrict ceramic blade deployment to straight-line cutting tasks, excluding torque-heavy applications.
Strategic Opportunities
- India foodservice expansion:Organized restaurant chains in Mumbai and Bangalore are establishing central kitchens with standardized knife protocols, creating first-mover advantage for NSF-certified suppliers.
- Sharpening-as-a-service:Mobile honing units using water-cooled grinding systems are penetrating casino and cruise line accounts that prioritize blade longevity over capital replacement.
- CSRD disclosure alignment:European operators subject to corporate sustainability reporting mandates are sourcing cutlery with documented recycled content and heat-treatment carbon footprints.
Industry Challenges
- Heat treater capacity bottleneck:Vacuum furnace availability for high-carbon stainless hardening is constrained in Solingen and Seki clusters, extending lead times for precision-forged orders.
- NSF certification backlog:Third-party sanitation testing queues for new handle polymers and antimicrobial coatings are stretching approval cycles beyond 14 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Cutlery Market |
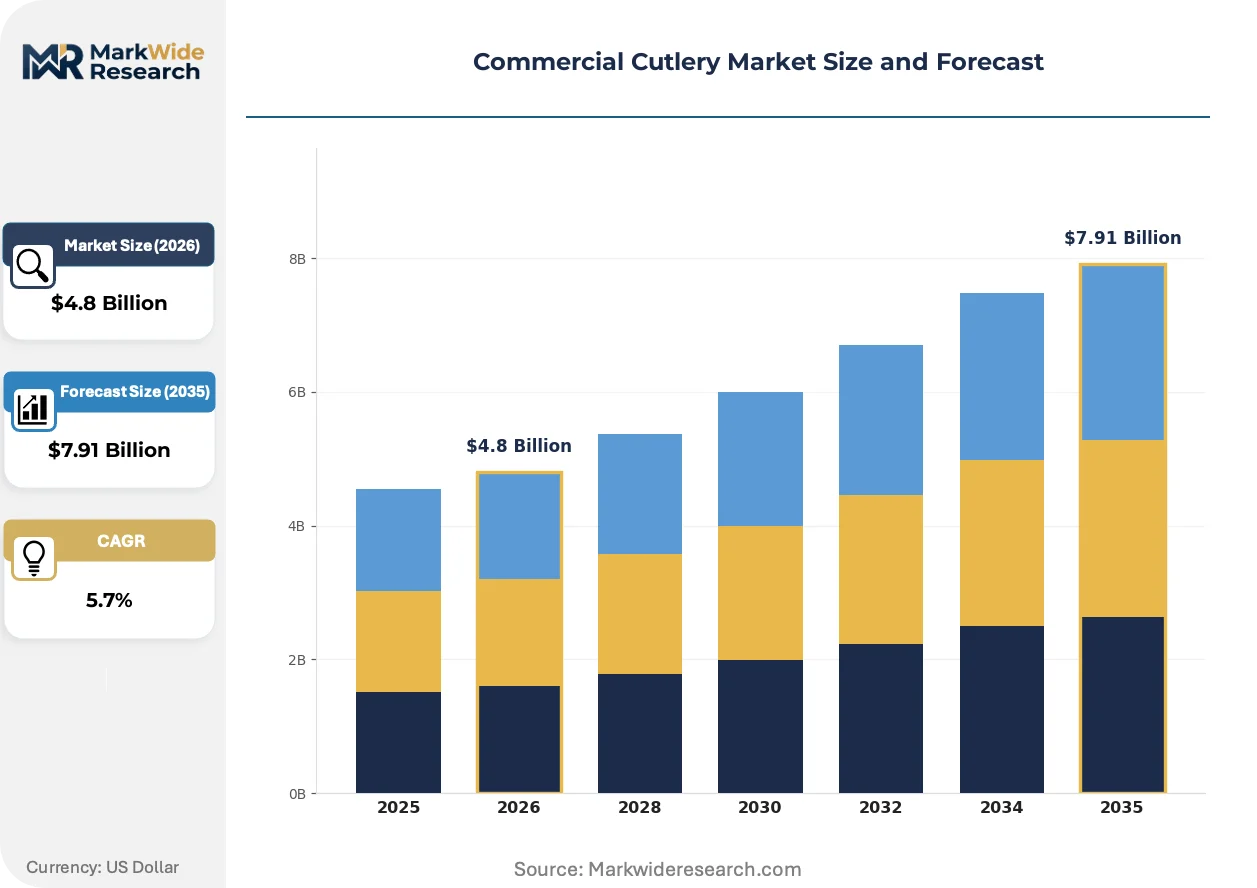
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chef Knives, Paring Knives, Bread Knives, Utility Knives Material: Stainless Steel, Carbon Steel, Ceramic, Plastic Application: Restaurants, Catering Services, Food Processing, Delis End User: Chefs, Cooks, Kitchen Staff, Culinary Schools |
| Companies Covered | Zwilling J.A. Henckels, Kai Corp., Victorinox, Friedr. Dick GmbH and Co. KG, MAC Knife Inc., Wüsthof, Messermeister, Mercer Tool Corp., Dexter-Russell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Cutlery Market Strategic Shifts
Digital traceability and closed-loop material recovery are redefining how commercial kitchens validate blade provenance and manage end-of-life inventory.
Laser-etched QR codes linking individual blades to alloy certificates and sharpening history are converging with blockchain-verified supply chain records. Large contract foodservice operators in the US are piloting these systems to satisfy FDA audit trails for high-risk preparation zones. This convergence is compressing supplier qualification timelines while raising barriers for undocumented imports.
The EU F-Gas Regulation's 2024 service ban on high-global-warming-potential refrigerants is cascading into heat treatment subcontractor networks. Furnace operators in Germany and northern Italy are replacing nitrogen-methanol atmospheres with cracked ammonia systems, reallocating capital from blade R&D toward environmental compliance infrastructure.
Specification consolidation among multi-unit restaurant groups is displacing fragmented distributor relationships with direct manufacturer agreements. Chains exceeding 200 locations are mandating unified Rockwell specifications and handle color-coding systems, compressing SKU diversity at the procurement tier. This concentration is most visible in US fast-casual expansion and UK contract catering consolidation.
Commercial Cutlery Market Segmentation
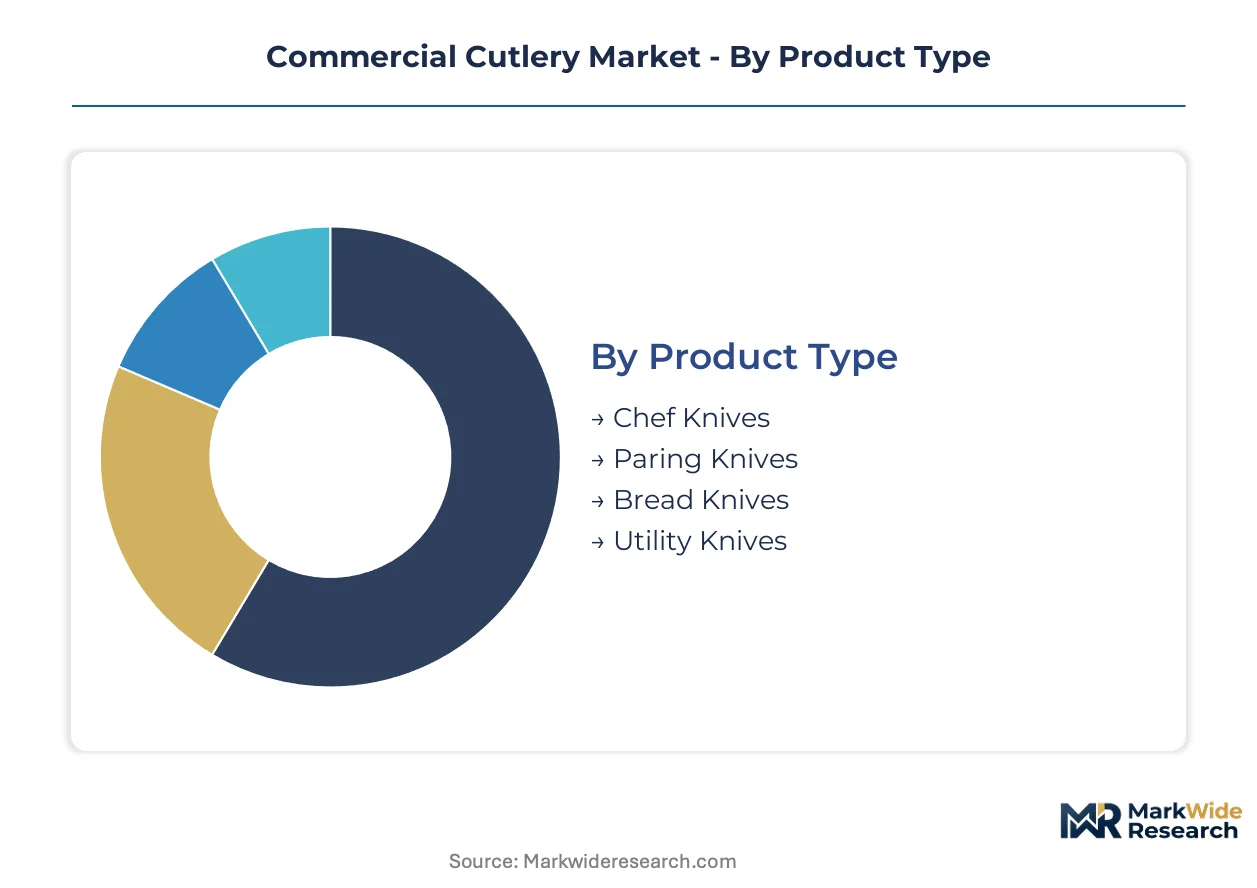
Commercial cutlery procurement splits across four intersecting dimensions that reshape inventory strategy. Product type determines blade geometry investment. Material selection governs heat treatment sourcing and regulatory compliance. Application context dictates durability specifications and replacement cycles.
Product Type:
Blade geometry concentration in Solingen and Seki manufacturing clusters shapes availability and lead time structures across each product category.
- Chef Knives:Full-tang construction with 8-10 inch blades dominates professional kitchen capital expenditure. Restaurant chains in Germany and the US standardize on Rockwell 58-60 HRC specifications for open-kitchen visibility and edge retention under continuous use.
- Paring Knives:Compact 3-4 inch blades with pointed tips concentrate in high-volume vegetable prep stations. Catering operators in France and Italy specify these for mobile kitchen efficiency where workspace constraints demand maneuverability over reach.
- Bread Knives:Serrated edge profiles with scalloped or wavy patterns slice through crust without compression. Longer 10-12 inch variants anchor bakery and deli procurement lists where artisan loaf processing requires clean crumb structure preservation.
- Utility Knives:Mid-length 5-7 inch blades fill the gap between chef and paring functions. Food processing facilities in Japan deploy these for protein portioning where blade length standardization reduces cross-contamination protocol complexity.
Today's leader: Chef Knives. Tomorrow's challenger: Utility Knives.
Material:
Alloy sourcing corridors from South African molybdenum and Chinese vanadium suppliers create cost tier differentiation that segments procurement budgets.
- Stainless Steel:Chromium-nickel alloys with 13-18% chromium content deliver corrosion resistance for wet kitchen environments. NSF certification requirements in US commercial kitchens lock in this material for 70% of institutional procurement volumes despite premium over carbon alternatives.
- Ceramic:Zirconium dioxide formulations achieving Rockwell 85+ hardness displace steel in specialized slicing applications. Japanese sushi operations and plant-based protein processors in California adopt these for oxidation-free cuts where metallic taste transfer is unacceptable.
- Carbon Steel:Higher carbon content enables sharper edge geometry but demands active maintenance to prevent rust. Traditional European craft butchers in Spain and Germany retain preference for hand-forged carbon blades in dry-aging rooms where patina development signals professional authenticity.
- Plastic:Glass-reinforced nylon and high-density polyethylene handles dominate disposable and color-coded kitchen systems. Quick-service restaurant chains in India specify these for cross-contamination prevention protocols in high-turnover training environments.
Volume dominance: Stainless Steel. Steepest expansion trajectory: Ceramic.
Application:
End-use environment severity determines blade specification tiering from premium forged to stamped economy alternatives.
- Restaurants:Open-kitchen concepts in London and New York drive procurement toward visually distinctive blade finishes and ergonomic handle designs. Visibility requirements compress tolerance for cosmetic defects that hidden back-of-house operations might absorb.
- Food Processing:Industrial-scale operations prioritize durability over weight, specifying thicker spine dimensions and polymer handles that withstand automated sanitation cycles. USDA-inspected facilities in the US mandate NSF certification for all blade-contact surfaces.
- Catering Services:Mobile kitchen contexts favor lighter blade profiles and compact storage solutions. Event operators in Dubai and Singapore standardize on interchangeable blade systems that reduce transport weight while maintaining prep capability diversity.
- Delis:Slicing-dominant workflows concentrate demand on long, thin blades with granton edges that reduce protein adhesion. Italian salumeria traditions sustain specialized procurement channels for hand-honed carbon steel in dry-cured meat applications.
Procurement scale leader: Food Processing. Premiumization focus: Restaurants.
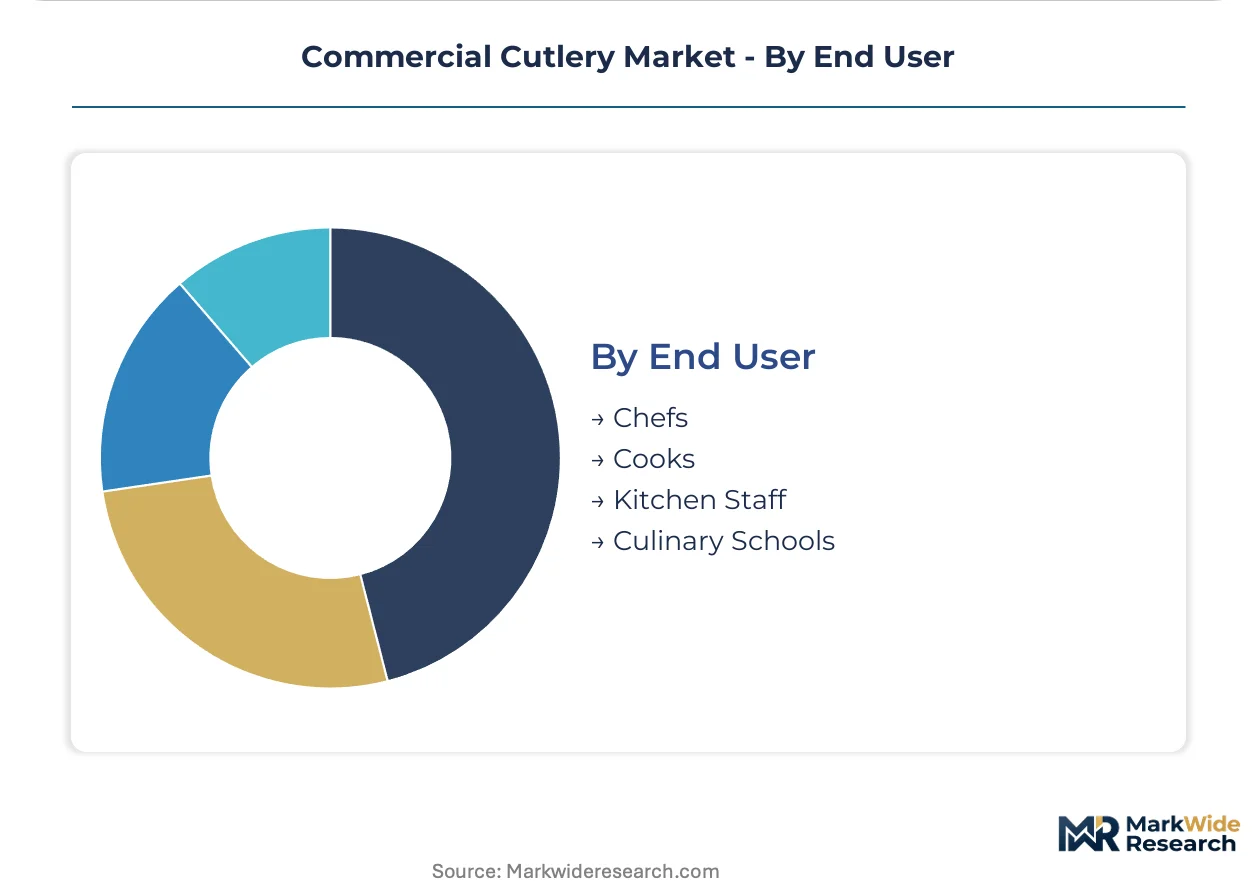
End User:
Skill level and training investment create divergent price sensitivity patterns across user categories.
- Chefs:Executive-level practitioners in Michelin-starred kitchens source personalized blade profiles through direct Solingen atelier relationships. Individual specification of spine thickness, handle material, and edge geometry sustains premium pricing tiers.
- Culinary Schools:North American training institutions standardize on value-tier forged blades from Mercer Tool Corp. that withstand repeated student misuse while delivering consistent edge geometry for technique instruction.
- Cooks:Line-level kitchen staff operate employer-provided inventory where durability and replaceability outweigh individual preference. Multi-unit restaurant groups mandate unified specifications across this user tier to simplify procurement and reduce theft exposure.
- Kitchen Staff:Entry-level and support roles utilize basic stamped blades with molded handles that minimize capital risk in high-turnover employment contexts. Color-coded polymer handles support HACCP compliance in large-scale institutional feeding operations.
Specification authority: Chefs. Volume concentration: Kitchen Staff.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial cutlery craftsmanship traces its industrial origins to Solingen, Germany, where water-powered grinding workshops emerged in the medieval period. This heritage cluster established metallurgical standards that persist across contemporary global production. Demand patterns now diverge across regulatory environments and foodservice development stages.
Germany
Restaurant chains operating open-kitchen concepts in Berlin and Munich specify Rockwell 58-60 HRC blades with distinctive finishes for guest visibility. The EU F-Gas Regulation forces heat-treatment facilities in Solingen to retrofit furnaces with hydrogen-based atmospheres. This regulatory pressure concentrates capital deployment in energy-efficient metallurgy within the historic craft cluster.
United States
Multi-unit restaurant groups exceeding 200 locations mandate unified specifications and handle color-coding systems to simplify procurement. FDA food-contact surface regulations and NSF International certification standards govern blade materials and handle sanitation design. Culinary schools across North America standardize on value-tier forged blades from Mercer Tool Corp. for technique instruction.
Japan
Sushi operations and plant-based protein processors adopt zirconium dioxide ceramic blades for oxidation-free cuts where metallic taste transfer is unacceptable. METI industrial standards support precision manufacturing in Seki, Gifu Prefecture. This blade-making cluster maintains apprenticeship pipelines and localized supply relationships for specialized slicing applications.
India
Organized restaurant chains in Mumbai and Bangalore establish central kitchens with standardized knife protocols, creating first-mover advantage for NSF-certified suppliers. FSSAI food safety regulations shape procurement specifications for commercial food preparation equipment. Quick-service chains specify glass-reinforced nylon handles for cross-contamination prevention in high-turnover training environments.
Italy
Italian salumeria traditions sustain specialized procurement channels for hand-honed carbon steel in dry-cured meat applications. ECHA substance restrictions on chromium VI surface treatments force reformulation of passivation chemistries for European-bound inventory. Furnace operators in northern Italy replace nitrogen-methanol atmospheres with cracked ammonia systems to meet environmental compliance requirements.
Commercial Cutlery Market Competitive Environment
Premium-margin players sit above commodity-margin players across heritage positioning and certification tiers. The vendor base stratifies between Solingen-based heritage manufacturers, Japanese precision-forged specialists, and North American value-tier suppliers. Three archetypes dominate: craft-atelier brands leveraging geographic origin, scale manufacturers anchoring supply relationships with major restaurant groups, and value specialists targeting institutional procurement. Competitive moves concentrate on direct manufacturer agreements displacing fragmented distributor relationships, and furnace retrofit investments addressing EU F-Gas compliance.
Within the heritage-atelier tier, Zwilling J.A. Henckels and Wüsthof exemplify Solingen-origin positioning that sustains premium pricing in European foodservice channels. Mercer Tool Corp. occupies a position at the value-tier vector, anchoring supply relationships with North American culinary training institutions. These three entities represent the geographic and pricing stratification that structures competitive positioning across procurement segments.
| Leading Market Players |
|---|
| Zwilling J.A. Henckels |
| Kai Corp. |
| Victorinox |
| Friedr. Dick GmbH and Co. KG |
| MAC Knife Inc. |
| Wüsthof |
| Messermeister |
| Mercer Tool Corp. |
| Dexter-Russell |
| Others |
Value Chain & Pricing Dynamics
Multi-unit restaurant groups mandating unified Rockwell specifications and handle color-coding systems are compressing SKU diversity and forcing suppliers to consolidate production runs. This procurement concentration shifts pricing power toward buyers with volume scale while rewarding manufacturers who can absorb specification standardization costs.
Pricing Analysis
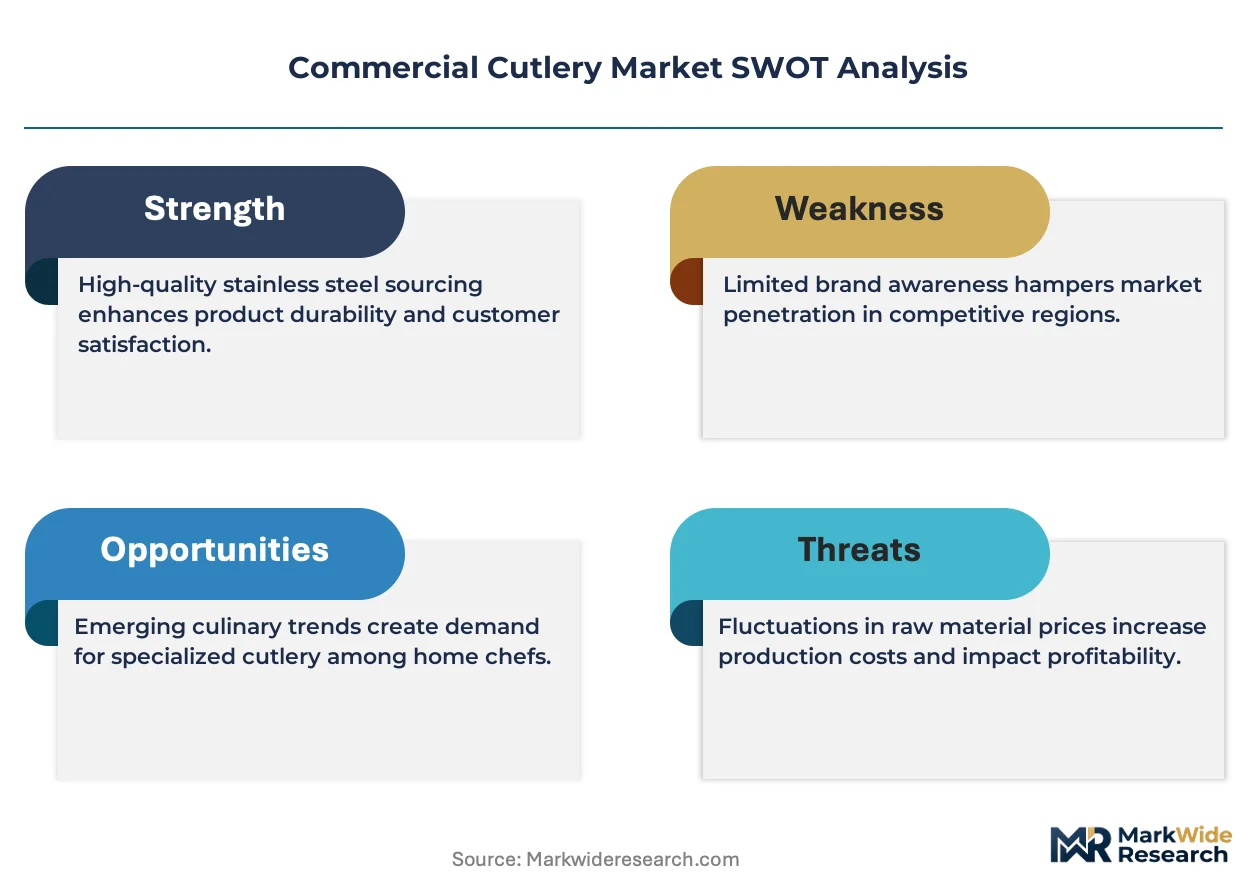
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and brand heritage. Solingen-origin manufacturers command premium positioning through geographic craft associations, while NSF certification tiers create price differentiation in US foodservice channels. Cost compression in the value tier is intensifying because South African molybdenum and Chinese vanadium concentrate volatility squeezes forged-blade margins. Culinary schools and high-turnover kitchen operations exhibit the highest price sensitivity, whereas executive chefs sourcing through direct atelier relationships demonstrate the lowest.
Supply Chain Analysis
Cobalt-alloyed steel supply rests on German specialty metallurgy producers and Japanese precision forgers in the Seki cluster. Blade manufacturing draws from South African molybdenum concentrate, Chinese vanadium feedstock, and Solingen-based heat treatment capacity. Single-source vulnerability concentrates in vacuum furnace availability for high-carbon stainless hardening, where retrofitting for EU F-Gas compliance has extended lead times. Distribution runs through direct manufacturer agreements with multi-unit restaurant groups, displacing fragmented distributor relationships at the procurement tier.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in commercial cutlery hinges on furnace energy efficiency gains and the premiumization of open-kitchen visibility specifications. Solingen heritage positioning and ceramic blade technology adoption create asymmetric upside for differentiated players.
For Market Incumbents: Deepen backward integration into cobalt-alloyed steel supply through captive relationships with German metallurgy specialists to defend against South African concentrate volatility. Expand direct manufacturer agreements with US fast-casual chains exceeding 200 locations to lock in specification consolidation benefits before competitors qualify. Prioritize hydrogen-based furnace retrofit investments to capture EU F-Gas compliance premiums. For New Entrants and Emerging Players: Enter via NSF certification for India's organized restaurant central kitchens in Mumbai and Bangalore, where standardized knife protocols create first-mover whitespace. Target mobile sharpening-as-a-service for casino and cruise line accounts that prioritize blade longevity over capital replacement. Position through water-cooled grinding system technology as a service-layer differentiator rather than blade manufacturing. For Investors and Strategic Acquirers: Asymmetric upside sits with ceramic blade specialists achieving Rockwell 85+ hardness formulations for Japanese sushi and California plant-based protein processing. Long-term viability over a 5-10 year window favors manufacturers with documented heat-treatment carbon footprints aligned to EU CSRD disclosure mandates. Watch for inflection in mobile honing unit penetration rates as a signal of service-layer revenue sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Based Furnace Retrofit | EU F-Gas compliance unlocks premium positioning in Solingen heritage manufacturing clusters. |
| Direct Manufacturer Agreement | Multi-unit restaurant groups in the US and UK consolidate procurement through unified specification mandates. |
| Ceramic Blade Scale-Up | Zirconium dioxide formulations at Rockwell 85+ hardness displace steel in oxidation-sensitive slicing applications. |
| Mobile Sharpening Service Launch | Water-cooled grinding systems penetrate casino and cruise line accounts prioritizing blade longevity. |
| CSRD-Aligned Carbon Disclosure | Documented recycled content and heat-treatment footprints satisfy European operator sustainability reporting mandates. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both procurement volume patterns and specification evolution dynamics. Primary engagement with executive chefs, culinary school procurement directors, restaurant group supply chain managers, and heat treatment facility operators informed demand-side segmentation. Secondary validation drew from FDA food-contact surface filings, NSF International certification databases, EU ECHA substance restriction updates, and trade flow data for molybdenum and vanadium concentrates. Bottom-up blade shipment analysis triangulated against top-down foodservice equipment expenditure estimates.
Historical reference periods anchored the projection horizon through documented specification shifts and regulatory implementation timelines. The analytical framework modeled segmentation across product type, material composition, application environment, and end-user skill tier, with additional dimensioning for regional regulatory cluster effects. CAGRs derived from fitted growth curves applied to validated baseline volumes, incorporating EU F-Gas furnace retrofit adoption curves and ceramic blade penetration rates in specialized slicing applications as industry-specific inputs.
Inputs from primary stakeholder interviews and secondary regulatory filings were available through the study window; gaps in real-time heat treatment capacity utilization data introduce uncertainty bands around precision-forged order lead time assumptions. Forecasts reflect documented specification consolidation trends and sustainability disclosure mandate expansion trajectories. Supply chain disruption from South African mining logistics or ECHA substance restriction amendments warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Saudi Arabia Pizza Restaurants Market
Food Service
North America Food Service Market
Food Service
Supermarkets Market
Food Service
Pasteurized Eggs Market
Food Service
West Africa Food Services Market
Food Service
India Foodservice Market
Food Service
Food Away from Home Market
Food Service
India Quick Service Restaurant Market
Food Service
Contract Blending Services Market
Food Service
Global Vending Machine Market
Food Service
Europe Inflight Catering Market
Food Service
Spain Food Service Market
Food Service
Instant Noodle Vending Machine Market
Food Service
Italy Foodservice Market
Food Service
Global Dark Store Market
Food Service
Mexico Foodservice Market