
 United States Cafes & Bars Market | 2026-2036
United States Cafes & Bars Market Size, Share, and Industry Trends Forecast 2026-2036
United States Cafes & Bars Market Insights
Texas is reshaping competitive dynamics through aggressive drive-thru expansion and labor market scale. Starbucks Corporation leverages its vertically integrated roasting network to sustain supply consistency across high-traffic corridors. Dutch Bros Inc. anchors growth in Sun Belt suburbs with compact formats and speed-of-service metrics. Dunkin' competes on value-tier breakfast attachment and franchisee density in Eastern and Midwestern markets.
United States cafes and bars encompass licensed foodservice establishments serving prepared beverages and light fare, operating equipment ranging from commercial espresso machines producing 9-bar extraction pressure to draft systems maintaining 38°F serving temperature for carbonated products. The primary commercial purpose centers on delivering repeatable, branded consumption experiences to transient and habitual clientele. Espresso and cold brew formats within product type segmentation dominate morning dayparts and capture premium pricing, while cocktails sustain evening margin pools through ingredient markup architecture. The service model dimension shows delivery and takeaway accelerating fastest, though dine-in retains loyalty program attach rates and average ticket elevation across upscale atmosphere classifications.
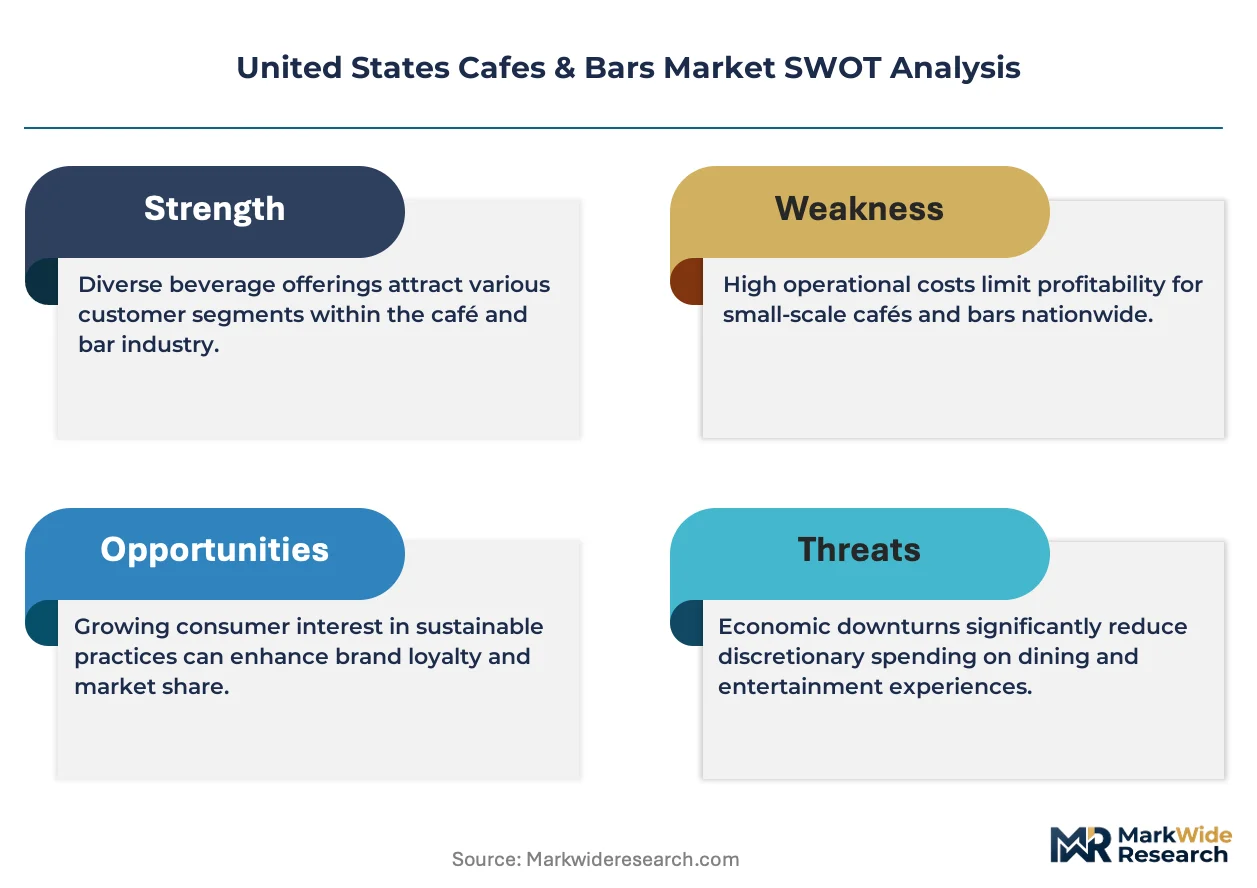
FDA food code compliance, state alcohol beverage control licensing, and local health department inspection grading shape operational viability and capital requirements for new entrants. OSHA workplace safety standards and EPA grease disposal regulations further constrain site selection and back-of-house design. Stakeholders must monitor labor cost trajectories and alcohol-to-coffee revenue mix shifts as automation investments and consumer occasion fragmentation redefine unit economics.
Market Dynamics
Drive-thru format proliferation across Texas and Florida metros is compressing real estate footprints while elevating throughput velocity as the dominant competitive axis for US cafes and bars.
Growth Catalysts
- OSHA workplace safety standards:Elevated compliance protocols reduce incident liability and lower insurance premiums for multi-unit operators.
- EPA grease disposal regulations:Mandated interceptor installations create barriers to entry that protect incumbent market positions in dense urban corridors.
- Young professionals in California metros:Sustained morning coffee ritual density supports premium pricing power for espresso and cold brew formats.
Market Restraints
- Arabica coffee bean price volatility:Weather-driven harvest disruptions in Brazil and Colombia transmit directly to margin compression.
- Alcohol beverage control licensing:State-by-state variance creates capital-intensive expansion timelines and franchisee qualification bottlenecks.
- Commercial real estate concentration:Limited drive-thru-zoned parcels in Texas and Florida metros inflate site acquisition costs.
Strategic Opportunities
- Suburban Sun Belt corridors:Underpenetrated exurban zones around Dallas-Fort Worth and Tampa-St. Petersburg offer format experimentation space.
- Automation-integrated service models:Convergence of mobile ordering platforms with robotic beverage preparation compresses labor cost trajectories.
- IRA clean energy incentives:Tax credits for energy-efficient equipment retrofits reduce capex burdens for refrigeration and HVAC upgrades.
Industry Challenges
- Barista skill scarcity:Labor market tightness in craft cocktail and specialty espresso preparation limits service consistency across expansion markets.
- Multi-jurisdiction compliance complexity:FDA food code alignment with county-level health department grading systems demands dedicated regulatory staffing.
- Legacy POS integration friction:Third-party delivery platform APIs conflict with established loyalty program architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Cafes & Bars Market |
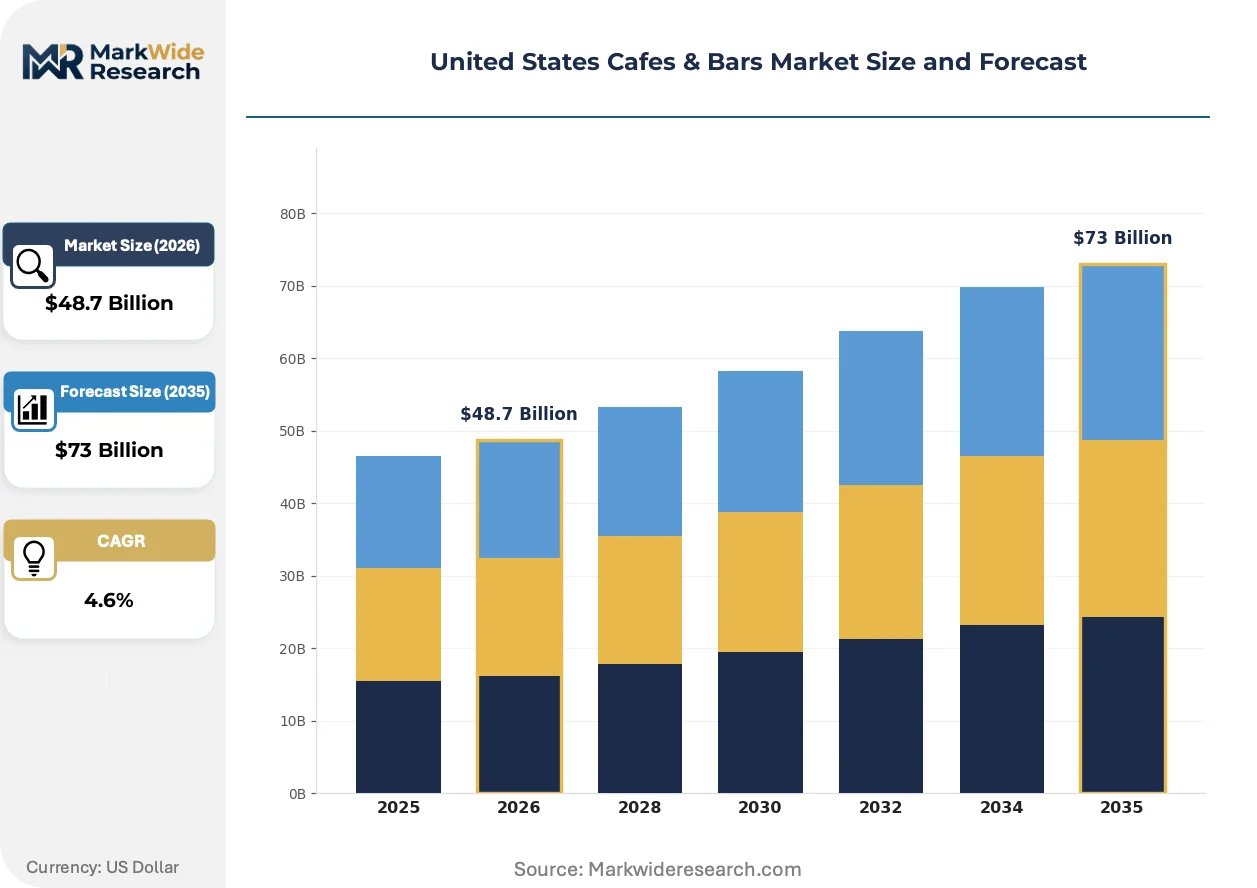
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $73 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Espresso, Cold Brew, Cocktails, Smoothies Service Model: Dine-In, Takeaway, Delivery, Catering Customer Type: Students, Professionals, Tourists, Families Atmosphere: Casual, Upscale, Themed, Outdoor |
| Companies Covered | Starbucks Corporation, Dunkin', Dutch Bros Inc., Tim Hortons, Caribou Coffee, Peet's Coffee, Blue Bottle Coffee, 7 Brew Coffee, BIGGBY Coffee, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Cafes & Bars Market Trends and Innovations
Digital ordering infrastructure and automated production systems are compressing service cycle times while fragmentating consumer touchpoints across physical and virtual environments.
Cloud-based kitchen display systems with predictive analytics engines are virtualizing order sequencing and inventory coordination. Multi-unit operators in California and Texas metros deploy these platforms to synchronize drive-thru throughput with mobile pickup staging. The technology is virtualizing traditional front-of-house labor allocation, compressing headcount per transaction while maintaining speed-of-service metrics.
FDA food code updates emphasizing temperature monitoring digitization are mandating IoT sensor deployment across cold chain equipment. California and Florida health departments now require automated HACCP logging for grade-A certification. Full-service cocktail lounges and high-volume coffee chains face the steepest compliance capital requirements, accelerating vendor consolidation around integrated compliance-as-a-service platforms.
Subscription-based beverage programs are displacing transactional purchasing patterns among habitual morning consumers. Corporate account channels and residential delivery services capture recurring revenue streams that traditional walk-in traffic cannot replicate. This shift concentrates most visibly in Austin, Miami, and Los Angeles metros where employer-subsidized coffee allowances and remote work routines normalize daily delivery scheduling.
United States Cafes & Bars Market Segmentation
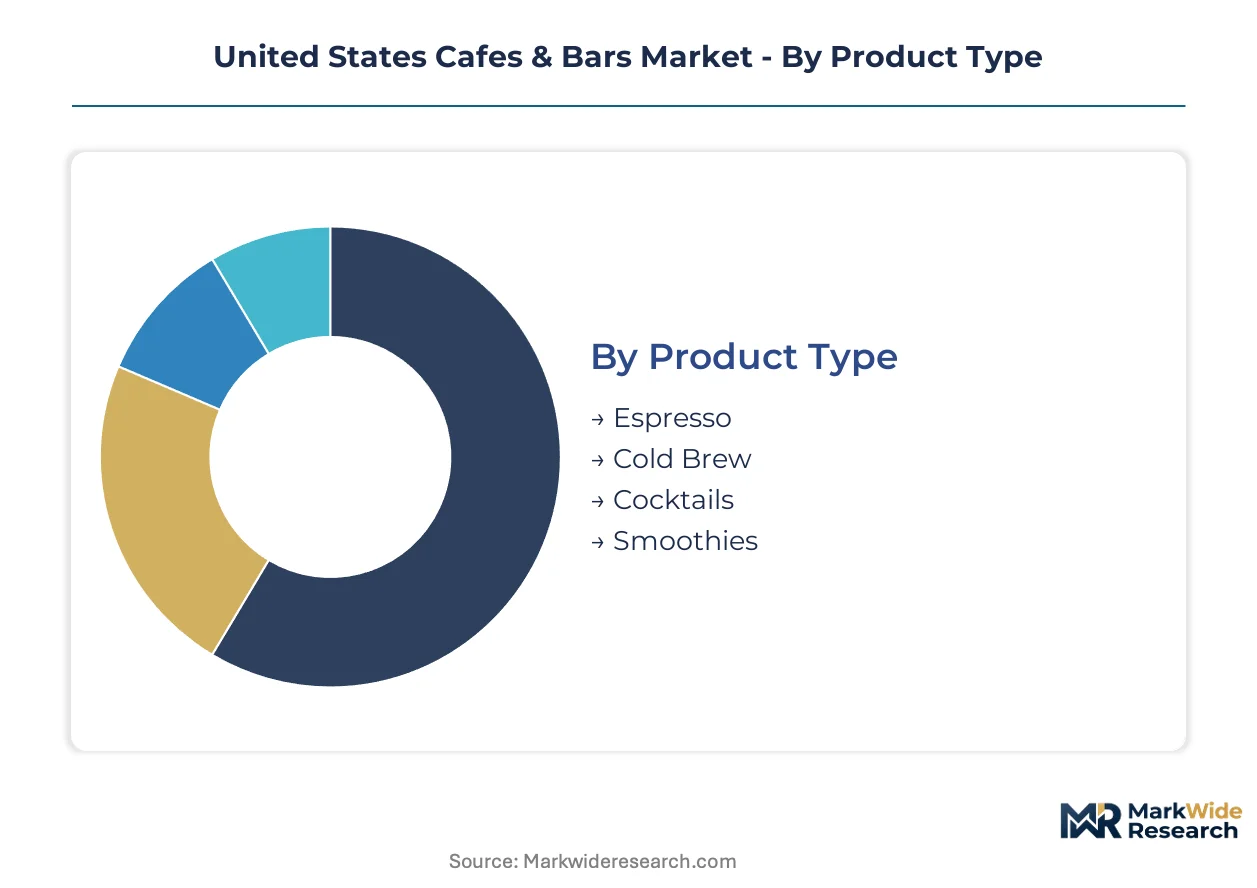
Segmentation in United States cafes and bars reveals divergent margin architectures across dayparts and service formats. Operators calibrate equipment investments, labor deployment, and real estate footprints to match distinct consumption occasions and customer lifetime value profiles.
Product Type:
Mature espresso and cocktail formats anchor revenue stability while emerging cold brew and smoothie categories reshape growth trajectories.
- Espresso:Nine-bar extraction systems produce concentrated coffee through pressurized hot water forced through finely ground arabica. Morning ritual density in California metros sustains premium pricing power despite equipment-intensive bar labor requirements.
- Cocktails:Spirit-forward and craft mixed beverages command ingredient markup multiples through evening occasion positioning. Texas and Florida lounge operators capture extended dwell-time revenue through experiential presentation formats.
- Cold Brew:Extended steeping at ambient temperature yields lower-acidity coffee concentrate served chilled or nitro-infused.
- Smoothies:Blended fruit and dairy or plant-based beverages target health-positioned dayparts with seasonal ingredient volatility.
Espresso retains volume leadership; cold brew holds the steepest expansion curve.
Service Model:
Cost tier differentiation separates capital-light formats from real estate-intensive operations with divergent break-even thresholds.
- Takeaway:Counter-service and drive-thru formats compress real estate costs while maximizing throughput velocity. Dutch Bros and similar operators in Sun Belt suburbs scale unit economics through sub-400-square-foot prototypes.
- Delivery:Third-party platform integration and dedicated ghost kitchen infrastructure fragment traditional storefront dependency. Mobile ordering convergence with predictive staging algorithms compresses customer wait times in Austin and Miami metros.
- Dine-In:Full-service seating with atmosphere-driven experience design commands ticket elevation through extended dwell time.
- Catering:B2B and event-based beverage service captures volume concentration with demand cyclicality tied to corporate and social calendar patterns.
Takeaway commands transaction volume density; delivery is climbing the fastest among service model investments.
Customer Type:
Application-based segmentation aligns product mix and daypart strategy with distinct occasion patterns and spending elasticity.
- Professionals:Habitual morning coffee rituals with employer-subsidized allowances drive subscription and corporate account penetration. Austin, Los Angeles, and Miami metros exhibit the highest recurring revenue attachment rates.
- Students:Price-sensitive frequency with extended dwell-time expectations shapes value-tier positioning and WiFi-enabled seating design.
- Tourists:Destination-driven trial behavior with low repeat probability favors iconic location capture and Instagram-optimized presentation.
- Families:Multi-generational occasion clustering demands menu breadth spanning adult beverages and child-friendly alternatives.
Professionals dominate revenue per visit; students represent the highest frequency engagement segment.
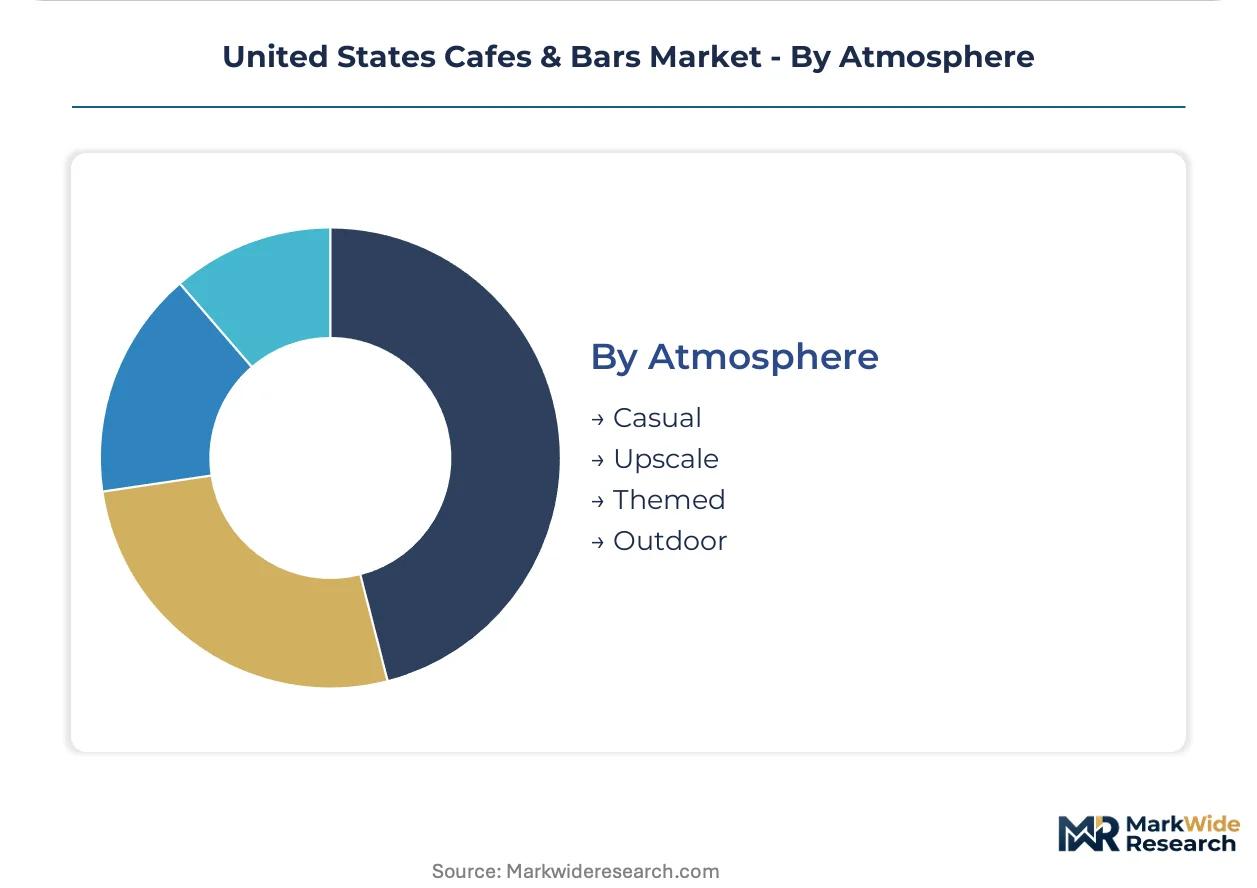
Atmosphere:
Margin stratification across experience tiers separates utility-driven transactions from premium positioning through design investment.
- Casual:Functional seating with minimal service layer supports throughput-focused operations in suburban and highway-adjacent locations. Starbucks and Dunkin' franchisees optimize this format for repeat convenience purchasing.
- Upscale:Curated interior design, craft cocktail programs, and trained service staff elevate average ticket through occasion premiumization. Miami and Los Angeles cocktail lounges concentrate competitive intensity in this tier.
- Themed:Concept-driven environments—speakeasy, literary, or entertainment-anchored—differentiate through experiential novelty with higher capital refresh cycles.
- Outdoor:Patio and sidewalk seating configurations capture weather-dependent demand elasticity with lower square-foot costs.
Casual atmosphere retains location count leadership; upscale formats deliver the steepest margin per square foot.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate Highway System and Class I rail corridors linking the Gulf Coast to the Midwest underpin distribution velocity for coffee roasting and spirits logistics across the United States.
California
San Francisco Bay Area and Los Angeles Basin clusters concentrate premium espresso roasting capacity and craft cocktail innovation. FDA food code compliance costs escalate with Los Angeles County health department grade posting mandates. San Diego's brewery district conversion to coffee-forward mixed-use developments signals format experimentation.
Texas
Dallas-Fort Worth and Houston metros anchor drive-thru format proliferation with sub-400-square-foot prototypes scaling rapidly. OSHA workplace safety standards elevate training costs for multi-unit operators expanding across Austin and San Antonio corridors. Interstate 35 corridor development concentrates new entrant activity between Waco and Temple.
Florida
Miami-Dade and Tampa-St. Petersburg markets sustain evening cocktail lounge density alongside morning coffee throughput. State alcohol beverage control licensing creates franchisee qualification bottlenecks for Tampa Bay expansion. Orlando's tourist corridor generates destination-driven trial volume with limited repeat probability.
New York Metro
Manhattan and Brooklyn preserve dine-in atmosphere premiums through curated interior design and extended dwell-time economics. EPA grease disposal regulations constrain back-of-house configurations in older building stock across the five boroughs. Hudson Valley satellite locations capture remote-work professionals migrating from core density.
Pacific Northwest
Seattle and Portland metros maintain specialty coffee origin positioning with roasting heritage and third-wave culture density. IRA clean energy incentives reduce refrigeration and HVAC capex burdens for equipment retrofits in Oregon and Washington. Boise and Spokane emerging as secondary market spillover zones.
United States Cafes & Bars Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with equipment and ingredient supply. The United States cafes and bars market structures around three tiers: national scale operators with vertically integrated roasting networks, regional drive-thru specialists optimizing throughput velocity, and boutique atmosphere-driven concepts capturing premium positioning. Strategic moves concentrate on real estate format compression and automation-integrated service model deployment.
Among publicly traded platform operators, Starbucks Corporation and Dutch Bros Inc. exemplify divergent format strategies—roasting-integrated national density versus Sun Belt suburban drive-thru specialization. Dunkin' occupies a position within value-tier breakfast attachment and Eastern franchisee density. These three anchors represent distinct archetypes: supply chain captivity, speed-of-service metrics, and price-positioned frequency.
| Leading Market Players |
|---|
| Starbucks Corporation |
| Dunkin' |
| Dutch Bros Inc. |
| Tim Hortons |
| Caribou Coffee |
| Peet's Coffee |
| Blue Bottle Coffee |
| 7 Brew Coffee |
| BIGGBY Coffee |
| Others |
Pricing and Supply Chain Analysis
Seattle's vertically integrated roasting cluster anchors arabica coffee pricing power through captive green bean procurement networks that insulate regional operators from C-market volatility. Downstream margin compression in Sun Belt drive-thru markets feeds back into equipment standardization decisions that favor single-origin contract stability over spot-market flexibility.
Pricing Analysis
Volume-discount tiering structures separate national account subscription pricing from transactional walk-in rates across the morning daypart. Premium-mid-economy pricing differentiation rests on espresso equipment investment depth and barista certification levels rather than ingredient cost alone. Cost compression in value-tier breakfast attachment is intensifying because Dunkin' franchisees leverage frozen dough centralization against craft coffee labor intensity. Students represent the most price-sensitive buyer archetype; corporate professionals with employer-subsidized allowances exhibit the least.
Supply Chain Analysis
Contract-manufacturing concentration for commercial espresso equipment centers on Italian OEMs and Chinese component foundries serving roasting system assembly. Green arabica sourcing draws from Brazil, Colombia, and Ethiopia with harvest timing staggered across hemispheres. Single-source vulnerability concentrates in Brazilian weather-dependent crop cycles that transmit directly to margin volatility. Distribution runs through Class I rail corridors to regional roasting hubs, then Interstate Highway System trucking to last-mile distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based beverage programs and employer-subsidized corporate accounts are expanding faster than equipment-heavy dine-in format rollouts, reframing this market as a service-attach opportunity with recurring revenue durability.
For Market Incumbents: Harden drive-thru throughput advantages through predictive mobile order staging algorithms that compress service cycle times below emerging competitor reach. Deepen backward integration into green bean procurement networks to defend margin position against arabica price volatility. Consolidate around cloud-based kitchen display systems that virtualize labor allocation across multi-unit footprints. For New Entrants and Emerging Players: Pursue underpenetrated exurban corridors around Dallas-Fort Worth and Tampa-St. Petersburg where drive-thru zoning availability exceeds incumbent saturation density. Target the professional customer segment with employer-subsidized subscription models that bypass transactional frequency building. Deploy compact sub-400-square-foot prototypes with speed-of-service metrics as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automation-integrated service models with robotic beverage preparation and IoT-enabled compliance logging. Long-term viability across the analysis window hinges on recurring revenue attachment rates rather than unit count expansion alone. Monitor barista skill scarcity indices and mobile order penetration rates as inflection indicators for labor cost trajectory shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Drive-Thru Format Proliferation | Sub-400-square-foot prototypes in Texas and Florida metros compress real estate costs while elevating throughput velocity metrics. |
| Subscription Program Launch | Employer-subsidized corporate accounts in Austin, Miami, and Los Angeles normalize daily delivery scheduling with recurring revenue durability. |
| Automation Integration | Robotic beverage preparation converges with mobile ordering platforms to compress labor cost trajectories across Sun Belt expansion markets. |
| Backward Integration into Roasting | Vertically integrated roasting networks insulate margin position from Brazilian weather-driven arabica price volatility transmission. |
| Regulatory Compliance Platform | IoT-enabled HACCP logging satisfies FDA food code digitization mandates for grade-A certification in California and Florida health departments. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with multi-unit franchise operators, roasting facility managers, and state alcohol beverage control licensing administrators; and secondary validation through FDA food code filings, state health department inspection databases, and SEC 10-K disclosures from publicly traded platform operators. Bottom-up unit economics modeling triangulated against top-down market sizing from trade association membership data and commercial real estate transaction records.
Forecast inputs span product type segmentation across espresso, cold brew, cocktail, and smoothie formats; service model differentiation between takeaway, delivery, dine-in, and catering; and customer type clustering around professionals, students, tourists, and families. CAGRs were derived from trend extrapolation anchored in observed daypart density and format penetration rates. Arabica futures curve shape and drive-thru zoning permit velocity in Texas and Florida metros served as industry-specific demand and supply-side calibration inputs.
The forecast holds incumbent behavior within observed patterns; aggressive automation deployment by emerging drive-thru specialists or abrupt shifts in employer-subsidized beverage allowances would shift outcomes beyond modeled ranges. Quarterly review of mobile order penetration rates, barista wage inflation indices, and green arabica futures curve backwardation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Commercial Grills Market
Food Service
Europe Vending Machine Market
Food Service
Catering Food Warmers Market
Food Service
India Online Grocery Market
Food Service
Global Sushi Restaurants Market
Food Service
Limited-Service Restaurants Market
Food Service
Saudi Arabia Full- Service Restaurants Market
Food Service
Haute Cuisine Market
Food Service
Singapore Food Service Market
Food Service
Contract Catering Market
Food Service
Foodservice Coffee Market
Food Service
Global Cafe and Bars Market
Food Service
Japan Foodservice Market
Food Service
Asia-Pacific and Middle-East Inflight Catering Market
Food Service
Popcorn Making Cart Market
Food Service
Smokeless Grill Market