
 Electrostatic Chucks Market | 2026-2036
Electrostatic Chucks Market Size, Share, and Industry Trends Forecast 2026-2036
Electrostatic Chucks Market Analysis
Monolithic ceramic-to-metal bonding is tilting electrostatic chuck architecture toward higher thermal uniformity and longer service intervals. Kyocera Corporation leverages its alumina and aluminum nitride ceramics portfolio to anchor high-purity substrate supply for chuck manufacturers. Shinko Electric Industries Co., Ltd. sustains dominance in Japan's captive semiconductor equipment chain through precision metallization capabilities. Applied Materials, Inc. competes by integrating chuck design with its broader wafer-processing platform, controlling end-to-end thermal management specifications.
An electrostatic chuck is a specialized workholding device that uses electrostatic force to clamp semiconductor wafers, flat-panel substrates, or precision components during vacuum-based processing, typically constructed from ceramic dielectric layers with embedded electrodes operating at voltages between 500V and 2000V. Its primary industrial purpose is to enable uniform thermal contact and eliminate mechanical stress during plasma etch, deposition, and ion implantation steps. Wafer chucks occupy the largest value share due to their irreplaceable role in 300mm foundry lines, while electrostatic holders represent the fastest-growing category as photovoltaic cell manufacturers adopt float-zone and directional solidification platforms requiring non-contact wafer fixation. Low voltage technology leads in new equipment design for sub-7nm nodes where electrostatic discharge sensitivity constrains high-voltage architectures.
The US CHIPS Act and the EU Chips Act are reshaping where electrostatic chuck demand materializes, with domestic content requirements pushing foundries toward qualified local suppliers. Japan's METI coordinates national semiconductor equipment standards through JIS frameworks that govern chuck surface roughness and particle generation thresholds. China's MIIT enforces GB standards for imported deposition equipment, creating compliance barriers for non-domestic chuck vendors. Stakeholders must monitor how divergent subsidy eligibility rules across Washington, Brussels, and Tokyo fragment procurement specifications and test protocols.
Market Dynamics
Semiconductor foundries in Taiwan and South Korea are expanding 300mm wafer-handling capacity at unprecedented rates, pulling electrostatic chuck architecture toward higher thermal uniformity specifications and longer service intervals between chamber maintenance cycles.
Growth Catalysts
- US CHIPS Act domestic content mandates:Foundries in Arizona and Texas must qualify local suppliers for deposition and etch equipment, accelerating certification timelines for electrostatic chuck vendors establishing US manufacturing footprints.
- Sub-7nm node proliferation:Advanced logic production requires low-voltage electrostatic chuck designs that minimize electrostatic discharge damage during high-aspect-ratio etch processes.
- Photovoltaic cell manufacturing expansion:Float-zone and directional solidification platforms for high-efficiency solar cells are adopting electrostatic holders for non-contact wafer fixation in crystal growth furnaces.
Market Restraints
- High-purity ceramic substrate concentration:Alumina and aluminum nitride supply chains concentrate among Japanese and German specialty ceramic producers, creating input bottlenecks during capacity expansion cycles.
- Plasma erosion limitations:Dielectric surface degradation in fluorine-based chemistries limits chuck service life in 3D NAND stack etch applications, forcing premature replacement cycles.
- China GB standards compliance friction:MIIT-mandated testing protocols for imported deposition equipment create technical barriers and extended qualification timelines for non-domestic chuck manufacturers.
Strategic Opportunities
- India semiconductor fabrication incentives:PLI scheme subsidies for display and chip manufacturing are attracting electrostatic chuck vendors to establish local service and refurbishment capabilities ahead of fabs in Gujarat and Assam.
- Compound semiconductor expansion:Silicon carbide and gallium nitride wafer processing for power electronics requires electrostatic chucks with modified thermal expansion coefficients and higher temperature stability.
- EU Chips Act green procurement mandates:CSRD-aligned sustainability reporting requirements for semiconductor equipment are favoring chuck suppliers with verified carbon footprint data and circular material recovery programs.
Industry Challenges
- Plasma process engineer scarcity:Specialized expertise in electrostatic chuck surface conditioning and particle management is concentrated among veteran technicians at established foundries, constraining new fab startup velocity.
- Multi-generational equipment integration:Legacy 200mm tool platforms require mechanical retrofits to accommodate advanced chuck designs with embedded temperature sensing, complicating upgrade economics.
- Cleanroom certification timeline compression:Accelerated fab construction schedules in Taiwan and Arizona are compressing chuck qualification windows, risking yield ramp delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrostatic Chucks Market |
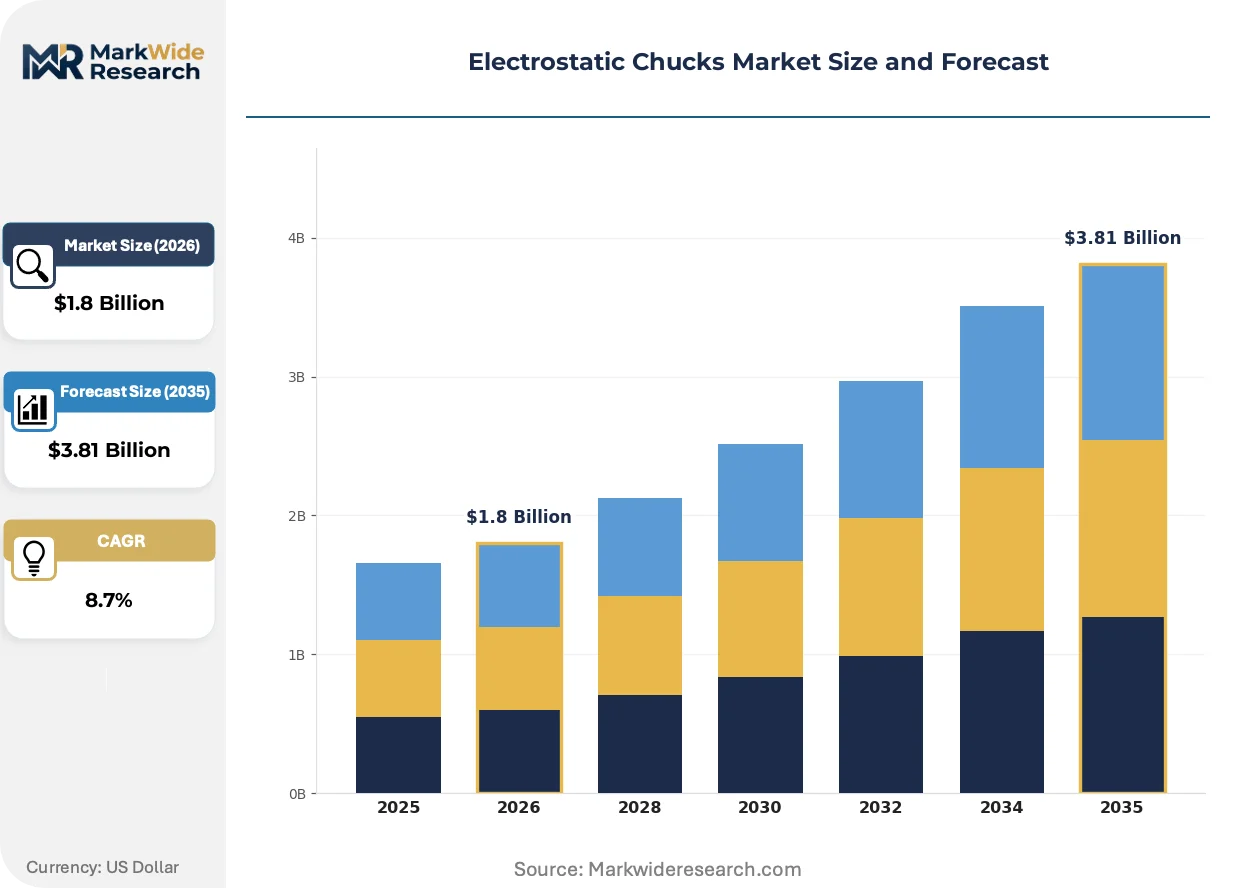
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wafer Chucks, Fixture Chucks, Electrostatic Holders, Target Chucks Application: Semiconductor Manufacturing, Photovoltaics Production, Display Fabrication, Precision Engineering Technology: High Voltage Technology, Low Voltage Technology, AC Technology, Capacitive Technology End User: Foundries, OEMs, Research Institutes, Electronics Manufacturers |
| Companies Covered | Shinko Electric Industries Co., Ltd., NGK Insulators, Ltd., Applied Materials, Inc., NTK CERATEC Co., Ltd., TOTO Ltd., Lam Research Corporation, Kyocera Corporation, Sumitomo Osaka Cement Co., Ltd., Entegris, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrostatic Chucks Market Emerging Trajectories
Electrostatic chuck technology is bifurcating between ultra-high-purity monolithic designs for leading-edge logic and cost-optimized configurations for mature-node and photovoltaic applications, with digitization of thermal management emerging as the defining architectural shift.
Monolithic ceramic-to-metal bonding is digitizing thermal uniformity control across 300mm wafer surfaces by embedding distributed temperature sensors directly within alumina and aluminum nitride dielectric layers. Foundries in Taiwan and South Korea are adopting these instrumented chucks for sub-5nm gate-all-around transistor processing. The technology is digitizing what were previously analog thermal compensation routines, compressing process development cycles and reducing particle defects from thermal gradients.
Japan's METI has revised JIS B 9920 surface roughness standards for electrostatic chucks used in EUV lithography proximity tools, mandating sub-nanometer Ra specifications and standardized particle generation test protocols. Equipment vendors must now submit third-party certification for chuck surface integrity before METI subsidy eligibility. Japanese captive equipment chains are responding by consolidating metrology capabilities in Yokohama and Kyoto certification centers.
After-sales service unbundling is fragmenting traditional equipment vendor relationships as foundries in Singapore and Ireland negotiate direct electrostatic chuck refurbishment contracts with ceramic specialists. Third-party remanufacturing shops in Penang and Dresden are capturing service revenue previously retained by original equipment manufacturers. This pattern is most visible among memory producers with large installed bases of 200mm and 300mm etch platforms seeking to extend chuck service life beyond OEM warranty periods.
Electrostatic Chucks Market Segmentation
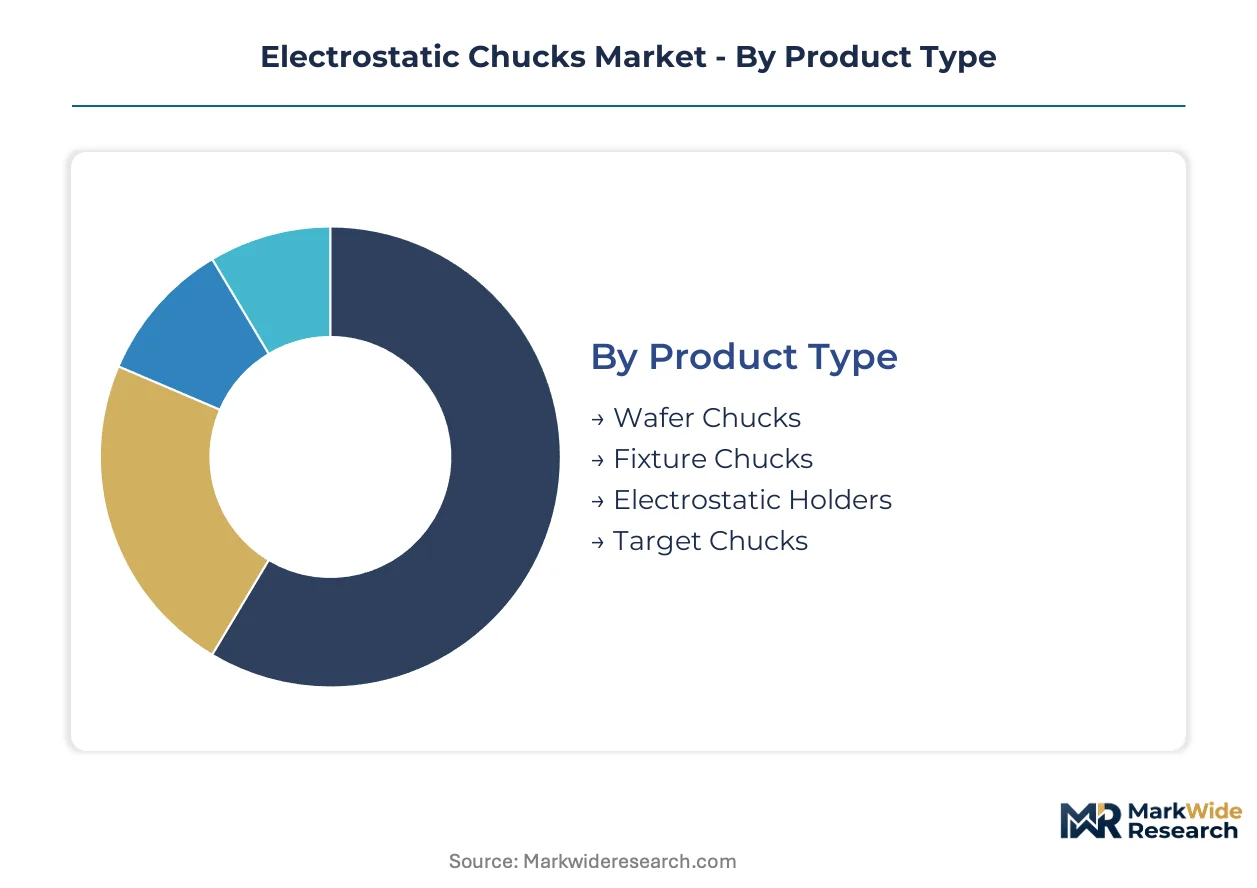
Electrostatic chuck architecture varies sharply across process requirements, voltage sensitivity, and thermal management specifications. Each segmentation dimension reveals distinct procurement patterns and supplier qualification barriers that shape vendor strategy.
Product Type:
Cost tier separates commodity handling platforms from precision wafer-processing systems requiring ceramic purity certification.
- Wafer Chucks:Monolithic alumina or aluminum nitride dielectric layers with embedded electrodes clamp 300mm silicon wafers during plasma etch and deposition. Foundries in Taiwan and South Korea specify sub-nanometer surface roughness for sub-7nm node production, driving premium pricing for certified suppliers.
- Electrostatic Holders:Non-contact fixation systems for float-zone crystal growth and directional solidification furnaces in photovoltaic manufacturing. Solar cell producers in China and Southeast Asia are adopting these holders to reduce mechanical stress during high-efficiency silicon ingot production.
- Fixture Chucks:General-purpose workholding for flat-panel substrate processing.
- Target Chucks:Specialized clamping for sputtering target alignment in thin-film deposition.
Wafer chucks command the established base. The steepest expansion runs through electrostatic holders.
Application:
Process thermal budget and contamination sensitivity create divergent specification corridors across manufacturing verticals.
- Semiconductor Manufacturing:Plasma etch, chemical vapor deposition, and ion implantation processes require electrostatic chucks with embedded temperature sensors and fluorine-resistant dielectric surfaces. The US CHIPS Act is accelerating qualification timelines for domestic suppliers serving Arizona and Texas fabs.
- Photovoltaics Production:Crystal growth furnaces and cell fabrication lines use modified chuck designs with higher thermal expansion tolerance. Chinese manufacturers under MIIT GB standards are driving volume demand for cost-optimized configurations.
- Display Fabrication:Large-area substrate handling for OLED and LCD production.
- Precision Engineering:Optical component and MEMS device manufacturing requiring sub-micron positioning stability.
Semiconductor manufacturing absorbs the dominant revenue share. Photovoltaics production is climbing the fastest as solar capacity expands.
Technology:
Voltage architecture selection hinges on electrostatic discharge sensitivity and process chemistry compatibility.
- Low Voltage Technology:Operating ranges between 500V and 800V minimize ESD damage during high-aspect-ratio etch of gate-all-around transistors. Sub-5nm foundries in Taiwan mandate low-voltage designs for advanced logic production.
- High Voltage Technology:1500V to 2000V systems deliver stronger clamping force for thick-film deposition and legacy node processing where ESD tolerance permits higher field strength.
- AC Technology:Alternating current excitation for specialized plasma uniformity control.
- Capacitive Technology:Dielectric barrier discharge configurations for specific etch chemistries.
High voltage technology retains the installed base. Low voltage technology is gaining share fastest from node migration.
End User:
Procurement authority and technical specification control vary dramatically across customer categories.
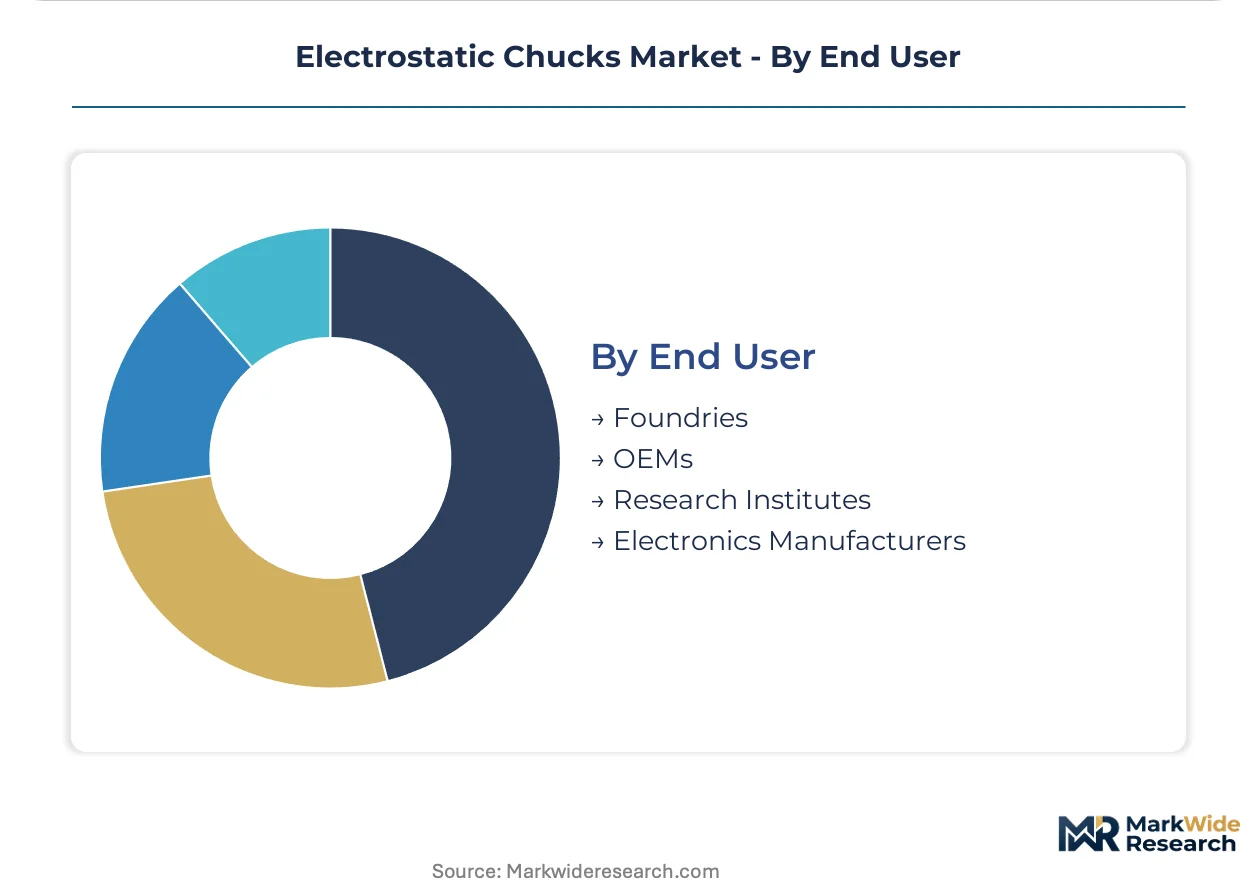
- Foundries:Taiwan Semiconductor Manufacturing and Samsung Electronics dictate chuck specifications directly, qualifying multiple vendors per tool platform to ensure supply security. These buyers negotiate multi-year service contracts with refurbishment rights.
- OEMs:Applied Materials and Tokyo Electron integrate proprietary chuck designs into complete wafer-processing platforms, controlling thermal management specifications end-to-end.
- Research Institutes:National laboratories and university cleanrooms purchase low-volume, high-customization units for process development.
- Electronics Manufacturers:Memory and logic producers with captive fabrication capacity.
Foundries command the specification authority. OEMs are expanding fastest through platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry buyers in Taiwan and South Korea concentrate procurement authority for electrostatic chucks, while equipment OEMs in the United States and Japan control thermal management specifications through platform integration. Domestic content mandates in Washington and Brussels are fragmenting supplier qualification pathways.
United States
Intel and TSMC are expanding 300mm fabrication capacity in Arizona, pulling demand for low-voltage electrostatic chuck designs compatible with sub-7nm production. The US CHIPS Act domestic content requirements accelerate certification timelines for suppliers establishing local manufacturing footprints. Phoenix and Austin clusters are compressing chuck qualification windows as fab construction schedules tighten.
Taiwan
TSMC and United Microelectronics dictate specifications directly, qualifying multiple vendors per tool platform to ensure supply security. The National Development Council coordinates industrial policy supporting advanced node expansion at the Hsinchu Science Park. Taichung and Tainan science parks are driving adoption of monolithic ceramic designs with embedded temperature sensors.
South Korea
Samsung Electronics and SK Hynix are expanding wafer-handling capacity at unprecedented rates, requiring higher thermal uniformity specifications. The Ministry of Trade, Industry and Energy administers K-Chips Act subsidies for domestic equipment supply chain development. Pyeongtaek and Yongin clusters are pulling architecture toward longer service intervals between chamber maintenance cycles.
Japan
Tokyo Electron and Shin-Etsu Chemical anchor captive equipment chains through precision metallization and ceramic substrate capabilities. METI revises JIS B 9920 surface roughness standards for EUV lithography proximity tools, mandating sub-nanometer Ra specifications. Yokohama and Kyoto certification centers are consolidating metrology capabilities for chuck surface integrity verification.
China
Yangtze Memory Technologies and SMIC are scaling domestic deposition and etch equipment procurement under import substitution directives. MIIT enforces GB standards for imported deposition equipment, creating compliance barriers for non-domestic chuck vendors. Shanghai and Beijing clusters are developing local ceramic supply chains for aluminum nitride substrate production.
Electrostatic Chucks Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three structural tiers. Equipment OEMs with captive chuck design capabilities capture premium pricing through end-to-end thermal management integration. Ceramic substrate specialists and precision metallization fabricators occupy mid-tier positions supplying certified components. The competitive arena features strategic partnerships between foundries and refurbishment specialists, alongside technology licensing arrangements for low-voltage architectures.
Within the ceramic substrate tier, Kyocera Corporation and NGK Insulators, Ltd. represent Japanese specialty material producers anchoring high-purity alumina and aluminum nitride supply. Applied Materials, Inc. exemplifies the integrated equipment platform model controlling thermal management specifications through proprietary chuck design. Shinko Electric Industries Co., Ltd. occupies a position within Japan's captive semiconductor equipment chain through precision metallization capabilities.
| Leading Market Players |
|---|
| Shinko Electric Industries Co., Ltd. |
| NGK Insulators, Ltd. |
| Applied Materials, Inc. |
| NTK CERATEC Co., Ltd. |
| TOTO Ltd. |
| Lam Research Corporation |
| Kyocera Corporation |
| Sumitomo Osaka Cement Co., Ltd. |
| Entegris, Inc. |
| Others |
Supply Flow & Price Mechanics
The Yokohama-to-Taichung air freight corridor carries high-purity alumina and aluminum nitride substrates that anchor electrostatic chuck pricing tiers, with logistics cost volatility feeding directly into premium-grade certification premiums and downstream foundry procurement decisions.
Pricing Analysis
Cost-plus contracts indexed to Japanese ceramic substrate spot markets dominate wafer chuck procurement, with JIS B 9920 certification tier separating premium monolithic designs from standard configurations. Price differentiation rests on surface roughness grade and embedded sensor density, with sub-nanometer Ra specifications commanding substantial premiums. Cost compression in photovoltaic-grade electrostatic holders intensifies as Chinese manufacturers scale directional solidification platforms. Memory foundries exhibit highest price sensitivity due to large installed base refurbishment cycles, while sub-7nm logic producers prioritize thermal uniformity over unit cost.
Supply Chain Analysis
Extended payment terms through supply-chain finance facilities in Osaka and Dresden stabilize working capital for precision metallization fabricators serving captive equipment chains. Raw material sourcing draws from Japanese alumina refiners, German aluminum nitride ceramic producers, and South Korean electrode suppliers. Single-source vulnerability concentrates in high-purity substrate certification, where Kyocera and NGK Insulators control critical capacity. Distribution runs through OEM-integrated platform sales for leading-edge nodes and direct refurbishment contracts for mature 200mm installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrostatic chuck procurement is approaching a platform-economics inflection as foundries unbundle after-sales service from OEM equipment packages, creating interoperability requirements that favor modular thermal management architectures over proprietary integrated designs.
For Market Incumbents: Pre-empt third-party refurbishment capture by consolidating ceramic remanufacturing capabilities in Penang and Dresden service hubs. Deepen backward integration into aluminum nitride substrate production to offset Japanese supply concentration risk. Lock in multi-year thermal management specification control through embedded sensor platform licensing to foundry customers. For New Entrants and Emerging Players: Build out India-based service and refurbishment capabilities ahead of Gujarat and Assam fab commissioning under PLI scheme subsidies. Target photovoltaic electrostatic holder segments where cost-optimized designs face lower JIS certification barriers. Pursue direct contracting relationships with memory producers seeking extended chuck service life beyond OEM warranty periods. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive ceramic substrate divisions serving semiconductor equipment as non-core revenue lines. Long-term viability hinges on qualification velocity for sub-5nm low-voltage architectures and circular material recovery program certification under EU CSRD alignment. Watch for METI subsidy eligibility revisions that consolidate Japanese captive equipment chains.| Strategic Initiative | Industry Significance |
|---|---|
| Monolithic Ceramic Platform Integration | Embedded temperature sensor architectures from Kyocera enable sub-5nm gate-all-around transistor processing for TSMC. |
| Refurbishment Capability Expansion | Third-party remanufacturing shops in Penang capture service revenue from memory producers extending 300mm etch platform life. |
| Domestic Content Qualification | US CHIPS Act mandates accelerate Arizona supplier certification timelines for Applied Materials deposition equipment integration. |
| Low-Voltage Architecture Licensing | Sub-7nm ESD-sensitive designs from specialized vendors displace high-voltage legacy configurations in Taiwan foundries. |
| Circular Material Recovery Program | CSRD-aligned sustainability reporting from Entegris meets EU Chips Act green procurement mandates for semiconductor equipment. |
Methodological Framework
The analysis maps wafer chuck, electrostatic holder, and fixture chuck sub-sectors, each validated through plasma process engineers, foundry procurement directors, OEM platform integration specialists, and ceramic substrate R&D leads. Primary fieldwork combined structured interviews with secondary triangulation across SEC equipment vendor filings, METI JIS standard revision notices, MIIT GB compliance bulletins, and EU Chips Act subsidy eligibility documentation. Bottom-up unit economics from individual fab qualification timelines were cross-checked against top-down capex flow analysis from Arizona, Taichung, and Pyeongtaek construction schedules.
Assumption sets held regional subsidy program continuity and sub-7nm node migration pace fixed across the projection horizon, while varying aluminum nitride supply elasticity and third-party refurbishment market penetration rates. Segmentation dimensions modeled include product architecture, voltage technology tier, application thermal budget, and end-user procurement authority structure. CAGRs were derived from equipment installation base expansion rates and replacement cycle compression factors, with specific inputs from EUV lithography proximity tool adoption curves and photovoltaic float-zone furnace deployment pipelines.
Stress conditions across ceramic substrate supply disruption, US-China technology transfer restrictions, and sub-5nm yield ramp delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding foundry construction completion timelines and JIS certification center capacity expansion. Macroeconomic contraction, regulatory subsidy program suspension, or breakthrough alternative wafer fixation technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Reticle Pod Cleaning System Market
Semiconductor Equipment
Global Atomic Layer Deposition (ALD) Equipment Market
Semiconductor Equipment
Lithography Equipment Market
Semiconductor Equipment
Lithographic Photomasks Market
Semiconductor Equipment
Semiconductor Dielectric Etching Equipment Market
Semiconductor Equipment
Vacuum Spin Coaters Market
Semiconductor Equipment
Global Laser Dicing Systems Market
Semiconductor Equipment
Ion Milling System Market
Semiconductor Equipment
Europe Chip Mounter Market
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
PVD Coaters Market
Semiconductor Equipment
Plasma Etching Equipment Market
Semiconductor Equipment
Semiconductor CVD Equipment Market
Semiconductor Equipment
Underfill Dispenser Market
Semiconductor Equipment
FOUP Cleaning System Market
Semiconductor Equipment
Single Wafer Wet Cleaning Equipment Market