
 Virtual Prototype Market | 2026-2036
Virtual Prototype Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Prototype Market Outlook
Platform licensing revenue is narrowing relative to perpetual software sales as vendors pivot toward subscription and consumption models. Autodesk leverages its construction and manufacturing crossover to sustain recurring revenue across design-to-simulation workflows. Siemens anchors its position through deep integration with industrial automation hardware and PLM ecosystems. Ansys competes on physics fidelity, extending its electromagnetic and thermal solver portfolio into automotive electrification programs.
Virtual prototyping encompasses digital representations of physical products, systems, or environments that enable functional verification, performance prediction, and iterative refinement without material fabrication; these environments typically integrate real-time physics engines, mesh-based finite element analysis, and hardware-in-the-loop interfaces to replicate operational conditions. The primary industrial purpose is to compress development timelines, reduce physical test iterations, and enable parallel engineering workflows across distributed teams. Simulation tools command the deepest margin pools due to specialized solver IP and high switching costs for mission-critical validation. Cloud-based deployment is expanding fastest among mid-market adoptees seeking elastic compute for burst simulation workloads. CAD systems remain the most mature segment, with incumbents defending position through format entrenchment and OEM supply chain mandates.
ISO 26262 functional safety standards shape automotive virtual validation requirements, compelling tool vendors to certify traceability and fault injection capabilities. The EU AI Act introduces conformity obligations for autonomous systems validated through simulation, affecting how European engineering firms document decision logic in virtual environments. FDA digital health pre-certification pathways are extending into software-based medical device testing, creating compliance-driven demand for healthcare simulation platforms. Stakeholders must monitor how regulatory divergence between jurisdictions fragments validation tool requirements and influences platform architecture decisions.
Market Dynamics
Automotive OEMs are compressing hardware-in-the-loop validation cycles through cloud-orchestrated simulation farms, forcing tool vendors to re-architect licensing models around burst compute consumption rather than perpetual seat sales.
Growth Catalysts
- ISO 26262 Functional Safety Mandates:Automotive suppliers in Germany's industrial corridor must certify virtual validation traceability, creating procurement pull for compliant simulation platforms.
- Electrification Physics Complexity:Battery thermal runaway modeling and motor electromagnetic interference prediction require multi-physics solvers that virtual prototyping uniquely delivers.
- Cloud Elasticity:Mid-market engineering teams in the United States access on-demand GPU clusters for crash simulation and aerodynamic validation without capital-intensive server farms.
Market Restraints
- Specialized Talent Scarcity:Industrial mathematics and solver algorithm expertise concentrates within Siemens, Dassault Systèmes, and Ansys, limiting new entrant technical depth.
- Legacy Format Entrenchment:Automotive supply chains mandate proprietary CAD kernel compatibility, erecting switching barriers against challenger platforms.
- Input Cost Volatility:NVIDIA GPU pricing and cloud egress fees introduce unpredictable operating expenditure for simulation-heavy workloads.
Strategic Opportunities
- Medical Device Digital Pre-Certification:FDA software-based testing pathways for Class II and III devices open healthcare simulation demand beyond traditional industrial verticals.
- AI-Generated Mesh Refinement:Machine learning surrogate models are hybridizing with classical finite element methods, promising order-of-magnitude speedups in structural analysis.
- India's PLI Manufacturing Incentives:Production-linked scheme beneficiaries require virtual commissioning tools for greenfield automotive and electronics facilities.
Industry Challenges
- Multi-Vendor Integration Complexity:OEMs operate heterogeneous toolchains spanning CAD, PLM, and simulation platforms, demanding costly middleware development for data continuity.
- Certification Timeline Compression:EU AI Act conformity documentation for autonomous decision systems validated in simulation requires new metadata architectures and audit trail capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Prototype Market |
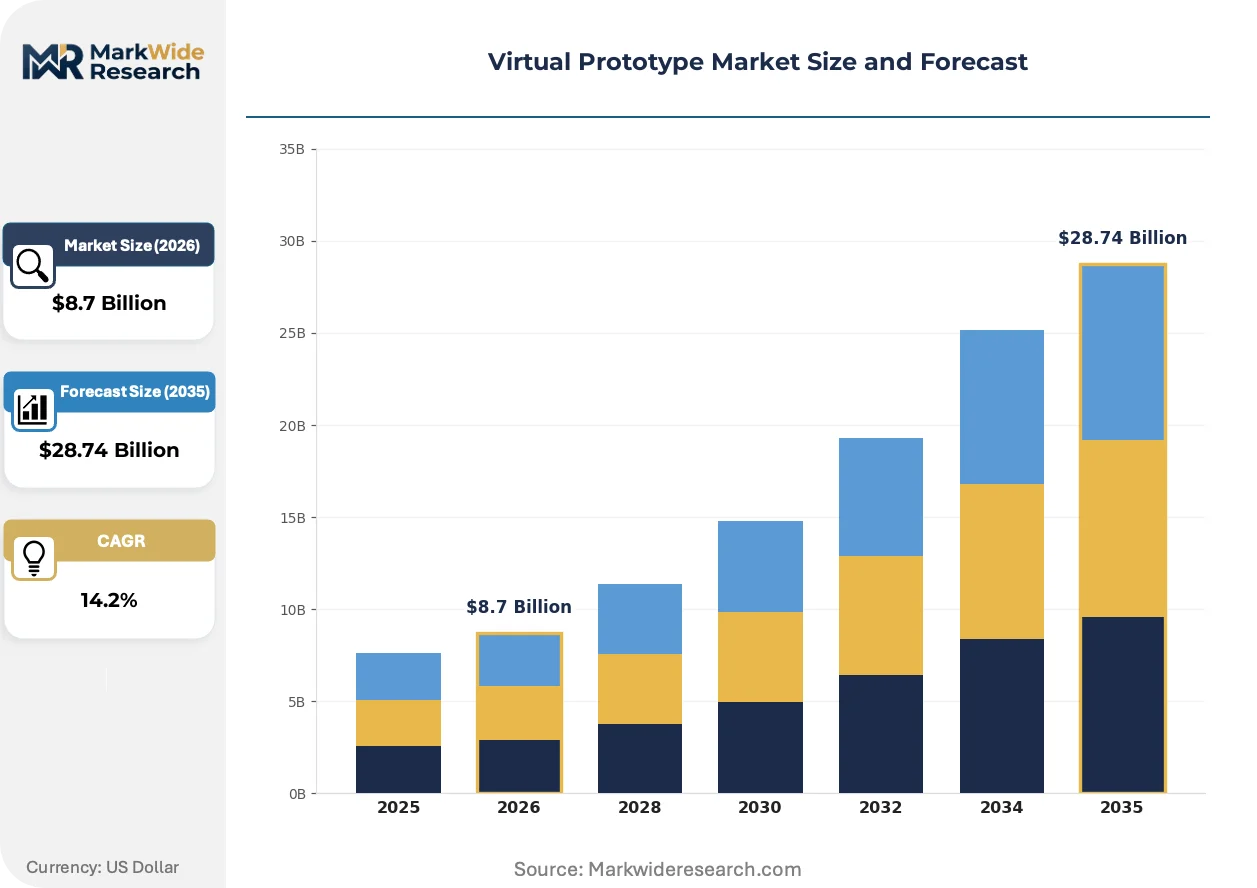
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Modeling Software, Simulation Tools, CAD Systems, VR Environments End User: Aerospace, Automotive, Consumer Electronics, Healthcare Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Application: Design Validation, Testing Simulations, User Experience, Training Programs |
| Companies Covered | Synopsys, Inc., Autodesk Inc., ESI Group, Cadence Design Systems, Inc., Arm Limited, PTC, Siemens, Ansys, Dassault Systèmes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Prototype Market Strategic Shifts
Real-time rendering engines and physics solvers are converging into unified digital twin environments, eroding the historical separation between design visualization and engineering validation workflows.
Physics-informed neural networks are hybridizing traditional computational fluid dynamics workflows, enabling automotive aerodynamicists to explore design spaces orders of magnitude faster than Reynolds-averaged Navier-Stokes methods permit. Tier 1 suppliers in Germany's Baden-Württemberg cluster deploy these surrogates for early-stage shape optimization before committing to high-fidelity validation. The compression of front-end exploration cycles is reallocating engineering headcount toward downstream physical prototype correlation.
The EU AI Act introduces conformity obligations for autonomous systems whose decision logic is validated through simulation, compelling European engineering firms to implement formal verification documentation within virtual environments. Tool vendors must now embed audit trail capture and explainability logging as native platform capabilities. Medical device manufacturers face parallel FDA digital health pre-certification pathway extensions, bifurcating platform development priorities across Atlantic regulatory regimes.
Consumption-based licensing is displacing perpetual seat sales as the dominant commercial model, with engineering teams purchasing simulation credits against cloud-hosted solver capacity rather than maintaining fixed on-premises installations. Mid-market adopters in the United States and United Kingdom favor this elasticity for burst workloads like crash simulation and electromagnetic compatibility testing. Vendor revenue predictability now depends on customer utilization forecasting rather than upfront license recognition.
Virtual Prototype Market Segmentation
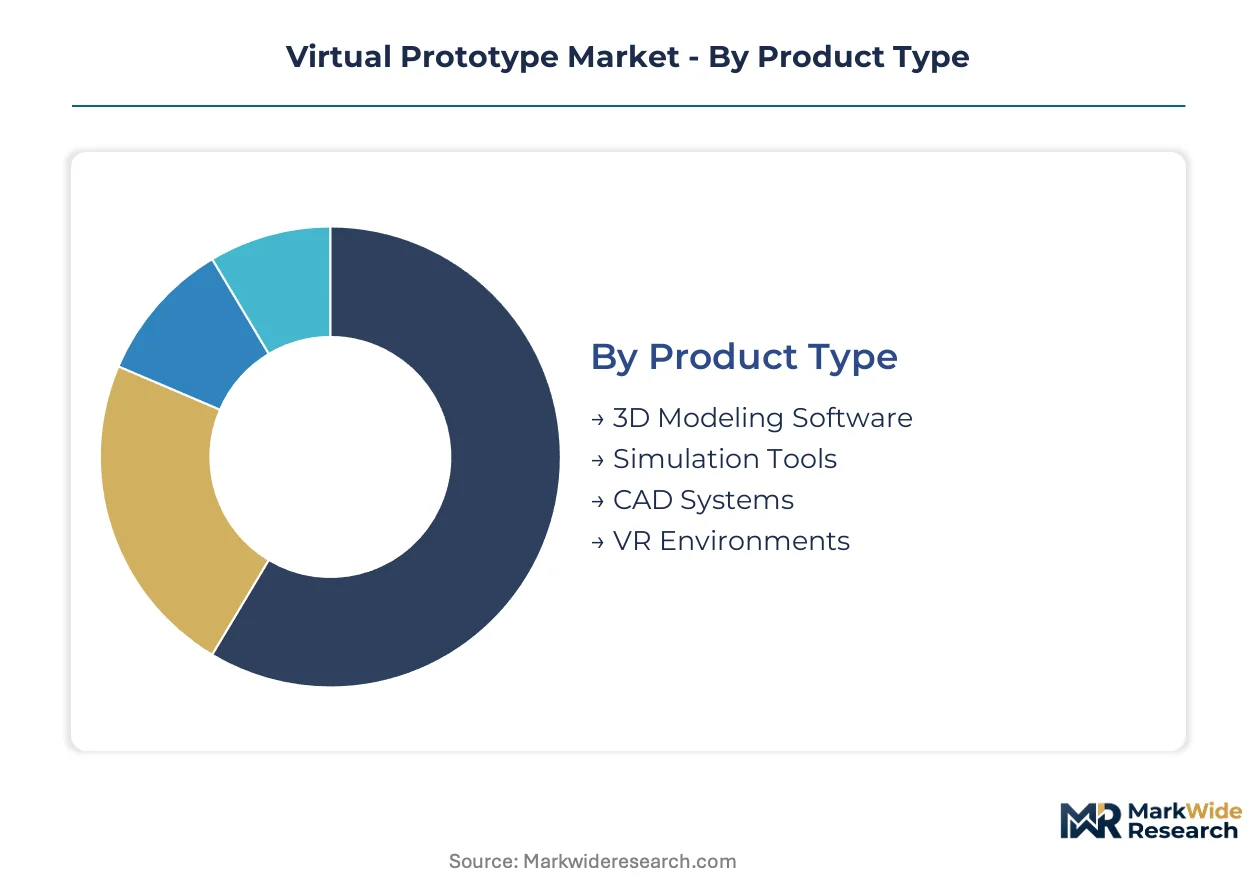
Virtual prototyping segments reflect divergent technical requirements across engineering workflows. Product type determines solver complexity and licensing economics. Deployment mode shapes capital intensity and burst compute access for distributed teams.
Product Type:
Use-case spectrum spans concept visualization through mission-critical physics validation.
- Simulation Tools:Multi-physics solvers integrate finite element analysis with real-time hardware-in-the-loop interfaces. Battery thermal runaway modeling for automotive electrification programs in Germany concentrates procurement of electromagnetic and thermal solver licenses.
- CAD Systems:Mesh-based geometric kernels anchor design-to-manufacturing workflows through proprietary format entrenchment. Automotive supply chain mandates in the United States and Germany erect switching barriers that defend incumbent positions.
- 3D Modeling Software:Surface and solid modeling environments prioritize visualization fidelity over physics accuracy for early-stage concept exploration.
- VR Environments:Immersive rendering engines merge with physics engines for operator training and design review applications.
Established volume favors CAD Systems; emerging adoption favors Simulation Tools.
End User:
Customer concentration varies by validation stringency and regulatory exposure.
- Automotive:OEMs deploy digital twins across powertrain, chassis, and autonomous system development. ISO 26262 functional safety mandates in Germany's supplier corridor compel traceable virtual validation platforms.
- Aerospace:Airframe and propulsion engineers require high-fidelity structural and aerodynamic solvers. FAA certification pathways for flight-critical software drive demand for formal verification documentation capabilities.
- Healthcare:Medical device manufacturers adopt simulation for FDA digital health pre-certification of Class II and III devices.
- Consumer Electronics:Smartphone and wearable producers leverage virtual prototyping for thermal management and drop-test simulation.
Procurement scale concentrates in Automotive; regulatory tailwinds accelerate Healthcare fastest.
Deployment:
Infrastructure economics separate capital-constrained mid-market adopters from enterprise IT mandates.
- Cloud-Based:Elastic GPU clusters enable burst simulation workloads without on-premises server farms. Engineering teams in the United States favor consumption-based licensing against cloud-hosted solver capacity for crash and aerodynamic validation.
- Hybrid:Sensitive IP remains on-premises while burst compute spills to cloud infrastructure. German automotive suppliers partition classified powertrain models locally while accessing elastic electromagnetic solvers remotely.
- On-Premises:Legacy perpetual license estates persist in defense and aerospace programs with air-gapped security requirements.
- SaaS:Browser-accessible simulation environments target small engineering consultancies with limited IT overhead.
Revenue recognition shifts from On-Premises toward Cloud-Based consumption models.
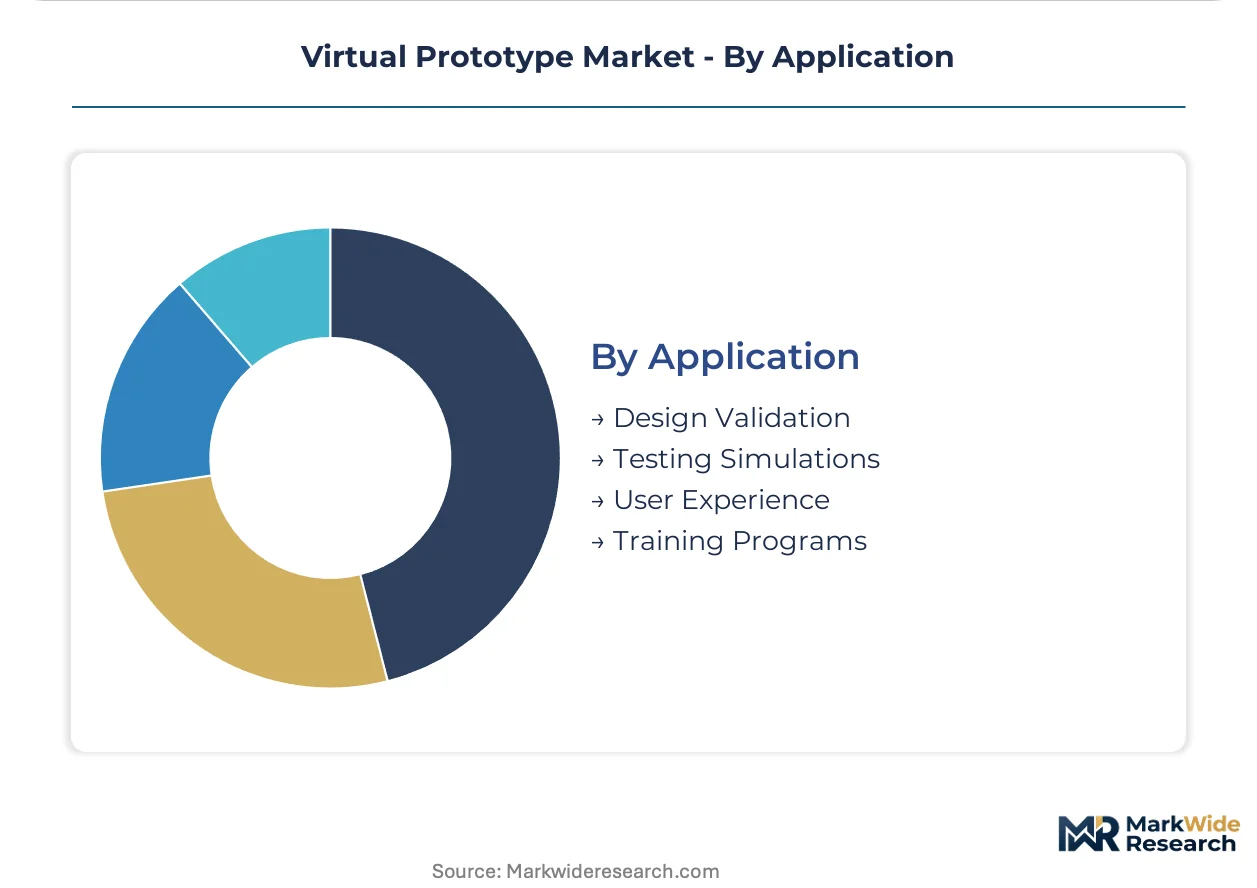
Application:
Workflow position determines tool integration depth and physics fidelity requirements.
- Design Validation:Early-stage geometry checking and interference detection compress iteration cycles before physical prototyping.
- Testing Simulations:Virtual crash, durability, and electromagnetic compatibility testing replace expensive physical test campaigns. Physics-informed neural networks accelerate aerodynamic exploration for Tier 1 suppliers in Baden-Württemberg.
- User Experience:Ergonomic and human factors simulation guides cockpit and cabin design decisions.
- Training Programs:Operator and maintenance simulations reduce field deployment risk for complex industrial equipment.
Margin depth concentrates in Testing Simulations; integration expansion favors Design Validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering teams in the United States demonstrate highest price elasticity for burst compute workloads, while German automotive suppliers accept premium licensing for ISO 26262 traceability. Cloud consumption models penetrate fastest where capital constraints meet elastic simulation demand.
United States
Mid-market engineering consultancies in Michigan and California drive cloud-based simulation adoption for crash and aerodynamic validation. FDA digital health pre-certification pathways for Class II and III medical devices expand healthcare simulation procurement beyond traditional industrial verticals. Detroit-area automotive engineering centers partition sensitive powertrain IP on-premises while bursting electromagnetic compatibility testing to GPU clusters.
Germany
Baden-Württemberg's Tier 1 supplier corridor mandates virtual validation traceability under ISO 26262 functional safety standards. KBA type-approval processes for autonomous driving systems compel formal verification documentation in simulation environments. Stuttgart and Munich engineering clusters deploy physics-informed neural networks for battery thermal runaway modeling in electrification programs.
China
Domestic EV manufacturers accelerate digital twin adoption for compressed development cycles under MIIT new energy vehicle mandates. Dual carbon goals pressure industrial enterprises to reduce physical prototype waste through virtual commissioning. Yangtze River Delta automotive hubs in Shanghai and Jiangsu province integrate cloud-based solver capacity for distributed R&D teams.
India
PLI scheme beneficiaries for automotive and electronics manufacturing require virtual commissioning tools for greenfield facility deployment. BIS standards for industrial safety equipment create compliance-driven demand for simulation-based certification. Karnataka and Tamil Nadu engineering services clusters build captive simulation capabilities to support OEM outsourcing contracts.
Japan
Automotive OEMs in Aichi and Kanagawa prefectures extend digital twin workflows into supplier quality assurance under METI manufacturing competitiveness initiatives. JIS standards for functional safety align with ISO 26262 traceability requirements for export market access. Tokyo and Nagoya engineering centers hybridize classical finite element methods with machine learning surrogates for structural analysis acceleration.
Virtual Prototype Market Competitive Environment
Capability concentration sits with specialized solver developers; scale advantage sits with diversified industrial software conglomerates. The market structures around three tiers: physics-fidelity specialists defending high-margin validation workflows, platform integrators bundling CAD-to-simulation pipelines, and cloud-native challengers attacking mid-market elasticity demand. Dominant competitive moves include consumption-based licensing re-architecture and AI-surrogate hybridization of classical solver methods.
Within the diversified platform tier, Autodesk Inc. and Siemens exemplify scale-driven bundling strategies spanning construction-to-manufacturing crossover workflows. Ansys occupies a position as physics-fidelity anchor for multi-physics electromagnetic and thermal validation in automotive electrification. Synopsys, Inc. sits within the semiconductor-centric simulation segment where hardware-software co-verification demands specialized solver IP.
| Leading Market Players |
|---|
| Synopsys, Inc. |
| Autodesk Inc. |
| ESI Group |
| Cadence Design Systems, Inc. |
| Arm Limited |
| PTC |
| Siemens |
| Ansys |
| Dassault Systèmes |
| Others |
Value Chain & Pricing Dynamics
Shanghai-to-Rotterdam container freight corridors transmit NVIDIA GPU cost volatility directly into simulation software licensing economics, compressing margins for cloud-hosted solver providers while amplifying price differentiation between on-premises perpetual licenses and consumption-based elastic compute tiers.
Pricing Analysis
After-sales service revenue streams anchored in solver maintenance and technical support contracts drive lifetime value capture for incumbent platform vendors. Three-tier pricing structure across premium, standard, and economy levels segments buyers by ISO 26262 certification requirements and multi-physics solver depth. Pricing pressure stems from mid-market engineering consultancies demanding burst compute elasticity without enterprise-scale commitments. Automotive OEMs in Germany exhibit lowest price sensitivity due to regulatory compliance mandates; United States-based consultancies show highest elasticity, prioritizing pay-per-simulation credit models.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for GPU-dependent simulation infrastructure. Hardware concentration rests on NVIDIA fabrication partnerships in Taiwan, assembly ecosystems in China, and cloud data center buildouts in the United States and Germany. Raw material dependencies span silicon wafers, high-bandwidth memory modules, and specialized cooling systems. Distribution runs through hyperscaler marketplaces and direct enterprise licensing agreements with tiered support entitlements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source physics engines and AI-generated surrogate models threaten incumbent solver margins by democratizing access to computational methods previously guarded by specialized algorithm expertise. Incumbents must navigate this substitution pressure while defending high-traceability validation workflows.
For Market Incumbents: Harden platform stickiness through deeper PLM integration and mandatory ISO 26262 certification tooling that open-source alternatives cannot replicate. Invest in captive GPU cluster partnerships to buffer cloud cost volatility. Defend electromagnetic and thermal solver portfolios against machine learning surrogate erosion by emphasizing physical validation correlation requirements.
For New Entrants and Emerging Players: Build out browser-accessible SaaS simulation environments targeting United Kingdom and United States mid-market engineering consultancies with limited IT infrastructure. India's PLI scheme beneficiaries present white-space demand for virtual commissioning tools without legacy format entrenchment barriers. Lead with consumption-based pricing against burst workload patterns to bypass incumbent perpetual license lock-in.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to monetize non-core simulation assets amid portfolio rationalization. Long-term viability favors physics-fidelity specialists with automotive electrification solver depth over visualization-heavy modeling platforms. Watch FDA digital health pre-certification pathway expansion rates as inflection signal for healthcare simulation platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deepens CAD-to-simulation workflow entrenchment within automotive OEM validation pipelines. |
| Consumption Licensing Re-architecture | Aligns revenue recognition with GPU cluster utilization patterns across mid-market adopters. |
| AI-Surrogate Hybridization | Accelerates aerodynamic exploration for Baden-Württemberg Tier 1 suppliers without solver fidelity loss. |
| Regulatory Certification Investment | Embeds EU AI Act audit trails and FDA pre-certification pathways as native platform capabilities. |
| Geographic Cloud Expansion | Positions elastic compute nodes near Yangtze River Delta and Karnataka engineering clusters. |
Study Parameters
Operator-level perspectives from OEM platform engineers, Tier 1 supplier procurement leads, simulation software product managers, and cloud infrastructure architects anchored the qualitative base. Primary interview findings triangulated against SEC 10-K filings, hyperscaler capex disclosures, automotive production databases, and EU regulatory implementation guidance. Bottom-up segment sizing across deployment modes and solver types reconciled with top-down market aggregation.
Scenario-bracketing framed projections across conservative, baseline, and expansion cases throughout the forecast period. Segmentation dimensions modeled include product type, deployment architecture, end-use vertical, and regional regulatory cluster. CAGRs derived from solver license growth rates, cloud consumption trajectories, and electrification program simulation intensity assumptions across automotive OEMs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by open-source physics engine consortia or hyperscaler vertical integration would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Global VR for Medical Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Immersive Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Solutions Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Smart Glasses for Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality and Virtual Reality (AR/VR) in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East and Africa Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Para-Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
AR-VR Head Display Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Spatial Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Consumer Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Reality Glasses Market