
 VR Box Glasses Market | 2026-2036
VR Box Glasses Market Size, Share, and Industry Trends Forecast 2026-2036
VR Box Glasses Market Insights
Subscription-based hardware leasing and asset-light procurement models is tilting competitive dynamics toward firms with balance-sheet flexibility. Meta Platforms leverages its captive content ecosystem to sustain recurring revenue attachment on standalone headsets. Sony Group Corporation anchors its position through backward integration into proprietary OLED microdisplay supply. HTC Corporation differentiates by specializing in enterprise-grade PC-based systems for corporate trainees and medical simulation.
VR box glasses are head-mounted display enclosures that position a smartphone or integrated screen at a fixed focal distance from dual aspheric lenses, typically offering 90-110 degree field-of-view with interpupillary adjustment for stereoscopic immersion. The primary commercial purpose is delivering portable, low-cost virtual reality experiences for gaming, education, and industrial training without requiring dedicated room-scale infrastructure. Smartphone-compatible units retain volume leadership due to minimal hardware cost, though standalone headsets incorporating onboard processing and Wi-Fi streaming represent the fastest-expanding margin pool. OLED technology leads premium positioning for gamers and healthcare professionals seeking high-contrast, low-persistence panels, while LCD dominates mid-tier educator and corporate trainee procurement through cost-scaled manufacturing.
The FCC governs radio frequency emissions and wireless connectivity standards for devices sold in the United States, directly affecting chipset selection and SAR testing protocols. CE marking under the EU MDR and RoHS directives constrains material composition and biocompatibility claims for European healthcare deployments. China's SAMR enforces GB standards for electromagnetic compatibility and battery safety, shaping which OEMs qualify for domestic hospital and school tenders. Stakeholders must monitor how divergent electromagnetic and optical safety regimes fragment certification costs and determine which technology tiers can profitably cross multiple jurisdictions.
Market Dynamics
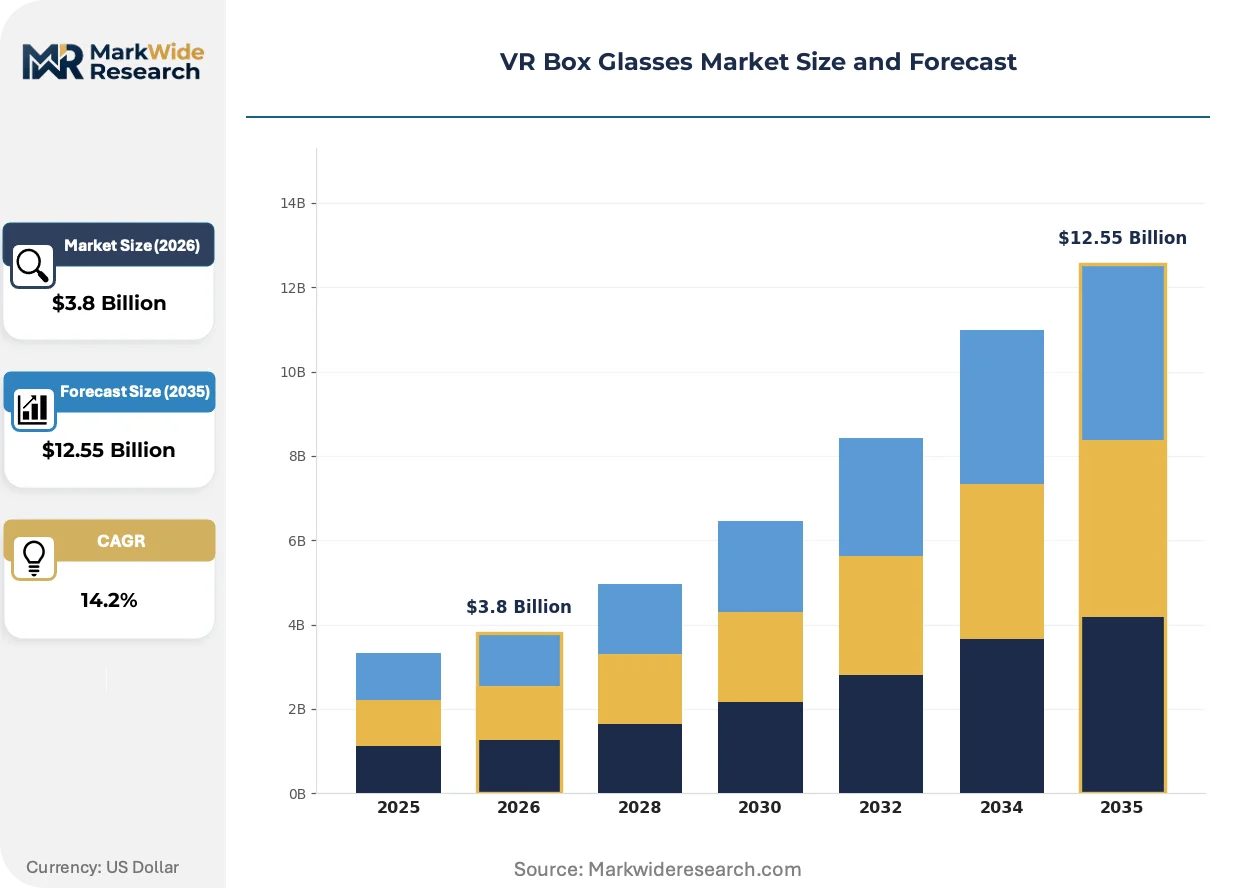
The VR box glasses market pivots on a fundamental tension between smartphone-tethered affordability and standalone processing power, with regulatory fragmentation across electromagnetic safety regimes now determining which hardware tiers can cross borders profitably.
Growth Catalysts
- EU AI Act compliance pathways:Medical-grade headsets cleared under the MDR's biocompatibility and data governance frameworks are unlocking hospital procurement tenders across Germany, France, and the Netherlands.
- Healthcare simulation demand:Surgical training programs in China and the United States are replacing cadaver-based instruction with haptic-integrated VR modules, driving volume orders for high-refresh-rate OLED units.
- Wi-Fi 6E chipset integration:Onboard streaming capabilities in standalone devices are eliminating PC-tethering infrastructure costs for corporate training deployments.
Market Restraints
- Display panel supply concentration:Samsung Display and BOE Technology control premium OLED microdisplay output, creating allocation bottlenecks for mid-tier OEMs scaling production.
- GB standard battery certification:China's SAMR enforcement of electromagnetic compatibility and thermal runaway testing extends domestic market entry timelines by 8-14 months for non-local manufacturers.
- Smartphone AR substitution:Apple and Google's spatial computing APIs on existing handsets are capturing casual gaming and retail visualization use cases without dedicated headset purchase.
Strategic Opportunities
- India's PLI scheme for electronics:Component manufacturing incentives are attracting assembly operations for smartphone-compatible enclosures targeting price-sensitive education sectors.
- Japan's METI digital therapeutics approval:Anxiety and PTSD treatment protocols using immersive exposure therapy are creating reimbursable prescription channels for clinical-grade hardware.
- 5G network slicing partnerships:Telecommunications carriers in South Korea and Germany are bundling low-latency connectivity with hardware leases for enterprise training as-a-service models.
Industry Challenges
- Optical engineer scarcity:Aspheric lens design and pupillary distance calibration expertise concentrates in Shenzhen and Taipei, constraining R&D expansion for European and North American entrants.
- MDR clinical evidence requirements:CE marking for patient-facing therapeutic applications demands 12-18 month prospective studies, compressing product refresh cycles against consumer electronics cadences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VR Box Glasses Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Smartphone-Compatible, PC-Based, Gaming Consoles Technology: OLED, LCD, LCoS, Varifocal End User: Gamers, Educators, Healthcare Professionals, Corporate Trainees Distribution Channel: Online Retail, Brick-and-Mortar, Third-Party Resellers, Direct Sales |
| Companies Covered | Meta Platforms, Inc., Sony Group Corporation, HTC Corporation, Samsung Electronics Co., Ltd., XREAL, RayNeo, VITURE, Rokid, Pico Interactive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VR Box Glasses Market Trends and Innovations
Pancake lens architectures and foveated rendering pipelines are compressing form factors while local processing capabilities sever dependency on external compute. These shifts are reconfiguring supply chain priorities and procurement evaluation criteria simultaneously.
Pancake optics utilizing polarized light folding is digitizing the traditional refractive lens stack, collapsing optical path length from 40mm to under 20mm. Medical simulation buyers in Switzerland and the United States are prioritizing these slim profiles for extended surgical training sessions. The technology is digitizing comfort thresholds that previously capped session duration and repeat purchase frequency.
The EU AI Act's risk classification framework for biometric emotion recognition is mandating algorithmic transparency documentation for headsets deployed in therapeutic settings. Hardware vendors must now submit technical files detailing data processing logic to notified bodies prior to CE marking. German and French hospital systems are delaying tenders until Q3 2025 to align procurement with finalized conformity assessment protocols.
Enterprise buyers are consolidating vendor relationships through multi-year hardware-as-a-service contracts that unbundle device ownership from software licensing. Industrial training departments in China's Guangdong province and automotive manufacturers in Michigan are shifting capital expenditure to operational expenditure models. This reconfiguration is most visible in corporate learning budgets exceeding 500-seat deployments where refresh cycles synchronize with content library updates rather than depreciation schedules.
VR Box Glasses Market Segmentation
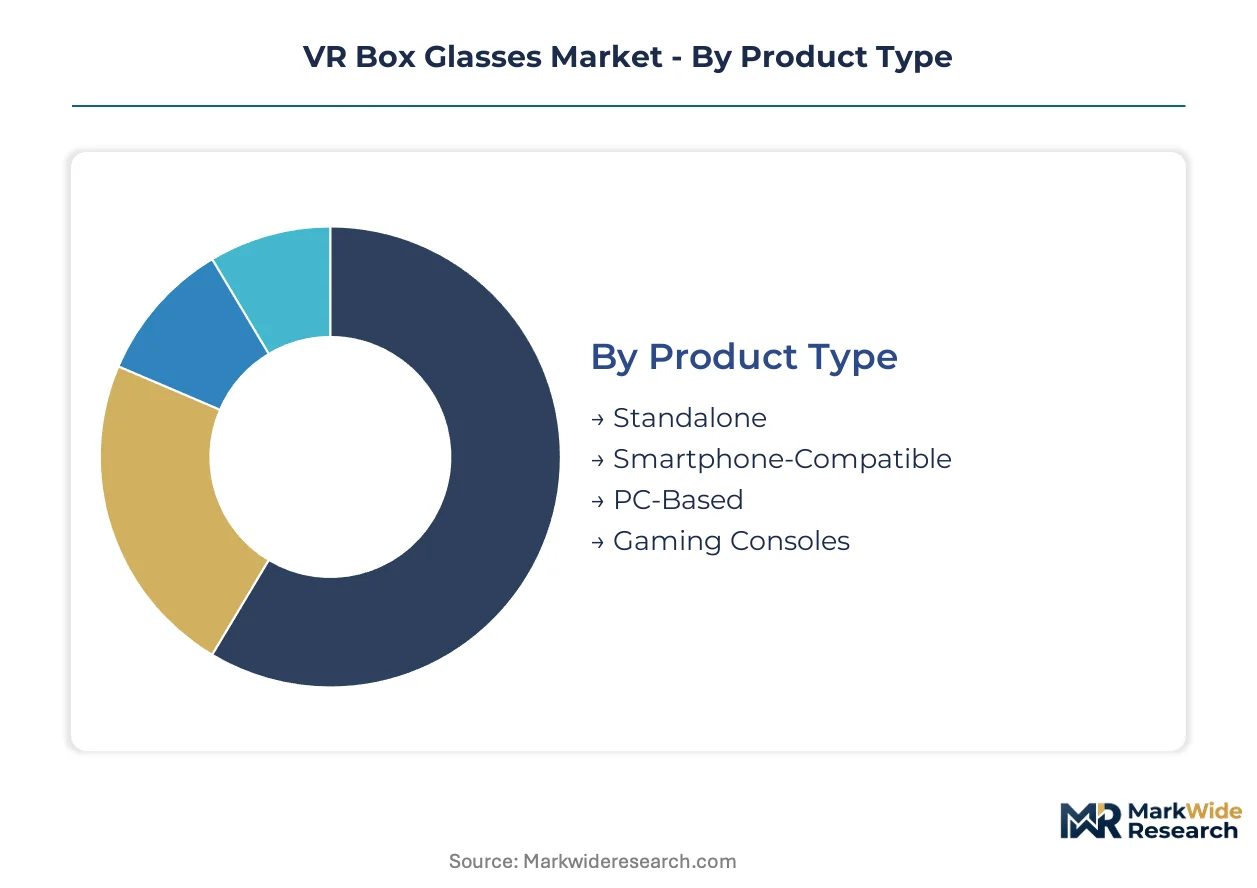
VR box glasses segment along four intersecting dimensions that determine procurement economics, regulatory pathway, and margin structure. Product architecture dictates tethering requirements and processing cost. Display technology governs refresh rate ceilings and therapeutic eligibility. End-user identity shapes volume concentration and certification burden. Channel choice determines geographic reach and working capital intensity.
Product Type:
Use-case spectrum spans casual smartphone-tethered viewing through room-scale PC-anchored simulation, with cost tier and mobility requirements determining hardware selection.
- Standalone:Onboard SoC processing eliminates external compute dependency while Wi-Fi 6E streaming supports untethered enterprise deployment. Healthcare simulation programs in Switzerland and Germany are prioritizing these units for surgical training modules requiring positional tracking without PC infrastructure.
- Smartphone-Compatible:Passive enclosures position handsets at fixed focal distances behind aspheric lenses, achieving sub-forty-dollar bill-of-materials. India's education procurement tenders and China's rural school digitalization initiatives are concentrating volume orders for these entry-tier units.
- PC-Based:External GPU rendering drives high-fidelity visual output for industrial design review and automotive prototyping. Corporate training departments in Michigan and Bavaria maintain installed bases tethered to workstation clusters.
- Gaming Consoles:Proprietary ecosystem lock-in delivers optimized latency for first-party content libraries. Sony's PlayStation VR2 anchors this segment through backward integration into OLED microdisplay supply.
Established volume favors smartphone-compatible enclosures; emerging adoption favors standalone processing architectures.
Technology:
Display panel selection governs contrast ratio, persistence artifacts, and MDR biocompatibility clearance eligibility for patient-facing applications.
- OLED:Self-emissive pixels achieve true black states and sub-ten-millisecond persistence, critical for surgical simulation verisimilitude. Samsung Display and BOE Technology control premium microdisplay output, creating allocation bottlenecks for mid-tier OEMs scaling clinical-grade production.
- LCD:Backlit TFT architectures deliver cost-scaled manufacturing for education and corporate procurement where contrast specifications are secondary to unit economics. China's Guangdong province hosts concentrated LCD module assembly for regional tender fulfillment.
- LCoS:Reflective liquid crystal on silicon enables high-resolution projection engines for enterprise augmented reality overlays. Industrial maintenance training programs in Japan are piloting these panels for see-through guidance applications.
- Varifocal:Mechanically or electrically adjustable focal planes address vergence-accommodation conflict in extended therapeutic sessions. Swiss hospital systems are evaluating varifocal prototypes for PTSD exposure therapy protocols requiring hour-plus immersion without visual fatigue.
Cost-scaled procurement anchors on LCD; clinical-grade reimbursement eligibility climbs fastest for OLED.
End User:
Customer identity determines regulatory pathway complexity, with medical device clearance adding twelve to eighteen months to product launch timelines versus consumer electronics cadences.
- Gamers:Refresh rate sensitivity and haptic integration drive premium positioning. Meta Platforms sustains recurring revenue attachment through captive content ecosystem lock-in on Quest standalone units.
- Educators:Volume procurement prioritizes durability and sanitization compatibility over optical performance. India's PLI scheme for electronics manufacturing is attracting assembly operations targeting price-sensitive institutional tenders.
- Healthcare Professionals:Surgical training and patient therapy represent the expanding margin pool. CE marking under the EU MDR and FDA 510(k) pathways govern biocompatibility claims and data governance documentation for hospital deployment.
- Corporate Trainees:Hardware-as-a-service leasing models are displacing capital expenditure procurement. Automotive manufacturers in Michigan and electronics assemblers in China's Guangdong province are consolidating vendor relationships through multi-year operational expenditure contracts.
Consumer volume concentrates among gamers; reimbursement-enabled expansion favors healthcare professionals.
Distribution Channel:
Channel selection determines certification cost recovery velocity and geographic market access, with direct sales bypassing retail margin extraction for enterprise accounts.
- Online Retail:Platform aggregation enables global reach without territorial distributor agreements. Amazon and JD.com dominate consumer-facing volume for smartphone-compatible units.
- Brick-and-Mortar:Physical demonstration requirements sustain electronics specialty retail for premium standalone headsets. Best Buy and Suning maintain experiential zones for Meta and Sony product lines.
- Third-Party Resellers:Regional system integrators bundle hardware with content licensing for institutional deployment. German and French hospital systems are delaying tenders until Q3 2025 to align procurement with finalized EU AI Act conformity assessment protocols.
- Direct Sales:Vendor field teams manage complex procurement cycles for五百-seat-plus enterprise training deployments. HTC Corporation anchors this channel for medical simulation and corporate learning accounts.
Consumer acquisition flows through online retail; enterprise consolidation favors direct sales engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in VR hardware tilt heavily toward Asian manufacturing clusters feeding North American and European consumption, with regulatory divergence in electromagnetic safety standards fragmenting cross-border shipment economics. Component trade concentrates in East Asian foundries while finished goods distribution faces certification bottlenecks at destination markets.
United States
Healthcare simulation programs at Johns Hopkins and Mayo Clinic are replacing cadaver-based surgical instruction with haptic-integrated VR modules. FDA 510(k) clearance pathways govern biocompatibility claims for patient-facing therapeutic headsets. Corporate training departments in Michigan's automotive corridor are consolidating vendor relationships through multi-year hardware-as-a-service contracts.
China
Government-backed digital infrastructure initiatives are accelerating rural school adoption of smartphone-compatible enclosures. SAMR enforcement of GB standards for electromagnetic compatibility and battery safety extends market entry timelines for non-local manufacturers. Shenzhen hosts concentrated optical engineering talent for aspheric lens design and pupillary distance calibration.
Germany
Hospital procurement tenders across Bavaria and North Rhine-Westphalia are unlocking for medical-grade headsets cleared under MDR biocompatibility frameworks. The EU AI Act's risk classification for biometric emotion recognition mandates algorithmic transparency documentation prior to CE marking. Automotive manufacturers in Stuttgart are piloting standalone units for industrial design review.
Japan
METI digital therapeutics approval for anxiety and PTSD treatment protocols is creating reimbursable prescription channels for clinical-grade hardware. Industrial maintenance training programs in Nagoya are piloting LCoS projection engines for see-through guidance applications. 5G network slicing partnerships with telecommunications carriers are bundling low-latency connectivity with enterprise hardware leases.
India
PLI scheme incentives for electronics manufacturing are attracting assembly operations for smartphone-compatible enclosures targeting price-sensitive education sectors. State-level digitalization tenders in Maharashtra and Karnataka are concentrating volume orders for entry-tier units. BIS certification requirements for electromagnetic compatibility are shaping which OEMs qualify for institutional procurement.
VR Box Glasses Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream controlling display and optical supply. The vendor base stratifies between captive ecosystem operators, enterprise-focused hardware vendors, and emerging Asian challengers leveraging domestic manufacturing scale. Three archetypes dominate: content-locked platform owners, medical-specialist system integrators, and component-scale assembly houses. Competitive moves center on backward integration into microdisplay supply and multi-year leasing contract consolidation for corporate accounts.
Among platform-anchored operators, Meta Platforms, Inc. and Sony Group Corporation exemplify the captive ecosystem model where hardware attach rates depend on proprietary content libraries. HTC Corporation occupies a position within the enterprise-specialist tier, serving medical simulation and corporate training accounts through direct sales engagement. These three anchors illustrate how competitive positioning diverges between consumer-facing scale and institutional procurement depth.
| Leading Market Players |
|---|
| Meta Platforms, Inc. |
| Sony Group Corporation |
| HTC Corporation |
| Samsung Electronics Co., Ltd. |
| XREAL |
| RayNeo |
| VITURE |
| Rokid |
| Pico Interactive |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's LCD module assembly corridors is compressing margins for mid-tier smartphone-compatible enclosures while simultaneously granting OLED microdisplay suppliers in South Korea and Taiwan exceptional pricing power over clinical-grade headset manufacturers. This utilization asymmetry forces procurement officers to navigate divergent cost structures across performance tiers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with certification grade and volume scale serving as the primary differentiation drivers. Pricing pressure stems from India's PLI scheme attracting assembly operations for entry-tier education procurement, compressing economy-tier margins. Healthcare professionals exhibit the least price sensitivity due to MDR reimbursement eligibility, while rural school digitalization initiatives in China and India drive acute cost consciousness among institutional purchasers.
Supply Chain Analysis
Export control restrictions on advanced semiconductor manufacturing equipment are constraining domestic OLED microdisplay capacity expansion outside East Asia, concentrating premium panel supply in South Korea, Taiwan, and Japan. The supply chain draws from gallium nitride substrates, rare-earth phosphors, and precision aspheric polymers as critical inputs. Single-source vulnerability persists for Samsung Display and BOE Technology's premium microdisplay output. Distribution runs through direct sales engagement for enterprise accounts above five hundred seats, with online retail platforms capturing consumer-facing volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware-as-a-service leasing models are expanding faster than unit sales, with software licensing and content library subscriptions generating recurring revenue streams that outpace device depreciation cycles.
For Market Incumbents: Harden backward integration into proprietary OLED microdisplay supply to defend against allocation bottlenecks from Samsung Display and BOE Technology. Deepen certification investment for EU AI Act compliance pathways to capture delayed hospital procurement tenders in Germany and France. Channel control through direct sales engagement remains essential for enterprise accounts exceeding five hundred seats. For New Entrants and Emerging Players: Pursue India's PLI scheme incentives for electronics manufacturing assembly targeting price-sensitive education sector tenders. White-space exists in smartphone-compatible enclosures for rural school digitalization where domestic OEMs hold procurement preference. Go-to-market through third-party reseller bundling with content licensing accelerates institutional penetration without field team infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward enterprise-specialist system integrators with established direct sales channels in medical simulation and corporate training verticals. Long-term viability over a five-to-ten year window favors vendors capturing hardware-as-a-service operational expenditure shifts. Watch for 5G network slicing partnership announcements with telecommunications carriers as an inflection indicator for enterprise training-as-a-service model maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microdisplay Supply | Captive OLED panel production insulates Meta and Sony from Samsung Display allocation constraints. |
| EU AI Act Compliance Pathway Investment | Algorithmic transparency documentation unlocks CE marking for biometric emotion recognition in therapeutic headsets. |
| Hardware-as-a-Service Contract Consolidation | Multi-year operational expenditure models displace capital procurement in Michigan automotive and Guangdong electronics training. |
| 5G Network Slicing Partnership | Telecommunications carriers in South Korea and Germany bundle low-latency connectivity with enterprise hardware leases. |
| Pancake Lens Architecture R&D | Slim form factors under 20mm optical path address Swiss hospital comfort thresholds for extended surgical training. |
Research Methodology
Initial hypotheses were tested against primary input from optical engineering directors, hospital procurement committee members, enterprise training budget owners, and VR content platform strategists and refined through secondary validation against SEC filings from headset manufacturers, SAMR GB standard enforcement notices, EU MDR technical documentation databases, and customs trade flow records. Bottom-up unit shipment estimates triangulated with top-down addressable market sizing across product architecture, display technology, end-user identity, and distribution channel dimensions.
Demand-supply balance modeling anchored the analytical framework across the projection horizon, with segmentation across standalone, smartphone-compatible, PC-based, and gaming console architectures intersecting with OLED, LCD, LCoS, and varifocal display technologies. CAGRs were derived from installed base growth rates, replacement cycle compression, and average selling price trajectory assumptions. Foveated rendering pipeline adoption and Wi-Fi 6E chipset integration curves served as technology-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, electromagnetic safety regulatory divergence, or healthcare reimbursement policy would shift the trajectory. Material shifts in EU AI Act conformity assessment protocol finalization or SAMR GB standard enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Global VR for Medical Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Enterprise Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Immersive Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Dressing Room Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality for Consumer Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Smart Augmented Reality Glasses for B2B Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Prototype Market
Virtual Reality (VR) and Augmented Reality (AR)
Extended Reality Display Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Content Creation Market
Virtual Reality (VR) and Augmented Reality (AR)
China Metaverse Market