
 Virtual Reality in Construction Market | 2026-2036
Virtual Reality in Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Reality in Construction Market Analysis
ISO 19650 certification for building information management is collapsing the barrier between traditional BIM workflows and immersive VR environments, forcing vendors to demonstrate interoperability credentials before procurement cycles begin. Matterport leverages its spatial data capture infrastructure to anchor large-scale digital twin deployments for infrastructure owners. Varjo differentiates through photorealistic headset resolution that meets aviation-grade simulation standards, extending its addressable base into mission-critical construction verticals. Meta competes on ecosystem breadth, sustaining developer loyalty through integrated hardware-software stacks that reduce deployment friction for mid-sized contractors.
Virtual Reality in Construction denotes immersive digital environments generated through head-mounted displays and positional tracking systems, typically rendering 3D architectural models at 90 frames per second to prevent motion sickness during extended training or design review sessions. Its primary commercial purpose is to reduce physical prototyping costs and eliminate site hazards by simulating construction sequences before ground breaking. Safety Training commands disproportionate procurement attention as insurers recognize immersive modules for reducing workers' compensation exposure on complex vertical builds. Cloud-Based deployment is accelerating fastest among multi-site contractors seeking centralized content libraries without hardware refresh cycles, while On-Premise configurations retain preference for classified government infrastructure projects where data sovereignty overrides convenience.
FAA simulator qualification standards and OSHA workplace training guidelines are converging to validate VR platforms for high-risk construction certifications, creating compliance-driven replacement cycles for legacy training equipment. The EU AI Act's risk classification framework for automated decision systems will pressure European vendors to document algorithmic transparency in generative design tools integrated with VR pipelines. Stakeholders must monitor whether emerging building codes in California and New York will mandate immersive hazard walkthroughs as pre-permit requirements, fundamentally altering sales cycle timing and buyer committee composition.
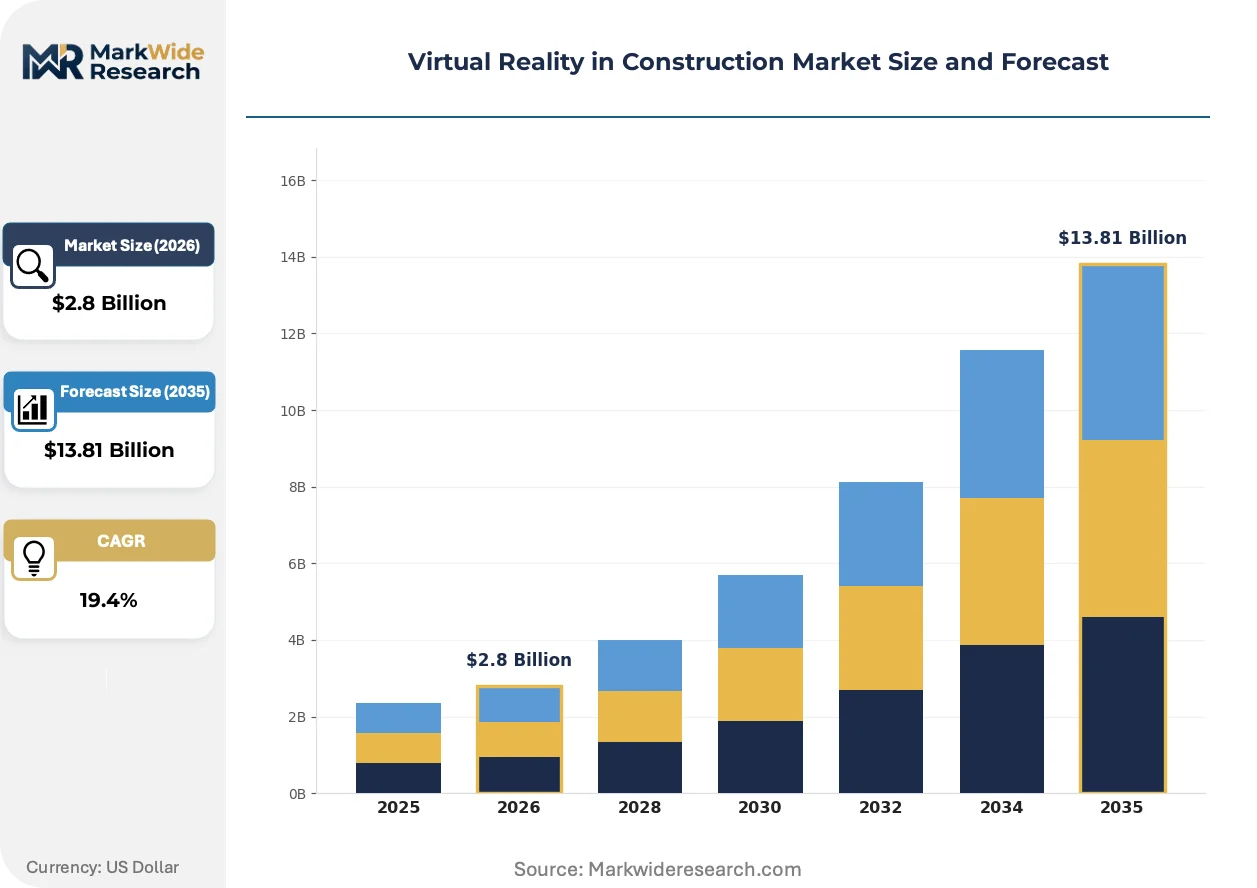
Market Dynamics
OSHA's updated crane operation training mandates are compressing sales cycles for immersive simulation platforms, forcing general contractors to replace legacy equipment with VR-certified systems before permit approvals. This regulatory pressure is restructuring vendor qualification criteria and procurement committee composition across commercial high-rise development.
Growth Catalysts
- OSHA Training Mandates:Updated crane operation certification requirements are compelling firms to adopt immersive simulation platforms for compliance, eliminating legacy training equipment replacement cycles.
- Texas and California Megaproject Corridors:Concentrated vertical build density in Houston, Dallas, Los Angeles, and San Francisco metro areas is driving centralized software procurement for site logistics planning.
- ISO 19650 Certification:Building information management standardization is collapsing barriers between BIM workflows and VR environments, mandating interoperability demonstrations before vendor selection.
Market Restraints
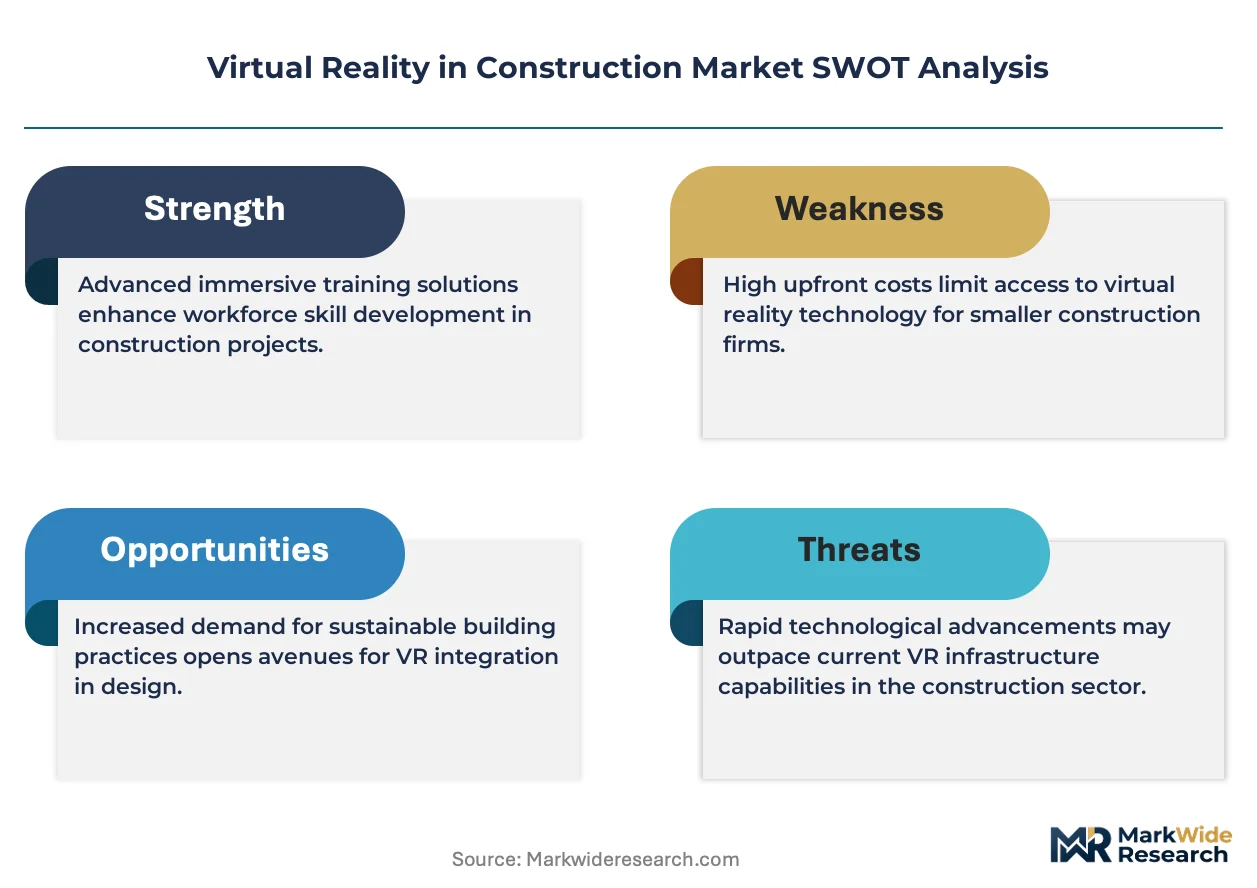
- Headset Hardware Costs:Aviation-grade photorealistic displays required for mission-critical construction verticals carry per-unit pricing that excludes mid-sized contractors from tier-one procurement.
- Cloud Data Sovereignty:Classified government infrastructure projects in defense and intelligence verticals retain on-premise deployment preferences, fragmenting vendor R&D allocation between architectures.
- Motion Sickness Technical Threshold:Sub-90 frames per second rendering in lower-cost hardware creates physiological barriers to extended training session adoption among older worker demographics.
Strategic Opportunities
- EU AI Act Risk Classification:Algorithmic transparency documentation requirements for generative design tools will create compliance service revenue streams for European vendors with established governance frameworks.
- California and New York Building Codes:Emerging mandates for immersive hazard walkthroughs as pre-permit requirements would fundamentally alter sales cycle timing and expand addressable buyer committees.
- Digital Twin Convergence:Integration of spatial data capture infrastructure with real-time sensor feeds is opening infrastructure owner contracts previously reserved to traditional engineering consultancies.
Industry Challenges
- Interoperability Skill Scarcity:BIM-to-VR pipeline engineering requires cross-trained technicians fluent in both ISO 19650 data protocols and Unity/Unreal engine deployment, creating talent acquisition bottlenecks.
- Workers' Compensation Insurer Validation:Safety training modules must achieve actuarial recognition from carriers before procurement committees can justify replacement of established physical simulation equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Reality in Construction Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13.81 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Design Visualization, Safety Training, Project Management, Virtual Tours Technology: VR Software, Hardware Systems, 3D Modeling Tools, Rendering Solutions End User: Architects, Contractors, Engineers, Developers Deployment Model: On-Premise, Cloud-Based, Hybrid, Standalone |
| Companies Covered | Realworld One, HQSoftware, Meta, Takeaway Reality, Program-Ace, Matterport, TSUKAT, Treeview, Varjo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Reality in Construction Market Emerging Trajectories
Head-mounted display engineering is compressing form factors while preserving aviation-grade resolution thresholds, enabling field deployment without dedicated simulation facilities. This hardware evolution is redrawing competitive boundaries between enterprise VR specialists and construction-technology incumbents.
Photorealistic headset resolution is miniaturizing through Varjo's foveated rendering architectures, maintaining 60 pixels per degree acuity in reduced-weight form factors. Mission-critical construction verticals including nuclear containment and aviation-adjacent infrastructure are adopting these systems for sub-millimeter tolerance verification. The technology is miniaturizing deployment footprints from fixed simulation centers to mobile job-site trailers, compressing capital requirements for tier-two contractors.
FAA simulator qualification standards and OSHA workplace training guidelines are converging to validate VR platforms for high-risk construction certifications. This regulatory alignment is creating unified procurement specifications that span aviation, energy, and commercial verticals. Equipment vendors serving multiple regulated industries are consolidating compliance documentation to accelerate cross-sector sales cycles.
Buyer committees are unbundling hardware procurement from content licensing, demanding modular software subscriptions that scale with project pipeline volatility. Multi-site contractors in Texas and California are piloting usage-based pricing for centralized cloud content libraries. This consumption-pattern shift is pressuring integrated hardware-software vendors to disaggregate pricing architectures or risk exclusion from enterprise RFP processes.
Virtual Reality in Construction Market Segmentation
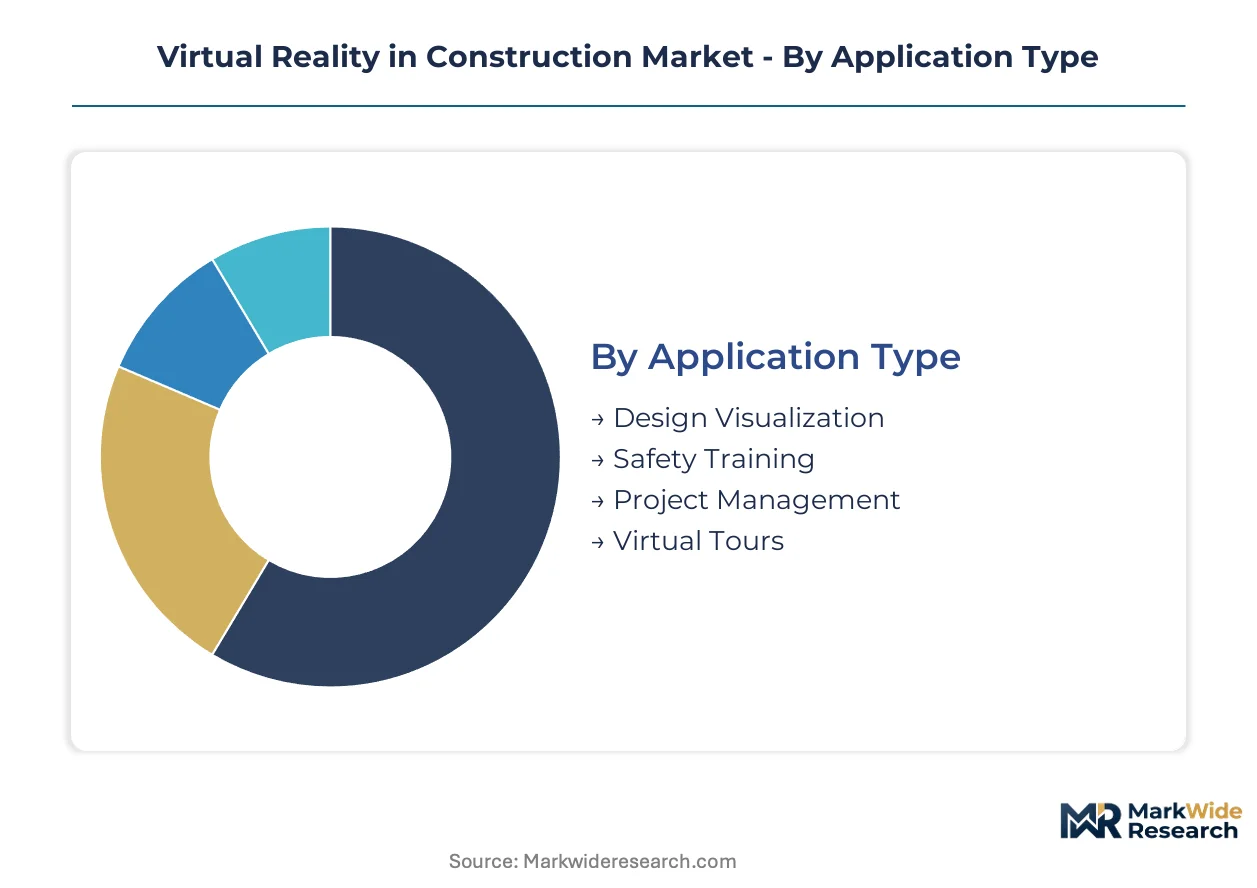
VR procurement in construction fragments across four intersecting dimensions, each channeling different buyer budgets and technical requirements. Application type determines whether sales cycles run through safety departments or design studios, while deployment model dictates whether vendors compete on capital expenditure or operational expenditure terms.
Application Type:
Safety Training and Design Visualization dominate direct enterprise sales, while Project Management and Virtual Tours increasingly route through software resellers and BIM consultancies.
- Safety Training:Immersive hazard simulation modules replicate crane operations, fall protection scenarios, and confined space entry at 90 frames per second to prevent motion sickness during extended sessions. Demand concentrates among Texas and California general contractors facing OSHA crane certification mandates, with procurement committees requiring actuarial validation from workers' compensation insurers before replacing physical simulation equipment.
- Design Visualization:Photorealistic architectural walkthroughs enable client sign-off on complex commercial high-rise geometries before groundbreaking, collapsing revision cycles that previously required physical mockups. Architects in Los Angeles and San Francisco metro corridors leverage these tools for megaproject stakeholder alignment, where ISO 19650-certified BIM-to-VR pipelines are becoming mandatory in vendor qualification.
- Project Management:4D construction sequencing overlays temporal data on spatial models for site logistics optimization.
- Virtual Tours:Pre-construction marketing tools for developer sales centers and investor presentations.
By volume, Safety Training leads procurement committees. By growth pace, Design Visualization is climbing the fastest as ISO 19650 certification mandates deepen BIM-VR integration requirements.
Technology:
Hardware Systems and VR Software capture divergent margin profiles, with the former requiring field service infrastructure and the latter scaling through subscription renewals.
- Hardware Systems:Head-mounted displays with aviation-grade resolution thresholds deliver 60 pixels per degree acuity for sub-millimeter tolerance verification in mission-critical verticals. Nuclear containment and aviation-adjacent infrastructure projects in Houston and Dallas drive demand for Varjo-class photorealistic units, though per-unit pricing excludes mid-sized contractors from tier-one procurement.
- VR Software:Modular content platforms enable centralized library management across multi-site contractor portfolios, with cloud-based deployment accelerating fastest among firms seeking to avoid hardware refresh cycles. California and Texas multi-site operators are piloting usage-based pricing for these centralized repositories.
- 3D Modeling Tools:Unity and Unreal engine deployments requiring cross-trained technicians fluent in both ISO 19650 protocols and immersive pipeline engineering.
- Rendering Solutions:Foveated architectures that reduce computational load while preserving peripheral visual fidelity.
Hardware Systems generate the highest absolute revenue per contract. VR Software subscriptions are expanding most quickly as buyer committees unbundle procurement from content licensing.
End User:
Contractors and Architects sit at opposite ends of the specification chain, with the former controlling implementation budgets and the latter influencing design-phase software selection.
- Contractors:General contractors in commercial high-rise development are expanding VR adoption for site logistics planning, with OSHA's updated crane operation training mandates compressing sales cycles for immersive simulation platforms. Texas and California megaproject density drives centralized software procurement for this segment.
- Architects:Design-phase visualization requirements are pushing firms toward photorealistic headset resolution that meets client presentation standards, extending procurement influence into mission-critical construction verticals.
- Engineers:Structural and MEP specialists using VR for clash detection and systems coordination.
- Developers:Pre-construction marketing and investor relations functions driving Virtual Tours adoption.
Contractors control the largest aggregate spending authority. Architects are gaining procurement influence fastest as ISO 19650 workflows collapse barriers between BIM and immersive environments.
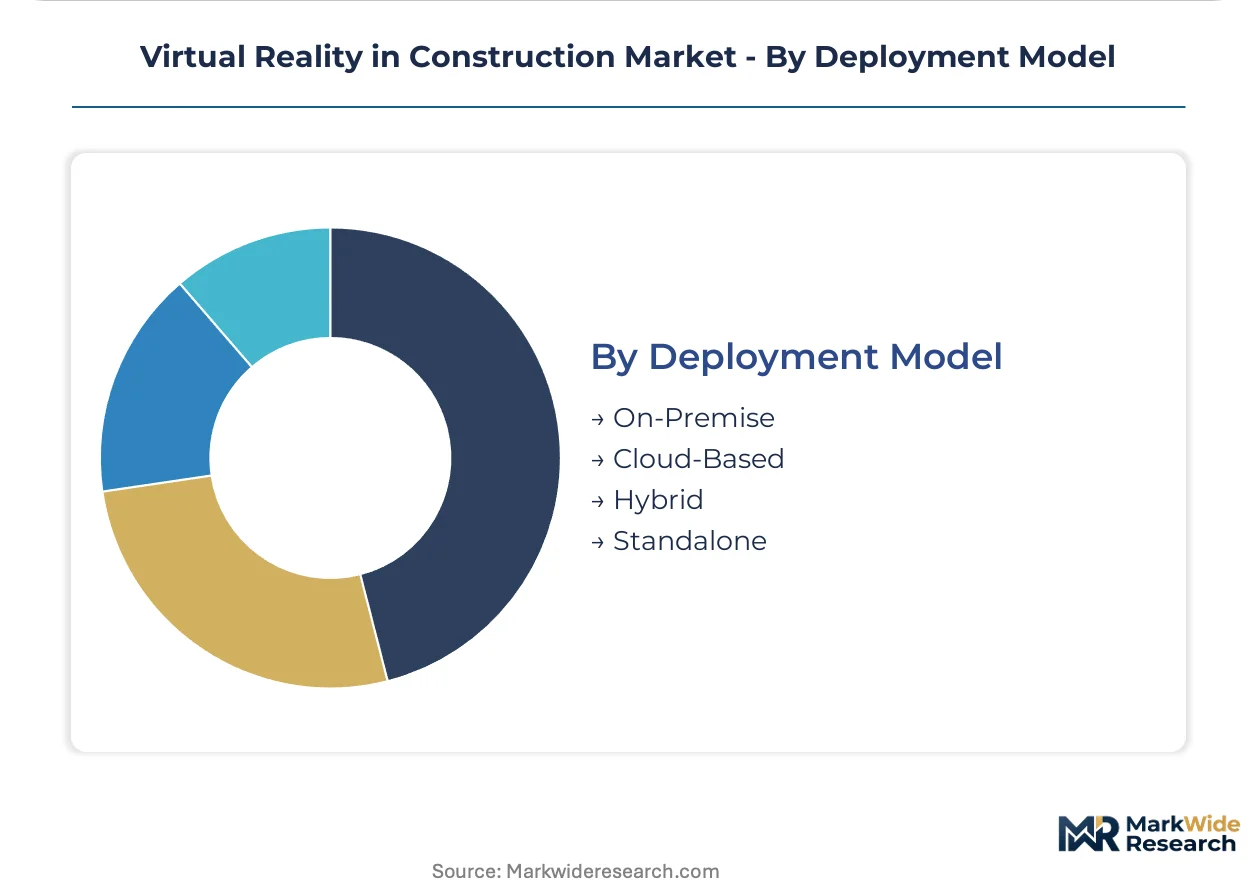
Deployment Model:
Cloud-Based and On-Premise configurations serve mutually exclusive buyer risk profiles, with data sovereignty requirements fragmenting vendor R&D allocation.
- Cloud-Based:Centralized content libraries enable multi-site contractors to standardize training modules and design assets without hardware refresh cycles, accelerating fastest among Texas and California firms with distributed project portfolios. Subscription pricing aligns vendor incentives with client usage patterns.
- On-Premise:Classified government infrastructure projects in defense and intelligence verticals retain this deployment preference, where data sovereignty overrides convenience and air-gapped networks are mandatory.
- Hybrid:Sensitive project data on-premise with collaboration tools cloud-hosted.
- Standalone:Mobile job-site trailers with reduced infrastructure requirements for tier-two contractors.
Cloud-Based deployments are expanding most quickly. On-Premise retains the highest contract values per installation due to customization and security requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
General contractors with distributed project portfolios drive procurement concentration in jurisdictions with dense vertical build activity and stringent training mandates. Buyer committees prioritize vendors demonstrating compliance documentation across multiple regulatory frameworks.
United States
OSHA crane operation certification requirements compress sales cycles for immersive simulation platforms among Texas and California general contractors. Federal workplace training guidelines validate VR systems for high-risk construction certifications. Houston and Dallas megaproject corridors drive centralized software procurement for site logistics planning.
Germany
ISO 19650 certification mandates for building information management deepen BIM-to-VR integration requirements among industrial contractors. EU AI Act risk classification frameworks pressure vendors to document algorithmic transparency in generative design tools. Bavaria and North Rhine-Westphalia engineering clusters adopt photorealistic headsets for sub-millimeter tolerance verification.
China
Dual carbon goals accelerate digital twin deployments for infrastructure efficiency optimization across state-owned construction enterprises. MIIT standards for industrial software interoperability shape vendor qualification criteria. Yangtze River Delta and Pearl River Delta metro corridors concentrate procurement for cloud-based training content libraries.
United Arab Emirates
NEOM and other giga-project developments create concentrated demand for immersive design visualization among international consortiums. Data sovereignty requirements for classified infrastructure sustain on-premise deployment preferences. Dubai and Abu Dhabi developer headquarters drive pre-construction virtual tour adoption for investor presentations.
United Kingdom
Building Safety Regulator mandates for hazard documentation create compliance-driven replacement cycles for legacy training equipment. CSRD sustainability reporting requirements extend to construction technology procurement decisions. London and Southeast England architectural practices lead ISO 19650-certified BIM-VR pipeline adoption for megaproject stakeholder alignment.
Virtual Reality in Construction Market Vendor Landscape
Player mix skews toward enterprise VR specialists with construction-technology incumbents expanding through strategic partnerships. Market structure exhibits moderate consolidation around vendors with established interoperability credentials and regulatory compliance documentation. Three archetypes dominate: photorealistic hardware specialists, spatial data capture platforms, and integrated ecosystem providers. Competitive moves center on ISO 19650 certification attainment and cloud-based subscription model transitions.
Among photorealistic hardware specialists, Varjo occupies a position exemplifying aviation-grade resolution standards that extend into mission-critical construction verticals. Matterport represents the spatial data capture archetype, anchoring large-scale digital twin deployments for infrastructure owners. Meta sits within the integrated ecosystem tier, sustaining developer loyalty through hardware-software stacks that reduce deployment friction.
| Leading Market Players |
|---|
| Realworld One |
| HQSoftware |
| Meta |
| Takeaway Reality |
| Program-Ace |
| Matterport |
| TSUKAT |
| Treeview |
| Varjo |
| Others |
Supply Flow & Price Mechanics
Fourteen-to-eighteen-week lead times for aviation-grade headset displays concentrate procurement power among Tier 1 contractors with sufficient balance-sheet depth to absorb pre-payment requirements, while mid-sized firms face exclusion from photorealistic hardware tiers due to working-capital constraints.
Pricing Analysis
Cost-plus contracts with semiconductor price indexation dominate enterprise headset procurement, insulating vendors from DRAM and OLED panel volatility while transferring margin risk to buyers. Price differentiation rests on ISO 19650 certification tier and after-sales field service bundling. Cost compression in mid-tier hardware is intensifying because Chinese display manufacturers are scaling foveated rendering alternatives. General contractors with distributed project portfolios exhibit highest price sensitivity, whereas nuclear and aviation-adjacent infrastructure buyers prioritize resolution specifications over unit economics.
Supply Chain Analysis
Just-in-time inventory strategies prevail among cloud-based software vendors, while hardware manufacturers maintain strategic stockpiles of optical components given Taiwan and South Korea foundry concentration. The supply chain draws from precision lens grinding in Germany, microdisplay fabrication in Japan, and final assembly in China. Single-source vulnerability in foveated rendering chipsets poses structural risk. Distribution runs through specialized AV integrators and BIM consultancy channels rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as ISO 19650 interoperability requirements collapse standalone hardware margins into integrated ecosystem plays.
For Market Incumbents: Compound ecosystem lock-in by embedding training content libraries within hardware-software stacks, neutralizing modular subscription threats from pure-play software vendors. Prioritize backward integration into spatial data capture to defend against Matterport-class digital twin encroachment. Accelerate FAA-OSHA dual certification documentation to capture cross-vertical procurement committees. For New Entrants and Emerging Players: ISO 19650 fast-track certification programs open procurement access to UK and German architectural practices where incumbent hardware relationships remain shallow. Target standalone deployment configurations for tier-two contractors excluded from Varjo-class pricing tiers. Pursue channel partnerships with regional BIM consultancies rather than direct enterprise sales. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-infrastructure play because OSHA mandate expansion and building code pre-permit requirements will institutionalize VR procurement as non-discretionary spend. Acquisition targets should display established interoperability credentials and regulatory documentation archives. Monitor California and New York legislative dockets for immersive hazard walkthrough mandate announcements as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 19650 Certification Investment | Qualifies vendors for UK and German public sector procurement where BIM-VR interoperability is mandatory. |
| Cloud Content Library Expansion | Enables usage-based pricing pilots among Texas and California multi-site contractors seeking operational expenditure alignment. |
| FAA-OSHA Dual Compliance Documentation | Consolidates cross-sector sales cycles spanning aviation, energy, and commercial verticals under unified specifications. |
| Spatial Data Capture Integration | Opens infrastructure owner contracts previously reserved to traditional engineering consultancies through digital twin anchoring. |
| Mobile Job-Site Trailer Deployment | Compresses capital requirements for tier-two contractors excluded from fixed simulation center investments. |
Methodological Framework
Cross-validation between primary interviews with VR platform engineers, construction safety directors, and BIM consultancy principals and secondary validation through OSHA regulatory filings, FAA simulator qualification databases, and ISO certification registries anchors the qualitative findings. Bottom-up triangulation against top-down macroeconomic indicators ensures segmentation integrity across deployment models and application types.
Sensitivity analysis around headset hardware cost trajectories and cloud adoption velocity shapes the analytical framework across the modeling period. Segmentation dimensions include application type, deployment architecture, end-user category, and regional regulatory cluster. CAGRs derive from installed base growth curves and replacement cycle compression observed in crane operation training mandates. Industry-specific inputs incorporate workers' compensation insurer validation timelines and building code amendment pipelines.
Underlying assumptions cover OSHA mandate enforcement consistency and ISO 19650 adoption velocity across European jurisdictions, with deviation risk concentrated in EU AI Act algorithmic transparency implementation schedules. Forecasts reflect these conditions without claiming predictive certainty. Revision becomes warranted when immersive hazard walkthrough pre-permit requirements cross legislative thresholds in California or New York.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Telepresence Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Para-Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
France Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality (AR) Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
VR in Sports Market
Virtual Reality (VR) and Augmented Reality (AR)
Extended Reality Display Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented and Virtual Reality (AR VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Amusement Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Spatial Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Germany Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality (AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality and Virtual Reality in Manufacturing Market