
 AR Glasses Market | 2026-2036
AR Glasses Market Size, Share, and Industry Trends Forecast 2026-2036
AR Glasses Market Analysis
High-resolution optical waveguide specifications is collapsing the gap between consumer aesthetics and enterprise functionality. XREAL, Inc. leverages proprietary birdbath optics to anchor premium consumer positioning. Magic Leap, Inc. sustains deep R&D intensity in photonic lightfield architectures for healthcare and defense applications. Microsoft dominates enterprise software-hardware integration through its Azure-connected industrial headset ecosystem.
AR glasses overlay digital information onto the physical world through transparent or semi-transparent displays, typically employing waveguide combiners or micro-projectors with field-of-view parameters exceeding 40 degrees for immersive utility. Their primary commercial purpose spans hands-free workflow guidance, real-time data visualization, and spatial computing interfaces across industrial and consumer contexts. Smart Glasses lead volume shipments as lightweight form factors penetrate retail and logistics end users, while Head-Mounted Displays concentrate margin pools in healthcare and defense where optical precision commands premium pricing. Optical Waveguide technology is displacing earlier prism-based architectures as manufacturers prioritize thickness reduction and luminance efficiency for all-day wearability.
FCC equipment authorization frameworks govern radio-frequency emissions for wireless-connected AR devices in the United States, while FDA oversight applies to diagnostic and surgical visualization claims in healthcare deployments. The EU AI Act and GDPR impose algorithmic transparency and biometric data restrictions on gaze-tracking and facial analysis features, reshaping product architecture for European market access. Stakeholders must monitor whether optical waveguide supply bottlenecks or regional content localization requirements become the binding constraint on geographic expansion.
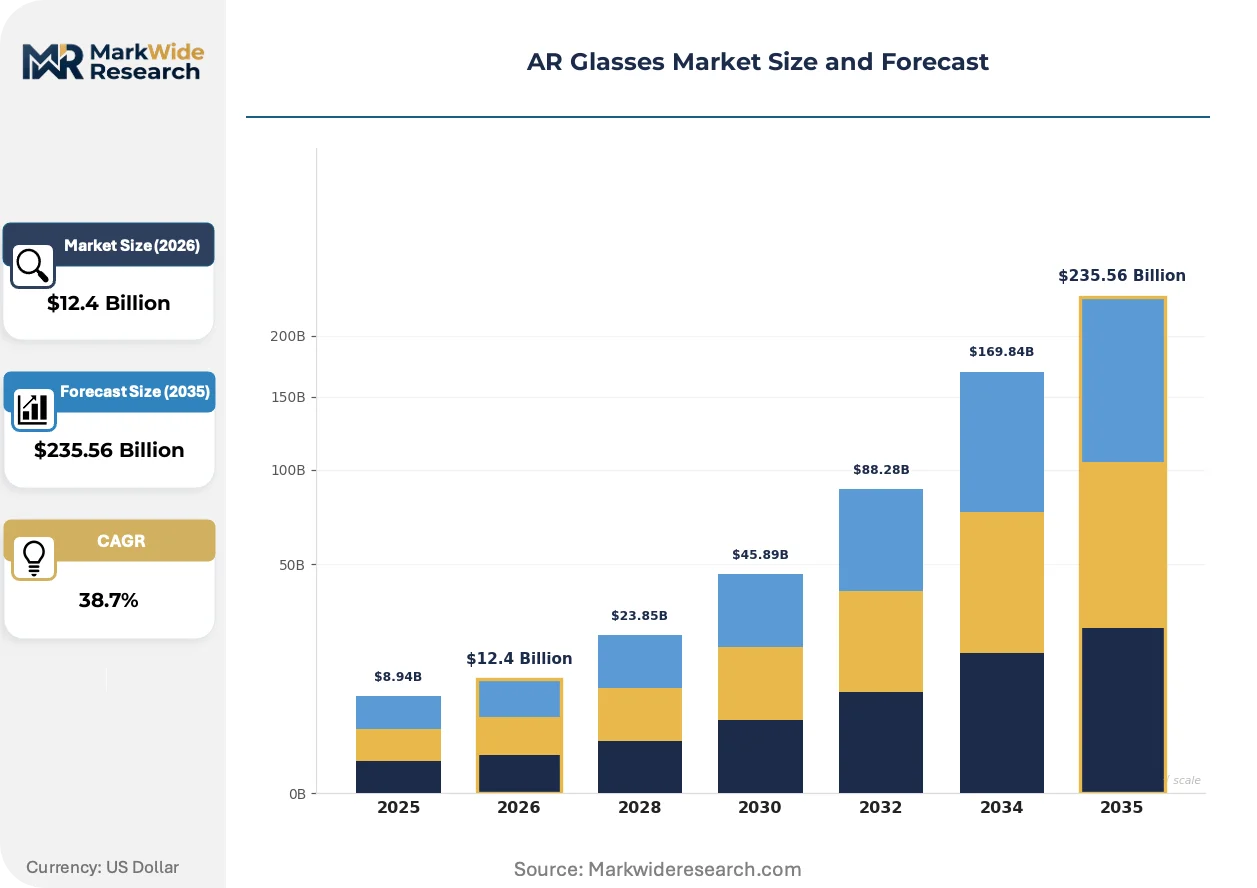
Market Dynamics
Optical waveguide supply concentration in East Asian photonics clusters is compressing component lead times and forcing hardware architects toward dual-source qualification strategies. This supply-side bottleneck is reshaping how enterprise and consumer OEMs stage their product roadmaps.
Growth Catalysts
- FDA 510(k) Pathway Clarity:The FDA's emerging guidance on optical see-through surgical displays is accelerating hospital procurement cycles for telemedicine training hardware. Health systems in the United States are expanding pilot programs.
- MIIT Smart Factory Mandates:China's Ministry of Industry and Information Technology directives for digital twin integration on assembly lines are pulling head-mounted displays into automotive and electronics manufacturing floors.
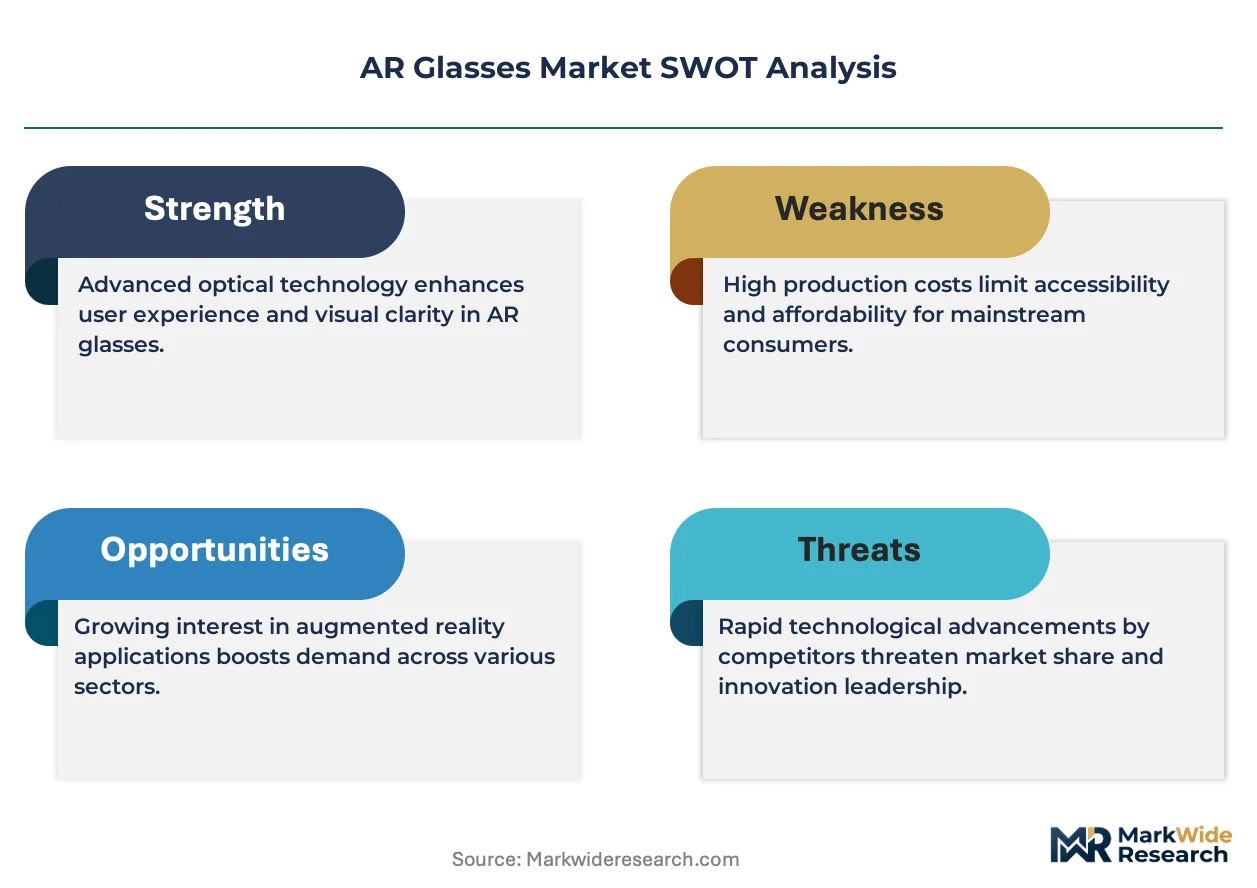
- Photonic Integration:Silicon nitride waveguide fabrication is collapsing the cost curve for high-brightness combiners, enabling thinner form factors that bridge consumer aesthetics with enterprise luminance requirements.
Market Restraints
- Input Cost Volatility:Rare-earth dopants for laser diode pump sources face price swings tied to Chinese export quota adjustments, squeezing margin structures for micro-projector subassemblies.
- Supply Concentration Risk:High-index glass wafer processing for waveguide substrates clusters in Japanese and Korean specialty foundries, creating single-source vulnerability for tier-two OEMs.
- Technical Limitation:Field-of-view expansion beyond 50 degrees without pupil swim distortion remains unresolved in birdbath architectures, capping immersive utility for gaming applications.
Strategic Opportunities
- Underpenetrated Geographies:India's industrial corridor shows minimal AR hardware penetration despite PLI scheme incentives for electronics manufacturing, creating first-mover whitespace for localized assembly partnerships.
- Regulatory Tailwind:The EU AI Act's risk-classification framework for biometric gaze-tracking is clarifying compliance boundaries, enabling European healthcare providers to greenlight diagnostic visualization deployments.
- Technology Convergence:Integration of edge AI inference chips with waveguide displays is enabling real-time object recognition without cloud tethering, opening field-service applications in bandwidth-constrained environments.
Industry Challenges
- Optomechanical Talent Scarcity:The intersection of precision optics design and thermal management engineering remains thinly staffed, elongating R&D timelines for waveguide-integrated thermal solutions.
- Certification Timeline Compression:FCC equipment authorization for millimeter-wave wireless connectivity in AR glasses faces backlog at test laboratories, delaying product launches by six to nine months.
- Legacy System Integration:Enterprise IT departments struggle to bridge Azure-connected industrial headsets with proprietary manufacturing execution systems, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AR Glasses Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $235.56 Billion |
| CAGR (2026 – 2036) | 38.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Glasses, Head-Mounted Displays, Lightweight Glasses, Enhanced Reality Visors End User: Retail, Education, Healthcare, Entertainment Technology: Optical Waveguide, Projection Technology, Display Technology, Sensor Technology Application: Gaming, Virtual Tours, Remote Assistance, Training |
| Companies Covered | XREAL, Inc., Magic Leap, Inc., Microsoft, Seiko Epson Corporation, Rokid, RealWear, Inc., Vuzix, Meta, EssilorLuxottica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AR Glasses Market Emerging Trajectories
Waveguide miniaturization and edge compute integration are converging to redefine performance benchmarks across consumer and enterprise form factors. Hardware architects are prioritizing luminance efficiency and thermal dissipation in lockstep.
Silicon nitride waveguide platforms are supplanting earlier silicon-on-insulator architectures for augmented reality combiners. Automotive head-up display manufacturers are adopting these platforms at accelerated cadences. The shift is compressing the traditional three-year optical qualification cycle into eighteen-month iterations.
The EU AI Act's algorithmic transparency mandates for biometric inference are reshaping firmware architecture for gaze-tracking subsystems. Device manufacturers must now document training data provenance and decision logic for European market access. Healthcare visualization OEMs are responding by segregating on-device inference from cloud analytics to limit regulatory exposure.
Industrial buyers are consolidating vendor relationships around full-stack hardware-software-service bundles rather than point-product procurement. This pattern concentrates purchasing power with Azure-connected ecosystem providers and squeezes standalone hardware vendors. German automotive assembly plants exhibit the most pronounced shift toward outcome-based fleet management contracts.
AR Glasses Market Segmentation
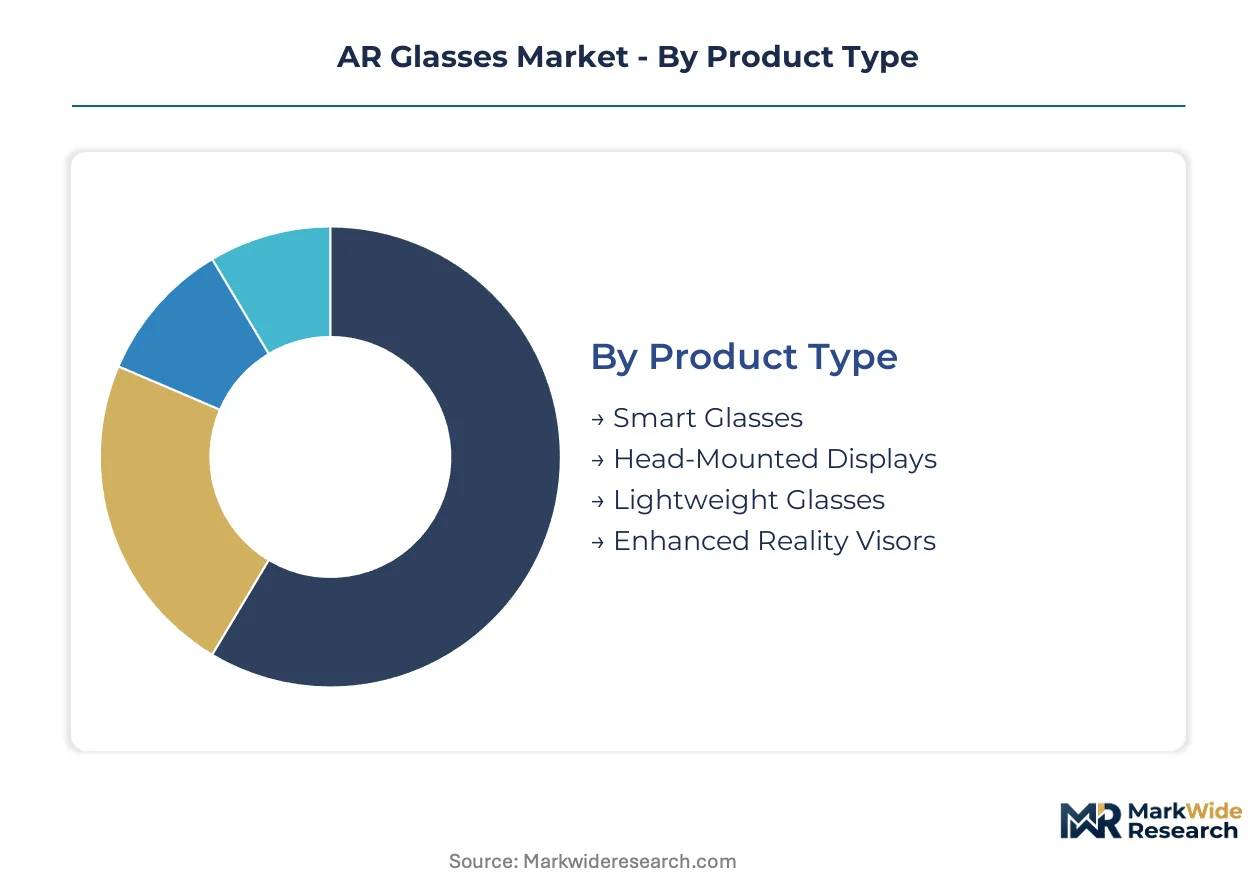
AR glasses segmentation reveals how hardware architects balance optical performance against wearability constraints. Product form factors and display technologies command divergent margin structures, while end-user applications determine pricing power and procurement cycles.
Product Type:
Margin pools concentrate in specialized form factors where optical precision justifies premium positioning, while volume shipments flow toward lightweight consumer-oriented designs.
- Smart Glasses:Lightweight frames with micro-projector or waveguide displays deliver hands-free notification access and basic overlay functionality. Retail and logistics operators in the United States are expanding fleet deployments for inventory management workflows.
- Head-Mounted Displays:High-resolution optical see-through systems with field-of-view parameters exceeding 50 degrees serve surgical training and telemedicine applications. FDA 510(k) pathway clarity is accelerating hospital procurement cycles for these devices.
- Lightweight Glasses:Consumer-oriented birdbath optic designs prioritize all-day wearability over immersive utility. XREAL, Inc. anchors premium positioning in this segment through proprietary optical architectures.
- Enhanced Reality Visors:Enclosed headsets with passthrough camera systems blend virtual and augmented environments for gaming and enterprise simulation.
The dominant share belongs to Smart Glasses, while Head-Mounted Displays is closing the gap fastest.
End User:
Application-specific regulatory requirements and procurement sophistication create tiered pricing structures across customer categories.
- Retail:Warehouse operators and last-mile logistics providers deploy Smart Glasses for pick-and-pack guidance and hands-free scanning. MIIT smart factory mandates in China are pulling comparable hardware into automotive parts distribution centers.
- Healthcare:Surgical visualization and remote assistance applications command the highest unit economics. Magic Leap, Inc. sustains R&D intensity in photonic lightfield architectures specifically for diagnostic and therapeutic deployments.
- Education:Vocational training programs adopt Head-Mounted Displays for hazardous environment simulation before field deployment.
- Entertainment:Gaming and immersive content consumption drives consumer volume but compresses margins through price-sensitive purchasing patterns.
Healthcare captures the highest margins per unit, with Retail expanding most quickly through enterprise fleet standardization.
Technology:
Display architecture choices determine luminance efficiency, form factor thickness, and manufacturing cost structures simultaneously.
- Optical Waveguide:Silicon nitride and high-index glass substrates enable see-through displays with sub-2mm thickness profiles. Japanese and Korean specialty foundries concentrate wafer processing capacity, creating supply bottlenecks for tier-two OEMs.
- Projection Technology:Laser-based pico-projector systems face input cost volatility from rare-earth dopant price swings tied to Chinese export quota adjustments.
- Display Technology:Micro-OLED and Micro-LED backplanes deliver pixel densities exceeding 3000 ppi for high-resolution near-eye applications.
- Sensor Technology:Gaze-tracking and spatial mapping subsystems integrate accelerometers, gyroscopes, and infrared cameras for six-degrees-of-freedom positioning.
Optical Waveguide holds the technology leadership position, while Sensor Technology is gaining share fastest through EU AI Act biometric compliance requirements.
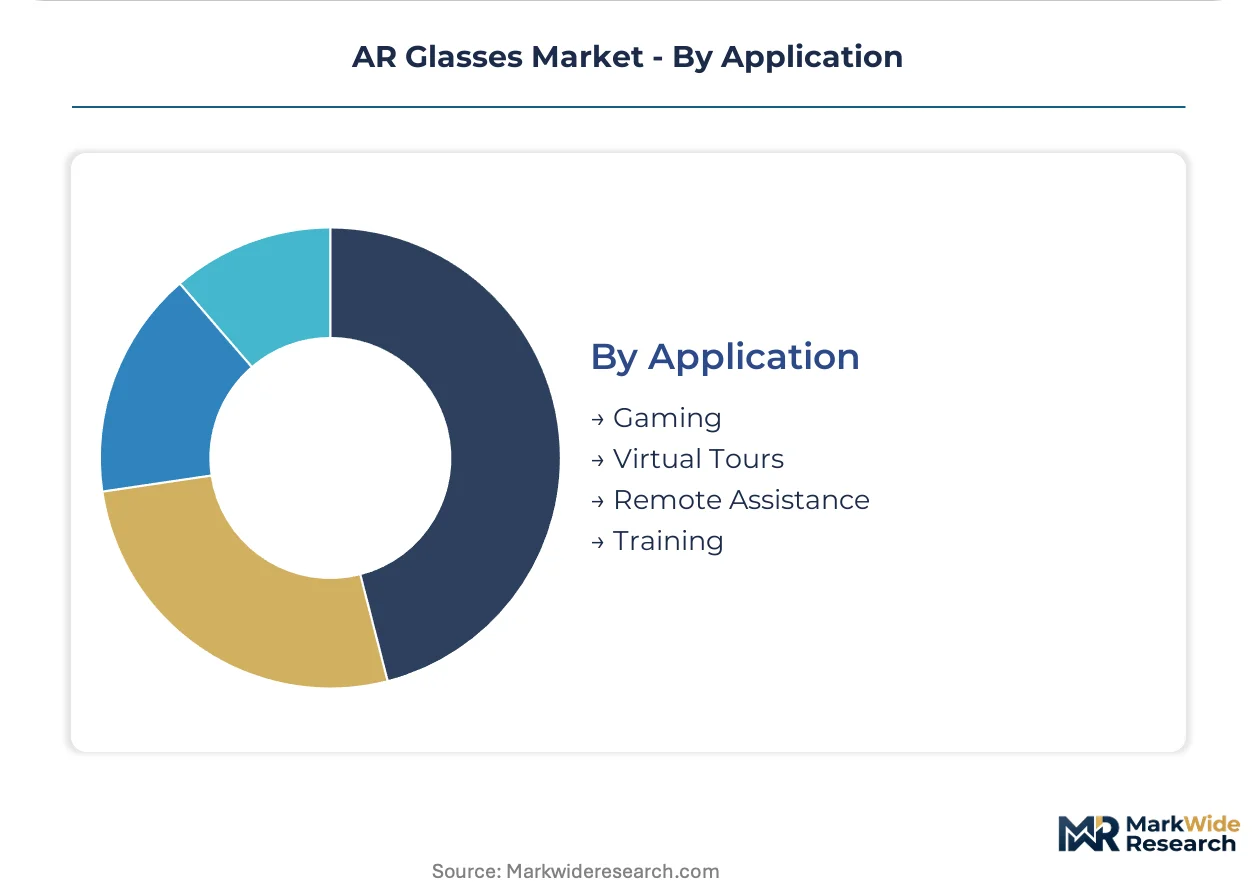
Application:
Use case maturity determines whether deployments prioritize standalone functionality or cloud-tethered compute architectures.
- Remote Assistance:Field-service technicians access expert guidance through shared visual feeds and spatial annotations. German automotive assembly plants are consolidating vendor relationships around Azure-connected full-stack bundles for this application.
- Training:Hazardous environment simulation and procedural rehearsal reduce live-training costs and safety incidents. Healthcare systems are expanding pilot programs for surgical telemedicine training hardware.
- Gaming:Immersive entertainment applications demand expanded field-of-view without pupil swim distortion, a technical limitation unresolved in current birdbath architectures.
- Virtual Tours:Real estate and cultural institution deployments leverage location-based content for visitor engagement.
Remote Assistance commands the deepest enterprise penetration, with Training showing the steepest expansion trajectory through regulatory tailwinds in European healthcare markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and Korean specialty foundries concentrate high-index glass wafer processing for waveguide substrates, creating supply bottlenecks that reshape procurement strategies for tier-one OEMs across consumer and enterprise segments.
United States
Hospital procurement cycles for surgical training hardware accelerate as FDA 510(k) pathway clarity emerges for optical see-through displays. The FCC governs millimeter-wave equipment authorization for wireless-connected devices, with test laboratory backlogs extending launch timelines. Boston and San Francisco anchor healthcare visualization pilot programs, while Seattle hosts Azure-connected industrial headset development.
China
MIIT smart factory mandates pull head-mounted displays into automotive and electronics manufacturing floors across the industrial corridor. SAMR oversees equipment standards compliance for workplace deployment. The Yangtze River Delta and Pearl River Delta concentrate assembly-line guidance hardware adoption, with Shenzhen hosting the densest cluster of waveguide-integrated device manufacturing.
Germany
Automotive assembly plants consolidate vendor relationships around Azure-connected full-stack bundles for remote assistance workflows. The KBA monitors vehicle-integrated AR display safety claims, while GDPR and EU AI Act requirements reshape gaze-tracking firmware architecture. Bavaria and Baden-Württemberg host the densest concentration of outcome-based fleet management contracts for industrial headsets.
Japan
METI industrial digitization programs accelerate enterprise adoption of head-mounted displays for precision manufacturing guidance. PMDA oversight applies to diagnostic visualization claims in healthcare deployments. Tokyo and Osaka anchor photonics R&D clusters, with Nagoya hosting specialized foundries for silicon nitride waveguide fabrication.
South Korea
MFDS regulatory frameworks clarify commercialization routes for medical-grade optical see-through systems. Samsung and LG supply chain affiliates drive micro-OLED backplane integration for near-eye displays. Seoul and Busan concentrate display technology manufacturing, with Daegu-Gyeongbuk hosting specialty glass processing operations for waveguide substrates.
AR Glasses Market Vendor Landscape
Concentration sits with technology-integrated platform providers rather than standalone hardware vendors. Microsoft anchors enterprise software-hardware integration through Azure-connected ecosystems, while consumer-oriented specialists compete on optical architecture differentiation. Strategic archetypes include full-stack industrial platform providers, premium consumer optics specialists, and healthcare visualization technology developers. Competitive moves center on waveguide supply chain dual-sourcing qualification and edge AI inference chip integration for bandwidth-constrained deployments.
Within the premium consumer optics tier, XREAL, Inc. and Magic Leap, Inc. occupy distinct positioning vectors. XREAL, Inc. represents the birdbath architecture specialist segment targeting lightweight all-day wearability. Magic Leap, Inc. exemplifies photonic lightfield R&D intensity for healthcare and defense applications. Microsoft anchors the enterprise platform integration archetype through its Azure-connected industrial headset ecosystem, consolidating vendor relationships around full-stack hardware-software-service bundles.
| Leading Market Players |
|---|
| XREAL, Inc. |
| Magic Leap, Inc. |
| Microsoft |
| Seiko Epson Corporation |
| Rokid |
| RealWear, Inc. |
| Vuzix |
| Meta |
| EssilorLuxottica |
| Others |
Supply Flow & Price Mechanics
Silicon nitride waveguide fabrication scale economies in Japanese and Korean specialty foundries simultaneously compress unit costs for high-brightness combiners and concentrate pricing power among tier-one OEMs with dual-source qualification capabilities. This capacity-utilization dynamic creates asymmetric margin pressure where tier-two hardware architects absorb input cost volatility while tier-one players extract premium positioning through supply security guarantees.
Pricing Analysis
FDA 510(k) pathway clarity dictates the pricing tier structure for surgical visualization hardware, separating FDA-cleared head-mounted displays from uncertified enterprise variants. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade, optical waveguide specification, and after-sales service bundling. Cost compression in the standard tier intensifies because Chinese MIIT smart factory mandates are pulling comparable hardware into industrial applications at volume scale. Retail and logistics operators exhibit the highest price sensitivity, while healthcare systems demonstrate the lowest due to reimbursement-adjacent procurement frameworks.
Supply Chain Analysis
Tsugaru Strait maritime transit underwrites critical photonics component flows between Japanese waveguide foundries and Korean micro-OLED backplane facilities. Geographic supply concentration centers on Japan, South Korea, and China, with raw material dependencies spanning rare-earth dopants for laser diodes, high-index glass substrates, and silicon nitride wafers. Single-source vulnerability in Japanese specialty foundries creates structural risk for tier-two OEMs lacking dual-source relationships. Distribution runs through direct enterprise fleet contracts for industrial headsets and consumer electronics retail channels for lightweight glasses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AR glasses market is emerging from a cyclical trough as FDA regulatory clarity and MIIT industrial mandates synchronize procurement cycles across healthcare and manufacturing verticals. Capital expenditure normalization in East Asian photonics clusters signals capacity expansion that will reshape competitive economics over the next technology cycle.
For Market Incumbents: Shield margin position by accelerating backward integration into silicon nitride waveguide fabrication through joint ventures with Japanese specialty foundries. Incumbent OEMs must simultaneously harden Azure-connected ecosystem lock-in against emerging edge-AI inference chip alternatives that threaten cloud-tethered architectures. Vertical integration into photonic lightfield R&D represents the critical defensive lever against Magic Leap's healthcare specialization.
For New Entrants and Emerging Players: Anchor in India's underpenetrated industrial corridor where PLI scheme incentives for electronics manufacturing create first-mover whitespace for localized assembly partnerships. New entrants should target field-service remote assistance applications in bandwidth-constrained environments, exploiting the technology convergence between edge AI inference and waveguide displays that incumbents have underinvested in. A direct enterprise sales model with outcome-based pilot contracts offers the most viable go-to-market angle against Microsoft's bundled ecosystem dominance.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors photonics-integrated platform providers over standalone hardware vendors. Long-term viability hinges on waveguide supply chain dual-sourcing capabilities and edge compute integration depth rather than consumer brand recognition. Acquisition target archetypes include silicon nitride fabrication specialists and gaze-tracking firmware developers with EU AI Act compliance documentation. The signal to watch is FCC equipment authorization timeline compression, which would indicate regulatory capacity expansion and accelerate product launch velocity across the vendor base.
| Strategic Initiative | Industry Significance |
|---|---|
| Waveguide Supply Dual-Source Qualification | Reduces single-source vulnerability to Japanese and Korean specialty foundry concentration. |
| Edge AI Inference Chip Integration | Enables real-time object recognition without cloud tethering for bandwidth-constrained field service. |
| FDA 510(k) Submission Acceleration | Captures hospital procurement cycles as optical see-through surgical display guidance clarifies. |
| EU AI Act Firmware Segregation | Limits regulatory exposure by separating on-device inference from cloud analytics for European access. |
| Azure-Connected Ecosystem Expansion | Consolidates vendor relationships around full-stack hardware-software-service bundles in German automotive. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, FDA 510(k) submission databases, MIIT equipment standards documentation, and hyperscaler capex disclosures. Primary interviews engaged optical engineers at waveguide foundries, hospital biomedical equipment procurement committees, automotive manufacturing IT directors, and enterprise fleet managers at logistics operators. Secondary validation drew from customs trade data for photonics components, GPO contracts for surgical visualization hardware, and EU regulatory filings for AI Act compliance. Bottom-up shipment estimates triangulated against top-down addressable market sizing across product type, end user, and technology segmentation.
Segmentation dimensions modeled include product form factor, display technology architecture, end-use application, and geographic regulatory cluster across the analysis window. CAGRs derived from regression analysis of historical procurement cycles against regulatory milestone timing and foundry capacity expansion announcements. Industry-specific forecast inputs incorporated MIIT smart factory mandate implementation schedules and FDA optical see-through guidance publication trajectories.
Decision-makers should treat outputs as directional under assumptions of continued East Asian photonics cluster dominance and stable rare-earth export quota regimes; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EU AI Act enforcement patterns and FCC equipment authorization backlog resolution evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
VR in Sports Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR in Training Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Collaboration Software Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR Solutions Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented and Virtual Reality (AR VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Industrial Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality (AR) Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Fitting Room Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Immersive Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in BFSI Market
Virtual Reality (VR) and Augmented Reality (AR)
India Desktop Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Extended Reality Display Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Tour Market