
 Global Enterprise Augmented Reality Market | 2026-2036
Global Enterprise Augmented Reality Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enterprise Augmented Reality Market Foresight
Multi-source hardware procurement is expanding as enterprise buyers diversify beyond single-vendor smart glass ecosystems. Microsoft Corporation leverages its HoloLens platform and Azure cloud integration to anchor enterprise deployments across manufacturing verticals. PTC Inc. specializes in industrial AR software through its Vuforia suite, competing on CAD-to-AR workflow continuity. Magic Leap Inc. navigates a narrower niche in design visualization, where its optical technology differentiates against mass-market alternatives.
Enterprise augmented reality encompasses wearable and stationary display systems that overlay digital information—3D models, real-time telemetry, or procedural guidance—onto physical environments through optical see-through or video pass-through architectures, typically operating at 60-90 Hz refresh rates with sub-10 millisecond motion-to-photon latency to prevent user discomfort. Its primary industrial purpose is to reduce operational errors, compress training cycles, and enable remote expert collaboration without physical co-location. Cloud-based deployment leads in new installations among mid-market firms seeking lower capital barriers, while edge computing configurations capture premium margins in defense and energy settings where latency constraints and air-gapped security predominate. SLAM-based technology dominates advanced use cases requiring persistent spatial mapping across large facility footprints, whereas marker-based approaches retain cost advantages in controlled training environments.
FDA scrutiny of AR-enabled surgical and diagnostic tools shapes product validation requirements for healthcare-adjacent enterprise vendors, while FCC equipment authorization governs radio frequency emissions from untethered headsets in US industrial facilities. EASA and national aviation regulators in France and Germany impose stringent human-factors certification on AR systems deployed in cockpit and ground-crew applications, creating compliance moats for established suppliers. Stakeholders must weigh interoperability standards against proprietary ecosystem lock-in as procurement committees consolidate vendor relationships across maintenance, training, and quality assurance functions.
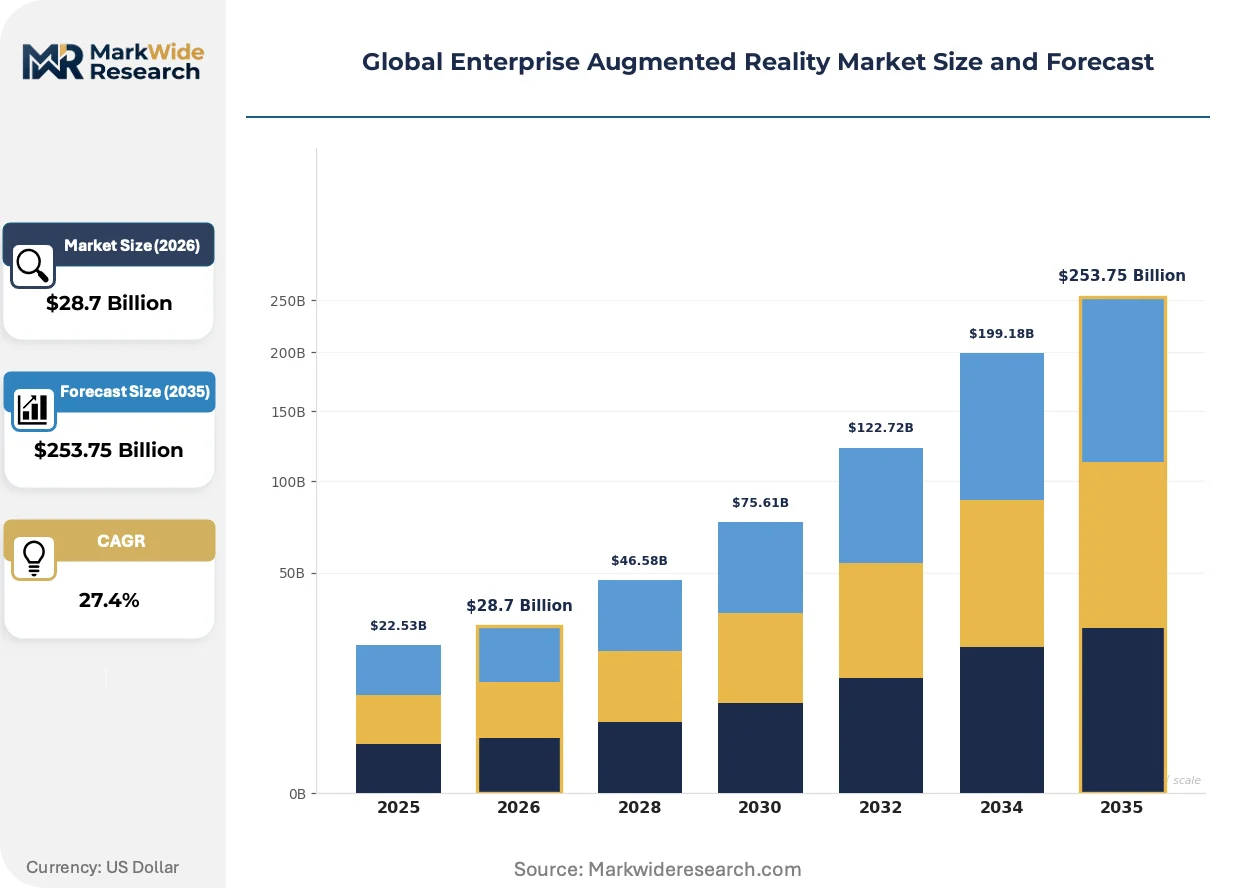
Market Dynamics
Enterprise AR deployment is bifurcating between cloud-native mid-market rollouts and sovereign-edge installations driven by EU AI Act data-localization mandates and defense-sector air-gapping requirements.
Growth Catalysts
- FDA 510(k) pathway expansion:Streamlined premarket notification for AR-guided surgical planning tools accelerates healthcare vendor entry into hospital procurement cycles.
- SLAM algorithm maturation:Persistent spatial mapping without environmental markers enables maintenance workflows in uncontrolled industrial settings.
- German automotive OEM integration:Assembly line quality assurance protocols at BMW and Volkswagen plants establish reference architectures for tier-one supplier adoption.
Market Restraints
- Waveguide display supply concentration:Korean and Taiwanese optical component foundries control 70%+ of high-resolution near-eye display substrate capacity.
- EASA human-factors certification timelines:Cockpit AR system validation requires 18-36 month airworthiness qualification cycles.
- Smartphone AR substitution:Video pass-through on iOS and Android devices satisfies training use cases at one-tenth the hardware cost.
Strategic Opportunities
- India PLI scheme incentives:Production-linked incentives for electronics manufacturing attract AR hardware assembly to Noida and Chennai industrial corridors.
- Digital twin convergence:Real-time sensor fusion between IoT infrastructure and AR visualization layers creates closed-loop maintenance systems.
- Outcome-based service contracts:Aviation MRO providers are piloting performance-linked pricing where AR-guided interventions reduce aircraft downtime guarantees.
Industry Challenges
- Optical engineering talent scarcity:Waveguide design and photonics integration expertise concentrates in Silicon Valley and Munich metropolitan clusters.
- Legacy ERP integration friction:SAP and Oracle system connectivity requires custom middleware development for AR telemetry ingestion.
- ISO/IEC 27001 certification burden:Cloud-deployed enterprise AR platforms face extended security audit cycles for financial services adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enterprise Augmented Reality Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $253.75 Billion |
| CAGR (2026 – 2036) | 27.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Application: Remote Assistance, Training & Simulation, Maintenance & Repair, Design & Visualization, Quality Assurance Technology: Marker-Based, Markerless, Projection-Based, Superimposition-Based, SLAM-Based End User: Manufacturing, Construction, Automotive OEMs, Aerospace & Defense, Energy & Utilities |
| Companies Covered | Microsoft Corporation, PTC Inc., Google LLC, Apple Inc., Meta Platforms Inc., Sony Group Corporation, Magic Leap Inc., Vuzix Corporation, Lenovo Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enterprise Augmented Reality Market Shifts & Advancements
Spatial computing architectures are absorbing compute workloads previously handled by tethered workstations, while regulatory fragmentation across aviation and healthcare verticals forces vendors into jurisdiction-specific product variants.
Optical waveguide technology is absorbing display functions previously requiring bulky projection engines. Aerospace maintenance divisions at Lufthansa Technik and Delta TechOps are deploying waveguide-based headsets for engine inspection workflows. The shift is absorbing capital previously allocated to fixed inspection stations and compressing facility footprint requirements.
EU AI Act risk-classification requirements are mandating conformity assessments for AR systems processing biometric data in workplace monitoring contexts. Industrial software vendors must maintain technical documentation and human-oversight protocols for high-risk applications. German chemical manufacturers are responding by localizing inference workloads on edge servers to limit cross-border data exposure.
Buyer committees are consolidating vendor relationships across maintenance, training, and quality assurance functions rather than procuring point solutions. Systems integrators and industrial distributors are displacing direct OEM sales in mid-market manufacturing verticals. France and Italy exhibit the fastest procurement centralization as engineering holding companies standardize AR platforms across subsidiary operations.
Global Enterprise Augmented Reality Market Segmentation
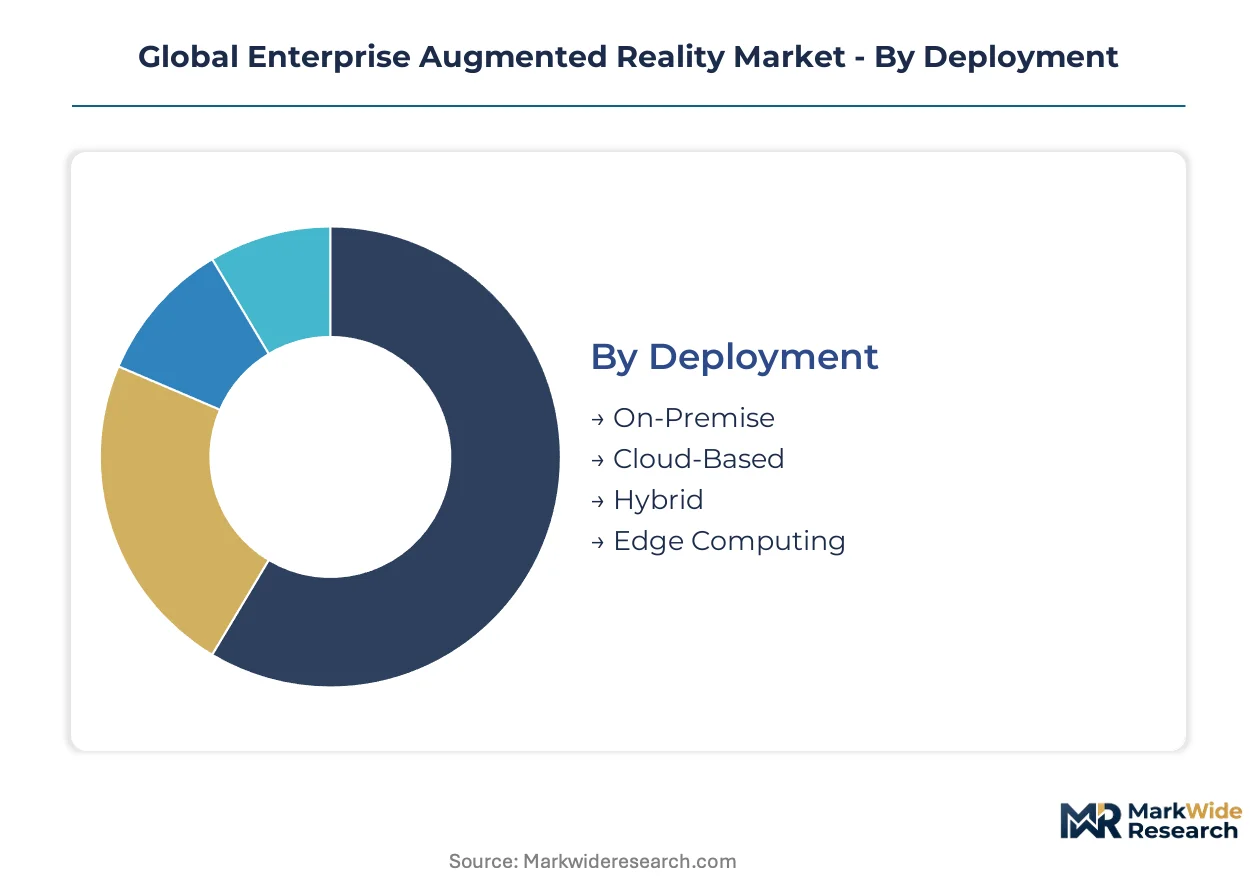
Enterprise AR procurement patterns diverge sharply between volume-driven mid-market rollouts and premium sovereign-edge installations. Deployment architecture, application workflow, and end-user vertical each create distinct margin pools and vendor qualification requirements.
Deployment:
Volume deployments favor subscription models with minimal infrastructure, while premium tiers absorb capital for air-gapped security and sub-10ms latency guarantees.
- On-Premise:Localized server infrastructure processes sensitive telemetry within facility firewalls. German chemical manufacturers and French defense contractors prioritize this architecture to satisfy GDPR data-localization mandates and EU AI Act conformity assessments.
- Cloud-Based:Azure and AWS-hosted workloads reduce upfront capital barriers for mid-market manufacturing firms. Procurement concentrates among North American and Western European buyers seeking rapid pilot-to-production scaling without dedicated IT staffing.
- Hybrid:Split architectures process non-sensitive training content in cloud instances while retaining proprietary CAD data on local nodes. Automotive OEMs in Stuttgart and Munich metropolitan clusters favor this flexibility for supplier network coordination.
- Edge Computing:On-device inference and localized sensor fusion eliminate round-trip latency for time-critical maintenance workflows. Energy sector deployments in North Sea offshore platforms and Texas Permian Basin facilities absorb premium hardware costs for connectivity-independent operation.
Mature deployment sits with Cloud-Based configurations. Newer deployment is concentrated in Edge Computing installations driven by defense and critical infrastructure requirements.
Application:
Workflow integration depth determines pricing tiers, with transactional remote assistance at the base and deeply embedded quality assurance at the premium.
- Remote Assistance:Real-time video annotation and expert guidance overlay reduce specialist travel requirements. Field service organizations in US industrial equipment sectors and German mechanical engineering clusters deploy this application for distributed asset maintenance.
- Training & Simulation:Immersive procedural rehearsal compresses competency development for hazardous or complex operations. Aviation maintenance divisions at Lufthansa Technik and Delta TechOps utilize AR-guided engine inspection protocols to reduce certification timelines.
- Maintenance & Repair:Step-by-step procedural guidance with hands-free navigation reduces error rates in high-consequence environments. Demand concentrates in aerospace MRO providers and nuclear power operators subject to stringent documentation requirements.
- Design & Visualization:Full-scale 3D model projection enables collaborative design review without physical prototyping. Magic Leap's optical technology differentiates in this niche against mass-market alternatives.
- Quality Assurance:Real-time dimensional verification and defect detection integrate directly with assembly line PLM systems. BMW and Volkswagen plants in Germany establish reference architectures for tier-one supplier adoption.
Early-stage adoption clusters around Remote Assistance. Embedded integration is advancing fastest in Quality Assurance workflows.
Technology:
Spatial mapping sophistication separates commodity training applications from industrial-grade persistent augmentation.
- Marker-Based:Pre-positioned visual fiducials anchor digital content in controlled environments. Retains cost advantages in classroom training settings where environmental control is assured.
- Markerless:Natural feature recognition eliminates preparation overhead for ad-hoc deployment. Gaining traction in construction site applications where marker placement is impractical.
- Projection-Based:Spatially aligned light projection onto work surfaces guides manual assembly without wearable hardware. Automotive assembly lines in Germany deploy this for torque sequence verification.
- Superimposition-Based:Direct overlay onto physical components enables direct comparison between as-built and as-designed states. Maintenance workflows at energy utilities utilize this for corrosion assessment and component replacement verification.
- SLAM-Based:Simultaneous localization and mapping enables persistent spatial anchoring across large facility footprints without environmental modification. Dominates advanced use cases in uncontrolled industrial settings where marker deployment is infeasible.
Established technology bases include Marker-Based and Projection-Based systems. SLAM-Based implementations are climbing the fastest as algorithm maturation reduces computational requirements.
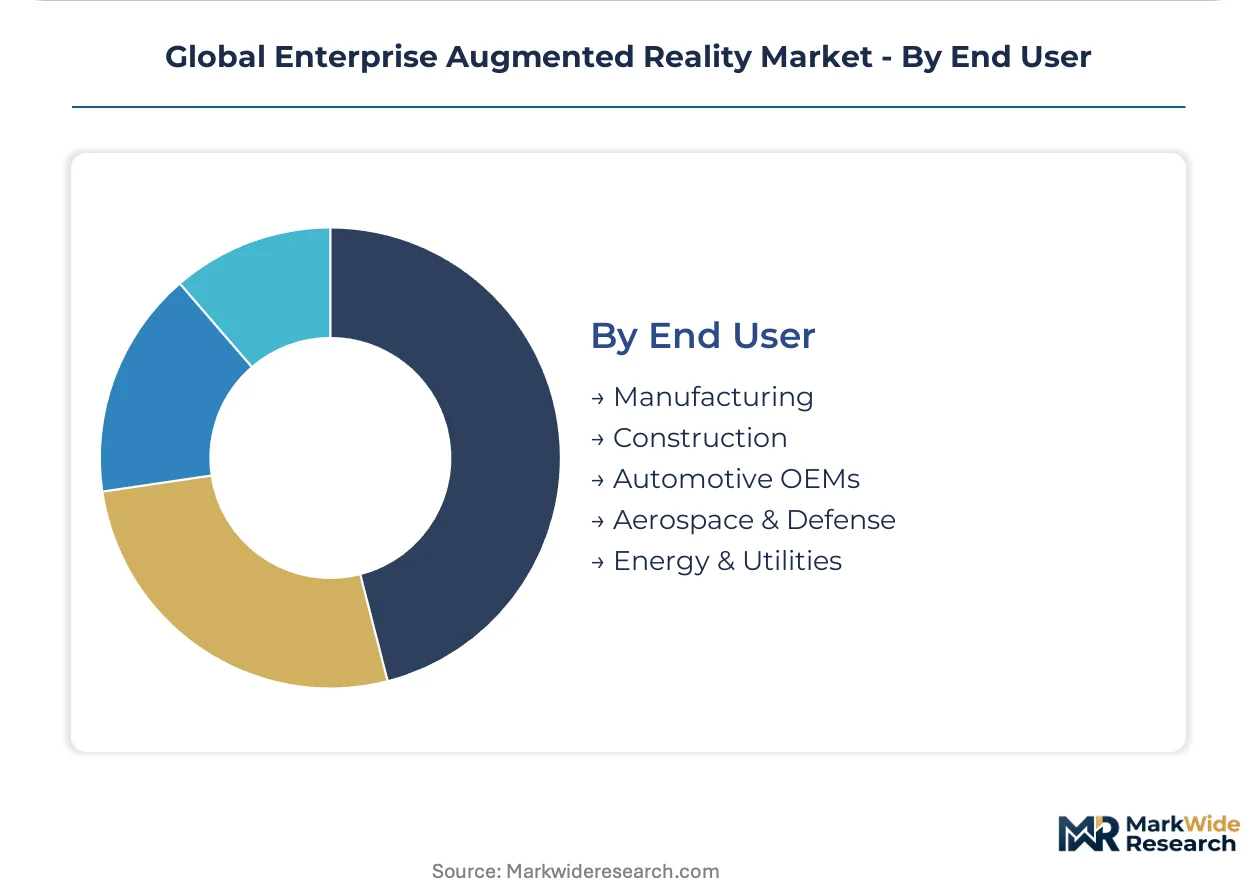
End User:
Vertical-specific compliance requirements and operational criticality create divergent procurement cycles and vendor stickiness.
- Manufacturing:Assembly line integration and supplier network standardization drive platform consolidation. Buyer committees centralize procurement across maintenance, training, and quality assurance functions.
- Construction:Site mobility and environmental variability favor ruggedized hardware with extended battery operation. BIM-to-field workflow continuity represents primary vendor selection criterion.
- Automotive OEMs:Quality assurance protocols and supplier tier integration establish reference architectures. German clusters lead standardization efforts with direct vendor co-development programs.
- Aerospace & Defense:EASA human-factors certification and air-gapped security requirements create compliance moats for established suppliers. Cockpit and ground-crew applications face 18-36 month validation cycles.
- Energy & Utilities:Hazardous area classification and connectivity independence prioritize edge computing configurations. Offshore and remote site operations absorb premium margins for reliability guarantees.
Procurement maturity is highest in Automotive OEMs. Steepest expansion trajectory appears in Energy & Utilities as infrastructure digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise AR deployment concentrates in industrial economies with advanced manufacturing bases and stringent regulatory frameworks that mandate localized data processing. Germany, the United States, Japan, China, and France collectively absorb the majority of sovereign-edge installations and cloud-native mid-market rollouts.
United States
FDA 510(k) pathway expansion accelerates healthcare AR vendor entry into hospital procurement cycles. FCC equipment authorization governs radio frequency emissions from untethered headsets in industrial facilities. Boeing maintenance divisions in Seattle and Delta TechOps in Atlanta deploy AR-guided engine inspection protocols to compress aircraft downtime.
Germany
Industrial engineering clusters and automotive OEMs integrate AR into assembly line quality assurance workflows. EU AI Act and GDPR compliance requirements push enterprises toward on-premise deployments with localized data processing. BMW and Volkswagen plants in Stuttgart and Munich metropolitan clusters establish reference architectures for tier-one supplier adoption.
Japan
Precision manufacturing and robotics integration drive demand for SLAM-based persistent spatial mapping in uncontrolled industrial settings. METI standards coordination shapes domestic vendor qualification requirements. Automotive suppliers in Nagoya and Osaka industrial corridors deploy projection-based AR for torque sequence verification.
China
Electronics manufacturing scale and MIIT industrial digitization mandates accelerate AR hardware assembly migration. GB standards and SAMR certification requirements create compliance frameworks for workplace monitoring applications. Noida and Chennai industrial corridors attract AR hardware assembly through India PLI scheme incentives serving Chinese OEM supply chains.
France
Aerospace MRO providers pilot outcome-based service contracts where AR-guided interventions reduce aircraft downtime guarantees. EASA human-factors certification requirements impose stringent validation timelines on cockpit and ground-crew applications. Engineering holding companies in Île-de-France standardize AR platforms across subsidiary operations.
Global Enterprise Augmented Reality Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors seek to bridge hardware-software gaps and secure vertical-specific certification pathways. The vendor base organizes around three tiers: cloud-integrated platform providers, specialized industrial software vendors, and optical technology specialists competing on display architecture differentiation. Two strategic archetypes have emerged: ecosystem orchestrators leveraging existing enterprise relationships, and component specialists capturing premium margins in regulated verticals. Portfolio diversification and geographic expansion represent the dominant competitive vectors as procurement committees consolidate vendor relationships across maintenance, training, and quality assurance functions.
Among platform-integrated providers, Microsoft Corporation anchors enterprise deployments through cloud infrastructure relationships, while PTC Inc. occupies a position exemplifying CAD-to-AR workflow continuity specialists. Magic Leap Inc. sits within the optical technology tier, representing display architecture differentiation against mass-market alternatives in design visualization niches.
| Leading Market Players |
|---|
| Microsoft Corporation |
| PTC Inc. |
| Google LLC |
| Apple Inc. |
| Meta Platforms Inc. |
| Sony Group Corporation |
| Magic Leap Inc. |
| Vuzix Corporation |
| Lenovo Group Ltd. |
| Others |
Supply & Pricing Matrix
Optical engineering talent scarcity in Silicon Valley and Munich metropolitan clusters widens pricing spreads between premium sovereign-edge installations and volume-driven cloud-native rollouts. Labor-cost differentials for waveguide design and photonics integration expertise compress margins at the standard tier while sustaining premium pricing for air-gapped, latency-guaranteed configurations.
Pricing Analysis
Warranty and service bundling separates premium AR hardware tiers from unbundled economy offerings. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—EASA human-factors validation and FDA 510(k) clearance command substantial uplifts. Pricing pressure stems from smartphone AR substitution satisfying training use cases at fractional hardware cost. Mid-market manufacturing firms exhibit highest price sensitivity, while defense contractors and aerospace MRO providers absorb premiums for sovereign-edge latency guarantees.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German automotive OEMs and US aerospace contractors, while systems integrators and industrial distributors capture mid-market manufacturing procurement. Waveguide display supply concentrates in Korean and Taiwanese optical component foundries. Diffractive optical elements, micro-LED substrates, and precision photonics packages constitute critical input dependencies. Single-source vulnerability in near-eye display substrate capacity exposes downstream vendors to allocation risk. Distribution runs through certified systems integrators for regulated verticals requiring EASA and FDA compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over optical component supply and CAD-to-AR workflow continuity determines margin capture. Players are pursuing backward integration into waveguide manufacturing to reduce dependency on concentrated Asian foundry capacity.
For Market Incumbents: Deploy certification co-development programs with EASA and FDA to extend compliance moats against emerging optical technology specialists. Strengthen channel control through exclusive systems integrator partnerships in German automotive clusters. Consolidate vendor relationships across maintenance, training, and quality assurance functions before procurement committees finalize platform standardization. Threat substitution from smartphone AR video pass-through demands defensive pricing action in training segments.
For New Entrants and Emerging Players: Mid-market construction firms in France and Italy represent an underserved buyer archetype seeking ruggedized hardware with BIM-to-field workflow continuity. White-space targets include projection-based assembly guidance for automotive tier-one suppliers and edge-computing configurations for North Sea offshore energy platforms. Go-to-market execution should leverage industrial distributor relationships displacing direct OEM sales in procurement centralization trends.
For Investors and Strategic Acquirers: Re-rating potential sits with optical technology specialists possessing differentiated waveguide architectures given SLAM algorithm maturation expanding addressable use cases. Long-term viability across the analysis window favors vendors with demonstrated EASA human-factors certification pathways and established German automotive OEM co-development relationships. Acquisition target archetype: component specialists with proprietary photonics integration expertise concentrated in Munich or Silicon Valley clusters. Signal to watch: outcome-based service contract adoption rates among aviation MRO providers as validation of AR-guided downtime reduction claims.
| Strategic Initiative | Industry Significance |
|---|---|
| Waveguide Manufacturing Backward Integration | Reduces single-source dependency on Korean and Taiwanese optical foundries for near-eye display substrates. |
| EASA Human-Factors Certification Investment | Creates 18-36 month compliance moats for cockpit and ground-crew AR system deployments. |
| CAD-to-AR Workflow Continuity Partnership | Secures platform stickiness with German automotive OEMs standardizing quality assurance protocols. |
| Edge Computing Configuration Development | Captures premium margins in defense and North Sea energy sectors requiring air-gapped operation. |
| Systems Integrator Channel Expansion | Displaces direct OEM sales in mid-market manufacturing verticals undergoing procurement centralization. |
Research Methodology
Multi-period observation of deployment architecture shifts, regulatory filing timelines, and procurement pattern evolution anchored the trend analysis, supplemented by interviews with AR platform engineering leads, industrial systems integrators, EASA certification specialists, automotive quality assurance directors, and defense procurement officers. Secondary validation drew from EASA airworthiness directives, FDA 510(k) premarket notifications, EU AI Act conformity assessment documentation, and hyperscaler cloud infrastructure capex disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic indicators for manufacturing digitization expenditure.
Segment-weighting across deployment architecture, application workflow depth, technology sophistication tier, and end-user vertical regulatory intensity informed the analytical framework. Deployment model splits between cloud-native subscription and sovereign-edge capital expenditure received particular attention given bifurcated buyer archetypes. CAGRs were derived from installed base expansion rates and average revenue per unit trajectories across the projection horizon. Industry-specific forecast inputs included SLAM algorithm computational efficiency improvements and EU AI Act enforcement timeline assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to waveguide display supply allocation disruptions, EASA certification timeline extensions, and smartphone AR capability advancement. Forecasts reflect documented assumptions regarding German automotive OEM adoption rates and defense sector air-gapping requirements. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
VR Ski Machines Market
Virtual Reality (VR) and Augmented Reality (AR)
Consumer Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) and Augmented Reality (AR) Microdisplay Market
Virtual Reality (VR) and Augmented Reality (AR)
Japan Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality and Virtual Reality (AR/VR) in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
Industrial Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented and Virtual Reality (AR VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
India Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
VR HMD Shipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East and Africa Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Collaboration Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
AR/VR Chip Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Simulator Market