
 North America Virtual Reality Market | 2026-2036
North America Virtual Reality Market Size, Share, and Industry Trends Forecast 2026-2036
North America Virtual Reality Market Analytics
Silicon carbide is broadening thermal management options for high-performance VR chipsets as manufacturers seek alternatives to traditional silicon substrates. Meta Platforms leverages its captive content ecosystem to sustain hardware-software integration across consumer and enterprise tiers. Apple anchors premium positioning through proprietary spatial computing architectures that command developer loyalty. Microsoft Corporation competes in commercial deployment by specializing in mixed-reality workplace tools for industrial clients.
North America Virtual Reality encompasses immersive digital environments rendered through stereoscopic displays with refresh rates typically exceeding 90 Hz, positional tracking systems, and spatial audio processing to simulate physical presence for training, entertainment, and therapeutic applications. Headsets command the dominant hardware revenue pool while software margins expand fastest as platform economics shift toward recurring licensing. Training simulations attract enterprise capital allocation as aviation, defense, and energy operators replace physical mock-ups with photorealistic virtual environments.
FCC equipment authorization requirements govern wireless transmission protocols for untethered VR devices, while FDA oversight applies to therapeutic and diagnostic software classified as medical devices. The CTA's interoperability standards influence peripheral compatibility across the ecosystem. Stakeholders must weigh spectrum policy evolution against medical-device certification timelines when allocating R&D resources between consumer entertainment and regulated healthcare applications.
Market Dynamics
Silicon carbide substrates are compressing thermal design cycles for high-performance VR chipsets, forcing manufacturers to reconfigure supply relationships away from legacy silicon foundries. FCC spectrum allocations for unlicensed wireless devices simultaneously enable untethered headset architectures while constraining transmission power budgets.
Growth Catalysts
- Healthcare reimbursement pathways:FDA 510(k) clearances for VR therapeutic software create predictable revenue streams for patient rehabilitation and pain management applications across United States hospital networks.
- Enterprise training substitution:Aviation, defense, and energy operators in Texas and California replace physical mock-ups with photorealistic simulations, redirecting capital from physical infrastructure to digital licensing.
- FCC spectrum policy:Unlicensed 6 GHz band allocations support low-latency wireless protocols that eliminate tethering constraints for warehouse logistics and surgical training deployments.
Market Restraints
- Silicon carbide wafer supply concentration:Limited qualified substrate vendors constrain thermal management component availability and extend procurement lead times for high-performance chipsets.
- FDA device classification friction:Software-as-a-medical-device pathways impose 12-18 month certification timelines that compress development runway for therapeutic VR applications.
- Display panel input cost volatility:Micro-OLED fabrication yield sensitivity creates margin pressure for premium headset manufacturers dependent on Korean and Taiwanese supply bases.
Strategic Opportunities
- Canadian healthcare expansion:Health Canada regulatory harmonization with FDA precedents accelerates market entry for cleared therapeutic software, opening provincial procurement channels.
- Spatial audio-EEG convergence:Integration of neural feedback loops with immersive environments enables next-generation neurorehabilitation protocols for stroke and PTSD patient populations.
- Direct-to-enterprise licensing:Platform economics shift toward recurring software subscriptions, displacing perpetual hardware sales in aviation and energy training verticals.
Industry Challenges
- Optical engineering talent scarcity:Waveguide design and pancake lens optimization expertise concentrates in established AR/VR hardware divisions, constraining startup hiring pipelines.
- Legacy simulation integration:Defense and aviation training facilities face multi-year reconfiguration cycles to interoperate VR headsets with existing motion platform and debriefing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Virtual Reality Market |
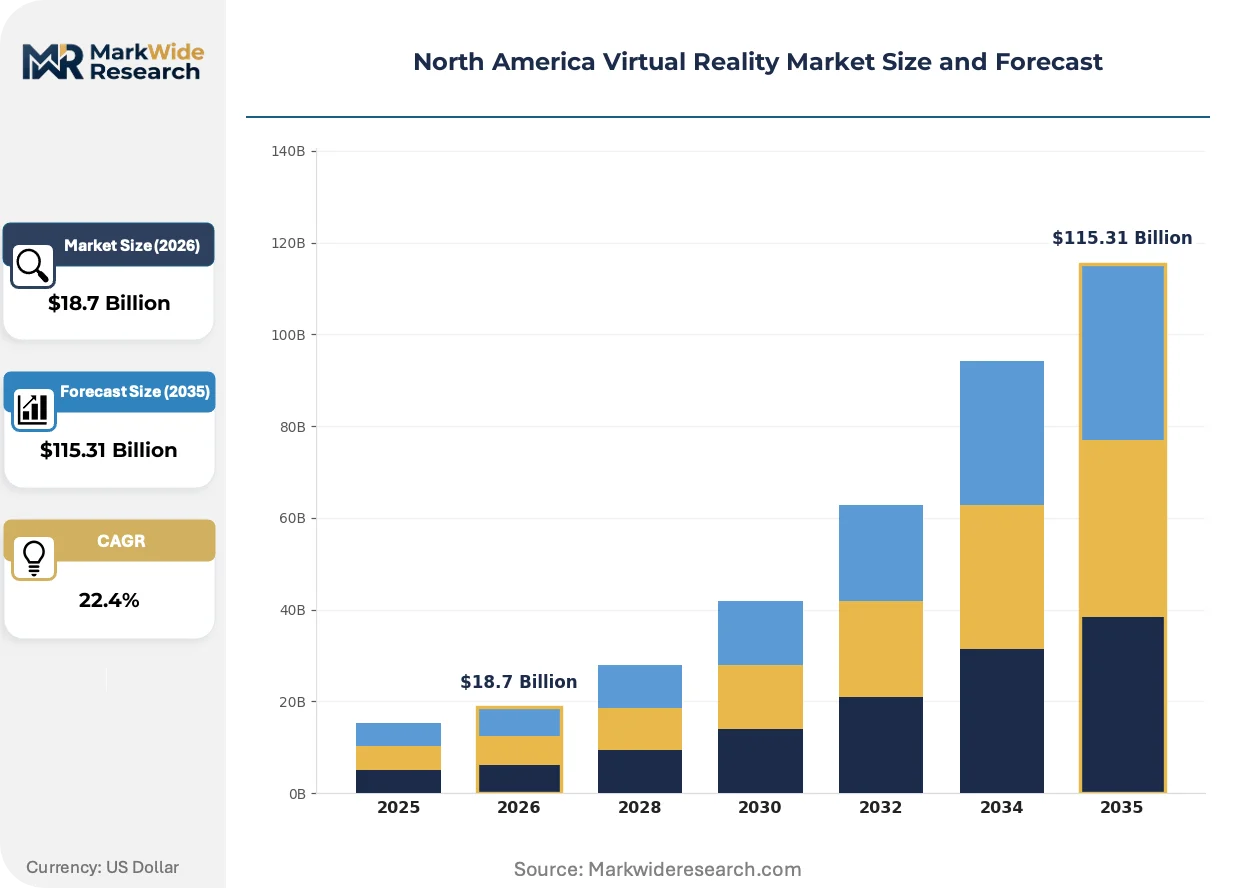
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headsets, Software, Accessories, Controllers End User: Gaming, Education, Healthcare, Real Estate Technology: Motion Tracking, Haptic Feedback, 3D Display, Cloud Computing Application: Training Simulations, Virtual Tours, Entertainment, Therapy |
| Companies Covered | Meta Platforms, Apple, Sony Corporation, Microsoft Corporation, Google, HTC Corporation, Samsung Electronics, Magic Leap, Unity Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Virtual Reality Market Evolving Landscape
Computational architectures are consolidating around heterogeneous chip designs that merge rendering, AI inference, and sensor fusion onto single die configurations. This integration is compressing headset form factors while elevating thermal design requirements.
Pancake optical stacks are unifying display and lens functions through folded light-path designs that halve headset thickness. Medical training programs at Johns Hopkins and Mayo Clinic are adopting these configurations for extended surgical rehearsal sessions. The technology is unifying previously separate industrial design and optical engineering workflows, collapsing vendor coordination overhead.
FCC equipment authorization requirements for 6 GHz unlicensed devices are mandating new interference testing protocols that extend pre-market validation timelines. Commercial deployment of warehouse logistics headsets faces 4-6 month certification delays. Enterprise buyers in California distribution centers are accelerating procurement decisions to lock spectrum-dependent hardware ahead of anticipated queue congestion.
Enterprise procurement is consolidating around outcome-based training effectiveness metrics rather than hardware unit volumes. Aviation maintenance operators in Texas now contract for proficiency certification rates rather than simulator seat-hours. This reconfiguration is most visible in defense and energy sectors where training budgets tie directly to workforce competency audits.
North America Virtual Reality Market Segmentation
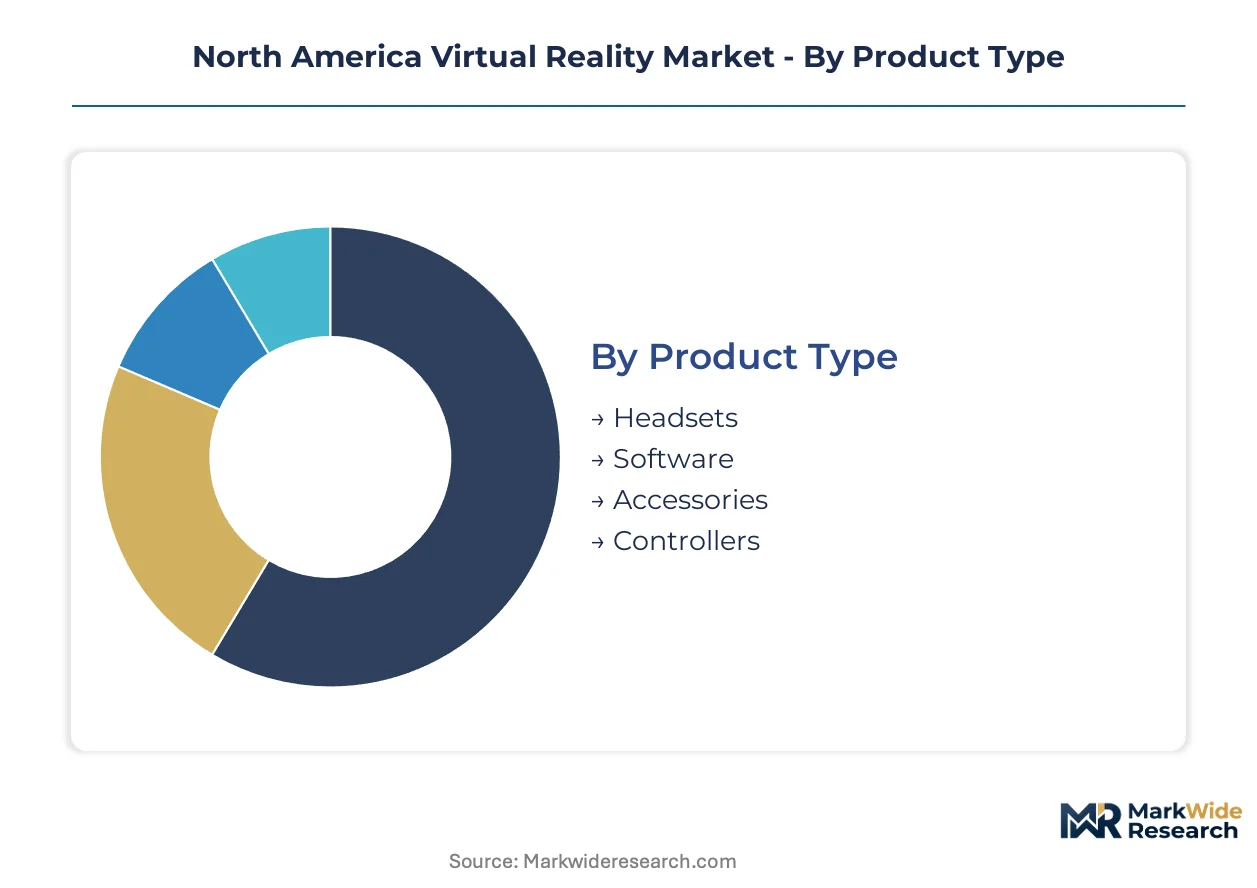
Segmentation in the North America Virtual Reality Market reveals how regulatory pathways and thermal engineering requirements fragment procurement decisions across hardware and software tiers. Buyers in California's enterprise clusters and Texas defense facilities weight certification timelines differently than consumer gaming distributors.
Product Type:
FDA 510(k) pathways apply selectively—therapeutic software faces 12-18 month reviews while headset hardware clears through FCC equipment authorization alone. Accessories and controllers fall outside medical-device classification entirely.
- Headsets:Stereoscopic displays with refresh rates exceeding 90 Hz integrate silicon carbide thermal substrates to manage chipset heat loads. Demand concentrates in California technology corridors where enterprise buyers contract for aviation and surgical training deployments, constrained by micro-OLED fabrication yield sensitivity from Korean supply bases.
- Software:Platform economics are displacing perpetual licenses with recurring subscriptions across enterprise verticals. Texas energy operators and defense aviation facilities in the state now procure proficiency certification rates rather than seat-hours, redirecting capital from hardware to digital licensing.
- Accessories:Peripheral ecosystems depend on CTA interoperability standards for cross-platform compatibility.
- Controllers:Haptic-enabled input devices face FCC unlicensed wireless testing protocols that extend pre-market validation timelines.
Leading the category by volume: Headsets. Expanding most quickly: Software.
End User:
Cost tier stratification separates premium therapeutic deployments from mass-market entertainment—healthcare budgets absorb FDA-certification premiums while gaming distributors compete on hardware unit economics.
- Gaming:Consumer entertainment drives headset volume through Meta Platforms' hardware-software integration and Apple's premium spatial computing positioning.
- Education:Institutional procurement in Canadian provincial systems accelerates as Health Canada harmonizes with FDA clearance precedents.
- Healthcare:Johns Hopkins and Mayo Clinic surgical training programs adopt pancake optical stacks for extended rehearsal sessions, collapsing vendor coordination overhead between industrial design and optical engineering workflows.
- Real Estate:Virtual property visualization in California and Texas metropolitan markets leverages photorealistic rendering for pre-construction sales.
Dominating revenue share: Healthcare. Gaining share fastest: Education.
Technology:
Application maturity separates deployed infrastructure from emerging integration—motion tracking and 3D display operate at commercial scale while haptic-cloud convergence remains developmental.
- Motion Tracking:Positional systems with sub-millimeter precision enable warehouse logistics headsets in California distribution centers, where buyers accelerate procurement ahead of anticipated FCC 6 GHz certification queue congestion.
- Haptic Feedback:Force-feedback gloves and exoskeletons face waveguide design talent scarcity that constrains startup hiring pipelines.
- 3D Display:Pancake optical stacks halve headset thickness through folded light-path designs, unifying display and lens functions.
- Cloud Computing:Edge-rendering architectures reduce onboard thermal loads, easing silicon carbide substrate procurement constraints.
Widest deployment: Motion Tracking. Steepest expansion trajectory: Cloud Computing.
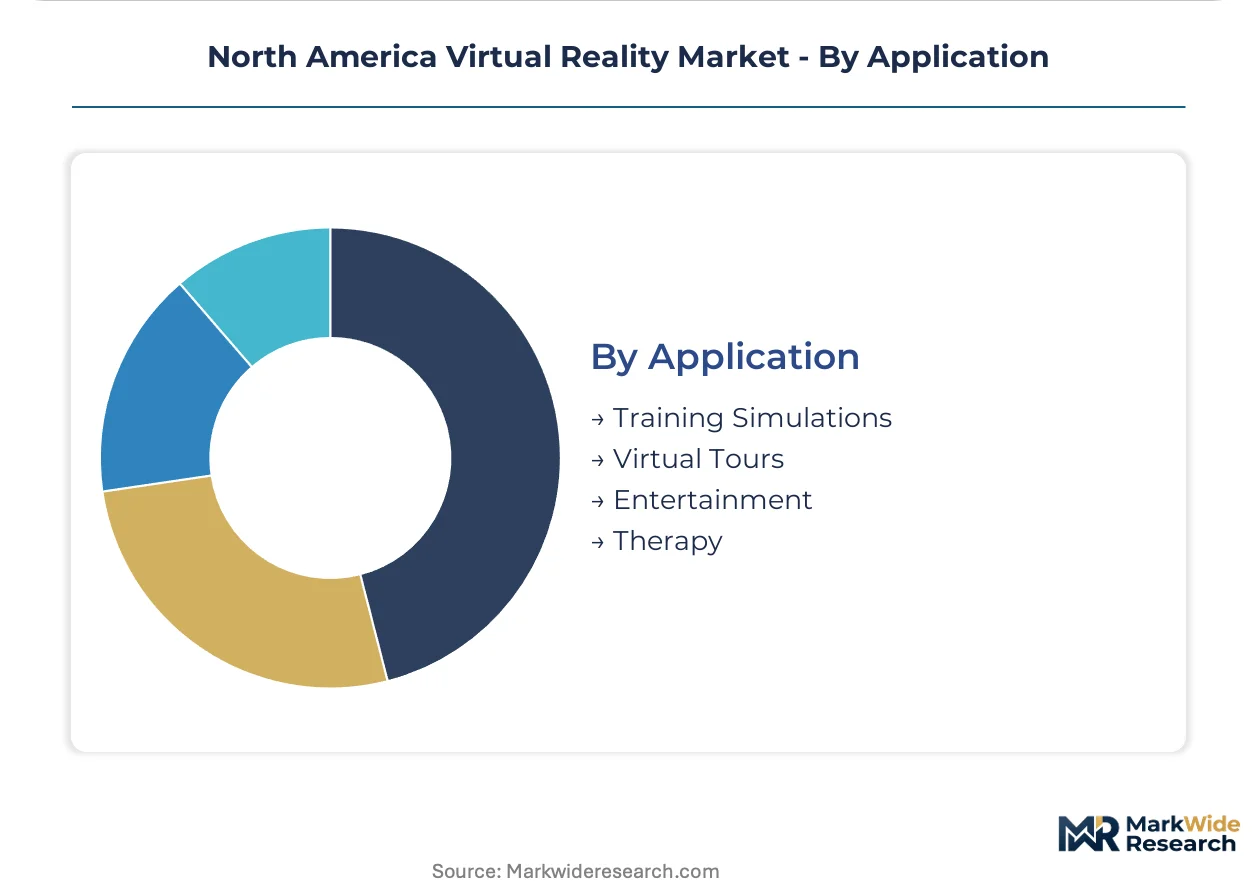
Application:
Customer type bifurcation distinguishes outcome-contracted enterprise training from transactional consumer entertainment—aviation maintenance operators now specify competency audit linkages in procurement terms.
- Training Simulations:Defense and energy operators replace physical mock-ups with virtual environments, though legacy motion platform integration imposes multi-year reconfiguration cycles.
- Virtual Tours:Real estate and hospitality deployments concentrate in California and Texas urban corridors.
- Entertainment:Spatial audio-EEG convergence enables neurorehabilitation protocols for stroke and PTSD populations, opening next-generation therapeutic verticals.
- Therapy:FDA-cleared pain management and rehabilitation software creates predictable revenue streams across United States hospital networks.
Generating highest contract values: Training Simulations. Climbing the fastest: Therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones in Texas and California concentrate enterprise VR deployment through state-level tax credits for simulation technology adoption. These incentives anchor North American demand concentration for surgical training and defense applications.
United States
Defense aviation maintenance operators in Texas now contract for workforce competency certification rates rather than physical simulator seat-hours. The FAA coordinates with the FCC on spectrum allocation for untethered logistics headsets in distribution centers. Johns Hopkins and Mayo Clinic surgical programs in Maryland and Minnesota adopt pancake optical configurations for extended rehearsal protocols.
Canada
Provincial healthcare procurement in Ontario and Quebec accelerates as Health Canada harmonizes FDA 510(k) clearance pathways for therapeutic software. The CTA interoperability standards govern peripheral compatibility for cross-border enterprise deployments. Toronto and Vancouver clusters concentrate developer talent for spatial audio-EEG neurorehabilitation integration.
Mexico
Manufacturing integration for VR headset assembly concentrates in Baja California and Chihuahua near US border logistics corridors. The country's federal economic development agency promotes electronics sector investment through maquiladora program incentives. Guadalajara's technology corridor hosts software localization operations for Spanish-language enterprise training modules.
North America Virtual Reality Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform-integrated ecosystems commanding premium positioning against component suppliers. The vendor base organizes around three strategic archetypes: captive content-hardware integrators, enterprise-focused mixed-reality specialists, and optical engineering component suppliers. Consolidation pressure operates most intensely in thermal substrate procurement and waveguide design talent acquisition. Dominant competitive moves include backward integration into silicon carbide supply chains and strategic partnerships for FCC certification acceleration.
Within the captive ecosystem tier, Meta Platforms and Apple exemplify divergent approaches to hardware-software integration. Microsoft Corporation occupies a distinct position serving industrial mixed-reality deployments. These three entities represent the primary competitive anchors shaping platform economics and developer loyalty structures across consumer and enterprise market layers.
| Leading Market Players |
|---|
| Meta Platforms |
| Apple |
| Sony Corporation |
| Microsoft Corporation |
| HTC Corporation |
| Samsung Electronics |
| Magic Leap |
| Unity Technologies |
| Others |
Value Network & Pricing Analysis
Captive silicon carbide substrate production anchors both supply security and margin protection for VR chipset manufacturers navigating thermal management complexity. Meta Platforms and Apple leverage in-house thermal engineering to buffer procurement volatility while commanding premium pricing tiers against hardware-software bundled offerings.
Pricing Analysis
Volume concentrates in consumer entertainment headsets while margin expansion accelerates in enterprise software subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified therapeutic deployments from mass-market gaming hardware, with certification premiums absorbing 12-18 month regulatory timelines. Cost compression in micro-OLED display tiers intensifies because Korean fabrication yield sensitivity constrains supply elasticity. Gaming distributors exhibit highest price sensitivity, whereas healthcare procurement committees prioritize regulatory clearance over unit economics.
Supply Chain Analysis
USMCA domestic-content provisions reshape sourcing decisions for final assembly operations in Baja California and Chihuahua. Silicon carbide substrates draw from Japanese and American qualified vendors, micro-OLED panels feed from Korean supply bases, and rare-earth magnet components for haptic actuators hinge on Chinese processing capacity. Single-source vulnerability concentrates in thermal substrate procurement where qualified vendors number fewer than five globally. Distribution runs through enterprise direct contracts for aviation and defense training verticals, bypassing retail channel markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 510(k) clearance pathways function as a cost-of-compliance moat, elevating capital requirements for therapeutic software entrants and protecting incumbent revenue streams in United States hospital networks.
For Market Incumbents: Anchor platform economics through backward integration into silicon carbide supply chains, securing thermal substrate allocation ahead of procurement queue congestion. Deepen FCC certification expertise to accelerate 6 GHz equipment authorization timelines, defending against emerging entrants lacking regulatory affairs infrastructure. Prioritize Health Canada harmonization to preempt provincial procurement channel access for Canadian healthcare expansion. For New Entrants and Emerging Players: Hospital GPO contracts offer the most penetrable entry vector for therapeutic software startups lacking Meta's hardware-software integration scale. Target Canadian provincial healthcare systems where Health Canada clearance precedents accelerate market entry without duplicative FDA investment. Pursue direct-to-enterprise licensing models displacing perpetual hardware sales in Texas energy and defense aviation training facilities. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-integrated ecosystem acquisitions by captive content-hardware integrators seeking thermal engineering and waveguide design talent. Long-term viability favors enterprises with FDA-cleared therapeutic software portfolios and recurring subscription revenue visibility. Monitor FCC 6 GHz certification queue congestion as inflection signal for enterprise hardware procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Integration | In-house thermal substrate production buffers procurement lead times for high-performance VR chipsets. |
| FDA 510(k) Clearance Investment | Regulatory certification creates predictable reimbursement pathways across United States hospital networks. |
| Enterprise Direct Licensing | Outcome-based contracts with Texas aviation operators displace perpetual hardware revenue models. |
| Spatial Audio-EEG Convergence | Neural feedback integration opens neurorehabilitation protocols at Johns Hopkins and Mayo Clinic. |
| Canadian Regulatory Harmonization | Health Canada alignment accelerates provincial procurement channel access for therapeutic software. |
Research Methodology
Document review covered FDA 510(k) clearance databases, FCC equipment authorization filings, and enterprise training procurement contracts, complemented by interviews with VR hardware engineering directors, healthcare GPO contract managers, and aviation maintenance training officers. Secondary validation drew from SEC filings of platform-integrated ecosystem providers, hyperscaler capex disclosures for cloud-rendering infrastructure, and Korean display panel export statistics. Bottom-up headset shipment estimates triangulated against top-down enterprise software licensing revenue across the analysis window.
Segmented outputs model product type, end user, technology, and application dimensions throughout the forecast period, with CAGRs derived from regression analysis against historical adoption curves in surgical training and defense simulation verticals. Inputs incorporated FCC spectrum allocation timelines, Health Canada regulatory harmonization progress, and micro-OLED fabrication yield trajectories from Korean supply base disclosures.
Caveats apply where FDA device classification friction extends beyond modeled timelines or silicon carbide wafer supply concentration triggers procurement disruptions beyond qualified vendor capacity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Global Mobile Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Italy Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Location-Based Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Location-Based VR Entertainment Market
Virtual Reality (VR) and Augmented Reality (AR)
Spatial Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Collaboration Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual and Augmented Reality in Tourism Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Immersive Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
AR & VR in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mixed Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive AR and VR Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Location Based VR Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East and Africa Virtual Reality Market