
 Europe Diagnostic Imaging Equipment Market | 2026-2036
Europe Diagnostic Imaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Diagnostic Imaging Equipment Market Foresight
Outpatient imaging centers is collapsing the traditional hospital-centric procurement model across Europe. Siemens Healthineers leverages its installed base of MRI and CT platforms to sustain service revenue streams throughout Germany and Scandinavia. Philips Healthcare anchors its position through hybrid imaging R&D intensity at its Eindhoven operations. GE HealthCare competes on digital integration, connecting imaging fleets to hospital information systems across British and French networks.
Europe diagnostic imaging equipment comprises electromechanical systems generating anatomical or functional visual data through ionizing radiation, magnetic fields, or acoustic waves, with spatial resolution parameters ranging from sub-millimeter CT slices to whole-body MRI field strengths of 1.5 to 3 Tesla, serving disease detection and treatment planning in clinical settings. CT scanner demand leads volume due to emergency department throughput requirements, while MRI commands premium positioning in neurology and orthopedics applications where soft-tissue contrast differentiates diagnostic confidence. Ultrasound occupies the fastest-expanding technology position through portable digital systems enabling point-of-care deployment in clinics and ambulatory settings.
EMA device oversight and the EU MDR framework tighten clinical evidence requirements for new imaging platform approvals, extending development timelines and favoring incumbents with established technical documentation. CE marking under MDR Article 20 mandates post-market surveillance protocols that reshape service contract structures between manufacturers and hospital buyers. France's ANSM and Germany's BfArM enforce national vigilance reporting that adds compliance layers beyond centralized EU processes. Stakeholders must monitor MDR transition deadlines and national reimbursement negotiations to calibrate capital deployment across European health systems.
Market Dynamics
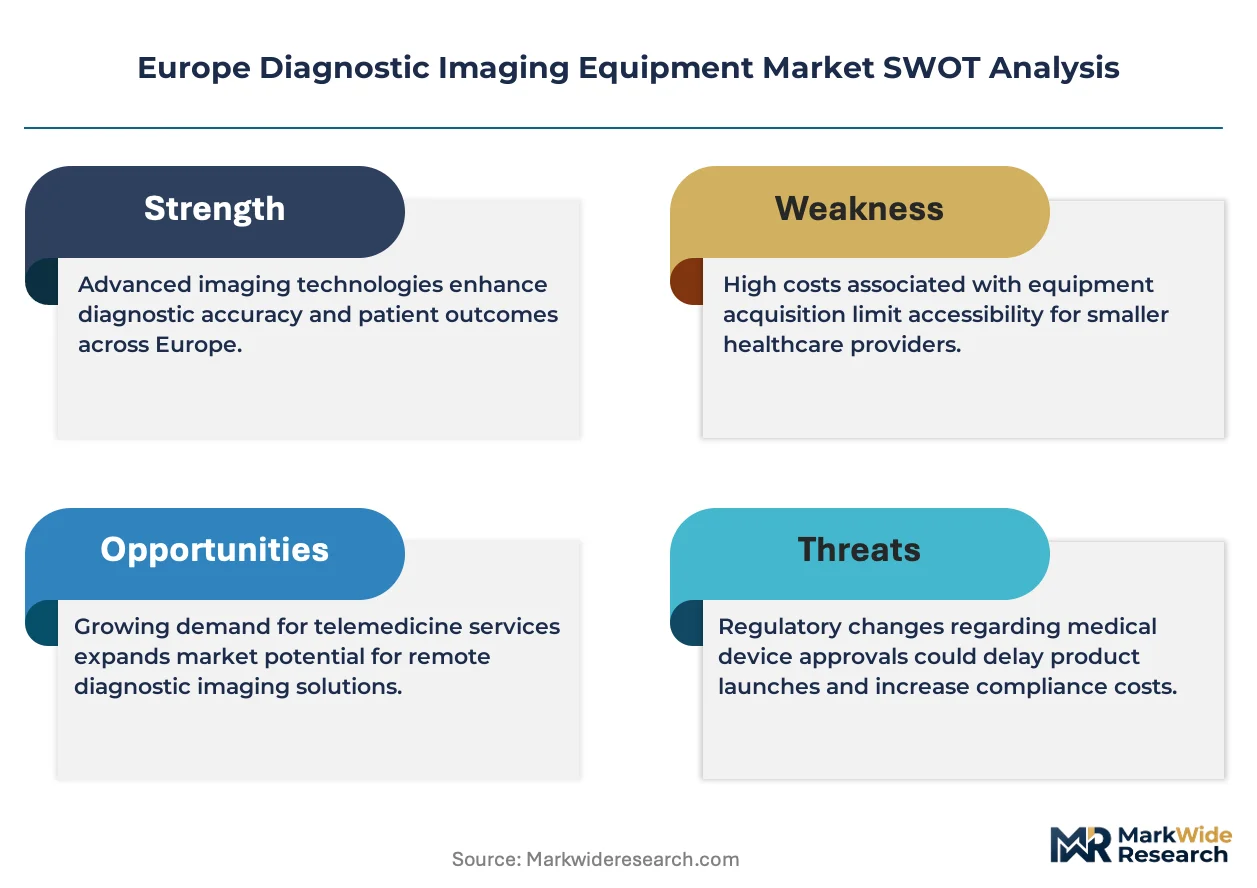
EU MDR compliance deadlines are compressing equipment replacement cycles across European health systems, forcing hospitals to accelerate capital deployment toward certified platforms while decommissioning legacy systems that lack updated technical documentation.
Growth Catalysts
- MDR Article 20 post-market surveillance:Mandated vigilance reporting protocols are compelling German university hospitals and French public hospital clusters to upgrade imaging fleets with compliant systems.
- Hybrid imaging R&D intensity:PET-MRI convergence is expanding diagnostic confidence in oncology applications, driving premium procurement decisions at tertiary centers.
- Point-of-care ultrasound:Portable digital systems are capturing ambulatory clinic demand in Italy and Spain, extending imaging access beyond traditional radiology departments.
Market Restraints
- Helium supply concentration:MRI magnet cooling depends on concentrated sourcing from Qatar and Algeria, exposing German and French manufacturers to price volatility and allocation constraints.
- MDR clinical evidence requirements:Extended development timelines for new platform approvals favor incumbents with established documentation, raising barriers for novel entrants.
- CT dose optimization limits:Ionizing radiation exposure thresholds constrain throughput expansion in emergency departments despite volume pressure.
Strategic Opportunities
- Eastern European hospital modernization:Poland and Romania present underpenetrated demand for MRI and CT replacement as EU cohesion funds flow into health infrastructure.
- AI-enabled image reconstruction:Deep learning algorithms are converging with hardware platforms to reduce scan times and expand patient throughput.
- Service contract unbundling:Independent service organizations are capturing maintenance revenue from hospital buyers seeking alternatives to manufacturer-captive agreements.
Industry Challenges
- CE marking timeline compression:MDR transition deadlines are straining notified body capacity, delaying product launches and freezing capital planning.
- Legacy PACS integration:New imaging platforms face interoperability friction with entrenched hospital information systems, extending deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Diagnostic Imaging Equipment Market |
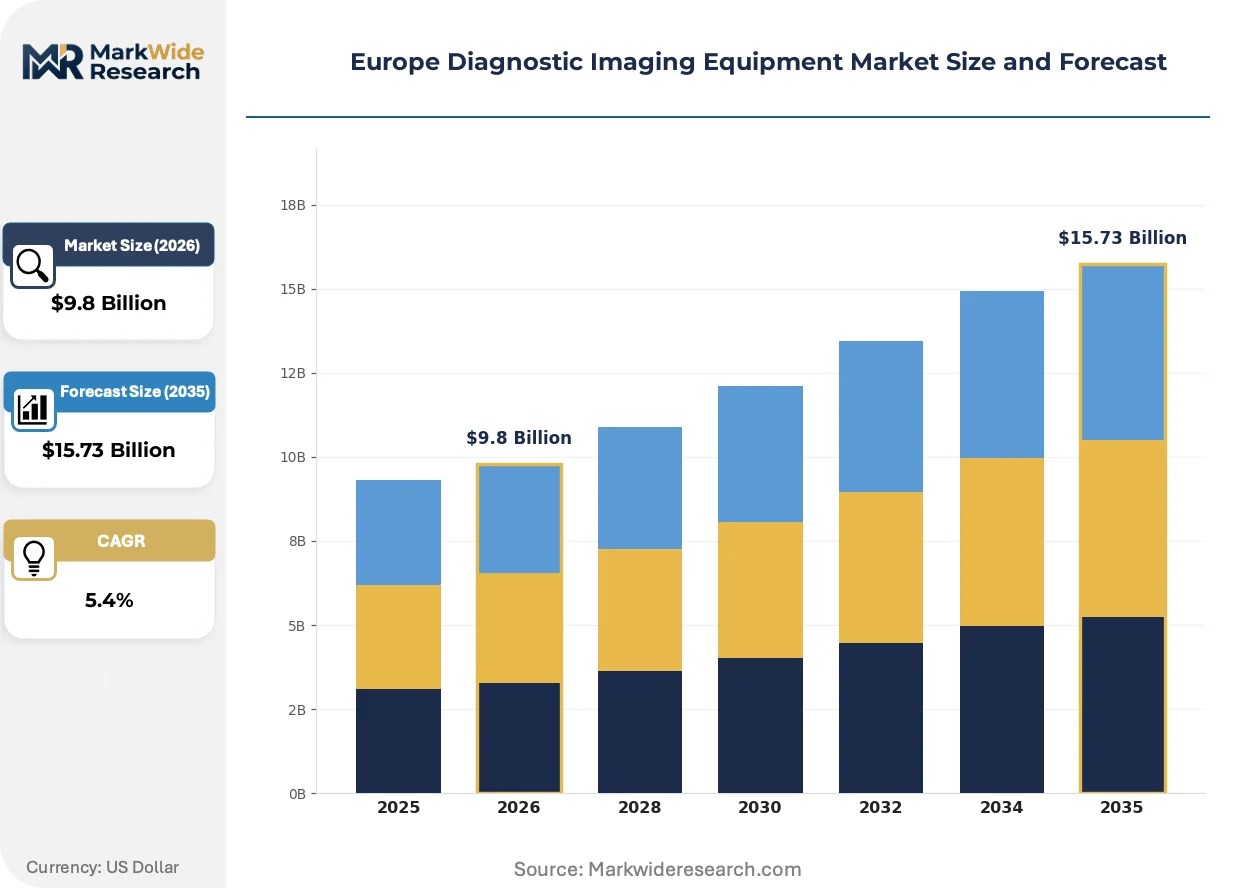
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray, MRI, CT Scanner, Ultrasound End User: Hospitals, Clinics, Imaging Centers, Research Facilities Technology: Digital, Analog, Hybrid, Portable Application: Oncology, Cardiology, Orthopedics, Neurology |
| Companies Covered | FUJIFILM Holdings Corporation, Esaote, Siemens Healthineers, Samsung Electronics, Shimadzu Corporation, Philips Healthcare, Canon Medical Systems Corporation, Agfa-Gevaert, GE HealthCare, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Diagnostic Imaging Equipment Market Shifts & Advancements
Digital workflow integration and autonomous image acquisition are redefining how European radiology departments deploy capital and manage technologist labor. Three developments merit particular attention.
Photon-counting CT detector technology is supplanting conventional energy-integrating detectors in premium scanner configurations. German university hospitals are prioritizing these platforms for cardiac and pulmonary imaging protocols. The technology is compressing dose-exposure thresholds while expanding spectral differentiation capabilities.
EU MDR Article 10 post-market clinical follow-up requirements are reshaping manufacturer-hospital data sharing arrangements. Device registries must now capture real-world performance metrics across installed bases. French ANSM vigilance reporting and German BfArM surveillance are enforcing national layers beyond centralized EU processes.
Subscription-based equipment access is displacing traditional capital purchase models in British and Dutch hospital networks. Procurement teams are prioritizing operational expenditure structures that bundle hardware, software, and service into per-scan pricing. This shift is most visible among NHS trusts facing constrained capital budgets and compressed replacement cycles.
Europe Diagnostic Imaging Equipment Market Segmentation
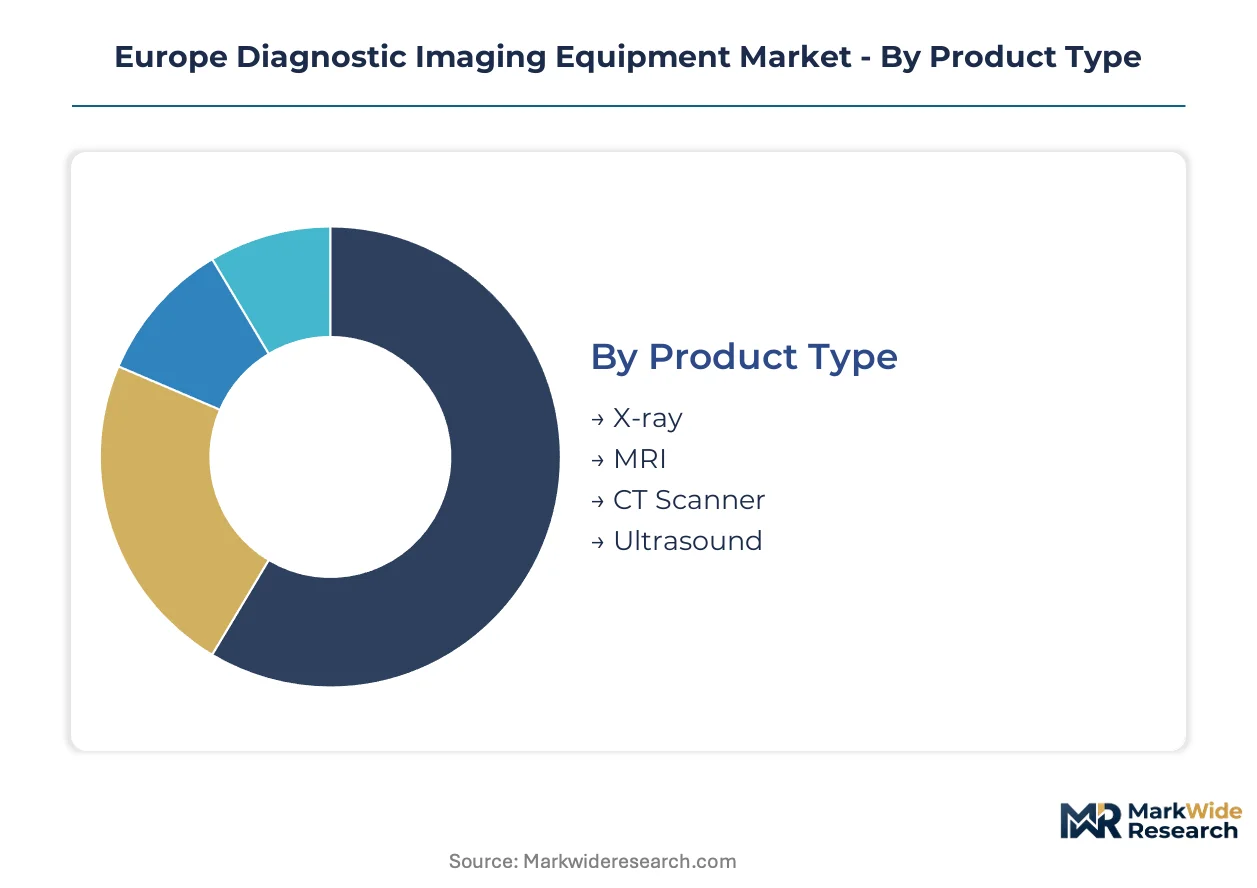
Segmentation in Europe's diagnostic imaging equipment market reveals how procurement priorities diverge across clinical settings and technology generations. Equipment replacement cycles, regulatory compliance deadlines, and reimbursement structures create distinct demand profiles that manufacturers must navigate simultaneously.
Product Type:
Portable ultrasound systems and AI-enabled CT platforms are exerting the strongest substitution pressure on conventional fixed-room imaging infrastructure across German and French hospital networks.
- X-ray:Conventional radiography systems generate two-dimensional projection images using ionizing radiation, with digital detector panels replacing analog film cassettes in routine skeletal and chest examinations. Demand concentrates in Italian regional hospitals and Spanish primary care centers where cost constraints limit premium modality deployment, though reimbursement compression is slowing upgrade cycles.
- MRI:Magnetic resonance imaging platforms exploit superconducting magnets and radiofrequency coils to produce high-contrast soft-tissue visualizations without ionizing radiation. German university hospitals and French public hospital clusters are prioritizing 3 Tesla systems for neuro-oncology protocols, driven by EU MDR compliance deadlines that decommission legacy 1.5 Tesla platforms lacking updated technical documentation.
- CT Scanner:Computed tomography systems reconstruct cross-sectional anatomical datasets from rotating X-ray source-detector arrays, serving emergency department throughput requirements.
- Ultrasound:Acoustic imaging platforms utilizing piezoelectric transducers for real-time anatomical visualization, with portable digital systems capturing Italian and Spanish ambulatory clinic demand.
CT scanner procurement anchors the volume base while portable ultrasound gains share at the steepest rate across outpatient settings.
End User:
Margin structures diverge sharply between capital-rich tertiary centers and budget-constrained community facilities, with imaging centers capturing the most favorable per-scan economics.
- Hospitals:Acute care institutions operate comprehensive imaging departments integrating multiple modalities under centralized radiology governance, with German university hospitals and French CHU clusters driving premium system procurement. EU MDR Article 20 post-market surveillance mandates are accelerating fleet replacement timelines, compressing capital planning cycles.
- Clinics:Outpatient facilities deploy point-of-care imaging for immediate diagnostic confirmation, with portable ultrasound dominating Italian and Spanish primary care networks. Reimbursement parity with hospital-based procedures is expanding addressable demand.
- Imaging Centers:Dedicated diagnostic facilities unbundling radiology services from hospital ownership, capturing favorable per-scan economics through volume concentration and specialized workflow design.
- Research Facilities:Academic and pharmaceutical research institutions operating preclinical and clinical trial imaging infrastructure, with hybrid PET-MRI platforms commanding premium positioning.
Hospitals retain the dominant installed base while imaging centers expand most quickly through service unbundling.
Technology:
Digital acquisition architectures are displacing analog legacy systems at uneven rates across European health systems, with portable configurations reshaping deployment geography.
- Digital:Detector systems converting physical signals directly into electronic data streams, enabling immediate image display and network transmission. German and Scandinavian hospital networks have achieved near-complete digital conversion, with France and Italy trailing in rural facility penetration.
- Analog:Film-based image capture requiring chemical processing and physical storage, concentrated in Eastern European facilities awaiting EU cohesion fund modernization.
- Hybrid:Combined modality platforms integrating functional and anatomical imaging, with PET-CT and PET-MRI systems commanding premium positioning in German oncology centers.
- Portable:Battery-powered or cart-based systems enabling bedside and ambulatory deployment, with ultrasound leading penetration into British and Dutch community care settings.
Digital platforms anchor the technology base while portable configurations climb the fastest through point-of-care expansion.
Application:
Clinical evidence requirements and reimbursement intensity vary substantially across therapeutic areas, with oncology commanding the highest per-scan valuation.
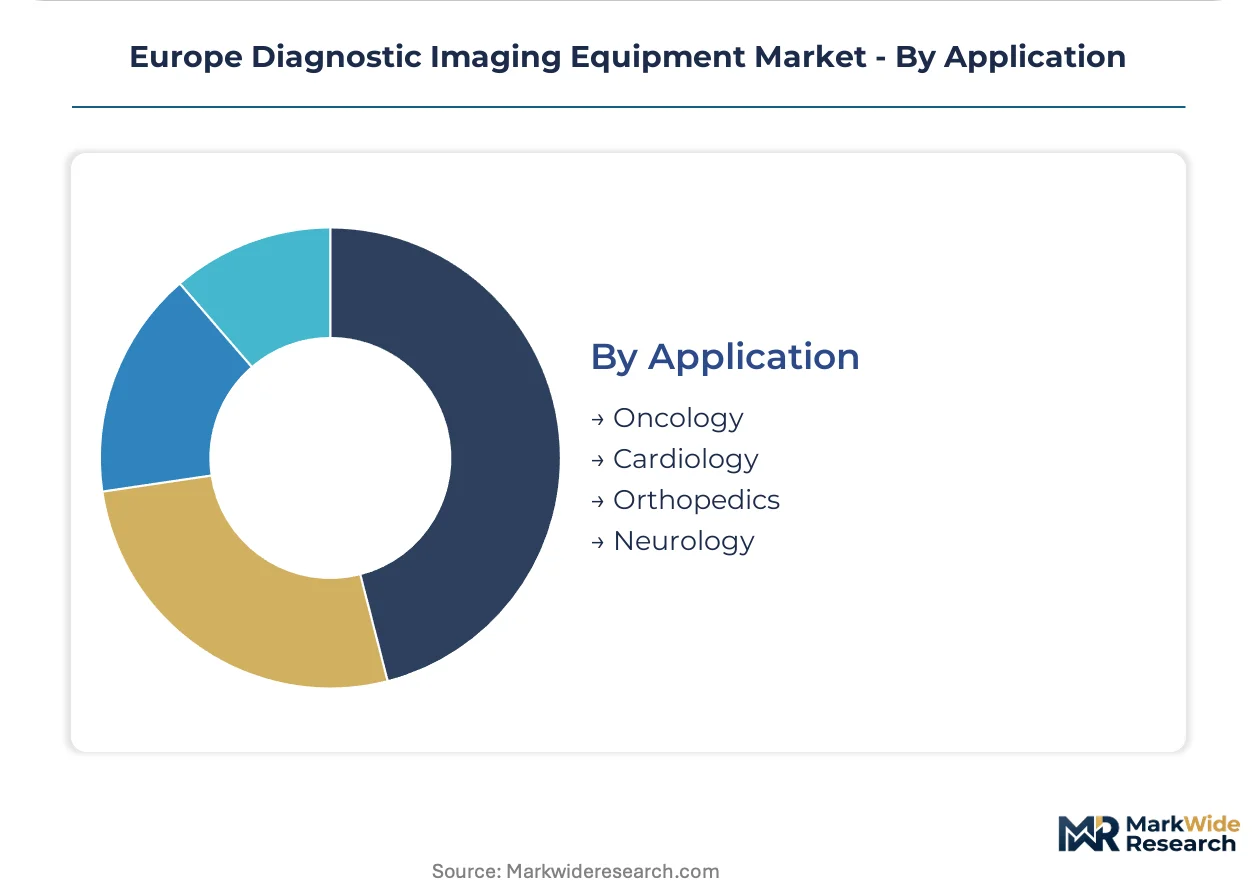
- Oncology:Cancer diagnosis and staging applications utilizing multi-modality imaging protocols, with hybrid PET-MRI platforms expanding diagnostic confidence in German tertiary centers. EU MDR clinical evidence requirements favor established manufacturers with robust post-market surveillance infrastructure.
- Cardiology:Cardiovascular imaging encompassing coronary CT angiography and cardiac MRI for ischemia and structural assessment, with photon-counting CT detectors gaining priority in German university hospital procurement.
- Orthopedics:Musculoskeletal imaging emphasizing MRI for soft-tissue and CT for osseous detail, serving sports medicine and arthroplasty planning workflows.
- Neurology:Central nervous system applications requiring highest-field MRI for demyelinating disease and dementia protocol standardization.
Oncology anchors the value base while cardiology shows the steepest technology upgrade intensity through detector innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing clusters concentrate in southern Germany and the Netherlands, with component sourcing stretching into Switzerland and Scandinavia. Hospital procurement authority fragments across national health systems, creating divergent capital deployment rhythms. Regulatory enforcement tightens most visibly in France and Germany, where notified body capacity constraints delay product launches.
Germany
University hospital networks in Berlin, Munich, and Heidelberg drive premium MRI and CT procurement as EU MDR deadlines accelerate fleet replacement. BfArM vigilance reporting mandates reshape service contract negotiations between manufacturers and public hospital clusters. The Baden-Württemberg and Bavaria industrial corridors host superconducting magnet fabrication and detector assembly operations serving domestic OEMs.
France
Public hospital clusters in Paris, Lyon, and Marseille prioritize hybrid imaging platforms for oncology protocols under compressed replacement timelines. ANSM post-market surveillance requirements layer national compliance obligations atop centralized EU MDR processes. The Île-de-France region concentrates R&D operations for PET-MRI convergence technologies.
United Kingdom
NHS trusts facing capital budget constraints shift toward subscription-based equipment access models bundling hardware, software, and service. MHRA recognition of EU MDR certifications streamlines market entry while preserving distinct national vigilance pathways. Greater London and the Southeast anchor imaging center expansion through service unbundling from hospital ownership.
Italy
Regional health authorities in Lombardy and Emilia-Romagna modernize aging CT installed bases while ambulatory clinics adopt portable ultrasound systems. Reimbursement parity between hospital and outpatient procedures expands addressable demand for point-of-care deployment. The Milan-Turin corridor sustains component supply relationships with German and Dutch OEMs.
Netherlands
Hospital networks in the Randstad region pilot AI-enabled image reconstruction platforms to compress scan times and expand throughput. Eindhoven hosts concentrated hybrid imaging R&D operations leveraging photonics and semiconductor manufacturing infrastructure. Dutch procurement teams favor operational expenditure structures that align equipment costs with utilization rates.
Europe Diagnostic Imaging Equipment Market Competitive Landscape
Concentration sits with diversified health technology conglomerates commanding integrated hardware-software-service portfolios across European hospital networks. Siemens Healthineers and Philips Healthcare anchor the premium tier through installed base scale and service contract penetration. Mid-tier specialists compete on modality-specific excellence in ultrasound and molecular imaging. Strategic moves center on AI licensing partnerships and unbundled service contracts targeting independent maintenance providers.
Among diversified imaging conglomerates, Siemens Healthineers and Philips Healthcare exemplify the integrated-platform archetype spanning MRI, CT, and hybrid modalities. GE HealthCare occupies a position emphasizing digital connectivity between imaging fleets and hospital information systems. Esaote represents the modality-specialist tier with concentrated ultrasound expertise. These anchors illustrate how competitive positioning diverges between full-line coverage and targeted clinical application depth.
| Leading Market Players |
|---|
| FUJIFILM Holdings Corporation |
| Esaote |
| Siemens Healthineers |
| Samsung Electronics |
| Shimadzu Corporation |
| Philips Healthcare |
| Canon Medical Systems Corporation |
| Agfa-Gevaert |
| GE HealthCare |
| Others |
Supply & Pricing Matrix
Take-or-pay service contracts spanning seven-to-ten year horizons lock German university hospitals and French public hospital clusters into predictable cost structures while securing manufacturer commitment to MDR-compliant technical documentation and spare parts availability. This contractual architecture concentrates pricing power with Siemens Healthineers and Philips Healthcare through installed base captivity and switching cost entrenchment.
Pricing Analysis
EU MDR Article 20 dictates the pricing tier structure across European diagnostic imaging equipment, separating premium hybrid imaging platforms with full post-market surveillance bundling from standard MRI and CT configurations with limited compliance documentation and economy-tier refurbished systems targeting Eastern European buyers. Price differentiation hinges on CE marking certification grade and after-sales service integration depth. Cost compression in the economy tier is intensifying because Polish and Romanian procurement teams prioritize upfront capital minimization over total cost of ownership. Imaging centers demonstrate the lowest price sensitivity due to per-scan revenue models, while Italian regional hospitals face acute budget constraints.
Supply Chain Analysis
Germany and the Netherlands anchor superconducting magnet fabrication and detector assembly operations serving domestic OEMs, with Switzerland and Austria feeding precision component streams into Baden-Württemberg manufacturing corridors. Raw material dependencies center on niobium-titanium superconducting wire, rare earth elements for gradient coils, and helium for magnet cooling sourced from Qatar and Algeria. Single-source vulnerability in helium supply exposes manufacturers to allocation constraints and price volatility. Distribution runs through manufacturer-direct sales teams serving hospital procurement committees, supplemented by GPO contracts and independent service organizations capturing maintenance revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's diagnostic imaging equipment market presents a defensive-moat story anchored in regulatory entrenchment. EU MDR compliance deadlines and CE marking technical documentation requirements create switching costs that cement incumbent positions.
For Market Incumbents: Shield installed base revenue through MDR transition service bundling that locks French public hospital clusters into extended maintenance agreements. Deepen backward integration into superconducting wire production to mitigate niobium-titanium supply concentration. Prioritize AI-enabled image reconstruction R&D to compress scan times and justify premium positioning against emerging software-centric competitors.
For New Entrants and Emerging Players: Lead with portable ultrasound platforms targeting Italian and Spanish ambulatory clinics where reimbursement parity with hospital procedures expands addressable demand. Poland and Romania present underpenetrated white-space for CT replacement as EU cohesion funds flow into health infrastructure. Pursue independent service organization partnerships to unbundle maintenance revenue from manufacturer-captive agreements.
For Investors and Strategic Acquirers: Capital is best deployed toward hybrid imaging specialists with PET-MRI convergence capabilities and established EMA technical documentation. Long-term viability over the next decade rests on regulatory compliance infrastructure rather than hardware innovation alone. Monitor notified body capacity constraints as an inflection indicator for product launch delays and capital planning freezes.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Article 10 clinical evidence requirements extend development timelines and favor incumbents. |
| Hospital System Partnership | German university hospital networks prioritize integrated hardware-software-service bundles. |
| Software Companion Development | AI-enabled image reconstruction platforms reduce scan times and expand throughput capacity. |
| Reimbursement Strategy | Italian regional health authorities expand outpatient procedure parity to ambulatory clinics. |
| Backward Integration | Superconducting wire production control mitigates niobium-titanium supply concentration risk. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement managers, biomedical engineers, GPO contracts managers, and radiology department heads. Secondary validation drew from EMA device filings, EU MDR transition databases, hospital procurement records, and notified body capacity reports. Bottom-up equipment shipment modeling and top-down health system capital expenditure analysis were triangulated to anchor market sizing.
Across the analysis window, forecasts segmented by modality type, end-user setting, technology generation, and application area were constructed using replacement cycle dynamics, regulatory deadline impacts, and reimbursement trajectory inputs. CAGRs were derived from installed base depreciation curves and modernization funding flow projections. Helium supply volatility and notified body bottlenecks were modeled as scenario variables.
Forecasts assume regulatory continuity in EU MDR enforcement and national reimbursement regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Asia Pacific Computed Tomography (CT) Market
Medical Imaging
Global Ultrasound Imaging Devices Market
Medical Imaging
Mobile Gamma Cameras Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Contrast Agents Market
Medical Imaging
Dental Digital X Ray Market
Medical Imaging
Optical Coherence Tomography Market
Medical Imaging
Medical X-Ray Market
Medical Imaging
Magnetic Resonance Imaging Market
Medical Imaging
Medical Hyperspectral Imaging Market
Medical Imaging
Diagnostic X-Ray System Market
Medical Imaging
Digital Mobile X-Ray Products Market
Medical Imaging
Global Technetium-99M Market
Medical Imaging
South Africa Mammography Market
Medical Imaging
Global Veterinary Diagnostic Imaging Market
Medical Imaging
US Imaging Services Market
Medical Imaging
United Kingdom Digital X-Ray Devices Market