
 Global Colonoscopes Market | 2026-2036
Global Colonoscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Colonoscopes Market Foresight
Japanese endoscope manufacturing is broadening its addressable scope beyond traditional reusable platforms. Olympus Corporation leverages decades of optical engineering dominance to sustain leadership in high-definition imaging systems. FUJIFILM Holdings Corporation competes through integrated sensor-to-display technology stacks that differentiate its endoscopy portfolio. Ambu A/S anchors the single-use segment with dedicated manufacturing capacity that positions it against established reusable incumbents.
A colonoscope is a flexible tubular instrument typically 130-170 cm in length with a distal tip articulation range of 180-210 degrees, designed for direct visual examination of the colonic mucosa and operative interventions such as polypectomy or biopsy retrieval. Its primary commercial purpose centers on enabling minimally invasive diagnostic and therapeutic procedures within the lower gastrointestinal tract. Single-use colonoscopes command premium positioning against standard reusable platforms as hospitals weigh reprocessing compliance costs against per-procedure disposable pricing. Narrow band imaging technology leads optical differentiation by enhancing vascular pattern visualization for polyp characterization, while confocal laser endomicroscopy occupies a specialized niche offering cellular-level resolution during live examination.
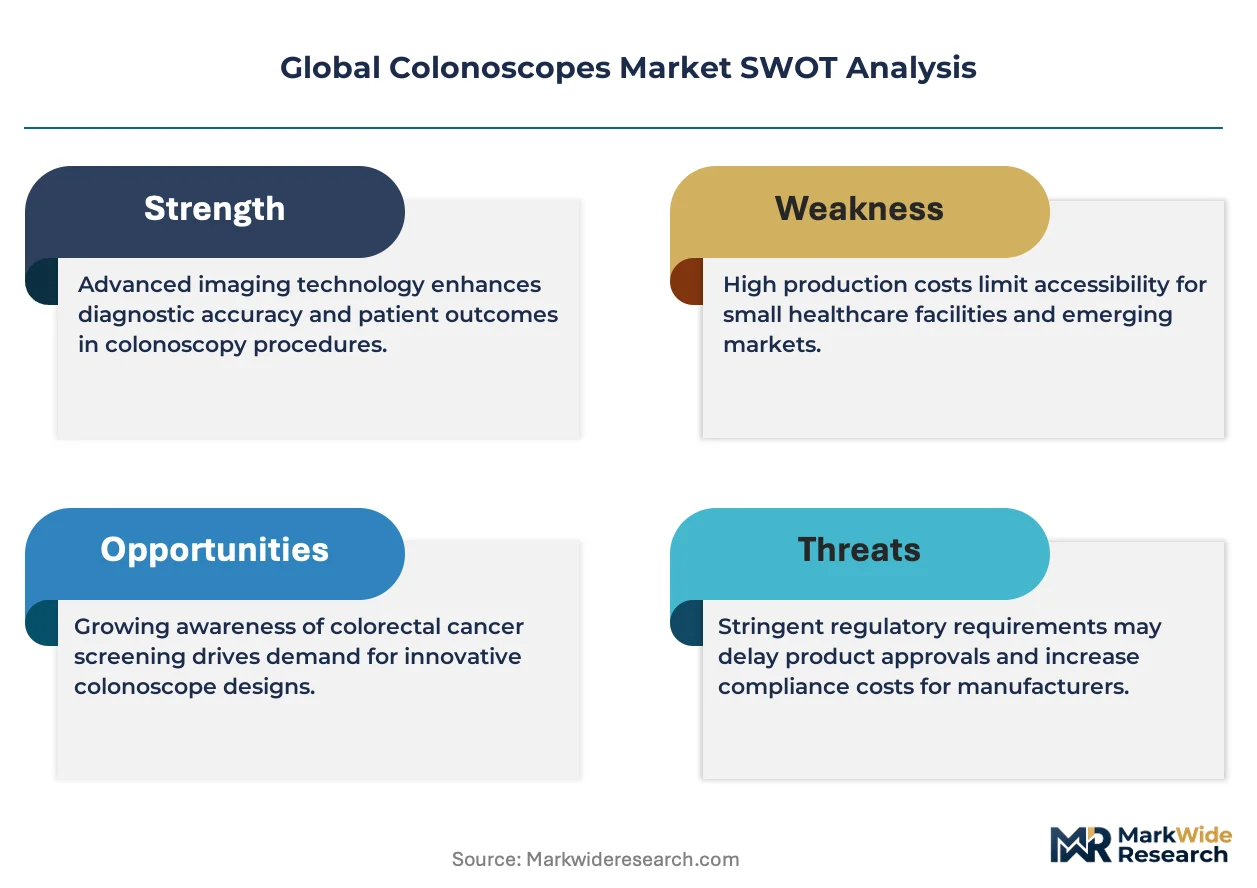
The FDA enforces reprocessing validation requirements under 510(k) pathways that shape manufacturer design controls and clinical testing obligations for reusable devices. The EU MDR and ISO 13485 quality management standards govern market access across European member states, with notified body scrutiny intensifying for devices classified as Class IIa or higher risk. Japan's PMDA maintains distinct pharmaceutical and medical device approval frameworks that filter foreign manufacturer entry. Stakeholders must monitor how reprocessing liability exposure and sustainability reporting obligations under the EU Green Deal redirect procurement criteria across hospital systems.
Market Dynamics
Single-use colonoscopes are compressing the installed base economics of reusable systems as ambulatory surgery centers absorb higher per-procedure costs to eliminate reprocessing liability and FDA validation burdens. This substitution dynamic is redrawing competitive boundaries between disposable specialists and established optical incumbents.
Growth Catalysts
- FDA Reprocessing Mandates:Stricter 510(k) validation requirements for reusable device reprocessing are accelerating facility migration toward disposable alternatives that bypass sterilization protocols entirely.
- Ambulatory Surgery Center Expansion:Freestanding outpatient facilities in the United States are prioritizing single-use inventory models that reduce capital equipment footprints and simplify infection control workflows.
- Narrow Band Imaging:Optical enhancement technology that improves vascular pattern visualization during polyp characterization is differentiating premium system purchases across Japanese and German hospital procurement cycles.
Market Restraints
- Polymer Input Volatility:Medical-grade thermoplastic elastomer prices fluctuate with petrochemical feedstock markets, compressing margins for single-use manufacturers dependent on consistent material costs.
- Optical Component Concentration:High-definition image sensor supply concentrates among Japanese and South Korean semiconductor foundries, creating single-source vulnerability for colonoscope camera modules.
- EU MDR Transition Friction:Extended notified body review timelines for Class IIa device recertification are delaying product line updates and freezing commercial expansion across European member states.
Strategic Opportunities
- Indian Screening Program Expansion:National colorectal cancer awareness initiatives and rising private hospital infrastructure investment are opening addressable procedure volume in underserved urban and semi-urban markets.
- Confocal Laser Endomicroscopy Convergence:Integration of cellular-resolution optical biopsy with standard colonoscope platforms enables real-time histology during live examination, commanding premium positioning in academic medical centers.
- EU Green Deal Procurement Criteria:Sustainability reporting obligations and circular economy mandates are redirecting hospital purchasing toward manufacturers with validated recyclable single-use material streams and carbon footprint disclosures.
Industry Challenges
- Reprocessing Technician Certification:Reusable system manufacturers face shrinking pools of credentialed sterile processing professionals capable of meeting evolving FDA and ISO 17664 documentation standards.
- Legacy System Integration Complexity:Disposable colonoscope adoption requires video processor compatibility with existing tower configurations, forcing manufacturers to maintain multi-generation connector protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Colonoscopes Market |
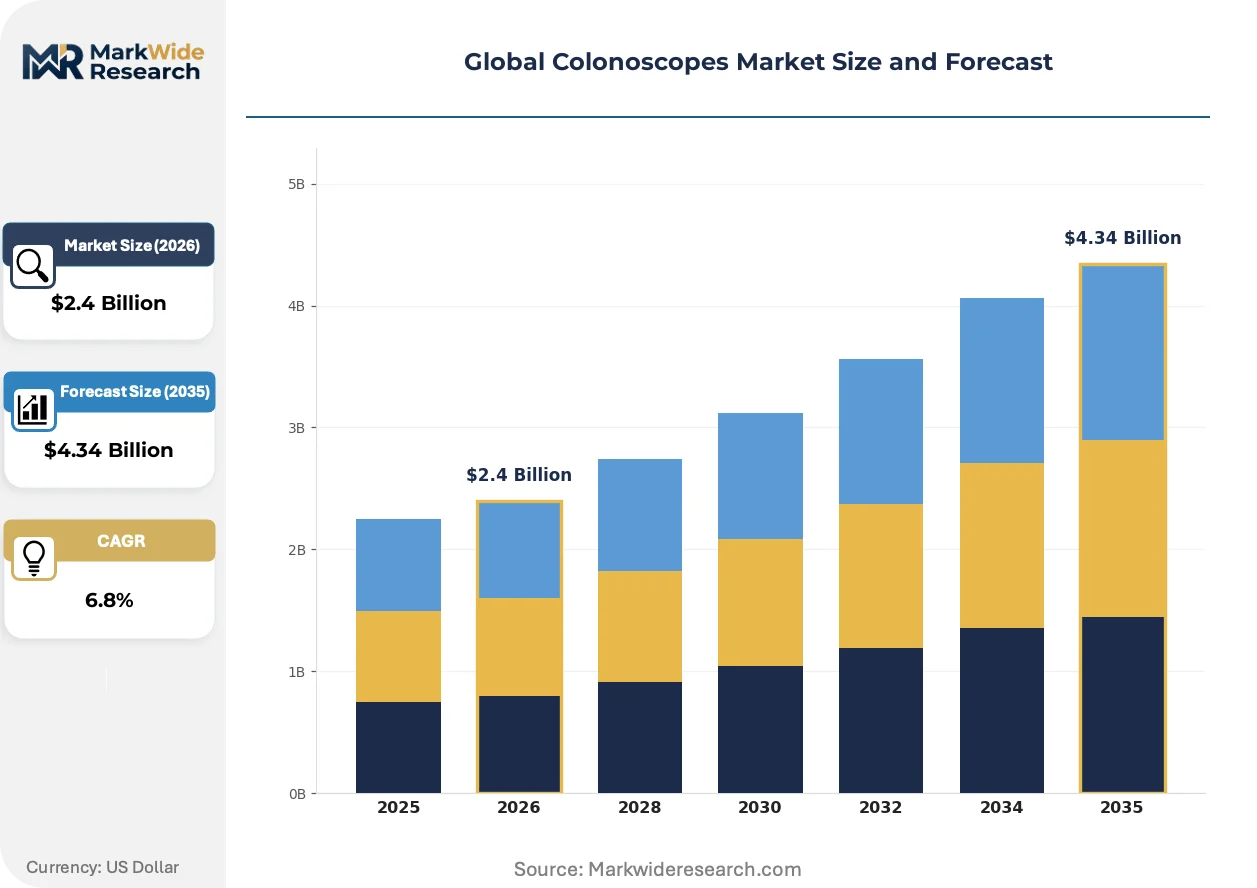
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Colonoscopes, Pediatric Colonoscopes, High-Definition Colonoscopes, Capsule Colonoscopes, Single-Use Colonoscopes Technology: Optical Imaging, Narrow Band Imaging, Chromoendoscopy, Autofluorescence Imaging, Confocal Laser Endomicroscopy Application: Colorectal Cancer Screening, Inflammatory Bowel Disease Diagnosis, Polyp Detection, Gastrointestinal Bleeding Investigation, Diverticulosis Analysis End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Clinics, Academic Research Institutes |
| Companies Covered | Olympus Corporation, FUJIFILM Holdings Corporation, PENTAX Medical, Medtronic, Ambu A/S, Endomed Systems GmbH, HOYA Corporation, KARL STORZ, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Colonoscopes Market Shifts & Advancements
Artificial intelligence-assisted polyp detection algorithms and disposable platform miniaturization are compressing the capability gap between high-end reusable systems and single-use alternatives. These developments are reshaping procurement criteria and R&D allocation across the supply base.
Sensor-integrated disposable colonoscopes are integrating complementary metal-oxide-semiconductor imaging chips directly into single-use distal tips, eliminating fiber optic bundles and enabling digital signal transmission. Ambulatory surgery centers in the United States are adopting these platforms at accelerated cadences to reduce capital depreciation cycles. This architecture is integrating onboard processing capability that enables real-time image enhancement without external processor dependency.
The EU MDR's intensified clinical evidence requirements for reusable device reprocessing claims are extending regulatory timelines and increasing notified body audit frequency. Manufacturers must now submit post-market surveillance data demonstrating sustained sterilization efficacy across declared device lifecycles. Japanese PMDA approval pathways for novel disposable platforms are compressing relative to European timelines, redirecting product launch sequencing toward Asian markets.
Hospital procurement departments are unbundling colonoscope acquisitions from bundled service contracts that previously locked facilities into single-vendor reprocessing ecosystems. Independent third-party sterilization validation services are displacing manufacturer-captive reprocessing programs in German and United States health systems. This purchasing autonomy is most visible in multi-hospital integrated delivery networks seeking to diversify supply risk across competing disposable and reusable platforms.
Global Colonoscopes Market Segmentation
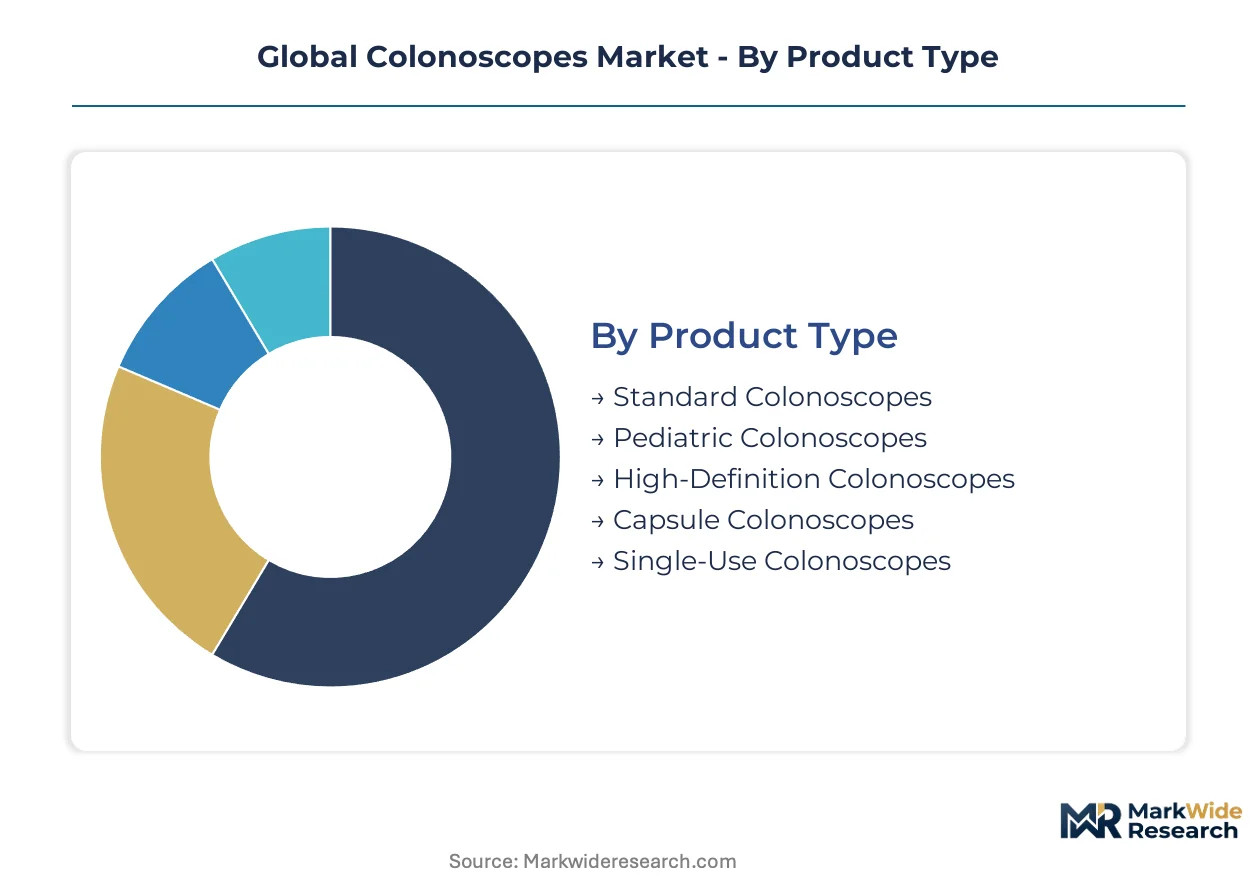
Colonoscope procurement patterns diverge sharply across product architectures, imaging modalities, and care settings. Understanding these fault lines reveals where capital deployment concentrates and which segments command pricing premiums.
Product Type:
Capital requirements vary dramatically across reusable and disposable platforms, with single-use manufacturing demanding dedicated cleanroom infrastructure while reusable systems require sustained R&D investment in optical durability.
- Standard Colonoscopes:Conventional reusable platforms with fiber optic or digital imaging bundles constitute the installed base majority across hospital systems. Demand concentrates in Germany and Japan where established screening programs sustain high procedure volumes and facilities amortize capital equipment over extended depreciation cycles.
- Single-Use Colonoscopes:Disposable polymer platforms eliminate reprocessing infrastructure entirely, commanding per-procedure premiums that ambulatory surgery centers absorb to reduce FDA compliance exposure. United States freestanding outpatient facilities are expanding adoption fastest as infection control protocols tighten and sterile processing technician shortages deepen.
- High-Definition Colonoscopes:Advanced imaging platforms with enhanced resolution sensors for polyp characterization.
- Pediatric Colonoscopes:Reduced-diameter instruments designed for neonatal and pediatric gastrointestinal examination.
- Capsule Colonoscopes:Ingestible imaging devices for non-invasive colonic visualization.
Most installed capacity flows through Standard Colonoscopes. Expansion is steepest in Single-Use Colonoscopes.
Technology:
Imaging modality selection tracks directly with reimbursement levels and academic medical center density, where advanced optical techniques justify premium procedure coding.
- Narrow Band Imaging:Optical filter technology enhances hemoglobin absorption patterns to improve vascular visualization during polyp characterization. Japanese hospital procurement cycles prioritize this capability for differentiating premium system purchases, with Olympus and FUJIFILM integrating the technology across their flagship platforms.
- Confocal Laser Endomicroscopy:Cellular-resolution optical biopsy enables real-time histology during live examination through miniatureized laser scanning microscopy. Academic medical centers in the United States and Germany command this capability for research applications and complex diagnostic cases where immediate tissue characterization alters therapeutic decisions.
- Optical Imaging:Standard white-light visualization systems forming the baseline imaging architecture.
- Chromoendoscopy:Dye-spray contrast enhancement for mucosal pattern delineation.
- Autofluorescence Imaging:Tissue autofluorescence detection for neoplasia identification.
Revenue concentration sits with Narrow Band Imaging. Gaining share fastest is Confocal Laser Endomicroscopy.
Application:
Procedure volume distribution aligns with population screening program maturity and colorectal cancer incidence demographics across national health systems.
- Colorectal Cancer Screening:Population-scale preventive examination programs drive the largest procedure volume category. Japan's national screening infrastructure and United States Medicare reimbursement for colonoscopy following positive stool tests sustain demand concentration in these markets.
- Polyp Detection:Therapeutic intervention during diagnostic examination for adenoma identification and removal. Ambulatory surgery centers in the United States prioritize disposable platforms for these procedures to minimize reprocessing liability while maintaining throughput efficiency.
- Inflammatory Bowel Disease Diagnosis:Diagnostic and surveillance examination for Crohn's disease and ulcerative colitis monitoring.
- Gastrointestinal Bleeding Investigation:Emergency and elective procedures for obscure or overt bleeding source identification.
- Diverticulosis Analysis:Examination for diverticular disease complications and differential diagnosis.
Procedure volume leadership belongs to Colorectal Cancer Screening. Climbing the fastest is Polyp Detection.
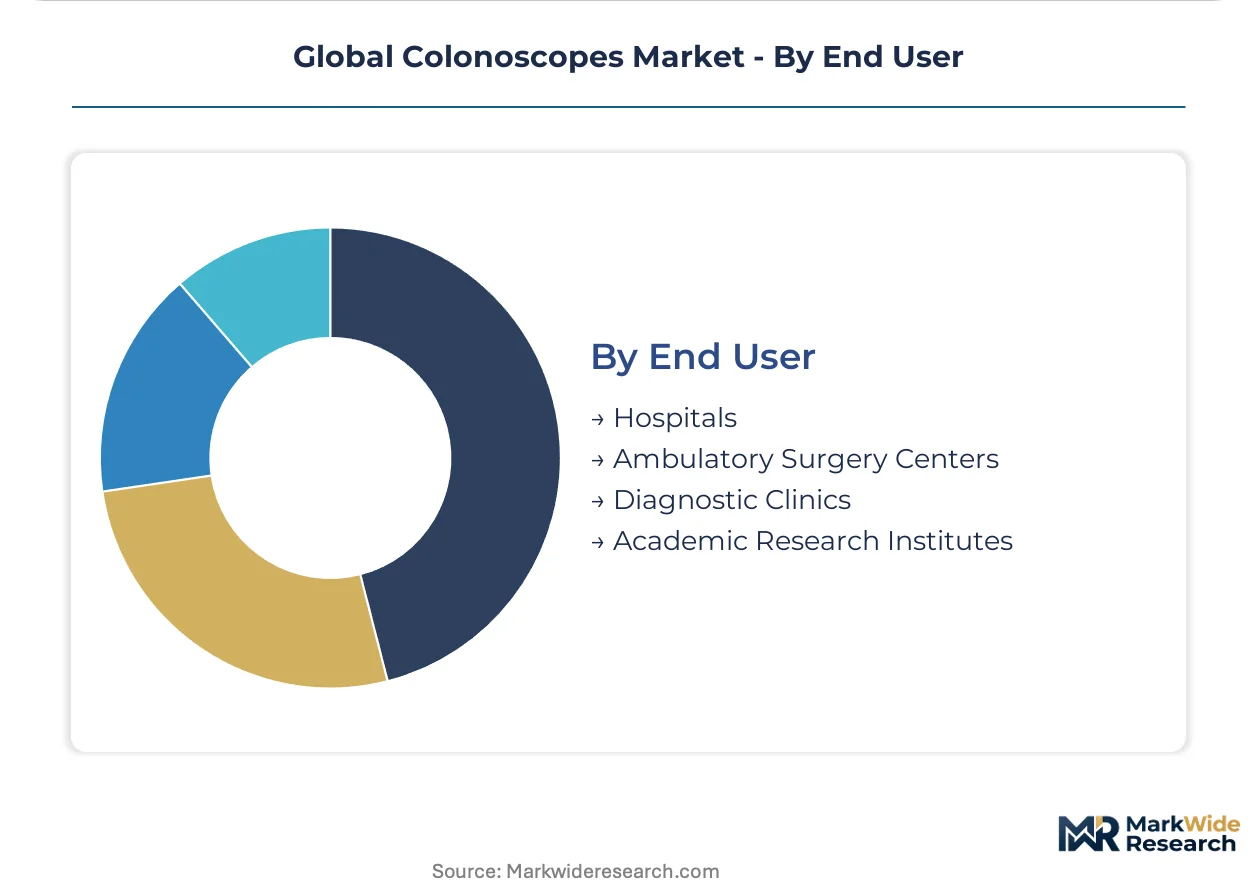
End User:
Facility type determines capital intensity tolerance, reprocessing infrastructure investment, and procurement autonomy within integrated delivery networks.
- Hospitals:Acute care institutions with captive sterile processing departments and multi-specialty endoscopy suites. German and Japanese hospital systems maintain substantial reusable platform fleets due to high procedure density and amortized capital equipment.
- Ambulatory Surgery Centers:Freestanding outpatient facilities prioritizing single-use inventory models to eliminate reprocessing infrastructure and reduce infection control complexity. United States ASC expansion is accelerating disposable colonoscope adoption as regulatory scrutiny of reusable device sterilization intensifies.
- Diagnostic Clinics:Specialized gastrointestinal examination facilities with focused endoscopy services.
- Academic Research Institutes:Teaching hospitals and research centers driving adoption of advanced imaging modalities for clinical investigation.
Equipment deployment concentrates in Hospitals. Steepest expansion trajectory runs through Ambulatory Surgery Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States screening volumes outpace German procedure density, while Japanese optical component clusters supply imaging systems to both markets. National health program maturity and regulatory stringency create divergent procurement patterns across these concentrated demand centers.
United States
Medicare reimbursement for diagnostic colonoscopy and stool-test follow-up procedures sustains the world's highest per-capita screening rates. FDA 510(k) reprocessing validation requirements for reusable devices are accelerating ambulatory surgery center migration toward disposable platforms. Minneapolis and Boston medical device corridors host sterile processing validation laboratories serving multi-hospital integrated delivery networks.
Germany
Statutory health insurance coverage for colorectal cancer screening beginning at age 50 maintains procedure volume concentration in Western Europe. EU MDR notified body scrutiny of Class IIa device recertification is extending product update timelines for reusable system manufacturers. Tübingen and Hamburg harbor endoscopy service clusters where independent third-party sterilization validation is displacing manufacturer-captive reprocessing programs.
Japan
National screening program infrastructure and aging demographics sustain dense procedure throughput in hospital-based endoscopy suites. PMDA approval pathways for novel disposable platforms are compressing relative to European regulatory timelines, redirecting product launch sequencing. Tokyo and Nagoya optical engineering clusters concentrate CMOS image sensor foundry capacity for high-definition colonoscope camera modules.
India
Private hospital infrastructure investment in tier-1 and tier-2 cities is expanding addressable procedure volume beyond government screening program limitations. CDSCO medical device registration requirements are filtering import-dependent supply chains toward domestic assembly partnerships. Mumbai and Bangalore medical device manufacturing zones are attracting contract sterilization services for reusable platform refurbishment.
South Korea
National cancer screening program expansion and rising private diagnostic clinic density are compressing procedure wait times in metropolitan health systems. MFDS quality management system audits for foreign manufacturers are standardizing import compliance documentation. Seoul Capital Area medical device distributors are consolidating procurement autonomy for multi-hospital networks seeking disposable-reusable platform diversification.
Global Colonoscopes Market Competitive Landscape
Japanese producers anchor one tier; Danish specialists hold the disposable platform vector. Market structure concentrates around optical engineering incumbents with decades of imaging system integration against single-use manufacturing specialists with dedicated cleanroom infrastructure. Three archetypes dominate: diversified medical technology conglomerates with endoscopy divisions, pure-play disposable platform manufacturers, and specialized optical component suppliers. Competitive moves center on video processor compatibility licensing and multi-generation connector protocol maintenance to preserve installed base relationships.
Within the diversified conglomerate tier, Olympus Corporation and FUJIFILM Holdings Corporation exemplify integrated sensor-to-display technology stacks that differentiate premium system positioning. Ambu A/S occupies the single-use specialist archetype with manufacturing capacity dedicated entirely to disposable platform production. These three entities represent the competitive fault line between reusable optical durability and disposable infection control elimination.
| Leading Market Players |
|---|
| Olympus Corporation |
| FUJIFILM Holdings Corporation |
| PENTAX Medical |
| Medtronic |
| Ambu A/S |
| Endomed Systems GmbH |
| HOYA Corporation |
| KARL STORZ |
| Boston Scientific Corporation |
| Others |
Supply & Pricing Matrix
Reusable-disposable platform divergence splits procurement economics between capital-intensive sterilization infrastructure and per-procedure premium absorption. Japanese optical component clusters feed sensor modules to German and United States assembly facilities, while polymer resin pricing volatility in single-use manufacturing compresses margin buffers against fixed reprocessing cost benchmarks.
Pricing Analysis
Distributor margins for reusable systems compress under direct-to-hospital GPO contracting, while disposable platforms command list-price premiums through specialty distributors serving ambulatory surgery centers. Pricing stratifies across premium high-definition imaging, standard fiber-optic bundles, and economy pediatric configurations, with FDA reprocessing validation costs pushing hospital procurement toward higher per-procedure disposable spend. Ambulatory surgery centers exhibit highest price sensitivity to capital equipment acquisition, whereas academic medical centers absorb premium imaging tariffs for narrow band and confocal capabilities.
Supply Chain Analysis
Single-source vulnerability sits with Japanese CMOS image sensor foundries supplying camera modules to Olympus and FUJIFILM assembly lines. Medical-grade thermoplastic elastomer feedstock draws from German and United States petrochemical complexes, while optical glass fiber concentrates in Japanese and South Korean specialty manufacturers. Tariff exposure on Chinese polymer intermediates threatens single-use margin structures. Distribution runs through hospital GPO contracts in the United States, statutory health insurance tenders in Germany, and regional distributor networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The colonoscopes market compounds steadily as aging demographics in developed economies sustain screening program volumes regardless of cyclical healthcare spending pressures.
For Market Incumbents: Lock in video processor compatibility licensing across multi-generation connector protocols to preserve installed base relationships against disposable platform substitution. Secure captive sterile processing validation capacity in Minneapolis and Boston corridors before technician certification shortages deepen. Vertical integration into CMOS sensor sourcing from Tokyo-Nagoya clusters reduces single-source exposure for high-definition camera modules. For New Entrants and Emerging Players: EU MDR transition friction in Germany opens a window for disposable platform market entry while notified body recertification delays freeze incumbent reusable line updates. Target United States ambulatory surgery center expansion in freestanding outpatient markets where infection control protocol tightening eliminates reprocessing infrastructure requirements. Lead with sensor-integrated disposable architectures that bypass external processor dependency and reduce capital depreciation cycles. For Investors and Strategic Acquirers: Consolidation pressure builds where sterile processing technician certification pools shrink beneath FDA and ISO 17664 documentation standards. Five-to-ten year viability favors pure-play disposable manufacturers with dedicated cleanroom infrastructure over diversified conglomerates managing legacy reusable platform obsolescence. Watch PMDA approval timeline compression relative to EU MDR as signal for Asian market launch sequencing advantages.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Disposable Platform | Bypasses reprocessing validation burdens that compress reusable system margins in United States ASCs. |
| CE Marking Pathway under EU MDR | Notified body scrutiny for Class IIa devices extends timelines but secures German statutory insurance access. |
| Hospital System Partnership | GPO contract penetration in United States integrated delivery networks diversifies across disposable and reusable supply. |
| Software Companion Development | AI-assisted polyp detection algorithms differentiate premium system positioning against commodity imaging. |
| Reimbursement Strategy | Medicare coverage for screening colonoscopy sustains United States procedure volume concentration. |
Research Methodology
Direct dialogue with hospital purchasing committees, biomedical engineers, GPO contracts managers, and sterile processing technicians grounded demand-side validation. Secondary sources encompassed FDA 510(k) filings, EU MDR notified body documentation, Japanese PMDA approval records, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up procedure volume estimates triangulated against top-down equipment installed base calculations.
Segment-level outputs across reusable-disposable platform split, imaging modality tier, application type, and end-user facility category fed into analytical framework spanning the projection horizon. CAGRs derived from procedure volume growth rates, equipment replacement cycles, and pricing trajectory assumptions. Model inputs incorporated aging demographic screening penetration, regulatory reprocessing mandate evolution, and ambulatory surgery center expansion cadence.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR recertification timeline extensions or polymer feedstock price spikes. Forecasts reflect documented assumptions regarding screening program adherence and disposable platform clinical acceptance. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Capsule Endoscopy Market
Endoscopy
Endoscopic Submucosal Dissection Market
Endoscopy
Non-Invasive Colon Cancer Screening Market
Endoscopy
Laryngeal Mirrors Market
Endoscopy
Global Disposable Endoscope Market
Endoscopy
Endoscopic Balloon Dilator Market
Endoscopy
South Africa Endoscopy Devices Market
Endoscopy
Bronchoscopy Market
Endoscopy
Global Endoscopic Vessel Harvesting Systems Market
Endoscopy
Endoscopy Equipment Market
Endoscopy
UAE Endoscopy Devices Market
Endoscopy
China Arthroscopy Market
Endoscopy
US Colonic Stents Market
Endoscopy
Brazil Endoscopy Devices Market
Endoscopy
France Endoscopy Devices Market
Endoscopy
United Kingdom Endoscopy Devices Market