
 Italy Endoscopy Devices Market | 2026-2036
Italy Endoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Endoscopy Devices Market Foresight
Buyer concentration among Italian hospital networks is recalibrating procurement dynamics across the endoscopy devices sector. Karl Storz SE & Co. KG anchors its position through deep specialization in rigid endoscope engineering for surgical suites. Olympus Corporation leverages its integrated visualization platform to sustain channel control across major northern hospital procurement consortia. Medtronic PLC competes by extending its therapeutic endoscope portfolio into bariatric and gastroenterology service lines.
Italy endoscopy devices encompass flexible and rigid optical instruments, visualization systems, and procedural accessories designed for minimally invasive diagnostic and therapeutic intervention inside hollow organs and body cavities. These instruments typically incorporate high-definition image sensors, dedicated irrigation channels, and biopsy ports enabling tissue sampling during live visualization. Flexible endoscopes dominate current procurement volumes due to their versatility across gastroenterology and pulmonology departments, while disposable endoscopes represent the fastest-expanding product category as infection control protocols tighten. Visualization systems capture disproportionate margin pools because software-integrated platforms lock hospitals into recurring service contracts and upgrade cycles.
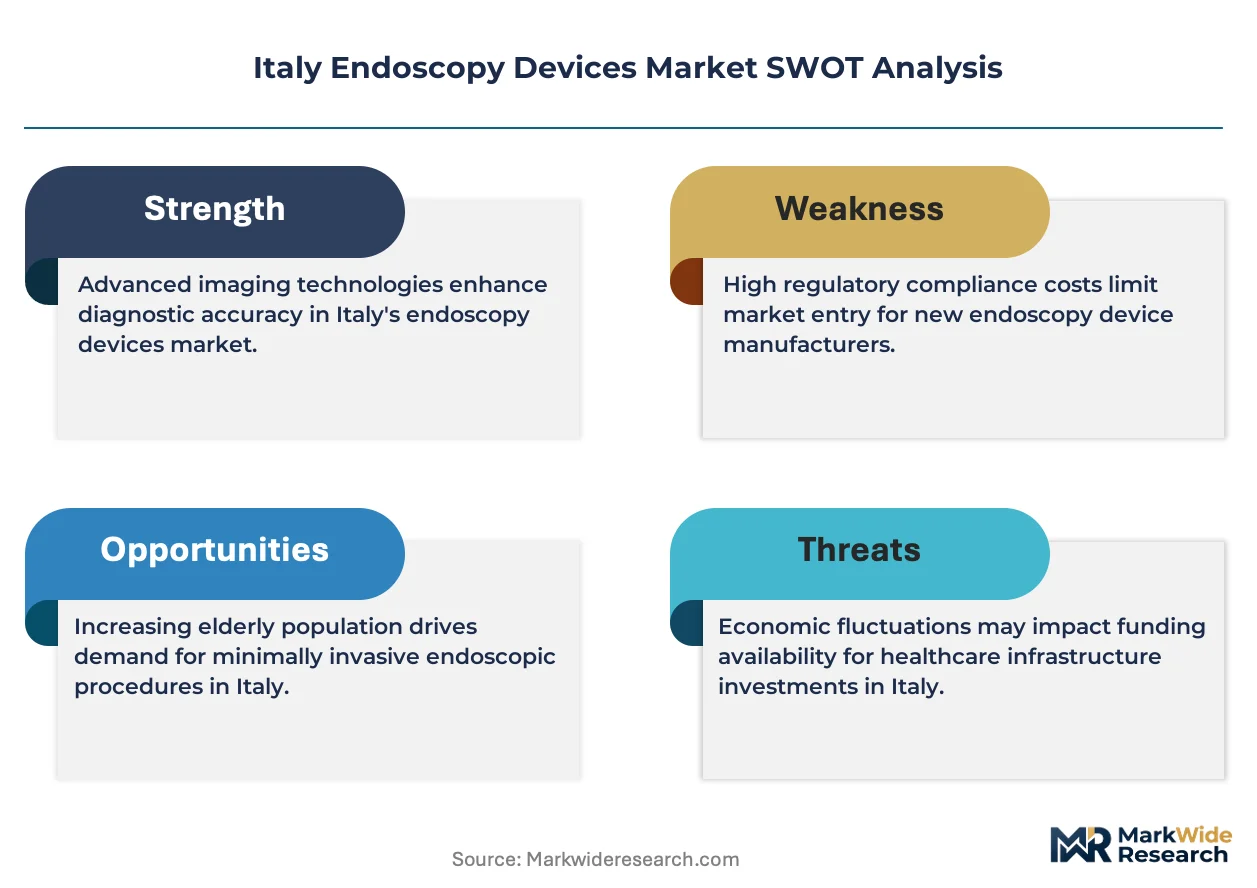
EU MDR and CE marking requirements shape product registration timelines and clinical evidence standards for all manufacturers serving Italian providers. Italy's Ministry of Health and regional health agencies enforce procurement transparency rules that favor vendors with established local technical service infrastructure. Stakeholders must monitor how EU AI Act provisions will classify emerging computer-aided detection modules embedded in next-generation visualization platforms.
Market Dynamics
EU MDR compliance deadlines are compressing product registration timelines and forcing manufacturers to rebuild clinical evidence portfolios for legacy devices already circulating in Italian hospital networks. This regulatory pressure is reshaping competitive access and procurement eligibility across the peninsula.
Growth Catalysts
- EU MDR traceability mandates:Enhanced device tracking requirements are accelerating replacement cycles for non-compliant legacy endoscopes in Lombardy and Veneto hospital consortia.
- Disposable endoscope technology:Infection control protocols in gastroenterology departments are driving rapid adoption of single-use flexible scopes for high-risk procedures.
- Northern industrial cluster density:Concentrated specialized service networks around Milan reduce downtime costs and support just-in-time procurement for acute care facilities.
Market Restraints
- EU MDR certification bottlenecks:Notified body capacity constraints extend product approval timelines by 12-24 months, freezing new entrants from commercial launch.
- Visualization platform lock-in:Proprietary software ecosystems from incumbent manufacturers create switching costs that fragment procurement autonomy for hospital networks.
- Reprocessing labor intensity:Manual cleaning protocols for reusable flexible endoscopes consume disproportionate sterile processing department capacity and compliance risk exposure.
Strategic Opportunities
- Central and southern regional expansion:Underpenetrated procurement networks in Campania, Sicily, and Calabria present whitespace for service-capable vendors willing to build local technical infrastructure.
- Computer-aided detection convergence:Integration of AI-powered polyp recognition with next-generation visualization platforms creates premium pricing power in screening programs.
- EU AI Act compliance positioning:Early certification of software-as-a-medical-device modules will secure preferred vendor status as algorithmic diagnostic aids become reimbursable.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized repair technicians for rigid endoscope optics are concentrated in northern Italy, constraining nationwide service response times.
- Legacy system integration friction:Hospital IT departments face complex interoperability demands when connecting new visualization platforms to existing PACS and EMR architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Endoscopy Devices Market |
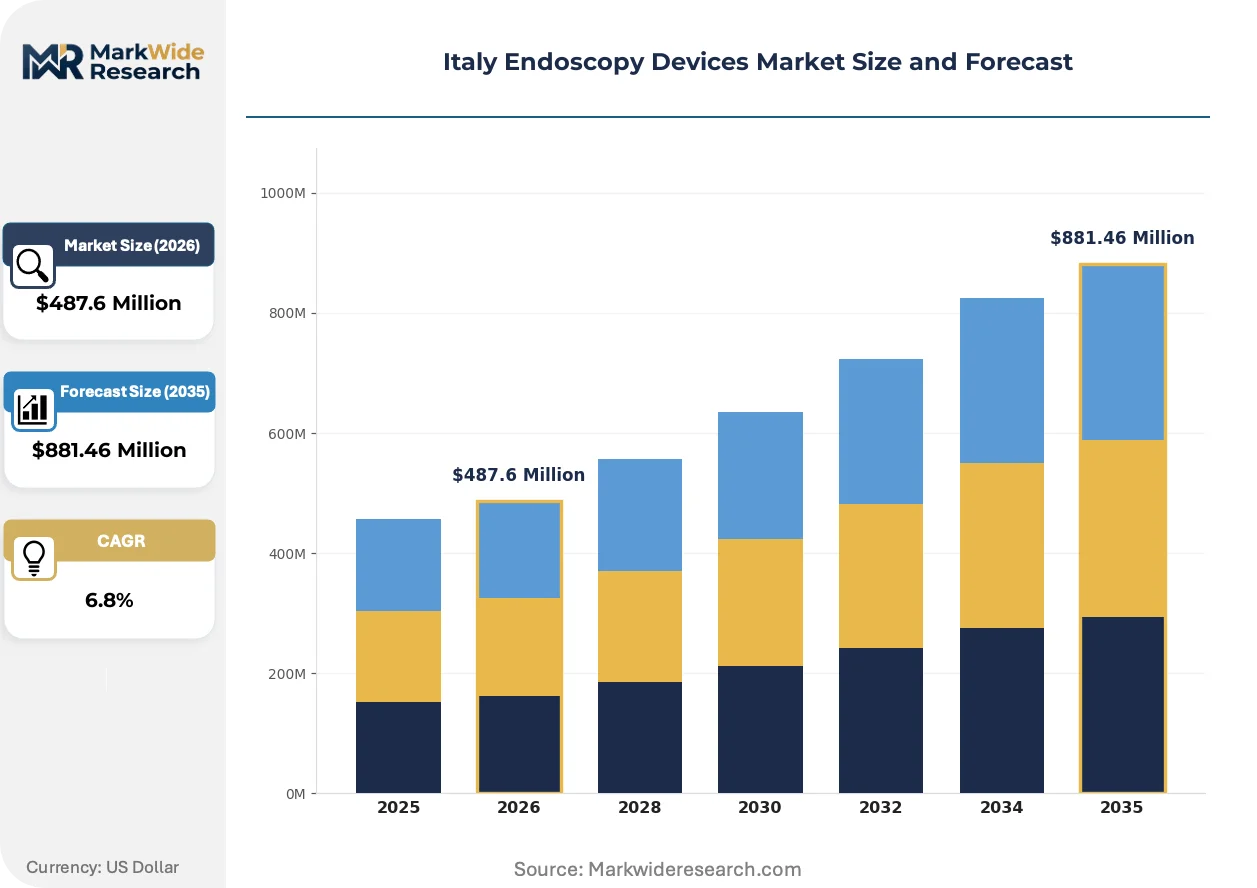
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Flexible Endoscopes, Rigid Endoscopes, Visualization Systems, Accessories Product Category: Diagnostic Endoscopes, Therapeutic Endoscopes, Surgical Endoscopes, Disposable Endoscopes End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Institutes Application: Gastroenterology, Pulmonology, Urology, Bariatric Surgery |
| Companies Covered | Karl Storz SE & Co. KG, Johnson & Johnson, Boston Scientific Corporation, Cook Group Incorporated, CONMED Corporation, Medtronic PLC, Fujifilm Holdings Corporation, Ambu, Olympus Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Endoscopy Devices Market Shifts & Advancements
Disposable endoscope technology is disrupting established reprocessing economics while AI-integrated visualization platforms are redefining diagnostic workflow efficiency in Italian screening programs.
Single-use flexible endoscopes are decentralizing infection control risk management from central sterile supply departments to point-of-care disposal protocols. Gastroenterology units in Emilia-Romagna and Tuscany are adopting these devices for ERCP and bronchoscopy procedures where cross-contamination liability is highest. This shift is decentralizing capital allocation decisions from procurement committees to individual department heads who prioritize procedure throughput over equipment amortization schedules.
EU AI Act risk classification frameworks are forcing manufacturers to restructure software development pipelines for computer-aided detection modules. The regulation's tiered conformity assessment requirements are compressing time-to-market for algorithmic diagnostic tools while elevating clinical validation standards. Visualization platform vendors serving Italian public hospitals are responding by segregating AI feature rollouts between Class IIa and Class III certification pathways to manage regulatory exposure.
Consolidated purchasing consortia in Piedmont and Liguria are unbundling after-sales service contracts from capital equipment leases. Hospital procurement officers now negotiate preventive maintenance and software upgrade terms through separate competitive tenders rather than accepting manufacturer-captive service bundles. This behavioral shift is most visible among medium-sized regional health authorities seeking to reduce total cost of ownership across multi-vendor endoscope fleets.
Italy Endoscopy Devices Market Segmentation
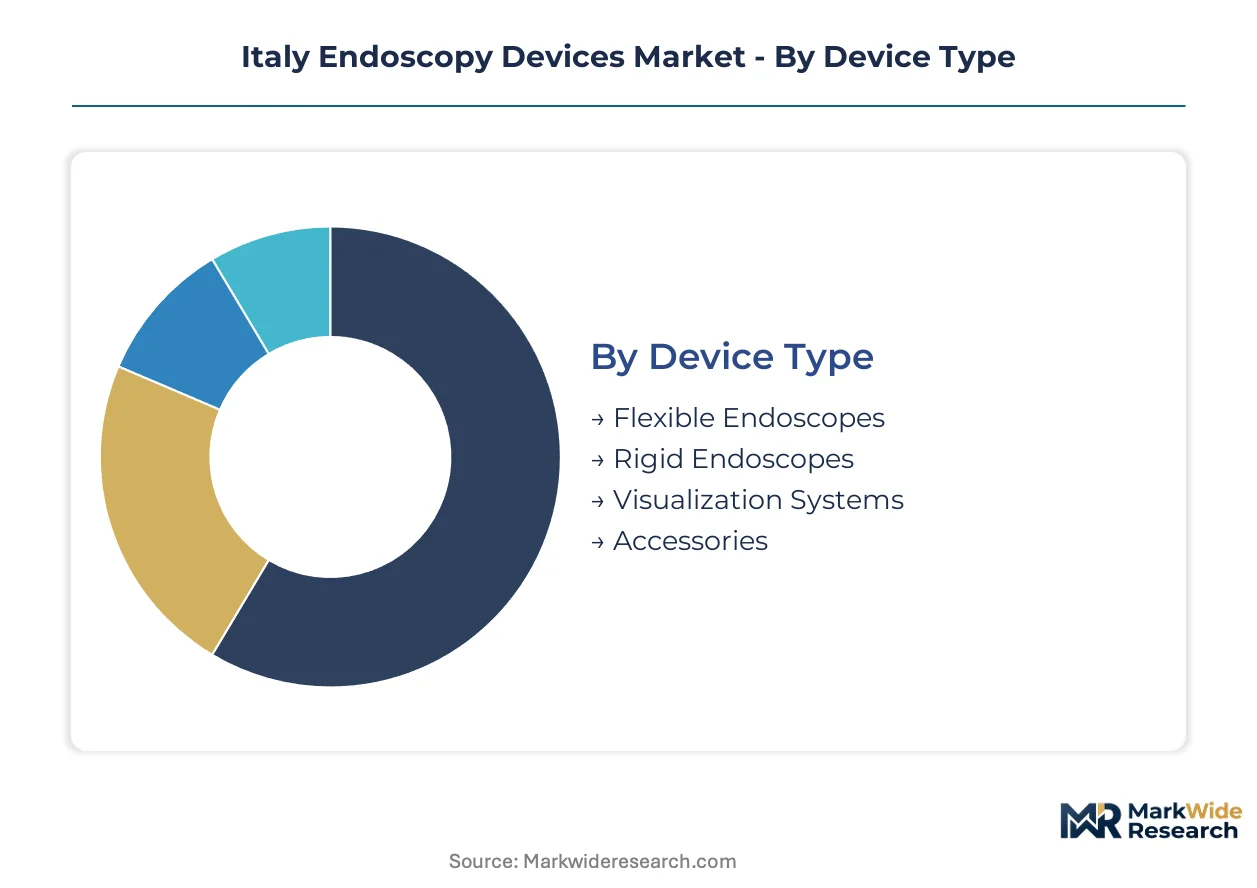
Endoscopy device procurement in Italy fragments across technical specifications, clinical application, and facility infrastructure requirements. Understanding these segmentation layers reveals where procurement budgets concentrate and which technology trajectories are reshaping competitive positioning.
Device Type:
Procurement committees prioritize total cost of ownership calculations spanning capital outlay, reprocessing labor, and service contract obligations.
- Flexible Endoscopes:Fiber-optic or video-chip instruments with steerable distal tips navigate tortuous anatomical pathways. Gastroenterology departments in Lombardy and Veneto drive procurement volumes for colonoscopy and EGD procedures where maneuverability dominates clinical utility.
- Visualization Systems:Integrated camera processors, light sources, and display monitors form proprietary technology stacks. Northern Italian hospital consortia favor these platforms for their lock-in effects on recurring software upgrades and predictive maintenance contracts.
- Rigid Endoscopes:Rod-lens optical systems deliver superior image resolution for laparoscopic and arthroscopic interventions.
- Accessories:Biopsy forceps, irrigation pumps, and electrosurgical attachments complete procedural kits.
Flexible endoscopes lead on scale; disposable variants within this category are gaining share fastest.
Product Category:
Clinical workflow differentiation separates screening protocols from interventional procedures, with infection control economics increasingly influencing category selection.
- Disposable Endoscopes:Single-use polymer constructs eliminate cross-contamination pathways and reprocessing labor. Tuscany and Emilia-Romagna gastroenterology units are adopting these for ERCP and high-risk bronchoscopy where sterilization failure liability concentrates.
- Therapeutic Endoscopes:Instruments with expanded working channels accommodate stent deployment, polypectomy snares, and hemostasis devices. Bariatric surgery centers in Milan and Turin generate concentrated demand for these capabilities.
- Diagnostic Endoscopes:Standard visualization instruments for screening and surveillance procedures.
- Surgical Endoscopes:Rigid systems optimized for minimally invasive operative suites.
Therapeutic endoscopes command premium pricing; disposable endoscopes are climbing the fastest.
End User:
Capital allocation authority varies by facility type, with consolidated purchasing power concentrating in networked hospital systems.
- Hospitals:Acute care facilities with centralized sterile processing departments and dedicated endoscopy suites. Regional health authorities in Piedmont and Liguria coordinate multi-hospital procurement tenders that extract volume discounts from incumbent manufacturers.
- Ambulatory Surgical Centers:Same-day procedure facilities with streamlined throughput requirements. These operators in northern industrial clusters favor disposable endoscopes to minimize capital equipment footprints and regulatory compliance overhead.
- Clinics:Outpatient diagnostic centers with limited procedural volume.
- Research Institutes:Academic medical centers driving early adoption of experimental visualization technologies.
Hospitals dominate procurement value; ambulatory surgical centers show steepest expansion trajectory.
Application:
Reimbursement schedules and screening program mandates shape demand intensity across clinical specialties.
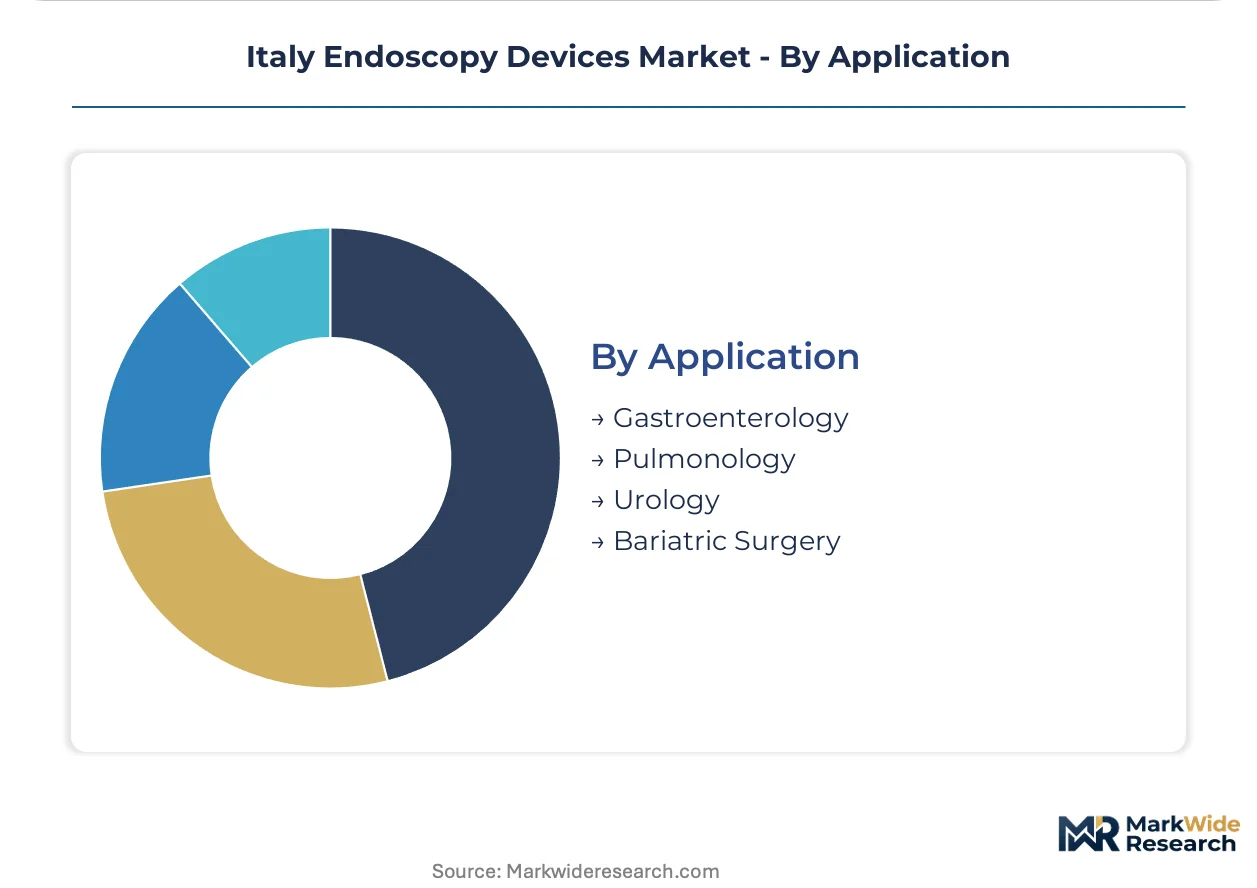
- Gastroenterology:Colorectal cancer screening programs and therapeutic interventions account for the dominant procedure volume. The national health service's organized screening initiatives in northern regions sustain predictable replacement cycles for colonoscopy platforms.
- Bariatric Surgery:Metabolic procedure expansion drives demand for specialized therapeutic endoscopes with suturing and stapling capabilities. Centers of excellence in Milan anchor this segment's technology requirements.
- Pulmonology:Bronchoscopy for lung cancer diagnosis and interventional procedures.
- Urology:Cystoscopy and ureteroscopy for diagnostic and stone management applications.
Gastroenterology leads on procedure volume; bariatric surgery shows strongest technology upgrade intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium positioning through engineering-intensive manufacturing clusters, whereas Italy differentiates via specialized service networks concentrated in northern industrial zones. France and Spain present contrasting procurement consolidation patterns that reshape competitive access across Mediterranean markets. Switzerland maintains distinct regulatory autonomy despite geographic proximity to EU harmonization frameworks.
Germany
Precision optics manufacturing in Tuttlingen and surgical instrument engineering in the Black Forest anchor rigid endoscope production capabilities. BfArM and CE marking convergence under EU MDR compress registration timelines for legacy device recertification. Bavarian hospital procurement consortia in Munich and Nuremberg enforce stringent technical service requirements that favor vendors with established German-speaking field engineering teams.
France
Organized colorectal cancer screening programs sustain predictable replacement cycles for colonoscopy platforms in Île-de-France and Auvergne-Rhône-Alpes. ANSM post-market surveillance requirements elevate clinical evidence standards for software-integrated visualization systems. Lyon-based biomedical engineering clusters support specialized repair infrastructure for flexible endoscope optics serving southeastern hospital networks.
Spain
Decentralized regional health authority procurement in Catalonia and Andalusia fragments purchasing power compared to northern European consolidation patterns. AEMPS medical device vigilance reporting mandates reshape distributor liability exposure for imported endoscopy equipment. Madrid and Barcelona anchor competing service networks that reduce equipment downtime for high-volume gastroenterology departments.
Switzerland
Swissmedic maintains independent device approval pathways that run parallel to EU MDR recognition procedures, extending market access timelines for non-EU manufacturers. Basel and Zurich concentrate private hospital procurement with premium pricing tolerance for next-generation visualization platforms. The country's bilateral agreements with Brussels preserve CE marking acceptance while preserving national regulatory discretion on software-as-a-medical-device classifications.
Italy Endoscopy Devices Market Competitive Landscape
German producers anchor one tier through precision engineering heritage in optical systems; Japanese specialists hold another via integrated visualization platform ecosystems. The vendor structure concentrates around three strategic archetypes: diversified medical technology conglomerates with therapeutic endoscope portfolios, pure-play endoscopy manufacturers with rigid scope specialization, and disposable device innovators disrupting reprocessing economics. Competitive moves center on M&A activity targeting AI-powered diagnostic software capabilities and backward integration into image sensor manufacturing.
Within the diversified technology tier, Medtronic PLC and Johnson & Johnson occupy positions exemplifying therapeutic endoscope breadth across bariatric and gastroenterology service lines. Among pure-play specialists, Karl Storz SE & Co. KG and Olympus Corporation represent contrasting engineering philosophies—German rigid scope precision against Japanese integrated platform ecosystems. Boston Scientific Corporation sits within the interventional therapeutics archetype, while Ambu anchors the disposable technology disruption vector challenging established reprocessing business models.
| Leading Market Players |
|---|
| Karl Storz SE & Co. KG |
| Johnson & Johnson |
| Boston Scientific Corporation |
| Cook Group Incorporated |
| CONMED Corporation |
| Medtronic PLC |
| Fujifilm Holdings Corporation |
| Ambu |
| Olympus Corporation |
| Others |
Supply & Pricing Matrix
Family-owned German optics specialists anchored in Tuttlingen maintain pricing discipline through captive manufacturing of rod-lens systems, while their reliance on Italian hospital procurement consortia ties pricing power to regional service infrastructure density. This ownership structure concentrates supply-side bargaining leverage in northern industrial clusters where technical response times determine contract renewal rates.
Pricing Analysis
Capacity additions in single-use polymer endoscope manufacturing are reshaping price floors for flexible scope categories, compressing margins on reusable instrument leasing models. Three-tier pricing structure across premium visualization platforms, standard diagnostic bundles, and economy disposable lines stratifies procurement committees by procedure volume. Cost compression in economy tiers is intensifying because Ambu and Chinese entrants flood gastroenterology departments with single-use alternatives. Ambulatory surgical centers in Milan and Turin exhibit highest price sensitivity; university hospital networks in Lombardy show lowest.
Supply Chain Analysis
Dual-sourcing qualification mandates from Piedmont and Liguria purchasing consortia force hospital networks to maintain approved vendor lists across at least two visualization platform ecosystems. Component supply draws from Germany for precision optics, Japan for CMOS image sensors, and China for polymer disposable constructs. Raw material dependencies center on optical glass, medical-grade polymers, and specialized illumination fibers. Single-source vulnerability concentrates in proprietary software modules that lock service contracts to original manufacturers. Distribution runs through manufacturer-direct field engineering teams for capital equipment, with third-party logistics handling disposable consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy endoscopy devices market reads as a late-cycle quality story where procurement committees prioritize total cost of ownership over capital outlay, reflecting demand-shift toward AI-integrated visualization platforms with predictive maintenance capabilities.
For Market Incumbents: To counter disposable endoscope entrants eroding reusable scope installed bases, deepen backward integration into image sensor manufacturing to protect margin pools on visualization platforms. Prioritize CE marking under EU MDR for legacy device recertification to maintain procurement eligibility across Lombardy and Veneto hospital consortia. For New Entrants and Emerging Players: The premium-economy price-point gap in therapeutic endoscopes creates whitespace for mid-tier bariatric surgery specialists in Campania and Sicily. Target underpenetrated central and southern regional health authorities with service-capable distribution partnerships. Lead with disposable bronchoscopy platforms where infection control liability drives rapid adoption. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play rigid endoscope repair specialists with concentrated biomedical engineering talent in northern Italy. Five-to-ten year viability hinges on AI-powered diagnostic software certification under EU AI Act provisions. The signal to watch is Swissmedic recognition timelines for algorithmic detection modules as leading indicator of platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Pathway | Notified body engagement secures continued procurement access across Lombardy hospital networks. |
| AI-Integrated Visualization Platform | Computer-aided detection modules command premium pricing in national colorectal screening programs. |
| Disposable Endoscope Manufacturing Scale-Up | Single-use polymer production capacity captures infection-control-driven demand from Tuscany gastroenterology units. |
| Regional Service Infrastructure Expansion | Technical response capabilities in Campania and Sicily unlock whitespace procurement from decentralizing health authorities. |
| Software-as-Medical-Device Certification | EU AI Act compliance positioning secures preferred vendor status for algorithmic diagnostic aids. |
Research Methodology
Multiple input streams — hospital procurement database analysis, GPO contract review, and EU MDR filing documentation — were reconciled against primary interviews with biomedical engineering directors, hospital purchasing committee members, and endoscopy service technicians. Secondary validation drew from Italian Ministry of Health procurement transparency filings, regional health authority tender records, and CE marking notification databases. Bottom-up procedure volume estimates and top-down equipment replacement cycle analysis were triangulated to anchor market sizing.
Data-stream reconciliation across the projection horizon applied segmentation dimensions spanning device type, product category, end-user facility tier, and clinical application. CAGRs were derived from equipment replacement cycle compression under EU MDR traceability mandates and disposable technology penetration curves. Forecast inputs incorporated northern industrial cluster service network density and central-southern regional expansion feasibility assessments.
Caveats apply where notified body capacity constraints or EU AI Act classification delays could materially shift the outlook. Deviation in MDR certification timelines or algorithmic diagnostic reimbursement decisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Gastrointestinal Endoscopy Devices Market
Endoscopy
France Endoscopy Devices Market
Endoscopy
Endoscopy Fluid Management Systems Market
Endoscopy
Endoscopy Video Systems Market
Endoscopy
Endoscopic Esophageal Varices Treatment Market
Endoscopy
Robot-Assisted Endoscope Market
Endoscopy
Global Endoscopy Ultrasound Market
Endoscopy
Global Colonoscopes Market
Endoscopy
North America Disposable Endoscopes Market
Endoscopy
Endobronchial Ultrasound Biopsy Market
Endoscopy
Global Bronchoscopes Market
Endoscopy
Endoscopic Submucosal Dissection Market
Endoscopy
Endoscopic Mucosal Resection Market
Endoscopy
Endoscopy Visualization Systems Market
Endoscopy
India Endoscopy Devices Market
Endoscopy
Single Use Bronchoscopes Market