
 Global Dental Obturators Market | 2026-2036
Global Dental Obturators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Obturators Market Foresight
Buyer concentration among dental clinics and oral surgery centers is shifting toward larger multi-specialty group practices that centralize procurement for complex maxillofacial procedures. Dentsply Sirona leverages its integrated digital dentistry platform to control distribution channels across North American and European prosthodontic networks. Kerr Corporation anchors its position through sustained R&D investment in medical-grade polyurethane formulations that meet evolving biocompatibility requirements. VDW Dental specializes in precision-manufactured screw-type obturators for cleft palate repair segments in German-speaking markets.
Dental obturators are removable prosthetic devices fabricated from silicone, acrylic resin, or thermoplastic elastomer that seal congenital or acquired palatal defects to restore speech, swallowing, and nasal partitioning functions. Manufacturing employs CAD/CAM milling or injection molding to achieve tissue-surface adaptation within 0.1 mm tolerances, with adjustable screw mechanisms enabling post-surgical fit refinement as healing progresses. Screw-type obturators dominate procedural volumes in post-tumor surgery applications where iterative modification preserves functional outcomes during radiation recovery. Flexible-type devices fabricated from medical-grade polyurethane represent the fastest-expanding material-application intersection, capturing margin pools among pediatric cleft palate specialists requiring frequent replacement as craniofacial structures develop.
FDA 510(k) premarket notification requirements govern obturator biocompatibility testing under ISO 10993 standards, while EU MDR technical documentation mandates clinical evidence for implantable prosthetic classifications that obturators increasingly approach. Japan's PMDA enforces JIS T 0313 material standards that restrict certain plasticizer additives in long-wear silicone devices. Stakeholders must monitor divergence between FDA and EU MDR testing protocols, as dual-certification costs will reshape competitive viability for mid-scale manufacturers serving both markets.
Market Dynamics
Dual-certification burdens under diverging FDA 510(k) and EU MDR protocols are compressing mid-scale manufacturer margins while channeling procurement toward vertically integrated suppliers with captive regulatory affairs capabilities.
Growth Catalysts
- Post-tumor reconstruction volume:Maxillofacial surgery centers in the United States are expanding dedicated prosthodontic units to manage rising head and neck oncology caseloads.
- EU MDR clinical evidence pathways:Implantable prosthetic classifications now require technical documentation that obturators increasingly trigger, elevating barrier credibility for certified incumbents.
- Thermoplastic elastomer advances:Medical-grade polyurethane formulations enable pediatric cleft palate devices that accommodate craniofacial growth without full remanufacture.
Market Restraints
- Silicone feedstock volatility:Medical-grade silicone precursor costs fluctuate with petrochemical supply disruptions, squeezing gross margins on long-wear devices.
- Japanese plasticizer restrictions:PMDA enforcement of JIS T 0313 standards blocks certain additive formulations, forcing reformulation cycles for multi-market suppliers.
- CAD/CAM equipment concentration:Precision milling system supply clusters in German and Swiss manufacturing corridors create geographic dependency for tolerances under 0.1 mm.
Strategic Opportunities
- Brazilian cleft palate backlog:ANVISA regulatory harmonization efforts with ISO 10993 standards are opening procurement pathways for certified exporters into underserved pediatric segments.
- Digital dentistry convergence:Intraoral scanning paired with cloud-based design platforms enables remote fit refinement for screw-type obturators in radiation recovery protocols.
- Indian prosthodontic training expansion:Central government dental college capacity additions are creating installed bases for mid-tier device demonstration and replacement cycles.
Industry Challenges
- Maxillofacial prosthodontist scarcity:Fellowship-trained specialists capable of complex post-surgical obturator fitting remain concentrated in tertiary academic centers.
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and sensitization studies extend product development cycles by 14-18 months for novel elastomer introductions.
- Legacy acrylic resin obsolescence:Dental laboratories face capital reconfiguration costs transitioning from conventional processing to injection-molded thermoplastic workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Obturators Market |
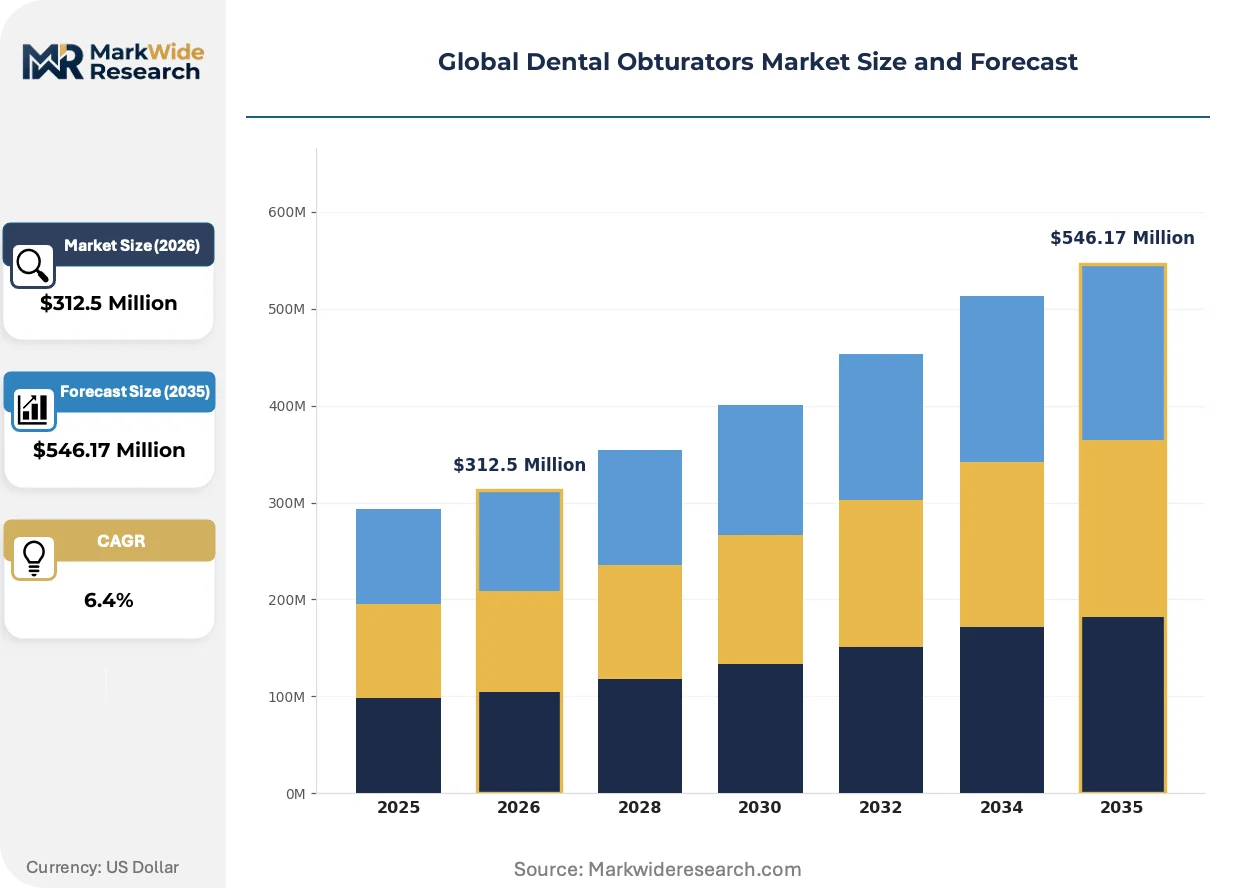
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Type, Plate Type, Flexible Type, Rigid Type, Adjustable Type Material: Silicone, Acrylic Resin, Thermoplastic Elastomer, Medical-Grade Polyurethane, Polypropylene Application: Maxillofacial Reconstruction, Cleft Palate Repair, Post-Tumor Surgery, Traumatic Injury, Congenital Defects End User: Dental Clinics, Oral Surgery Centers, Prosthodontists, Maxillofacial Specialists, Dental Laboratories |
| Companies Covered | Dentsply Sirona, Kerr Corporation, VDW Dental, META BIOMED, Pac-Dent Inc, DiaDent, Essential Dental Systems, FKG Dentaire, Ultradent Products Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Obturators Market Shifts & Advancements
CAD/CAM-enabled manufacturing is collapsing traditional fabrication timelines while regulatory divergence between major markets is fragmenting certification strategies. These forces are compressing competitive sets around technology-advantaged suppliers.
Medical-grade polyurethane injection molding is consolidating fabrication workflows for flexible-type obturators. Pediatric cleft palate specialists in German-speaking markets are adopting these devices at accelerating replacement cadences. This material transition is consolidating margin pools among suppliers with captive polymer formulation capabilities and freezing out conventional acrylic resin processors.
EU MDR technical documentation requirements for implantable prosthetic classifications are tightening clinical evidence thresholds. Obturator manufacturers must now compile post-market surveillance data previously exempt under the Medical Devices Directive. German and Austrian notified bodies are processing these submissions with 8-12 month backlogs, compressing launch timelines for mid-scale competitors.
Multi-specialty group practices are centralizing procurement decisions for complex maxillofacial procedures. Independent dental clinics are losing direct supplier relationships as purchasing migrates to consolidated procurement officers within larger health systems. This concentration is most visible across United States metropolitan markets where hospital-affiliated oral surgery centers now control majority volume.
Global Dental Obturators Market Segmentation
Dental obturator segmentation reveals how fabrication complexity and clinical workflow requirements fragment procurement across distinct technical specifications. Manufacturers must align material science capabilities with end-user specialization levels to capture margin pools effectively.
Product Type:
Screw-type obturators concentrate manufacturing investment among German and Swiss precision equipment corridors where 0.1 mm tolerance milling systems cluster.
- Screw Type:These devices incorporate adjustable mechanisms enabling post-surgical fit refinement as tissue healing progresses. Demand concentrates in United States maxillofacial surgery centers managing head and neck oncology caseloads where iterative modification preserves functional outcomes during radiation recovery.
- Flexible Type:Fabricated from medical-grade polyurethane or thermoplastic elastomer, these devices accommodate dynamic tissue movement and pediatric craniofacial growth. German-speaking markets show accelerating replacement cadences among cleft palate specialists requiring frequent device updates without full remanufacture.
- Plate Type:Fixed-configuration devices serve stable congenital defects with minimal post-fitting adjustment requirements.
- Rigid Type:Acrylic resin or polypropylene constructions dominate cost-sensitive dental laboratory workflows.
- Adjustable Type:Hybrid designs combine screw mechanisms with flexible borders for complex traumatic injury cases.
Today's leader: Screw Type. Tomorrow's challenger: Flexible Type.
Material:
Cost tier differentiation separates premium biocompatible formulations from commodity resin processing, with feedstock volatility reshaping margin structures across the value chain.
- Thermoplastic Elastomer:Medical-grade polyurethane formulations enable injection-molded fabrication workflows that collapse traditional laboratory timelines. Pediatric cleft palate applications in Austria and Germany drive fastest volume expansion as craniofacial growth necessitates frequent replacement cycles.
- Silicone:Long-wear devices for post-tumor reconstruction require medical-grade precursors subject to petrochemical supply disruptions. Japan's PMDA enforces JIS T 0313 standards restricting certain plasticizer additives, forcing reformulation cycles for multi-market suppliers.
- Acrylic Resin:Legacy processing faces capital reconfiguration costs transitioning to injection-molded workflows.
- Medical-Grade Polyurethane:Distinct from general thermoplastic elastomers, this grade meets ISO 10993 cytotoxicity thresholds for extended mucosal contact.
- Polypropylene:Cost-optimized option for provisional obturators in emerging market dental colleges.
Volume concentrates in silicone. Margin expansion favors thermoplastic elastomer.
Application:
Customer type stratification separates tertiary academic centers from community dental clinics based on procedural complexity and reimbursement pathways.
- Post-Tumor Surgery:Head and neck oncology reconstruction demands screw-type devices with iterative fit refinement capabilities. United States metropolitan markets show dedicated prosthodontic unit expansion as hospital-affiliated oral surgery centers consolidate procurement decisions.
- Cleft Palate Repair:Pediatric craniofacial development necessitates frequent device replacement, concentrating demand among specialized centers in Germany, Austria, and expanding Brazilian markets following ANVISA harmonization with ISO 10993.
- Maxillofacial Reconstruction:Trauma and congenital defect repair spans both rigid and flexible device categories.
- Traumatic Injury:Acute cases require rapid-turnaround provisional devices before definitive prosthodontic fitting.
- Congenital Defects:Stable palatal anomalies suit plate-type or rigid configurations with minimal adjustment needs.
Revenue pools center on post-tumor surgery. Volume expansion accelerates in cleft palate repair.
End User:
Geographic concentration of fellowship-trained specialists limits addressable market access, with procurement migrating toward consolidated multi-specialty group practices.
- Maxillofacial Specialists:Fellowship-trained prosthodontists capable of complex post-surgical fitting remain concentrated in United States tertiary academic centers and German university hospitals. Their procurement decisions increasingly flow through centralized purchasing officers within larger health systems.
- Dental Laboratories:Traditional fabrication workflows face equipment reconfiguration pressures as CAD/CAM milling and injection molding displace conventional acrylic processing. Swiss and German manufacturing corridors supply precision tolerance equipment.
- Dental Clinics:Independent practices lose direct supplier relationships as purchasing consolidates.
- Oral Surgery Centers:Hospital-affiliated entities now control majority volume in United States metropolitan markets.
- Prosthodontists:General specialists handle less complex congenital defect cases with standardized device configurations.
Access concentrates with maxillofacial specialists. Scale advantages shift toward dental laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates precision manufacturing for screw-type devices while the United States drives post-tumor reconstruction demand through hospital-affiliated oral surgery networks.
United States
Hospital-affiliated oral surgery centers in metropolitan markets are consolidating procurement decisions for complex maxillofacial procedures. FDA 510(k) premarket notification requirements under ISO 10993 standards govern biocompatibility testing for silicone and thermoplastic elastomer devices. Tertiary academic centers in Boston, New York, and Houston concentrate fellowship-trained prosthodontists capable of iterative post-surgical fitting.
Germany
Maxillofacial surgery units at university hospitals in Munich and Hamburg are expanding dedicated prosthodontic capacity for head and neck oncology reconstruction. EU MDR technical documentation requirements for implantable prosthetic classifications now mandate clinical evidence previously exempt under the Medical Devices Directive. Precision milling equipment manufacturers cluster in Stuttgart and Aachen, supplying 0.1 mm tolerance systems for screw-type obturator fabrication.
Japan
Aging demographics are expanding caseloads for post-tumor reconstruction among Tokyo and Osaka metropolitan medical centers. PMDA enforces JIS T 0313 material standards that restrict certain plasticizer additives in long-wear silicone devices, forcing reformulation cycles for multi-market suppliers. Nagoya-based dental laboratories are transitioning from conventional acrylic processing to CAD/CAM-enabled thermoplastic workflows.
Brazil
ANVISA regulatory harmonization efforts with ISO 10993 standards are opening procurement pathways for certified exporters into underserved pediatric cleft palate segments. São Paulo and Rio de Janeiro craniofacial centers are building capacity for complex congenital defect repair. Federal university dental colleges in Minas Gerais are expanding prosthodontic training programs that create installed bases for device demonstration.
India
Central government dental college capacity additions in Delhi-NCR and Maharashtra are creating installed bases for mid-tier device demonstration and replacement cycles. CDSCO medical device regulations are aligning with ISO standards for biocompatible material classifications. Ahmedabad and Mumbai dental laboratories face capital reconfiguration pressures transitioning from conventional acrylic processing to injection-molded thermoplastic workflows.
Global Dental Obturators Market Competitive Landscape
German and Swiss producers anchor the precision-fabrication tier; United States-based conglomerates hold integrated distribution networks. The vendor base stratifies across three tiers: multinational dental conglomerates with captive regulatory affairs capabilities, mid-scale European specialists with polymer formulation expertise, and regional laboratories serving cost-sensitive provisional device segments. Consolidation pressures favor players with dual FDA-EU MDR certification capacity and captive CAD/CAM equipment supply chains.
Within the multinational tier, Dentsply Sirona and Kerr Corporation exemplify integrated platform strategies that combine digital dentistry infrastructure with polymer science capabilities. VDW Dental occupies a specialist position among German-speaking market precision fabricators. These three anchors represent divergent competitive archetypes: conglomerate-scale regulatory leverage, materials-science R&D depth, and geographic-specialist manufacturing focus respectively.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Kerr Corporation |
| VDW Dental |
| META BIOMED |
| Pac-Dent Inc |
| DiaDent |
| Essential Dental Systems |
| FKG Dentaire |
| Ultradent Products Inc |
| Others |
Supply & Pricing Matrix
Medical-grade polyurethane injection molding is collapsing traditional laboratory fabrication timelines while simultaneously concentrating margin capture among suppliers with captive polymer formulation capabilities. This production-method transition feeds pricing power upstream toward German and Swiss precision equipment corridors, squeezing mid-scale acrylic resin processors that lack capital for CAD/CAM reconfiguration.
Pricing Analysis
Capacity additions in Indian dental colleges are reshaping price floors for provisional obturator tiers. Three-tier pricing structure across premium screw-type, standard flexible-type, and economy rigid-type levels separates certification-grade silicone devices from commodity polypropylene alternatives. Cost compression in pediatric cleft palate segments is intensifying because thermoplastic elastomer injection molding eliminates remanufacturing labor. Community dental clinics exhibit highest price sensitivity; hospital-affiliated oral surgery centers prioritize fit precision over unit cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Nagoya, and Minneapolis anchor hub-and-spoke patterns for precision-milled screw-type components. Manufacturing gravity draws from Germany, Switzerland, and Japan for 0.1 mm tolerance milling systems. Raw material flows hinge on medical-grade silicone precursors, thermoplastic elastomer pellets, and acrylic resin monomers. Single-source vulnerability concentrates in German precision equipment corridors. Distribution runs through dental laboratory networks and consolidated procurement officers at multi-specialty group practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on thermoplastic elastomer substitution eliminating remanufacturing costs for pediatric applications. Premium-tier shift toward screw-type devices with iterative fit capabilities supports pricing power at hospital-affiliated oral surgery centers.
For Market Incumbents: Lock in regulatory affairs capabilities spanning FDA 510(k) and EU MDR dual-certification pathways to defend against mid-scale competitors facing 8-12 month notified body backlogs. Deepen backward integration into medical-grade polyurethane formulation to capture margin pools from acrylic resin processors. Channel control through digital dentistry platform integration preserves distributor relationships as procurement consolidates.
For New Entrants and Emerging Players: Cloud-based design platforms paired with intraoral scanning partnerships offer a direct route to radiation recovery protocols where remote fit refinement commands premium positioning. Brazilian pediatric cleft palate segments present the most penetrable geography following ANVISA harmonization with ISO 10993. Target demonstration programs at expanding Indian dental colleges to establish replacement cycle relationships before competitors consolidate.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale European specialists with polymer formulation expertise but incomplete regulatory coverage. Long-term viability favors targets with captive CAD/CAM equipment supply chains and demonstrated EU MDR technical documentation capabilities. Watch notified body processing backlogs as the inflection signal for certification-constrained supply.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Clinical evidence thresholds now mandate post-market surveillance data previously exempt under MDD. |
| Medical-Grade Polyurethane Formulation Partnership | Captive polymer science capabilities consolidate margin pools from conventional acrylic processors. |
| Digital Dentistry Platform Integration | Intraoral scanning and cloud-based design workflows collapse traditional laboratory fabrication timelines. |
| Hospital System Procurement Consolidation | Multi-specialty group practices centralize purchasing decisions away from independent dental clinics. |
| Brazilian ANVISA Certification Pathway | ISO 10993 harmonization opens procurement channels into underserved pediatric cleft palate segments. |
Research Methodology
Bottom-up prosthodontic procedure modeling reconciled against top-down dental laboratory capacity tracking forms the analytical core. Primary interviews with maxillofacial prosthodontists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR notified body databases, PMDA submission records, and hospital procurement databases. Triangulation across stakeholder inputs and regulatory documentation ensures segmentation integrity.
Input-output matrices map screw-type, flexible-type, plate-type, rigid-type, and adjustable-type device flows against material-grade tiers and end-user specialization levels across the projection horizon. CAGRs derive from procedure volume trajectories, replacement cycle frequencies, and material substitution elasticities. Forecast inputs include maxillofacial specialist fellowship pipeline data, CAD/CAM equipment installation rates, and biocompatibility testing timeline extensions.
The model assumes a particular technology adoption path; alternative pathways for injection-molded thermoplastic elastomer workflows would alter the outlook. Forecasts reflect documented assumptions including regulatory harmonization timelines and specialist concentration patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
North America Dental Implants and Prosthetics Market
Dental Devices
US Dental Splint Market
Dental Devices
Subperiosteal Dental Implants Market
Dental Devices
North America Dental Lab Market
Dental Devices
Chile Dental Market
Dental Devices
Dental Air Abrasion Market
Dental Devices
Orthodontics Market
Dental Devices
Digital Dental Cameras Market
Dental Devices
Dental Hand Tools Market
Dental Devices
Titanium Dental Implants Market
Dental Devices
Dental Forceps Market
Dental Devices
Nano Dentistry Market
Dental Devices
Dental Composite Filling Market
Dental Devices
US Orthodontics Market
Dental Devices
Dental Regeneration Market
Dental Devices
Global Dental Crowns and Bridges Market