
 Global Dental Crowns and Bridges Market | 2026-2036
Global Dental Crowns and Bridges Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Crowns and Bridges Market Foresight
The prosthodontist end-user segment is broadening its share of fixed restoration procedures as patients prioritize durability and aesthetics over removable dentures. Straumann Group leverages its integrated implant-to-restoration workflow to control laboratory and chairside channels across premium markets. Ivoclar Vivadent AG specializes in lithium disilicate glass-ceramic systems and dominates digital material science for chairside milling applications. Henry Schein sustains distribution density across North American dental clinics through its broad consumables and equipment portfolio.
Dental crowns and bridges are fixed prosthetic devices cemented onto prepared natural teeth or implant abutments to restore morphology, occlusion, and phonation; zirconia frameworks now achieve flexural strength exceeding 900 MPa through hot isostatic pressing, displacing porcelain-fused-to-metal in posterior indications. The zirconia product type segment leads absolute volume due to its biocompatibility and aesthetic translucency, while ceramic segments capture margin pools in anterior aesthetic cases where light transmission mimics natural dentin. Dental laboratories represent the fastest-growing end-user channel as outsourcing of CAD/CAM fabrication accelerates among general practitioner clinics lacking in-house milling capacity.
The FDA regulates dental prosthetic materials under 21 CFR 872, requiring biocompatibility testing and quality system compliance for market entry, while the EU Medical Device Regulation (MDR) reclassifies custom-made dental devices and intensifies clinical evidence requirements for notified body certification. Japan's PMDA enforces Japan Industrial Standards (JIS) for dental metal alloys, shaping alloy composition and corrosion resistance specifications for manufacturers targeting Japanese prosthodontists. Stakeholders must monitor evolving MDR technical documentation requirements and digital workflow validation standards as regulatory scrutiny of patient-matched manufacturing intensifies.
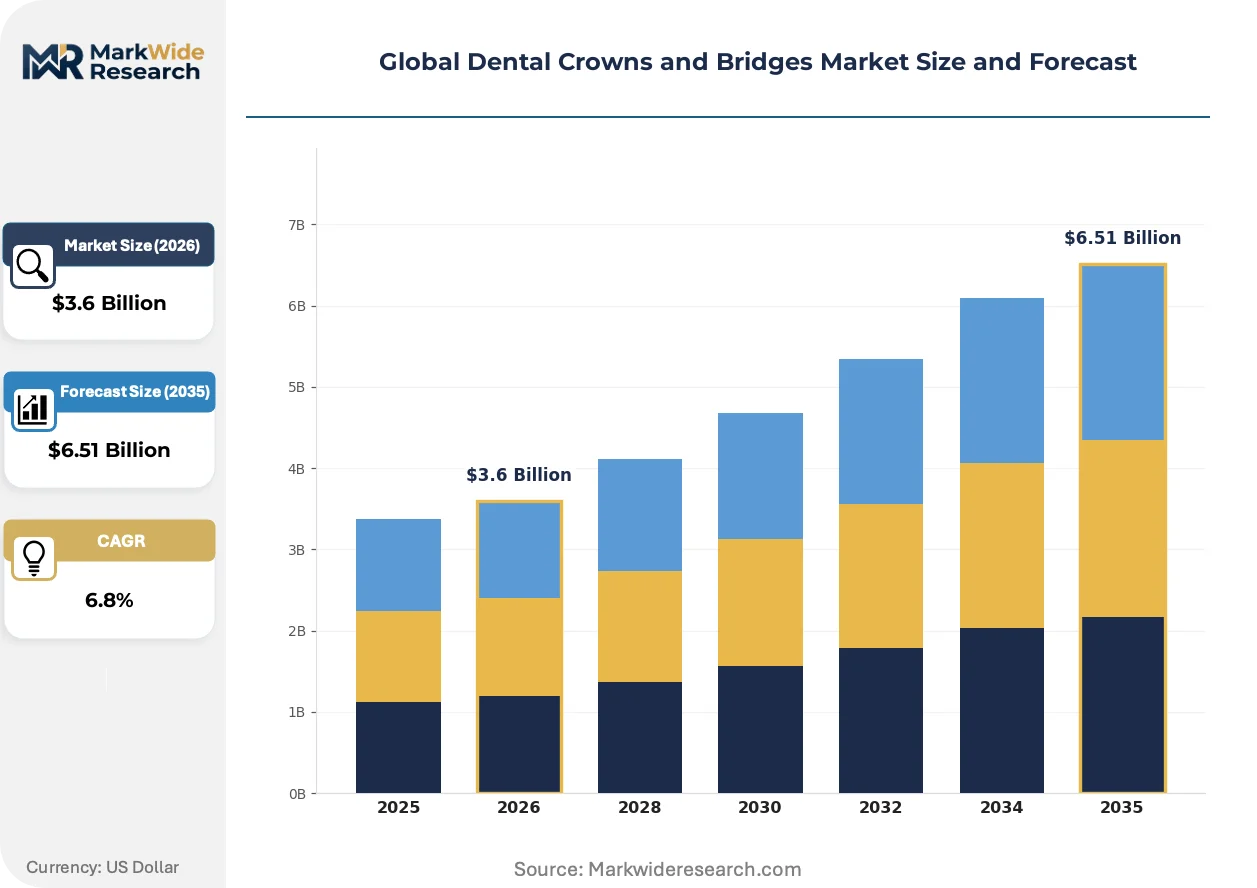
Market Dynamics
CAD/CAM milling and 3D printing of zirconia substructures are compressing fabrication timelines from weeks to days, forcing dental laboratories to retool or exit as chairside workflows bypass traditional outsourcing channels.
Growth Catalysts
- EU MDR reclassification:The intensified clinical evidence requirements for custom-made dental devices under the EU Medical Device Regulation are consolidating notified body relationships and favoring manufacturers with robust quality systems, accelerating market share concentration among compliant producers.
- Japan's aging demographic:Japan's PMDA enforcement of JIS standards for dental metal alloys coincides with expanding prosthodontist capacity in Tokyo and Osaka, where favorable reimbursement sustains volume growth for fixed restorations over removable alternatives.
- Zirconia hot isostatic pressing:This manufacturing process achieves flexural strength exceeding 900 MPa, enabling monolithic zirconia crowns to displace porcelain-fused-to-metal in posterior indications where mechanical load tolerance is critical.
Market Restraints
- Yttria-stabilized zirconia powder concentration:Sourcing of high-purity ceramic powders concentrates among limited specialty chemical suppliers, exposing dental manufacturers to input cost volatility and supply disruption risk.
- FDA 21 CFR 872 compliance burden:Biocompatibility testing requirements and quality system validation for dental prosthetic materials extend product development timelines and elevate regulatory capital requirements for market entrants.
- Chairside milling substitution:General practitioner clinics investing in in-house CAD/CAM units reduce case flow to commercial dental laboratories, compressing outsourcing volumes for traditional crown and bridge fabrication.
Strategic Opportunities
- German digital workflow adoption:Dental laboratories in Berlin and Munich are integrating AI-driven design automation with five-axis milling centers, creating service tiers that capture mid-market clinics seeking faster turnaround without chairside capital investment.
- US implant-to-restoration convergence:Prosthodontist practices are bundling surgical implant placement with definitive restoration workflows, capturing margin pools previously fragmented between oral surgeons and independent laboratories.
- Lithium disilicate anterior aesthetics:Glass-ceramic systems optimized for chairside milling applications address the premium segment where light transmission properties mimic natural dentin, opening differentiation beyond mechanical performance.
Industry Challenges
- CAD/CAM technician scarcity:Dental laboratories face recruitment friction for operators proficient in digital design software and five-axis milling machine programming, constraining capacity expansion despite equipment availability.
- Legacy PFM inventory stranding:Laboratories maintaining porcelain-fused-to-metal production lines confront asset obsolescence as zirconia monolithics capture posterior volume, forcing write-downs or stranded capacity decisions.
- MDR technical documentation validation:Manufacturers must rebuild clinical evidence packages for legacy products to maintain EU market access, diverting R&D resources from next-generation material development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Crowns and Bridges Market |
| Market Size in 2026 | $3.6 Billion |
| Market Size in 2035 | $6.51 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Porcelain Fused to Metal, Ceramic, Zirconia, Gold Alloy, Resin Material Composition: Composite Resin, Lithium Disilicate, Alumina, Metal Alloys, Glass Ceramics Application: Tooth Restoration, Aesthetic Enhancement, Bite Function Improvement, Structural Support End User: Dental Clinics, Orthodontists, Prosthodontists, Dental Laboratories |
| Companies Covered | Dentsply Sirona, Nobel Biocare Services AG, Straumann Group, Zimmer Biomet, Ivoclar Vivadent AG, 3M, Dentium Co., Henry Schein, BioHorizons, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Crowns and Bridges Market Shifts & Advancements
Digital manufacturing workflows are restructuring competitive boundaries between chairside, laboratory, and industrial production channels, with material science advances enabling new performance tiers that redefine restoration longevity standards.
Multi-layer zirconia with gradient translucency is electrifying aesthetic outcomes in anterior crown applications. Prosthodontists in aesthetic-focused practices are adopting these materials at accelerating rates for veneer and single-unit anterior cases. This technology is electrifying the premium segment by collapsing the historical trade-off between mechanical strength and optical properties that previously forced material compromises.
The EU Medical Device Regulation's enhanced scrutiny of patient-matched manufacturing is reshaping documentation burdens for dental device producers. Notified bodies now demand clinical performance data for CAD/CAM-produced restorations that previously entered markets through predicate equivalence. German and Swiss manufacturers with established quality management systems are capturing disproportionate certification capacity as smaller competitors withdraw from EU registration.
Dental laboratories are unbundling design services from physical production, selling digital files directly to clinics with chairside milling capacity. This channel innovation disrupts the traditional laboratory-clinic relationship in the United States, where general practitioners seek margin retention through in-house fabrication. The model concentrates most visibly in California and Texas, where dental service organizations aggregate sufficient volume to justify dedicated design subscriptions.
Global Dental Crowns and Bridges Market Segmentation
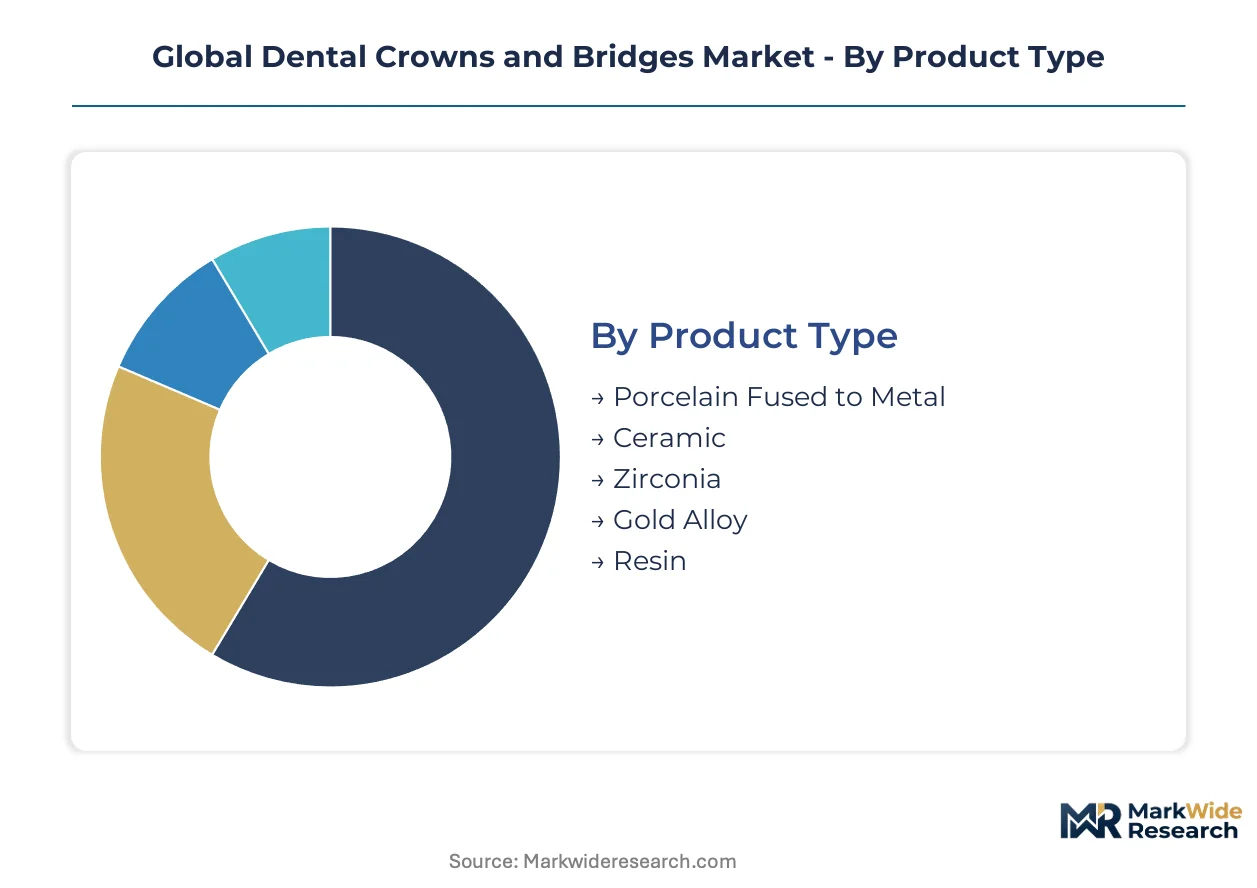
Segmentation in dental crowns and bridges determines regulatory pathway complexity, reimbursement eligibility, and manufacturing process selection. Material composition and end-user channel dictate whether products clear FDA 21 CFR 872, EU MDR, or Japan's PMDA frameworks.
Product Type:
FDA 21 CFR 872 governs biocompatibility testing for all product types, though zirconia and ceramic segments face intensified EU MDR scrutiny for custom-device classification.
- Zirconia:Monolithic frameworks achieve flexural strength exceeding 900 MPa through hot isostatic pressing. Demand concentrates among prosthodontists in Germany and Japan where posterior load-bearing applications require mechanical performance that displaces porcelain-fused-to-metal alternatives.
- Ceramic:Lithium disilicate glass-ceramics optimize light transmission for anterior aesthetic cases. Prosthodontist practices in the United States prioritize these materials where patient self-pay for veneer and crown aesthetics sustains premium pricing.
- Porcelain Fused to Metal:Legacy PFM restorations retain reimbursement footholds in price-sensitive dental clinics.
- Gold Alloy:High-noble alloys maintain niche demand among Japanese prosthodontists under JIS corrosion resistance standards.
- Resin:Temporary and provisional applications dominate this cost-tier segment.
Leading the category by volume: Zirconia. Growing fastest: Ceramic.
Material Composition:
Cost tiers separate premium lithium disilicate and glass ceramics from economy composite resin and base metal alloys.
- Lithium Disilicate:Chairside milling compatibility drives adoption in US dental clinics investing in CAD/CAM capital equipment.
- Glass Ceramics:Gradient translucency technologies enable monolithic anterior restorations that rival layered porcelain aesthetics.
- Composite Resin:Temporary crown fabrication dominates volume in general practitioner settings.
- Alumina:High-strength oxide ceramics serve implant abutment applications.
- Metal Alloys:Cobalt-chrome and nickel-chrome substrates face biocompatibility documentation burdens under EU MDR.
Volume concentration: Lithium Disilicate. Steepest expansion trajectory: Glass Ceramics.
Application:
Patient-matched manufacturing intensity varies by application, with aesthetic enhancement requiring the most complex CAD/CAM validation documentation.
- Tooth Restoration:Functional rehabilitation of caries-damaged dentition represents the core volume driver across US, German, and Japanese reimbursement systems.
- Aesthetic Enhancement:Veneer and anterior crown demand clusters in private-pay prosthodontist practices where patient willingness-to-pay exceeds standard restoration tariffs.
- Bite Function Improvement:Occlusal reconstruction cases require specialized laboratory articulator workflow.
- Structural Support:Post-and-core applications bridge endodontic and prosthodontic service lines.
Dominant by procedure volume: Tooth Restoration. Gaining share fastest: Aesthetic Enhancement.
End User:
Channel selection determines whether restorations flow through centralized dental laboratories or bypass toward chairside production.
- Dental Laboratories:CAD/CAM outsourcing accelerates among US general practitioners lacking five-axis milling capacity or AI-driven design automation expertise.
- Prosthodontists:Bundled implant-to-restoration workflows capture surgical and definitive restoration margins previously fragmented between oral surgeons and independent laboratories.
- Dental Clinics:In-house milling investment compresses case flow to external laboratories.
- Orthodontists:Limited restoration volume concentrates on temporary anchorage device applications.
Channel commanding highest value per unit: Prosthodontists. Expanding most quickly: Dental Laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Dongguan concentrate zirconia powder processing and CAD/CAM equipment assembly, attracting dental technology manufacturers through tax incentives and streamlined customs procedures for ceramic raw material imports.
United States
Prosthodontist practices in California and Texas drive fixed restoration volume as dental service organizations aggregate patient flow for bundled implant-to-restoration workflows. FDA 21 CFR 872 biocompatibility testing requirements shape market entry timelines for imported zirconia frameworks. Los Angeles and Houston laboratories specialize in AI-driven design automation for mid-market clinics lacking in-house milling capacity.
Germany
Berlin and Munich dental laboratories integrate five-axis milling centers with gradient translucency zirconia processing to capture premium anterior aesthetic cases. EU MDR reclassification of custom-made devices intensifies notified body certification requirements, favoring manufacturers with established quality management systems. The Bavarian industrial corridor concentrates hot isostatic pressing equipment fabrication for monolithic crown production.
Japan
Tokyo and Osaka prosthodontists sustain volume growth for fixed restorations through favorable reimbursement tariffs that displace removable alternatives. PMDA enforcement of JIS standards for dental metal alloys shapes corrosion resistance specifications for high-noble alloy frameworks. The Kanto region hosts specialized ceramic powder distributors serving domestic zirconia manufacturers.
Switzerland
Swissmedic certification requirements for patient-matched manufacturing concentrate digital workflow validation expertise in the Zurich-Basel corridor. Precision milling technology developers cluster near Swiss Federal Institute of Technology research partnerships. Lucerne and Geneva laboratories export CAD/CAM design services to EU clinics seeking MDR-compliant technical documentation support.
China
Yangtze River Delta manufacturing zones supply yttria-stabilized zirconia powder to global dental ceramic producers. NMPA medical device registration requirements for imported prosthetic materials extend approval timelines for foreign manufacturers. Shenzhen special economic zone assembles chairside milling units for export to North American and European dental clinics.
Global Dental Crowns and Bridges Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated implant-to-restoration workflows commanding premium positioning while independent laboratories compete on turnaround speed and design automation. The market structure tiers into three archetypes: multinational conglomerates with end-to-end dental portfolios, specialized ceramic and implant-focused firms, and regional laboratory service networks. Dominant competitive moves include strategic partnerships between equipment manufacturers and material suppliers, plus backward integration into zirconia powder sourcing to secure input cost stability.
Among Swiss and Liechtenstein-based specialists, Straumann Group and Ivoclar Vivadent AG exemplify the premium-tier archetype through captive control over laboratory and chairside channels. Henry Schein represents the North American distribution-heavy model, sustaining clinic density through consumables bundling rather than manufacturing ownership. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning without converging on identical capability stacks.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Nobel Biocare Services AG |
| Straumann Group |
| Zimmer Biomet |
| Ivoclar Vivadent AG |
| 3M |
| Dentium Co. |
| Henry Schein |
| BioHorizons |
| Others |
Supply & Pricing Matrix
Dental service organizations in California and Texas concentrate procurement volume for fixed restorations, anchoring a pricing model where fabrication lead times determine premium tiers and spot inventory availability commands discount positioning. This buyer concentration compresses margin pools for independent laboratories while rewarding integrated implant-to-restoration workflows with pricing power over fragmented competitors.
Pricing Analysis
Lead time compression drives premium pricing for same-day chairside restorations against standard laboratory turnaround schedules. Three-tier pricing structure across premium, standard, and economy levels separates lithium disilicate anterior aesthetics from monolithic zirconia posterior units and base metal alloy alternatives. Price differentiation hinges on certification grade under FDA 21 CFR 872 and EU MDR compliance status, with notified body validation commanding substantial markups. Pricing pressure stems from general practitioner clinics investing in in-house CAD/CAM capacity, eroding outsourcing volumes. Price sensitivity concentrates among mid-market dental clinics lacking capital for five-axis milling equipment, while prosthodontist practices demonstrate lower elasticity due to bundled procedure margins.
Supply Chain Analysis
Freight costs for yttria-stabilized zirconia powder shipments from Chinese processing centers to German milling facilities represent a material cost component amplified by ceramic raw material density. Supply concentrates in China for powder synthesis, Germany for hot isostatic pressing equipment fabrication, and Switzerland for precision milling technology development. Raw material dependencies center on high-purity zirconium oxide, specialized lithium disilicate ingots, and cobalt-chrome alloy substrates. Single-source vulnerability concentrates among limited specialty chemical suppliers for ceramic powder grades meeting dental biocompatibility standards. Distribution runs through dental laboratories serving as intermediaries between manufacturers and clinical end users, though direct digital file transfers are compressing this channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental crowns and bridges market operates as a vertical-integration race where control over zirconia powder sourcing and chairside milling technology deployment determines margin retention. Players are pursuing upstream captive supply of yttria-stabilized ceramic inputs to insulate against input cost volatility and supply disruption.
For Market Incumbents: Lock in notified body relationships under intensified EU MDR documentation requirements before certification capacity saturates. Consolidate design automation capabilities through AI-driven software acquisition to defend against dental laboratories unbundling digital services from physical production. Straumann Group's integrated implant-to-restoration workflow demonstrates how channel control across surgical and definitive restoration stages captures margin pools previously fragmented between oral surgeons and independent laboratories. For New Entrants and Emerging Players: Dental laboratories in mid-tier US metropolitan markets lacking five-axis milling capacity present the most penetrable white-space target. Focus on AI-driven design subscription services that sell digital files directly to general practitioner clinics with chairside milling investment, bypassing capital-intensive physical production infrastructure. Partner with dental service organizations in Texas and California aggregating sufficient volume to justify dedicated design relationships rather than competing for fragmented individual clinic accounts. For Investors and Strategic Acquirers: The window for entry favors specialized ceramic powder processors with established purity grades and dental biocompatibility documentation. Long-term viability hinges on positioning upstream of manufacturing consolidation as laboratories retool or exit under chairside substitution pressure. Monitor FDA 510(k) clearance velocity for monolithic zirconia anterior applications as the inflection signal indicating whether gradient translucency technologies have achieved regulatory validation sufficient to displace layered porcelain aesthetics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zirconia Powder Sourcing | Captive supply of yttria-stabilized ceramic inputs insulates German and Swiss manufacturers from specialty chemical supplier concentration risk. |
| AI-Driven Design Automation Deployment | Berlin and Munich laboratories leverage machine learning to compress design timelines for mid-market clinics lacking in-house expertise. |
| EU MDR Technical Documentation Rebuild | Clinical evidence packages for legacy CAD/CAM-produced restorations secure notified body certification capacity before competitor withdrawal. |
| Implant-to-Restoration Workflow Bundling | Prosthodontist practices in California capture surgical and definitive restoration margins previously fragmented across provider types. |
| Digital File Subscription Model Launch | Laboratories unbundle design from production to serve Texas and California dental service organizations with chairside milling capacity. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews across prosthodontists, dental laboratory technicians, CAD/CAM equipment procurement officers, and biomedical materials scientists. FDA 21 CFR 872 submissions, EU MDR notified body certification databases, and Japan PMDA device registration records provided regulatory pathway intelligence. Bottom-up triangulation against top-down macroeconomic indicators validated volume and value estimates across the projection horizon.
Granularity-level modeling disaggregated the market by material composition, end-user channel, and application intensity across the analysis window. Segmentation dimensions included zirconia monolithic versus layered ceramic frameworks, dental laboratory versus chairside production workflows, and posterior functional versus anterior aesthetic indications. CAGRs derived from regression analysis against aging demographic projections and prosthodontist capacity expansion in target markets. Forecast inputs incorporated reimbursement tariff trajectories in Japan, dental service organization consolidation velocity in the United States, and EU MDR implementation friction for custom-made device classification.
Several conditions sit outside the modeled scope, including unforeseen ceramic powder supply disruptions, abrupt reimbursement tariff reductions in concentrated markets, and technological leapfrogging that displaces current CAD/CAM architectures. Forecasts reflect assumptions about regulatory stability and material science advancement trajectories that stakeholder operating contexts may diverge from. Stakeholders should weight assumptions against their own procurement relationships and capital deployment timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
India Dental Devices Market
Dental Devices
Root Canal Market
Dental Devices
Global Dental Restorative Market
Dental Devices
Toothbrush Sterilizer Market
Dental Devices
Dental Implants and Abutment Systems Market
Dental Devices
Dental Devices and Consumables Market
Dental Devices
Global Dental Obturators Market
Dental Devices
Plaque Disclosing Aids Market
Dental Devices
Global Dental Lasers Market
Dental Devices
Global Restorative Dentistry Market
Dental Devices
Asia Pacific Dental Market
Dental Devices
Dental Erbium Lasers Market
Dental Devices
Global Digital Dentistry Market
Dental Devices
US Orthodontics Market
Dental Devices
Dental Apex Locator Market
Dental Devices
South Africa Dental Devices Market