
 Schrenz Paper Market | 2026-2036
Schrenz Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Schrenz Paper Market Analytics
A capital-intensity divergence between integrated pulp-to-paper operators and merchant converters is redrawing competitive boundaries in the Schrenz Paper landscape. Meyer Verpackungen leverages captive forestry holdings in Bavaria to secure fiber cost predictability across multi-year supply cycles. Fabrika Hartije Beograd anchors its position through dedicated machine lines serving Balkan packaging clusters with custom grammage specifications.
Schrenz Paper denotes a multi-ply kraft-based board stock engineered from unbleached softwood fibers, typically manufactured in grammages ranging from 80 to 350 gsm through cylinder machine or Fourdrinier wet-laid processes for protective interleaving, wrapping, and void-fill applications. Uncoated Paper and Recycled Paper segments dominate volume throughput, with Recycled Paper capturing expanding share as EU circular-economy compliance hardens virgin fiber substitution requirements. Specialty Paper commands premium positioning among precision-engineering exporters requiring controlled moisture vapor transmission rates for corrosion-sensitive cargo.
Germany's KBA enforces transport packaging safety standards that directly specify Schrenz Paper burst strength minimums for automotive component shipments, while REACH chemical restrictions constrain sizing agent formulations across EU-sourced production. The EU Green Deal's packaging waste reduction targets are accelerating mill investment in closed-loop fiber recovery systems. Stakeholders must monitor how impending EU Deforestation Regulation traceability requirements reshape pulp sourcing economics for non-integrated producers.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing virgin fiber tolerance thresholds, forcing mills to reconfigure recovery lines around higher-yield mechanical pulping while automotive logistics networks in Central Europe scale protective paper procurement.
Growth Catalysts
- REACH chemical compliance:ECHA restrictions on conventional sizing agents are accelerating migration to bio-based alternatives, opening specification windows for mills with certified green chemistry portfolios.
- Automotive parts distribution:Poland and Czech Republic logistics hubs require moisture-resistant kraft interlayers for corrosion-sensitive component shipments, concentrating demand in these corridors.
- Cylinder machine technology:Multi-ply wet-laid forming is enabling grammage precision down to 5-gsm tolerance bands, satisfying precision-engineering exporters with tight burst-strength specifications.
Market Restraints
- Softwood fiber cost volatility:Unbleached kraft pulp prices fluctuate with Nordic timber harvest cycles and energy input costs, squeezing margin predictability for non-integrated converters.
- Supply concentration in Bavaria:Captive forestry holdings controlled by integrated operators limit merchant access to cost-stable fiber, fragmenting procurement leverage among smaller mills.
- Plastic film substitution threat:Stretch-wrapped polyethylene retains cost advantage for non-corrosion-sensitive void-fill applications, capping Schrenz Paper penetration in commodity logistics segments.
Strategic Opportunities
- Balkan packaging clusters:Serbia and Romania show underpenetrated demand for custom-grammage protective papers serving emerging automotive supplier parks near Belgrade and Timișoara.
- EU Deforestation Regulation traceability:Early compliance with EUDR chain-of-custody documentation positions non-integrated producers for premium sourcing contracts with sustainability-audited buyers.
- Digital printing convergence:Inkjet-compatible surface sizing is supplanting traditional uncoated stocks in branded protective wrapping, enabling logo-printed interlayers for high-value electronics exports.
Industry Challenges
- Closed-loop fiber recovery capex:Mill investment in de-inking and repulping infrastructure runs into eight-figure euro commitments, straining balance sheets of mid-cap operators.
- Moisture vapor transmission certification:Automotive OEMs require ISO 2528-compliant testing documentation with 90-day validation cycles, extending sales-to-shipment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Schrenz Paper Market |
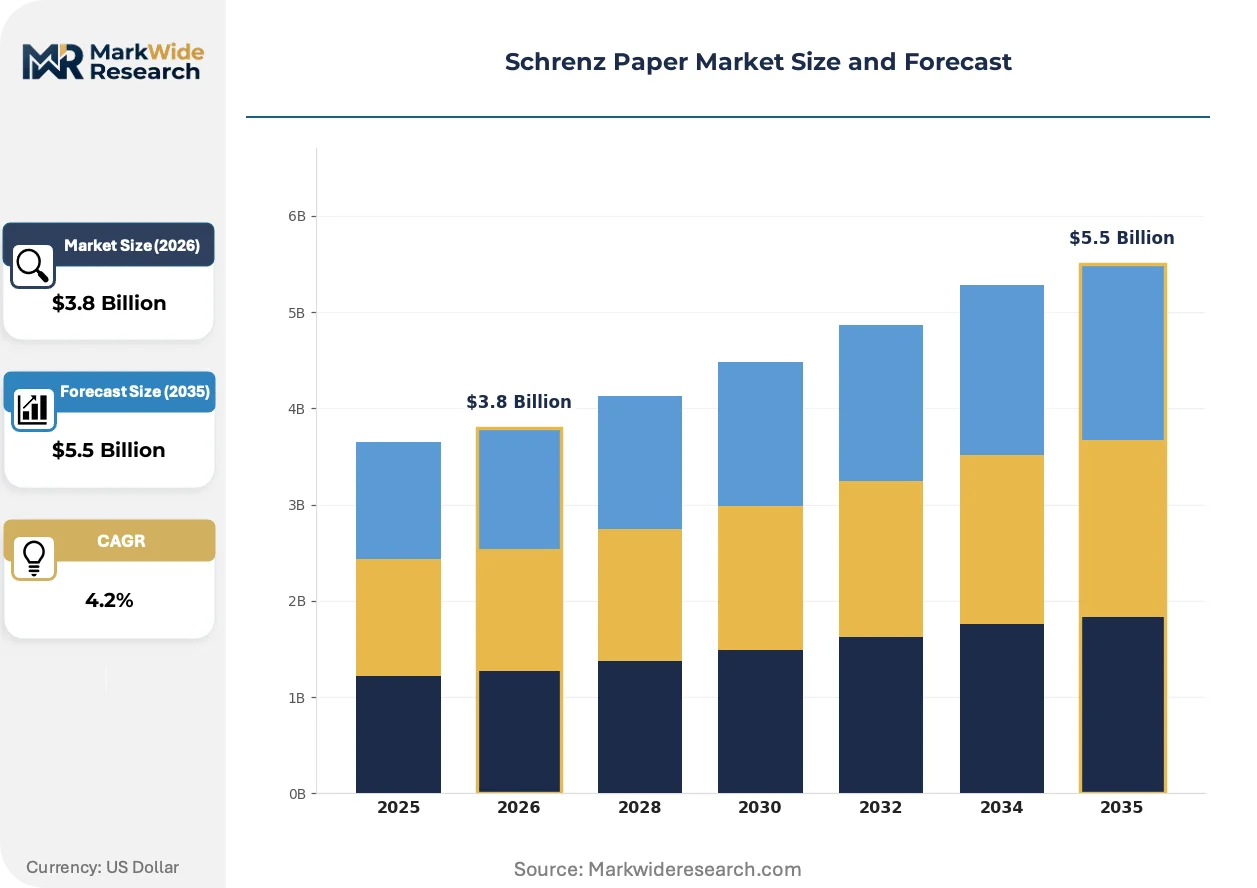
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Paper, Uncoated Paper, Specialty Paper, Recycled Paper Application: Printing, Packaging, Stationery, Publication End User: Publishers, Advertisers, Manufacturers, Retailers Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Meyer Verpackungen, Aubry Papier, Rossmann, Fabrika Hartije Beograd, Vrancart, EcoPaper, Stepa s.r.o., APV Germany GmbH, J Hoogstraten, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Schrenz Paper Market Evolving Landscape
Active transformation in this market centers on fiber recovery efficiency, regulatory chemistry substitution, and precision-forming automation reshaping mill output specifications.
Twin-wire forming technology is supplanting traditional cylinder machine production for grammages below 150 gsm, enabling automotive packaging engineers in Stuttgart and Munich to specify tighter caliper tolerance bands for robotic handling compatibility.
EU Green Deal packaging waste reduction targets are mandating 70% recycled content minimums by 2030, compelling Polish and Czech mills to retrofit recovery lines with advanced screening systems that preserve long-fiber strength through multiple reuse cycles.
Consolidated procurement through packaging converter cooperatives is displacing spot-market purchasing among mid-sized automotive tier suppliers, with Silesian and Moravian logistics clusters negotiating multi-year volume commitments that lock in grammmage specifications and delivery cadences.
Schrenz Paper Market Segmentation
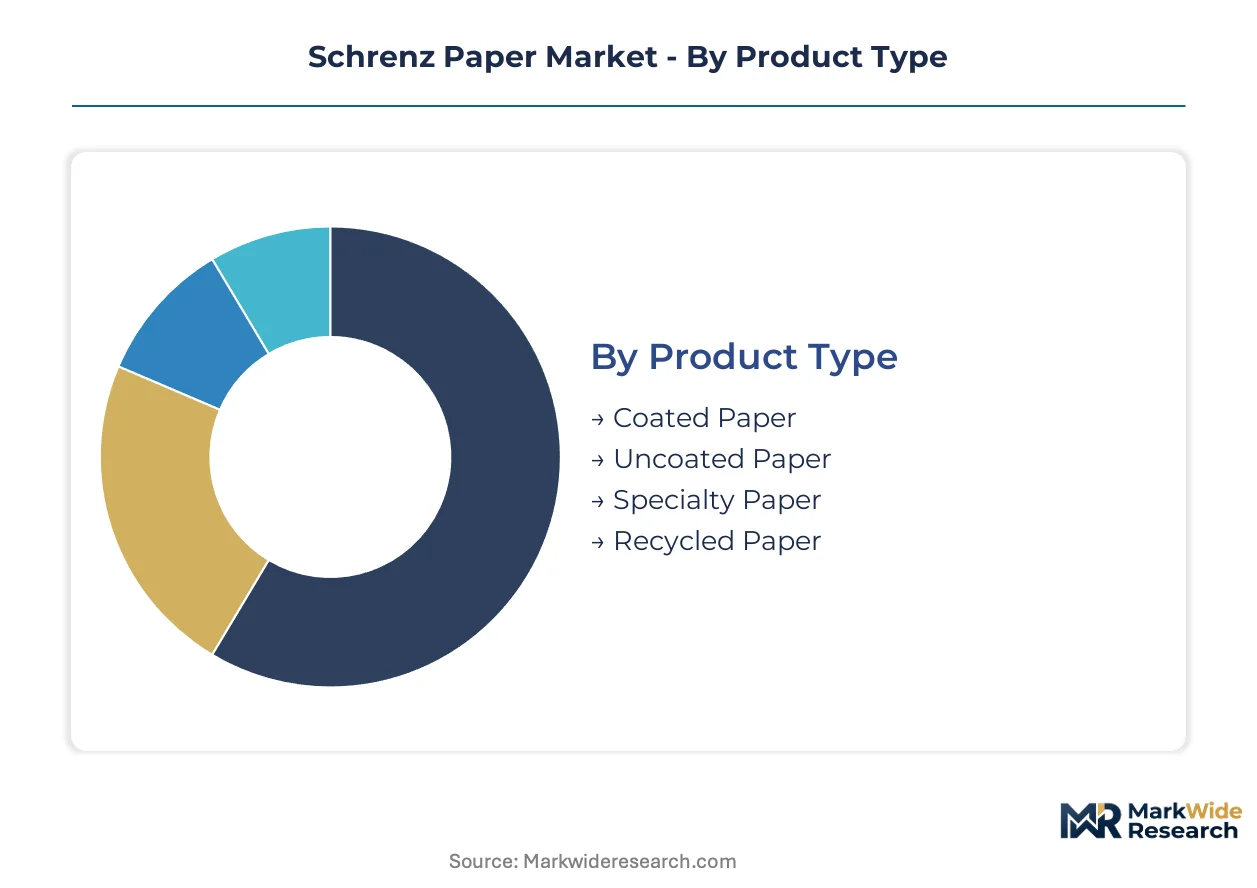
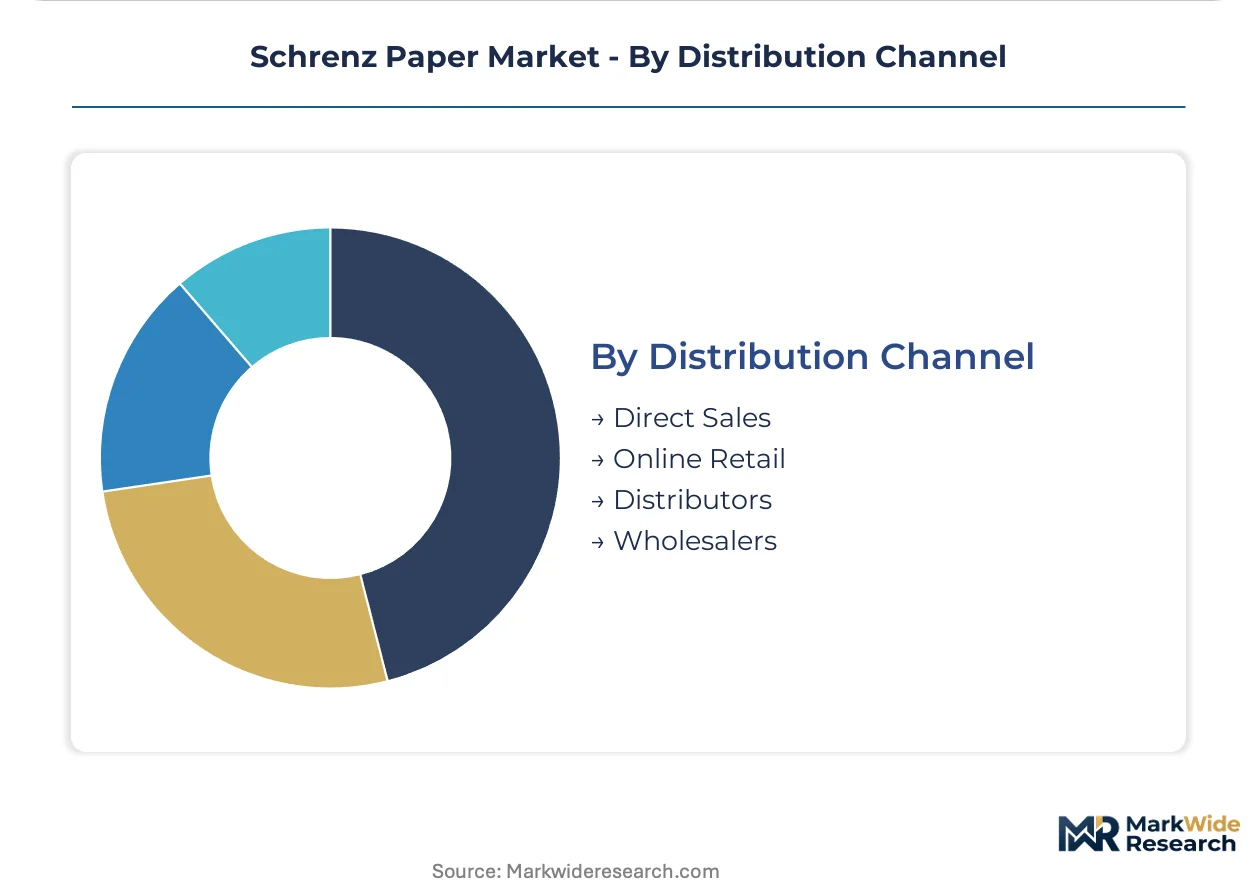
Schrenz Paper procurement flows through distinct channel pathways that vary by product complexity and order scale. Understanding these segment dynamics reveals where margin capture concentrates and which specifications command premium positioning across Central European supply chains.
Product Type:
Channel mix varies sharply by product type, with commodity grades moving through distributor networks while specialty grades require direct mill relationships for technical validation.
- Uncoated Paper:Multi-ply kraft stock manufactured through cylinder machine processes dominates volume throughput for protective interleaving. Polish automotive logistics clusters source this grade through Silesian packaging cooperatives negotiating multi-year grammmage commitments.
- Recycled Paper:Post-consumer fiber recovery with advanced screening preserves long-fiber strength through reuse cycles. Czech mills are retrofitting recovery lines to meet EU Packaging and Packaging Waste Regulation mandates, accelerating procurement from sustainability-audited buyers.
- Coated Paper:Surface-treated stocks for moisture barrier applications in precision electronics exports.
- Specialty Paper:Engineered grades with ISO 2528-compliant moisture vapor transmission certification for corrosion-sensitive automotive components.
By volume, Uncoated Paper leads. By growth pace, Recycled Paper is expanding most quickly.
Application:
Cost tier stratification separates high-specification automotive applications from commodity logistics uses where polyethylene film substitution threatens penetration.
- Packaging:Protective wrapping and void-fill applications for automotive parts distribution networks. KBA transport safety standards in Germany enforce burst strength minimums that cylinder machine technology satisfies through multi-ply wet-laid forming precision.
- Printing:Inkjet-compatible surface sizing enables branded protective wrapping with logo-printed interlayers for high-value electronics exports from Stuttgart and Munich engineering centers.
- Stationery:Lower-grammage grades for document protection and archival applications.
- Publication:Minimal penetration given Schrenz Paper's industrial protective focus.
Packaging commands the largest revenue share. Printing applications are gaining share fastest as digital convergence reshapes specification requirements.
End User:
Customer type determines contract structure, with integrated automotive OEMs locking in grammmage specifications while merchant converters face fiber cost volatility.
- Manufacturers:Automotive tier suppliers in Moravian logistics clusters require moisture-resistant kraft interlayers with 5-gsm tolerance bands for robotic handling compatibility.
- Retailers:Electronics exporters specifying controlled moisture vapor transmission rates for corrosion-sensitive cargo bound for Middle Eastern and Asian distribution hubs.
- Publishers:Limited demand concentrated in archival and document protection niches.
- Advertisers:Emerging interest in branded protective wrapping for premium unboxing experiences.
Manufacturers represent the deepest volume base. Retailers are climbing the fastest as e-commerce export packaging requirements tighten.
Distribution Channel:
Supply concentration in Bavarian captive forestry holdings limits merchant access to cost-stable fiber, fragmenting procurement leverage across channel types.
- Distributors:Consolidated procurement through packaging converter cooperatives is displacing spot-market purchasing among mid-sized automotive tier suppliers in Central Europe.
- Direct Sales:Integrated operators with captive forestry holdings in Bavaria secure multi-year supply cycles bypassing merchant intermediaries entirely.
- Wholesalers:Balkan packaging clusters in Serbia and Romania source custom-grammage specifications through regional wholesale networks serving emerging automotive supplier parks.
- Online Retail:Minimal penetration given specification complexity and validation requirements for protective paper applications.
Distributors handle the greatest transaction volume. Direct Sales channels are gaining share fastest as integrated operators deepen upstream control over fiber supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polish automotive logistics clusters demonstrate the highest demand elasticity, squeezing margins through cooperative procurement, while German precision-engineering exporters accept premium pricing for certified moisture barrier specifications.
Germany
Stuttgart and Munich engineering centers drive specification-grade demand for robotic-handling-compatible interlayers with sub-5-gsm tolerance bands. KBA transport packaging safety standards enforce burst strength minimums that cylinder machine producers must satisfy through multi-ply wet-laid forming precision. Bavarian captive forestry holdings anchor supply concentration around integrated pulp-to-paper operators.
Poland
Silesian automotive supplier parks concentrate procurement through packaging converter cooperatives negotiating multi-year grammmage commitments and delivery cadences. EU Packaging and Packaging Waste Regulation mandates compress virgin fiber tolerance thresholds, forcing mills toward higher-yield recovery processes. Warsaw-based logistics networks require moisture-resistant kraft interlayers for corrosion-sensitive component shipments to Middle Eastern distribution hubs.
Czech Republic
Moravian logistics clusters scale protective paper procurement for automotive parts distribution networks serving German OEM supply chains. REACH chemical restrictions constrain sizing agent formulations across EU-sourced production, accelerating migration to bio-based alternatives. Brno-area mills retrofit recovery lines with advanced screening systems to preserve long-fiber strength through multiple reuse cycles.
Serbia
Belgrade automotive supplier parks generate underpenetrated demand for custom-grammage protective papers serving emerging Balkan packaging clusters. EU Deforestation Regulation traceability requirements reshape pulp sourcing economics for non-integrated producers seeking sustainability-audited buyer contracts. Fabrika Hartije Beograd anchors regional supply through dedicated machine lines with specification flexibility.
Romania
Timișoara automotive supplier parks cluster near Western European logistics corridors, creating procurement pull for protective interleaving applications. Regional wholesale networks source custom-grammage specifications from mills with EUDR chain-of-custody documentation positioning. Bucharest-based distributors consolidate spot-market purchasing displacement among mid-sized tier suppliers.
Schrenz Paper Market Competitive Landscape
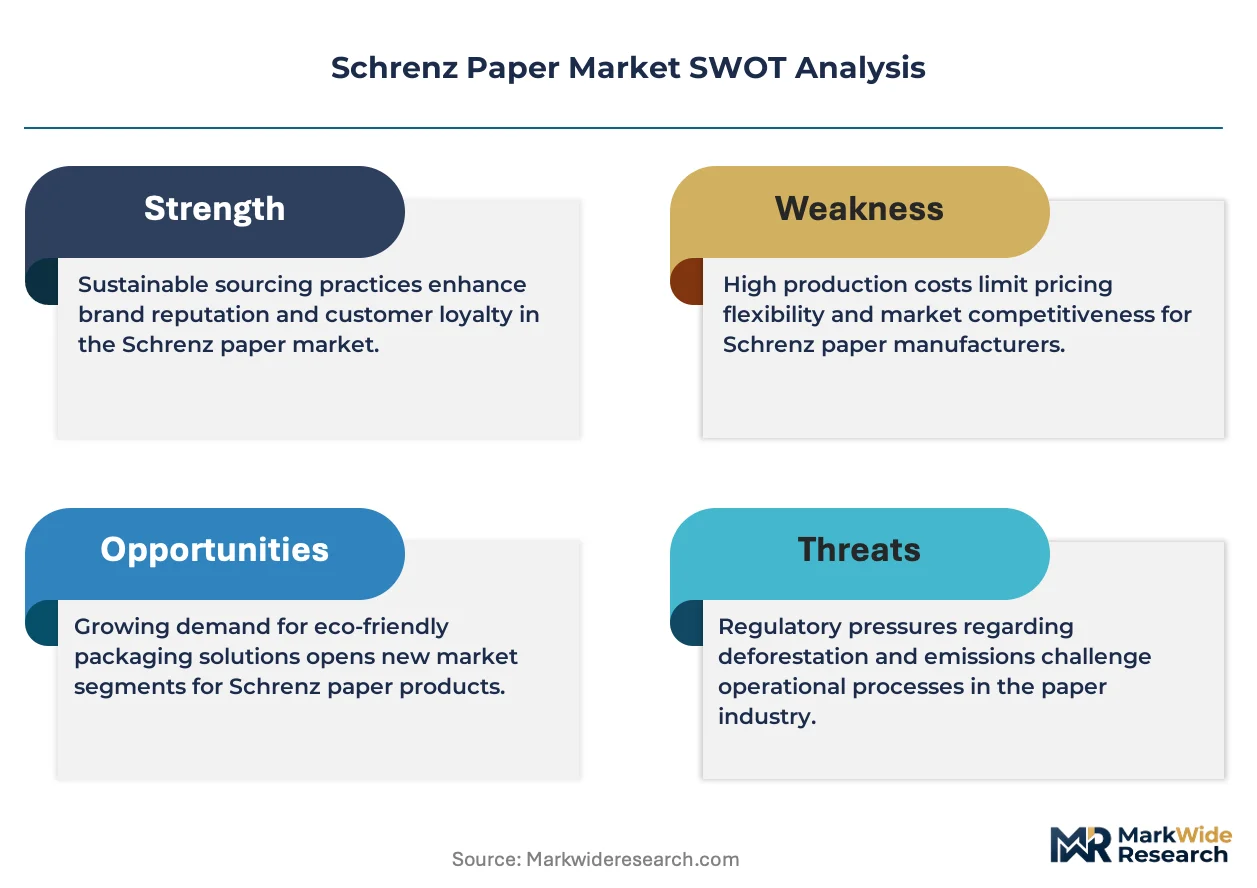
A small set of integrated leaders sits above a broader specialist tier, with captive forestry holdings separating cost-stable fiber access from merchant converter volatility. The structure rewards backward integration into pulp supply and punishes spot-market fiber dependence during Nordic timber harvest cycle fluctuations. Three archetypes dominate: Bavarian-anchored integrated operators, Balkan custom-grammage specialists, and cooperative-procurement-serving Polish distributors. Competitive moves concentrate on multi-year supply cycle locking and recovery line retrofitting for circular-economy compliance.
Within the integrated tier, Meyer Verpackungen exemplifies captive forestry leverage through Bavarian holdings securing multi-year fiber cost predictability. Fabrika Hartije Beograd occupies a specialist position serving Balkan packaging clusters with dedicated machine line flexibility for custom specifications. Among Central European distributors, Stepa s.r.o. represents the cooperative-procurement vector consolidating Silesian and Moravian logistics cluster demand.
| Leading Market Players |
|---|
| Meyer Verpackungen |
| Aubry Papier |
| Rossmann |
| Fabrika Hartije Beograd |
| Vrancart |
| EcoPaper |
| Stepa s.r.o. |
| APV Germany GmbH |
| J Hoogstraten |
| Others |
Value Network & Pricing Analysis
EU Packaging and Packaging Waste Regulation recycled content mandates gate both mill qualification for automotive supplier contracts and the price premiums that ISO 2528-certified moisture barrier grades command over commodity kraft interlayers. KBA transport safety standards in Germany enforce burst strength minimums that cylinder machine producers satisfy through multi-ply wet-laid forming precision, segmenting pricing power between specification-grade suppliers and volume-commodity converters.
Pricing Analysis
After-sales service bundling for moisture vapor transmission certification and 90-day validation cycles drives lifetime value capture among precision-engineering exporters. Three-tier pricing structure across premium, standard, and economy levels separates ISO 2528-certified specialty grades from uncoated kraft interlayers and recycled fiber commodity stocks. Cost compression in standard-grade protective wrapping intensifies as Polish packaging cooperatives consolidate procurement leverage through multi-year volume commitments. Automotive tier suppliers in Silesian logistics clusters exhibit highest price sensitivity, while Stuttgart and Munich engineering centers accept premium positioning for robotic-handling-compatible specifications.
Supply Chain Analysis
Germany and Poland anchor integrated pulp-to-paper production for specification-grade Schrenz Paper serving automotive OEM supply chains. Unbleached softwood kraft pulp, bio-based sizing agents, and cylinder machine wet-laid forming capacity constitute critical input dependencies. Single-source vulnerability concentrates around Bavarian captive forestry holdings controlled by integrated operators like Meyer Verpackungen, fragmenting merchant converter access to cost-stable fiber. Distribution runs through packaging converter cooperatives in Silesia and Moravia that displace spot-market purchasing with locked grammmage specifications and delivery cadences.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Schrenz Paper sits in early-cycle expansion as EU circular-economy compliance hardens virgin fiber substitution requirements and automotive logistics networks scale protective paper procurement across Central Europe.
For Market Incumbents: Secure captive fiber supply through multi-year timber harvest contracts or backward integration into Nordic pulp sourcing before EUDR traceability requirements reshape procurement economics. Defend specification-grade positioning by accelerating ISO 2528 certification cycles and investing in twin-wire forming technology for sub-5-gsm tolerance bands that robotic handling systems in Stuttgart engineering centers demand. For New Entrants and Emerging Players: Custom-grammage flexibility for Balkan automotive supplier parks near Belgrade and Timișoara represents the most penetrable white space, as regional mills lack dedicated machine line adaptability. Target Serbia and Romania through wholesale networks with EUDR chain-of-custody documentation that positions for sustainability-audited buyer contracts. Lead with digital printing convergence for inkjet-compatible branded protective wrapping serving high-value electronics exporters. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed merchant converters in Poland and Czech Republic facing fiber cost volatility and stranded recovery line capex. Five-to-ten year viability hinges on circular-economy compliance infrastructure and captive pulp supply integration. Watch for EUDR enforcement acceleration as the inflection signal that separates compliance-ready mills from stranded capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Bavarian captive forestry holdings anchor cost predictability for Meyer Verpackungen across multi-year supply cycles. |
| Recovery Line Retrofitting | Polish and Czech mills preserve long-fiber strength through advanced screening systems meeting EU Packaging and Packaging Waste Regulation mandates. |
| Digital Printing Surface Sizing Development | Inkjet-compatible stocks enable logo-printed interlayers for Stuttgart and Munich electronics engineering centers. |
| EUDR Chain-of-Custody Certification | Traceability documentation positions non-integrated producers for premium sourcing contracts with sustainability-audited automotive buyers. |
| Cooperative Procurement Consolidation | Silesian and Moravian logistics clusters lock grammmage specifications and delivery cadences through multi-year volume commitments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with packaging converter procurement directors, mill operations managers, automotive tier supplier logistics heads, and cylinder machine technology specialists. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, ECHA REACH substance restriction updates, KBA transport safety standard documentation, and customs trade data for unbleached kraft pulp flows. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and regional production cluster dimensions.
Across the analysis window, value projections rest on segment-level demand elasticity and input cost trajectory modeling. Segmentation dimensions include product complexity tier, end-use industry vertical, distribution channel structure, and regional regulatory compliance cluster. CAGRs were derived from trend extrapolation of procurement volume commitments and capacity expansion announcements, with cross-reference to automotive production forecasts for protective interleaving intensity per vehicle.
Underlying assumptions cover EU Green Deal packaging waste reduction target enforcement, EUDR implementation timelines, and Nordic timber harvest cycle stability, with deviation risk concentrated in softwood fiber price volatility and plastic film substitution acceleration for non-corrosion-sensitive applications. Recalibration cycles align with material shifts in regulatory mandate enforcement and automotive OEM specification updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Corrugated Board Market
Paper & Paperboard Packaging
Middle East and Africa Paper Cone Market
Paper & Paperboard Packaging
India Paper Packaging Market
Paper & Paperboard Packaging
Binder's Board Market
Paper & Paperboard Packaging
Mottled Test Liner Market
Paper & Paperboard Packaging
Plywood Box Market
Paper & Paperboard Packaging
North America Corrugated Board Packaging Market
Paper & Paperboard Packaging
Macerated Paper Padded Mailers Market
Paper & Paperboard Packaging
Composite Cardboard Tube Packaging Market
Paper & Paperboard Packaging
Freezer Paper Market
Paper & Paperboard Packaging
Paper Boxes Market
Paper & Paperboard Packaging
Corrugated Boxes Market
Paper & Paperboard Packaging
Wax-Coated Paper Market
Paper & Paperboard Packaging
Global Solid Board Market
Paper & Paperboard Packaging
Paper Bottles Market
Paper & Paperboard Packaging
Sublimation Paper Market