
 Construction Valve Seat Insert Market | 2026-2036
Construction Valve Seat Insert Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Valve Seat Insert Market Insights
Aftermarket service revenue is narrowing as original equipment manufacturers capture lifecycle value through extended warranty programs tied to proprietary insert specifications. MAHLE leverages captive foundry capacity to control material grades across its construction valve seat portfolio. Tenneco anchors North American supply through direct relationships with heavy equipment assemblers. Eaton competes on powder metallurgy expertise for high-wear mining applications.
A construction valve seat insert is a precision-machined annular component, typically cast from alloyed iron or sintered powder metal, that provides a sealing surface within valve assemblies used in hydraulic and pneumatic systems of construction machinery. The insert must maintain dimensional stability under cyclic pressure loads exceeding 20 MPa and resist abrasive wear from contaminated working fluids in earthmoving and material-handling equipment. Cast iron formulations dominate current volume due to cost-efficiency in standard gate and globe valve configurations, while stainless steel grades command premium positioning in corrosive marine construction environments. Application environment segmentation shows heavy equipment and mining sites generating the most intensive replacement cycles, with infrastructure projects shifting toward longer-life bronze alloys for buried pipeline systems.
OSHA workplace safety directives and EPA emissions compliance for non-road diesel equipment shape material selection and durability testing protocols for construction valve seat inserts in the United States. China's GB standards and MIIT equipment certification requirements mandate specific hardness ratings and leak-test performance for domestically sourced valve components in state-funded projects. Stakeholders must monitor how regional decarbonization regulations redefine acceptable alloy compositions and whether supplier qualification criteria consolidate around integrated material-traceability systems.
Market Dynamics
Equipment manufacturers are consolidating valve seat insert procurement around hardened alloy specifications as infrastructure resilience mandates tighten across OECD jurisdictions, compressing supplier qualification timelines and elevating material traceability requirements.
Growth Catalysts
- OSHA workplace safety directives:US construction equipment mandates now require extended leak-test intervals, forcing upgrades to premium seat materials in hydraulic systems.
- China's high-speed rail corridors:State-backed contractors specify premium alloy grades for dam and rail infrastructure, creating concentrated demand pull for certified suppliers.
- Powder metallurgy sintering:Advanced compaction techniques enable complex geometries that reduce machining waste and improve wear resistance in mining valve assemblies.
Market Restraints
- Alloy input cost volatility:Nickel and cobalt price swings destabilize foundry margins for high-performance stainless steel formulations.
- Supply concentration in Chinese casting:Overreliance on Hebei and Shandong province foundries exposes procurement chains to regional environmental shutdown orders.
- Cast iron performance ceiling:Standard gate valve configurations face hard limits in cyclic pressure applications exceeding 25 MPa, restricting upgrade paths.
Strategic Opportunities
- India's PLI scheme for construction equipment:Domestic manufacturing incentives attract component suppliers to establish captive foundry capacity near Pune and Chennai industrial clusters.
- Marine construction corrosion resistance:Offshore platform specifications create premium positioning for duplex stainless steel grades in subsea valve systems.
- Digital material traceability:Blockchain-integrated certification systems open procurement access to EU-funded infrastructure projects requiring full alloy provenance documentation.
Industry Challenges
- Metallurgical technician shortage:Specialized heat-treatment expertise for powder metal sintering commands wage premiums that constrain foundry expansion.
- Dual certification timelines:Simultaneous GB standard and ISO compliance testing extends product qualification cycles by eight to fourteen months.
- Legacy hydraulic system integration:Bronze alloy retrofits face dimensional mismatch risks with existing cast iron valve bodies in buried pipeline infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Valve Seat Insert Market |
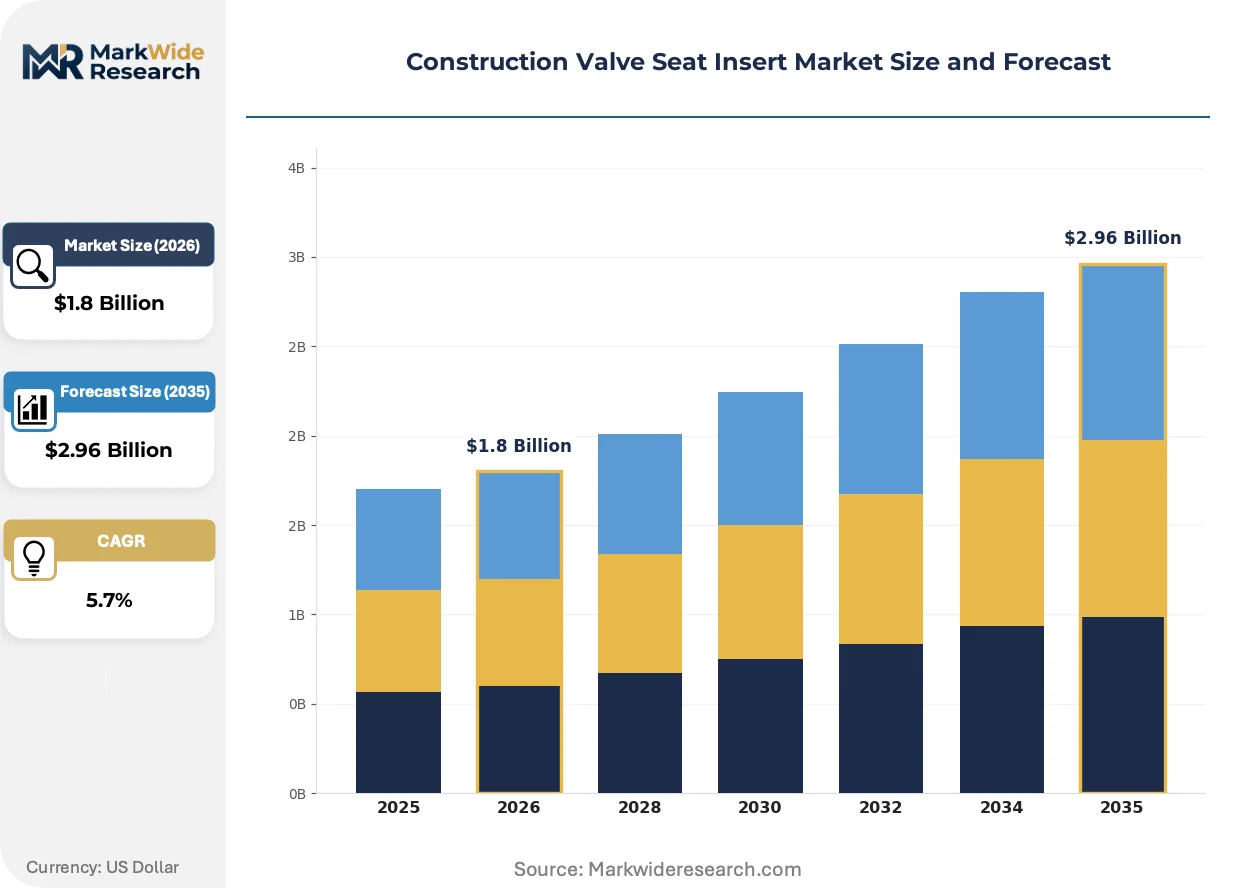
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cast Iron, Stainless Steel, Bronze, Brass, Carbon Steel, Copper Valve Type: Gate Valve, Globe Valve, Ball Valve, Butterfly Valve, Check Valve, Needle Valve Application Environment: Heavy Equipment, Infrastructure Projects, Mining Sites, Marine Constructions, Oil Field Equipment, Agricultural Machinery End User: Construction Contractors, Equipment Manufacturers, Aftermarket Suppliers, Municipal Authorities |
| Companies Covered | MAHLE, Tenneco, Eaton, Mitsubishi Materials, BorgWarner, Nippon Piston Ring, AVL List, GKN Automotive, Forvia SE (Faurecia), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Valve Seat Insert Market Trends and Innovations
Digital twin technology and predictive maintenance protocols are reconfiguring how valve seat durability is specified, with real-time wear monitoring displacing scheduled replacement intervals in premium equipment segments.
Powder metallurgy compaction with controlled atmosphere sintering is virtualizing traditional casting workflows for complex seat geometries. Mining equipment assemblers in Western Australia and Chilean copper districts specify these net-shape components for high-cycle hydraulic systems. The technology is virtualizing supplier relationships by enabling direct digital file transfers from OEM engineering teams to regional sintering facilities, compressing traditional foundry procurement channels.
REACH substance restrictions on hexavalent chromium coatings are forcing conversion to trivalent alternatives or ceramic surface treatments for valve seats in European construction equipment. German and French equipment assemblers now mandate coating-substitution documentation in supplier qualification packets. Marine construction valves face the tightest compliance windows, with North Sea platform operators accelerating specification updates ahead of 2026 enforcement milestones.
Equipment fleet operators are unbundling valve seat replacement from comprehensive maintenance contracts, creating spot-purchase channels through certified parts distributors. Heavy equipment rental companies in Texas and Alberta oil sands regions now source inserts independently from OEM service networks. This pattern concentrates in high-wear mining verticals where replacement frequency exceeds warranty coverage periods, pressuring traditional captive aftermarket structures.
Construction Valve Seat Insert Market Segmentation
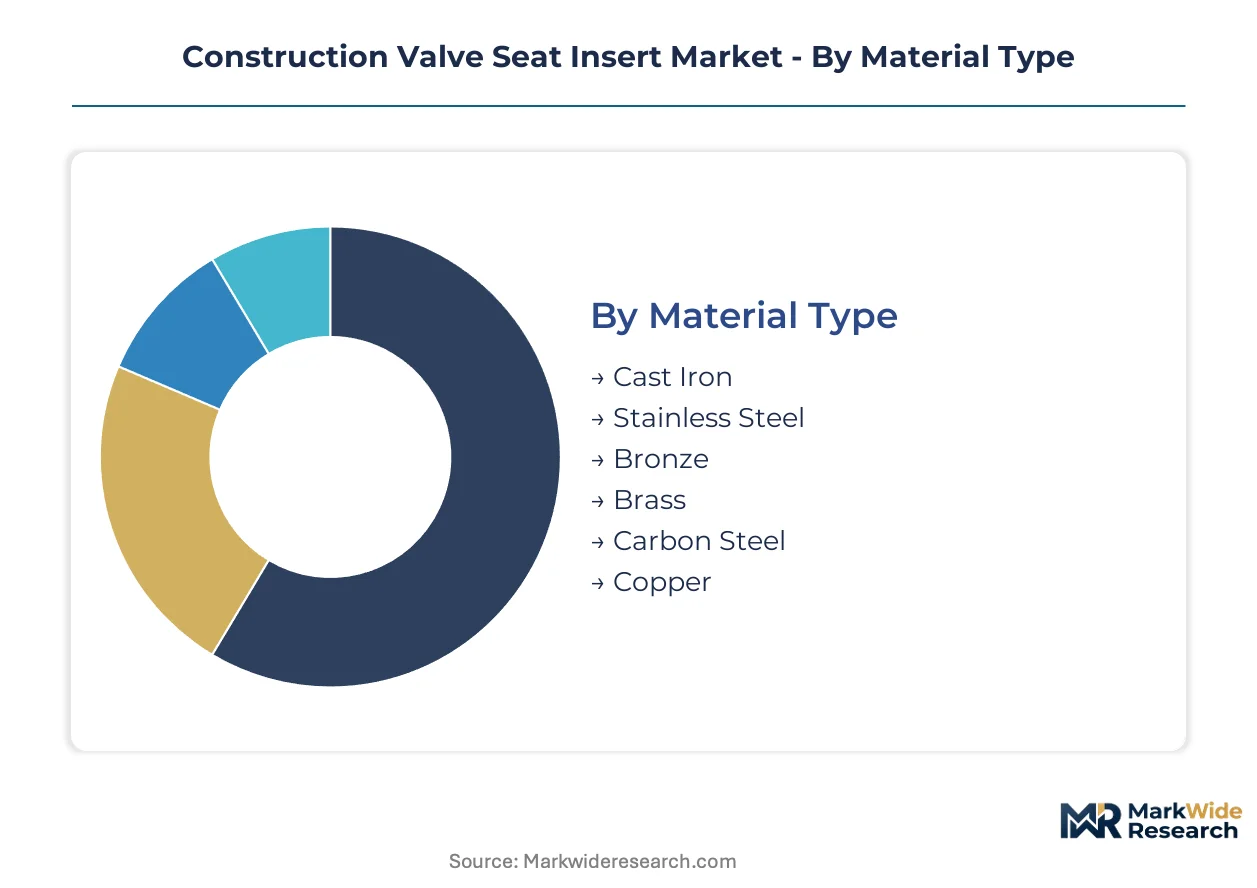
Segmentation in construction valve seat inserts tracks how material specifications, valve architectures, and application severity drive replacement-cycle economics. Procurement patterns diverge sharply between OEM captive supply and independent aftermarket channels, with warranty-integrated service models reshaping volume allocation across end-user categories.
Material Type:
After-sales-service intensity varies dramatically by material grade, with premium alloys commanding extended warranty bundles and cast iron relying on high-frequency spot replacement.
- Cast Iron:Alloyed gray and ductile iron formulations dominate standard hydraulic valve configurations through cost-efficient machinability and established foundry supply chains. Demand concentrates in China's state-funded infrastructure corridors where contractors prioritize procurement economy over extended service intervals for above-ground equipment.
- Stainless Steel:Austenitic and martensitic grades deliver dimensional stability under cyclic pressure loads exceeding 25 MPa in corrosive operating environments. Marine construction specifications in the North Sea and Gulf of Mexico mandate duplex stainless for subsea valve systems, with coating-substitution documentation now required under REACH substance restrictions.
- Bronze:Copper-tin alloys provide galling resistance and extended wear life in buried pipeline infrastructure where replacement access is restricted.
- Brass:Lead-free formulations address potable water system compliance in municipal construction projects.
- Carbon Steel:Heat-treated grades serve medium-pressure applications where cost constraints limit alloy selection.
- Copper:Pure copper inserts address specialized thermal conductivity requirements in cryogenic valve assemblies.
Cast iron holds the largest share; momentum sits with stainless steel as corrosion-resistant specifications tighten in offshore and chemical processing environments.
Valve Type:
Valve architecture determines insert geometry complexity, machining waste coefficients, and suitability for powder metallurgy net-shape production.
- Gate Valve:Linear-motion sealing surfaces in wedge or parallel disk configurations experience high-cycle wear in mining hydraulic systems. Western Australian copper districts specify sintered powder metal seats to reduce machining waste and improve abrasive wear resistance from contaminated working fluids.
- Globe Valve:Throttling-optimized seat geometries face severe cavitation erosion in high-pressure differential applications. Dam construction in China's Sichuan and Yunnan provinces drives demand for hardened alloy inserts certified to GB hardness ratings.
- Ball Valve:Rotating spherical closure elements require precision-machined annular seats for bubble-tight sealing in natural gas distribution.
- Butterfly Valve:Elastomer-lined or metal-seated configurations serve large-bore low-pressure applications in water treatment infrastructure.
- Check Valve:Passive flow-control seats minimize reverse-flow damage in pump discharge systems.
- Needle Valve:Fine-metering seat geometries address high-precision flow control in instrumentation and test equipment.
Gate valve configurations anchor current volume; globe valve specifications are expanding most quickly as infrastructure resilience mandates extend leak-test intervals.
Application Environment:
Operating severity and fluid contamination levels create tiered replacement-frequency patterns that structure aftermarket revenue concentration.
- Heavy Equipment:Earthmoving and material-handling hydraulic systems generate intensive replacement cycles due to abrasive particle ingestion. Texas and Alberta oil sands rental fleets now source inserts independently from OEM service networks, unbundling valve seat replacement from comprehensive maintenance contracts.
- Mining Sites:High-cycle pressure loading exceeding 20 MPa in Chilean copper districts and Western Australian iron ore operations demands premium wear-resistant materials. Powder metallurgy sintering enables complex geometries that compress traditional foundry procurement channels through direct digital file transfers.
- Infrastructure Projects:Buried pipeline systems shift toward longer-life bronze alloys where replacement access is economically prohibitive.
- Marine Constructions:Subsea valve specifications create premium positioning for duplex stainless steel grades facing accelerated corrosion timelines.
- Oil Field Equipment:Sour service environments mandate NACE-compliant material selections for hydrogen sulfide resistance.
- Agricultural Machinery:Seasonal operating patterns and cost-sensitive procurement favor standard cast iron configurations with shorter replacement intervals.
Heavy equipment commands the greatest replacement frequency; mining applications are gaining share fastest as autonomous fleet expansion intensifies hydraulic system utilization rates.
End User:
Customer type determines procurement channel structure, with OEM captive supply consolidating around proprietary specifications and aftermarket channels fragmenting across certified distributors.
- Construction Contractors:State-backed entities in China's high-speed rail corridors specify premium alloy grades with mandatory MIIT certification, compressing supplier qualification timelines and elevating material traceability requirements.
- Equipment Manufacturers:Heavy equipment assemblers consolidate procurement around hardened alloy specifications tied to extended warranty programs, capturing lifecycle value that previously flowed to independent service providers.
- Aftermarket Suppliers:Independent distributors face narrowing revenue pools as OEM warranty integration displaces traditional spot-purchase channels, though mining verticals with replacement frequency exceeding warranty coverage sustain independent sourcing.
- Municipal Authorities:Public procurement frameworks prioritize total lifecycle cost over initial acquisition price, favoring extended-service-interval materials in buried infrastructure.
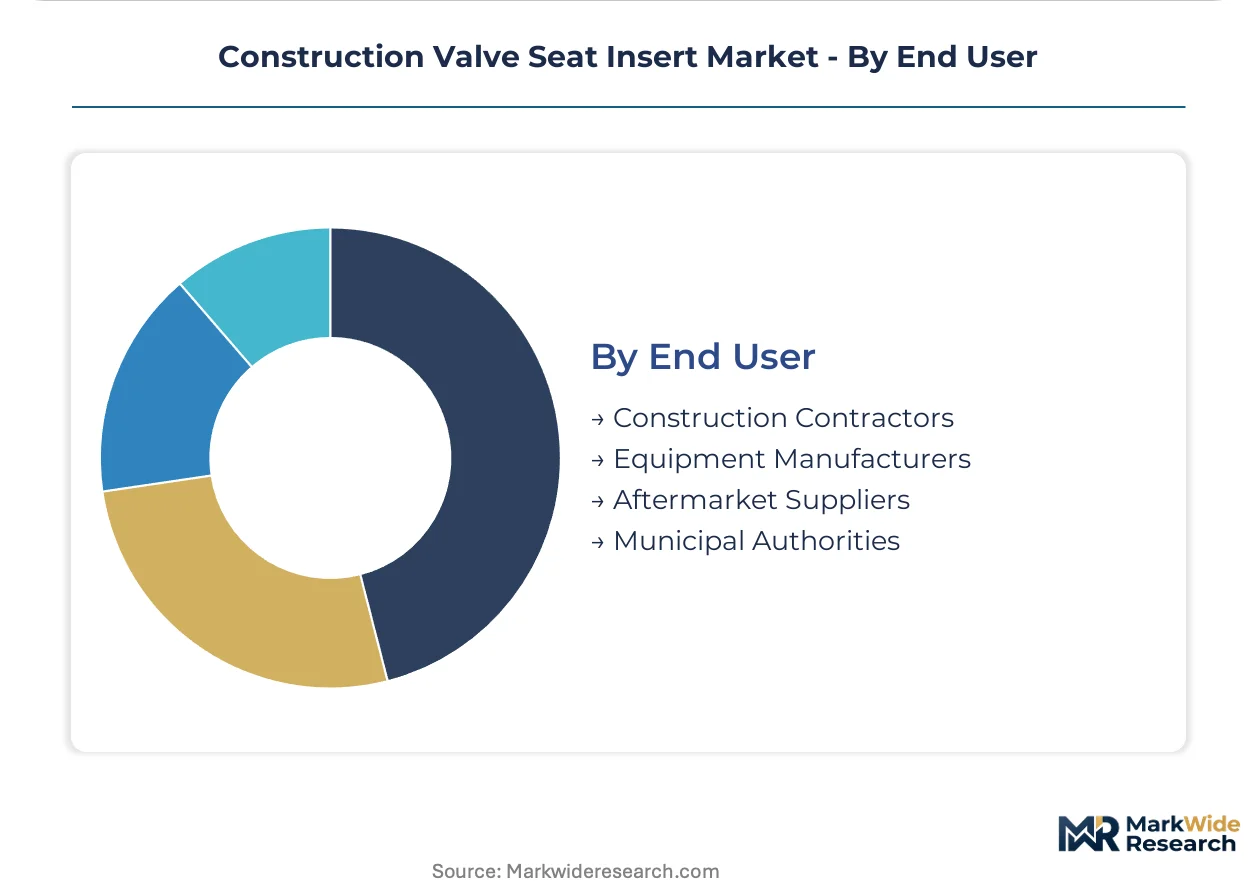
Equipment manufacturers hold the largest share; aftermarket suppliers face steepest structural pressure as captive service models extend coverage periods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese state contractors exhibit the lowest price elasticity, specifying premium alloy grades for certified infrastructure, while agricultural machinery operators in India and Brazil remain most sensitive to procurement costs, driving volume toward standard cast iron configurations.
United States
OSHA workplace safety directives now mandate extended leak-test intervals for construction hydraulic systems, elevating demand for hardened alloy seat materials. EPA emissions compliance for non-road diesel equipment shapes durability testing protocols across equipment categories. Texas oil sands rental fleets source valve seat inserts independently from OEM service networks, unbundling replacement from comprehensive maintenance contracts.
China
State-backed contractors in high-speed rail and dam construction corridors specify premium alloy grades with mandatory MIIT certification requirements. GB standards mandate specific hardness ratings and leak-test performance for domestically sourced valve components. Hebei and Shandong province foundries anchor casting supply, though regional environmental shutdown orders expose procurement chains to disruption risk.
Germany
REACH substance restrictions on hexavalent chromium coatings force conversion to trivalent alternatives or ceramic surface treatments for valve seats in European construction equipment. German equipment assemblers now mandate coating-substitution documentation in supplier qualification packets. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia concentrate powder metallurgy sintering expertise for complex seat geometries.
India
The PLI scheme for construction equipment attracts component suppliers to establish captive foundry capacity near Pune and Chennai industrial clusters. BIS certification requirements shape material selection protocols for domestically manufactured valve components. Maharashtra and Tamil Nadu industrial corridors concentrate emerging foundry investment targeting infrastructure resilience standards.
Australia
Western Australian copper districts specify sintered powder metal seats to reduce machining waste and improve abrasive wear resistance in high-cycle hydraulic systems. METI-aligned technical standards influence procurement specifications for mining equipment assemblers operating in the region. Perth-based equipment distributors serve as regional hubs for valve component supply to Chilean and Indonesian mining operations.
Construction Valve Seat Insert Market Competitive Landscape
Integrated automotive suppliers and specialized powder metallurgy firms split the market between captive OEM supply and independent aftermarket channels. The vendor base concentrates around three strategic archetypes: diversified powertrain component manufacturers with captive foundry capacity, precision sintering specialists serving mining equipment verticals, and regional casting houses competing on procurement economy for standard configurations. Dominant competitive moves include backward integration into alloy supply chains and technology licensing agreements for controlled-atmosphere sintering processes.
Within the diversified powertrain tier, MAHLE and Tenneco occupy positions defined by captive manufacturing infrastructure and direct OEM relationships. MAHLE exemplifies the vertically integrated archetype through foundry capacity that controls material grades across construction valve seat portfolios. Tenneco anchors North American supply through proximity to heavy equipment assemblers. Eaton represents the powder metallurgy specialization vector, with expertise positioning concentrated in high-wear mining applications where complex geometries and abrasive resistance command premium specifications.
| Leading Market Players |
|---|
| MAHLE |
| Tenneco |
| Eaton |
| Mitsubishi Materials |
| BorgWarner |
| Nippon Piston Ring |
| AVL List |
| GKN Automotive |
| Forvia SE (Faurecia) |
| Others |
Pricing and Supply Chain Analysis
Foundry undercapacity in Hebei province compresses lead times for premium alloy grades while elevating spot pricing power among certified suppliers serving China's state-backed infrastructure contractors. This utilization squeeze propagates through procurement chains, forcing equipment manufacturers to absorb cost premiums or downgrade material specifications.
Pricing Analysis
Aftermarket service contracts now capture the majority of lifetime value, with OEMs bundling extended warranty programs around proprietary insert specifications. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and material traceability depth. Cost compression in cast iron tiers is intensifying because Hebei foundries face environmental compliance-driven output restrictions. Agricultural machinery operators in India and Brazil exhibit the highest price sensitivity, while marine construction specifications in the North Sea demonstrate minimal elasticity.
Supply Chain Analysis
Extended payment terms from heavy equipment assemblers now reach 90-120 days, straining working capital for regional casting houses and accelerating consolidation toward vertically integrated suppliers. Raw material sourcing draws from nickel and cobalt streams subject to LME price volatility, alloyed iron feedstock concentrated in Chinese blast furnace output, and powder metal premixes anchored in German and Japanese chemical reduction facilities. Single-source vulnerability concentrates in Hebei and Shandong province foundries exposed to MEE environmental shutdown orders. Distribution runs through OEM captive service networks for warranty-integrated volumes, with independent aftermarket channels fragmenting across certified parts distributors in mining-intensive regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized heat-treatment expertise for powder metal sintering commands wage premiums that constrain foundry expansion, creating a durable bottleneck for quality-assured supply.
For Market Incumbents: Entrench market position through captive foundry capacity additions near Pune and Chennai industrial clusters, securing proximity to India's PLI-subsidized equipment manufacturing. Deepen backward integration into alloy supply chains to buffer nickel and cobalt price volatility. Defend against independent aftermarket encroachment by extending warranty coverage periods beyond replacement cycles in high-wear mining verticals. For New Entrants and Emerging Players: Pursue white-space opportunities in marine construction corrosion resistance, where duplex stainless steel specifications face tight compliance windows ahead of REACH enforcement milestones. Target India's emerging foundry corridor with blockchain-integrated certification systems enabling EU-funded infrastructure procurement access. Establish direct digital file transfer capabilities for powder metallurgy net-shape production, compressing traditional foundry procurement channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among powder metallurgy specialists serving autonomous mining fleet operators with predictive maintenance-integrated service models. Long-term viability favors suppliers with demonstrated GB standard and ISO dual certification capabilities, as qualification timelines extend product commercialization cycles. Watch for inflection signals in regional decarbonization regulations redefining acceptable alloy compositions and consolidating supplier qualification criteria around integrated material-traceability systems.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Capacity Expansion | MAHLE's vertically integrated model controls material grades across construction valve seat portfolios. |
| Powder Metallurgy Sintering Investment | Eaton's expertise positions for high-wear mining applications with complex net-shape geometries. |
| Blockchain Certification Integration | Digital provenance systems open EU-funded infrastructure procurement to certified suppliers. |
| Dual Standard Compliance Pathway | Simultaneous GB and ISO qualification compresses supplier timelines for China's state contractors. |
| Aftermarket Channel Unbundling | Texas and Alberta rental fleets now source inserts independently from OEM service networks. |
Research Methodology
A standing panel of foundry operations directors, heavy equipment procurement managers, aftermarket service heads, and metallurgical R&D specialists provided ongoing calibration across primary fieldwork. Secondary validation drew from customs and trade data, SEC 10-K filings of diversified powertrain suppliers, MIIT equipment certification registries, and OECD infrastructure investment databases. Bottom-up volume triangulation against top-down alloy consumption estimates anchored segmentation-level outputs.
Scenario-bracketing around commodity price volatility and regulatory enforcement timelines shaped projections across the analysis window. Segmentation dimensions modeled include material grade tier, valve architecture type, application severity environment, and end-user procurement channel structure. CAGRs were derived from fitted growth curves incorporating equipment fleet utilization rates, infrastructure investment pipelines, and replacement cycle compression from predictive maintenance adoption. Industry-specific inputs encompassed autonomous mining fleet expansion trajectories and REACH substance restriction compliance deadlines.
Macroeconomic conditions sit as an overlay; deviation in nickel and cobalt price trajectories, Chinese environmental enforcement intensity, or OECD infrastructure stimulus magnitude would shift the trajectory. Forecasts reflect documented assumptions around supplier qualification timelines and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Valve Interlocks Market
Valves
Vacuum Insulated Pipe Market
Valves
Expansion Valves Market
Valves
Industrial Valves Market
Valves
Pneumatic Positioner Market
Valves
Flare Stack Monitoring Systems Market
Valves
US Water & Wastewater Valves Market
Valves
Global Marine Actuators and Valves Market
Valves
Global Globe Valve Market
Valves
Pup Joint Market
Valves
Electro Pneumatic Positioner Market
Valves
Float Traps Market
Valves
Pipeline Pigging Valves Market
Valves
Stainless Steel Valve Tag Market
Valves
Electronic Expansion Valves Market
Valves
Global Gas Pressure Regulator Market