
 Low Voltage (LV) and Medium Voltage (MV) Switchgear Market | 2026-2036
Low Voltage (LV) and Medium Voltage (MV) Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
Low Voltage (LV) and Medium Voltage (MV) Switchgear Market Foresight
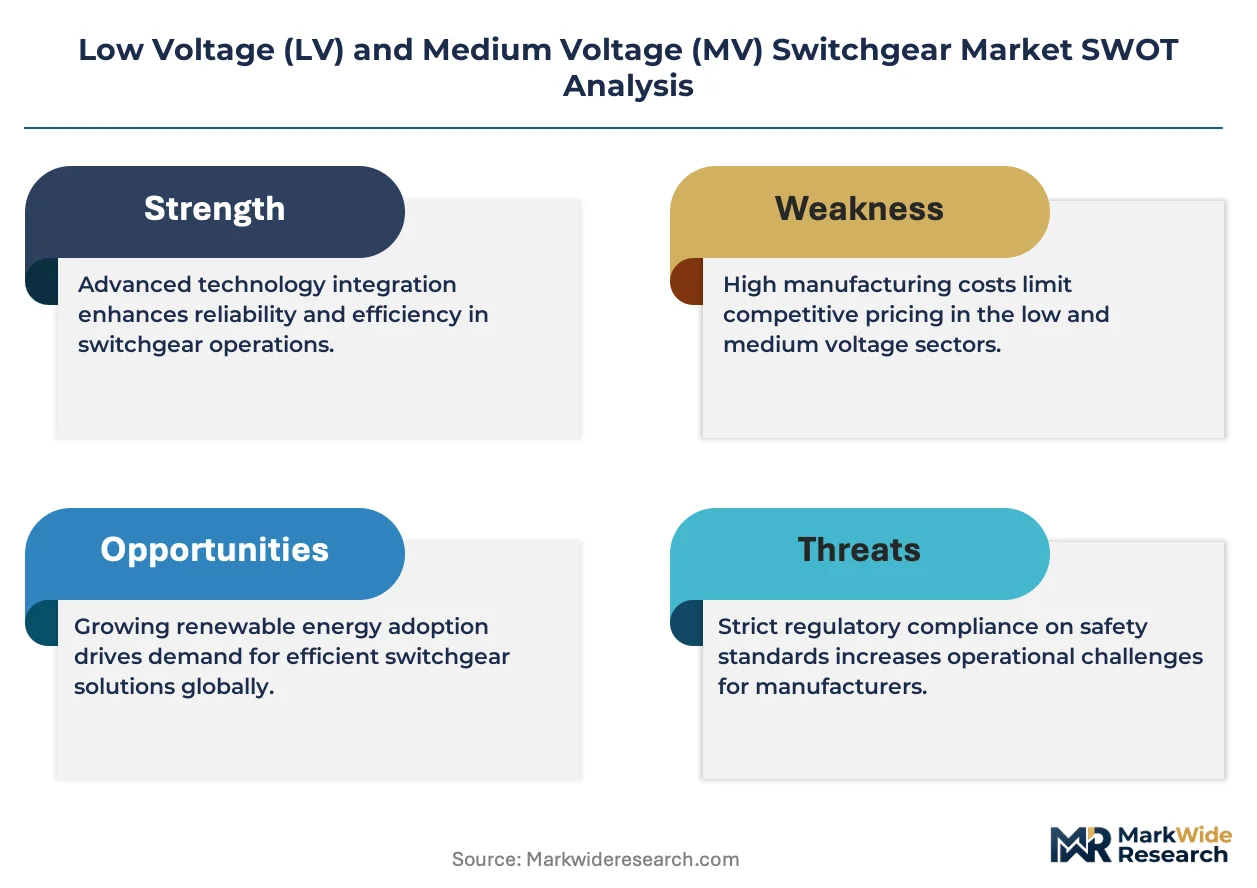
Copper is decoupling from traditional busbar assemblies as aluminum-silver hybrid conductors gain traction in cost-sensitive MV switchgear designs. Schneider Electric leverages backward integration into contactor manufacturing to protect margin pools across its LV portfolio. ABB anchors its European position through vacuum interrupter technology leadership, while Siemens AG dominates digital switchgear platforms with integrated condition monitoring.
Low voltage and medium voltage switchgear encompasses electrical distribution apparatus rated up to 52 kV that controls, protects, and isolates power circuits using electromechanical or solid-state switching elements. These assemblies incorporate molded-case circuit breakers, vacuum interrupters, and intelligent protection relays to ensure selective coordination across radial and ring-main network topologies. Vacuum technology leads the technology segment due to its zero-global-warming-potential profile and maintenance intervals exceeding twenty years, while air-insulated variants capture share in space-constrained urban substations. The industrial end-user segment concentrates margin pools where arc-flash compliance and selective coordination requirements command specification premiums over standard commercial installations.
The EU F-Gas Regulation and REACH framework restrict SF6 deployment in new switchgear, compelling manufacturers to certify vacuum and air-insulated alternatives under harmonized CE marking protocols. The US EPA maintains voluntary partnerships for SF6 emission reductions while OSHA and NFPA standards govern arc-energy containment in industrial LV assemblies. Stakeholders must monitor how IEC 62271-100 revisions on vacuum interrupter endurance testing reshape product qualification timelines and competitive access across European and North American procurement channels.
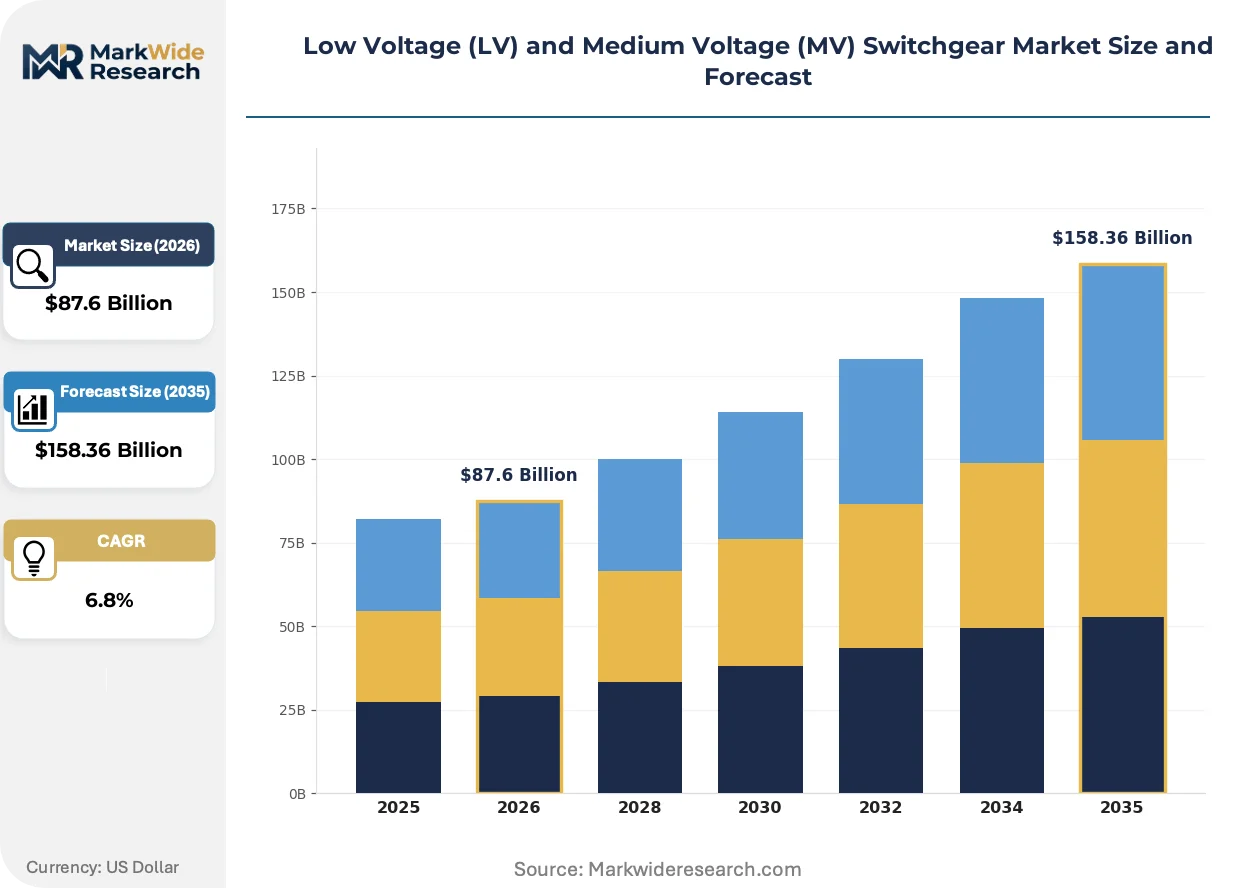
Market Dynamics
EU F-Gas Regulation mandates are compressing SF6 switchgear replacement cycles while AI data center electrification concentrates procurement volumes among hyperscale operators in Germany and the United States.
Growth Catalysts
- EU F-Gas phase-down mandates:The regulation accelerates vacuum and air-insulated switchgear certification timelines, forcing utilities across Germany, France, and Italy into synchronized replacement programs.
- Data center power density escalation:Hyperscale operators in Northern Virginia and Frankfurt require 36 kV and 52 kV MV switchgear clusters to support AI training loads exceeding 100 MW per facility.
- Aluminum-silver hybrid conductor adoption:Cost-sensitive MV designs are substituting copper busbars with aluminum-silver composites, reducing material costs without sacrificing thermal performance.
Market Restraints
- Copper price volatility:Raw material swings compress margin pools for LV assembly manufacturers dependent on spot-market copper procurement.
- Vacuum interrupter supply concentration:Production of ceramic vacuum bottles clusters in East Asian manufacturing zones, creating single-source risk for European switchgear OEMs.
- IEC 62271-100 endurance testing delays:Revised qualification protocols extend product certification timelines by 8-14 months, freezing new entrant access to CE-marked procurement channels.
Strategic Opportunities
- Digital switchgear platform penetration:Integrated condition monitoring and predictive maintenance modules command specification premiums in German industrial electrification programs.
- India grid modernization tailwinds:The country's national smart grid mission and renewable integration targets create underpenetrated demand for 11 kV and 33 kV ring-main units.
- Air-insulated technology convergence:Dry-air insulation systems are capturing share in space-constrained urban substations across Tokyo and Singapore where SF6 alternatives face footprint constraints.
Industry Challenges
- Vacuum interrupter engineering talent scarcity:Specialized ceramic metallization and brazing expertise concentrates among aging workforces in Japan and Germany.
- Legacy IEC 61850 integration complexity:Brownfield substations require protocol gateway layers to bridge proprietary SCADA architectures with modern digital switchgear communications stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Voltage (LV) and Medium Voltage (MV) Switchgear Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Miniature Circuit Breakers, Air Circuit Breakers, Switch Disconnectors, Fuse Switches Technology: Vacuum, SF6, Oil-Insulated, Air-Insulated Installation: Indoor, Outdoor, Wall-Mounted, Floor-Mounted End User: Utilities, Industrial, Commercial, Residential |
| Companies Covered | Schneider Electric, ABB, Siemens AG, Eaton Corporation, Mitsubishi Electric Corporation, General Electric, Toshiba, Fuji Electric, Hyosung, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Voltage (LV) and Medium Voltage (MV) Switchgear Market Shifts & Advancements
Solid-state switching elements are displacing electromechanical breakers in selective coordination schemes, while regulatory chemistry restrictions and procurement centralization reshape competitive access patterns.
Vacuum interrupter technology is converging with solid-state fault current limiters in next-generation MV switchgear designs. German utilities and Nordic grid operators are piloting hybrid assemblies that combine 20-year maintenance intervals with sub-cycle fault isolation. This convergence compresses the addressable market for pure electromechanical solutions while elevating qualification barriers for component suppliers.
The EU F-Gas Regulation and REACH framework now prohibit SF6 in new switchgear installations across member states. Manufacturers must certify vacuum and dry-air alternatives under harmonized CE marking protocols administered by ECHA. German TSOs and French distribution utilities face the steepest compliance cliffs, with replacement cycles front-loaded into 2027-2029 procurement windows.
Hyperscale data center operators are consolidating switchgear procurement through direct OEM relationships, bypassing traditional electrical distributor channels. This concentration compresses reseller margins while rewarding manufacturers with captive vacuum interrupter production and modular platform architectures. The pattern is most visible in Northern Virginia, Frankfurt, and Amsterdam where AI facility power densities exceed 50 MW per site.
Low Voltage (LV) and Medium Voltage (MV) Switchgear Market Segmentation
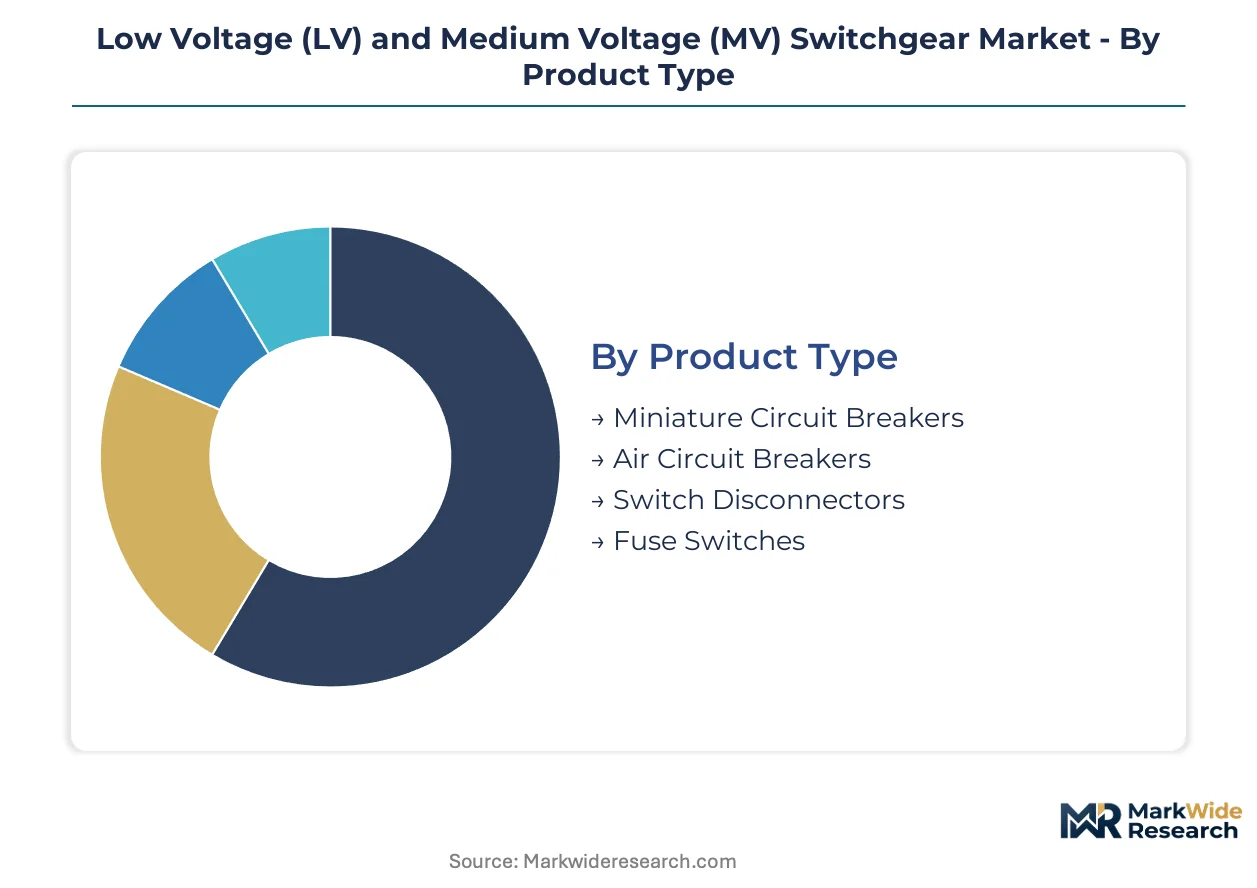
Switchgear segmentation reveals how procurement centralizes around specific technical specifications and installation contexts. Product type and technology choices determine margin pools, while end-user concentration shapes competitive access patterns across utilities and hyperscale data center operators.
Product Type:
Supply concentration for contactor subassemblies and trip units tilts competitive advantage toward manufacturers with backward integration into breaker production.
- Miniature Circuit Breakers:Modular thermal-magnetic protection devices rated up to 125A dominate residential and light commercial distribution panels. Demand clusters in German housing electrification programs and Indian smart meter rollouts where DIN-rail compatibility commands specification premiums.
- Air Circuit Breakers:Draw-out frame designs rated 630A to 6300A protect main bus sections in industrial facilities and data center substations. Northern Virginia and Frankfurt hyperscale operators specify intelligent ACBs with integrated power monitoring and Modbus communications for selective coordination across 36 kV and 52 kV clusters.
- Switch Disconnectors:Load-break switches provide visible isolation points in ring-main units and transformer circuits.
- Fuse Switches:Cost-critical protection for distribution transformers and capacitor banks in developing grid infrastructure.
Air circuit breakers absorb the bulk of installed capacity in industrial and data center applications; miniature circuit breakers are expanding most quickly through residential electrification mandates.
Technology:
Material chemistry restrictions and maintenance interval requirements segment procurement between legacy insulation media and zero-GWP alternatives.
- Vacuum:Ceramic interrupter bottles with copper-chromium contacts achieve dielectric recovery in sub-cycle times without atmospheric contamination. German TSOs and French distribution utilities mandate vacuum for all new 12 kV to 52 kV installations under EU F-Gas Regulation compliance timelines.
- SF6:Sulfur hexafluoride insulation retains installed base in existing substations but faces prohibition for new installations across EU member states.
- Oil-Insulated:Legacy technology persists in rural Indian and Southeast Asian distribution networks where capital constraints delay replacement cycles.
- Air-Insulated:Dry-air dielectric systems with epoxy resin bushings capture urban substation projects in Tokyo and Singapore where footprint constraints exclude SF6 alternatives.
Vacuum technology commands the dominant share of new procurement; air-insulated designs are climbing the fastest through space-constrained metropolitan installations.
Installation:
Environmental exposure ratings and accessibility requirements determine enclosure engineering and thermal management specifications.
- Indoor:Metal-clad assemblies with IP4X ingress protection serve climate-controlled electrical rooms in industrial facilities and commercial buildings. German automotive manufacturing plants specify indoor MV switchgear with arc-flash containment and integrated condition monitoring.
- Outdoor:Weatherproof enclosures with anti-condensation heaters protect rural distribution substations and renewable generation interconnection points.
- Wall-Mounted:Compact LV distribution boards optimize floor space in retail and healthcare facilities.
- Floor-Mounted:Free-standing switchgear lines accommodate heavy draw-out breakers and cable termination chambers in heavy industrial environments.
Indoor installations retain the largest installed base; outdoor configurations are gaining share fastest through utility-scale solar and wind farm electrification.
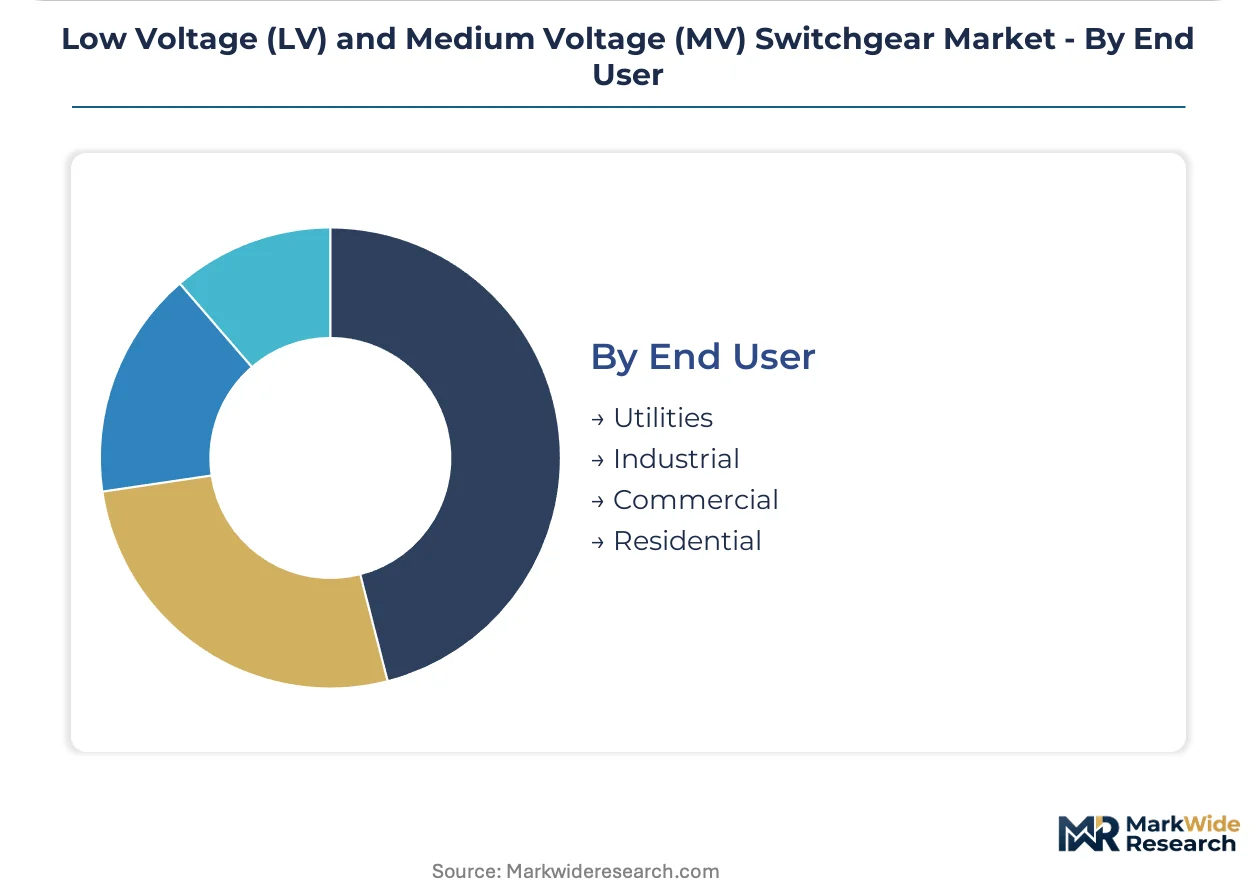
End User:
Specification authority and procurement scale vary dramatically across customer categories, with utilities and hyperscale operators wielding disproportionate influence over product roadmaps.
- Utilities:Transmission and distribution operators specify type-tested assemblies under IEC 62271 and IEEE C37 standards with mandatory seismic and short-circuit withstand certification. German TSOs synchronize replacement programs with EU F-Gas phase-down mandates.
- Industrial:Manufacturing and process facilities prioritize arc-flash safety and selective coordination compliance over initial capital cost. Petrochemical complexes in Texas and Rotterdam specify LV switchgear with zone-selective interlocking and maintenance-free vacuum interrupters.
- Commercial:Office, retail, and healthcare facilities procure standardized LV assemblies through electrical distributor channels with emphasis on space efficiency and ease of installation.
- Residential:Single-family and multi-family housing developers drive high-volume, low-margin demand for miniature circuit breakers and distribution boards.
Utilities represent the deepest specification expertise and longest replacement cycles; industrial end users are expanding procurement fastest through electrification and data center buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Virginia's data center corridor concentrates hyperscale procurement for 36 kV and 52 kV MV switchgear clusters supporting AI training loads exceeding 100 MW per facility.
United States
Hyperscale operators in Northern Virginia and Dallas-Fort Worth drive 52 kV switchgear procurement for AI data center electrification. The EPA maintains voluntary SF6 emission reduction partnerships while OSHA governs arc-energy containment standards. Texas petrochemical complexes specify LV assemblies with zone-selective interlocking and maintenance-free vacuum interrupters.
Germany
Transmission system operators synchronize replacement programs with EU F-Gas phase-down mandates for 12 kV to 52 kV installations. The ECHA administers harmonized CE marking protocols for vacuum and dry-air alternatives. Bavarian automotive manufacturing plants specify indoor MV switchgear with arc-flash containment and integrated condition monitoring systems.
China
State Grid Corporation drives demand for 11 kV and 33 kV ring-main units through national smart grid mission targets. The MIIT oversees GB standards alignment for vacuum interrupter endurance testing protocols. Yangtze River Delta manufacturing clusters absorb aluminum-silver hybrid conductor designs for cost-sensitive MV switchgear production.
India
The national smart grid mission and renewable integration targets create underpenetrated demand for 33 kV ring-main units across distribution networks. The CEA mandates technical standards for grid-connected switchgear under central electricity regulatory frameworks. Maharashtra and Gujarat industrial corridors specify LV assemblies for manufacturing electrification programs.
Japan
Tokyo metropolitan utilities deploy dry-air insulation systems in space-constrained urban substations where SF6 alternatives face footprint constraints. METI guides vacuum interrupter technology development through industrial policy coordination. Osaka-Kobe manufacturing clusters retain specialized ceramic metallization expertise for vacuum bottle production.
Low Voltage (LV) and Medium Voltage (MV) Switchgear Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated OEMs commanding premium positions in digital switchgear while component suppliers capture volume in standardized LV assemblies. The vendor base concentrates around three strategic archetypes: captive vacuum interrupter producers, modular platform architects, and backward-integrated electrical distributors. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers secure ceramic bottle supply and certify alternatives under revised IEC protocols.
Within the integrated technology tier, Schneider Electric, ABB, and Siemens AG exemplify distinct positioning archetypes. The French multinational occupies a position emphasizing backward integration into contactor manufacturing to protect margin pools across LV portfolios. The Swiss-Swedish group anchors European market presence through vacuum interrupter technology leadership. The German engineering conglomerate sits within digital switchgear platforms featuring integrated condition monitoring capabilities for predictive maintenance modules.
| Leading Market Players |
|---|
| Schneider Electric |
| ABB |
| Siemens AG |
| Eaton Corporation |
| Mitsubishi Electric Corporation |
| General Electric |
| Toshiba |
| Fuji Electric |
| Hyosung |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists across Germany and Japan anchor vacuum interrupter production, transmitting pricing discipline downstream through captive supply agreements with European switchgear OEMs. Their ownership structures resist short-term margin compression, reinforcing premium positioning for ceramic bottle assemblies while forcing cost-sensitive MV tiers toward aluminum-silver hybrid conductor designs.
Pricing Analysis
Short lead-time premiums command specification weight in German TSO procurement windows compressed by EU F-Gas compliance deadlines. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and volume scale, with IEC 62271-100 type-tested assemblies capturing margin pools above uncertified alternatives. Pricing pressure stems from copper spot-market volatility squeezing LV assembly margins. Data center operators exhibit lowest price sensitivity, prioritizing 36 kV cluster availability over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore orchestrate hub-and-spoke patterns for vacuum interrupter ceramic bottles sourced from Japan, Germany, and China. Raw material dependencies center on high-purity copper-chromium contact alloys, epoxy resin bushings, and aluminum-silver composite conductors. Single-source vulnerability concentrates in Osaka-Kobe metallization expertise for vacuum bottle production. Distribution runs through direct OEM relationships with hyperscale operators, bypassing traditional electrical distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around manufacturers with captive vacuum interrupter production, as IEC 62271-100 certification delays and EU F-Gas mandates force subscale competitors into exit or acquisition.
For Market Incumbents: Hedge against ceramic bottle supply disruption by securing dual-source agreements with Japanese and German metallization specialists. Expand backward integration into contactor manufacturing to protect LV margin pools from copper price volatility. Prioritize digital switchgear platform R&D to capture predictive maintenance premiums in German industrial electrification programs. For New Entrants and Emerging Players: Direct-to-utility digital channels offer white-space access in India's 33 kV ring-main unit segment, where national smart grid targets outpace local manufacturing capacity. Target Maharashtra and Gujarat industrial corridors with modular LV assemblies certified under CEA technical standards. Pursue joint venture structures with established vacuum interrupter suppliers to bypass 8-14 month IEC 62271-100 qualification barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap European switchgear specialists with stranded SF6 product lines facing EU F-Gas prohibition. Long-term viability hinges on vacuum technology transition completion within a 5-10 year technology replacement window. Monitor German TSO procurement acceleration as inflection indicator for sector-wide replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Interrupter Production | Captive ceramic bottle supply protects margin pools from East Asian single-source concentration risk. |
| Digital Switchgear Platform Development | Integrated condition monitoring commands specification premiums in German automotive manufacturing electrification. |
| CE Marking Certification for Air-Insulated Alternatives | ECHA harmonized protocols unlock procurement access across EU member state replacement programs. |
| Aluminum-Silver Hybrid Conductor Adoption | Cost-sensitive MV designs reduce material exposure while maintaining thermal performance standards. |
| Direct OEM Relationships with Hyperscale Operators | Bypassing distributor channels captures full margin on 52 kV clusters for Northern Virginia AI facilities. |
Research Methodology
Multi-period observation of EU F-Gas replacement cycle timing, vacuum interrupter lead times, and hyperscale data center power density escalation anchored the trend analysis, supplemented by interviews with transmission system operator planning officers, industrial plant engineers, OEM procurement teams, and aftermarket service heads. Secondary validation drew from IEC 62271-100 revision documentation, ECHA CE marking protocols, CEA technical standards filings, and customs data on ceramic bottle trade flows. Bottom-up project pipeline analysis triangulated against top-down grid investment forecasts.
Segment-weighting across product type, technology, installation context, and end-user category shaped volume and value outputs over the projection horizon. Modeled dimensions included voltage rating tier, insulation medium, enclosure specification, and regional regulatory cluster. CAGRs derived from utility capital expenditure trajectories, industrial electrification program commitments, and data center power density scaling curves.
Inputs from German TSO procurement disclosures and Indian smart grid mission documentation were available through the study window; gaps in Chinese State Grid vacuum interrupter inventory data introduce uncertainty bands around East Asian supply assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Fluid Power Cylinder Market
Valves
Wind Energy Fasteners Market
Valves
Bend Restrictors and Stiffeners Market
Valves
Float Traps Market
Valves
North America Industrial Valves Market
Valves
Thermal Power Valve Market
Valves
Europe Electro Hydraulic Servo Valve Market
Valves
Global Valves in Chemical Market
Valves
Hot Blast Valves Market
Valves
Pneumatic Positioner Market
Valves
Global Control Valves Market
Valves
Europe Butterfly Valve Market
Valves
Oil Drain Valves Market
Valves
Pipeline Equipment Market
Valves
North America High Voltage Switchgear Market
Valves
Top Drive Systems Market