
 Explosion Proof Solenoid Valves Market | 2026-2036
Explosion Proof Solenoid Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Explosion Proof Solenoid Valves Market Analysis
A scarcity of certified hazardous-area technicians is unwinding capacity expansion timelines across valve OEMs and system integrators. Emerson Electric Co. leverages its global service network to train and deploy explosion-protection specialists in key energy corridors. Parker Hannifin Corp. sustains engineering density through dedicated facilities in Houston and Rotterdam that focus solely on flameproof and intrinsically safe valve architectures. Danfoss competes by anchoring its North Sea and Middle East project teams with permanent ATEX-competent field engineers rather than subcontracted labor.
Explosion proof solenoid valves are electromechanically actuated flow control devices engineered with encapsulated coils, flameproof enclosures, and pressure-resistant sealing to contain internal ignition in explosive gas or dust atmospheres; they operate on 24V DC or 110V AC supply with IP66/67 ingress protection and T6 temperature class ratings, serving primarily to isolate or modulate process media in zones classified 1 or 21 under IEC 60079. Two-way valve configurations dominate installed base volumes due to their simplicity and lower unit cost, while three-way valve demand is accelerating in safety instrumented systems where redundant venting and exhaust functions consolidate into single valve bodies. Oil and gas end users command the largest margin pool because project specifications mandate third-party witnessed factory acceptance testing and full material traceability, both of which inflate pricing power for qualified suppliers.
ATEX directives, IECEx certification schemes, and OSHA 1910.307 electrical safety standards collectively dictate enclosure design, coil insulation grades, and documentation depth required for market access across Europe, international export markets, and United States industrial facilities. EPA risk management plan regulations and EU Seveso III directives further compel chemical processors to maintain spare valve inventories and documented maintenance intervals, sustaining aftermarket parts demand. Stakeholders must monitor how emerging hydrogen economy infrastructure codes revise ignition energy thresholds and material compatibility specifications for solenoid valve elastomers and housing alloys.
Market Dynamics
The explosion proof solenoid valves market is being reshaped by tightening certification requirements that force manufacturers to maintain parallel production lines for ATEX, IECEx, and OSHA-compliant variants, fragmenting economies of scale across regional supply chains.
Growth Catalysts
- Seveso III Directives:EU chemical processors must maintain documented spare valve inventories and preventive maintenance schedules, sustaining aftermarket demand for certified replacement units.
- Hydrogen Infrastructure Codes:Emerging ignition energy thresholds and material compatibility specifications for elastomers and housing alloys are creating specification upgrade cycles across refueling station projects in Germany and the Netherlands.
- Petrochemical Capacity Additions:Refinery upgrade investments in Texas, Louisiana, and the US Gulf Coast corridor are accelerating procurement of flameproof valve assemblies with witnessed factory acceptance testing.
Market Restraints
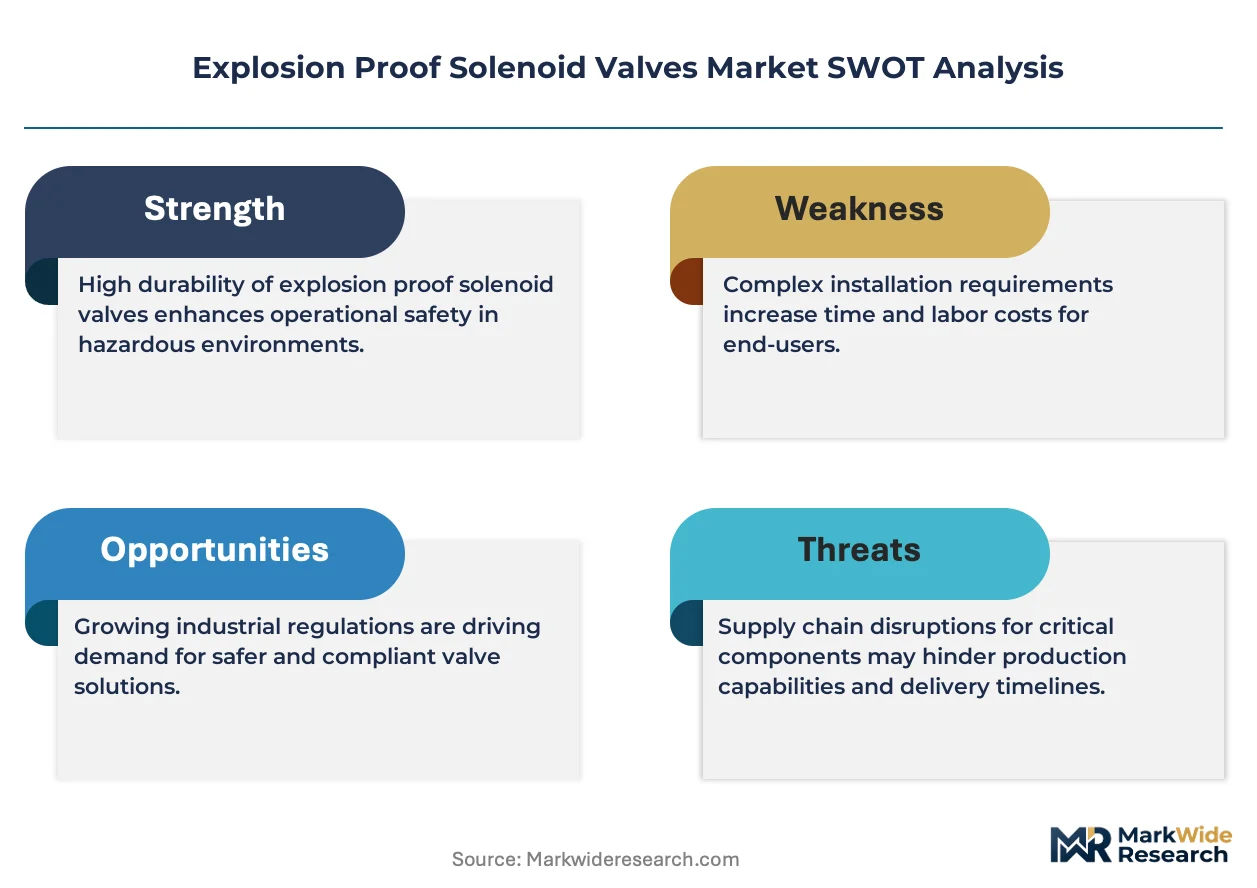
- Specialized Technician Scarcity:The limited pool of certified hazardous-area technicians extends commissioning timelines and inflates field service costs for valve OEMs and system integrators.
- Copper and Rare Earth Volatility:Encapsulated coil production depends on copper windings and neodymium magnets, exposing margin stability to commodity price swings in concentrated mining jurisdictions.
- Intrinsically Safe Alternatives:Low-power barrier-isolated valve actuators are displacing flameproof architectures in Zone 2 applications, compressing addressable market for traditional explosion proof designs.
Strategic Opportunities
- Green Hydrogen Electrolysis:Alkaline and PEM electrolyzer OEMs in Denmark and Spain require modified valve specifications for high-purity hydrogen service, opening new specification-setting relationships.
- Digital Twin Integration:Convergence of IIoT sensor packages with solenoid valve diagnostics enables predictive maintenance offerings that capture recurring revenue streams from chemical plant operators.
- Carbon Border Adjustment Mechanism:EU CBAM compliance documentation requirements favor suppliers with verifiable supply chain emissions data, creating first-mover advantage for certified low-carbon valve manufacturers.
Industry Challenges
- ATEX Competency Certification:The 18-24 month training pipeline for explosion-protection specialists constrains service network expansion and project staffing flexibility.
- Legacy System Integration:Safety instrumented systems in brownfield refineries require valve architectures compatible with 4-20mA analog loops, complicating adoption of digital communication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Explosion Proof Solenoid Valves Market |
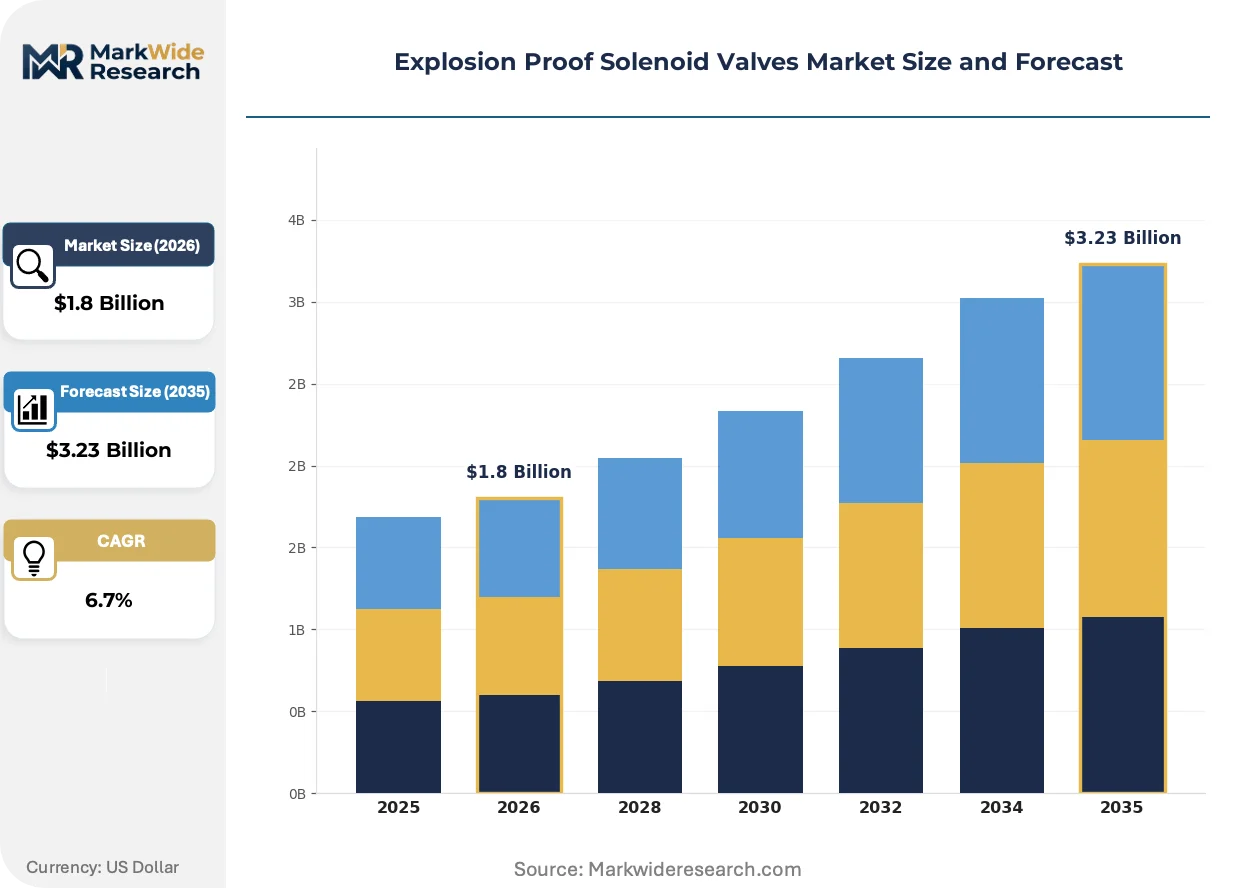
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Way Valve, Three-Way Valve, Positioner, Actuator End User: Oil & Gas, Chemical Processing, Pharmaceuticals, Food & Beverage Application: Control Systems, Safety Systems, Electrical Systems, Automated Systems Installation Type: Panel Mounted, Pipe Mounted, Surface Mounted, Wall Mounted |
| Companies Covered | Emerson Electric Co., Parker Hannifin Corp., Danfoss, Bosch Rexroth AG, ASCO, SMC Corporation, Festo, Kendrion, Christian Bürkert GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Explosion Proof Solenoid Valves Market Emerging Trajectories
Valve architectures are diverging along functional lines as end-users demand tighter integration between process control and safety systems, forcing suppliers to recalibrate R&D allocation between mechanical reliability and digital connectivity.
Advanced coil encapsulation using thermally conductive epoxy compounds is bifurcating the installed base. Offshore platform operators in the North Sea are specifying these materials for T6 temperature class ratings in compact enclosures. The technology is compressing demand for traditional oil-filled coil designs while enabling valve downsizing in space-constrained skid packages.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are compelling seal material transitions. Fluorocarbon elastomer suppliers must validate replacement compounds for explosive atmosphere compatibility. German chemical processors are front-loading qualification testing to avoid supply discontinuity when PFAS limitations tighten in 2026.
Integrated procurement of valve assemblies with pre-terminated cable harnesses is displacing field-wired installations. EPC contractors on Middle East petrochemical projects are mandating this configuration to reduce hazardous-area wiring labor. The practice is most visible in lump-sum turnkey contracts where schedule certainty outweighs unit cost premiums.
Explosion Proof Solenoid Valves Market Segmentation
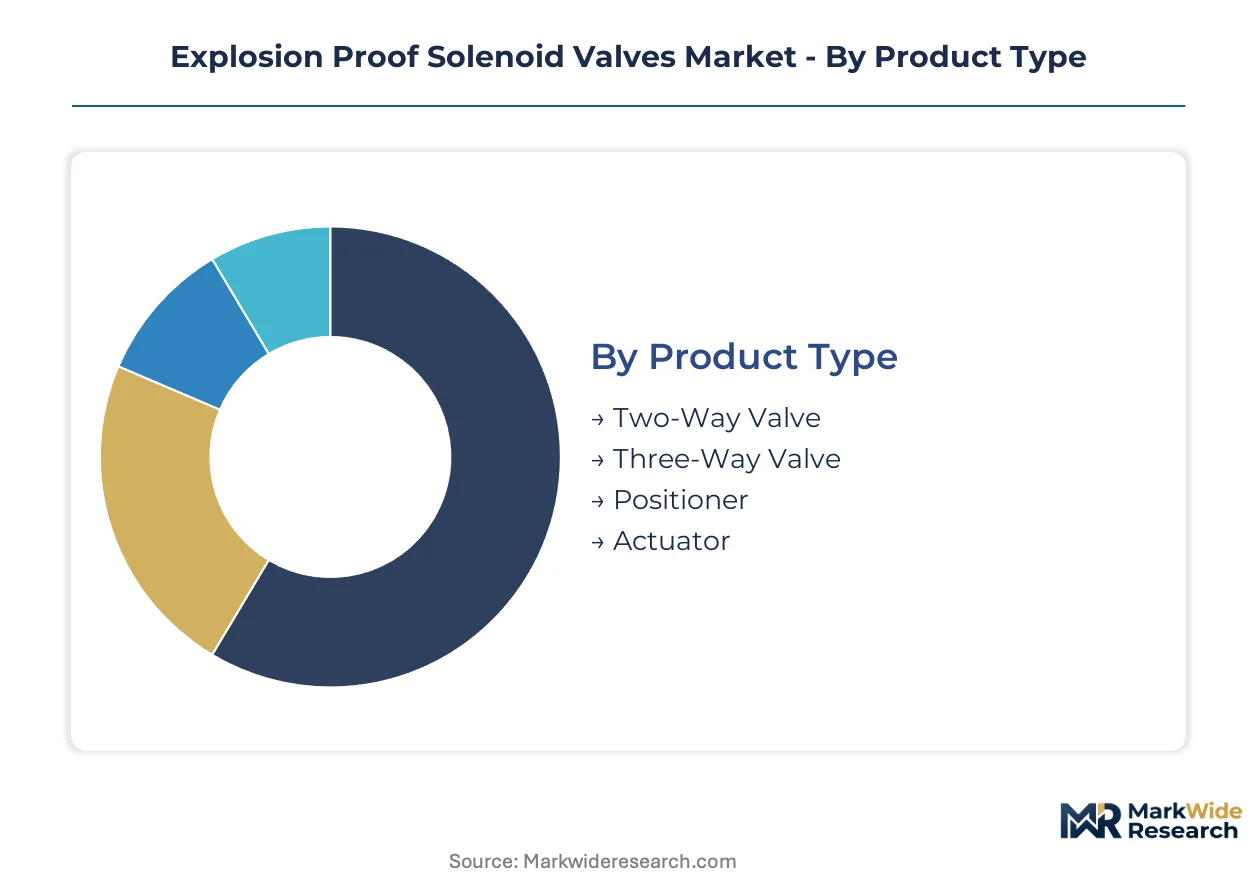
Explosion proof solenoid valve procurement channels diverge sharply by segment. Project-based EPC contractors dominate safety systems and oil and gas applications, while MRO distributors capture recurring demand from chemical processors and food manufacturers maintaining spare valve inventories.
Product Type:
Channel economics favor simpler configurations through distribution, while engineered solutions move through direct OEM engagement with witnessed factory acceptance testing.
- Two-Way Valve:Simple on/off flow isolation with single inlet and outlet port. German petrochemical expansions and US Gulf Coast refinery upgrades concentrate demand for certified two-way units with full material traceability. By volume, two-way valves lead. By growth pace, three-way configurations are climbing the fastest.
- Three-Way Valve:Integrates redundant venting and exhaust functions into single valve bodies for safety instrumented systems. Alkaline and PEM electrolyzer OEMs in Denmark and Spain are specifying modified three-way architectures for high-purity hydrogen service.
- Positioner:Digital valve positioners with 4-20mA feedback loops enable precise flow modulation in brownfield refinery retrofits.
- Actuator:Pneumatic and electromechanical actuators provide torque output for larger valve sizes in offshore platform installations.
Direct sales penetration runs deepest where witnessed testing and ATEX documentation complexity exceed distributor technical capabilities.
End User:
Margin structures stratify by regulatory exposure and documentation burden, with chemical and oil and gas commanding premium pricing for certified compliance packages.
- Oil & Gas:Upstream, midstream, and downstream operators mandate third-party witnessed factory acceptance testing and full material traceability. Middle East lump-sum turnkey contractors are mandating pre-terminated cable harness configurations to reduce hazardous-area wiring labor.
- Chemical Processing:EU Seveso III directives and EPA risk management plans compel documented maintenance intervals and spare valve inventories. German processors are front-loading seal material qualification to avoid supply discontinuity when REACH PFAS limitations tighten.
- Pharmaceuticals:Batch process isolation and clean-in-place systems require sanitary valve configurations with surface finishes meeting ASME-BPE standards.
- Food & Beverage:Hygienic design priorities and frequent washdown cycles favor stainless steel enclosures with IP69K ingress protection ratings.
Oil and gas commands the largest margin pool. Pharmaceuticals is expanding most quickly as bioprocessing capacity adds explosion-proof requirements.
Application:
Functional segmentation tracks the convergence between process control and safety systems, with integrated procurement blurring traditional category boundaries.
- Control Systems:Continuous process modulation in refining and chemical operations. North Sea offshore platforms are specifying thermally conductive epoxy coil encapsulation for T6 temperature ratings in compact skids.
- Safety Systems:Emergency shutdown and venting functions in safety instrumented systems. Hydrogen refueling station projects in the Netherlands are driving specification upgrades for ignition energy thresholds.
- Electrical Systems:Power distribution isolation in hazardous-area electrical enclosures.
- Automated Systems:IIoT-enabled predictive maintenance integration with digital twin platforms.
Control systems anchor current installed base volumes. Safety systems are gaining share fastest as functional safety standards tighten.
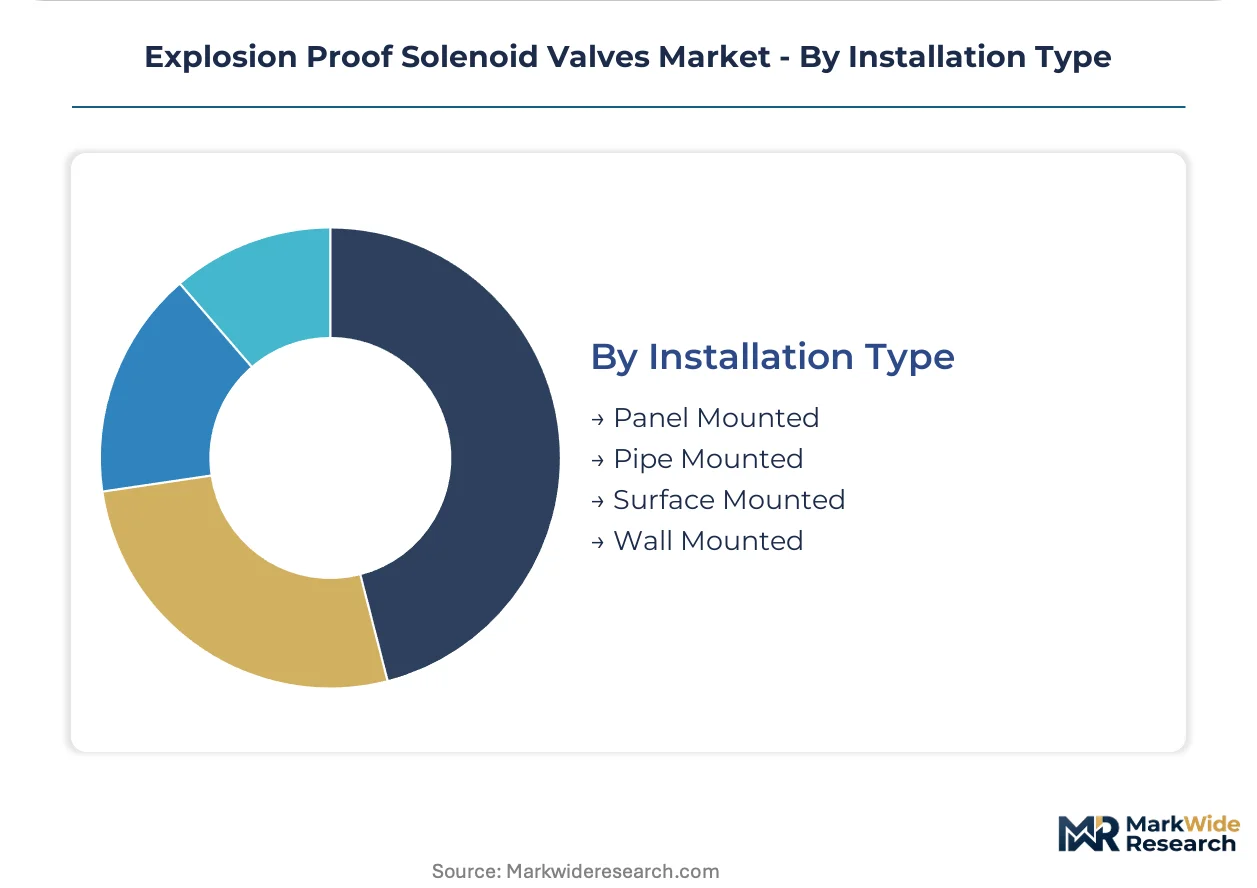
Installation Type:
Mounting configuration selection reflects space constraints, accessibility requirements, and wiring topology preferences across greenfield and brownfield projects.
- Panel Mounted:Centralized control cabinet integration for distributed control system architectures. Houston and Rotterdam engineering facilities focus flameproof and intrinsically safe valve architectures on panel-mounted configurations for space-constrained offshore modules.
- Pipe Mounted:Direct inline installation with process piping eliminates additional enclosure requirements. US Gulf Coast EPC contractors favor pipe-mounted assemblies in lump-sum contracts where schedule certainty outweighs unit cost premiums.
- Surface Mounted:Flat-surface attachment for auxiliary equipment and instrument air systems.
- Wall Mounted:Vertical surface installation in compressor stations and utility buildings.
Pipe mounted dominates greenfield construction. Panel mounted is expanding most quickly as modular skid packages gain favor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical processors stock explosion proof solenoid valves for Seveso III compliance, while US Gulf Coast refineries prioritize witnessed factory acceptance testing. Chinese petrochemical expansions emphasize ATEX documentation depth for export qualification.
Germany
Green hydrogen electrolyzer OEMs in Bavaria and North Rhine-Westphalia specify modified valve architectures for high-purity hydrogen service. REACH Annex XVII PFAS restrictions compel front-loaded seal material qualification by chemical processors in Ludwigshafen and Leverkusen. The country's national chemical regulator enforces documented maintenance intervals under Seveso III directives.
United States
Texas and Louisiana refinery upgrades accelerate procurement of flameproof valve assemblies with third-party witnessed testing. OSHA 1910.307 electrical safety standards dictate enclosure design and coil insulation grades for hazardous-area installations. Houston engineering facilities concentrate flameproof and intrinsically safe valve architecture development.
China
Petrochemical capacity additions in Jiangsu and Zhejiang provinces drive ATEX and IECEx certification procurement for export-qualified valve assemblies. GB standards and MIIT regulations shape domestic explosion-protection product qualification thresholds. Yangtze River Delta valve OEMs maintain parallel production lines for regional and international certification variants.
Netherlands
Hydrogen refueling station projects in Rotterdam and Amsterdam drive specification upgrades for ignition energy thresholds and elastomer compatibility. EU Seveso III directives sustain aftermarket demand for certified replacement units in chemical processing clusters. The Port of Rotterdam petrochemical complex mandates pre-terminated cable harness configurations to reduce hazardous-area wiring labor.
Saudi Arabia
Middle East lump-sum turnkey contractors specify explosion proof solenoid valve assemblies with full material traceability for downstream petrochemical projects. The country's national industrial regulator aligns hazardous-area equipment standards with IECEx certification schemes. Jubail Industrial City concentrates demand for flameproof valve configurations in refinery and chemical processing installations.
Explosion Proof Solenoid Valves Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the explosion proof solenoid valves market. The upper tier maintains global service networks and dedicated engineering facilities for flameproof and intrinsically safe architectures. Mid-scale specialists compete through ATEX-competent field engineering teams anchored to regional energy corridors. Dominant competitive moves include certification portfolio diversification across ATEX, IECEx, and OSHA variants, plus geographic expansion through permanent field engineering presence rather than subcontracted labor.
Among diversified industrial conglomerates, Emerson Electric Co. and Parker Hannifin Corp. exemplify the integrated archetype through global service infrastructure. Danfoss occupies a position within the specialist tier, representing the regional engineering-density model. Bosch Rexroth AG and SMC Corporation sit within the automation-focused segment, anchoring competitive positioning around electromechanical system integration rather than standalone valve supply.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Parker Hannifin Corp. |
| Danfoss |
| Bosch Rexroth AG |
| ASCO |
| SMC Corporation |
| Festo |
| Kendrion |
| Christian Bürkert GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
Fourteen-to-eighteen-week lead times for ATEX-certified coil assemblies concentrate pricing power with German and Chinese OEMs possessing in-house encapsulation lines. Buyers without long-term offtake commitments face spot-market premiums during petrochemical project surges.
Pricing Analysis
Project-based contracting dominates procurement for oil and gas applications, with lump-sum turnkey EPC contracts bundling witnessed factory acceptance testing and full material traceability into unit pricing. Price differentiation separates OEMs with permanent ATEX-competent field engineers from distributors relying on subcontracted labor. Cost compression in standard two-way valves is intensifying because Chinese manufacturers are expanding IECEx-certified capacity for export markets. Chemical processors under Seveso III mandates exhibit lowest price sensitivity due to compliance-driven replacement schedules.
Supply Chain Analysis
Copper winding supply from Chile and neodymium magnet dependence on Chinese rare earth processing create dual chokepoints for encapsulated coil production. Valve housing alloys draw from German specialty steel mills and Chinese stainless foundries. Single-source vulnerability concentrates in thermally conductive epoxy compounds qualified for T6 temperature ratings. Distribution runs through authorized distributors for MRO replacement demand and direct OEM engagement for greenfield project specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The explosion proof solenoid valves market is recovering from a cyclical trough as petrochemical capacity additions in the US Gulf Coast and German hydrogen infrastructure projects reactivate capital deployment.
For Market Incumbents: Secure permanent ATEX-competent engineering teams in Rotterdam and Houston to defend against intrinsically safe actuator substitution in Zone 2 applications. Deepen backward integration into copper winding production to offset commodity volatility from Chilean concentrate supply. Certification portfolio diversification across OSHA 1910.307 and emerging hydrogen codes protects margin pools.
For New Entrants and Emerging Players: Aftermarket service gaps in Middle East lump-sum turnkey contracts where incumbent response times extend commissioning schedules present white-space entry points. Target green hydrogen electrolyzer OEMs in Denmark and Spain with modified three-way valve architectures for high-purity hydrogen service. Lead with pre-terminated cable harness configurations to reduce hazardous-area wiring labor.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because tightening ATEX and IECEx certification thresholds create durable moats around qualified suppliers. Acquisition candidates with captive epoxy encapsulation capabilities and documented spare valve inventory relationships with EU chemical processors offer defensive positioning. Monitor hydrogen infrastructure code revisions for ignition energy threshold adjustments as inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| ATEX Competency Certification Investment | Eighteen-to-twenty-four-month training pipelines constrain service network expansion for valve OEMs. |
| Backward Integration into Coil Encapsulation | In-house thermally conductive epoxy compound production insulates margin stability from qualified-material scarcity. |
| Hydrogen Service Specification Development | Alkaline and PEM electrolyzer OEMs in Denmark require modified elastomer compatibility validation. |
| Digital Twin Integration Partnership | IIoT sensor convergence with valve diagnostics enables predictive maintenance recurring revenue from chemical operators. |
| Pre-terminated Cable Harness Configuration | Middle East EPC contractors mandate this to reduce hazardous-area wiring labor in lump-sum contracts. |
Methodological Framework
Desk research of IECEx equipment certification databases, EPA risk management plan filings, and EU Seveso III regulatory guidance preceded structured interviews with valve OEM product managers, EPC contractor procurement leads, and chemical plant maintenance directors. Primary fieldwork with ATEX-competent field engineers and hazardous-area system integrators in Houston, Rotterdam, and Jubail Industrial City validated secondary trade flow data. Bottom-up unit demand estimates triangulated against top-down petrochemical capacity addition announcements.
Variance decomposition across product type, end-user industry, and installation configuration dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate blending weighted by margin pool contribution. Hydrogen infrastructure code revision timelines and REACH Annex XVII PFAS restriction implementation schedules served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in ATEX directives and OSHA electrical safety standards; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as hydrogen ignition energy thresholds and copper commodity volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Pipeline Equipment Market
Valves
Pneumatic Slide Gates Market
Valves
Lined Valves Market
Valves
Air Jet Ejectors Market
Valves
Reciprocating Compressor Components Market
Valves
Explosion Isolation Valves Market
Valves
Europe Industrial Valves Market
Valves
Pipeline Integrity Management (PIM) Market
Valves
Emergency Shutdown Valves Market
Valves
Global Plug Valve Market
Valves
Pipeline Strainers Market
Valves
Deluge Valve Market
Valves
Ball Valves Market
Valves
Battery Safety Valve Market
Valves
Rupture Discs Market
Valves
Liner Regulators Market