
 Curb Valves Market | 2026-2036
Curb Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Curb Valves Market Insights
Project finance tied to municipal water infrastructure bonds is tilting competitive access toward suppliers with balance-sheet capacity to carry long-dated receivables. Mueller Co. leverages its vertically integrated foundry network to control lead times on ductile iron castings. AVK Group anchors its position through dedicated waterworks distribution partnerships across North American utilities.
Curb valves are quarter-turn or multi-turn shutoff devices installed at the property line between water mains and service lines, typically rated for working pressures between 150 and 300 psi with threaded, flanged, or mechanical joint end connections; they enable emergency isolation, meter servicing, and leak containment without main-line disruption. Brass-bodied gate valves dominate municipal specifications due to corrosion resistance and lead-free compliance, while stainless steel ball valves are gaining share in industrial facility applications where chemical compatibility requirements are tightening. Below-ground installation types command premium positioning because of the engineering complexity involved in waterproofing, traffic-load certification, and cathodic protection integration.
The EPA enforces lead-free standards under Section 1417 of the Safe Drinking Water Act, which directly determines material eligibility for federal funding participation; AWWA C800 standards govern curb stop dimensions, operating nut configurations, and test protocols that manufacturers must satisfy for utility approval. State-level regulators such as the California State Water Resources Control Board layer additional certification requirements that fragment market access rules. Stakeholders must monitor how infrastructure spending authorization timelines interact with evolving lead-free alloy specifications to align inventory and R&D commitments.
Market Dynamics
Municipal water infrastructure renewal programs are compressing replacement cycles for below-ground brass installations, while EPA lead-free mandates under the Safe Drinking Water Act are forcing material upgrades across distribution networks. This regulatory-material tension is concentrating procurement authority among utilities with bond-financed capital programs.
Growth Catalysts
- AWWA C800 Standards:Municipal specifications for curb stop dimensions and operating nut configurations create compliance-driven replacement demand across US water utilities.
- Lead-Free Alloys:Section 1417 of the Safe Drinking Water Act mandates material eligibility for federal funding participation, accelerating brass body upgrades.
- California State Water Resources Control Board:Layered certification requirements beyond federal standards fragment market access and create premium positioning for certified suppliers.
Market Restraints
- Copper-Zinc Alloy Volatility:Brass input costs fluctuate with copper commodity markets, compressing margin visibility for foundry-dependent manufacturers.
- Below-Ground Engineering Complexity:Waterproofing, traffic-load certification, and cathodic protection integration extend development timelines and qualification costs.
- Substitution by Stainless Steel Ball Valves:Industrial facility applications are pivoting toward stainless steel alternatives where chemical compatibility requirements are tightening.
Strategic Opportunities
- Smart Valve Integration:Convergence of IoT sensors with quarter-turn shutoff mechanisms enables remote leak detection and pressure monitoring for utility asset management.
- Service Line Replacement Programs:Aging lead service line inventories in Midwest and Northeast US states create concentrated demand pockets for compliant curb valve installations.
- Direct Utility Partnerships:Bypassing traditional waterworks distributors through municipal procurement portals captures margin from disintermediated channel structures.
Industry Challenges
- Lead-Free Alloy R&D Timeline:Evolving EPA specifications for acceptable lead content in wetted surfaces force continuous reformulation and retesting cycles.
- Legacy Mechanical Joint Compatibility:New valve designs must integrate with century-old cast iron distribution infrastructure without compromising seal integrity.
- Qualified Foundry Capacity:Specialized brass casting expertise for potable water applications concentrates among a limited supplier base, constraining volume scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Curb Valves Market |
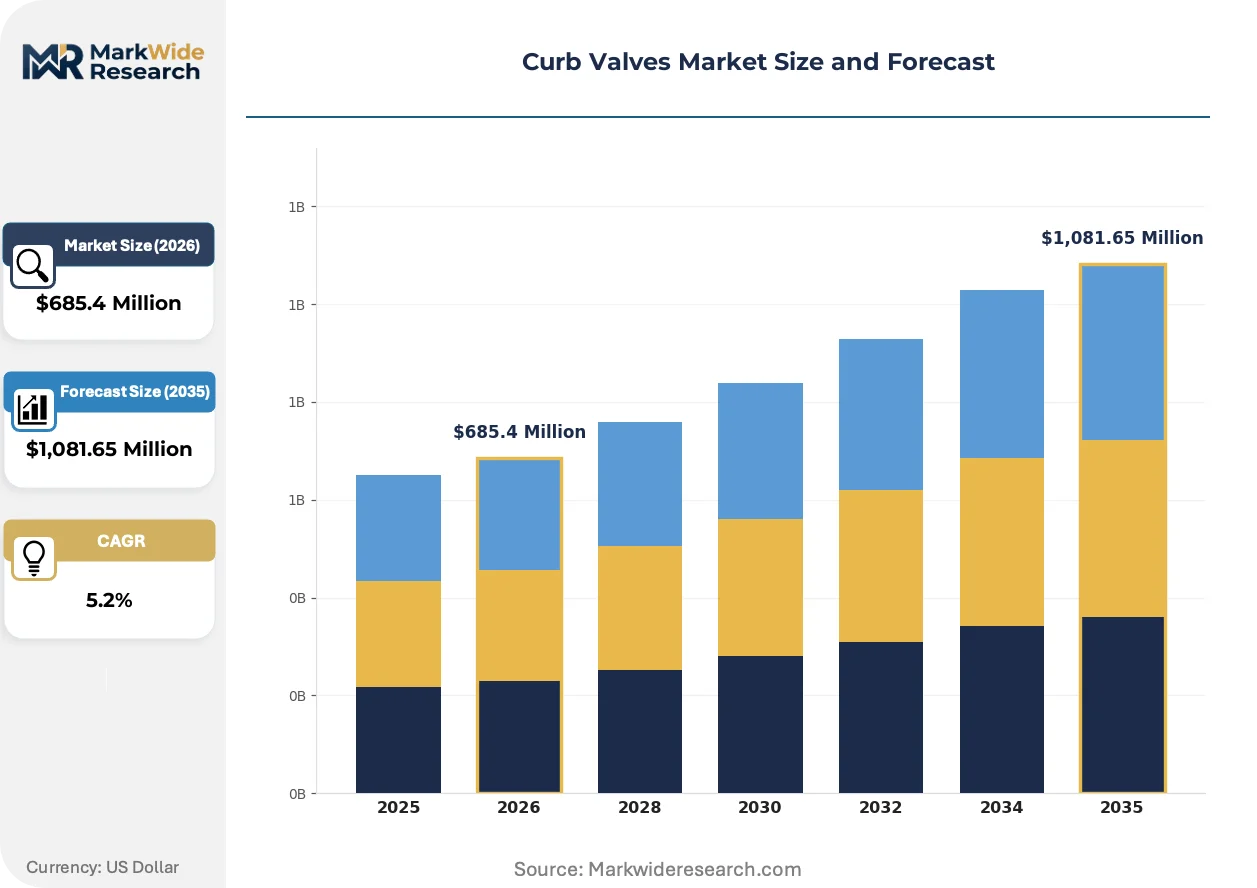
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gate Valve, Butterfly Valve, Check Valve, Ball Valve Installation Type: Above Ground, Below Ground, Directly Buried, System Integrated Material: Brass, PVC, Stainless Steel, Ductile Iron End User: Municipalities, Industrial Facilities, Residential Properties, Agricultural Operations |
| Companies Covered | Mueller Co., Ford Meter Box Co. Inc., AVK Group, Cla-Val, EJ, A.Y. McDonald Mfg. Co., Singer Valve, Kennedy Valve, AS-SUR Industrial Valve Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Curb Valves Market Trends and Innovations
Material science advances and digital infrastructure integration are converging to reshape how curb valves are specified, manufactured, and maintained across municipal water systems.
Corrosion-resistant lead-free brass alloys with bismuth or silicon substitutions are collapsing the performance gap between traditional leaded brass and higher-cost stainless steel alternatives. Water utilities in the US Great Lakes region are specifying these alloys for new installations at accelerating rates. This material transition is compressing the addressable market for stainless steel ball valves in municipal applications while expanding brass valve lifecycle economics.
EPA enforcement of Section 1417 lead-free standards is tightening material traceability requirements throughout the supply chain. Manufacturers must now document alloy composition through third-party certification to maintain utility approval status. Brass valve producers are responding by integrating spectrographic testing into foundry quality protocols and locking multi-year copper supply contracts to guarantee compliance continuity.
Asset management platforms are unbundling valve replacement decisions from reactive maintenance schedules. Large municipal utilities are adopting predictive analytics that prioritize curb valve replacement based on pressure fluctuation data and adjacent main break history. This behavioral shift is most visible in California and Texas water districts, where capital planning cycles now synchronize valve procurement with smart meter deployment timelines.
Curb Valves Market Segmentation
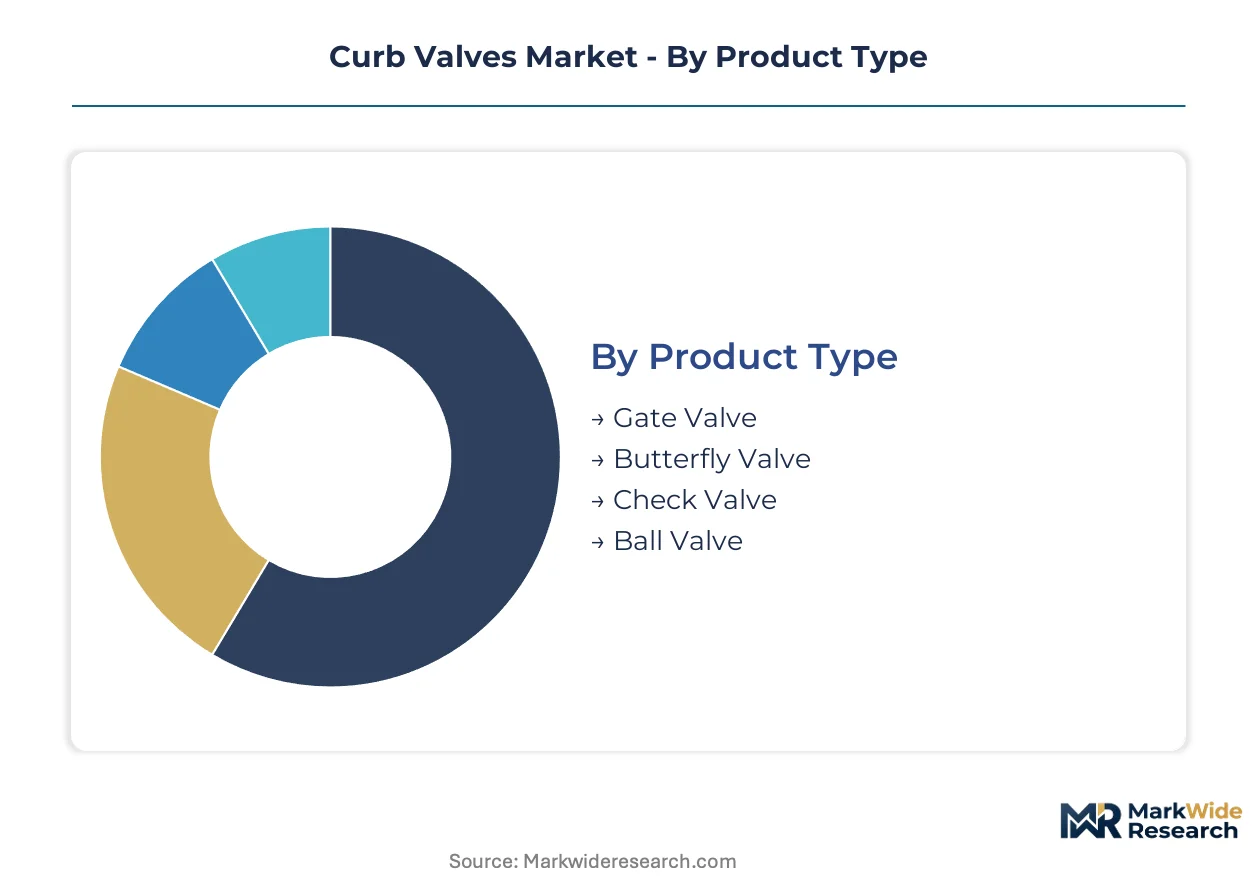
Curb valve procurement patterns diverge sharply across installation contexts and material specifications, with replacement cycles ranging from decades for buried brass infrastructure to years for above-ground industrial applications. Understanding these segment dynamics clarifies where inventory investments and certification efforts generate the highest returns.
Product Type:
Gate valves turn over slowest due to below-ground permanence, while ball valves cycle faster in accessible industrial settings where chemical exposure accelerates wear.
- Gate Valve:Linear-motion shutoff devices with wedge-shaped discs seal against fluid pressure in fully open or closed positions. Municipal water utilities in the US Midwest specify these for service line isolation where century-old cast iron mains require compatible mechanical joint interfaces.
- Ball Valve:Quarter-turn spherical closure elements deliver tight shutoff with minimal operating torque. Industrial facilities across Texas chemical corridors favor stainless steel variants for rapid isolation during process upsets, though brass configurations penetrate municipal specifications as lead-free alloys improve.
- Butterfly Valve:Rotating disc mechanisms suit large-diameter transmission mains where space constraints favor compact actuation profiles.
- Check Valve:Passive flow-direction devices prevent backflow contamination in dual-feed distribution zones.
Gate valve specifications anchor the volume base while ball valve configurations gain share at the steepest rate.
Installation Type:
Cost structures stratify sharply, with below-ground installations commanding engineering premiums that above-ground alternatives cannot capture.
- Below Ground:Direct-buried assemblies with traffic-load certification and cathodic protection integration dominate municipal capital programs. California water districts specify these for lead service line replacements where EPA funding eligibility requires full encapsulation.
- Above Ground:Exposed installations in industrial facilities permit faster access for maintenance but sacrifice freeze protection and vandalism resistance.
- Directly Buried:Shallow-set configurations without vault structures reduce first cost in low-traffic residential zones.
- System Integrated:Pre-assembled valve-meter assemblies streamline utility meter changeout operations.
Below-ground installations capture the highest unit margins while directly buried configurations expand most quickly in cost-constrained programs.
Material:
Volume concentrates in brass specifications where lead-free compliance unlocks federal infrastructure dollars, while stainless steel commands industrial premiums.
- Brass:Copper-zinc alloys with bismuth or silicon substitutions satisfy Safe Drinking Water Act Section 1417 requirements for wetted surfaces. AWWA C800-certified brass castings from US Great Lakes foundries supply the majority of municipal curb stop replacements.
- Stainless Steel:Austenitic grades resist aggressive chemistries in industrial process water loops. Food and beverage processors across Wisconsin specify 316L ball valves for clean-in-place compatibility.
- PVC:Thermoplastic constructions serve irrigation and non-potable applications where pressure ratings permit.
- Ductile Iron:High-strength ferrous castings anchor large-diameter transmission valve bodies.
Brass specifications dominate municipal procurement volumes while stainless steel climbs fastest in industrial facility retrofits.
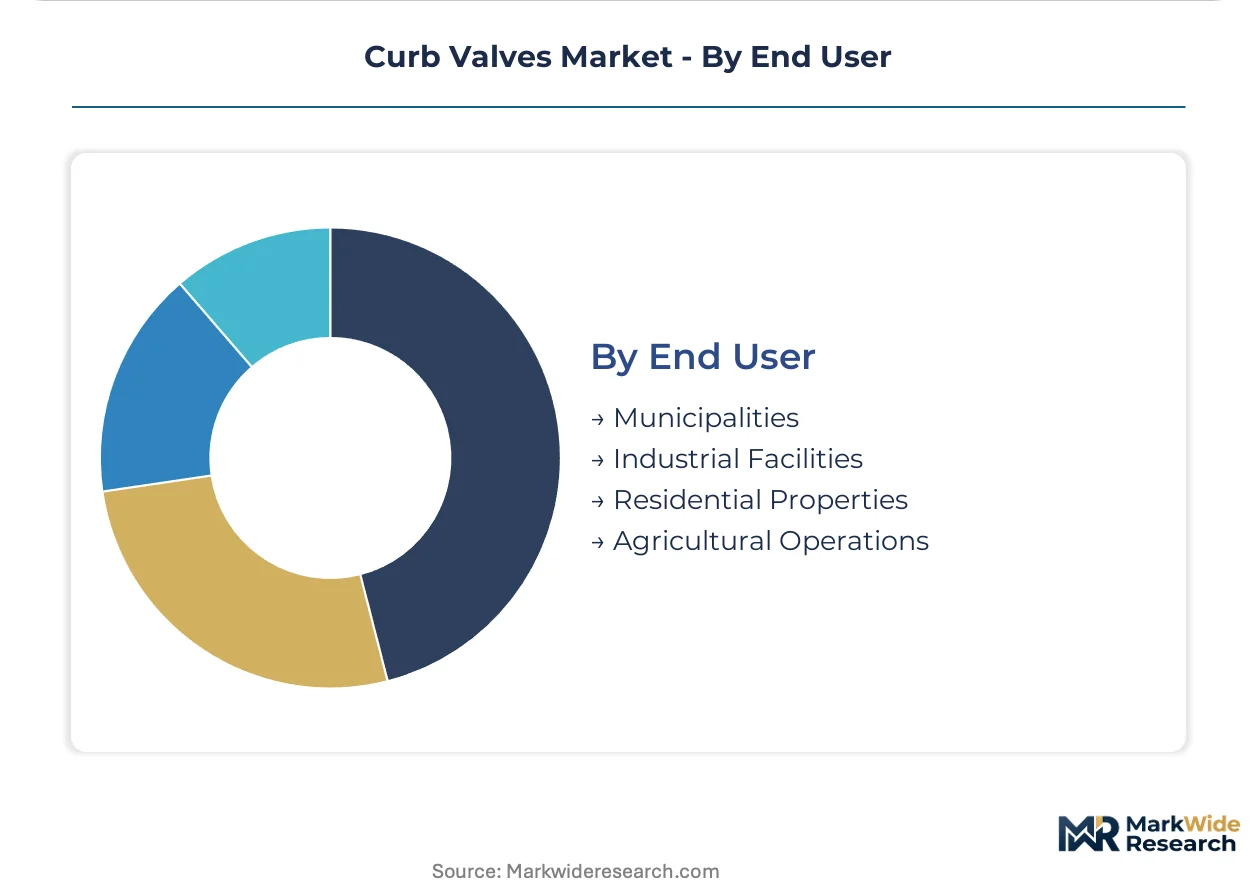
End User:
Customer concentration varies from fragmented residential service lines to consolidated municipal capital programs with multi-year visibility.
- Municipalities:Bond-financed water utilities consolidate procurement authority through master service agreements with pre-qualified manufacturers. EPA infrastructure grants accelerate replacement cycles in legacy lead service line corridors.
- Industrial Facilities:Process water users specify chemical-compatible materials with documented traceability for FDA or USDA compliance.
- Residential Properties:Individual service line replacements generate sporadic demand through contractor channels.
- Agricultural Operations:Irrigation districts prioritize low-cost PVC or ductile iron specifications for non-potable distribution.
Municipal procurement anchors the revenue base while industrial facility upgrades expand at the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA infrastructure grants and Safe Drinking Water Act enforcement are accelerating curb valve procurement across municipal water systems, with regional demand patterns tracking federal funding disbursements and lead service line replacement mandates.
United States
Midwest and Northeast states concentrate aging lead service line inventories requiring full replacement cycles. EPA Section 1417 lead-free mandates determine material eligibility for federal infrastructure dollars. Chicago and Detroit water districts drive below-ground brass valve demand through bond-financed capital programs targeting century-old distribution networks.
Canada
Municipal water utilities in Ontario and Quebec prioritize corrosion-resistant alloys for harsh freeze-thaw cycling conditions. Health Canada guidelines on lead in drinking water parallel EPA standards, creating compliance-driven upgrade cycles. Toronto's water infrastructure renewal program anchors procurement volume for AWWA C800-certified installations.
Germany
Industrial facility upgrades in the Ruhr and Rhine-Ruhr regions specify stainless steel ball valves for chemical process water loops. REACH regulations on substance restrictions influence material selection for wetted surfaces. Bavarian water technology clusters develop smart valve integration for predictive asset management platforms.
China
Rapid urbanization in the Yangtze River Delta and Pearl River Delta drives municipal water distribution expansion. GB standards for potable water equipment establish domestic certification requirements for valve manufacturers. Shanghai's water utility modernization program imports AWWA-compliant brass specifications for high-pressure service line applications.
Australia
Drought-resilient water infrastructure investments in New South Wales and Victoria accelerate smart metering and valve integration projects. TGA-adjacent water quality frameworks emphasize material traceability for potable system components. Sydney Water's digital asset management platform prioritizes IoT-enabled curb valves for leak detection networks.
Curb Valves Market Competitive Landscape
Channel-controlling players compete with product-specialist players across municipal procurement portals and waterworks distribution networks. The vendor base organizes into three tiers: vertically integrated foundry operators with captive brass casting capacity, regional assemblers sourcing certified components, and smart technology integrators layering sensors onto mechanical platforms. Dominant competitive moves include backward integration into lead-free alloy supply chains and direct utility partnerships that disintermediate traditional distributors.
Within the foundry-integrated tier, Mueller Co. and AVK Group exemplify archetypes of scale-driven manufacturers with in-house casting capabilities. Among North American specialists, Ford Meter Box Co. Inc. and A.Y. McDonald Mfg. Co. occupy positions tied to AWWA certification depth and municipal specification authority. Kennedy Valve and Singer Valve represent the technology-forward segment where smart valve integration converges with traditional quarter-turn mechanisms.
| Leading Market Players |
|---|
| Mueller Co. |
| Ford Meter Box Co. Inc. |
| AVK Group |
| Cla-Val |
| EJ |
| A.Y. McDonald Mfg. Co. |
| Singer Valve |
| Kennedy Valve |
| AS-SUR Industrial Valve Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
US Great Lakes foundry clusters anchor brass casting capacity for curb valve production, concentrating upstream supply leverage among vertically integrated manufacturers who translate captive alloy supply into pricing power over municipal procurement cycles.
Pricing Analysis
Certification level (AWWA C800/EPA Section 1417-compliant) creates the primary spread between premium and standard tiers. Contract-based long-term offtake dominates municipal procurement, with price differentiation resting on lead-free alloy grade and foundry proximity to reduce freight costs. Cost compression in standard brass configurations is intensifying because copper-zinc commodity volatility squeezes margin visibility. Small regional assemblers exhibit highest price sensitivity, while bond-financed utilities prioritize certification continuity over unit cost.
Supply Chain Analysis
Copper concentrate from Chile and Peru feeds US Great Lakes smelters, while bismuth and silicon alloy additives source from China and Canada. Raw material dependencies center on copper cathode, zinc ingot, and certified lead-free alloy formulations. Single-source vulnerability concentrates in specialized potable-water foundry capacity. Distribution runs through waterworks distributors and direct municipal procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA lead service line replacement mandates are accelerating below-ground brass valve adoption, positioning this market as an early-cycle expansion story where infrastructure funding disbursements outpace historical replacement rates.
For Market Incumbents: Harden AWWA C800 certification depth against emerging stainless steel substitutes by locking multi-year copper supply contracts and expanding spectrographic testing protocols. Defensive consolidation should prioritize foundry capacity in Midwest states where lead service line inventories concentrate, insulating against qualified casting supply shortages. For New Entrants and Emerging Players: Build out smart valve integration capabilities targeting California and Texas water districts where predictive asset management platforms prioritize IoT-enabled installations. The most penetrable white space sits in direct utility partnerships that bypass traditional waterworks distributors, with go-to-market traction through municipal procurement portals. For Investors and Strategic Acquirers: Long-term, this sits as a regulated infrastructure replacement play because EPA enforcement timelines and federal funding authorization create multi-year demand visibility. Acquisition targets should concentrate on foundry-integrated specialists with captive lead-free alloy supply. The signal to watch is infrastructure spending authorization velocity relative to qualified foundry capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lead-Free Alloy Supply | Captive bismuth-silicon alloy production secures EPA Section 1417 compliance continuity for municipal contracts. |
| Smart Valve Sensor Integration | IoT pressure monitoring aligns with California water district predictive analytics procurement requirements. |
| Direct Utility Partnership Development | Municipal procurement portal access captures margin from disintermediated waterworks distribution channels. |
| AWWA C800 Certification Expansion | Extended certification depth opens bond-financed capital program participation in Midwest legacy corridor replacements. |
| Multi-Year Copper Supply Contracting | Locked concentrate supply insulates against copper-zinc commodity volatility compressing foundry margins. |
Research Methodology
Desk research of AWWA technical standards, EPA regulatory filings, and municipal bond disclosure documents preceded structured interviews with water utility procurement directors, foundry operations managers, and waterworks distribution channel heads. Primary fieldwork with brass valve manufacturers and secondary validation through customs trade data and utility capital improvement plans enabled bottom-up and top-down triangulation across product type, installation configuration, material specification, and end-user segments.
Assumptions held infrastructure spending authorization timelines and lead-free alloy specifications fixed while varying copper commodity price scenarios and municipal procurement cycle intensity across the analysis window. Segmentation dimensions modeled include valve mechanism type, burial depth configuration, brass versus stainless steel material grade, and utility versus industrial end-use. CAGRs derived from replacement cycle frequency analysis weighted by EPA funding eligibility and service line age demographics, with copper input cost trajectories and foundry capacity utilization as industry-specific forecast inputs.
Sensitivities concentrate around infrastructure spending authorization delays, lead-free alloy specification revisions, and qualified foundry capacity constraints. Forecasts reflect these assumptions with acknowledged uncertainty from regulatory enforcement timing and commodity price volatility. Quarterly review of municipal bond issuance velocity and EPA grant disbursement rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Middle East and Africa Machined Seals Market
Valves
Mechanical Shaft Seal Market
Valves
Instrumentation Valves and Fittings Market
Valves
Global Marine Actuators and Valves Market
Valves
Emergency Venting System Market
Valves
Safety Valve Market
Valves
Reciprocating Compressor Components Market
Valves
Asia-Pacific Medium Voltage Switchgear Market
Valves
Middle East and Africa Industrial Valves Market
Valves
North America Residential Ball Valves Market
Valves
Steam Trap Valve Market
Valves
Tank Hydrogen Valve Market
Valves
Large Bore Vacuum Insulated Pipe Market
Valves
Backflow Preventers Market
Valves
Fin Tube Market
Valves
Global Compression Packing Market