
 Instrumentation Valves and Fittings Market | 2026-2036
Instrumentation Valves and Fittings Market Size, Share, and Industry Trends Forecast 2026-2036
Instrumentation Valves and Fittings Market Intelligence
EPA methane performance standards for oil and gas infrastructure are shifting the cost-of-entry calculus toward certified low-emission valve designs. Swagelok leverages its captive forging capacity to sustain margin control across stainless steel needle valve lines. Parker Hannifin anchors North American distribution through its broad instrumentation portfolio. Fujikin Incorporated specializes in ultra-high purity fittings for semiconductor fabrication, competing on material traceability rather than volume scale.
Instrumentation valves and fittings are precision-engineered flow control devices manufactured from stainless steel, brass, or engineered plastics to withstand pressures exceeding 10,000 psi in process analytical and fluid handling systems. These components maintain system integrity by enabling isolation, regulation, and directional control of gases and liquids in critical industrial loops. Ball valves and needle valves lead product type revenue due to their ubiquity in sampling and calibration skids, while stainless steel dominates material selection for corrosion resistance in sour gas environments. Threaded connections retain the largest share across maintenance-intensive sectors, though welded configurations are gaining traction in power generation where leak-tight permanence is mandated.
FDA sanitary standards for pharmaceutical processing equipment and OSHA process safety management requirements for highly hazardous chemicals both elevate specification stringency for end users. The EU F-Gas Regulation and REACH compliance frameworks restrict certain sealing materials, redirecting European procurement toward perfluoroelastomer-qualified suppliers. Stakeholders must monitor evolving fugitive emissions testing protocols and material substitution timelines to avoid stranded inventory positions.
Market Dynamics
EPA methane performance standards are compressing specification timelines for oil and gas infrastructure, forcing procurement departments to prioritize certified low-emission designs over legacy catalog selections.
Growth Catalysts
- Chemical processing expansion:Gulf Coast petrochemical corridor operators are accelerating instrumentation upgrades to support ethane cracker commissioning and derivative unit expansions.
- REACH material restrictions:ECHA's phased limitations on fluorinated sealing compounds are redirecting European buyers toward perfluoroelastomer-qualified suppliers with established compliance documentation.
- Semiconductor fabrication scale-up:Ultra-high purity fitting demand from advanced node wafer facilities is creating specification premiums for material traceability and surface finish certification.
Market Restraints
- Nickel alloy input volatility:Hastelloy and Inconel price swings compress margin predictability for severe-service valve manufacturers serving sour gas applications.
- Forging capacity concentration:Captive stainless steel forging operations cluster in select North American and East Asian supplier networks, limiting second-source options during demand spikes.
- Welding qualification bottlenecks:ASME Section IX certification timelines for orbital welding procedures extend project delivery schedules in power generation installations.
Strategic Opportunities
- Hydrogen infrastructure buildout:Electrolyzer and fueling station projects require 10,000+ psi-rated components with embrittlement-resistant metallurgy, opening premium specification tiers.
- Biopharma single-use integration:Stainless steel-to-disposable hybrid skids demand specialized sanitary valve configurations with rapid changeover capabilities.
- Carbon capture injection networks:Supercritical CO2 transport specifications are creating demand for dense-phase rated fittings with enhanced crack-arrest properties.
Industry Challenges
- Orbital welding technician scarcity:Qualified automated pipe welders for high-purity semiconductor and pharmaceutical systems command premium wages and extended recruitment cycles.
- Dual certification complexity:Simultaneous FDA sanitary and EPA fugitive emissions compliance requires overlapping documentation trails that strain quality management bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instrumentation Valves and Fittings Market |
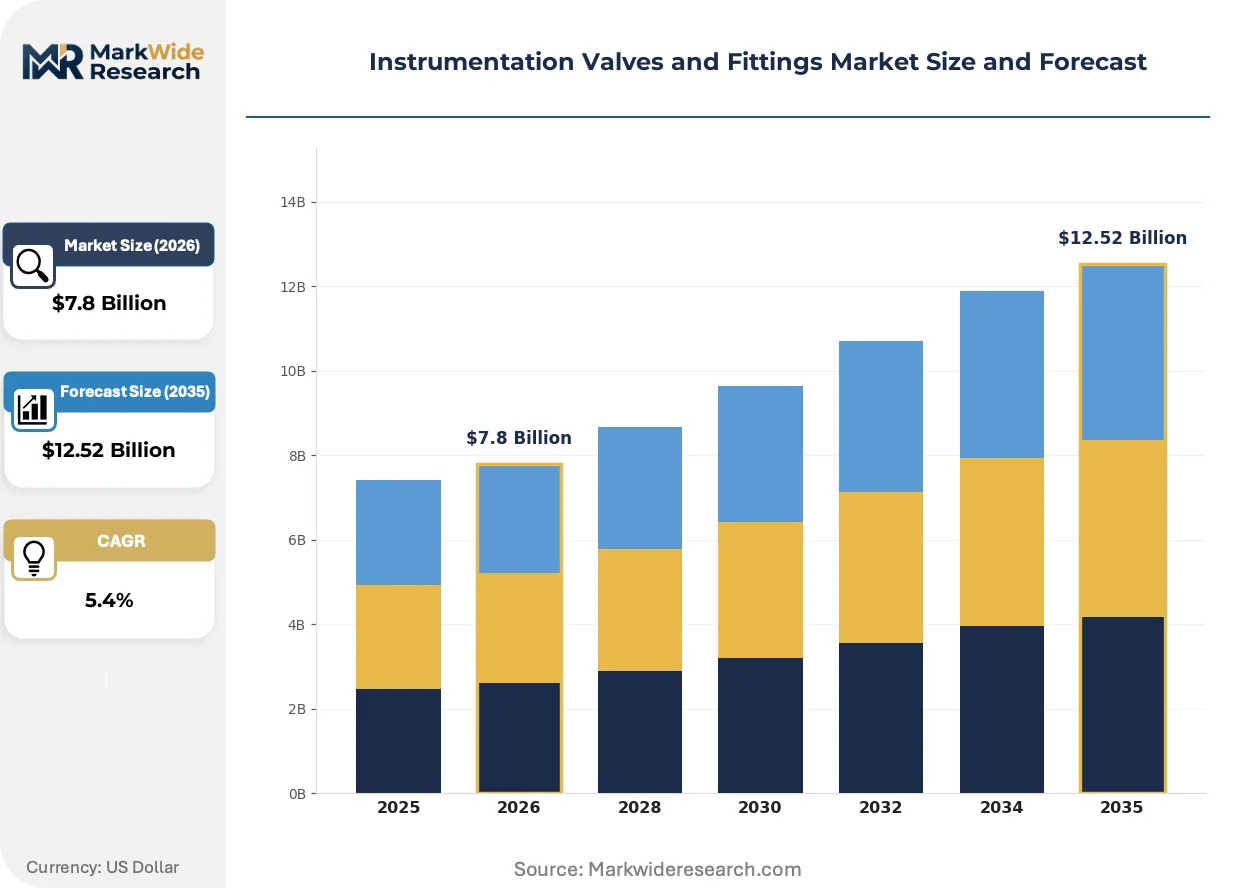
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valves, Gate Valves, Check Valves, Needle Valves Material: Stainless Steel, Brass, Plastic, Carbon Steel End User: Oil & Gas, Chemical Processing, Water Treatment, Power Generation Connection Type: Threaded, Welded, Flanged, Clamp |
| Companies Covered | Parker Hannifin, Swagelok, CIRCOR International, Hy-Lok Corporation, Ham-Let, AS-Schneider, SSP Fittings Corporation, Fujikin Incorporated, Hex Valve, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instrumentation Valves and Fittings Market Strategic Shifts & Innovations
Electrification of valve actuation and sensing is merging process control with power distribution architectures, compressing the traditional separation between mechanical and electrical specification teams.
Smart valve positioners with embedded diagnostics are electrifying maintenance workflows in offshore platforms and remote pipeline stations. Operators in the North Sea and Permian Basin are deploying these units to shift from calendar-based to condition-based intervention schedules. The technology is electrifying aftermarket service revenue models toward predictive analytics subscriptions.
The EU F-Gas Regulation's phasedown schedule is forcing refrigeration and semiconductor process cooling systems toward lower-global-warming-potential sealing materials. Equipment OEMs are qualifying graphite and thermoplastic alternatives for applications previously dominated by PTFE compounds. European pharmaceutical and chemical processors are absorbing qualification costs ahead of 2030 material availability deadlines.
Specification consolidation among engineering-procurement-construction firms is compressing vendor lists to suppliers with multi-site stocking agreements and integrated CAD-to-order capabilities. Major EPCs serving LNG and hydrogen projects are demanding single-source accountability for instrumentation packages spanning multiple pressure classes. This concentration is most pronounced in Texas and Louisiana project corridors where contractor prequalification gates have tightened.
Instrumentation Valves and Fittings Market Segmentation
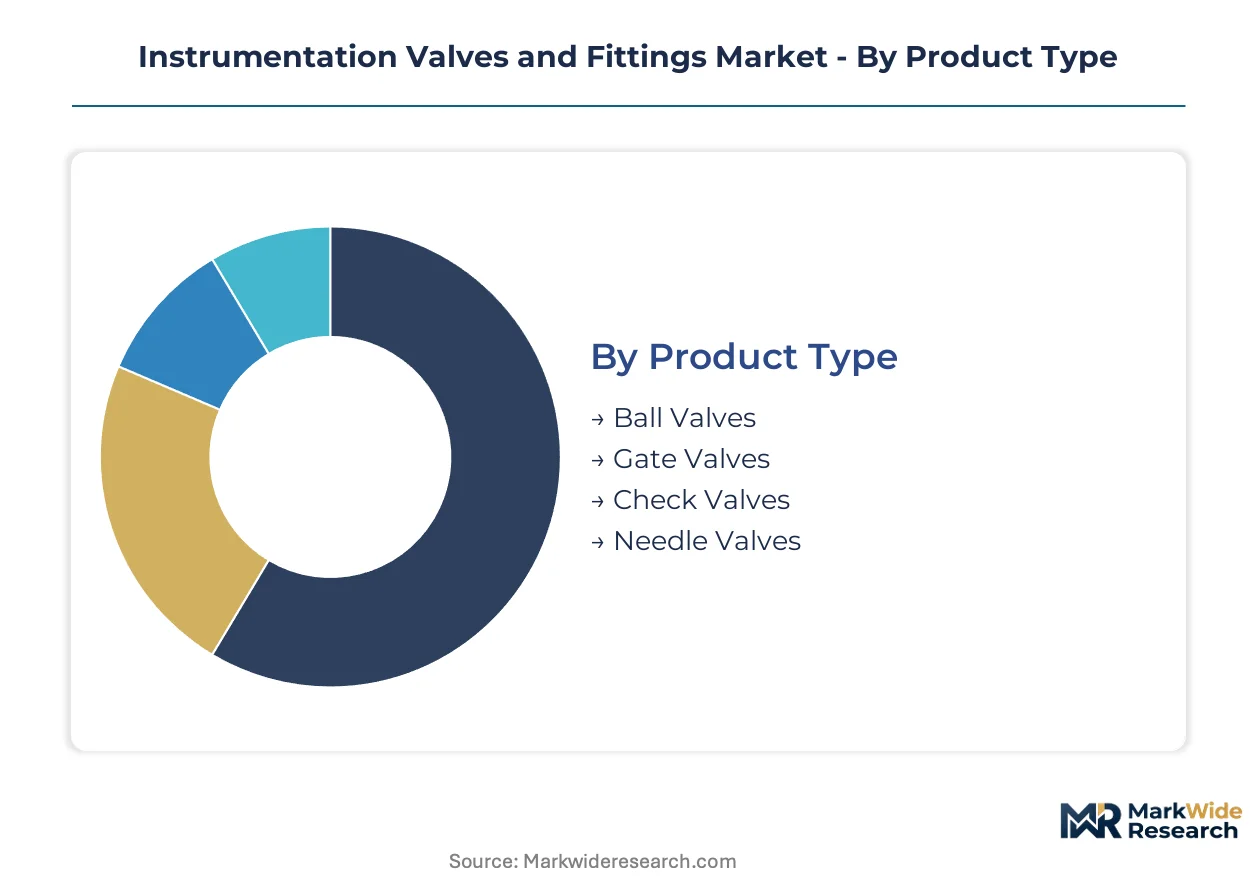
Precision instrumentation markets fragment across pressure ratings, material specifications, and connection geometries that dictate procurement workflows. Each segmentation axis carries distinct supplier qualifications, lead time structures, and margin profiles that shape competitive positioning.
Product Type:
Ball and needle valve production concentrates in captive forging networks across Texas, Ohio, and Osaka, constraining second-source availability during demand surges.
- Ball Valves:Quarter-turn isolation devices engineered for bubble-tight shutoff at pressures exceeding 10,000 psi in sampling and calibration skids. Demand clusters in US Gulf Coast ethane cracker projects where rapid cycling durability reduces maintenance turnaround frequency.
- Needle Valves:Fine-threaded stem designs enabling precise flow modulation in analytical instrumentation and pressure gauge isolation loops. Semiconductor fabrication facilities in Hsinchu and Pyeongtaek specify these for ultra-high purity gas distribution where particle generation must stay below Class 1 thresholds.
- Gate Valves:Linear-motion shutoff devices for full-bore, low-pressure-drop applications in bulk fluid transfer lines.
- Check Valves:Spring-loaded or swing-type configurations preventing backflow in compressor discharge and pump outlet piping.
Today's leader: Ball Valves. Tomorrow's challenger: Needle Valves.
Material:
Raw material cost tiers stratify procurement budgets, with nickel alloy premiums compressing margins for severe-service applications.
- Stainless Steel:Austenitic and duplex grades dominating sour gas environments where hydrogen sulfide corrosion resistance is mandatory. US Permian Basin operators specify 316L and 6Mo superaustenitic grades for wellhead instrumentation exposed to brine and CO2 mixtures.
- Brass:Lead-free alloys for low-pressure pneumatic and potable water systems where cost sensitivity outweighs corrosion exposure.
- Plastic:PVDF and PTFE-lined configurations for aggressive chemical media where metallic contamination risks batch integrity.
- Carbon Steel:ASTM A105 and A350 LF2 forgings for high-pressure hydrocarbon service in upstream production manifolds.
Stainless Steel commands volume leadership. Plastic formulations are climbing the fastest on semiconductor and biopharma qualification timelines.
End User:
Customer concentration patterns vary sharply, with chemical processing procurement consolidating through EPC frameworks while power generation retains fragmented utility-level specification authority.
- Oil & Gas:Upstream, midstream, and downstream installations requiring fugitive emissions certification under EPA methane performance standards. Major integrated operators in the Permian and Bakken fields are retrofitting wellhead instrumentation with low-leak valve designs ahead of compliance deadlines.
- Chemical Processing:Petrochemical, specialty chemical, and agrochemical facilities with dual pressure-temperature requirements. Ethane cracker expansions along the US Gulf Coast are driving instrumentation package orders for derivative unit feedstock control.
- Water Treatment:Municipal desalination and industrial wastewater facilities specifying NSF-certified materials for potable and process water contact.
- Power Generation:Combined cycle, nuclear, and renewable hydrogen turbine installations requiring ASME Section III and B31.1 code compliance for steam and feedwater systems.
Chemical Processing anchors current procurement volume. Power Generation holds the steepest expansion trajectory on hydrogen turbine and carbon capture injection project pipelines.
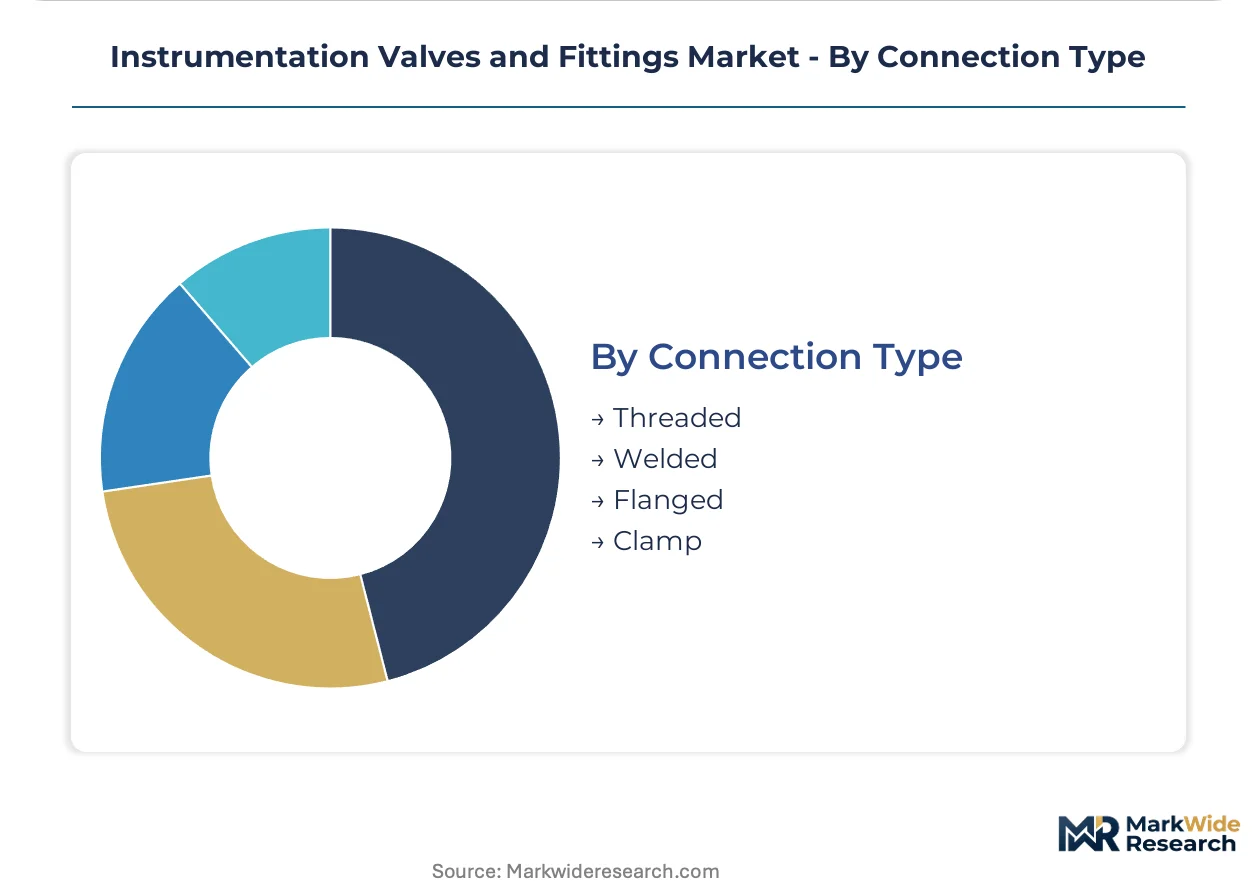
Connection Type:
Installation labor intensity and leak-tight permanence requirements drive specification divergence between maintenance-accessible and permanent-weld applications.
- Threaded:NPT and BSPP tapered connections dominating maintenance-intensive sectors where field disassembly is routine. Offshore platform instrumentation in the North Sea favors these for replacement accessibility in congested module layouts.
- Welded:Socket-weld and butt-weld configurations for leak-tight permanence in power generation and high-purity systems. ASME Section IX orbital welding qualification bottlenecks extend project schedules for nuclear and semiconductor facilities.
- Flanged:ASME B16.5 and API 6A flanged connections for high-pressure large-bore isolation in process piping headers.
- Clamp:Tri-clamp and DIN 32676 sanitary fittings for pharmaceutical and food processing equipment requiring rapid clean-in-place disassembly.
Threaded connections retain installed base dominance. Welded configurations are gaining share fastest on permanence mandates in hydrogen infrastructure and advanced node semiconductor facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled orbital welding technicians cluster in Houston, Osaka, and Rotterdam, anchoring regional supply capabilities for high-integrity instrumentation systems. Their geographic concentration shapes where precision fabrication capacity expands and where project timelines face bottlenecks.
United States
Ethane cracker commissioning along the Texas and Louisiana Gulf Coast drives instrumentation package demand for derivative unit feedstock control. EPA methane performance standards force Permian Basin operators to retrofit wellhead equipment with certified low-emission designs ahead of compliance deadlines. Houston anchors North American distribution networks with captive stainless steel forging capacity concentrated in Ohio and Texas supplier networks.
Germany
Chemical processing equipment OEMs in the Rhine-Ruhr corridor absorb qualification costs for REACH-compliant sealing materials ahead of 2030 deadlines. ECHA phased limitations on fluorinated compounds redirect procurement toward perfluoroelastomer-qualified suppliers with established documentation trails. BASF Ludwigshafen complex instrumentation upgrades exemplify specification stringency for dual FDA sanitary and fugitive emissions compliance.
China
Advanced node semiconductor fabrication in Hsinchu and Shanghai creates specification premiums for ultra-high purity fittings with material traceability certification. MIIT industrial upgrading programs accelerate domestic valve manufacturer qualification for 10,000 psi-rated hydrogen infrastructure components. Yangtze River Delta petrochemical complexes concentrate demand for sour gas-resistant superaustenitic stainless steel instrumentation.
Japan
Ultra-high purity gas distribution systems in Kyushu and Tohoku wafer facilities specify needle valves for particle generation control below Class 1 thresholds. METI hydrogen society roadmaps stimulate electrolyzer project demand for embrittlement-resistant metallurgy at extreme pressure ratings. Osaka-based captive forging operations constrain second-source availability during demand spikes for precision stainless steel components.
South Korea
Pyongtaek and Yongin semiconductor clusters drive qualification timelines for surface finish certification on ultra-high purity fittings. MFDS pharmaceutical equipment standards elevate specification stringency for sanitary valve configurations with rapid clean-in-place capabilities. Busan-Ulsan petrochemical corridor instrumentation upgrades support ethylene derivative unit expansions with severe-service valve requirements.
Instrumentation Valves and Fittings Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered specification bands. The vendor base stratifies between scale-driven distributors with multi-site stocking agreements and captive forging operators controlling margin structures. Three archetypes dominate: integrated instrumentation portfolio houses, ultra-high purity specialists competing on material traceability, and severe-service manufacturers with nickel alloy expertise. Capacity expansion and strategic partnerships constitute the dominant competitive moves as EPC prequalification gates tighten.
Among North American fabricators, Parker Hannifin and Swagelok occupy positions across the premium specification tier, with CIRCOR International representing the diversified industrial conglomerate archetype. These companies exemplify contrasting strategic postures: captive forging integration versus broad distribution anchoring. Their positioning reflects how procurement consolidation among engineering-procurement-construction firms compresses vendor lists toward suppliers with integrated CAD-to-order capabilities and multi-site accountability.
| Leading Market Players |
|---|
| Parker Hannifin |
| Swagelok |
| CIRCOR International |
| Hy-Lok Corporation |
| Ham-Let |
| AS-Schneider |
| SSP Fittings Corporation |
| Fujikin Incorporated |
| Hex Valve |
| Others |
Cost & Logistics Intelligence
Nickel alloy ingot costs cascade through three pricing tiers before reaching end-user procurement desks, with Hastelloy and Inconel premiums compressing margins for severe-service manufacturers while captive forging operators in Ohio and Texas retain pricing power on stainless steel needle valve lines.
Pricing Analysis
Bundled aftermarket service contracts separate premium suppliers from transactional catalog competitors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and geographic delivery cost differentials. Price erosion runs through economy-tier brass fittings as Asian imports intensify competition. Chemical processing EPCs demonstrate lowest price sensitivity due to specification stringency, while municipal water treatment procurement shows highest elasticity.
Supply Chain Analysis
Domestic-content mandates in US hydrogen infrastructure projects and South Korean semiconductor fab expansions are redirecting sourcing toward qualified local forging networks. Captive stainless steel forging capacity clusters in the United States, Japan, and Germany. Supply chains draw from nickel ore processing in Indonesia, specialty steel production in Austria, and precision machining in Taiwan. Single-source vulnerability concentrates around Osaka-based forging operations. Distribution runs through engineering-procurement-construction firms with multi-site stocking agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with EPA methane performance standards and REACH material restrictions forcing procurement toward certified premium specifications that resist commodity price competition.
For Market Incumbents: Cement market position by deepening captive forging integration in Texas and Ohio supplier networks against nickel alloy input volatility. Prioritize dual FDA-EPA certification investment to capture specification premiums in biopharma single-use integration projects. Lock EPC prequalification status through integrated CAD-to-order capabilities before vendor list compression accelerates.
For New Entrants and Emerging Players: Capture white-space in hydrogen infrastructure electrolyzer projects requiring 10,000+ psi-rated components with embrittlement-resistant metallurgy. Target carbon capture injection networks in the US Gulf Coast corridor where dense-phase rated fitting specifications outpace incumbent qualification timelines. Lead with orbital welding technician training partnerships to bypass ASME Section IX certification bottlenecks.
For Investors and Strategic Acquirers: Consolidation pressure builds where EPC vendor list compression eliminates sub-scale distributors lacking multi-site accountability. Five-to-ten-year viability favors pure-play ultra-high purity specialists with semiconductor material traceability certification over diversified industrial conglomerates. Watch hydrogen turbine project pipelines as inflection signal for premium specification tier expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Forging Capacity Expansion | Swagelok's Ohio stainless steel operations demonstrate margin control against nickel volatility. |
| Dual Certification Investment | Simultaneous FDA sanitary and EPA fugitive emissions compliance opens biopharma-chemical crossover demand. |
| Orbital Welding Technician Training | ASME Section IX qualification bottlenecks in nuclear and semiconductor sectors create service revenue premiums. |
| Perfluoroelastomer Material Qualification | ECHA REACH phased limitations redirect European procurement toward compliant sealing suppliers. |
| Hydrogen Infrastructure Component Development | Electrolyzer and fueling station projects require embrittlement-resistant metallurgy at extreme pressure ratings. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers, EPC procurement leads, aftermarket service heads, and technical R&D directors at valve manufacturers with secondary validation through EPA regulatory filings, ASME code documentation, ECHA REACH substance databases, and customs trade records. Bottom-up segment sizing and top-down macro anchoring were cross-referenced for triangulation.
Segment-weighted modeling distributed value and volume across product type, material specification, end-use industry, connection geometry, and regional production hub dimensions throughout the forecast period. CAGRs were derived from fitted trend extrapolation against announced capacity expansion timelines and regulatory compliance deadlines. Hydrogen infrastructure project pipelines and semiconductor fab buildout schedules served as industry-specific demand inputs.
Raw material price volatility, regulatory timeline delays, and skilled technician availability are the dominant revision risks to forecast assumptions. Model boundaries exclude speculative technologies not yet qualified for 10,000+ psi service. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Static Seals Market
Valves
Christmas Tree Valves Market
Valves
North America Butterfly Valve Market
Valves
Mooring Inspection Market
Valves
Low Voltage (LV) and Medium Voltage (MV) Switchgear Market
Valves
Asia-Pacific Industrial Valves Market
Valves
Servo Valves Market
Valves
Pipeline Pigging Valves Market
Valves
Vacuum Insulated Pipe Market
Valves
Mobile Hydraulic Valves Market
Valves
Mechanical Shaft Seal Market
Valves
Curb Valves Market
Valves
3-Way Pilot Operated Directional Control Valves Market
Valves
North America High Voltage Switchgear Market
Valves
Safety Valve Test Benches Market
Valves
Battery Safety Valve Market