
 Host Cell Protein Testing Market | 2026-2036
Host Cell Protein Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Host Cell Protein Testing Market Outlook
Aftermarket service revenue for legacy ELISA platforms is narrowing as pharma customers migrate to integrated mass spectrometry workflows. Thermo Fisher Scientific Inc. leverages its Orbitrap installed base to anchor high-margin consumables pull-through. Bio-Rad Laboratories, Inc. competes through specialized ddPCR reagents for residual DNA quantification. Cygnus Technologies, LLC dominates the polyclonal antibody niche with proprietary coverage libraries against CHO and E. coli host cell proteins.
Host cell protein testing encompasses analytical methods that detect and quantify process-related impurities originating from the cellular expression system used to manufacture recombinant biologics. These impurities comprise thousands of endogenous proteins with molecular weights spanning 10 to 250 kDa, whose co-purification can trigger immunogenic responses in patients; manufacturers deploy orthogonal detection strategies to demonstrate clearance below regulatory thresholds across downstream purification trains. Mass spectrometry reagents are capturing the fastest margin expansion as multi-attribute methods displace single-analyte ELISA for release testing. Contract Research Organizations represent the most concentrated demand growth vector among end users, outsourcing analytical development to specialized providers rather than building in-house mass spectrometry competency.
FDA enforces host cell protein limits through ICH Q6B guidelines, while EMA's MDR framework extends purity verification requirements to novel cell therapy manufacturing platforms. The country's national pharmaceutical regulator in India, CDSCO, now mandates HCP documentation for biosimilar filings, tightening market access for imported reference products. Stakeholders must monitor how regulators harmonize mass spectrometry acceptance criteria across jurisdictions before committing capital to multi-platform analytical suites.
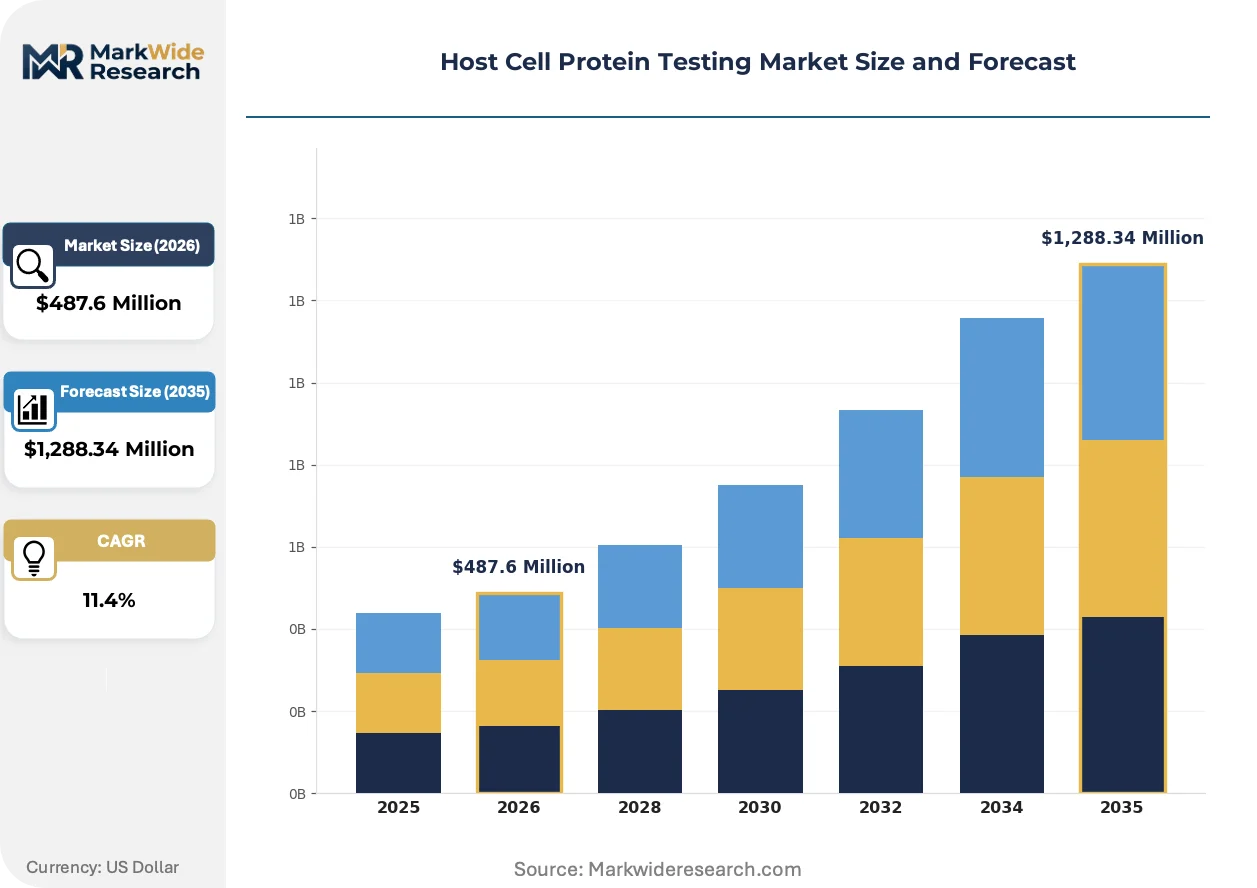
Market Dynamics
The migration from ELISA to mass spectrometry-based multi-attribute methods is compressing testing timelines while elevating capital requirements for analytical suites. Biopharmaceutical manufacturers face simultaneous pressure from FDA's ICH Q6B enforcement and EMA's MDR purity mandates, forcing orthogonal detection strategies across downstream purification trains.
Growth Catalysts
- EMA MDR Framework:Extended purity verification requirements to novel cell therapy manufacturing platforms, compelling manufacturers to validate clearance below regulatory thresholds.
- CDSCO Mandates:India's national pharmaceutical regulator now requires HCP documentation for biosimilar filings, tightening market access for imported reference products.
- Mass Spectrometry Workflows:Contract development and manufacturing organizations invest heavily in analytical validation capacity to satisfy multi-jurisdictional release testing demands.
Market Restraints
- High-Purity Solvent Costs:Mass spectrometry reagent-grade solvents and isotopically labeled standards command premium pricing, elevating per-test consumables spend.
- Antibody Supply Concentration:Proprietary coverage libraries against CHO and E. coli host cell proteins remain concentrated among specialized polyclonal antibody suppliers.
- Cross-Reactivity Limitations:ELISA platforms struggle with HCP subset detection where antibody coverage gaps persist, forcing redundant orthogonal validation.
Strategic Opportunities
- Process Analytical Technology Convergence:Integration of at-line mass spectrometry with chromatography systems enables real-time HCP clearance monitoring during downstream processing.
- CDSCO Biosimilar Pathway:India's tightening documentation requirements create demand for validated reference standard kits among domestic contract research organizations.
- Specialized CRO Channel:Outsourcing analytical development to providers with captive mass spectrometry competency accelerates regulatory submission timelines for emerging biopharma.
Industry Challenges
- Mass Spectrometry Talent Scarcity:Multi-attribute method development requires hybrid skill sets spanning protein chemistry, bioinformatics, and regulatory documentation.
- Legacy ELISA Integration Friction:Pharmaceutical quality control labs face workflow disruption when bridging historical ELISA data with new mass spectrometry release protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Host Cell Protein Testing Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assays, Kits, Reagents, Instruments Application: Biopharmaceuticals, Vaccine Development, Diagnostic Laboratories, Research Institutes Technology: ELISA, Mass Spectrometry, Western Blotting, PCR End User: Pharma Companies, Contract Research Organizations, Academic Research, Clinical Laboratories |
| Companies Covered | Thermo Fisher Scientific Inc., Bio-Rad Laboratories, Inc., Enzo Life Sciences, Inc., Cytiva, Abcam plc, Cygnus Technologies, LLC, Biogenes GmbH, Charles River Laboratories International, Inc., Cisbio Bioassays, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Host Cell Protein Testing Market Strategic Shifts
Detection methodologies are converging toward platform-agnostic quantification standards while regulatory agencies harmonize acceptance criteria across jurisdictions. This shift compresses method development cycles and elevates the strategic value of proprietary reagent libraries.
High-resolution mass spectrometry is digitizing host cell protein profiling by converting complex proteomic signatures into searchable spectral databases. Biopharmaceutical manufacturers adopting these platforms compress method development from months to weeks. The technology is digitizing regulatory submission packages, enabling electronic cross-referencing of clearance data across purification train stages.
FDA's enforcement of ICH Q6B guidelines intensifies scrutiny of orthogonal validation packages for release testing. Manufacturers must demonstrate HCP clearance below immunogenicity thresholds using complementary detection principles. United States-based contract manufacturing organizations respond by staffing dedicated mass spectrometry competency centers rather than relying on external analytical partnerships.
Buyer concentration among large biopharmaceutical developers is compressing service contract structures toward integrated multi-year analytical partnerships. Small and mid-cap drug developers, lacking in-house mass spectrometry infrastructure, now prioritize contract research organizations with validated platform transfer protocols. This preference shift concentrates demand growth among specialized analytical service providers in the United States and Germany.
Host Cell Protein Testing Market Segmentation
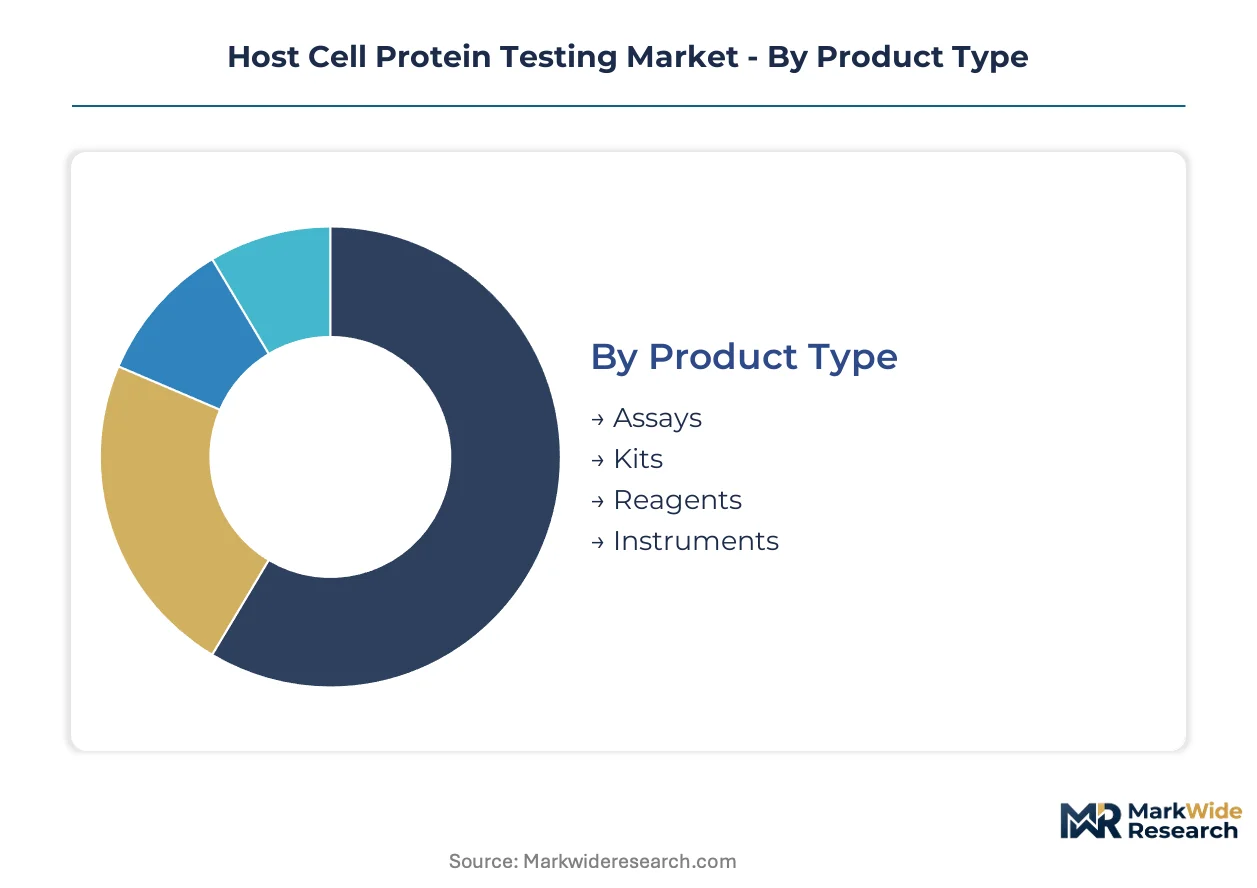
Host cell protein testing segments reflect divergent technology maturities and regulatory compliance pressures. Product portfolios span mature ELISA platforms alongside emerging mass spectrometry suites, while end-user concentration tilts toward outsourced analytical validation.
Product Type:
Mature consumable categories dominate transaction volumes, though emerging platform technologies reshape margin structures.
- Assays:Pre-validated immunoassay panels deliver standardized HCP quantification for routine release testing. Biopharmaceutical manufacturers in the United States favor multiplexed assay formats that compress analytical timelines for IND-enabling studies.
- Reagents:Isotopically labeled peptide standards and high-purity solvents command premium positioning within mass spectrometry workflows. Contract manufacturing organizations absorb elevated per-test consumables spend to satisfy FDA multi-attribute method requirements.
- Kits:Commercial off-the-shelf ELISA kits retain deployment across legacy quality control labs with established SOPs.
- Instruments:High-resolution mass spectrometers require substantial capital commitment and specialized operator training.
Assays retain volume leadership; reagents hold the steepest expansion curve.
Application:
Cost tier stratification separates high-value biologic manufacturing from commoditized diagnostic screening.
- Biopharmaceuticals:Recombinant protein and monoclonal antibody production mandates orthogonal HCP clearance verification across downstream purification trains. FDA ICH Q6B enforcement compels manufacturers to demonstrate immunogenicity risk mitigation below threshold limits.
- Vaccine Development:Cell-culture-derived vaccine substrates require HCP monitoring distinct from bacterial expression systems. EMA's extended purity mandates for novel manufacturing platforms accelerate analytical method transfers to contract research organizations.
- Diagnostic Laboratories:Reference labs deploy simplified ELISA protocols for batch release of in vitro diagnostic components.
- Research Institutes:Academic facilities prioritize cost-efficient Western blotting for exploratory proteomic characterization.
Biopharmaceuticals anchor revenue concentration; vaccine development climbs fastest on regulatory tailwinds.
Technology:
Customer type differentiation separates validated release platforms from exploratory research tools.
- Mass Spectrometry:Label-free multi-attribute methods digitize HCP profiling into searchable spectral databases. CDSCO's biosimilar documentation requirements in India drive adoption among domestic contract research organizations lacking legacy ELISA infrastructure.
- ELISA:Antibody-dependent detection remains entrenched where historical validation packages support regulatory continuity. Cross-reactivity limitations force redundant orthogonal confirmation when coverage gaps persist against low-abundance protein subsets.
- Western Blotting:Semi-quantitative immunodetection serves early-stage clone selection rather than release testing.
- PCR:Residual DNA quantification complements protein impurity workflows in integrated clearance demonstration.
ELISA maintains installed base dominance; mass spectrometry gains share fastest on speed-to-validation advantages.
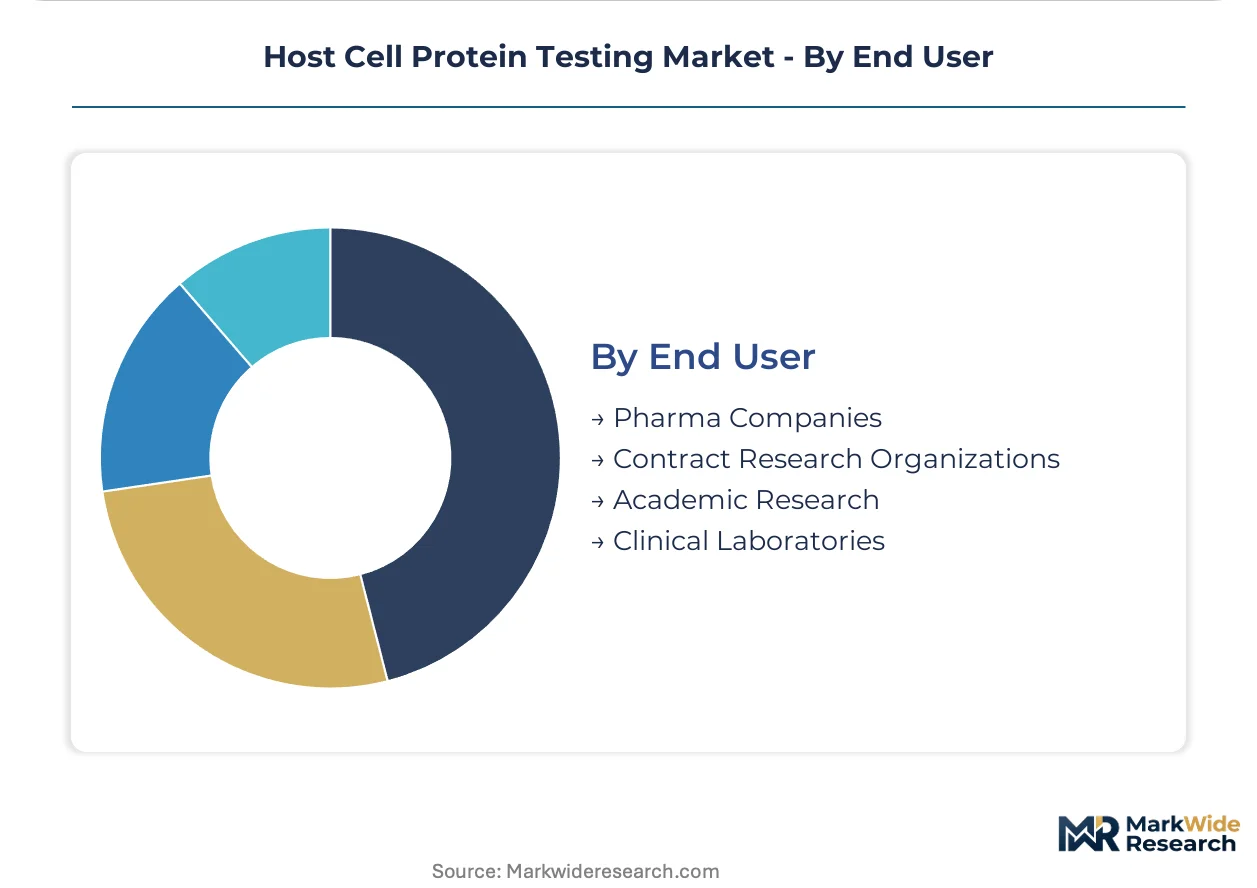
End User:
Supply concentration among analytical service providers redirects procurement patterns toward captive competency centers.
- Contract Research Organizations:Specialized providers aggregate mass spectrometry talent and regulatory documentation expertise that emerging biopharma cannot replicate in-house. United States-based CROs capture disproportionate demand growth from mid-cap developers outsourcing IND-enabling analytical packages.
- Pharma Companies:Large biopharmaceutical developers consolidate multi-year analytical partnerships with preferred service providers rather than building redundant internal capacity. Quality control labs face workflow disruption bridging historical ELISA data with new mass spectrometry release protocols.
- Academic Research:University labs constrain spending to grant-funded consumable purchases without capital equipment investment.
- Clinical Laboratories:Hospital-affiliated testing facilities deploy standardized HCP assays for therapeutic monitoring applications.
Pharma companies retain direct procurement volume; contract research organizations expand most quickly on outsourcing acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States deploys mass spectrometry for release testing at scale, while Germany and Switzerland retain hybrid ELISA-MS workflows, and India leapfrogs directly to multi-attribute methods without legacy infrastructure baggage.
United States
FDA's ICH Q6B enforcement drives orthogonal validation demand among biopharmaceutical manufacturers. The agency's intensified scrutiny of immunogenicity risk documentation compels CDMOs to staff dedicated mass spectrometry competency centers. Greater Boston anchors the highest analytical service provider density, with Cambridge-area CROs capturing disproportionate outsourcing flows from mid-cap developers.
Germany
EMA's MDR framework extends purity mandates to novel cell therapy platforms, accelerating method transfers to specialized analytical houses. The country's national pharmaceutical regulator, BfArM, coordinates with EMA on harmonized mass spectrometry acceptance criteria. The Rhine-Main cluster around Frankfurt concentrates contract manufacturing investment in high-resolution proteomics infrastructure.
Switzerland
Swissmedic maintains stringent HCP documentation requirements for biologic license applications, preserving premium pricing for validated reagent kits. The regulator's alignment with EMA standards eases multi-jurisdictional submission pathways for Basel-headquartered pharma developers. The Basel-Zurich corridor hosts dense concentrations of analytical development talent serving both internal R&D and external client portfolios.
India
CDSCO's biosimilar filing mandates create first-mover advantages for domestic CROs building mass spectrometry capacity without ELISA legacy constraints. The regulator's tightening documentation requirements tighten market access for imported reference products. Hyderabad and Bangalore emerge as analytical service hubs, with Telangana-based providers capturing contract flows from emerging domestic biotech developers.
United Kingdom
MHRA post-Brexit alignment with ICH Q6B preserves FDA-equivalent purity verification standards for biopharmaceutical exports. The regulator's continued participation in international harmonization working groups sustains methodological continuity with EU and US markets. The Golden Triangle between London, Cambridge, and Oxford retains analytical talent concentration despite facility relocation pressures to continental Europe.
Host Cell Protein Testing Market Competitive Environment
Capability concentration sits with specialized polyclonal antibody suppliers and mass spectrometry platform providers; scale advantage sits with diversified life science conglomerates with installed instrument bases. The market structures around three archetypes: reagent specialists with proprietary coverage libraries, platform-agnostic service providers with regulatory documentation expertise, and integrated conglomerates leveraging consumables pull-through. Dominant competitive moves include strategic partnerships between antibody suppliers and mass spectrometry vendors, plus geographic expansion of analytical service capacity into high-growth biosimilar markets.
Within the reagent specialist tier, Cygnus Technologies, LLC and Biogenes GmbH exemplify concentrated capability in host cell protein coverage libraries. Thermo Fisher Scientific Inc. anchors the integrated conglomerate position, leveraging scale advantages in mass spectrometry platform deployment. These three occupy distinct competitive spaces—specialized antibody production, regional analytical services, and global platform ecosystems—without direct head-to-head confrontation across identical customer segments.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories, Inc. |
| Enzo Life Sciences, Inc. |
| Cytiva |
| Abcam plc |
| Cygnus Technologies, LLC |
| Biogenes GmbH |
| Charles River Laboratories International, Inc. |
| Cisbio Bioassays |
| Others |
Value Chain & Pricing Dynamics
Isotopically labeled peptide standards and high-purity solvents concentrate manufacturing in the United States and Germany, anchoring margin pools with mass spectrometry platform providers and specialized reagent houses rather than legacy ELISA kit distributors.
Pricing Analysis
Long-term offtake agreements dominate procurement between biopharmaceutical manufacturers and mass spectrometry consumables suppliers, locking in volume commitments against preferential pricing for isotopically labeled standards. Price differentiation hinges on regulatory certification tier and customization depth, with FDA-validated reagent kits commanding substantial premiums over research-grade alternatives. Pricing pressure stems from contract manufacturing organizations consolidating purchasing power through multi-year analytical partnerships. Emerging biopharma developers exhibit highest price sensitivity, while large pharmaceutical houses prioritize validation depth over unit cost.
Supply Chain Analysis
Export-control regimes restricting high-resolution mass spectrometer sales to certain jurisdictions fragment instrument availability across analytical service networks. Manufacturing concentrates in the United States, Germany, and Switzerland for precision components, with China and India supplying base chemicals and consumable substrates. Raw material dependencies center on helium-3 isotopes for ionization sources, rare-earth magnets for detector assemblies, and fluorinated solvents for mobile phases. Single-source vulnerability characterizes polyclonal antibody production for CHO coverage libraries. Distribution runs through authorized distributor networks serving contract research organizations and pharmaceutical quality control labs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The host cell protein testing market sits at a platform-economics inflection where mass spectrometry ecosystems displace antibody-dependent workflows, rewarding interoperability investments that bridge historical ELISA validation packages with multi-attribute method data structures.
For Market Incumbents: Harden defensive positions by deepening proprietary coverage libraries against emerging cell therapy expression systems and securing exclusive reagent supply contracts with high-throughput contract manufacturing organizations. Threat substitution from label-free proteomics platforms demands accelerated R&D in spectral database interoperability. Vertical integration into isotopically labeled standard production secures margin capture against solvent cost volatility. For New Entrants and Emerging Players: Pursue white-space opportunities in at-line mass spectrometry integration with continuous bioprocessing equipment, where real-time HCP clearance monitoring remains underdeveloped. India's biosimilar analytical services market offers the most penetrable geography given CDSCO documentation mandates and absence of legacy ELISA infrastructure. A go-to-market angle anchored in regulatory documentation expertise accelerates platform adoption among emerging biopharma lacking internal mass spectrometry competency. For Investors and Strategic Acquirers: Capital is best deployed toward specialized analytical service providers with captive mass spectrometry talent and validated platform transfer protocols, as these assets concentrate long-term outsourcing demand from mid-cap drug developers. The five-to-ten year viability window favors providers building multi-jurisdictional regulatory submission expertise over pure reagent manufacturers facing platform commoditization. Watch for inflection signals in FDA mass spectrometry acceptance criteria harmonization across ICH member states.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Orbitrap-ELISA data bridging accelerates regulatory submission timelines for biopharmaceutical manufacturers. |
| Regulatory Approval Pathway | CDSCO biosimilar documentation mandates create first-mover advantages for domestic Indian analytical service providers. |
| Strategic Partnership | Antibody supplier-mass spectrometry vendor alliances lock in coverage library exclusivity against emerging expression platforms. |
| Geographic Expansion | Frankfurt and Hyderabad analytical hubs capture contract flows from EMA MDR and CDSCO enforcement respectively. |
| Acquisition of Specialist Firm | Polyclonal antibody coverage library assets concentrate irreplaceable regulatory validation heritage. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with biopharmaceutical analytical development heads, regulatory affairs leads, contract research organization procurement managers, and mass spectrometry platform engineers; and secondary validation against FDA 483 inspection observations, EMA marketing authorization assessment reports, CDSCO biosimilar approval databases, and SEC 10-K instrument revenue disclosures. Bottom-up and top-down triangulation cross-checked consumables pull-through rates against installed base estimates.
Forecast inputs considered technology migration velocity from ELISA to mass spectrometry, regulatory harmonization progress across ICH Q6B jurisdictions, and contract manufacturing organization capacity expansion plans. Segmentation dimensions modeled encompassed detection technology, application area, end-user archetype, and regional regulatory cluster. CAGRs derived from slope-intercept analysis of historical instrument placements and consumables attach rates across the projection horizon. Industry-specific inputs included polyclonal antibody coverage breadth metrics and multi-attribute method validation timelines.
Sensitivities concentrate around FDA mass spectrometry acceptance criteria finalization and EMA-CDSCO regulatory harmonization pace. Forecasts reflect documented assumptions regarding biopharmaceutical pipeline composition and outsourcing penetration rates. Material shifts in ICH Q6B enforcement intensity or mass spectrometry platform standardization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Pneumococcal Testing Market
Testing Services
Home Care Testing Market
Testing Services
Global Creatinine Assay Kits Market
Testing Services
Healthcare Analytical Testing Services Market
Testing Services
Thyroid Test Market
Testing Services
Pharmaceutical Sterility Testing Market
Testing Services
Self-Testing Market
Testing Services
Apoptosis Testing Market
Testing Services
Global GI Stool Testing Market
Testing Services
Preclinical Medical Device Testing Services Market
Testing Services
Faecal Calprotectin Testing Market
Testing Services
Autoimmune Disease Testing Market
Testing Services
Global Thyroid Function Test Market
Testing Services
Global Biological Safety Testing Market
Testing Services
Europe Medical Device Testing Market
Testing Services
Global Sterility Testing Market