
 Pharmaceutical Dosage Form Testing Systems Market | 2026-2036
Pharmaceutical Dosage Form Testing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Dosage Form Testing Systems Market Analytics
The EU Green Deal's pharmaceutical sustainability criteria is broadening equipment replacement cycles across European manufacturing sites. Sotax AG leverages its Swiss engineering heritage to dominate high-precision dissolution testing platforms. Thermo Fisher Scientific anchors its position through integrated chromatography workflows that span discovery through quality control. Eurofins Scientific competes by extending its analytical services footprint into emerging biologics hubs.
Pharmaceutical dosage form testing systems encompass instruments and analytical platforms that evaluate physical, chemical, and performance properties of drug products including tablet hardness, capsule dissolution rates, and liquid formulation stability under ICH conditions. These systems employ validated methodologies to ensure batch-to-batch consistency, bioequivalence, and shelf-life determination prior to regulatory submission. Dissolution testing technology commands the largest installed base due to its universal mandate across solid oral dosage forms, while mass spectrometry segments capture premium margins through complex biologic characterization demands. Quality control applications sustain the highest volume throughput as pharmaceutical companies maintain continuous batch release protocols.
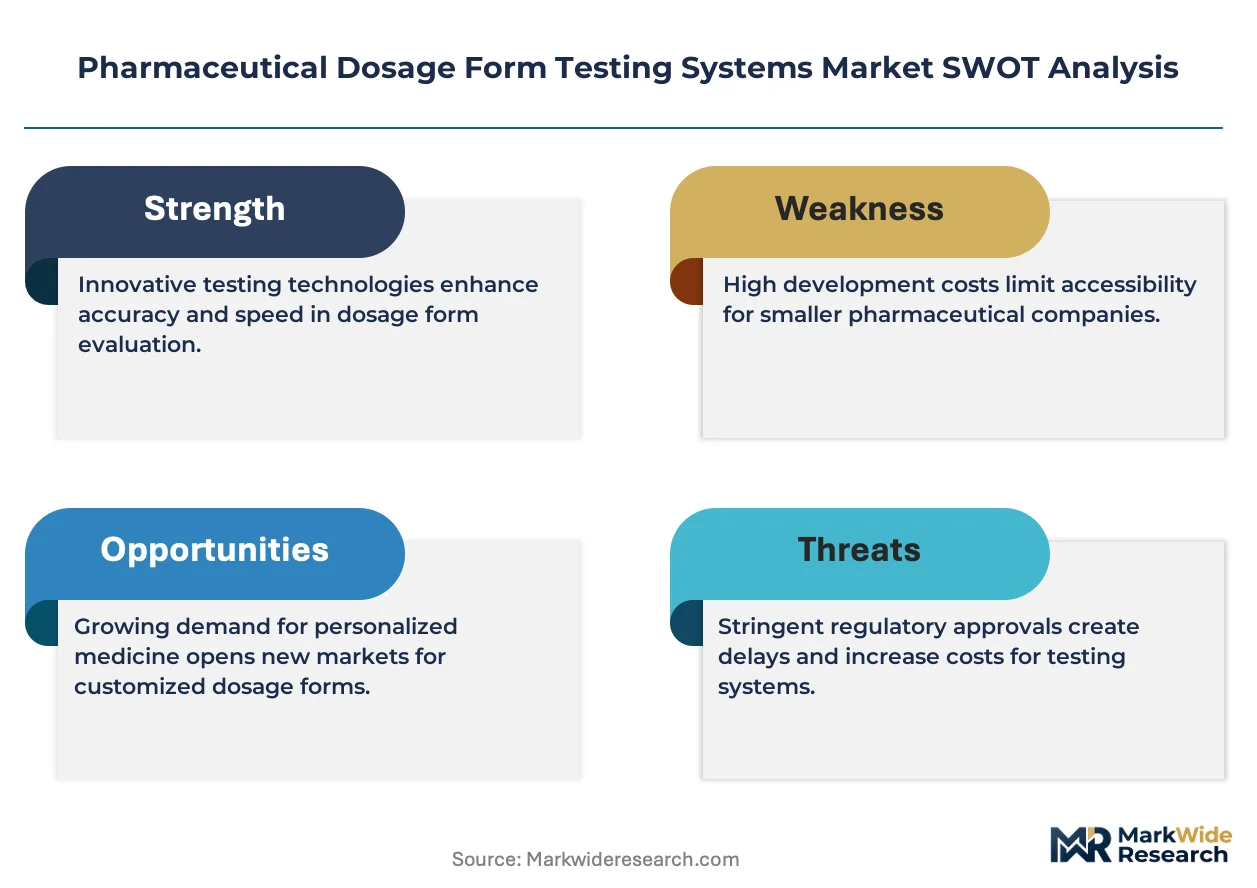
FDA dissolution method validation requirements, EMA's ICH Q12 lifecycle management guidelines, and USP-NF general chapters on physical tests collectively determine instrument specifications and software compliance architectures for market access. The EPA's pharmaceutical effluent guidelines additionally constrain solvent recovery and waste handling capabilities in testing laboratories. Stakeholders must monitor evolving pharmacopeial harmonization between FDA, EMA, and WHO prequalification standards to anticipate equipment upgrade cycles and validation burden shifts.
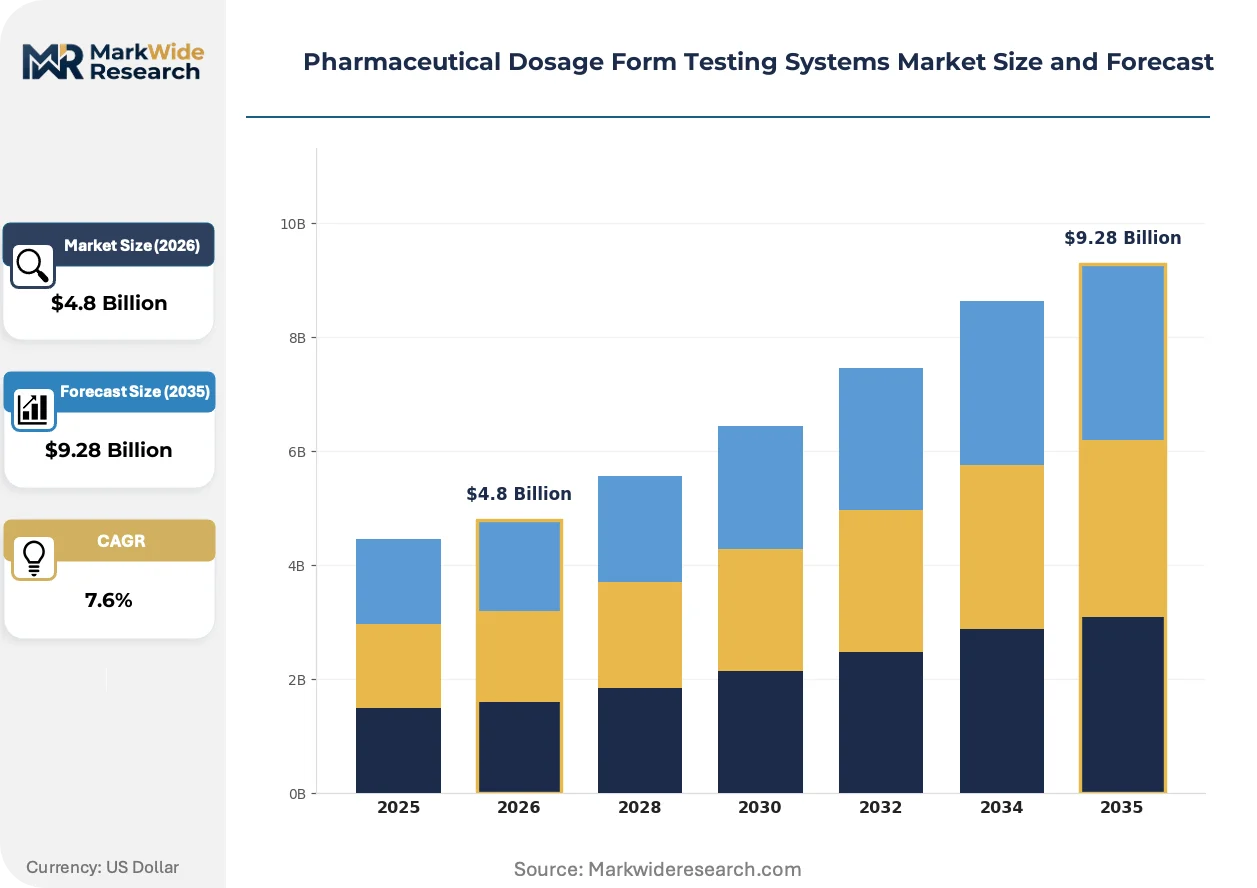
Market Dynamics
Contract research organizations are consolidating analytical testing capacity around high-throughput dissolution platforms to capture biopharma outsourcing volume. This concentration is compressing equipment procurement cycles and elevating validation requirements across manufacturing networks.
Growth Catalysts
- FDA Bioequivalence Guidance:Updated dissolution method validation mandates require pharmaceutical manufacturers to upgrade legacy testing infrastructure. Equipment replacement cycles have shortened as facilities race to meet abbreviated new drug application timelines.
- Biologics Characterization Demand:Complex therapeutic proteins and monoclonal antibodies require mass spectrometry platforms that extend beyond traditional small-molecule testing. Analytical service providers are expanding chromatography capacity to serve this segment.
- German Precision Manufacturing Cluster:Dense concentration of dissolution instrument engineering around Düsseldorf and Karlsruhe creates supply proximity for European pharmaceutical operations. Regional equipment sourcing advantages accelerate deployment timelines.
Market Restraints
- High-Purity Solvent Cost Volatility:Chromatography-grade acetonitrile and methanol prices fluctuate with petrochemical feedstock markets. Testing laboratories face margin compression when solvent procurement spikes coincide with fixed service contract pricing.
- Single-Source Component Dependency:Precision dissolution paddles and vessel specifications often originate from specialized German or Swiss suppliers. Geographic concentration of critical subcomponent manufacturing creates supply vulnerability during trade disruptions.
- Legacy Equipment Interoperability Limits:Pre-2015 dissolution systems lack data integrity architecture required by FDA 21 CFR Part 11. Full platform replacement costs exceed incremental upgrade economics for mid-sized generic manufacturers.
Strategic Opportunities
- Indian CDMO Expansion:Contract development and manufacturing organizations in Hyderabad and Ahmedabad are building dedicated analytical testing wings. Equipment vendors can establish localized service networks to capture installation and validation revenue.
- EMA Quality-by-Design Mandates:Lifecycle management guidelines under ICH Q12 incentivize real-time release testing investments. Continuous manufacturing integration creates demand for in-line dissolution monitoring systems.
- AI-Enabled Method Development:Machine learning algorithms trained on historical dissolution profiles are converging with robotic sample handling. Automated method transfer reduces validation burden for multisite pharmaceutical operations.
Industry Challenges
- Analytical Chemist Talent Scarcity:Specialized expertise in USP dissolution method development and validation is concentrated among retiring practitioners. Training pipelines have not scaled to match biopharma analytical outsourcing growth.
- Multi-Site Data Harmonization:Pharmaceutical companies operating across FDA, EMA, and WHO prequalification jurisdictions face divergent electronic record requirements. Software validation costs multiply when platforms must satisfy incompatible audit trail standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Dosage Form Testing Systems Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Liquids, Ointments Application: Quality Control, Research & Development, Regulatory Compliance, Stability Testing Technology: HPLC, UV-Vis Spectroscopy, Mass Spectrometry, Dissolution Testing End User: Pharmaceutical Companies, Contract Research Organizations, Academic Research Institutes, Quality Control Laboratories |
| Companies Covered | Sotax AG, Mettler-Toledo International Inc., Thermo Fisher Scientific, Eurofins Scientific, GEA Process Engineering, Copley Scientific, Charles River Laboratories, SGS, Erweka GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Dosage Form Testing Systems Market Evolving Landscape
Automation and connected data systems are compressing testing throughput timelines while regulatory harmonization efforts reshape equipment specification requirements across manufacturing networks.
Raman spectroscopy is overtaking traditional UV-Vis detection for in-situ dissolution monitoring. Biopharma quality control departments are adopting fiber-optic probes to eliminate manual sampling interruptions. This shift is overtaking conventional offline analytical workflows and enabling real-time release decisions for high-value oral solid dosage forms.
EMA's ICH Q14 analytical procedure development guidelines now require enhanced method understanding documentation. Pharmaceutical companies must demonstrate predictive dissolution models linking formulation variables to release kinetics. Small-molecule generic manufacturers in Southern Europe are responding by contracting specialized analytical development services rather than building in-house capability.
Consolidated procurement through group purchasing organizations is displacing direct equipment vendor relationships. Hospital-affiliated pharmacy operations and mid-sized generic manufacturers now negotiate dissolution testing platforms through centralized supply contracts. This concentration is most visible in North American contract manufacturing, where three buying collectives control majority analytical capital expenditure decisions.
Pharmaceutical Dosage Form Testing Systems Market Segmentation
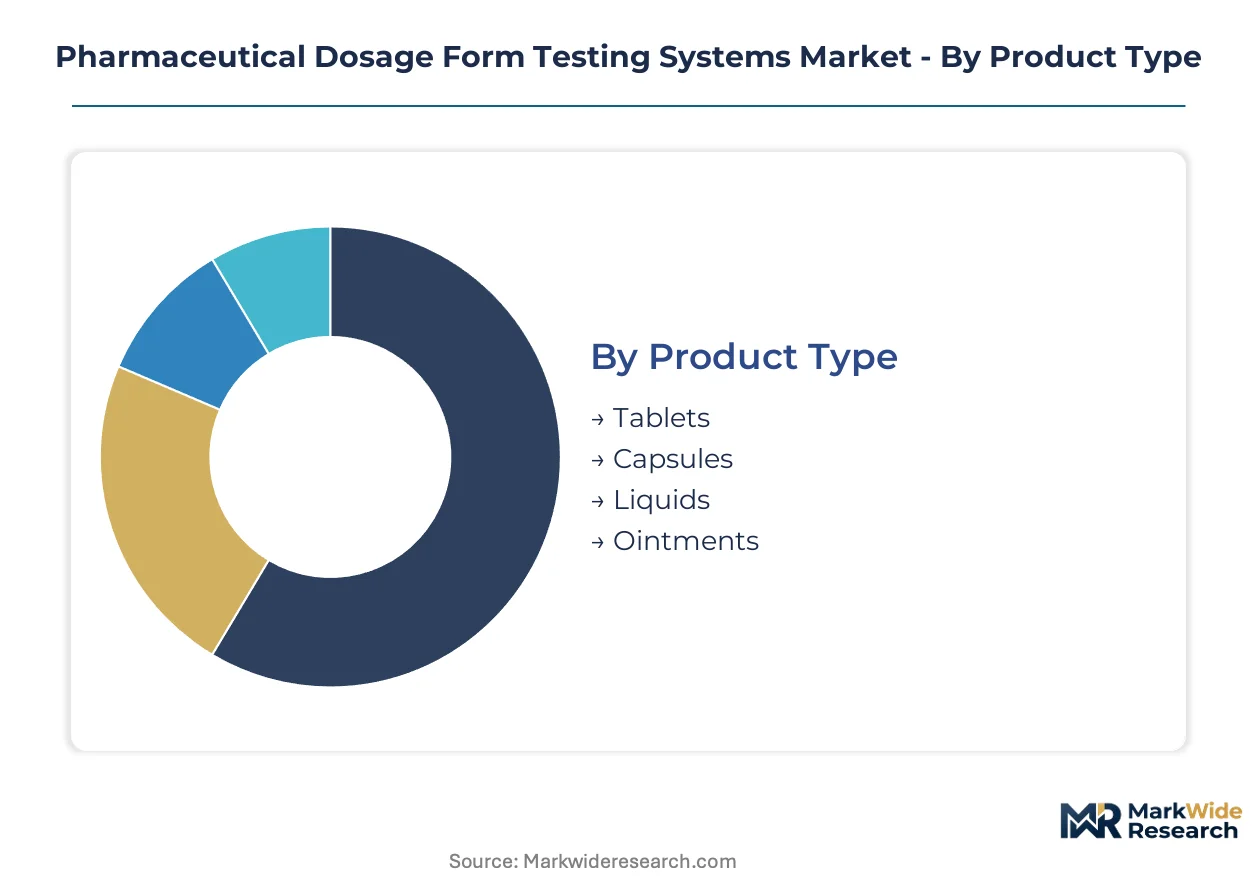
Segmentation in pharmaceutical dosage form testing systems reveals distinct procurement patterns across product formats, analytical workflows, and customer archetypes. Equipment specifications diverge sharply between high-volume quality control operations and precision-driven R&D environments. Understanding these fault lines enables vendors to align validation support, service networks, and software architectures with buyer economics.
Product Type:
Tablets dominate installed equipment bases through sheer prescription volume, while biologics growth elevates liquid formulation testing to premium positioning.
- Tablets:Compression hardness testers and friability apparatus constitute the foundational equipment layer across oral solid dosage manufacturing. Demand concentrates in Indian and Chinese generic API operations where batch release volumes strain dissolution platform capacity.
- Capsules:Gelatin and HPMC shell integrity testing requires specialized dissolution vessel configurations with sinker adaptations. European nutraceutical contract manufacturers in Italy and Spain drive replacement cycles as they adopt EMA quality-by-design protocols.
- Liquids:Viscosity meters and particle size analyzers serve parenteral and oral solution stability programs.
- Ointments:Rheometers and spreadability testers address topical formulation release kinetics for dermatological applications.
Today's leader: Tablets. Tomorrow's challenger: Liquids.
Application:
Quality control applications sustain continuous throughput economics, while regulatory compliance investments spike around pharmacopeial revision cycles.
- Quality Control:Automated dissolution platforms process hundreds of batch release samples daily with LIMS-integrated data integrity. Pharmaceutical manufacturers in Germany and Switzerland prioritize 21 CFR Part 11-compliant software architectures to satisfy FDA inspection readiness.
- Research & Development:Early-phase formulation screening employs miniature dissolution apparatus and high-throughput UV-Vis plate readers. Biotech startups in Boston and San Diego outsource method development to specialized analytical CROs rather than building in-house capability.
- Regulatory Compliance:Bioequivalence studies for abbreviated new drug applications demand USP apparatus qualification and media validation protocols.
- Stability Testing:ICH Q1A long-term storage conditions drive environmental chamber investments with forced degradation kinetic profiling.
Quality control commands current capital deployment. R&D instrumentation is climbing fastest as preclinical pipelines expand.
Technology:
Dissolution testing anchors volume procurement through universal regulatory mandate, while mass spectrometry captures margin through biologic complexity premiums.
- HPLC:Reverse-phase chromatography systems separate active pharmaceutical ingredients from degradants with validated gradient methods. Generic manufacturers in Hyderabad and Ahmedabad deploy UHPLC platforms to accelerate impurity profiling turnaround times.
- UV-Vis Spectroscopy:Cost-effective quantification dominates content uniformity testing for single-API solid dosages. Mid-sized European generics houses in Poland and Hungary standardize on diode-array detectors for multi-wavelength assay flexibility.
- Mass Spectrometry:LC-MS/MS platforms characterize peptide therapeutics and antibody-drug conjugates with molecular specificity.
- Dissolution Testing:USP apparatus 1 and 2 configurations remain mandatory across all solid oral dosage regulatory submissions.
Dissolution Testing holds installed base dominance. Mass Spectrometry is gaining share fastest through biologics characterization demand.
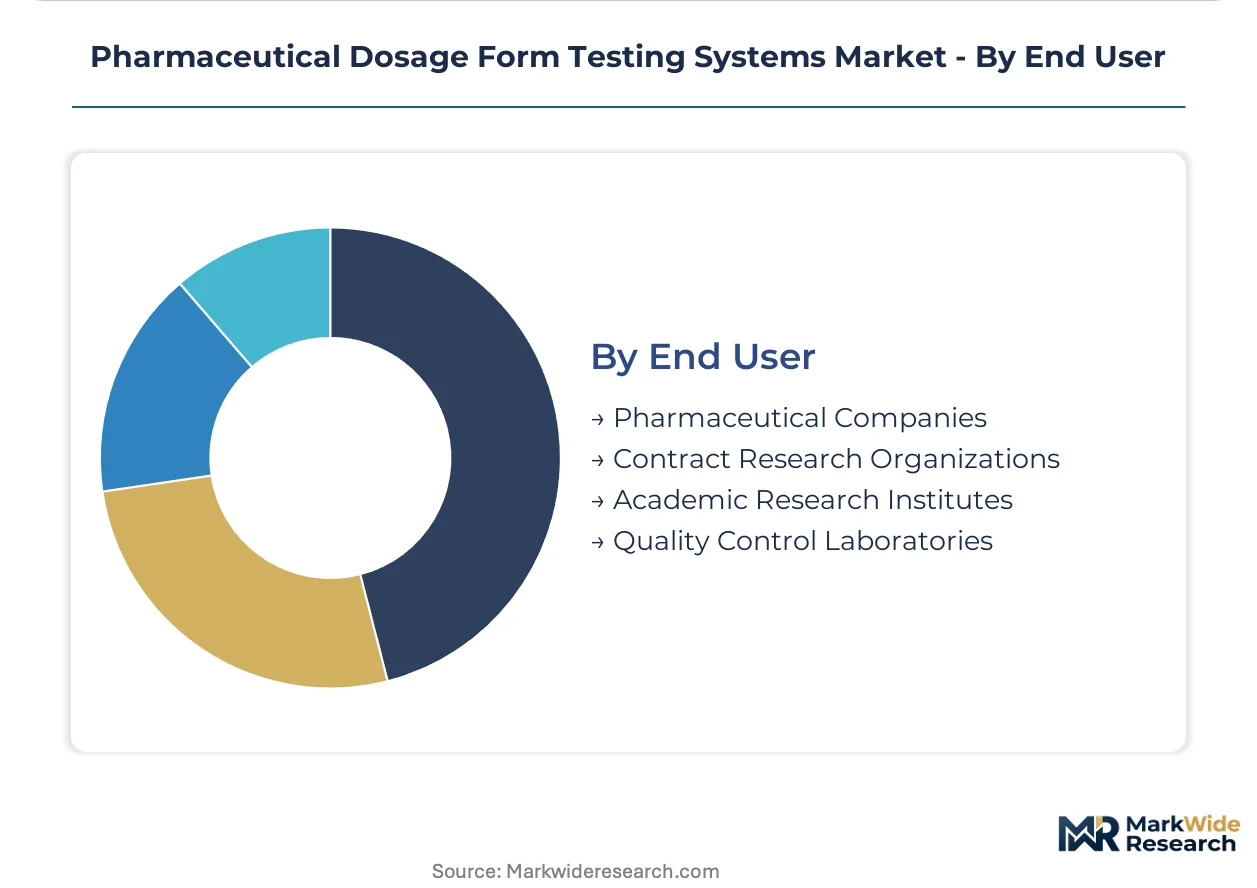
End User:
Pharmaceutical companies consolidate analytical capital expenditure, while contract research organizations fragment procurement through specialized service line buildouts.
- Pharmaceutical Companies:Multinational innovators maintain captive testing laboratories with integrated chromatography workflows. Swiss and German headquarters operations centralize method validation expertise to support global manufacturing network harmonization.
- Contract Research Organizations:Analytical service providers expand dissolution capacity to capture biopharma outsourcing volume. CDMOs in Hyderabad and Singapore build dedicated stability wings with walk-in chamber infrastructure.
- Academic Research Institutes:University pharmacology departments employ teaching-grade dissolution apparatus for formulation science curricula.
- Quality Control Laboratories:Independent testing facilities serve regional generic manufacturers with USP monograph compliance verification.
Pharmaceutical Companies anchor equipment revenue. Contract Research Organizations represent the steepest expansion trajectory through analytical outsourcing growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The pharmaceutical dosage form testing systems industry traces its origins to Swiss and German precision engineering traditions established during the post-war expansion of analytical chemistry. Early dissolution apparatus designs from Basel and Karlsruhe set standards that persist in current regulatory frameworks. Equipment manufacturing subsequently dispersed to serve regional pharmaceutical production clusters.
United States
FDA bioequivalence guidance updates drive equipment replacement cycles among generic manufacturers and contract research organizations. The agency's 21 CFR Part 11 data integrity requirements force legacy system upgrades across quality control laboratories. Boston and San Diego biotech clusters outsource analytical method development to specialized service providers rather than building captive testing infrastructure.
Germany
Düsseldorf and Karlsruhe anchor Europe's densest concentration of dissolution instrument engineering, with GEA Process Engineering and Erweka GmbH maintaining precision manufacturing heritage. EMA quality-by-design mandates under ICH Q12 tighten lifecycle management documentation requirements for pharmaceutical manufacturers. Regional equipment sourcing advantages accelerate deployment timelines for European contract manufacturing organizations.
Switzerland
Swiss engineering heritage supports high-precision dissolution testing platform dominance through Sotax AG and specialized chromatography workflows. Swissmedic regulatory alignment with EMA standards ensures equipment qualification protocols transfer seamlessly across European manufacturing networks. Basel's pharmaceutical headquarters operations centralize method validation expertise for global network harmonization.
India
Hyderabad and Ahmedabad contract development and manufacturing organizations build dedicated analytical testing wings to capture biopharma outsourcing volume. CDSCO regulatory convergence with ICH guidelines elevates equipment validation standards for export-oriented generic manufacturers. Localized service networks emerge to capture installation and qualification revenue from expanding dissolution platform deployments.
China
NMPA pharmacopeial harmonization efforts with USP and EP standards drive equipment specification convergence for domestic and export markets. Yangtze River Delta pharmaceutical manufacturing clusters upgrade testing infrastructure to satisfy international abbreviated new drug application requirements. Shanghai and Suzhou analytical service providers expand chromatography capacity to serve biologics characterization demand.
Pharmaceutical Dosage Form Testing Systems Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology complexity and regulatory validation depth. The market structures into three tiers: integrated life science conglomerates with chromatography-to-software workflows; precision instrument specialists with multi-generational engineering heritage; and analytical service providers extending equipment-dependent revenue models. Consolidation pressures concentrate around high-throughput dissolution platforms. Strategic partnerships between equipment vendors and contract research organizations displace direct pharmaceutical procurement relationships.
Within the precision instrument heritage tier, Sotax AG and Erweka GmbH exemplify multi-generational engineering concentration around Swiss and German manufacturing traditions. Thermo Fisher Scientific represents the integrated conglomerate archetype with chromatography workflow span. These three anchors illustrate competitive positioning across technology integration depth versus specialized engineering focus.
| Leading Market Players |
|---|
| Sotax AG |
| Mettler-Toledo International Inc. |
| Thermo Fisher Scientific |
| Eurofins Scientific |
| GEA Process Engineering |
| Copley Scientific |
| Charles River Laboratories |
| SGS |
| Erweka GmbH |
| Others |
Value Network & Pricing Analysis
Precision-performance bifurcation between USP-compliant dissolution platforms and research-grade chromatography systems manifests in divergent pricing architectures and supply chain configurations. German and Swiss engineering heritage commands premium positioning through validated qualification protocols, while commodity-grade testing equipment from Asian manufacturing clusters competes on procurement cost and localized service response.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment procurement, with FDA 21 CFR Part 11 software validation and EMA ICH Q12 lifecycle documentation serving as the primary price differentiation drivers. Pricing pressure stems from consolidated procurement through group purchasing organizations in North American contract manufacturing. Mid-sized generic manufacturers in Southern Europe exhibit highest price sensitivity, while Swiss and German multinational innovators prioritize compliance architecture over procurement cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized German and Swiss suppliers of precision dissolution paddles and vessel specifications. Manufacturing concentration in Germany, Switzerland, and China creates geographic dependency for critical subcomponents. Chromatography-grade acetonitrile and methanol feed from petrochemical supply chains introduces raw material cost volatility. Tariff exposure on precision-engineered components from European suppliers amplifies procurement risk. Distribution runs through authorized dealer networks with factory-trained qualification engineers rather than direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contract research organizations in India offer labor-arbitrage advantages of 40-60% below European analytical service costs, while CDSCO regulatory convergence with ICH guidelines enables export-quality equipment validation at emerging-market infrastructure investment levels.
For Market Incumbents: Lock in dissolution platform installed bases through multi-year service contracts bundling validation support and software upgrade rights. Capacity addition in Hyderabad and Singapore addresses biopharma outsourcing migration. Certification investment in USP apparatus qualification protocols defends against emerging analytical CROs with lower compliance overhead. For New Entrants and Emerging Players: Begin with automated dissolution method development services for Indian CDMOs expanding analytical testing wings. The most penetrable segment sits with mid-sized generic manufacturers in Poland and Hungary seeking USP-compliant equipment without Swiss engineering premiums. A go-to-market angle anchored in AI-enabled dissolution profile prediction differentiates against legacy manual method transfer workflows. For Investors and Strategic Acquirers: Asymmetric upside sits with precision instrument specialists possessing multi-generational engineering heritage and captive service revenue streams. Long-term viability hinges on biologics characterization demand sustaining mass spectrometry platform margins. Acquisition targets should demonstrate installed base density in FDA-inspected facilities. The signal to watch is EMA quality-by-design mandate acceleration forcing equipment replacement cycles among European generic manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA bioequivalence guidance updates compress equipment validation timelines for ANDA submissions. |
| Manufacturing Scale-Up | High-throughput dissolution platform deployment captures biopharma outsourcing volume concentration. |
| Backward Integration | In-house production of precision dissolution vessels reduces dependency on German subcomponent suppliers. |
| Strategic Partnership | Equipment vendor alliances with CDMOs displace direct pharmaceutical procurement relationships. |
| Geographic Expansion | Localized service networks in Hyderabad and Ahmedabad capture installation revenue from Indian CDMO expansion. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured perspectives from analytical laboratory directors, regulatory affairs specialists at pharmaceutical manufacturers, dissolution method development chemists, and procurement managers at contract research organizations. Secondary validation drew from FDA guidance documents, EMA ICH guideline revisions, USP-NF monograph updates, and pharmacopeial harmonization working group proceedings. Bottom-up equipment shipment modeling and top-down pharmaceutical R&D expenditure allocation were cross-referenced for triangulation.
Historical reference periods anchored demand modeling to pre-pandemic baseline through current analysis window, with projection horizons extending across the modeling period. Segmentation dimensions included dosage form category, analytical application workflow, technology platform type, and end-user archetype. CAGRs were derived from equipment replacement cycle analysis and regulatory mandate timing. Forecast inputs incorporated dissolution testing mandate expansion under FDA bioequivalence programs and biologics characterization complexity premiums.
Caveats apply where pharmacopeial harmonization delays or trade disruption in precision component supply chains could materially shift the outlook. Forecasts reflect assumptions around regulatory enforcement consistency and solvent cost stabilization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Ige Allergy Blood Tests Market
Testing Services
North America and Europe Preclinical Medical Device Testing Services Market
Testing Services
Sickle Cell Anemia Testing and Screening Market
Testing Services
Retrovirus Testing Market
Testing Services
Testing and Analysis Services Market
Testing Services
Antibiotic Residue Test Kits Market
Testing Services
Influenza a/B Combo Testing Market
Testing Services
Procalcitonin Reagent Test Kit Market
Testing Services
Cholesterol Testing Services Market
Testing Services
Warfarin Sensitivity Testing Market
Testing Services
Drug Testing Market
Testing Services
Global GMP Testing Service Market
Testing Services
Nipah Virus Testing Market
Testing Services
Rapid Coagulation Testing Market
Testing Services
Global Bilirubin Colorimeter Assay Market
Testing Services
Blood Sugar Tester Market