
 Rapid Antigen Testing Market | 2026-2036
Rapid Antigen Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Rapid Antigen Testing Market Analytics
A shift from single-source government procurement to multi-source commercial distribution is repositioning how manufacturers reach end users. Abbott Laboratories leverages its point-of-care installed base to sustain channel dominance across pharmacy networks. Thermo Fisher Scientific anchors laboratory-grade antigen supply through controlled distribution to hospital systems. Becton, Dickinson and Company competes on manufacturing scale for nasopharyngeal swab formats in clinical settings.
Rapid antigen testing detects specific viral proteins through immunochromatographic lateral flow assays, typically delivering results within fifteen to thirty minutes without laboratory infrastructure. The method serves outbreak containment, travel clearance, and clinical triage where speed outweighs molecular sensitivity. Nasopharyngeal swabs retain the largest volume share among product types due to established clinical trust and reimbursement alignment, while saliva tests capture the fastest expansion as home testing protocols simplify collection logistics. Point-of-care delivery dominates value generation through higher per-test pricing and institutional procurement contracts, though home testing erodes this premium as direct-to-consumer channels mature.
FDA emergency use authorization and CE marking under the EU In Vitro Diagnostic Regulation shape product entry pathways, with FDA's template-based review streamlining pandemic-era submissions while MDR transition delays create European backlog. India's CDSCO enforces import registration and post-market surveillance for self-test kits, tightening quality gates on Asian manufacturing sources. Stakeholders must monitor evolving multiplex authorization standards that combine respiratory targets into single assays, as regulatory precedent for combination claims will determine next-generation R&D allocation.
Market Dynamics
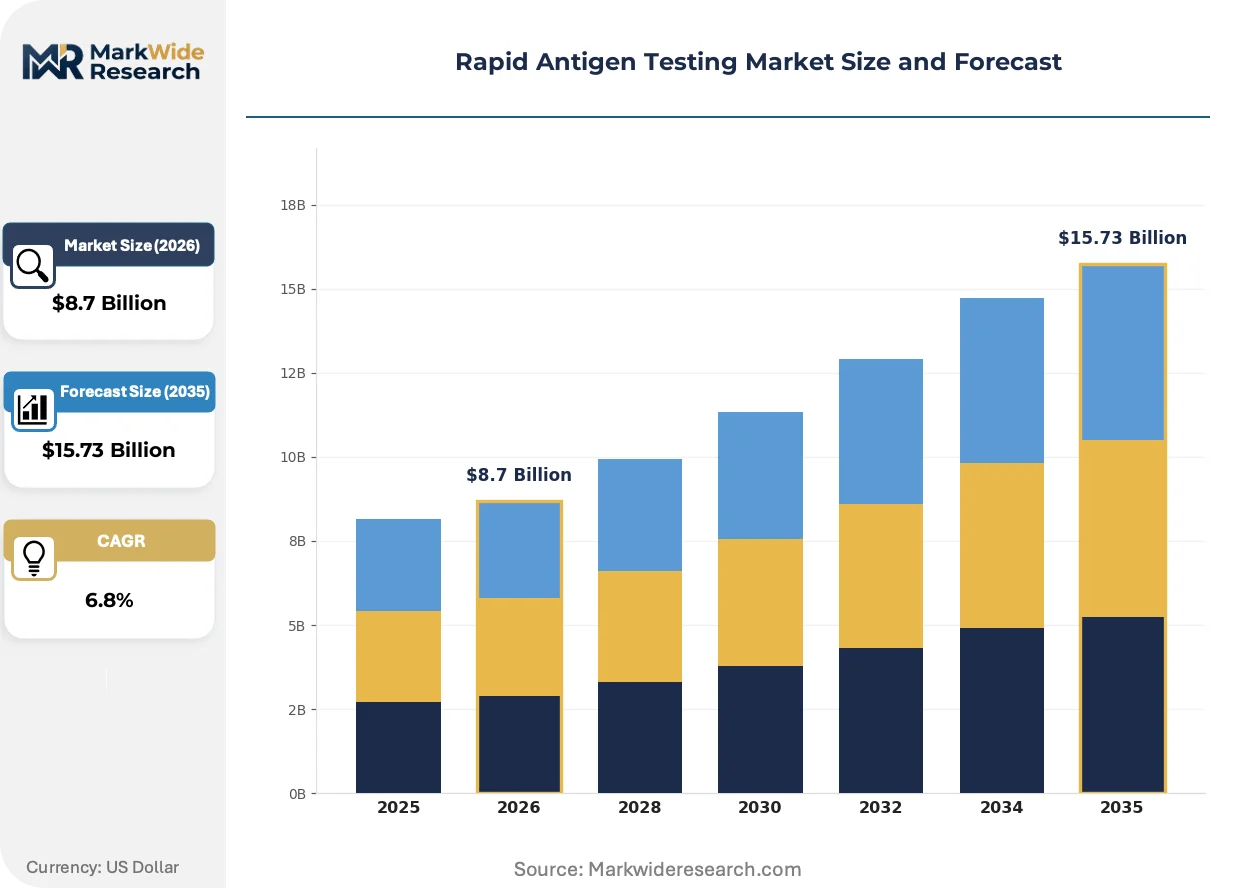
Multiplex assay authorization is compressing single-target test margins while redistributing R&D budgets toward combination respiratory panels that satisfy institutional procurement efficiency mandates.
Growth Catalysts
- EMA self-test pathway:Germany's diagnostic laboratories expand decentralized testing menus under streamlined CE marking procedures, accelerating pharmacy channel penetration for home-use formats.
- Saliva collection protocols:Simplified specimen logistics eliminate cold-chain requirements and expand deployability in remote clinic settings previously dependent on trained phlebotomy staff.
- India's tier-1 pharmacy networks:CDSCO registration requirements for import kits concentrate demand in Mumbai, Delhi, and Bangalore retail channels where consumer familiarity with OTC diagnostics is highest.
Market Restraints
- Nitrocellulose membrane supply:Concentrated Asian manufacturing of this substrate material exposes producers to input cost volatility and freight disruption during regional lockdowns.
- MDR transition backlog:European Union In Vitro Diagnostic Regulation implementation delays create certification queues that freeze product launches for twelve to eighteen months.
- Molecular PCR sensitivity gap:Antigen detection thresholds miss low-viral-load infections, limiting clinical adoption in oncology and immunocompromised patient triage where false negatives carry severe liability.
Strategic Opportunities
- Multiplex respiratory panels:FDA template-based review pathways for combined SARS-CoV-2, influenza, and RSV assays open premium positioning in hospital system seasonal procurement contracts.
- Direct-to-consumer subscription models:Pharmacy chains in the United States pilot recurring delivery services that bypass institutional purchasing committees and capture patient lifetime value.
- ISO 13485 certification arbitrage:Quality management system gaps among emerging Asian contract manufacturers create acquisition targets for established players seeking backward integration into lateral flow production.
Industry Challenges
- Lateral flow assay engineering talent:Shortage of biochemists with immunochromatographic strip design experience extends product development cycles and inflates compensation packages in Boston and San Diego clusters.
- Legacy laboratory information system integration:Hospital IT departments resist API modifications required for point-of-care result transmission, forcing manual data entry that erodes workflow efficiency gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rapid Antigen Testing Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nasopharyngeal Swabs, Saliva Tests, Serum Tests, Fingerstick Tests Delivery Mode: Home Testing, Point-of-Care Testing, Laboratory Testing, Drive-through Testing End User: Hospitals, Clinics, Pharmacies, Laboratories Application: COVID-19, Influenza, Respiratory Infections, Others |
| Companies Covered | Becton, Dickinson and Company, Thermo Fisher Scientific, Abbott Laboratories, PerkinElmer Inc., QuidelOrtho, F. Hoffmann-La Roche AG, bioMérieux SA, Bio-Rad Laboratories Inc., Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rapid Antigen Testing Market Evolving Landscape
Digital readout technologies and connected health platforms are transforming result interpretation from visual band assessment to quantitative smartphone-based analysis, altering liability structures and reimbursement coding.
Fluorescent nanoparticle reporters are rewriting the sensitivity-performance tradeoff that has constrained antigen testing to high-viral-load detection. Reference laboratories in the United States are adopting these substrates for near-patient settings previously reserved for molecular methods. The technology is compressing the acceptable performance gap between rapid and laboratory-grade diagnostics, forcing pricing recalibration across both categories.
CE marking under the EU In Vitro Diagnostic Regulation now requires clinical performance studies with defined sensitivity specifications against PCR comparators. German notified bodies are enforcing stricter documentation of limit-of-detection claims than under previous directives. Manufacturers are responding by consolidating European submissions around higher-specification product variants rather than maintaining parallel economy-tier SKUs.
Home testing protocols are displacing occupational health screening contracts as the primary volume driver for saliva-based formats. Employers in the United States are terminating on-site testing programs and shifting to employee-purchased reimbursement models. This behavioral pivot concentrates demand in retail pharmacy channels and reduces the installed base of workplace point-of-care devices.
Rapid Antigen Testing Market Segmentation
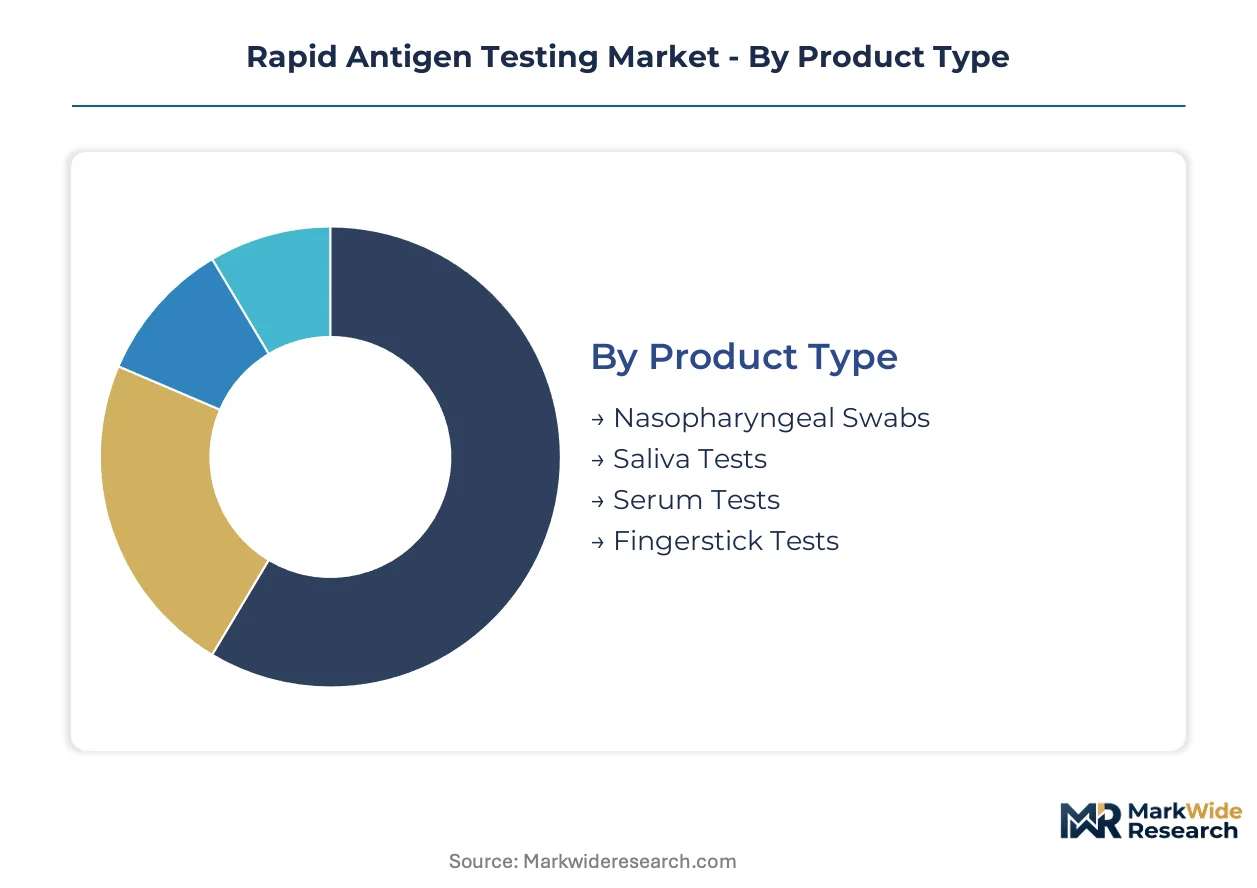
Antigen test manufacturers align R&D roadmaps with distinct performance requirements across specimen types and care settings. Segment boundaries determine pricing architecture, regulatory pathways, and distribution partnerships.
Product Type:
Upgrade cycles favor tests with simplified collection protocols over formats requiring trained phlebotomy staff.
- Nasopharyngeal Swabs:Deep nasal cavity sampling captures higher viral loads for immunochromatographic detection. Established clinical trust in Germany and India sustains volume dominance despite patient discomfort and collection skill requirements.
- Saliva Tests:Non-invasive specimen collection eliminates cold-chain logistics and enables unsupervised home administration. Demand concentrates in US pharmacy retail channels where employers are shifting from on-site occupational health programs to employee reimbursement models.
- Serum Tests:Blood-based detection requires venipuncture or capillary collection, limiting deployment to clinical settings with trained personnel.
- Fingerstick Tests:Capillary blood sampling from fingertip puncture offers intermediate convenience between serum draws and non-invasive alternatives.
Volume placements concentrate in nasopharyngeal formats; the faster expansion belongs to saliva tests.
Delivery Mode:
Cost tiering separates institutional procurement contracts from direct-to-consumer retail channels.
- Point-of-Care Testing:Fifteen-to-thirty-minute turnaround at clinics and physician offices commands premium per-test pricing through hospital system contracts. Workflow integration with laboratory information systems remains a persistent friction point for IT departments resisting API modifications.
- Home Testing:Over-the-counter distribution through pharmacy networks eliminates institutional purchasing committee gatekeeping. CDSCO registration requirements in India concentrate demand in Mumbai, Delhi, and Bangalore retail channels with established OTC diagnostic familiarity.
- Laboratory Testing:Batch processing at centralized facilities achieves economies of scale for high-throughput screening programs.
- Drive-through Testing:Temporary surge capacity deployments peaked during pandemic containment phases and now serve seasonal outbreak response.
Institutional procurement sustains point-of-care margins; home testing is gaining share fastest as subscription models mature.
End User:
Application maturity varies across care settings with divergent reimbursement and liability structures.
- Hospitals:Emergency department triage and pre-surgical screening drive demand for rapid turnaround with documented sensitivity specifications against PCR comparators.
- Clinics:Outpatient settings balance speed requirements with cost constraints through mid-tier product selection.
- Pharmacies:Retail health expansion positions pharmacies as diagnostic access points for consumers seeking convenience without appointment scheduling.
- Laboratories:Reference labs adopt fluorescent nanoparticle reporter technologies to compress the performance gap with molecular methods in near-patient configurations.
Hospital procurement maintains the highest per-test pricing; pharmacy channels show the steepest expansion trajectory.
Application:
Multiplex authorization is compressing single-target test margins and redirecting R&D investment.
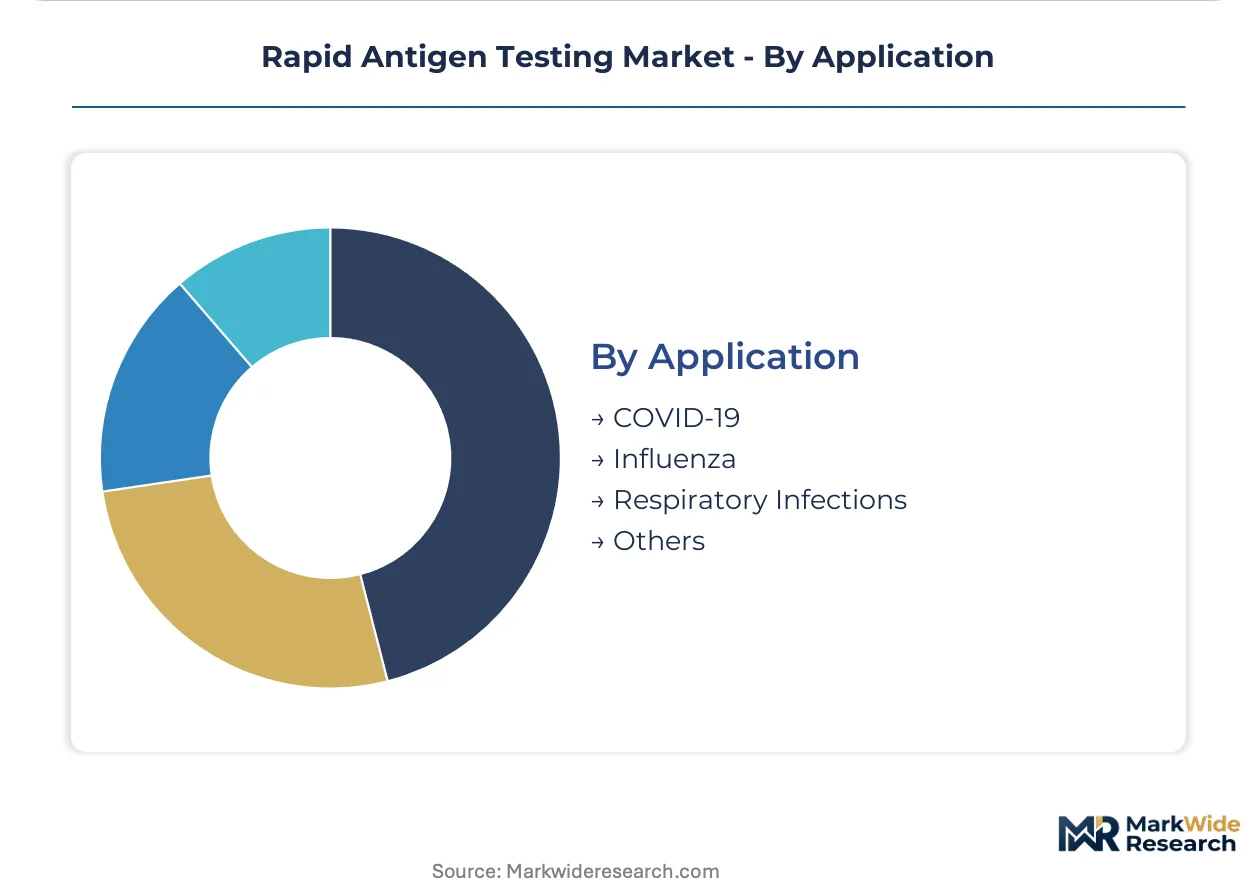
- COVID-19:SARS-CoV-2 detection established the installed base for lateral flow infrastructure and trained consumer behavior on home testing protocols.
- Influenza:Seasonal demand patterns align with hospital system procurement cycles for respiratory panel contracts.
- Respiratory Infections:RSV and combined pathogen targets are capturing R&D allocation as FDA template-based review pathways streamline multiplex submissions.
- Others:Emerging targets including streptococcal and gastrointestinal pathogens extend platform applicability.
COVID-19 placements retain installed base concentration; respiratory combination panels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany's diagnostic laboratory networks, India's tier-1 pharmacy channels, and the United States' retail health expansion. Regulatory divergence across FDA, EMA, and CDSCO frameworks is fragmenting product authorization pathways. Each geography presents distinct procurement and reimbursement architectures.
United States
Pharmacy chains and direct-to-consumer subscription models are displacing occupational health contracts as the primary volume driver. FDA emergency use authorization maintains streamlined template-based review for multiplex respiratory panels. Boston and San Diego clusters host lateral flow assay engineering talent pools where compensation inflation extends development cycles.
Germany
Diagnostic laboratories are expanding decentralized testing menus under EMA self-test pathway requirements. CE marking under EU In Vitro Diagnostic Regulation enforces stricter clinical performance documentation than previous directives. Berlin-Brandenburg and Bavaria notified bodies are consolidating submissions around higher-specification product variants.
India
CDSCO registration requirements for import kits concentrate demand in Mumbai, Delhi, and Bangalore retail channels with established OTC diagnostic familiarity. Pharmacy network penetration accelerates as self-test authorization pathways mature. Domestic manufacturers face tightening quality gates on post-market surveillance obligations.
China
NMPA regulatory requirements shape product entry for lateral flow substrates and nitrocellulose membrane inputs. Manufacturing concentration in coastal provinces exposes supply chains to regional lockdown freight disruption. Yangtze River Delta production clusters dominate substrate material output for global antigen test assembly.
United Kingdom
London and Southeast England retail health networks position pharmacies as diagnostic access points without appointment requirements. Post-Brexit regulatory divergence from EU MDR frameworks creates parallel authorization pathways. NHS procurement committees balance cost constraints against turnaround speed requirements in outpatient settings.
Rapid Antigen Testing Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers hedge against single-target test margin compression. The vendor base stratifies across three tiers: diversified life science conglomerates with point-of-care installed bases, laboratory-grade diagnostic specialists, and emerging contract manufacturers seeking ISO 13485 certification. Two strategic archetypes occupy distinct positions: channel dominators leveraging pharmacy network relationships, and technology licensors monetizing fluorescent nanoparticle reporter patents. Competitive moves center on multiplex R&D allocation and backward integration into lateral flow substrate production.
Among US-based diversified diagnostics manufacturers, Abbott Laboratories, Becton Dickinson and Company, and Thermo Fisher Scientific exemplify contrasting scale strategies. Abbott occupies a position as channel anchor through pharmacy network dominance. Becton Dickinson represents manufacturing scale specialization for clinical-format nasopharyngeal products. Thermo Fisher exemplifies laboratory-grade supply control through hospital system contracting. These three entities collectively illustrate how installed base, manufacturing footprint, and distribution architecture determine competitive positioning without requiring identical strategic postures.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Thermo Fisher Scientific |
| Abbott Laboratories |
| PerkinElmer Inc. |
| QuidelOrtho |
| F. Hoffmann-La Roche AG |
| bioMérieux SA |
| Bio-Rad Laboratories Inc. |
| Danaher Corporation |
| Others |
Value Network & Pricing Analysis
Nitrocellulose membrane spot prices on Asian commodity exchanges cascade through three distinct cost tiers, concentrating margin pressure on mid-scale manufacturers while rewarding integrated players with captive substrate production. The lateral flow assay supply chain funnels pricing power toward German and Chinese producers controlling membrane casting and conjugate pad assembly, forcing brand holders to absorb input volatility or surrender market share.
Pricing Analysis
Volume placements in economy-tier nasopharyngeal formats compress per-unit margins below sustainable thresholds for non-integrated assemblers, while premium multiplex panels retain pricing power through hospital system contracting. Price differentiation rests on CE marking tier under EU MDR and FDA emergency use authorization status, with certified self-test kits commanding retail pharmacy premiums. Cost compression in single-target COVID-19 assays intensifies as inventory liquidation from pandemic stockpiling floods direct-to-consumer channels. Pharmacy procurement committees exhibit highest price sensitivity; reference laboratories purchasing fluorescent nanoparticle reporter platforms show lowest.
Supply Chain Analysis
Reverse logistics for expired or recalled rapid antigen kits remains underdeveloped, with most distributors lacking established return channels for consumer-facing home test formats. Geographic supply concentration centers on China's Yangtze River Delta for nitrocellulose substrates, India's Gujarat and Maharashtra clusters for plastic cassette molding, and Germany's Berlin-Brandenburg corridor for conjugate reagent formulation. Raw material dependencies include gold nanoparticle colloids, glass fiber sample pads, and desiccant canisters. Single-source vulnerability in Asian membrane production exposes assemblers to regional lockdown freight disruption. Distribution runs through pharmacy wholesale networks in developed markets and direct import relationships for CDSCO-registered kits in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race where control over lateral flow substrate production determines survival against margin compression from multiplex assay transition. Players are pursuing backward integration into nitrocellulose membrane casting as the decisive upstream lever.
For Market Incumbents: Acquire membrane casting facilities and conjugate pad production lines to defend against emerging Asian contract manufacturers with ISO 13485 certification gaps. Consolidate around higher-specification product variants for European MDR submissions rather than maintaining parallel economy-tier SKUs. Channel control through pharmacy network exclusivity agreements represents the priority defensive lever against direct-to-consumer subscription entrants. For New Entrants and Emerging Players: Direct-to-consumer telehealth integration offers the lowest barrier entry path around entrenched hospital procurement committees. White-space targets include saliva-based home testing for seasonal respiratory panels in US pharmacy retail and CDSCO-registered import kits for Mumbai and Bangalore pharmacy networks. Telehealth platform partnerships provide the most penetrable go-to-market angle for bypassing institutional purchasing gatekeeping. For Investors and Strategic Acquirers: The window for entry favors contract manufacturers with latent ISO 13485 quality management systems and underutilized lateral flow assembly capacity. Long-term viability hinges on consolidation into three-to-four vertically integrated platform players controlling substrate-through-distribution value capture. Acquisition target archetype: mid-scale Asian assemblers with membrane supply relationships and pending European notified body submissions. Watch fluorescent nanoparticle reporter patent litigation as the inflection signal for technology transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Multiplex Assay Development | FDA template-based review for combined SARS-CoV-2, influenza, and RSV panels opens premium hospital contracting. |
| Backward Integration into Substrates | Captive nitrocellulose membrane production insulates margin structure from Asian supply volatility. |
| Direct-to-Consumer Subscription Launch | Recurring delivery models bypass pharmacy purchasing committees and capture patient lifetime value. |
| CE Marking Pathway Consolidation | German notified body submissions around higher-specification variants reduce MDR transition backlog exposure. |
| Hospital System Partnership | Laboratory information system integration contracts lock in point-of-care placement against home testing erosion. |
Research Methodology
Multi-period observation of CDSCO registration volumes, FDA emergency use authorization filings, and EMA self-test pathway approvals anchored the trend analysis, supplemented by interviews with lateral flow assay engineering directors, hospital procurement committee members, pharmacy chain category managers, and diagnostic laboratory operations heads. Secondary validation drew from FDA 510(k) and EUA submission databases, EMA public assessment reports, CDSCO import registration records, and hospital GPO contract disclosures. Bottom-up test volume modeling triangulated against top-down market size estimates from regulatory filing trends.
Input-output matrix architecture linked specimen type, delivery mode, and end-user segments to pricing tier assumptions across the projection horizon. Segmentation dimensions modeled include product format, care setting, target pathogen panel, and regional regulatory cluster. CAGRs derived from regression analysis of historical authorization-to-adoption lag patterns and procurement contract renewal cycles. Forecast inputs incorporated nitrocellulose membrane price indices and notified body certification queue estimates.
The model holds under stable MDR implementation timelines and sustained FDA template-based review pathways; deviation in European notified body capacity or multiplex assay sensitivity standard revisions would shift volume and value trajectories. Practitioners should monitor CDSCO post-market surveillance enforcement intensity and fluorescent nanoparticle reporter patent expiration schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Cholesterol Testing Products and Services Market
Testing Services
Asia Pacific Sterility Testing Market
Testing Services
Ready-To-Use Laboratory Test Kits Market
Testing Services
Fertility Testing Market
Testing Services
Global Metabolic Testing Market
Testing Services
Europe IVD Regulatory Affairs Outsourcing Market
Testing Services
Instrument Calibration Services Market
Testing Services
Platelet Function Testing Market
Testing Services
Urodynamic Testing Market
Testing Services
Global Direct to Consumer Laboratory Testing Market
Testing Services
United States Esoteric Testing Market
Testing Services
Staphylococcus Aureus Testing Market
Testing Services
Global Anti Thrombin III Testing Market
Testing Services
Medical Device Testing, Inspection, and Certification Market
Testing Services
Irradiation Sterilization Services Market
Testing Services
Monkeypox Testing Market