
 Global Upper Gastrointestinal (GI) Series Market | 2026-2036
Global Upper Gastrointestinal (GI) Series Market Size, Share, and Industry Trends Forecast 2026-2036
Global Upper Gastrointestinal (GI) Series Market Intelligence
The increasing reliance on outsourced teleradiology services for diagnostic interpretation is rebalancing operational models for healthcare providers. This shift allows for greater efficiency and access to specialized radiologists. GE Healthcare leverages its extensive portfolio of digital radiography systems to support these distributed workflows. In parallel, Motus GI Holdings Inc. specializes in novel technologies that augment procedural effectiveness within GI units.
An Upper Gastrointestinal (GI) Series is a fluoroscopic imaging procedure used to examine the esophagus, stomach, and duodenum. It involves the patient ingesting a contrast agent, typically barium sulfate, to visualize the internal lining of these organs. Demand for Double Contrast techniques is rising for detailed mucosal evaluation in applications like Gastric Ulcer detection. Concurrently, Digital Radiography technology is becoming the standard, displacing older imaging systems in most Diagnostic Imaging Centers.
Regulatory oversight from bodies like the U.S. FDA and Europe's EMA establishes strict guidelines for the approval of contrast media. Medical device regulations, including the EU's MDR, impose rigorous safety and performance standards on fluoroscopy equipment. Compliance with these frameworks is essential for market access in key countries like the United States and within the European Union. Stakeholders must now prioritize investment in systems that support enhanced PACS Integration and comply with evolving data privacy rules.
Market Dynamics
The central dynamic shaping the market is the technology upgrade cycle within diagnostic facilities, driven by the transition from analog to digital radiography. This shift is fundamentally altering procedural workflows, data management, and capital expenditure priorities for healthcare providers globally.
Growth Catalysts
- Double Contrast Techniques:The rising clinical preference for double-contrast studies to achieve superior mucosal visualization is spurring demand for advanced fluoroscopy systems capable of supporting these detailed examinations for conditions like Gastric Ulcers.
- Demographic Shifts in Germany:Germany's aging population and highly developed healthcare infrastructure create concentrated demand for diagnostic imaging, positioning the country as a key driver for market growth in Europe.
- Diagnostic Center Modernization:Independent Diagnostic Imaging Centers are actively upgrading their equipment portfolios, replacing older systems with modern Digital Radiography technology to improve efficiency and maintain a competitive edge.
Market Restraints
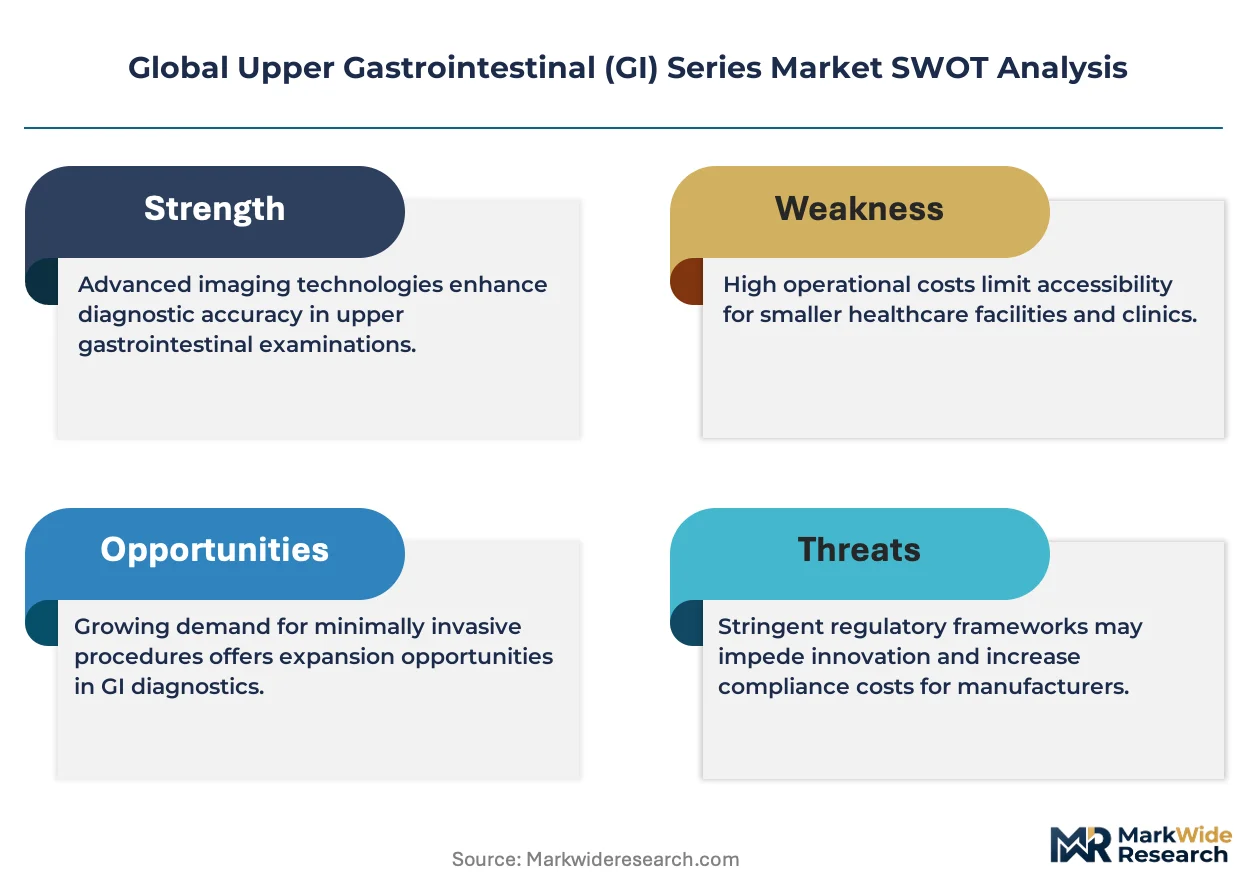
- High Capital Investment:The substantial cost associated with acquiring new Flat Panel Detector and Digital Radiography systems presents a significant financial barrier for smaller hospitals and clinics, slowing technology adoption in some segments.
- Alternative Diagnostic Modalities:Endoscopy offers a direct visualization and therapeutic alternative to fluoroscopic procedures, posing a substitution threat, particularly in cases where a biopsy or intervention is anticipated.
- Stringent Contrast Media Regulation:The rigorous and lengthy approval pathways for new contrast agents, enforced by regulators like the U.S. FDA and Europe's EMA, limit the introduction of innovative formulations.
Strategic Opportunities
- Teleradiology Integration:Expanding the integration of fluoroscopy systems with teleradiology platforms offers an opportunity to provide specialized diagnostic interpretation services to underserved or remote healthcare facilities.
- Emerging Market Expansion:There is significant opportunity for market entry and expansion in developing regions of Latin America and Southeast Asia, where healthcare infrastructure investment is rising.
- Specialized Contrast Agents:Developing and marketing barium sulfate formulations tailored for specific patient populations, such as pediatric or bariatric patients, addresses unmet clinical needs and creates new revenue streams.
Industry Challenges
- Radiologist and Technician Shortage:A scarcity of technologists and radiologists with expertise in modern digital fluoroscopy equipment and advanced imaging techniques creates operational bottlenecks and limits service expansion for providers.
- System Interoperability:Ensuring seamless integration of new Upper GI series equipment with diverse legacy PACS and Electronic Health Record systems remains a significant technical and logistical challenge for many healthcare organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Upper Gastrointestinal (GI) Series Market |
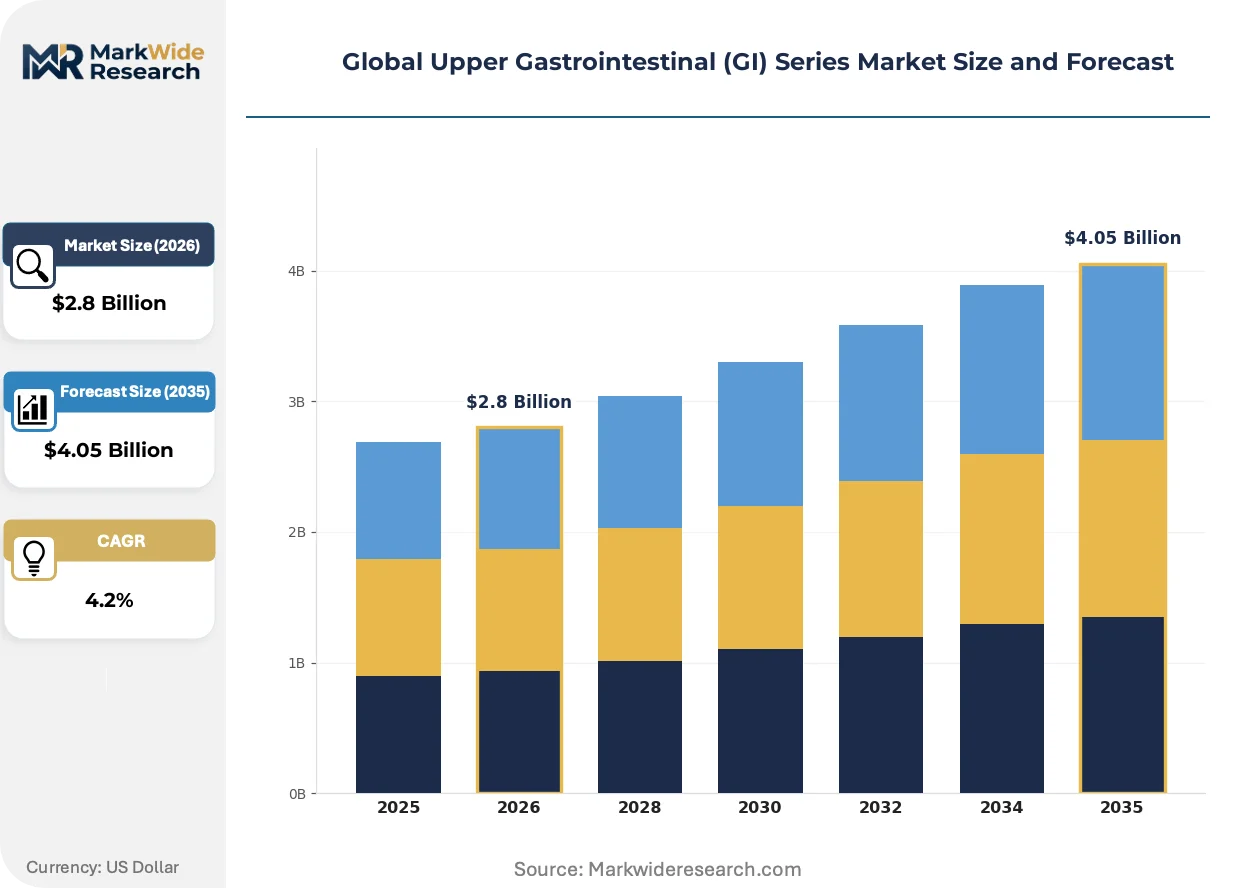
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.05 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Barium Swallow, Fluoroscopy, Esophagram, Upper GI Radiography, Single Contrast, Double Contrast Technology: Digital Radiography, Computed Radiography, Flat Panel Detector, Portable X-Ray, PACS Integration, 3D Imaging End User: Diagnostic Imaging Centers, Outpatient Clinics, Specialized Radiology Units, Academic Hospitals, Ambulatory Centers Application: Gastroesophageal Reflux, Gastric Ulcers, Esophageal Strictures, Hiatal Hernia, Motility Disorders |
| Companies Covered | Eisai Co. Ltd, Purdue Pharma L.P., Motus GI Holdings Inc., AstraZeneca, Alfa Wassermann SPA, GE Healthcare, Cadila Pharmaceuticals Limited, Ironwood Pharmaceuticals Inc., GastroIntestinal Specialists LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Upper Gastrointestinal (GI) Series Market Strategic Shifts & Innovations
Digitalization of the imaging workflow is redefining the standards for procedural efficiency and diagnostic accuracy in Upper GI examinations. Data-centric innovations are enabling more collaborative and distributed models of care, moving beyond the physical confines of the radiology department.
Artificial intelligence-based image analysis software provides decision support during fluoroscopic procedures. Diagnostic Imaging Centers and large hospital networks are adopting this technology to improve the detection of subtle mucosal abnormalities and increase radiologist throughput. This software is integrating with digital radiography systems and PACS, creating a more automated and precise workflow.
The European Union's Medical Device Regulation (MDR) establishes more stringent requirements for clinical evidence and post-market surveillance on all medical equipment. This policy directly increases the time and cost associated with bringing new fluoroscopy systems to the European market. The medical device segment is most affected, forcing manufacturers to invest significantly in generating robust clinical data to maintain their CE marking.
A distinct behavioral shift is occurring as healthcare providers increasingly use outsourced teleradiology firms for diagnostic interpretation. This model allows hospitals and clinics to manage costs and gain access to GI radiology subspecialists without employing them full-time. The trend is most visible in the United States and the United Kingdom, where it helps address radiologist shortages and provides after-hours coverage.
Global Upper Gastrointestinal (GI) Series Market Segmentation
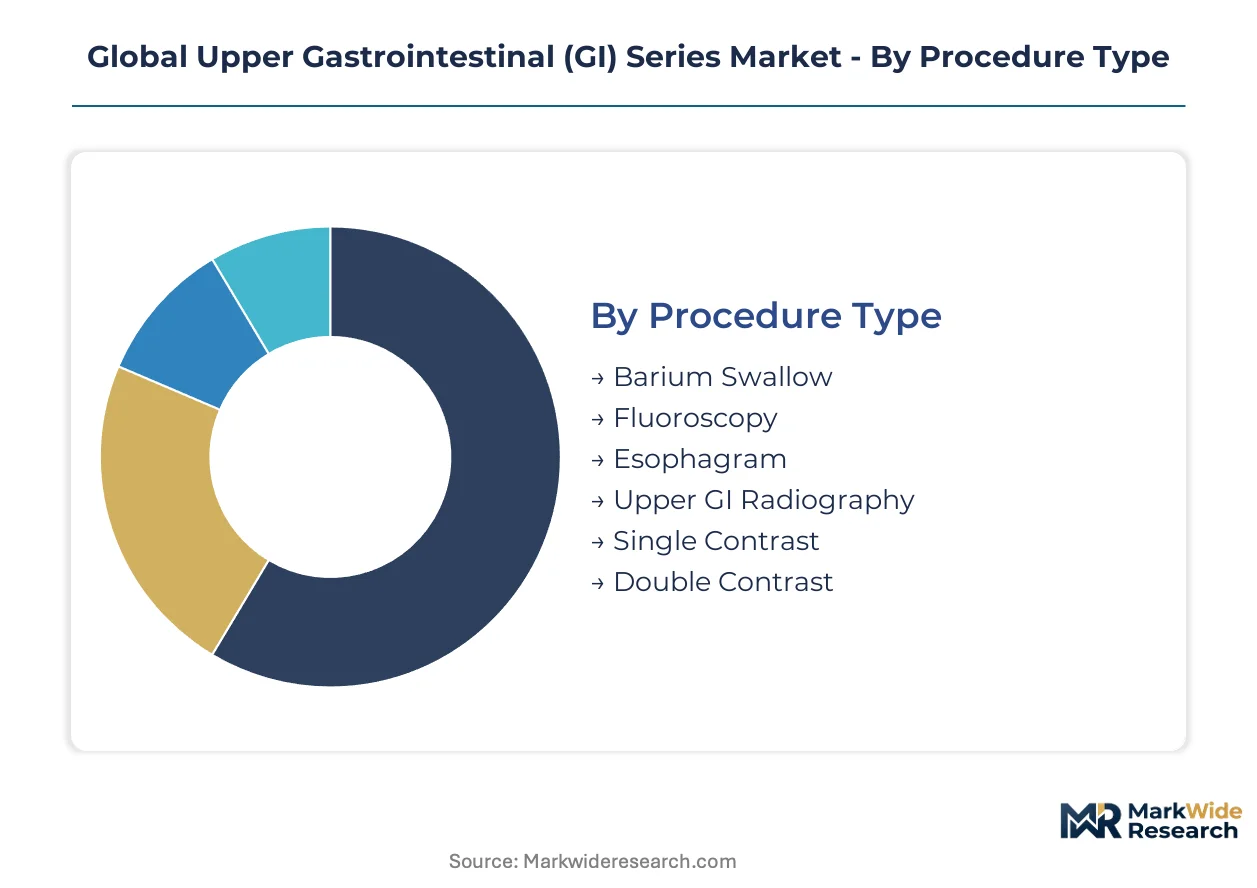
The Global Upper Gastrointestinal (GI) Series Market is analyzed across key dimensions, providing a granular understanding of its structure and operational dynamics. This segmentation helps stakeholders identify specific areas of demand, technological shifts, and end-user preferences within the diagnostic imaging landscape.
Procedure Type:
The market for Upper GI Series procedures is differentiated by the specific imaging techniques and contrast methods employed.
- Barium Swallow:This procedure specifically examines the pharynx and esophagus, using barium sulfate as a contrast agent to visualize swallowing function and structural abnormalities. Demand for this technique remains consistent for initial assessment of dysphagia and esophageal reflux symptoms.
- Fluoroscopy:This dynamic imaging technique provides real-time visualization of the GI tract's movement and structure, crucial for assessing motility disorders and anatomical variations. Demand for fluoroscopy is concentrated in specialized radiology units that require live imaging capabilities for complex diagnostic cases.
- Esophagram:An esophagram focuses on the esophagus, often performed to evaluate conditions like strictures, tumors, or hiatal hernias. It is frequently employed in conjunction with a barium swallow.
- Upper GI Radiography:This general term encompasses X-ray examinations of the esophagus, stomach, and duodenum, often using barium contrast. It serves as a foundational diagnostic tool in many healthcare settings.
- Single Contrast:This technique involves filling the GI tract with a single layer of barium, primarily used to visualize gross anatomical features and large lesions. It is a simpler, quicker procedure often selected for initial screening.
- Double Contrast:This advanced technique uses both barium and gas to distend the GI tract, providing a thin coating of barium that highlights mucosal details and subtle lesions. Demand for double contrast techniques is rising for detailed mucosal evaluation in applications like Gastric Ulcer detection.
Mature deployment sits with Single Contrast. Newer deployment is concentrated in Double Contrast.
Technology:
Technology segmentation highlights the foundational imaging systems and data management solutions driving diagnostic capabilities.
- Digital Radiography:This technology captures X-ray images directly onto digital sensors, offering immediate image viewing, enhanced post-processing capabilities, and reduced radiation exposure. Digital Radiography technology is becoming the standard, displacing older imaging systems in most Diagnostic Imaging Centers.
- Flat Panel Detector:These advanced digital detectors replace traditional film or computed radiography plates, providing superior image resolution, wider dynamic range, and improved procedural efficiency. Demand for Flat Panel Detector technology is concentrated in facilities upgrading their equipment for higher diagnostic accuracy and faster workflows.
- Computed Radiography:This method uses photostimulable phosphor plates to capture X-ray images, which are then scanned and converted into digital data. It offers a bridge between analog and fully digital systems.
- Portable X-Ray:These mobile X-ray units allow for imaging at the patient's bedside or in remote locations, providing flexibility for non-ambulatory patients or during emergency situations. They are crucial for expanding diagnostic access.
- PACS Integration:Picture Archiving and Communication Systems (PACS) integration enables seamless storage, retrieval, and distribution of medical images across healthcare networks. This capability supports efficient teleradiology workflows and collaborative care models.
- 3D Imaging:While less common for routine Upper GI Series, advanced 3D imaging techniques can provide multi-planar views and volumetric data for complex anatomical assessments. This technology offers enhanced spatial understanding.
Digital Radiography represents the fastest-growing trajectory in imaging system upgrades.
End User:
End-user segmentation reflects the diverse healthcare settings where Upper GI Series procedures are performed.
- Diagnostic Imaging Centers:These specialized facilities focus solely on diagnostic imaging services, often equipped with the latest technology and staffed by expert radiologists. Independent Diagnostic Imaging Centers are actively upgrading their equipment portfolios.
- Academic Hospitals:Large teaching hospitals integrate patient care with medical education and research, performing a high volume of complex GI procedures and often driving technological adoption. These institutions frequently require advanced imaging capabilities.
- Outpatient Clinics:These clinics provide non-emergency medical services, including diagnostic tests, offering convenience and accessibility for routine Upper GI Series examinations. They serve a significant patient population seeking specialized care.
- Specialized Radiology Units:Dedicated units within hospitals or larger clinics focus on specific imaging modalities or body systems, providing highly specialized expertise for GI diagnostics. These units often handle complex cases.
- Ambulatory Centers:These facilities offer same-day medical procedures and diagnostic services, providing a cost-effective alternative to hospital-based care for certain Upper GI Series examinations. They cater to patients requiring less intensive oversight.
Diagnostic Imaging Centers lead in equipment modernization while outpatient clinics prioritize accessibility.
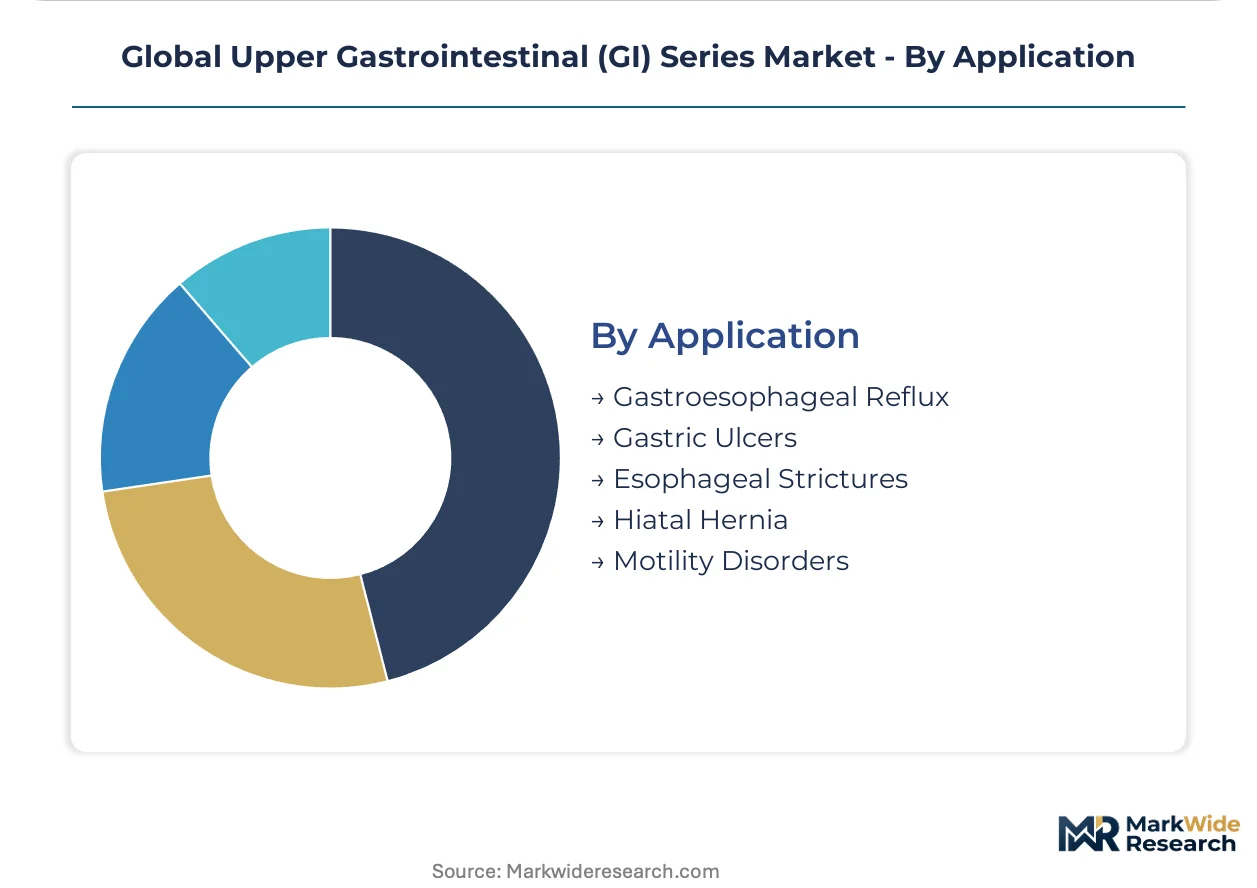
Application:
Application segmentation outlines the primary clinical conditions diagnosed using Upper GI Series examinations.
- Gastroesophageal Reflux:This application involves diagnosing the backward flow of stomach acid into the esophagus, which can cause heartburn and esophageal damage. Upper GI Series helps identify anatomical causes of reflux.
- Gastric Ulcers:This application focuses on detecting open sores that develop on the lining of the stomach, which can cause pain and bleeding. Demand for Double Contrast techniques is rising for detailed mucosal evaluation in applications like Gastric Ulcer detection.
- Esophageal Strictures:This application identifies narrowing of the esophagus, often caused by inflammation, scarring, or tumors, which can impede swallowing. Fluoroscopy is essential for assessing the extent of strictures.
- Hiatal Hernia:This application diagnoses a condition where part of the stomach pushes up through the diaphragm into the chest cavity. Upper GI Series clearly visualizes the stomach's position.
- Motility Disorders:This application evaluates abnormalities in the muscular contractions of the esophagus and stomach, which can affect food transport. Dynamic fluoroscopic imaging is crucial for assessing these functional issues.
Gastric Ulcers drive demand for detailed mucosal imaging, with Gastroesophageal Reflux requiring frequent diagnostic assessment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for Upper GI Series procedures concentrates in regions with advanced healthcare infrastructure and significant aging populations. Diagnostic Imaging Centers globally are upgrading their capabilities, driving technology adoption. This modernization supports detailed mucosal evaluations for conditions like Gastric Ulcers.
United States
The United States market experiences sustained demand due to a high prevalence of various gastrointestinal disorders. U.S. FDA regulations establish stringent guidelines for new contrast media and fluoroscopy equipment. Major medical device manufacturers in the Boston area invest in developing next-generation digital radiography systems.
Germany
Germany's aging population and highly developed healthcare infrastructure generate substantial demand for advanced diagnostic imaging. The EU's MDR imposes rigorous safety and performance standards on all fluoroscopy equipment. Specialized radiology units in cities like Munich integrate Flat Panel Detector technology.
Japan
Japan exhibits robust demand for Upper GI Series due to proactive gastric cancer screening programs and a sophisticated healthcare sector. The PMDA ensures strict adherence to medical device regulations for diagnostic imaging systems. Leading academic hospitals in Tokyo deploy advanced digital radiography systems with PACS integration.
China
China's expanding healthcare infrastructure and rising disposable income fuel increased demand for diagnostic procedures. The NMPA's regulatory framework dictates approval for fluoroscopy equipment and contrast agents. New Diagnostic Imaging Centers in Shanghai modernize equipment portfolios with Digital Radiography technology.
Brazil
Brazil represents an emerging market opportunity driven by increasing healthcare infrastructure investments and a growing middle class. ANVISA regulations govern the import and use of medical devices and contrast media. Private hospital networks in São Paulo actively upgrade to modern Digital Radiography systems.
Global Upper Gastrointestinal (GI) Series Market Key Industry Players
Technology upgrade cycles dominate the current landscape, driving shifts in competitive positioning among market participants. The market exhibits a tiered structure, featuring large diversified healthcare technology providers and specialized medical device innovators. Strategic archetypes include established imaging system manufacturers offering comprehensive solutions and emerging companies focused on enhancing procedural effectiveness. Portfolio diversification, geographic expansion, and strategic partnerships are dominant competitive moves.
Among large diversified players, GE Healthcare occupies a position as a leading provider of digital radiography systems and integrated workflow solutions. Motus GI Holdings Inc. exemplifies a specialized innovator, focusing on novel technologies that augment procedural effectiveness within GI units. AstraZeneca, a global pharmaceutical company, represents a significant player in the broader gastrointestinal health sector, often involved in related therapeutic areas and potentially contrast agent development. These companies anchor different segments of the market, from imaging equipment to specialized procedural tools and pharmaceutical support.
| Leading Market Players |
|---|
| Eisai Co. Ltd |
| Purdue Pharma L.P. |
| Motus GI Holdings Inc. |
| AstraZeneca |
| Alfa Wassermann SPA |
| GE Healthcare |
| Cadila Pharmaceuticals Limited |
| Ironwood Pharmaceuticals Inc. |
| GastroIntestinal Specialists LLC |
| Others |
Cost & Logistics Intelligence
European Union's Medical Device Regulation (MDR) establishes stringent requirements for product lifecycle and material safety, gating qualified supply of fluoroscopy equipment and influencing premium-tier pricing access.
Pricing Analysis
High-volume transactional sales for basic Upper GI Radiography contrast agents compete on cost, while specialized fluoroscopy systems command higher margins. Pricing stratifies across premium, standard, and economy tiers based on Flat Panel Detector technology and PACS Integration capabilities. Pricing softness in standard contrast agents stems from commodity-like competition among suppliers. Outpatient clinics exhibit higher price sensitivity for basic systems, whereas academic hospitals prioritize advanced features over cost.
Supply Chain Analysis
Direct distribution channels serve large diagnostic imaging centers and academic hospitals for fluoroscopy equipment, ensuring specialized installation and support. Geographic supply concentration for advanced Digital Radiography systems lies in Germany and the United States, while China contributes to component manufacturing. Barium sulfate is a primary input for contrast agents, and digital sensors are critical for Flat Panel Detector technology. Single-source vulnerability for specialized digital components poses a structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Upper GI Series market faces supply constraints, primarily due to limited manufacturing capacity for advanced Flat Panel Detector technology, which props up pricing for high-resolution systems.
For Market Incumbents:Cement market leadership by investing in next-generation Digital Radiography R&D, particularly for AI-based image analysis software. Consolidate market share through strategic partnerships with teleradiology providers, expanding service reach. This counters the substitution threat from endoscopy by offering superior diagnostic detail. Focus R&D efforts on enhancing image resolution and procedural efficiency to maintain a competitive edge.
For New Entrants and Emerging Players:The U.S. FDA's expedited review pathways for novel contrast agents open a window for specialized barium sulfate formulations targeting pediatric patients. Target underserved outpatient clinics in Latin America and Southeast Asia with portable X-ray solutions. A value-based pricing model for accessible, mobile diagnostic units offers a compelling go-to-market angle. Focus on regional regulatory compliance to streamline market entry.
For Investors and Strategic Acquirers:Sustained growth in teleradiology service adoption is the leading indicator that distributed diagnostic models offer long-term value. The market shows consistent demand driven by demographic shifts and technological upgrades, ensuring long-term viability. Identify vertically integrated mid-cap specialists in digital radiography with strong PACS integration capabilities as key acquisition targets. Increasing M&A activity among software providers for image analysis indicates a strong signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-powered image analysis software | Enhances diagnostic accuracy for Gastric Ulcers, improving radiologist throughput. |
| Expand Flat Panel Detector manufacturing capacity | Addresses supply constraints for advanced Digital Radiography systems, meeting global demand. |
| Form strategic partnerships with teleradiology firms | Extends diagnostic interpretation services to underserved regions, leveraging specialized radiologists. |
| Launch specialized barium sulfate formulations | Meets unmet clinical needs for pediatric patients, opening new revenue streams. |
| Acquire firms specializing in PACS integration | Streamlines workflow for Diagnostic Imaging Centers, ensuring seamless data management. |
Research Approach
Trade association data, regulatory filings from the U.S. FDA, and medical device customs records anchored secondary inputs for this study. Primary interviews with radiologists, hospital procurement managers, medical device engineers, and teleradiology service providers validated market dynamics. This approach combined bottom-up volume analysis with top-down market sizing for comprehensive triangulation.
Data-stream reconciliation across multiple sources informed the comprehensive analytical framework used to project market trajectories. The model incorporated segmentation dimensions including Procedure Type, Technology, End User, Application, and regional healthcare expenditure across the analysis window. Compound Annual Growth Rates were computed from historical trends and projected future demand, considering population demographics in Germany and diagnostic imaging center modernization rates.
The model assumes a particular technology adoption path; alternative pathways for Artificial Intelligence integration in image analysis would alter the outlook. Forecasts reflect these documented assumptions. Regulatory changes from the EU's MDR or shifts in healthcare reimbursement policies could revise forecasts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Solutions
Middle East and Africa Lung Cancer Screening Software Market
Diagnostic Solutions
Global Enzyme-Linked Immunosorbent Assay (ELISA) Market
Diagnostic Solutions
Protein Assays Market
Diagnostic Solutions
Near-Patient Molecular Solutions Market
Diagnostic Solutions
Global Ioversol Market
Diagnostic Solutions
Mobile Applications for Melanoma Detection Market
Diagnostic Solutions
Multiple Reaction Monitoring Assay Market
Diagnostic Solutions
Total Bile Acid Assay Kit Market
Diagnostic Solutions
Global Lung Cancer Screening Software Market
Diagnostic Solutions
Oral Screening Systems Market
Diagnostic Solutions
Protein Detection and Quantification Market
Diagnostic Solutions
Hepatitis C Diagnosis and Treatment Market
Diagnostic Solutions
North America Lung Cancer Screening Software Market
Diagnostic Solutions
Europe Lung Cancer Screening Software Market