
 Global Ioversol Market | 2026-2036
Global Ioversol Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ioversol Market Analysis
Hospital procurement of contrast media is pivoting toward centralized purchasing agreements, consolidating volume across integrated delivery networks. Guerbet leverages its European manufacturing footprint to sustain supply continuity across Western markets. Jiangsu Hengrui Medicine Co. anchors its position through backward integration into active pharmaceutical ingredient production. Mallinckrodt Pharmaceuticals competes on geographic dominance in North American distribution channels.
Ioversol is a non-ionic, low-osmolar iodinated contrast agent containing three iodine atoms per molecule, synthesized through multi-step organic substitution of a triiodinated benzene ring core; it functions primarily to enhance radiographic visualization of vascular structures and organs during computed tomography and angiographic procedures. The intravenous product type dominates procedural volume due to its established safety profile in CT angiography and cardiac catheterization, while the cardiology application segment captures significant margin pools given the complexity of interventional procedures. Parenteral delivery mode leads hospital adoption, though oral formulations retain niche utility in select gastrointestinal imaging protocols.
The FDA oversees contrast agent approval and post-market surveillance in the United States, while the EMA governs centralized marketing authorization across European Union member states; both agencies enforce pharmacovigilance requirements that directly shape manufacturer labeling investments and clinical trial obligations. China's NMPA implements GB standards for pharmaceutical quality that condition market access for imported and domestically produced iodinated contrast media. Stakeholders must monitor evolving regulatory divergence between major jurisdictions to optimize registration strategies and avoid supply disruptions from compliance gaps.
Market Dynamics
Centralized hospital procurement agreements are consolidating purchasing power across integrated delivery networks, compressing margins for iodinated contrast media suppliers while favoring manufacturers with scale and geographic reach.
Growth Catalysts
- CT angiography volume expansion:Rising cardiovascular disease screening protocols in the United States and China are driving procedural demand for non-ionic contrast agents.
- FDA labeling guidance updates:Enhanced safety documentation requirements are accelerating product differentiation investments among compliant manufacturers.
- Diagnostic infrastructure buildout:Germany's hospital modernization programs are expanding installed CT scanner base and associated contrast media consumption.
Market Restraints
- Iodine raw material concentration:Chilean and Japanese iodine suppliers control critical feedstock, exposing producers to supply disruption risk.
- EMA pharmacovigilance burden:Post-market surveillance obligations for iodinated contrast agents inflate regulatory compliance costs across European markets.
- Ultrasound contrast agent substitution:Microbubble-based echocardiography agents are displacing iodinated products in select cardiac imaging applications.
Strategic Opportunities
- India diagnostic imaging penetration:CDSCO streamlined approval pathways for contrast media are opening access to underpenetrated tier-2 and tier-3 hospital markets.
- Dual-energy CT protocol adoption:Advanced scanner technology is creating demand for optimized contrast dosing protocols and specialized formulation variants.
- Outpatient imaging center channel expansion:Freestanding diagnostic facilities in the United States are diversifying beyond hospital-centric distribution models.
Industry Challenges
- Radiopharmacist staffing shortages:Specialized contrast administration expertise gaps are constraining procedure throughput in high-volume cardiac centers.
- Legacy PACS integration complexity:Contrast tracking and documentation systems require costly interoperability upgrades with existing hospital informatics infrastructure.
- Batch release timeline compression:Sterile manufacturing validation and quality control protocols are extending production lead times amid demand volatility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ioversol Market |
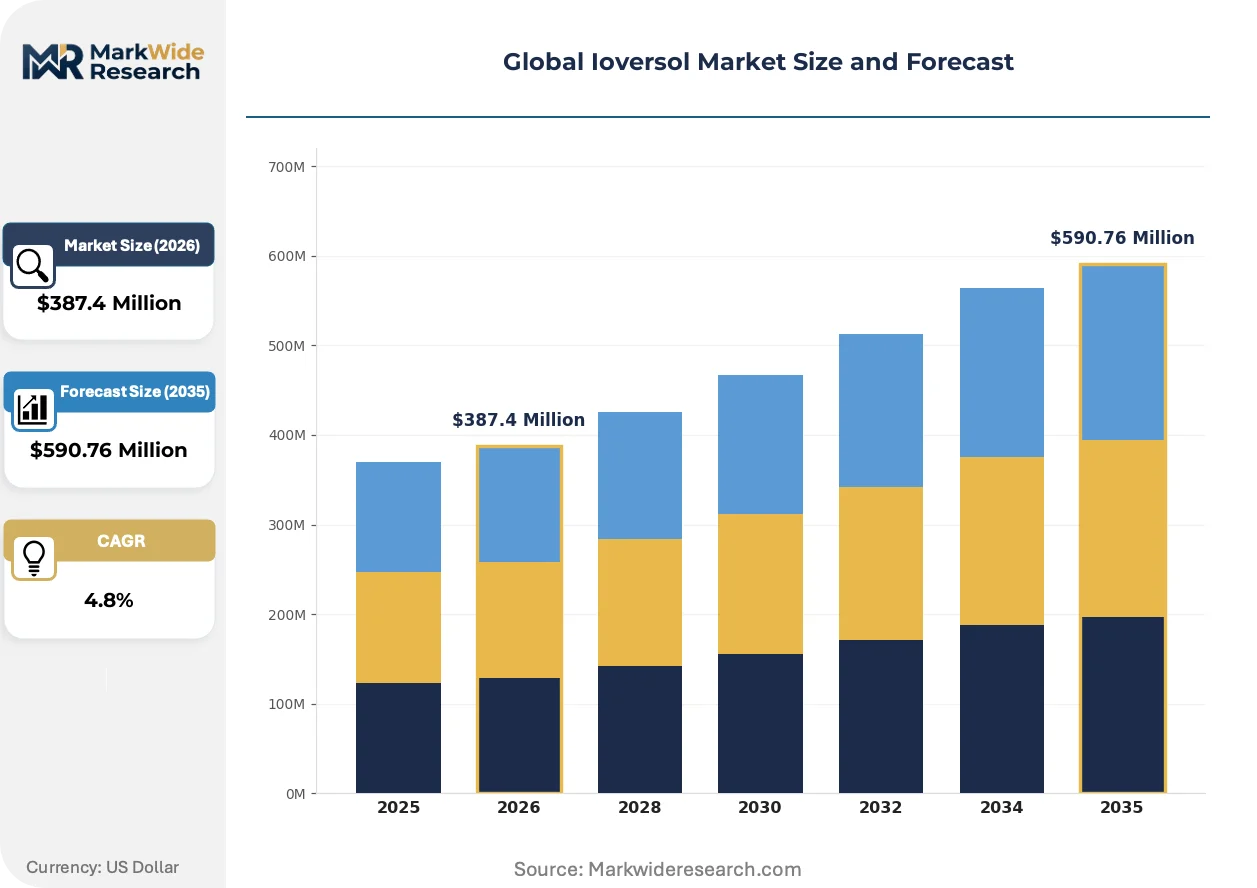
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $590.76 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intravenous, Injection, Contrast Agent, Diagnostic Aid Delivery Mode: Oral, Parenteral, Topical, Inhalation End User: Hospitals, Diagnostic Centers, Outpatient Clinics, Research Laboratories Application: Cardiology, Radiology, Oncology, Gastroenterology |
| Companies Covered | Liebel-Flarsheim Company LLC, Guerbet, Jiangsu Hengrui Medicine Co., Mallinckrodt Pharmaceuticals, Ultraject, China Resources Pharmaceutical Co., HB Ocean, Stellence Pharmscience Pvt. Ltd., Novalek Pharmaceuticals Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ioversol Market Emerging Trajectories
Automation of contrast injection protocols and real-time patient monitoring systems is redefining clinical workflow efficiency in radiology departments worldwide.
AI-enabled contrast dose optimization software is automating weight-based and renal-function-adjusted injection calculations. Major academic medical centers in the United States and Germany are deploying these systems to reduce contrast-induced nephropathy incidence. The technology is automating previously manual dosing decisions while generating procedure data for quality registry submissions.
REACH registration requirements for iodinated pharmaceutical intermediates are tightening supply chain documentation obligations for European manufacturers. EMA guidance on nitrosamine impurity thresholds is forcing reformulation investments across multiple contrast agent portfolios. Injectable product categories face the steepest compliance cost escalation as analytical testing protocols expand.
Hospital buying consortiums are consolidating annual contrast media contracts into multi-year sole-source agreements with price-volume indexing. Integrated delivery networks in the United States are displacing fragmented departmental purchasing through centralized formulary control. This concentration is most pronounced in Texas and Florida markets where health system consolidation has advanced furthest.
Global Ioversol Market Segmentation
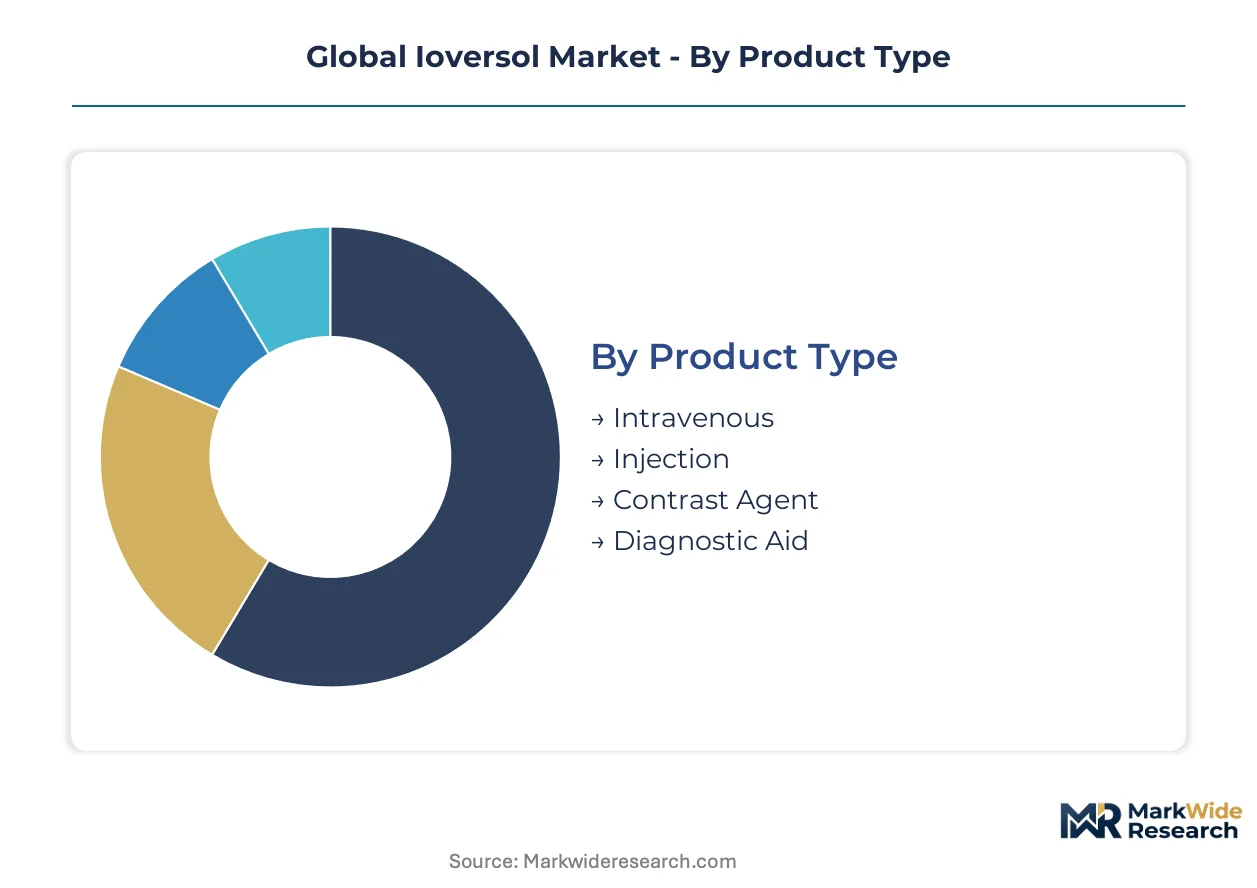
Ioversol segmentation reveals distinct procurement patterns across delivery modes and clinical settings. Hospital formulary committees evaluate product variants against specific procedural protocols and patient risk profiles.
Product Type:
Replacement cycles for contrast media inventory accelerate as hospitals adopt weight-based dosing automation and integrate AI-enabled injection systems.
- Intravenous:Non-ionic formulation administered directly into venous circulation for rapid systemic distribution during CT angiography. United States cardiac catheterization labs favor this route for its established safety documentation and compatibility with power injector systems.
- Injection:Sterile solution packaged in pre-filled syringes or vials for manual or automated administration. China's expanding diagnostic imaging infrastructure drives concentrated procurement of multi-dose containers for high-throughput CT suites.
- Contrast Agent:Iodinated compound engineered for radiographic opacity enhancement across vascular and soft tissue imaging. Germany's hospital modernization programs specify osmolality parameters for pediatric and renal-impaired populations.
- Diagnostic Aid:Ancillary formulation supporting specialized procedural workflows including cholangiography and arthrography. Niche applications in interventional radiology suites.
Intravenous formulations sit at the top of the volume ranking, with Diagnostic Aid climbing the fastest as interventional procedures diversify.
Delivery Mode:
Cost tier differentiation separates premium sterile injectables from economy oral preparations in hospital procurement negotiations.
- Parenteral:Direct bloodstream delivery via intravenous or intra-arterial routes dominates procedural economics. United States integrated delivery networks consolidate annual contracts around parenteral volume commitments.
- Oral:Enteric-coated preparation for gastrointestinal tract opacification during CT enterography. Retains utility in pediatric populations where intravenous access proves challenging.
- Topical:Mucosal application for fistulography and sinography procedures. Limited demand concentrates in specialized ENT and surgical practices.
- Inhalation:Experimental aerosolized delivery for bronchial tree visualization. Research laboratory procurement only.
Parenteral delivery commands the highest procurement spend, with Oral formulations expanding most quickly in pediatric-focused facilities.
End User:
Customer type segmentation tracks divergent buying authority between centralized hospital systems and fragmented outpatient channels.
- Hospitals:Acute care institutions with integrated radiology departments and cardiac catheterization laboratories. China's tier-1 cities anchor procurement volume as public hospital networks expand CT scanner installation.
- Diagnostic Centers:Freestanding imaging facilities operating outside hospital ownership. United States outpatient channel growth accelerates as Medicare reimbursement shifts favor site-neutral payment.
- Outpatient Clinics:Ambulatory surgical centers and physician office labs performing limited contrast studies. Procurement scales with procedure volume thresholds.
- Research Laboratories:Academic medical centers and contract research organizations conducting imaging biomarker studies. FDA investigational new drug requirements govern supply access.
Hospitals retain dominant procurement volume, with Diagnostic Centers gaining share fastest as site-of-care migration accelerates.
Application:
Margin concentration varies sharply across clinical specialties, with interventional cardiology commanding premium pricing.
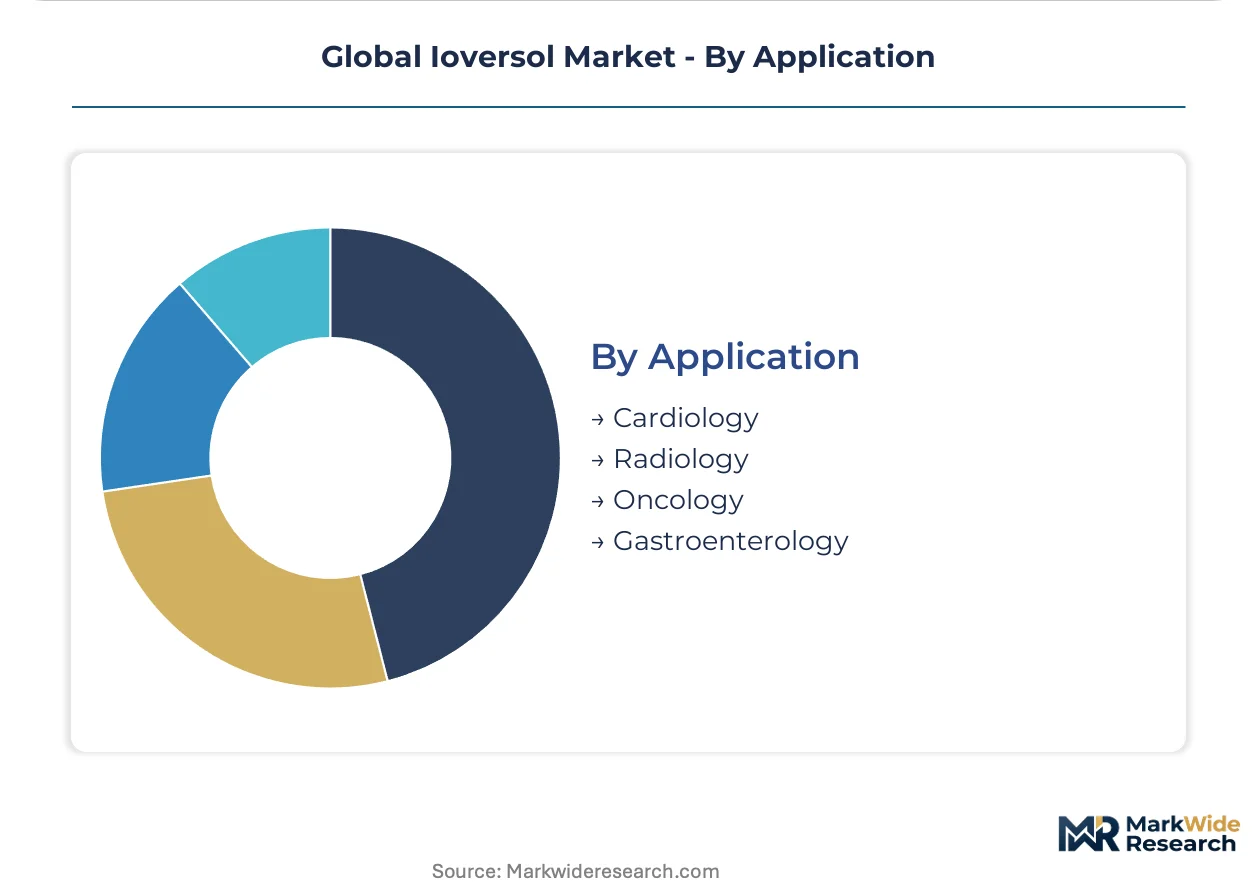
- Cardiology:Coronary angiography and electrophysiology procedures require precise contrast timing and dosing. Germany's statutory health insurance funds reimburse at elevated rates for complex interventional cases.
- Radiology:Cross-sectional body imaging including CT urography and pulmonary angiography represents the procedural volume base. China's NMPA registration pathways prioritize radiology indications for new market entrants.
- Oncology:Tumor perfusion imaging and treatment response assessment in academic medical centers. Dual-energy CT protocols create demand for specialized concentration formulations.
- Gastroenterology:CT colonography and enterography applications. Screening program adoption in United States health systems drives intermittent demand spikes.
Cardiology captures the steepest margin tier, with Oncology applications climbing fastest as precision imaging protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hospital modernization programs contrast with India's diagnostic imaging penetration gaps, revealing divergent infrastructure maturity across major markets. The United States and China anchor procurement volume through distinct channel structures. Japan maintains specialized formulation requirements that condition manufacturer compliance investments.
United States
Medicare site-neutral payment shifts accelerate outpatient imaging center proliferation beyond hospital ownership. FDA updated guidance on iodinated contrast agent safety labeling imposes documentation investments on all suppliers. Texas and Florida health system consolidation drives centralized formulary control across integrated delivery networks.
China
Tier-1 city public hospital networks expand CT scanner installation at pace with cardiovascular disease screening protocol adoption. NMPA implements GB standards for pharmaceutical quality that condition market access for domestic and imported iodinated contrast media. Yangtze River Delta manufacturing clusters concentrate active pharmaceutical ingredient production capacity.
Germany
Statutory health insurance funds reimburse complex interventional cardiology at elevated rates, sustaining premium formulation demand. EMA pharmacovigilance obligations inflate regulatory compliance costs across iodinated contrast agent portfolios. Bavaria and Baden-Württemberg hospital systems specify osmolality parameters for pediatric and renal-impaired populations.
India
Tier-2 and tier-3 hospital markets remain underpenetrated despite CDSCO streamlined approval pathways for contrast media. The national pharmaceutical regulator enforces quality documentation that domestic manufacturers must satisfy for institutional procurement. Maharashtra and Gujarat diagnostic infrastructure buildout concentrates in private hospital chains.
Japan
PMDA maintains stringent post-market surveillance requirements that extend product registration timelines for iodinated agents. METI industrial policy supports domestic pharmaceutical manufacturing self-sufficiency in critical medical supplies. Kanto region academic medical centers pioneer dual-energy CT protocol adoption requiring specialized concentration formulations.
Global Ioversol Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation and distribution capabilities. The vendor base organizes into three tiers: integrated pharmaceutical conglomerates with contrast media divisions, regional manufacturers with captive iodine supply, and contract specialists serving niche administration device segments. Scale advantages concentrate procurement leverage among hospital buying consortiums. Geographic reach and sterile manufacturing validation capacity represent the dominant competitive vectors.
Among European-based manufacturers, Guerbet exemplifies the integrated conglomerate archetype with sustained supply continuity across Western markets. Jiangsu Hengrui Medicine Co. anchors the Asia-Pacific tier through backward integration into active pharmaceutical ingredient production. Mallinckrodt Pharmaceuticals occupies a position emphasizing North American distribution channel density.
| Leading Market Players |
|---|
| Liebel-Flarsheim Company LLC |
| Guerbet |
| Jiangsu Hengrui Medicine Co. |
| Mallinckrodt Pharmaceuticals |
| Ultraject |
| China Resources Pharmaceutical Co. |
| HB Ocean |
| Stellence Pharmscience Pvt. Ltd. |
| Novalek Pharmaceuticals Pvt. Ltd. |
| Others |
Supply Flow & Price Mechanics
Iodine spot price indices from Chilean caliche ore deposits cascade through multi-stage chemical synthesis into three-tier pricing structure across premium, standard, and economy levels for finished ioversol formulations. Procurement managers at United States integrated delivery networks leverage volume commitments to compress price floors, while EMA nitrosamine testing requirements inflate quality-tier premiums for European hospital formulary access.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing clusters are reshaping price floors for standard-grade ioversol injectables. Pricing stratifies across premium, standard, and economy tiers based on osmolality specification compliance and sterile validation batch release documentation. Cost compression in economy-tier multi-dose vials is intensifying because of backward integration among domestic API producers. Outpatient diagnostic centers exhibit highest price sensitivity, while German statutory health insurance funds absorb premium-tier pricing for complex interventional cardiology protocols.
Supply Chain Analysis
Iodine feedstock supply rests on Chilean caliche mining operations and Japanese natural gas brine extraction, with Chinese synthetic iodine production expanding as a third source. Critical inputs include triiodinated benzene ring precursors, organic substitution reagents, and sterile filtration membranes. Single-source vulnerability concentrates in Chilean iodine concentrate shipments through Panama Canal logistics chokepoints. Distribution runs through regional pharmaceutical wholesalers serving hospital buying consortiums and direct contracts with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ioversol market represents a late-cycle quality story as hospital formulary committees prioritize osmolality-optimized formulations for renal-impaired and pediatric populations over commodity-grade alternatives.
For Market Incumbents: Hedge against ultrasound microbubble substitution in cardiac imaging by deepening captive supply of high-purity iodine precursors and accelerating dual-energy CT protocol formulation development. Defensive consolidation through sterile manufacturing capacity additions in Texas and Florida integrated delivery network territories protects share against regional price competition. For New Entrants and Emerging Players: Launch via CDSCO-fast-tracked regulatory pathways into India's tier-2 and tier-3 private hospital chains where diagnostic imaging penetration remains underdeveloped. White-space concentration in oral formulation pediatric applications and research laboratory specialized concentration variants offers lowest competitive density against established parenteral giants. For Investors and Strategic Acquirers: Consolidation pressure builds where EMA pharmacovigilance compliance costs disproportionately burden mid-scale European manufacturers lacking API backward integration. Acquisition target archetype: regional sterile injectable specialists with validated dual-energy CT formulation pipelines and existing hospital GPO contracts. Watch FDA guidance expansion on contrast-induced nephropathy risk stratification as inflection indicator for premium formulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Production | Jiangsu Hengrui Medicine Co. anchors cost position through captive iodine precursor supply. |
| Dual-Energy CT Protocol Formulation Development | Kanto region academic medical centers in Japan pioneer specialized concentration requirements. |
| Hospital System Partnership Expansion | Texas and Florida health system consolidation drives multi-year sole-source contract capture. |
| EMA Nitrosamine Compliance Investment | Reformulation costs filter sub-scale competitors from European hospital procurement pools. |
| CDSCO Regulatory Fast-Track Utilization | Streamlined approval pathways open access to Maharashtra and Gujarat diagnostic infrastructure buildout. |
Methodological Framework
Bottom-up hospital procurement modeling reconciled against top-down iodinated contrast media production tracking forms the analytical core of this study. Primary interviews with radiology department heads, hospital formulary committee chairs, GPO contracts managers, and pharmaceutical regulatory affairs directors combined with secondary validation against FDA 510(k) filings, EMA centralized marketing authorization databases, NMPA registration records, and customs trade data for iodine derivative imports. Cross-referencing bottom-up procedure volume estimates with top-down manufacturer shipment reports enables triangulation.
Historical trendline analysis of CT angiography procedure growth rates, scanner installation patterns, and contrast media consumption per procedure informs projection modeling across delivery mode, application, and end-user segmentation dimensions. CAGRs derive from regression-adjusted trend extrapolation incorporating NMPA GB standards implementation timelines and Medicare site-neutral reimbursement policy phase-ins. Industry-specific forecast inputs include dual-energy CT protocol adoption curves and AI-enabled injection system penetration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under iodine supply disruption scenarios or accelerated ultrasound contrast agent substitution in cardiology. Forecasts reflect documented assumptions regarding hospital consolidation trajectories and regulatory divergence between FDA, EMA, and NMPA pharmacovigilance frameworks. A small set of named triggers—Chilean iodine export policy shifts, EMA nitrosamine threshold revisions, and CDSCO approval pathway modifications—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Solutions
Oral Screening Systems Market
Diagnostic Solutions
Global Upper Gastrointestinal (GI) Series Market
Diagnostic Solutions
Protein Detection and Quantification Market
Diagnostic Solutions
Hepatitis C Diagnosis and Treatment Market
Diagnostic Solutions
Europe Lung Cancer Screening Software Market
Diagnostic Solutions
Middle East and Africa Lung Cancer Screening Software Market
Diagnostic Solutions
Mobile Applications for Melanoma Detection Market
Diagnostic Solutions
North America Lung Cancer Screening Software Market
Diagnostic Solutions
Global Enzyme-Linked Immunosorbent Assay (ELISA) Market
Diagnostic Solutions
Protein Assays Market
Diagnostic Solutions
Global Lung Cancer Screening Software Market
Diagnostic Solutions
Total Bile Acid Assay Kit Market
Diagnostic Solutions
Multiple Reaction Monitoring Assay Market
Diagnostic Solutions
Near-Patient Molecular Solutions Market