
 Protein Detection and Quantification Market | 2026-2036
Protein Detection and Quantification Market Size, Share, and Industry Trends Forecast 2026-2036
Protein Detection and Quantification Market Intelligence
Fluorescent dyes are broadening assay sensitivity thresholds in protein quantification workflows. Thermo Fisher Scientific Inc. leverages its reagent-manufacturing scale to dominate high-throughput fluorescence kit supply. Bio-Rad Laboratories Inc. anchors its position through specialized chemiluminescence detection platforms for western blotting applications. Danaher Corporation competes across multiple technology tiers through its operating-company structure in life sciences instrumentation.
Protein detection and quantification encompasses analytical methods that measure protein concentration, identity, and post-translational modification using optical, electrochemical, or mass-based readouts with detection limits ranging from picogram to milligram scales. These techniques serve biopharmaceutical quality control, clinical biomarker verification, and food allergen surveillance by converting molecular binding events into quantifiable signals. Mass spectrometry instrumentation commands premium pricing and occupies the fastest-expanding margin pool as biologics manufacturers adopt multi-attribute monitoring for batch release. Immunoassay formats retain volume leadership in diagnostics labs where ELISA kits deliver standardized, regulator-friendly workflows for routine protein quantification. Academic institutions sustain steady demand for electrophoresis and western blotting systems despite slower growth relative to automated platforms.
FDA biosimilar guidelines and EMA's ICH Q5E comparability standards shape analytical method selection by mandating orthogonal protein characterization approaches for regulatory submission. ISO 17025 accreditation requirements for diagnostics labs in Europe and CLIA regulations in the United States enforce instrument calibration protocols that drive recurring reagent consumption. China's NMPA alignment with ICH quality guidelines is accelerating adoption of mass spectrometry-based protein quantification among domestic biopharma contract manufacturers. Stakeholders must evaluate which detection modality investments align with evolving multi-jurisdiction regulatory expectations for biologics characterization.
Market Dynamics
Biosimilar comparability requirements are forcing biopharma manufacturers to adopt orthogonal protein characterization methods, compressing method development timelines while expanding instrumentation footprints in quality control laboratories.
Growth Catalysts
- FDA Biosimilar Guidelines:Mandates for multi-attribute monitoring drive mass spectrometry adoption in batch release protocols across contract manufacturing organizations.
- Biologics Pipeline Expansion:Pharmaceutical companies are advancing monoclonal antibody programs that require precise titer determination and impurity profiling at clinical and commercial scales.
- Fluorescence Detection Sensitivity:Next-generation dye chemistries enable picogram-scale protein quantification in high-throughput screening workflows for drug discovery.
Market Restraints
- Mass Spectrometer Capital Intensity:Seven-figure instrument price points restrict adoption to well-capitalized biopharma manufacturers and large reference laboratories.
- Reagent Supply Concentration:Critical antibody and enzyme suppliers cluster in the United States and Germany, creating vulnerability to export control disruptions.
- ELISA Throughput Ceiling:Plate-based immunoassays face displacement pressure from automated alternatives in high-volume clinical diagnostic settings.
Strategic Opportunities
- China NMPA ICH Alignment:Domestic biopharma contract manufacturers are accelerating mass spectrometry adoption to meet international quality standards for export markets.
- Point-of-Care Protein Testing:Lateral flow and electrochemical biosensor formats are penetrating emergency medicine and resource-limited clinical settings.
- Mass Spectrometry-AI Convergence:Machine learning deconvolution of complex spectra reduces analytical method development time from months to weeks.
Industry Challenges
- Bioinformatics Talent Scarcity:Shortage of analysts trained in mass spectrometry data interpretation and multi-attribute method validation delays regulatory submissions.
- Legacy System Integration:Automated protein quantification platforms require substantial reconfiguration of existing laboratory information management infrastructure.
- ISO 17025 Accreditation Timelines:European diagnostics laboratories face extended audit cycles for instrument calibration protocol certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein Detection and Quantification Market |
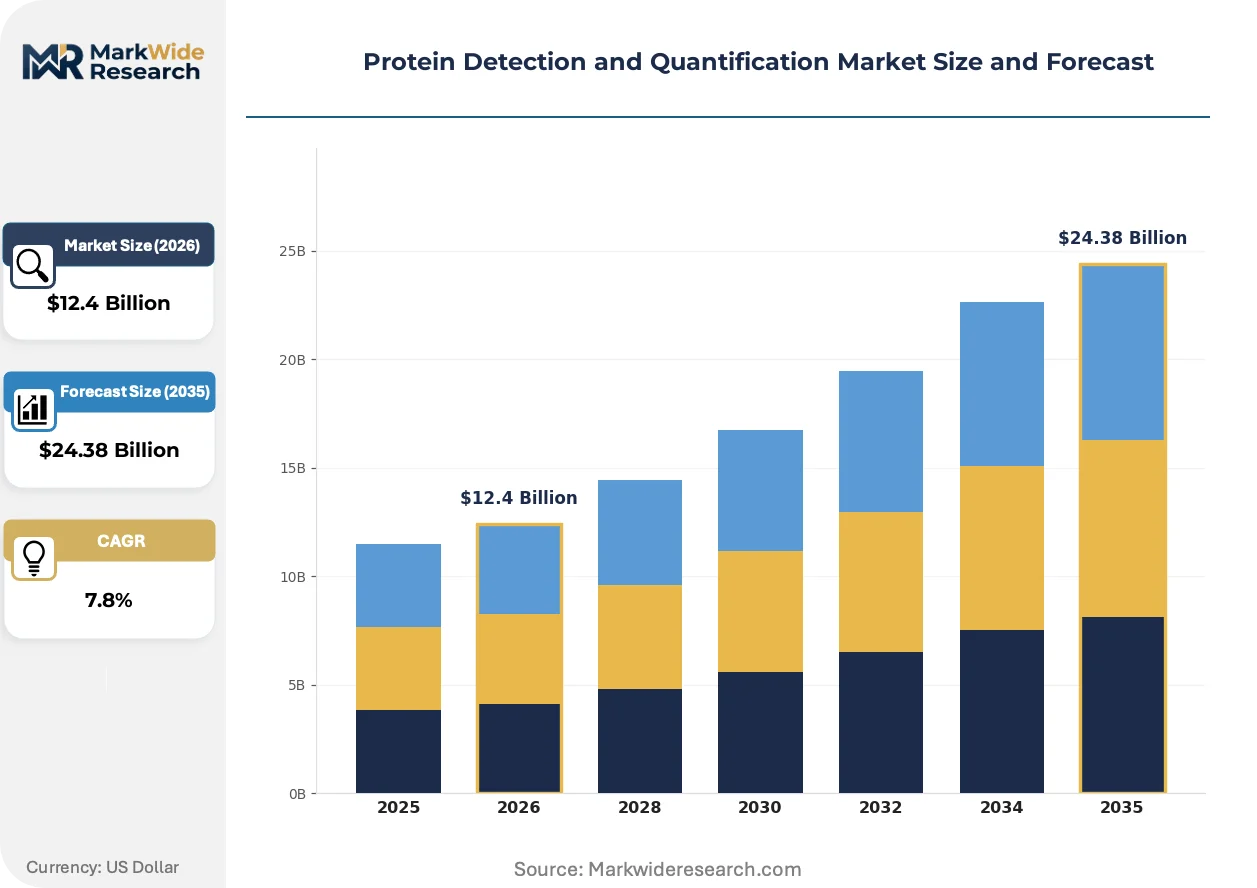
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $24.38 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA Kits, Western Blotting, Mass Spectrometry, Immunoassays Technology: Fluorescence, Chemiluminescence, Electrophoresis, Chromatography End User: Academic Institutions, Pharmaceutical Companies, Diagnostics Labs, Research Organizations Application: Clinical Diagnostics, Drug Development, Food Safety, Environmental Testing |
| Companies Covered | Thermo Fisher Scientific Inc., Agilent Technologies Inc., Bio-Rad Laboratories Inc., Danaher Corporation, Merck KGaA, PerkinElmer Inc., Promega Corporation, Sartorius AG, Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein Detection and Quantification Market Strategic Shifts & Innovations
Protein detection workflows are converging around automation and multi-modal readouts, compressing analytical timelines while expanding the accessible dynamic range for complex biologic matrices.
Label-free biosensors based on surface plasmon resonance and biolayer interferometry are overtaking traditional ELISA formats in kinetic characterization applications. Biopharma process development groups are adopting these platforms for real-time binding affinity measurements. The shift is compressing lead optimization cycles and reducing reagent consumption in early-stage biologics programs.
EMA's ICH Q5E comparability standards now require orthogonal confirmation of protein structural attributes for biosimilar approval. Manufacturers must demonstrate equivalence through multiple independent analytical principles. Mass spectrometry and circular dichroism combinations are becoming baseline expectations for European regulatory submissions.
Consolidated procurement of integrated protein analytics platforms is displacing point-solution purchasing in large biopharma quality control operations. Single-vendor ecosystems for sample preparation through data analysis are capturing multi-year service contracts. This concentration is most visible in United States and German manufacturing clusters where standardization reduces regulatory audit burden.
Protein Detection and Quantification Market Segmentation
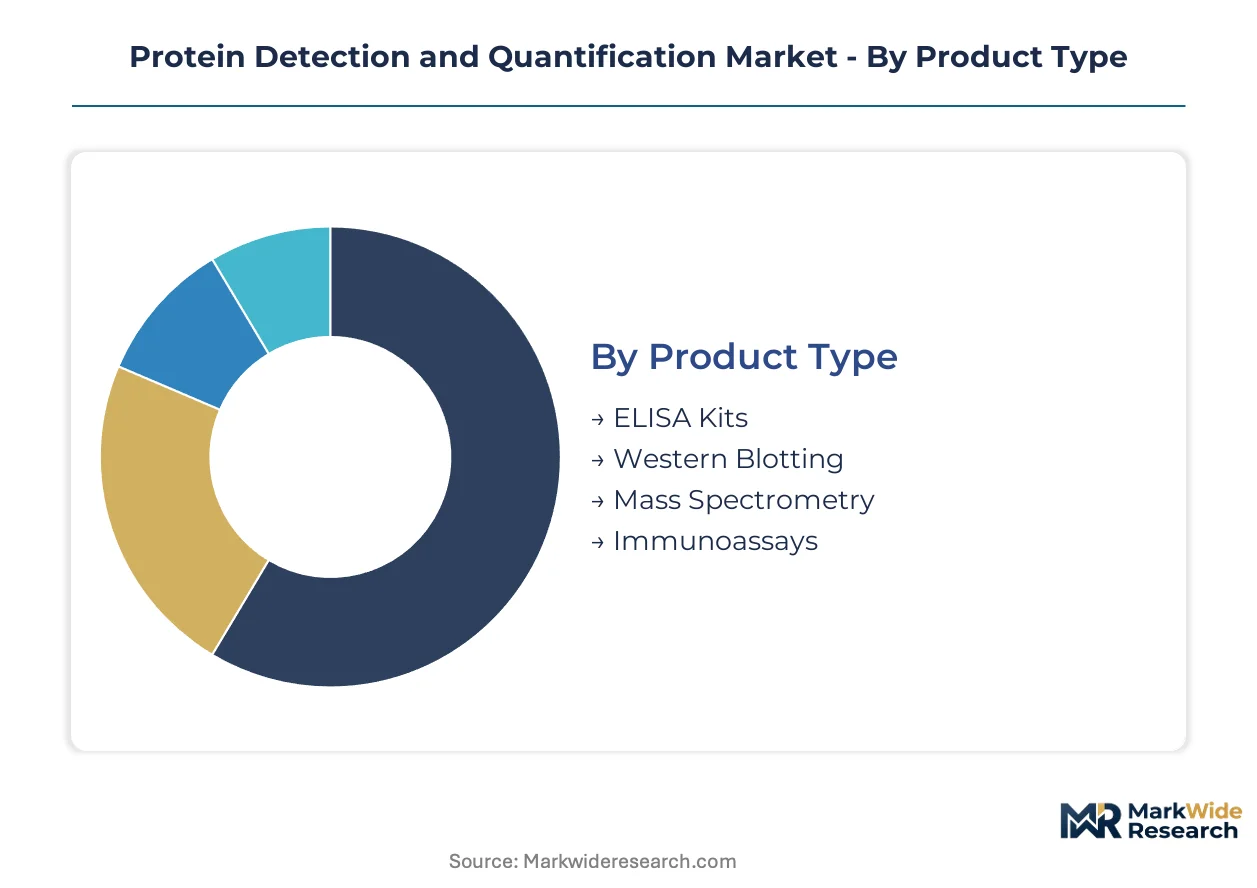
Protein detection and quantification technologies serve divergent workflow requirements across research, clinical, and industrial settings. Segmentation reveals where capital-intensive instrumentation dominates versus where consumable-driven platforms sustain recurring revenue models.
Product Type:
Standalone benchtop systems command premium positioning in GMP environments, while modular kits integrate into automated liquid handling infrastructure for high-throughput screening.
- ELISA Kits:Plate-based immunoassay consumables deliver standardized workflows for routine protein quantification in clinical and quality control settings. Diagnostics laboratories in the United States and Germany consume the highest kit volumes under CLIA and ISO 17025 calibration mandates.
- Western Blotting:Gel electrophoresis combined with antibody detection enables molecular weight determination and post-translational modification analysis. Academic institutions sustain steady demand despite slower automation adoption relative to other platforms.
- Mass Spectrometry:Multi-attribute monitoring platforms for biopharma batch release.
- Immunoassays:Automated analyzer-compatible reagent systems for clinical diagnostics.
ELISA Kits lead volumes today; Mass Spectrometry is gaining share fastest.
Technology:
Optical readout methods stratify by sensitivity threshold and reagent cost structure, with fluorescence and chemiluminescence occupying distinct positions in the value chain.
- Fluorescence:Dye-based detection achieves picogram-scale sensitivity through engineered fluorophore chemistries. Drug discovery operations in United States biopharma clusters favor this modality for high-throughput screening of protein-protein interactions.
- Chemiluminescence:Enzyme-amplified light emission delivers femtogram detection limits with extended dynamic range. Western blotting workflows in European academic and contract research settings prefer this technology for low-abundance protein visualization.
- Electrophoresis:Charge-based separation for protein sizing and purity assessment.
- Chromatography:Liquid-phase separation coupled with detection for complex mixture analysis.
Fluorescence leads volumes today; Chemiluminescence is expanding most quickly in regulated testing.
End User:
Customer types diverge sharply in procurement authority, with pharmaceutical quality control groups driving capital equipment decisions versus academic labs constrained by grant funding cycles.
- Academic Institutions:Research laboratories prioritize modular, grant-funded platforms with publication-grade data output. Electrophoresis and western blotting systems remain staples despite slower replacement cycles compared to industrial users.
- Pharmaceutical Companies:Biopharma manufacturers invest in mass spectrometry and automated immunoassay platforms for GMP-compliant release testing. FDA biosimilar guidelines force orthogonal method adoption, expanding instrumentation footprints in quality control departments.
- Diagnostics Labs:High-volume clinical testing facilities with regulatory accreditation requirements.
- Research Organizations:Contract research and government laboratories with diversified project portfolios.
Pharmaceutical Companies lead volumes today; Diagnostics Labs are climbing the fastest with accreditation-driven automation.
Application:
Use cases span regulated clinical environments to industrial quality assurance, with method validation requirements determining technology selection.
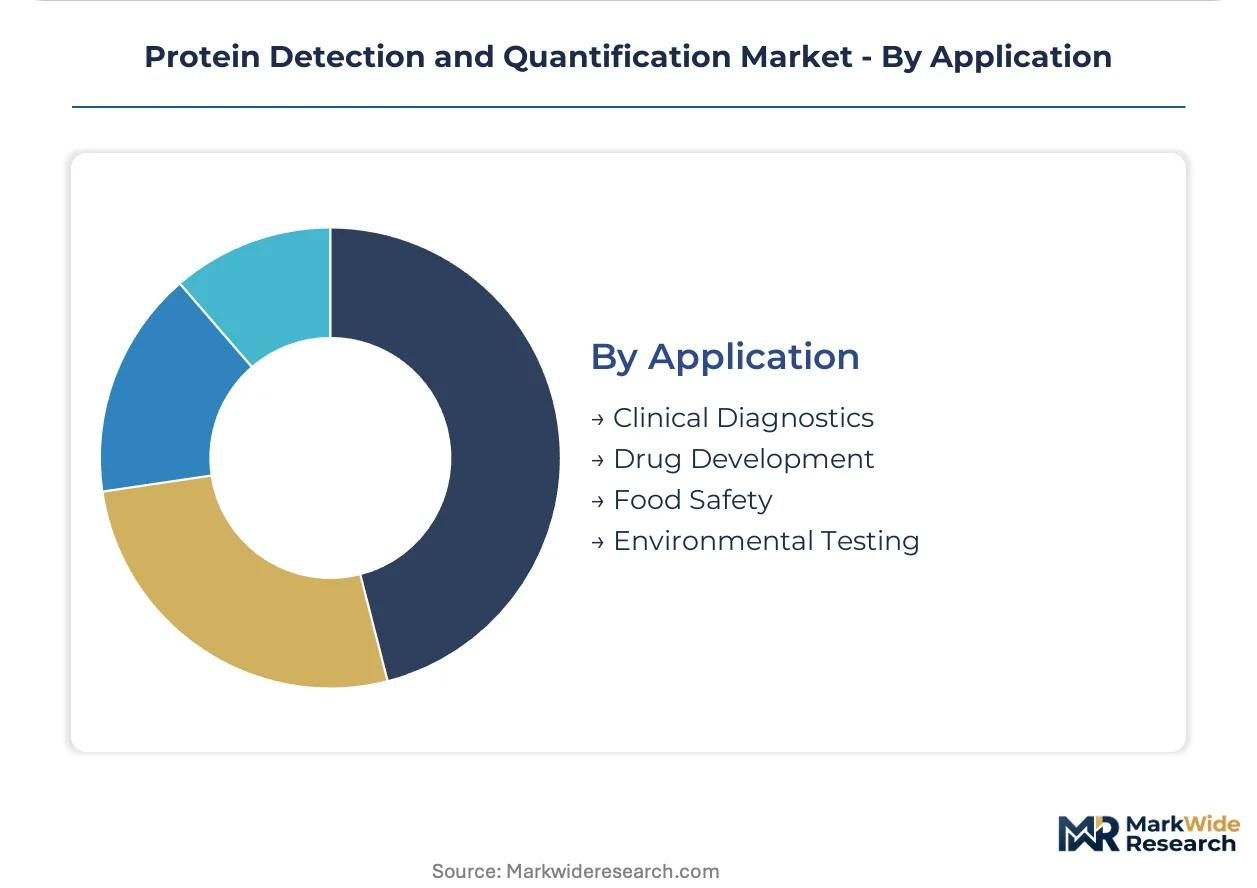
- Clinical Diagnostics:Patient sample protein biomarker quantification under stringent regulatory oversight. United States reference laboratories and hospital systems drive demand for FDA-cleared immunoassay platforms with established analytical performance claims.
- Drug Development:Biologics process development and characterization from discovery through commercial manufacturing. EMA ICH Q5E comparability standards mandate orthogonal protein characterization, accelerating mass spectrometry adoption in European biopharma.
- Food Safety:Allergen detection and protein adulteration testing for regulatory compliance.
- Environmental Testing:Protein-based toxicity assays and biomonitoring applications.
Clinical Diagnostics leads volumes today; Drug Development is expanding most quickly with biologics pipeline growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston-Cambridge anchors biopharma protein analytics demand through concentrated monoclonal antibody development. Contract manufacturing organizations in this cluster drive mass spectrometry instrumentation procurement for GMP batch release. FDA biosimilar guidelines shape purchasing specifications across United States quality control laboratories.
United States
Pharmaceutical quality control groups in Massachusetts and California expand mass spectrometry footprints for multi-attribute monitoring. FDA mandates for orthogonal protein characterization accelerate instrumentation replacement cycles. The Boston-Cambridge corridor concentrates demand from biologics contract manufacturers serving both domestic and export markets.
Germany
EMA ICH Q5E comparability standards force Heidelberg and Munich biopharma clusters toward dual-technology platforms. ISO 17025 accreditation requirements for diagnostics laboratories sustain recurring reagent consumption. The Rhine-Main manufacturing belt standardizes on single-vendor ecosystems to reduce regulatory audit burden.
China
NMPA alignment with ICH quality guidelines accelerates mass spectrometry adoption among Suzhou and Shanghai contract manufacturers. Domestic biopharma exporters upgrade protein quantification capabilities to meet European and United States regulatory submissions. The Yangtze River Delta biotech corridor drives fastest regional growth in automated platform procurement.
Japan
PMDA quality expectations sustain demand for high-sensitivity fluorescence detection in Osaka and Tokyo pharmaceutical development centers. Academic institutions in Kansai maintain steady electrophoresis and western blotting system replacement. Japanese biopharma manufacturers prioritize integrated platforms that compress analytical method development timelines.
Switzerland
Swissmedic biosimilar oversight drives Basel and Zurich biopharma toward premium mass spectrometry configurations. Precision medicine initiatives in Lake Geneva research clusters expand clinical biomarker verification workflows. Swiss contract manufacturers leverage regulatory reputation to capture European biologics characterization outsourcing.
Protein Detection and Quantification Market Key Industry Players
Strategic partnerships dominate the current landscape as vendors bundle instrumentation with multi-year service contracts. The market structures around three tiers: diversified life sciences conglomerates with reagent-manufacturing scale, specialized detection platform developers, and analytical instrument pure-plays. Consolidated procurement trends favor vendors offering integrated sample-to-data ecosystems. Technology licensing agreements and geographic expansion represent the primary competitive vectors as manufacturers seek regulatory footprint in China and European markets.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify scale-driven positioning through broad life sciences instrumentation portfolios. Bio-Rad Laboratories Inc. occupies a specialized position representing detection platform developers focused on chemiluminescence and fluorescence workflows. These three companies anchor the competitive structure by demonstrating how reagent scale, operating-company diversification, and application-specific specialization create distinct market positions.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Agilent Technologies Inc. |
| Bio-Rad Laboratories Inc. |
| Danaher Corporation |
| Merck KGaA |
| PerkinElmer Inc. |
| Promega Corporation |
| Sartorius AG |
| Shimadzu Corporation |
| Others |
Cost & Logistics Intelligence
ISO 17025 accreditation requirements gate qualified supply for European diagnostics laboratories while compressing margin structures for uncertified reagent providers. CLIA calibration mandates in the United States enforce similar quality-tier segmentation, allowing premium-tier vendors to capture multi-year service contracts while economy-grade suppliers face price erosion in unregulated research segments.
Pricing Analysis
Input-cost pass-through from engineered fluorophore chemistries and recombinant antibody production runs through to end-user kit pricing. Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated mass spectrometry platforms from research-grade electrophoresis systems. Cost compression in high-throughput fluorescence consumables is intensifying because Thermo Fisher leverages reagent-manufacturing scale. Academic institutions exhibit highest price sensitivity; pharmaceutical quality control groups show lowest sensitivity due to regulatory compliance imperatives.
Supply Chain Analysis
Reverse-logistics flows for mass spectrometer refurbishment and certified pre-owned instrumentation create secondary supply channels that extend equipment lifecycles. Critical antibody and enzyme production concentrates in the United States and Germany, with contract manufacturing expanding in China. The supply chain rests on recombinant protein expression systems, specialized optical components, and high-purity solvent chemistries. Single-source vulnerability around rare-earth-doped laser crystals for fluorescence detection platforms poses structural risk. Distribution runs through direct field service organizations for capital equipment and distributor networks for consumable reagents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate in China, where NMPA alignment with ICH quality guidelines allows domestic contract manufacturers to capture European and United States biopharma outsourcing at 30-40% cost differentials versus Western CMOs.
For Market Incumbents: Deepen captive supply control over recombinant antibody production to defend against emerging biosensor platform developers. Fortify multi-year service contract penetration in Boston-Cambridge and Rhine-Main manufacturing clusters where consolidated procurement trends favor single-vendor ecosystems. Accelerate ISO 17025 accreditation investment for European diagnostics channel lock-in.
For New Entrants and Emerging Players: Direct-to-clinic digital distribution routes bypass entrenched distributor relationships in point-of-care protein testing segments. Target lateral flow and electrochemical biosensor formats for emergency medicine applications where regulatory pathways remain less congested than central laboratory diagnostics. Pursue white-label manufacturing partnerships with Yangtze River Delta contract manufacturers to establish NMPA-registered production capacity.
For Investors and Strategic Acquirers: Roll-up economics work for specialized detection platform developers because EMA ICH Q5E comparability standards force orthogonal method adoption that fragments purchasing decisions across multiple vendors. Five-to-ten year viability hinges on mass spectrometry-AI convergence capabilities that compress analytical method development timelines. Monitor FDA biosimilar guideline expansion timelines as inflection indicator for multi-attribute monitoring platform demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | ISO 17025 and CLIA compliance opens multi-year reagent contracts in accredited diagnostics laboratories. |
| Backward Integration into Reagent Manufacturing | Captive antibody production secures margin control against supply concentration in United States and Germany. |
| Platform-AI Convergence Development | Machine learning deconvolution capabilities differentiate mass spectrometry offerings in biopharma quality control. |
| Geographic Expansion into China | NMPA ICH alignment creates regulatory pathway for export-oriented biopharma contract manufacturing capture. |
| Point-of-Care Format Miniaturization | Lateral flow and electrochemical biosensors penetrate emergency medicine and resource-limited clinical settings. |
Research Approach
Multiple input streams — primary interviews with biopharma quality control directors, regulatory affairs specialists, and diagnostics laboratory managers; secondary validation through FDA 510(k) filings, EMA scientific advice letters, and NMPA registration databases; plus trade data from customs records and instrument import registries — were reconciled through bottom-up and top-down triangulation.
Cross-referencing historical instrument placement data against expert panel input on biologics pipeline expansion shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, detection technology, end-user category, and application area, with additional stratification by regional regulatory cluster. CAGRs were derived from instrument replacement cycle analysis and consumable attach-rate modeling, incorporating biopharma manufacturing capacity expansion and biosimilar approval velocity as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for label-free biosensor platforms would alter the outlook if surface plasmon resonance overtakes ELISA formats faster than projected. Forecasts reflect underlying assumptions about regulatory timeline continuity and reagent supply chain stability. Practitioners should monitor FDA biosimilar guideline enforcement intensity and NMPA inspection calendar acceleration for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Solutions
Mobile Applications for Melanoma Detection Market
Diagnostic Solutions
Global Ioversol Market
Diagnostic Solutions
Total Bile Acid Assay Kit Market
Diagnostic Solutions
Hepatitis C Diagnosis and Treatment Market
Diagnostic Solutions
Near-Patient Molecular Solutions Market
Diagnostic Solutions
Oral Screening Systems Market
Diagnostic Solutions
Middle East and Africa Lung Cancer Screening Software Market
Diagnostic Solutions
Global Lung Cancer Screening Software Market
Diagnostic Solutions
Protein Assays Market
Diagnostic Solutions
Global Enzyme-Linked Immunosorbent Assay (ELISA) Market
Diagnostic Solutions
Multiple Reaction Monitoring Assay Market
Diagnostic Solutions
Global Upper Gastrointestinal (GI) Series Market
Diagnostic Solutions
North America Lung Cancer Screening Software Market
Diagnostic Solutions
Europe Lung Cancer Screening Software Market