
 Global Enzyme-Linked Immunosorbent Assay (ELISA) Market | 2026-2036
Global Enzyme-Linked Immunosorbent Assay (ELISA) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enzyme-Linked Immunosorbent Assay (ELISA) Market Foresight
The gap between manual plate-based workflows and fully integrated automated ELISA systems is narrowing as laboratories seek higher throughput with reduced technician intervention. Thermo Fisher Scientific leverages its instrument-reagent bundling strategy to sustain installed-base loyalty across high-volume clinical labs. Bio-Rad Laboratories anchors its position through specialized autoimmune and infectious disease assay menus that differentiate its catalog from generalist competitors. Danaher competes by extending its life sciences automation architecture into diagnostic-grade ELISA platforms with embedded quality control software.
Enzyme-Linked Immunosorbent Assay refers to a plate-based immunochemical technique that uses enzyme-conjugated antibodies and chromogenic or chemiluminescent substrates to detect and quantify antigens, antibodies, or proteins in liquid samples, typically requiring 96-well or 384-well microplate formats with optical density readouts at specified wavelengths. The method serves as a foundational tool for disease serology, biomarker validation, and contaminant screening in regulated environments. Sandwich ELISA configurations command premium positioning due to their superior specificity and sensitivity in biomarker quantification, while chemiluminescent detection technology leads growth trajectories as laboratories replace colorimetric endpoints with broader dynamic range and lower detection limits. Pharmaceutical research applications remain the most mature segment with established protocols, whereas food safety testing represents an emerging margin pool driven by expanding mycotoxin and allergen surveillance mandates.
FDA 510(k) clearance pathways and EMA in vitro diagnostic regulation shape product development timelines and performance validation requirements for commercial assay manufacturers. ISO 13485 quality management standards and CLSI analytical performance guidelines further constrain design controls and lot-release testing protocols for instruments and reagents sold into clinical markets. Stakeholders must monitor evolving harmonization between FDA and IVDR conformity assessment routes to anticipate dual-labeling cost structures and competitive access barriers.
Market Dynamics
Automated microplate processing systems are compressing technician-to-sample ratios across centralized diagnostic networks, forcing manual workflow providers to accelerate robotics integration or retreat to niche research segments.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for predicate-based ELISA submissions are shortening commercialization cycles for infectious disease panels.
- Chemiluminescent substrate chemistry:Enhanced signal-to-noise ratios in high-sensitivity biomarker detection are expanding oncology monitoring applications.
- China reference laboratory consolidation:Provincial health commissions are mandating centralized testing hubs that standardize on automated ELISA platforms.
Market Restraints
- Monoclonal antibody input concentration:Three suppliers control specialty enzyme-conjugate supply, creating lot-to-lot variability risks for assay manufacturers.
- IVDR conformity assessment bottlenecks:European notified body capacity constraints are extending EMA certification timelines by 8-14 months for novel diagnostic claims.
- Lateral flow immunoassay substitution:Point-of-care rapid tests are capturing low-complexity serology volumes previously served by laboratory ELISA.
Strategic Opportunities
- India tier-2 city laboratory networks:District hospital upgrading under the PLI scheme is creating first-time automated platform demand outside metropolitan clusters.
- Cell therapy potency assay integration:CAR-T manufacturing workflows require lot-release cytokine quantification that sandwich ELISA configurations uniquely satisfy.
- ISO 13485:2016 transition services:Smaller assay developers face quality management system overhauls, opening consulting and outsourced manufacturing partnerships.
Industry Challenges
- Multiplex assay bioinformatics integration:Laboratory information system vendors lack standardized data structures for combined ELISA and molecular diagnostic reporting.
- Cross-reactivity validation burden:Expanding autoimmune panel menus require extensive interference testing against heterogeneous patient antibody populations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enzyme-Linked Immunosorbent Assay (ELISA) Market |
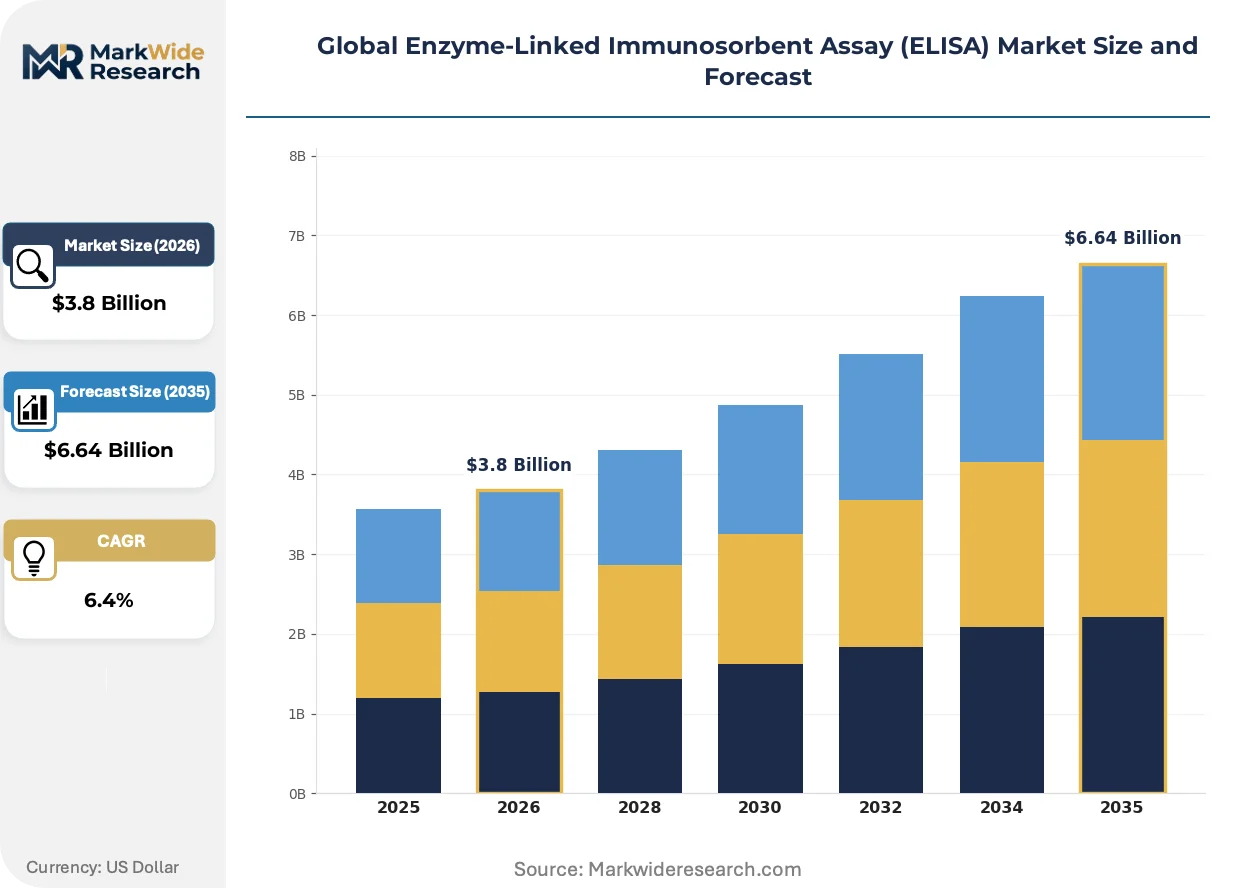
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct ELISA, Indirect ELISA, Sandwich ELISA, Competitive ELISA Application: Infectious Disease Diagnosis, Food Safety Testing, Veterinary Testing, Pharmaceutical Research, Environmental Monitoring End User: Diagnostic Laboratories, Biotechnology Firms, Academic Research Centers, Contract Research Organizations, Quality Control Units Technology: Colorimetric Detection, Chemiluminescent Detection, Fluorescent Detection, Electrochemical Detection |
| Companies Covered | PerkinElmer, Abbott Laboratories, Thermo Fisher Scientific, Revvity, DiaSorin, Bio-Rad Laboratories, Tecan Group, Bio-Techne, Danaher, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enzyme-Linked Immunosorbent Assay (ELISA) Market Shifts & Advancements
Digital microfluidics and artificial intelligence-enabled image analysis are converging to redefine sample-to-answer workflows, compressing both physical footprint and interpretive latency in high-throughput environments.
Electrochemiluminescence detection technology is rendering obsolete traditional colorimetric endpoint readers in reference laboratories. Academic medical centers in Germany and the United States are retrofitting existing plate infrastructure with Meso Scale Discovery-compatible modules. The transition is compressing competitive positioning around dynamic range specifications rather than throughput alone.
EMA In Vitro Diagnostic Regulation Article 10.4 post-market surveillance requirements are mandating annual performance reporting for Class C and D devices. Assay manufacturers must maintain traceable calibrator stability data across temperature excursion scenarios. Autoimmune and allergy panel providers face the steepest documentation burden, driving consolidation among smaller kit developers.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships at integrated delivery networks. Hospital systems in the United States are unbundling reagent supply from instrument service contracts, forcing vendors to compete on per-test economics rather than capital lease structures. This behavioral shift is most pronounced in California and Texas, where multi-hospital alliances command substantial volume leverage.
Global Enzyme-Linked Immunosorbent Assay (ELISA) Market Segmentation
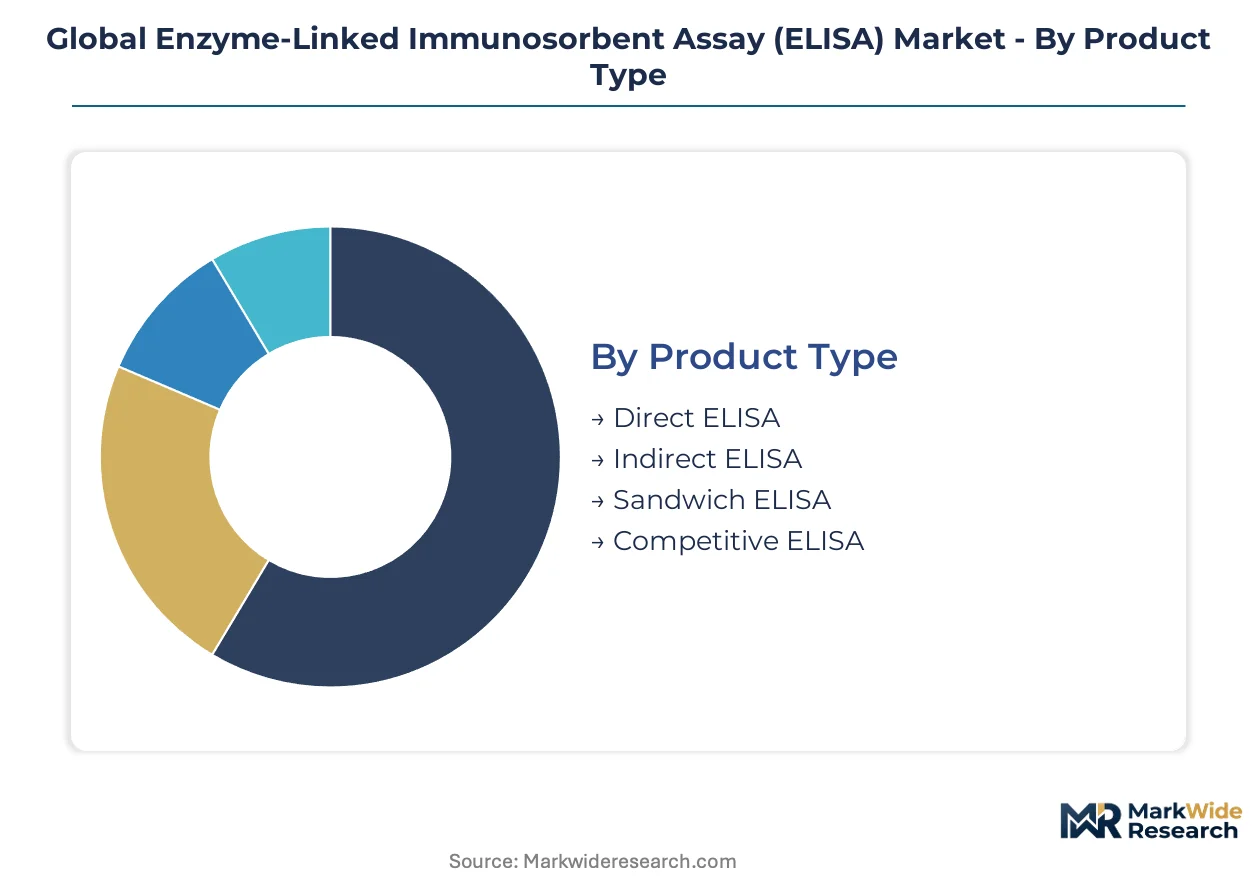
ELISA market segmentation reveals how assay configurations, detection modalities, and end-user workflows fragment across regulated diagnostic environments versus exploratory research settings. Configuration choices directly determine sensitivity thresholds, throughput economics, and regulatory pathway complexity.
Product Type:
Use-case spectrum spans rapid screening to high-precision quantification, with each configuration occupying distinct positions along the specificity-throughput tradeoff curve.
- Sandwich ELISA:Dual-antibody capture architecture delivers picogram-level detection limits through cooperative binding geometry. Germany's reference laboratory networks specify sandwich configurations for tumor marker monitoring, driven by EMA Class C device performance requirements for oncology companion diagnostics.
- Competitive ELISA:Single-antibody format quantifies small molecules and haptens through displacement kinetics. Veterinary steroid residue testing in Brazil's beef export certification program demands competitive formats for regulatory compliance with ANVISA agricultural chemical limits.
- Indirect ELISA:Secondary antibody amplification suits serological screening where antigen coating costs must be minimized.
- Direct ELISA:Single-step conjugate binding offers fastest turnaround for high-titer antibody detection in blood bank screening protocols.
Established volume favors Sandwich ELISA; emerging adoption favors Competitive ELISA.
Application:
Cost tier separation distinguishes commodity screening from premium regulated testing, with reimbursement and certification requirements driving margin stratification.
- Pharmaceutical Research:Bioanalytical method validation for pharmacokinetic studies demands rigorous standard curve linearity and inter-batch precision. China's NMPA now requires ELISA-based immunogenicity assessments for biosimilar submissions, expanding contract laboratory demand in Shanghai and Suzhou clusters.
- Infectious Disease Diagnosis:Serological confirmation of HIV, hepatitis, and emerging pathogens operates under FDA 510(k) and WHO prequalification schemes. India's CDSCO has centralized ELISA-based NAT confirmation for blood safety at 12 regional transfusion centers under 2023 technical standards.
- Food Safety Testing:Mycotoxin and allergen surveillance mandates expand under EU regulation 2023/915 and China's GB standards revision.
- Veterinary Testing:Export certification for livestock products drives brucellosis and tuberculosis serology in agricultural economies.
- Environmental Monitoring:Endocrine-disrupting compound detection in wastewater applies competitive ELISA for regulatory compliance screening.
Pharmaceutical Research commands premium pricing; Food Safety Testing shows steepest expansion trajectory.
End User:
Customer type fragmentation reflects capital intensity, regulatory burden, and sample volume heterogeneity across the value chain.
- Diagnostic Laboratories:High-throughput clinical reference labs in the United States, Germany, and China consolidate on automated walk-away systems. India's PLI scheme is upgrading 300 district hospital laboratories with first-time ELISA automation for infectious disease panels.
- Contract Research Organizations:GLP-compliant bioanalytical services for pharmaceutical sponsors require validated ELISA platforms with full audit trails. South Korean CROs near Seoul and Osong bioclusters specialize in biosimilar immunogenicity testing for export markets.
- Biotechnology Firms:Cell therapy developers use cytokine quantification for CAR-T lot release under FDA guidance.
- Academic Research Centers:Grant-funded exploratory work tolerates manual workflows and open-source reagent sourcing.
- Quality Control Units:In-process testing for biologics manufacturing demands rapid endotoxin and host cell protein detection.
Diagnostic Laboratories dominate installed base; Contract Research Organizations gain share fastest.
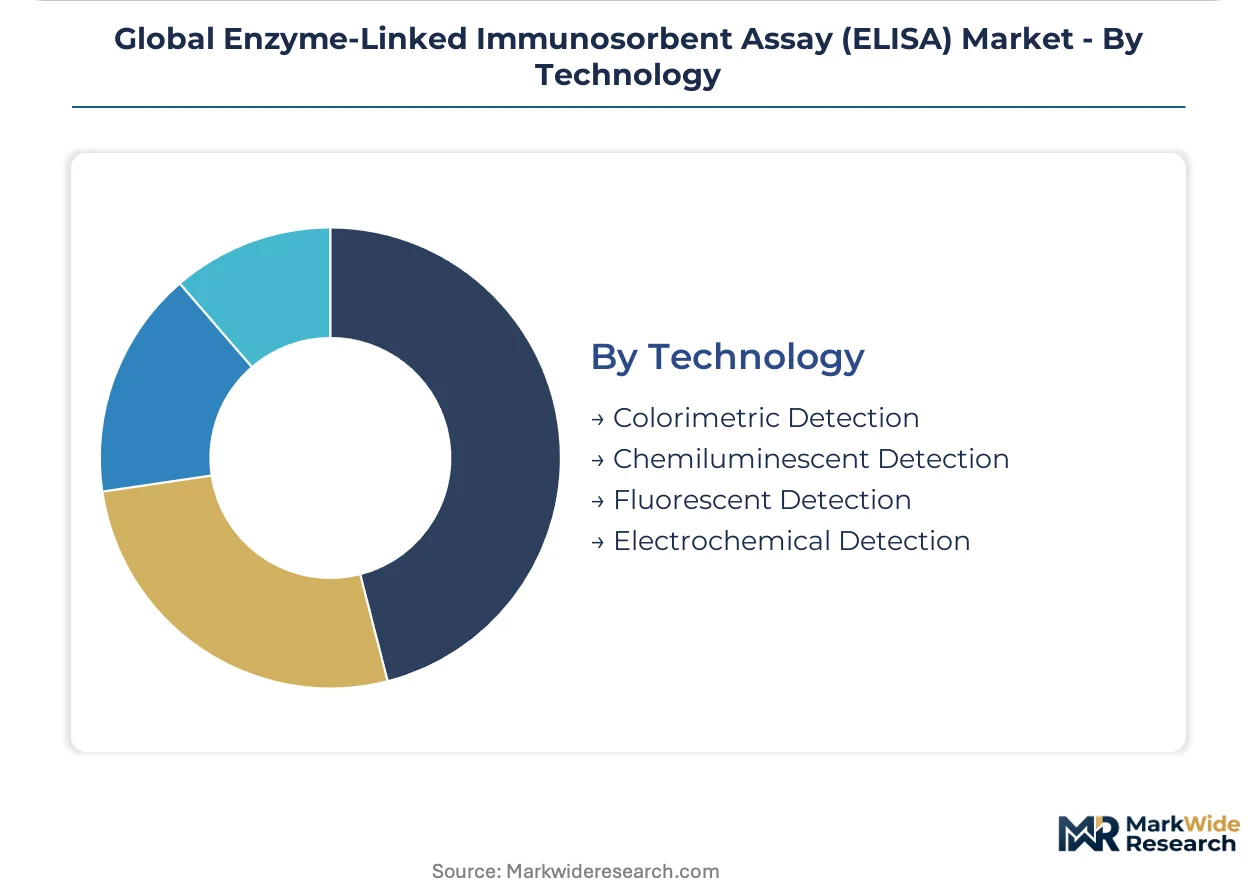
Technology:
Detection modality maturity curves separate legacy colorimetric infrastructure from next-generation signal amplification chemistries.
- Chemiluminescent Detection:Enzymatic light emission through luminol or acridinium ester substrates extends dynamic range across four orders of magnitude. Academic medical centers in Germany and the United States are retrofitting plate readers with Meso Scale Discovery-compatible modules for oncology biomarker panels.
- Colorimetric Detection:Horseradish peroxidase with TMB substrate remains the workhorse for resource-limited settings and teaching laboratories. India's tier-2 city networks under the PLI scheme standardize on colorimetric platforms for cost-effective hepatitis B and C screening.
- Fluorescent Detection:Time-resolved fluorescence europium chelates reduce background in autoimmune multiplex panels.
- Electrochemical Detection:Amperometric readouts enable miniaturization for point-of-care device integration.
Colorimetric Detection retains volume leadership; Chemiluminescent Detection drives replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-engineered ELISA instrumentation and reagent systems to diagnostic networks across the United States, China, and India, establishing a dominant trade corridor in high-sensitivity assay platforms.
United States
Academic medical centers in Boston and Houston retrofit existing plate infrastructure with electrochemiluminescence modules. FDA 510(k) clearance timelines compress commercialization cycles for infectious disease panels. California and Texas hospital systems unbundle reagent supply from instrument service contracts, forcing per-test economic competition.
Germany
Reference laboratory networks in Bavaria and Baden-Württemberg specify sandwich ELISA configurations for tumor marker monitoring. EMA In Vitro Diagnostic Regulation Article 10.4 mandates annual performance reporting for Class C and D devices. The Rhine-Ruhr cluster concentrates autoimmune and allergy panel development under intensified documentation burdens.
China
Provincial health commissions mandate centralized testing hubs that standardize on automated ELISA platforms. NMPA requires ELISA-based immunogenicity assessments for biosimilar submissions, expanding contract laboratory demand. Shanghai and Suzhou bioclusters specialize in biosimilar testing for export markets.
India
District hospital upgrading under the PLI scheme creates first-time automated platform demand outside metropolitan clusters. CDSCO has centralized ELISA-based NAT confirmation for blood safety at 12 regional transfusion centers under 2023 technical standards. Tier-2 city networks standardize on colorimetric platforms for cost-effective hepatitis B and C screening.
South Korea
Seoul and Osong bioclusters specialize in biosimilar immunogenicity testing for export markets. MFDS alignment with international standards accelerates predicate-based submissions for novel diagnostic claims. The capital region concentrates GLP-compliant bioanalytical services for pharmaceutical sponsors requiring full audit trails.
Global Enzyme-Linked Immunosorbent Assay (ELISA) Market Competitive Landscape
On the supply side, the industry is consolidating around instrument-reagent bundling strategies that lock in installed-base loyalty across high-volume clinical laboratories. Three strategic archetypes dominate: diversified life sciences conglomerates with diagnostic-grade automation architectures, specialized assay developers with differentiated autoimmune and infectious disease menus, and precision instrument manufacturers with embedded quality control software. Competitive moves concentrate on M&A for technology licensing and strategic partnerships for geographic expansion into tier-2 city networks.
Among diversified conglomerates, Thermo Fisher Scientific and Danaher exemplify the instrument-reagent bundling archetype through their diagnostic-grade platform strategies. Bio-Rad Laboratories occupies a specialist position within the autoimmune and infectious disease assay segment. These three entities represent the dominant competitive vectors: scale-driven automation integration, specialized menu differentiation, and life sciences architecture extension into regulated diagnostics.
| Leading Market Players |
|---|
| PerkinElmer |
| Abbott Laboratories |
| Thermo Fisher Scientific |
| Revvity |
| DiaSorin |
| Bio-Rad Laboratories |
| Tecan Group |
| Bio-Techne |
| Danaher |
| Others |
Supply & Pricing Matrix
Monoclonal antibody conjugate supply concentration among three specialty enzyme suppliers determines both tiered pricing spreads across assay configurations and the geographic shape of reagent manufacturing networks. This single-source dependency compresses margins for mid-tier kit developers while amplifying pricing power for integrated instrument-reagent bundlers in high-volume clinical segments.
Pricing Analysis
Prior-generation colorimetric platforms anchor economy-tier per-test economics, current-generation chemiluminescent systems command standard-tier positioning, and next-generation electrochemiluminescence modules define premium-tier pricing. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—FDA 510(k) cleared assays versus research-use-only reagents versus CE-marked IVDR Class C devices. Pricing pressure stems from hospital system unbundling of reagent supply from instrument service contracts in California and Texas. Contract Research Organizations exhibit highest price sensitivity due to sponsor-driven cost pass-through requirements, while cell therapy manufacturers show lowest sensitivity given lot-release compliance imperatives.
Supply Chain Analysis
Contract manufacturing concentration rests with Thermo Fisher Scientific's reagent foundry network, Danaher's GMP kit assembly facilities, and Bio-Rad's specialized conjugate production sites. Geographic supply concentration centers on the United States for precision instrumentation, Germany for reference-grade optical modules, and China for cost-optimized plastic consumables. Raw material dependencies include horseradish peroxidase enzyme stocks, high-binding polystyrene microplates, and luminol-based chemiluminescent substrates. Single-source vulnerability in monoclonal antibody conjugate supply creates lot-to-lot variability exposure. Distribution runs through group purchasing organizations at integrated delivery networks and direct manufacturer relationships at academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Enzyme-Linked Immunosorbent Assay Market is entering a cyclical recovery phase driven by IVDR conformity assessment backlog clearance and replacement demand for electrochemiluminescence-enabled platforms. Laboratory automation capital expenditure cycles are turning after extended deferral periods.
For Market Incumbents: Build switching-cost moats through embedded quality control software that locks diagnostic laboratories into automated walk-away workflows. Deepen backward integration into enzyme-conjugate manufacturing to offset supply concentration risk among specialty antibody suppliers. Expand instrument-reagent bundling into India's tier-2 city networks under PLI scheme incentives before competitor platform standardization takes hold. For New Entrants and Emerging Players: Establish a beachhead in cell therapy potency assay services where CAR-T manufacturers require cytokine quantification expertise that incumbent generalists lack. Target ISO 13485:2016 transition consulting for smaller assay developers facing quality management system overhauls under EMA Article 10.4 documentation burdens. Pursue white-label manufacturing partnerships with district hospital networks in India seeking first-time ELISA automation. For Investors and Strategic Acquirers: IVDR Class C and D device annual performance reporting mandates reshape the acquisition landscape toward quality-system-mature targets with traceable calibrator stability data infrastructure. Long-term viability favors specialized autoimmune and infectious disease assay developers with differentiated menus over generalist commodity kit manufacturers. Monitor notified body capacity expansion rates as the signal to watch for certification timeline normalization and valuation multiple recovery.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Conformity Assessment Acceleration | EMA notified body capacity expansion compresses certification timelines for novel diagnostic claims. |
| Electrochemiluminescence Platform Retrofit | German and US academic medical centers upgrade existing plate infrastructure with Meso Scale Discovery-compatible modules. |
| India Tier-2 Laboratory Network Expansion | PLI scheme district hospital upgrading creates first-time automated ELISA platform demand outside metropolitan clusters. |
| Cell Therapy Potency Assay Integration | CAR-T manufacturing workflows require lot-release cytokine quantification that sandwich ELISA configurations uniquely satisfy. |
| Reagent Supply Unbundling Response | California and Texas hospital systems force per-test economic competition by separating reagent procurement from instrument service contracts. |
Research Methodology
A spread of perspectives from diagnostic laboratory directors, regulatory affairs specialists at assay manufacturers, biomedical engineers at academic medical centers, and procurement managers at integrated delivery networks converged on the working assumptions underlying this analysis. Primary fieldwork was validated against FDA 510(k) clearance databases, EMA IVDR technical documentation filings, CDSCO blood safety technical standards, and NMPA biosimilar immunogenicity guidance documents. Bottom-up segment sizing and top-down macro constraint triangulation were applied throughout.
Demand-supply balance dynamics across the analysis window were modeled through instrument installed base depreciation curves, reagent consumption per test metrics, and replacement cycle timing for colorimetric-to-chemiluminescence platform transitions. Segmentation dimensions include assay configuration type, detection technology modality, end-user workflow intensity, and regional regulatory cluster. CAGRs were derived from weighted average growth contributions across these segments. Forecast inputs incorporated provincial health commission centralization mandates in China and PLI scheme implementation velocity in India.
Stress conditions across monoclonal antibody supply disruption scenarios, IVDR notified body capacity constraints, and lateral flow immunoassay substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding laboratory automation capital expenditure recovery trajectories and reference laboratory network consolidation timing. Quarterly review of EMA Article 10.4 post-market surveillance compliance rates and group purchasing organization contract renegotiation activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Solutions
Global Ioversol Market
Diagnostic Solutions
Near-Patient Molecular Solutions Market
Diagnostic Solutions
Europe Lung Cancer Screening Software Market
Diagnostic Solutions
Multiple Reaction Monitoring Assay Market
Diagnostic Solutions
Oral Screening Systems Market
Diagnostic Solutions
North America Lung Cancer Screening Software Market
Diagnostic Solutions
Global Upper Gastrointestinal (GI) Series Market
Diagnostic Solutions
Hepatitis C Diagnosis and Treatment Market
Diagnostic Solutions
Protein Detection and Quantification Market
Diagnostic Solutions
Protein Assays Market
Diagnostic Solutions
Global Lung Cancer Screening Software Market
Diagnostic Solutions
Middle East and Africa Lung Cancer Screening Software Market
Diagnostic Solutions
Mobile Applications for Melanoma Detection Market
Diagnostic Solutions
Total Bile Acid Assay Kit Market