
 North America Lung Cancer Screening Software Market | 2026-2036
North America Lung Cancer Screening Software Market Size, Share, and Industry Trends Forecast 2026-2036
North America Lung Cancer Screening Software Market Analytics
Buyer concentration among US hospital systems is hardening as integrated delivery networks consolidate radiology purchasing decisions across multiple sites. GE Healthcare leverages deep imaging hardware integration to sustain captive demand for its screening analytics stack. Siemens Healthineers anchors enterprise contracts through cross-platform compatibility with existing CT fleets. Nuance Communications competes by embedding voice-AI documentation directly into lung nodule follow-up workflows.
North America lung cancer screening software comprises algorithmic platforms that process low-dose computed tomography scans to detect pulmonary nodules, quantify malignancy risk via volumetric analysis, and automate patient tracking across multi-year surveillance protocols. These systems integrate with PACS infrastructure to reduce radiologist interpretation time and standardize Lung-RADS reporting for reimbursement compliance. Cloud-based Platforms lead deployment preferences among mid-sized diagnostic centers seeking scalable infrastructure without capital intensity. AI-driven Tools represent the fastest-expanding technology segment as FDA-cleared algorithms proliferate for nodule detection and malignancy risk stratification. Integrated Solutions command premium positioning by unifying imaging, patient management, and billing functions within single-vendor environments.
The FDA regulates algorithmic screening tools as Class II medical devices under 510(k) pathways, creating substantial validation requirements that filter software entrants. The US Preventive Services Task Force screening guidelines and CMS reimbursement determinations directly shape hospital adoption velocity and software procurement budgets. HIPAA compliance frameworks impose data architecture constraints on cloud deployments, particularly for cross-state patient cohort management. Stakeholders must monitor evolving FDA guidance on adaptive AI algorithms and state-level Medicaid expansion decisions that alter addressable screening populations.
Market Dynamics
Consolidation of radiology purchasing authority within US integrated delivery networks is compressing vendor negotiation cycles and favoring enterprise-scale software contracts over site-specific deployments.
Growth Catalysts
- CMS Reimbursement Expansion:Medicare coverage for low-dose CT screening under the US Preventive Services Task Force expanded eligibility criteria directly enlarges the addressable patient pool for software vendors.
- AI Algorithm Proliferation:FDA 510(k) clearances for machine learning-based nodule detection are accelerating hospital procurement of automated risk stratification tools.
- Midwest IDN Concentration:Integrated delivery networks across Illinois, Ohio, and Michigan are standardizing lung cancer screening protocols across multi-hospital systems, creating centralized software procurement demand.
Market Restraints
- Validation Cost Burden:FDA Class II medical device pathways impose substantial clinical validation requirements that filter software entrants lacking capital reserves for multi-site trials.
- Cloud Infrastructure Constraints:HIPAA compliance frameworks impose data architecture limitations on cross-state patient cohort management, particularly for community health centers lacking dedicated compliance infrastructure.
- Radiologist Workflow Inertia:Established PACS integration patterns and interpretive habits create switching friction even for superior algorithmic detection capabilities.
Strategic Opportunities
- Southeast Medicaid Expansion:State-level Medicaid expansion decisions in Georgia, North Carolina, and Alabama are altering addressable screening populations for safety-net hospital systems.
- Voice-AI Documentation Convergence:Integration of natural language processing with nodule follow-up workflows creates white space for vendors embedding automated reporting into existing radiology speech recognition infrastructure.
- Community Diagnostic Center Channel:Mid-sized independent imaging centers seeking scalable cloud-based platforms without capital intensity represent an underpenetrated distribution channel beyond academic medical centers.
Industry Challenges
- Interoperability Complexity:Integration with heterogeneous PACS environments and legacy patient management systems requires substantial professional services investment per deployment.
- Adaptive Algorithm Governance:Evolving FDA guidance on continuously learning AI systems creates compliance uncertainty for vendors deploying model updates without full 510(k) resubmission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Lung Cancer Screening Software Market |
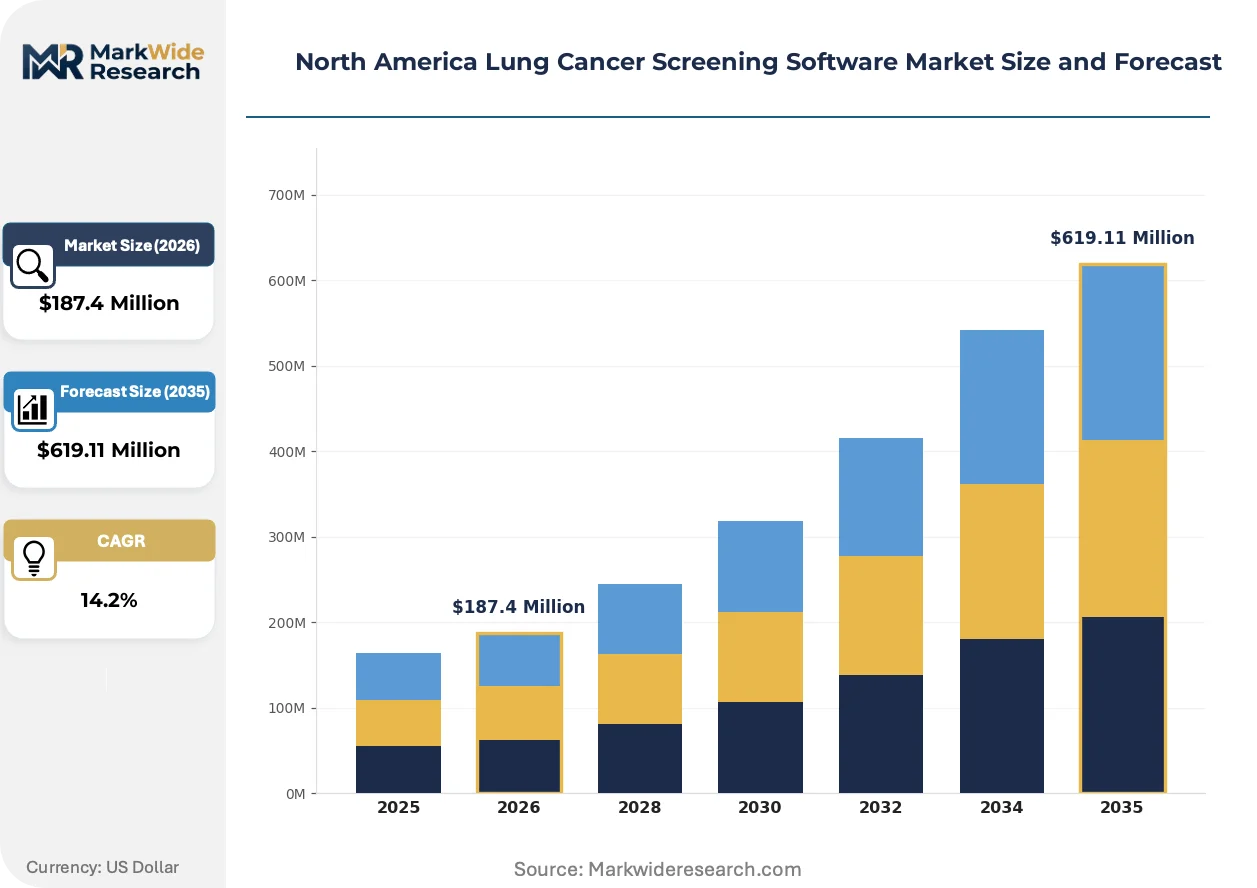
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Software, Integrated Solutions, Cloud-based Platforms, Mobile Applications End User: Hospitals, Diagnostic Centers, Oncology Clinics, Research Institutions Deployment Model: On-premises, SaaS, Hybrid, Web-based Technology: AI-driven Tools, Imaging Solutions, Data Analytics, Patient Management Systems |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips N.V., Nuance Communications, Inc., PenRad Technologies Inc., Medtronic, FUJIFILM Holdings Corporation, Volpara Health Limited, Thynk Health, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Lung Cancer Screening Software Market Evolving Landscape
Volumetric analysis algorithms are displacing diameter-based nodule measurement as the clinical standard, compressing interpretation time while elevating software sophistication requirements across radiology departments.
Deep learning-based malignancy risk calculators are consolidating radiologist decision support around single-vendor platforms that unify detection, quantification, and patient tracking. Academic medical centers in the Northeast and West Coast are adopting these integrated stacks fastest, while community hospitals lag by eighteen to twenty-four months. This consolidation is compressing standalone nodule detection vendors into acquisition targets or niche positioning.
FDA draft guidance on predetermined change control plans for machine learning-enabled devices is altering software development roadmaps. Vendors must now architect update mechanisms that preserve validation evidence across model iterations. Cloud-native platforms with modular algorithm containers are responding most aggressively, while legacy on-premise installations face retrofitting costs.
Subscription-based licensing is displacing perpetual software purchases across mid-sized diagnostic centers. Buyers prefer operational expenditure treatment and embedded professional services over capital allocation for depreciating assets. This shift is most visible in Texas and Florida imaging chains, where private equity ownership favors predictable quarterly software costs aligned with volume-based revenue models.
North America Lung Cancer Screening Software Market Segmentation
Vendor selection in lung cancer screening software hinges on how procurement authority concentrates within integrated delivery networks. Understanding segment boundaries clarifies where enterprise contracts consolidate versus where point solutions retain viability.
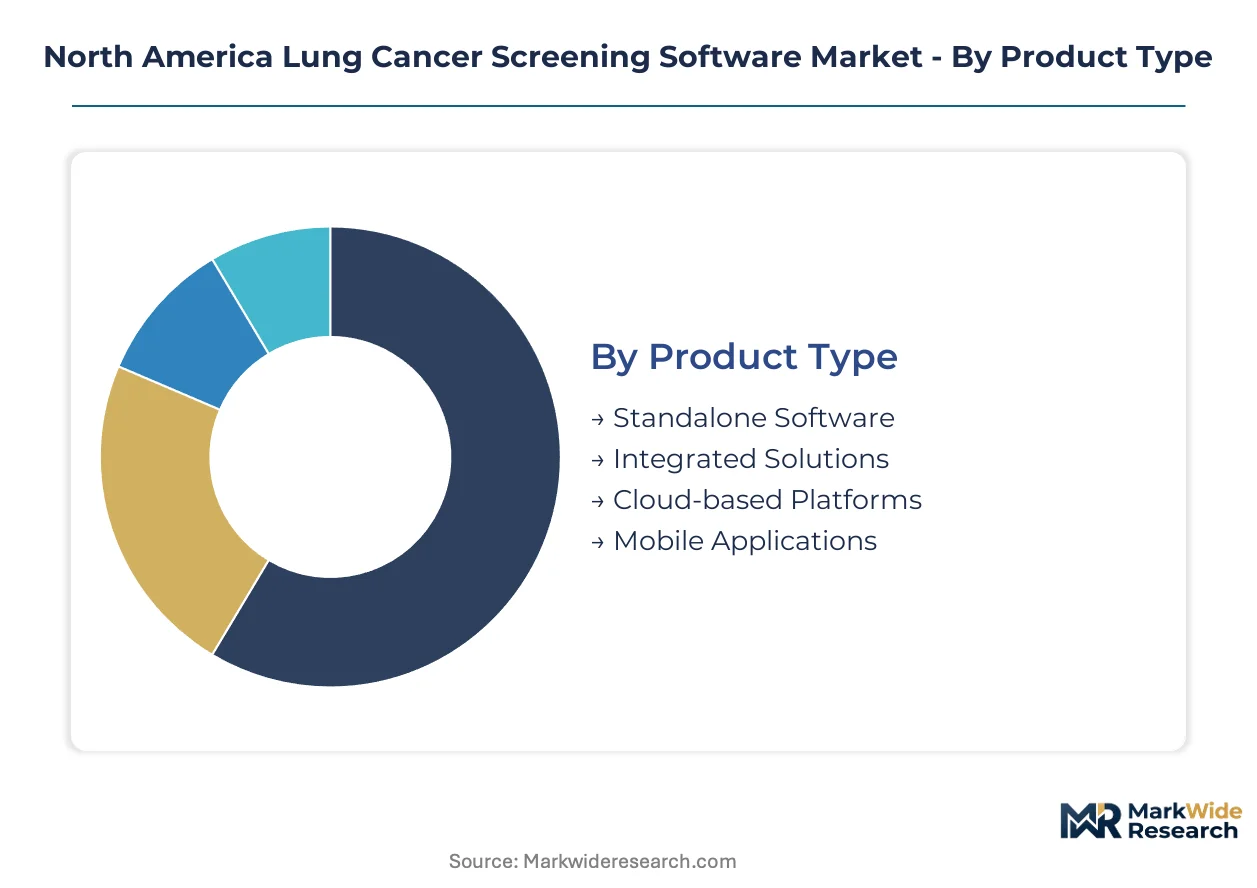
Product Type:
Capital allocation preferences across Midwest and Southeast IDNs determine which product architectures secure multi-site deployments.
- Integrated Solutions:These platforms unify imaging analytics, patient tracking, and billing compliance within single-vendor environments. US academic medical centers in the Northeast and West Coast adopt these stacks fastest, compressing standalone vendors into acquisition targets.
- Cloud-based Platforms:Scalable infrastructure without capital intensity attracts mid-sized diagnostic centers in Texas and Florida imaging chains. Private equity ownership in these markets favors operational expenditure treatment and predictable quarterly costs aligned with volume-based revenue models.
- Standalone Software:Nodule detection algorithms without patient management integration serve community hospitals with legacy PACS investments.
- Mobile Applications:Remote radiologist access tools address on-call coverage gaps in rural health systems across the Mountain West.
Integrated Solutions lead on scale; Cloud-based Platforms lead on momentum.
End User:
Reimbursement pathway complexity shapes software procurement authority across care settings.
- Hospitals:CMS reimbursement for low-dose CT screening flows through hospital outpatient departments, concentrating software budgets in institutions with established Lung-RADS compliance infrastructure.
- Diagnostic Centers:Independent imaging facilities in Georgia and North Carolina pursue scalable platforms as Medicaid expansion decisions alter addressable screening populations.
- Oncology Clinics:Nodule surveillance coordination requires interoperability with medical oncology workflows and tumor board documentation.
- Research Institutions:Clinical trial data collection demands drive adoption of platforms with automated volumetric tracking and longitudinal patient registries.
Hospitals dominate procurement volume; Diagnostic Centers show the steepest expansion trajectory.
Deployment Model:
HIPAA compliance architecture and cross-state patient cohort management constrain cloud migration pace.
- SaaS:Subscription licensing aligns with private equity-owned imaging chains seeking operational expenditure treatment. FDA draft guidance on predetermined change control plans favors cloud-native platforms with modular algorithm containers.
- On-premises:Legacy installations face retrofitting costs as adaptive AI governance evolves, though they persist in health systems with dedicated compliance infrastructure.
- Hybrid:Split architectures accommodate nodule detection in cloud while retaining patient identifiers on local servers.
- Web-based:Browser-accessible tools without full cloud backend serve teleradiology networks with distributed reading pools.
SaaS captures the fastest share gains; On-premises retains the largest installed base.
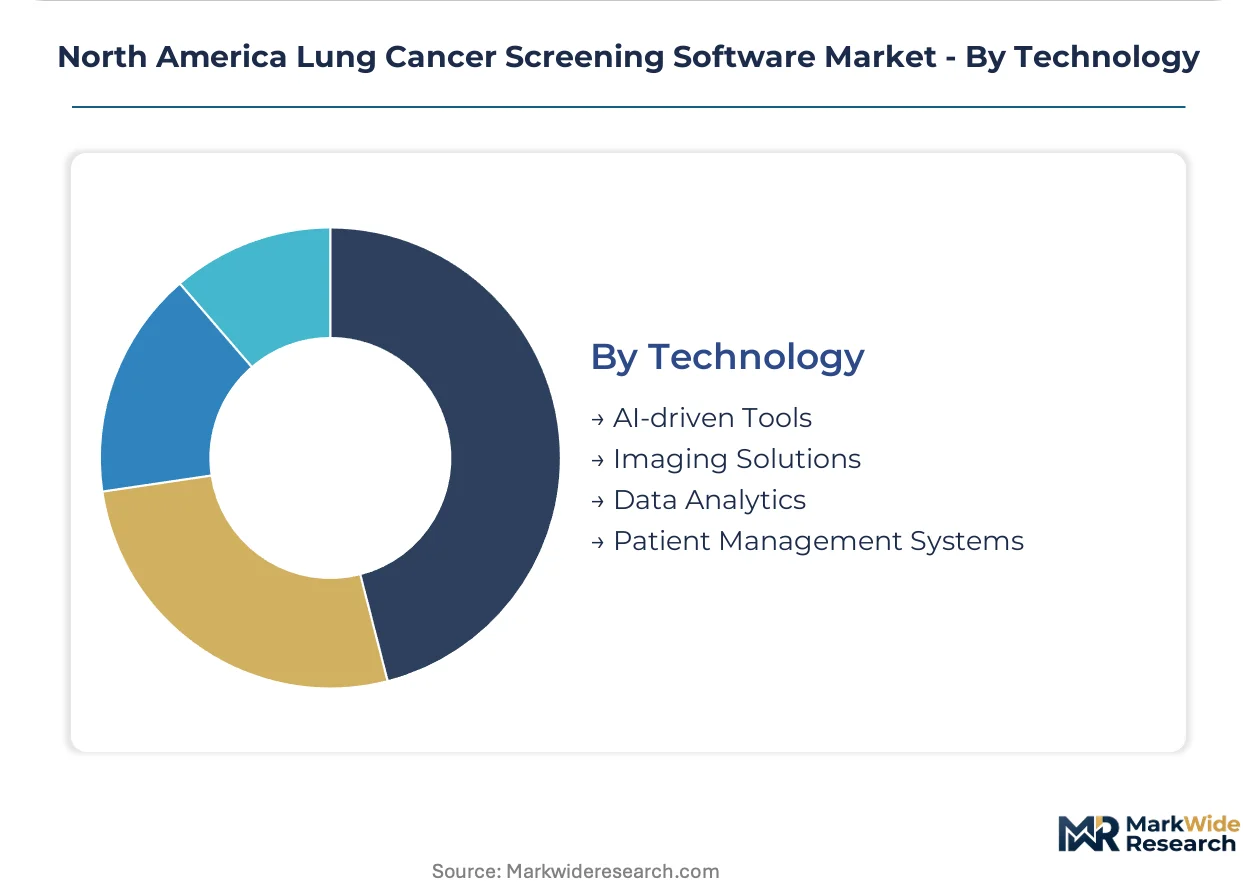
Technology:
FDA 510(k) clearance velocity stratifies competitive position across algorithmic sophistication tiers.
- AI-driven Tools:Machine learning-based nodule detection and malignancy risk stratification accelerate hospital procurement. FDA clearances for volumetric analysis algorithms displace diameter-based measurement as the clinical standard.
- Imaging Solutions:PACS-integrated visualization and Lung-RADS reporting automation reduce radiologist interpretation time.
- Data Analytics:Population-level screening program metrics support quality reporting and reimbursement compliance.
- Patient Management Systems:Automated surveillance scheduling and recall protocols address multi-year follow-up adherence gaps.
AI-driven Tools command premium positioning; Imaging Solutions provide the foundational layer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiologist density and academic medical center concentration anchor software procurement patterns across North American sub-regions. Hospital system consolidation and Medicaid expansion decisions reshape addressable screening populations state by state.
Midwest
Integrated delivery networks across Illinois, Ohio, and Michigan standardize lung cancer screening protocols across multi-hospital systems. CMS reimbursement for low-dose CT screening flows through hospital outpatient departments with established Lung-RADS compliance infrastructure. Chicago and Cleveland anchor enterprise software procurement demand as health systems consolidate radiology purchasing authority.
Southeast
State-level Medicaid expansion decisions in Georgia, North Carolina, and Alabama alter addressable screening populations for safety-net hospital systems. The US Preventive Services Task Force expanded eligibility criteria directly enlarges patient pools in non-expansion states. Atlanta and Charlotte diagnostic centers pursue scalable cloud-based platforms as reimbursement pathways shift.
Northeast
Academic medical centers in Massachusetts and New York adopt integrated AI-driven screening stacks fastest, compressing standalone vendors into acquisition targets. HIPAA compliance frameworks impose data architecture constraints on cross-state patient cohort management. Boston and New York City health systems lead volumetric analysis algorithm adoption eighteen to twenty-four months ahead of community hospitals.
Southwest
Texas and Florida imaging chains with private equity ownership favor subscription-based licensing and predictable quarterly software costs. Cloud-native platforms with modular algorithm containers respond aggressively to FDA draft guidance on predetermined change control plans. Houston and Miami diagnostic centers represent underpenetrated distribution channels beyond academic medical centers.
Canada
Provincial health system procurement concentrates software budgets within single-payer infrastructure. Health Canada regulates algorithmic screening tools under medical device pathways parallel to FDA Class II frameworks. Toronto and Vancouver academic hospitals pilot AI-driven risk stratification tools within publicly funded screening programs.
North America Lung Cancer Screening Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the lung cancer screening software landscape. Imaging hardware manufacturers leverage deep PACS integration to sustain captive demand for analytics stacks. Three archetypes dominate: integrated imaging vendors, voice-AI documentation specialists, and cloud-native algorithm platforms. M&A activity compresses standalone nodule detection vendors into acquisition targets, while strategic partnerships between software firms and hospital systems accelerate enterprise contract velocity.
Among diversified imaging conglomerates, GE Healthcare, Siemens Healthineers, and Koninklijke Philips N.V. occupy positions anchored by cross-platform compatibility with existing CT fleets. These manufacturers exemplify the hardware-integrated archetype, using imaging equipment relationships to secure software procurement decisions. Nuance Communications sits within the voice-AI specialization tier, embedding natural language processing into radiology speech recognition infrastructure. The competitive dynamic pits scale-driven enterprise contracts against agile cloud deployments targeting mid-sized diagnostic centers.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Nuance Communications, Inc. |
| PenRad Technologies Inc. |
| Medtronic |
| FUJIFILM Holdings Corporation |
| Volpara Health Limited |
| Thynk Health |
| Others |
Value Network & Pricing Analysis
FDA 510(k) clearance stratification between enterprise-integrated stacks and standalone nodule detection modules creates a bifurcation that manifests in both subscription pricing tiers and supply chain sourcing patterns. Premium vendors with pre-cleared AI algorithms command annual SaaS rates three to five times above unvalidated point solutions, while hardware-integrated suppliers leverage captive CT fleet relationships to bundle software at marginal cost.
Pricing Analysis
Capacity additions in cloud-native software development across Texas and Florida imaging chains are reshaping price floors for mid-sized diagnostic centers. Three-tier pricing structure across enterprise, standard, and modular levels dominates the market, with FDA clearance tier and PACS integration depth serving as primary price differentiation drivers. Pricing pressure stems from private equity-owned imaging chains demanding operational expenditure treatment with embedded professional services. Community hospitals with legacy infrastructure investments show highest price sensitivity, while academic medical centers prioritize algorithmic sophistication over cost.
Supply Chain Analysis
AI/ML engineering talent scarcity in Boston and San Francisco clusters constrains algorithm development velocity for emerging vendors. Software development concentrates in the United States, with cloud infrastructure provisioning distributed across domestic and Canadian data centers. The supply chain draws from specialized medical imaging hardware manufacturers, HIPAA-compliant cloud service providers, and radiology workflow integration specialists. Single-source vulnerability in FDA regulatory consulting creates bottlenecks for 510(k) pathway navigation. Distribution runs through direct enterprise sales teams for hospital systems and value-added resellers for independent diagnostic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in lung cancer screening software rests on the shift from perpetual licensing to recurring SaaS revenue, amplified by cloud infrastructure cost efficiencies that improve gross margins at scale.
For Market Incumbents: Deepen PACS integration moats by embedding patient management and billing compliance within single-vendor environments to counter standalone AI detection entrants. Prioritize certification investment in FDA predetermined change control plans to preserve validation evidence across model updates without full 510(k) resubmission. Channel control through exclusive radiology speech recognition partnerships with Nuance Communications represents a critical defensive lever against voice-AI documentation convergence. For New Entrants and Emerging Players: Capture community diagnostic center demand in Texas and Florida where private equity ownership favors predictable quarterly software costs aligned with volume-based revenue models. The most penetrable segment lies in mid-sized independent imaging centers seeking scalable cloud-based platforms without capital intensity. A targeted go-to-market angle emphasizes modular algorithm containers that respond aggressively to evolving FDA guidance on adaptive AI governance. For Investors and Strategic Acquirers: Consolidation pressure builds where standalone nodule detection vendors lack capital reserves for multi-site clinical validation trials required under FDA Class II pathways. Long-term viability favors platforms with integrated imaging analytics, patient tracking, and Lung-RADS compliance automation rather than point solutions. The acquisition target archetype comprises cloud-native algorithm platforms with modular architecture and established hospital system pilot contracts. Watch FDA draft guidance finalization on continuously learning AI systems as the key inflection indicator for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Reduces time-to-revenue for AI-driven nodule detection algorithms entering hospital procurement cycles. |
| Hospital System Partnership | Secures multi-site enterprise contracts across Midwest IDNs consolidating radiology purchasing authority. |
| Cloud-Native Platform Migration | Enables modular algorithm containers that preserve validation evidence under FDA predetermined change control plans. |
| Voice-AI Workflow Integration | Embeds automated reporting into existing radiology speech recognition infrastructure for nodule follow-up. |
| Reimbursement Strategy Alignment | Positions software procurement budgets to capture CMS Medicare coverage expansion for low-dose CT screening. |
Research Methodology
Bottom-up hospital and diagnostic center procurement modeling reconciled against top-down AI algorithm clearance tracking forms the analytical core of this study. Primary interviews with radiology department chairs, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and FDA regulatory affairs specialists combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement determinations, hospital procurement databases, and GPO contract repositories. Triangulation between demand-side budget allocation patterns and supply-side product development pipelines ensures methodological rigor.
Input-output matrices map software deployment volumes against reimbursement pathway expansion, segmentation dimensions modeled across deployment model, health system size, PACS integration complexity, and regional adoption pattern. CAGRs derive from algorithmic diffusion curves fitted to historical FDA clearance velocity and hospital procurement cycle timing. Industry-specific forecast inputs include US Preventive Services Task Force eligibility criteria expansion trajectories and state-level Medicaid expansion decisions.
FDA guidance revisions, CMS reimbursement determinations, and radiologist workforce availability shifts are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding AI algorithm adoption curves and IDN consolidation velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Solutions
Global Enzyme-Linked Immunosorbent Assay (ELISA) Market
Diagnostic Solutions
Mobile Applications for Melanoma Detection Market
Diagnostic Solutions
Protein Assays Market
Diagnostic Solutions
Middle East and Africa Lung Cancer Screening Software Market
Diagnostic Solutions
Protein Detection and Quantification Market
Diagnostic Solutions
Global Lung Cancer Screening Software Market
Diagnostic Solutions
Near-Patient Molecular Solutions Market
Diagnostic Solutions
Europe Lung Cancer Screening Software Market
Diagnostic Solutions
Oral Screening Systems Market
Diagnostic Solutions
Total Bile Acid Assay Kit Market
Diagnostic Solutions
Global Ioversol Market
Diagnostic Solutions
Multiple Reaction Monitoring Assay Market
Diagnostic Solutions
Hepatitis C Diagnosis and Treatment Market
Diagnostic Solutions
Global Upper Gastrointestinal (GI) Series Market