
 Total Bile Acid Assay Kit Market | 2026-2036
Total Bile Acid Assay Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Total Bile Acid Assay Kit Market Insights
Modular kit configurations is shifting buyer preference toward flexible assay formats that combine reagents, standards, and calibrators in adjustable volumes. Thermo Fisher Scientific leverages its distribution scale to dominate bulk procurement channels for high-throughput clinical laboratories. Diazyme Laboratories specializes in enzyme-based detection chemistries that anchor its position in reference lab networks. Abcam competes through antibody specificity claims that differentiate its immunoassay portfolios.
Total bile acid assay kits are in vitro diagnostic systems that quantify serum or plasma bile acid concentrations through enzymatic cycling or antibody binding reactions, typically achieving detection thresholds in the micromolar range for clinical hepatology and metabolic research applications. Colorimetric assays sustain the largest installed base due to compatibility with standard spectrophotometers, while fluorescent assays represent the fastest-expanding segment as multiplexing protocols gain traction in drug metabolism studies. ELISA kits occupy mature positions in research institutions where protocol standardization outweighs throughput demands.
FDA 510(k) clearance pathways and EMA in vitro diagnostic regulation frameworks govern market access for clinical-grade kits, compelling manufacturers to document analytical sensitivity and lot-to-lot consistency. ISO 13485 quality management standards shape supplier qualification for pharmaceutical companies integrating assay kits into compound screening workflows. Stakeholders must monitor evolving harmonization between FDA and EMA performance criteria as dual-market registration becomes essential for kit vendors serving multinational diagnostic networks.
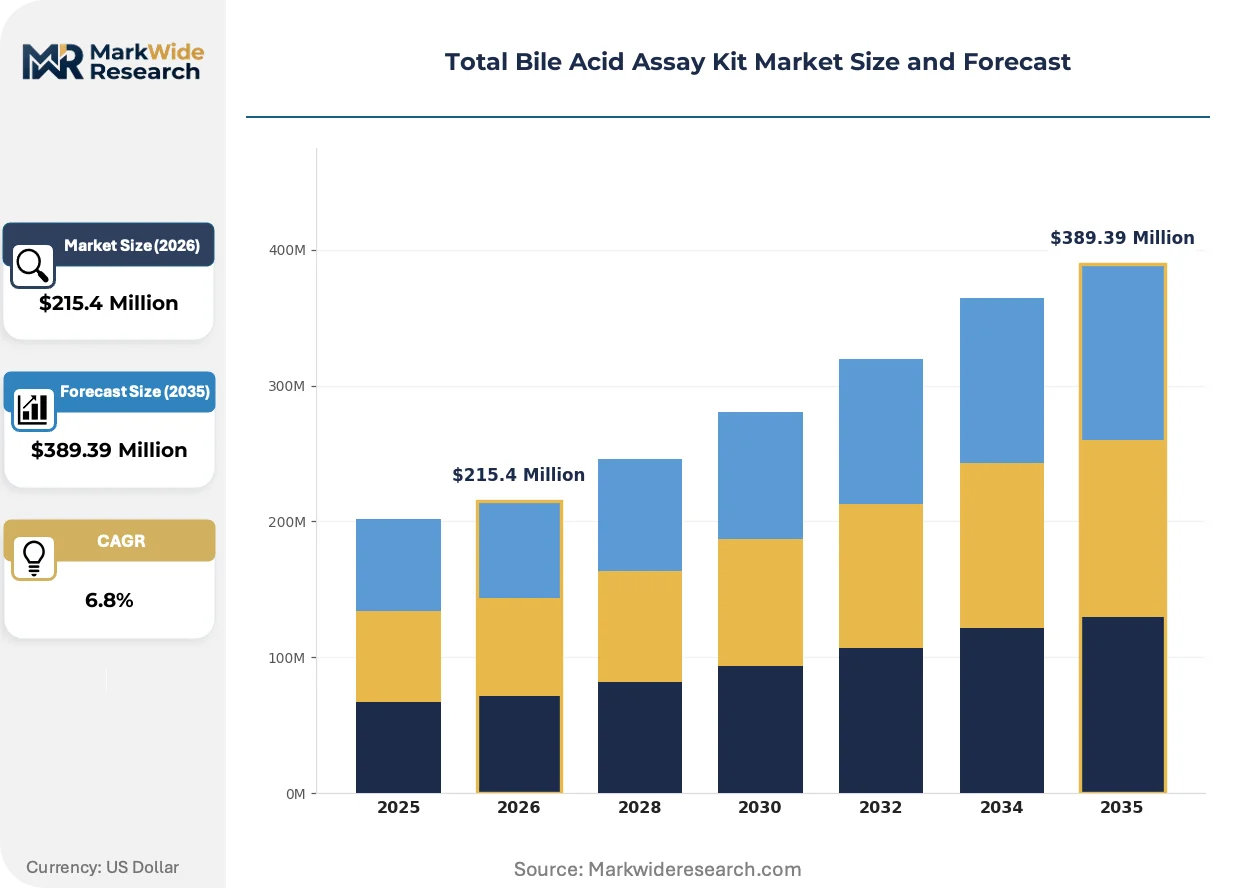
Market Dynamics
Modular kit configurations are compressing procurement cycles as clinical laboratories demand flexible reagent volumes that align with fluctuating test volumes rather than fixed-format bulk purchases. This structural shift toward adjustable assay formats is redistributing margin capture from manufacturers to distributors capable of configuring custom kit bundles.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for enzymatic cycling assays are shortening product launch intervals for manufacturers targeting high-throughput clinical laboratories in the United States.
- Hepatology research funding concentration:Sustained National Institutes of Health allocations for non-alcoholic fatty liver disease studies are expanding reference laboratory demand for quantitative bile acid panels.
- Multiplexing protocol adoption:Fluorescent detection chemistries are penetrating drug metabolism research as pharmaceutical companies integrate bile acid quantification into compound screening workflows.
Market Restraints
- Enzyme raw material concentration:Supply of high-purity 3α-hydroxysteroid dehydrogenase concentrates among three specialty biochemical suppliers in Germany creates input cost volatility and lot-to-lot consistency risks.
- ISO 13485 certification burden:Small and mid-size kit vendors face extended timeline and documentation requirements for quality management system compliance, compressing their addressable market to research-grade segments.
- Colorimetric assay substitution:Standard spectrophotometer compatibility sustains installed base loyalty to established detection formats, slowing fluorescent assay penetration in budget-constrained hospital laboratories.
Strategic Opportunities
- India reference laboratory expansion:CDSCO regulatory harmonization with IVD performance standards is opening clinical-grade kit registration pathways as private diagnostic chains scale hepatology testing menus.
- Point-of-care format development:Miniaturized enzymatic cycling platforms are addressing urgent care and physician office laboratory segments currently served by centralized reference testing.
- EMA in vitro diagnostic regulation alignment:Common technical documentation requirements across EU member states are reducing dual-market registration friction for manufacturers pursuing United States and European commercialization.
Industry Challenges
- Analytical validation specialist scarcity:Shortage of personnel experienced in enzymatic cycling method development and cross-reactivity assessment is extending kit development timelines for emerging vendors.
- Lot-to-lot consistency maintenance:Antibody and enzyme batch variation management requires substantial quality control infrastructure investment, particularly for immunoassay kit producers scaling manufacturing volume.
- Legacy ELISA protocol integration:Research institutions with entrenched standardized workflows resist format migration despite superior fluorescent assay performance characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Total Bile Acid Assay Kit Market |
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $389.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA Kits, Fluorescent Assays, Colorimetric Assays, Immunoassays End User: Clinical Laboratories, Research Institutions, Pharmaceutical Companies, Diagnostic Centers Technology: Centrifugation, Chromatography, Spectrophotometry, Microplate Reader Packaging Type: Boxed Kits, Bulk Packaging, Custom Solutions, Sample Packs |
| Companies Covered | Cell Biolabs, Diazyme Laboratories, Abcam, BioVision, Crystal Chem, BioAssay Systems, Sigma-Aldrich Corporation, Thermo Fisher Scientific, Assay Genie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Total Bile Acid Assay Kit Market Trends and Innovations
Detection chemistry diversification is fragmenting competitive positioning as fluorescent and luminescent formats challenge the colorimetric installed base. Regulatory documentation harmonization and procurement model evolution are simultaneously reshaping vendor qualification requirements and buyer-seller relationships.
Fluorescent multiplexing platforms are expanding into pharmaceutical compound screening operations as contract research organizations adopt bile acid panels alongside cytochrome P450 metabolism assays. Drug discovery units at major pharmaceutical companies are retrofitting existing plate readers for fluorescent detection, compressing capital requirements for assay expansion. This technology convergence is expanding into academic core facilities where shared instrumentation access models reduce individual laboratory equipment burden.
EMA in vitro diagnostic regulation frameworks are tightening analytical performance documentation requirements for clinical-grade kit registration. Manufacturers must now submit extended stability data and interference studies prior to CE marking authorization, extending product development timelines by twelve to eighteen months. European reference laboratories are responding by consolidating vendor qualification around established suppliers with proven regulatory track records, compressing market access for emerging entrants.
Consolidated procurement through group purchasing organizations is concentrating buyer power among United States health system networks. Independent clinical laboratories are losing negotiating leverage as integrated delivery networks centralize reagent purchasing decisions, forcing kit vendors to restructure distributor relationships and volume discount frameworks. This concentration is most visible in the southeastern United States where hospital system mergers have reduced the number of independent purchasing entities by over one-third since 2020.
Total Bile Acid Assay Kit Market Segmentation
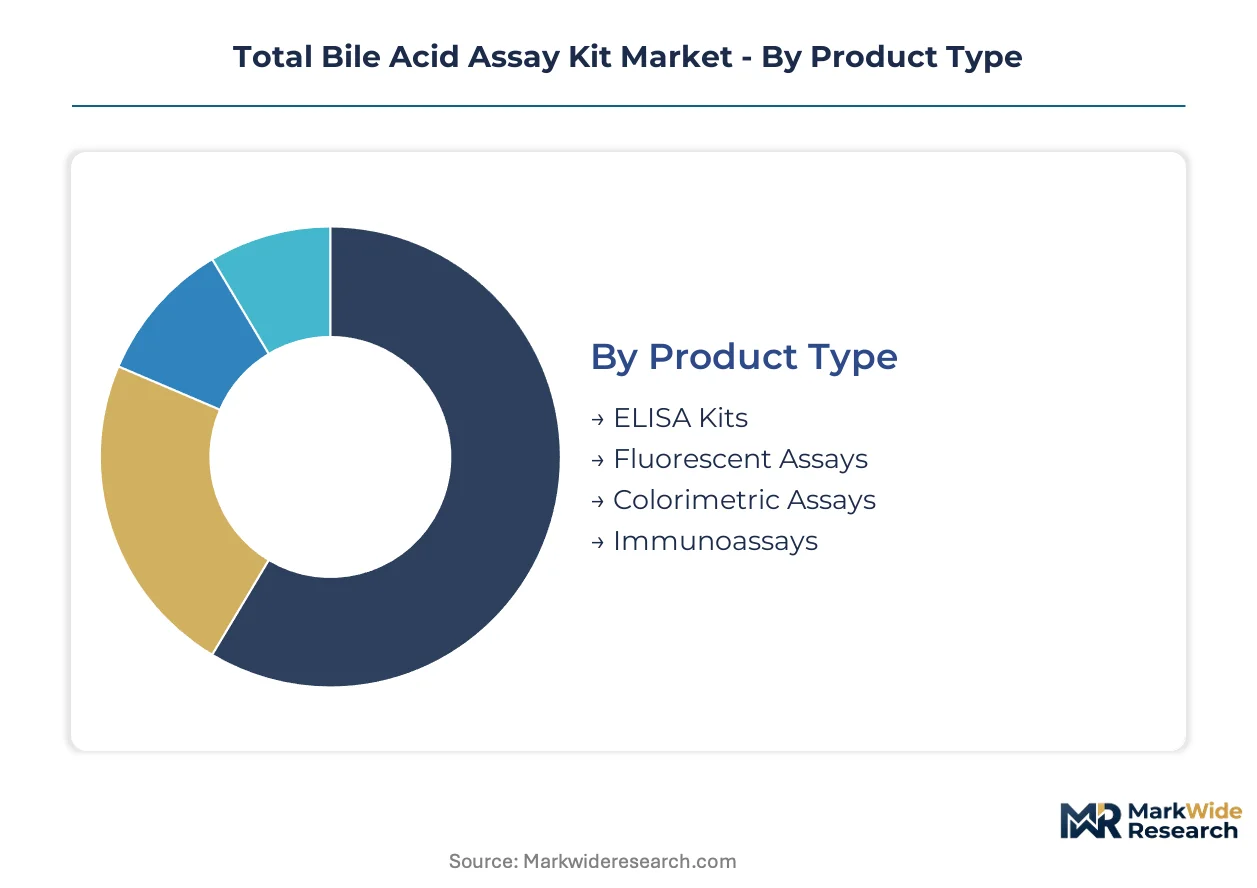
Segmentation in the Total Bile Acid Assay Kit Market reveals divergent technology preferences between high-throughput clinical operations and specialized research environments. Product format decisions cascade through procurement cycles, regulatory pathways, and end-user workflow integration requirements.
Product Type:
Volume concentration favors standardized formats with broad instrument compatibility, while premium positioning accrues to specialized detection chemistries with superior sensitivity specifications.
- Colorimetric Assays:These enzymatic cycling systems leverage 3α-hydroxysteroid dehydrogenase reactions with visible wavelength detection, achieving micromolar sensitivity thresholds using standard spectrophotometers. Hospital laboratories in the United States and Germany sustain demand due to capital equipment compatibility and established SOP integration, though enzyme raw material concentration among German suppliers creates lot-to-lot consistency risks.
- Fluorescent Assays:Multiplexing-capable detection platforms enable simultaneous bile acid quantification alongside cytochrome P450 metabolism markers in compound screening workflows. Pharmaceutical companies in the northeastern United States and contract research organizations are retrofitting existing plate readers, compressing capital barriers for assay adoption in drug discovery operations.
- ELISA Kits:Antibody-based sandwich formats with standardized protocol documentation dominate academic core facilities where method validation burden outweighs throughput optimization.
- Immunoassays:Chemiluminescent and electrochemiluminescent variants serve reference laboratory networks requiring extended dynamic range for hepatology panels.
Today's leader: Colorimetric Assays. Tomorrow's challenger: Fluorescent Assays.
End User:
Customer type determines regulatory burden intensity and procurement decision centralization, with integrated health systems consolidating purchasing power differently than fragmented research buyers.
- Clinical Laboratories:High-throughput reference labs and hospital core facilities drive enzymatic cycling assay volume through automated platform integration. United States health system networks are consolidating reagent procurement through group purchasing organizations, compressing vendor negotiation leverage for independent laboratories.
- Pharmaceutical Companies:Drug metabolism and pharmacokinetic units require multiplexing-compatible formats for compound screening cascades. Fluorescent detection chemistries are penetrating these workflows as bile acid panels integrate with hepatotoxicity assessment protocols.
- Research Institutions:Academic core facilities with shared instrumentation access models favor ELISA standardization over format migration despite performance limitations.
- Diagnostic Centers:Point-of-care and physician office laboratory segments represent emerging demand for miniaturized enzymatic cycling platforms currently underserved by centralized testing models.
Procurement consolidation is accelerating among clinical buyers while research purchasers retain fragmented decision structures.
Technology:
Detection modality selection constrains assay format compatibility and throughput scalability across end-user environments.
- Spectrophotometry:Visible-range absorbance detection sustains the largest installed base through compatibility with colorimetric enzymatic cycling assays and standard laboratory equipment.
- Microplate Reader:Fluorescent and luminescent detection capabilities enable multiplexing protocols in pharmaceutical screening operations and academic core facilities.
- Chromatography:HPLC and LC-MS/MS methods serve reference laboratories requiring structural isomer resolution unavailable through immunoassay formats.
- Centrifugation:Sample preparation automation integrates with upstream detection platforms in high-throughput clinical environments.
Instrument legacy binds colorimetric users while fluorescent platforms capture growth in screening-intensive segments.
Packaging Type:
Procurement model evolution is redistributing margin capture between manufacturers and distributors capable of configuring flexible reagent volumes.
- Boxed Kits:Fixed-format configurations with predetermined reagent volumes serve small and mid-size laboratories with predictable test volumes and limited storage infrastructure.
- Bulk Packaging:High-volume reagent supply agreements support automated platform integration in reference laboratories with dedicated cold chain capacity.
- Custom Solutions:Adjustable assay formats with configurable calibrator and standard concentrations align with fluctuating test menus in multi-specialty diagnostic networks.
- Sample Packs:Low-commitment evaluation units facilitate vendor qualification and protocol validation prior to volume procurement decisions.
Flexible procurement terms are displacing fixed-format purchasing as laboratories prioritize working capital efficiency over unit cost minimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enzymatic cycling assays for bile acid quantification achieved commercial scale in Germany during the 1980s through specialty biochemical suppliers concentrated in the Rhine-Ruhr industrial corridor. Clinical adoption subsequently diffused through reference laboratory networks in the United States and academic research institutions in Japan. Today procurement patterns reflect divergent regulatory pathways and health system consolidation trajectories across major diagnostic markets.
United States
Hospital system networks in the southeastern United States have consolidated purchasing entities by over one-third since 2020, compressing vendor negotiation leverage for independent clinical laboratories. FDA 510(k) pathway streamlining accelerates clearance timelines for enzymatic cycling assays targeting high-throughput reference facilities. The National Institutes of Health sustains hepatology research funding concentration in the Boston-Cambridge corridor and Research Triangle Park.
Germany
Three specialty biochemical suppliers in Germany concentrate supply of high-purity 3α-hydroxysteroid dehydrogenase, creating input cost volatility for colorimetric assay manufacturers. EMA in vitro diagnostic regulation frameworks govern CE marking authorization with extended stability documentation requirements. The Rhine-Ruhr region anchors enzyme raw material production while Heidelberg and Munich host reference laboratory networks driving clinical-grade kit demand.
Japan
Academic core facilities in the Kanto region retain entrenched ELISA protocol standardization despite fluorescent assay performance advantages. PMDA regulatory harmonization with IVD performance standards shapes product registration pathways for clinical-grade kits. The Osaka-Kobe industrial zone concentrates pharmaceutical company drug metabolism units adopting multiplexing bile acid panels.
India
Private diagnostic chains in Maharashtra and Karnataka are scaling hepatology testing menus as CDSCO regulatory harmonization opens clinical-grade kit registration pathways. The country's national pharmaceutical regulator aligns IVD performance standards with international benchmarks, reducing market access friction. Hyderabad and Bengaluru host contract research organizations expanding compound screening operations.
United Kingdom
Research institutions in the Cambridge-Oxford-London triangle maintain fragmented procurement decision structures resistant to format migration from legacy ELISA workflows. MHRA post-Brexit regulatory autonomy creates documentation requirements divergence from EMA frameworks. The London metropolitan area concentrates hospital laboratory networks evaluating miniaturized point-of-care enzymatic cycling platforms.
Total Bile Acid Assay Kit Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory certification intensity and distribution scale dimensions in the Total Bile Acid Assay Kit Market. The vendor base stratifies into three tiers: multinational life science conglomerates with integrated reagent-instrument platforms, mid-size specialty biochemical suppliers with enzyme production capabilities, and research-grade kit assemblers serving academic segments. Dominant competitive moves include strategic partnerships with group purchasing organizations and portfolio diversification into fluorescent detection chemistries.
Among United States-based life science conglomerates, Thermo Fisher Scientific occupies a position exemplifying distribution scale advantages in bulk procurement channels. Diazyme Laboratories represents the specialty biochemical supplier archetype with concentrated enzyme-based detection chemistry expertise. Abcam sits within the research-grade tier, anchoring antibody specificity positioning in immunoassay portfolios. These three entities collectively illustrate the competitive spectrum from high-throughput clinical penetration to academic research standardization.
| Leading Market Players |
|---|
| Cell Biolabs |
| Diazyme Laboratories |
| Abcam |
| BioVision |
| Crystal Chem |
| BioAssay Systems |
| Sigma-Aldrich Corporation |
| Thermo Fisher Scientific |
| Assay Genie |
| Others |
Pricing and Supply Chain Analysis
Fluorescent detection chemistry adoption is compressing per-test cost economics while redistributing margin capture toward distributors with flexible reagent bundling capabilities. This dual shift simultaneously intensifies price competition in colorimetric segments and concentrates supply leverage among enzyme raw material producers in Germany.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared clinical kits from research-grade formats and bulk uncalibrated reagents. Price differentiation hinges on ISO 13485 certification status and automated platform integration depth. Cost compression in economy-tier colorimetric assays is intensifying because hospital laboratories prioritize capital equipment compatibility over sensitivity specifications. Research institutions exhibit highest price sensitivity due to fragmented procurement budgets, while pharmaceutical compound screening units absorb premium pricing for multiplexing-capable fluorescent formats.
Supply Chain Analysis
Direct-to-laboratory channels serve high-throughput reference facilities with dedicated cold chain infrastructure, while distributor-mediated procurement dominates mid-size clinical networks. Enzyme raw material production concentrates in Germany, the United States, and Japan, with 3α-hydroxysteroid dehydrogenase supply anchored in the Rhine-Ruhr corridor. Kit assembly draws from antibody production clusters in Massachusetts and Cambridgeshire. Single-source vulnerability in German enzyme suppliers creates lot-to-lot consistency risks that propagate through colorimetric assay manufacturing. Distribution runs through group purchasing organizations that consolidate negotiating leverage among United States health system networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as hepatology diagnostics shift toward multiplexing-capable fluorescent specifications that demand superior analytical validation documentation. Premium positioning now requires demonstrated lot-to-lot consistency rather than throughput metrics alone.
For Market Incumbents: Hedge against colorimetric format commoditization by securing captive supply of 3α-hydroxysteroid dehydrogenase through backward integration into German enzyme production or long-term offtake agreements. Prioritize fluorescent assay portfolio expansion to capture pharmaceutical screening demand, while defending clinical laboratory relationships through automated platform co-development with major instrument manufacturers. For New Entrants and Emerging Players: Point-of-care miniaturization platforms offer the most penetrable white-space opportunity, as urgent care and physician office laboratory segments remain underserved by centralized reference testing models. CDSCO regulatory harmonization in India creates accessible clinical-grade registration pathways for mid-size vendors lacking FDA 510(k) track records. Pursue contract research organization partnerships as initial reference customers to validate performance claims before health system procurement engagement. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-size specialty biochemical suppliers with enzyme production capabilities but limited distribution scale. Long-term viability across the analysis window favors vendors with dual-market FDA and EMA registration expertise as harmonization reduces compliance friction. Watch EMA in vitro diagnostic regulation implementation timelines as the inflection indicator for European reference laboratory vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Shortened clearance timelines compress product launch intervals for enzymatic cycling assays targeting high-throughput laboratories. |
| Fluorescent Detection Chemistry Expansion | Multiplexing capabilities capture pharmaceutical compound screening demand alongside cytochrome P450 metabolism panels. |
| GPO Partnership Consolidation | Integrated delivery network procurement concentration in the southeastern United States demands restructured distributor relationships. |
| Point-of-Care Format Development | Miniaturized platforms address urgent care segments currently dependent on centralized reference laboratory testing. |
| EMA CE Marking Pathway Investment | Extended stability documentation requirements favor established suppliers with proven regulatory track records. |
Research Methodology
Direct dialogue with hepatology reference laboratory directors, IVD regulatory affairs specialists, pharmaceutical DMPK unit heads, and group purchasing organization contract managers grounded qualitative assessment. Secondary validation drew from FDA 510(k) premarket notification databases, EMA in vitro diagnostic guidance documents, NIH RePORTER funding records, and ISO 13485 certification registries. Bottom-up and top-down triangulation reconciled assay kit shipment data with end-user procurement survey responses.
Bottom-up modeling aggregated segment-level volume assumptions across product type, end user, and technology dimensions, while top-down analysis cross-checked aggregate market scale against macroeconomic healthcare expenditure trends. Segmentation incorporated detection chemistry format, regulatory certification tier, packaging configuration, and regional procurement pattern variations across the projection horizon. CAGR derivation weighted historical adoption curves for fluorescent assays against colorimetric installed base loyalty factors and enzyme raw material supply constraints.
The model holds under stable regulatory harmonization trajectories and sustained hepatology research funding; deviation in CDSCO implementation timelines or German enzyme supplier consolidation would shift geographic growth distribution. Forecasts reflect documented assumptions regarding multiplexing protocol adoption rates and health system merger momentum. Periodic stress-testing of base assumptions against FDA guidance updates and EMA MDR transition progress is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Solutions
Global Lung Cancer Screening Software Market
Diagnostic Solutions
Europe Lung Cancer Screening Software Market
Diagnostic Solutions
Global Ioversol Market
Diagnostic Solutions
Hepatitis C Diagnosis and Treatment Market
Diagnostic Solutions
Oral Screening Systems Market
Diagnostic Solutions
Protein Detection and Quantification Market
Diagnostic Solutions
Global Upper Gastrointestinal (GI) Series Market
Diagnostic Solutions
Protein Assays Market
Diagnostic Solutions
North America Lung Cancer Screening Software Market
Diagnostic Solutions
Near-Patient Molecular Solutions Market
Diagnostic Solutions
Middle East and Africa Lung Cancer Screening Software Market
Diagnostic Solutions
Mobile Applications for Melanoma Detection Market
Diagnostic Solutions
Multiple Reaction Monitoring Assay Market
Diagnostic Solutions
Global Enzyme-Linked Immunosorbent Assay (ELISA) Market