
 Europe Lung Cancer Screening Software Market | 2026-2036
Europe Lung Cancer Screening Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Lung Cancer Screening Software Market Foresight
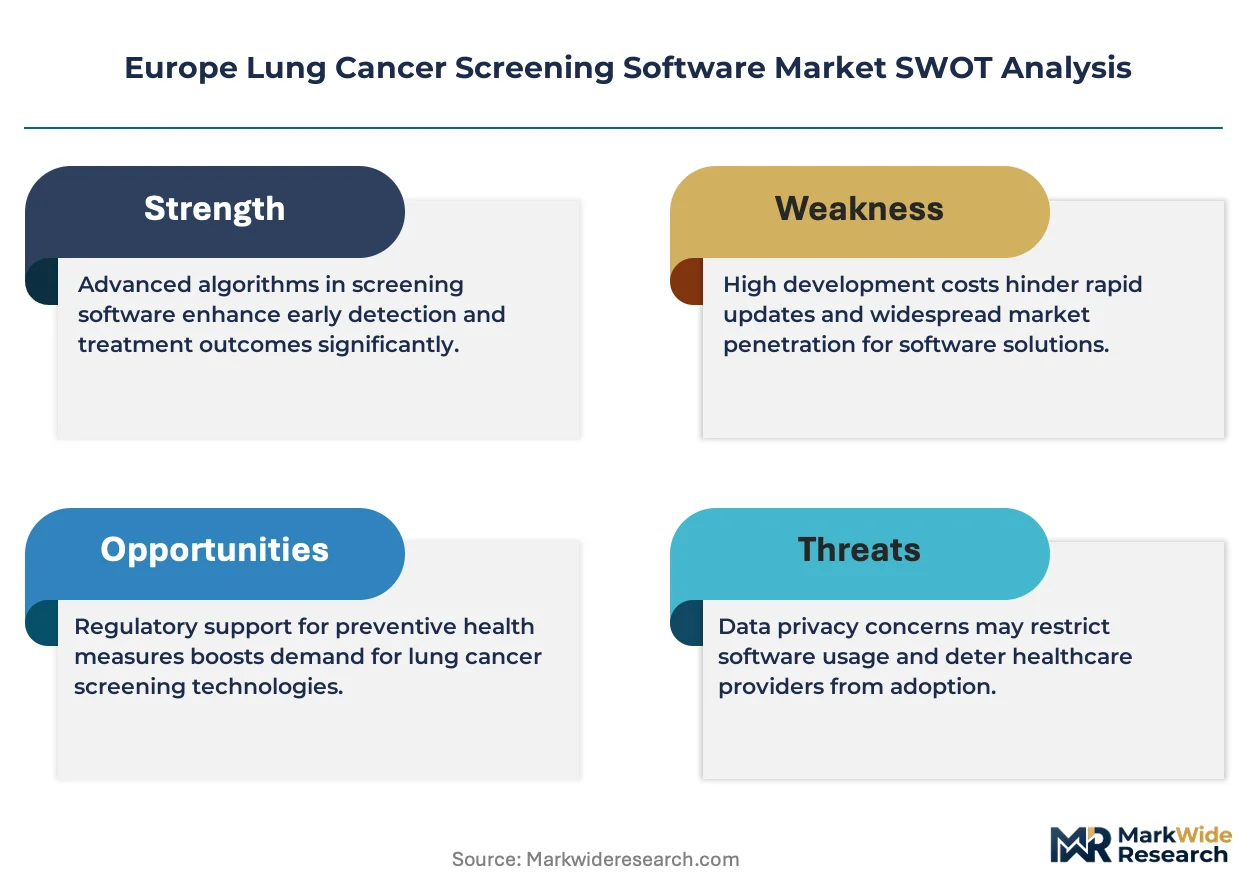
Hospital procurement channels across Europe are tilting toward bundled enterprise contracts that combine imaging hardware with AI screening modules. Siemens Healthineers leverages its installed base of CT systems to anchor software attach rates in German university hospitals. Koninklijke Philips N.V. competes through integrated workflows that link lung nodule tracking to electronic health records. MeVis Medical Solutions AG specializes in quantitative imaging analysis, occupying a niche among research-intensive screening programs.
Europe lung cancer screening software comprises algorithmic platforms that process thoracic CT volumes to detect, classify, and monitor pulmonary nodules, typically operating at slice thickness thresholds of 1.0–1.25 millimeters and integrating DICOM-structured reporting for longitudinal comparison. CT scan software leads revenue contribution due to its centrality in low-dose screening protocols, while predictive analytics platforms represent the fastest-expanding segment as risk stratification models gain reimbursement traction. Cloud-based deployment is capturing share among multi-site hospital networks seeking centralized algorithm updates, though on-premise installations sustain dominance where data residency requirements prevail.
The EU Medical Device Regulation (MDR) and CE marking framework govern software qualification as Class IIa or IIb medical devices, compelling vendors to maintain clinical evidence portfolios for algorithm validity. Germany's Federal Institute for Drugs and Medical Devices (BfArM) and France's National Agency for Food, Environmental and Occupational Health Safety (ANSES) coordinate on early detection program standards that shape procurement specifications. Stakeholders must monitor reimbursement decisions by national health technology assessment bodies, as these will determine whether AI-assisted screening transitions from pilot budgets to sustainable operational funding.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing vendor timelines for clinical validation, forcing lung cancer screening software developers to rebuild evidence portfolios under Class IIa and IIb device classifications before CE marking renewal deadlines.
Growth Catalysts
- Germany's national screening pilots:The Federal Institute for Drugs and Medical Devices (BfArM) is certifying reference sites that create procurement templates for French and Dutch hospital networks seeking proven AI-assisted nodule detection workflows.
- Cloud deployment architectures:Multi-site hospital networks across Scandinavia are adopting centralized algorithm update models that reduce per-site IT overhead while maintaining DICOM-structured reporting compatibility.
- CE marking pathway clarity:The MDR's software-as-medical-device framework provides predictable qualification routes that de-risk R&D investment for vendors targeting European hospital procurement channels.
Market Restraints
- Clinical evidence generation costs:Retrospective validation studies using annotated CT datasets from 1,000-plus patient cohorts impose six-figure euro expenditures that exclude early-stage software developers from MDR compliance.
- Radiologist workflow integration friction:PACS interoperability gaps between legacy imaging archives and AI screening modules create implementation delays averaging 8-14 months in university hospital settings.
- Reimbursement uncertainty:Health technology assessment bodies in France, Italy, and Spain have not issued definitive AI-assisted screening tariff codes, leaving procurement budgets dependent on pilot program allocations.
Strategic Opportunities
- Poland and Eastern European expansion:Underpenetrated screening infrastructure in Warsaw and Prague clinical centers creates first-mover positioning for vendors with CE-marked tools and Polish-language interfaces.
- Risk stratification integration:Convergence of volumetric nodule analysis with smoking history biomarkers enables predictive analytics platforms to access reimbursement codes currently reserved for diagnostic CT staging.
- EU AI Act alignment:High-risk AI system documentation requirements create competitive moats for vendors with pre-existing MDR clinical evidence portfolios that satisfy overlapping conformity assessment obligations.
Industry Challenges
- Dual-qualified regulatory talent scarcity:Software engineers with simultaneous expertise in ISO 13485 quality management and deep learning model architecture command premium compensation that strains mid-cap vendor burn rates.
- Legacy PACS integration complexity:Hospital IT departments face 12-18 month project timelines to establish HL7 FHIR connectivity between AI screening modules and electronic health record systems from incumbent vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Lung Cancer Screening Software Market |
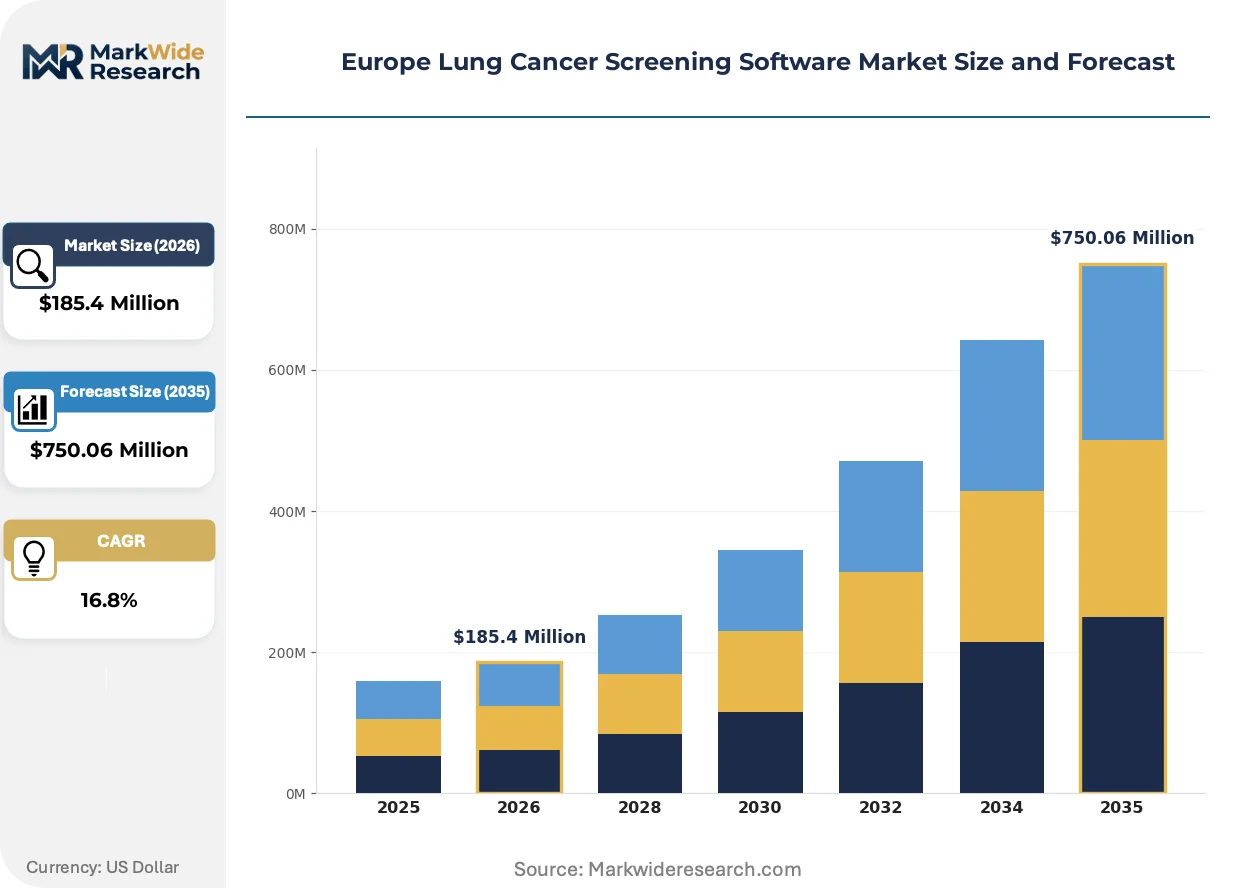
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $750.06 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Scan Software, MRI Solutions, Data Integration Tools, Predictive Analytics Platforms Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Solutions End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Clinics Application: Early Detection, Patient Management, Treatment Planning, Data Reporting |
| Companies Covered | Siemens Healthineers AG, Koninklijke Philips N.V, GE Healthcare, PenRad Technologies Inc., Nuance Communications, Inc., Canon Medical Systems Corporation, FUJIFILM Holdings Corporation, Medtronic, MeVis Medical Solutions AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Lung Cancer Screening Software Market Shifts & Advancements
Algorithmic nodule characterization is displacing threshold-based diameter measurements as the primary decision input in European screening protocols, compressing the radiologist review burden while raising software performance requirements.
Volumetric growth rate analysis using semiautomated segmentation is rendering obsolete the traditional RECIST-inspired linear measurement protocols that dominated early low-dose CT screening programs. German university hospitals in Heidelberg and Munich are deploying these tools in prospective pilot cohorts exceeding 50,000 participants. The shift is compressing false-positive recall rates by eliminating inter-reader measurement variability while extending software validation requirements to longitudinal accuracy benchmarks.
The EU AI Act's high-risk system classification for medical diagnostic software is mandating conformity assessments that parallel MDR clinical evidence requirements, creating overlapping compliance burdens for vendors seeking CE marking. France's National Agency for Food, Environmental and Occupational Health Safety (ANSES) is coordinating with BfArM on harmonized documentation standards that reduce redundant submissions. Screening software developers are responding by consolidating regulatory affairs functions and pre-submission engagement with notified bodies.
Hospital procurement committees are unbundling AI screening modules from bundled CT hardware contracts, creating standalone software evaluation processes that prioritize algorithmic performance over equipment brand loyalty. French public hospital groups in the Île-de-France region are piloting multi-vendor bake-offs that separate imaging acquisition from interpretation workflow. The pattern is most visible in Germany, where university hospital procurement offices now maintain dedicated AI validation labs for independent performance benchmarking.
Europe Lung Cancer Screening Software Market Segmentation
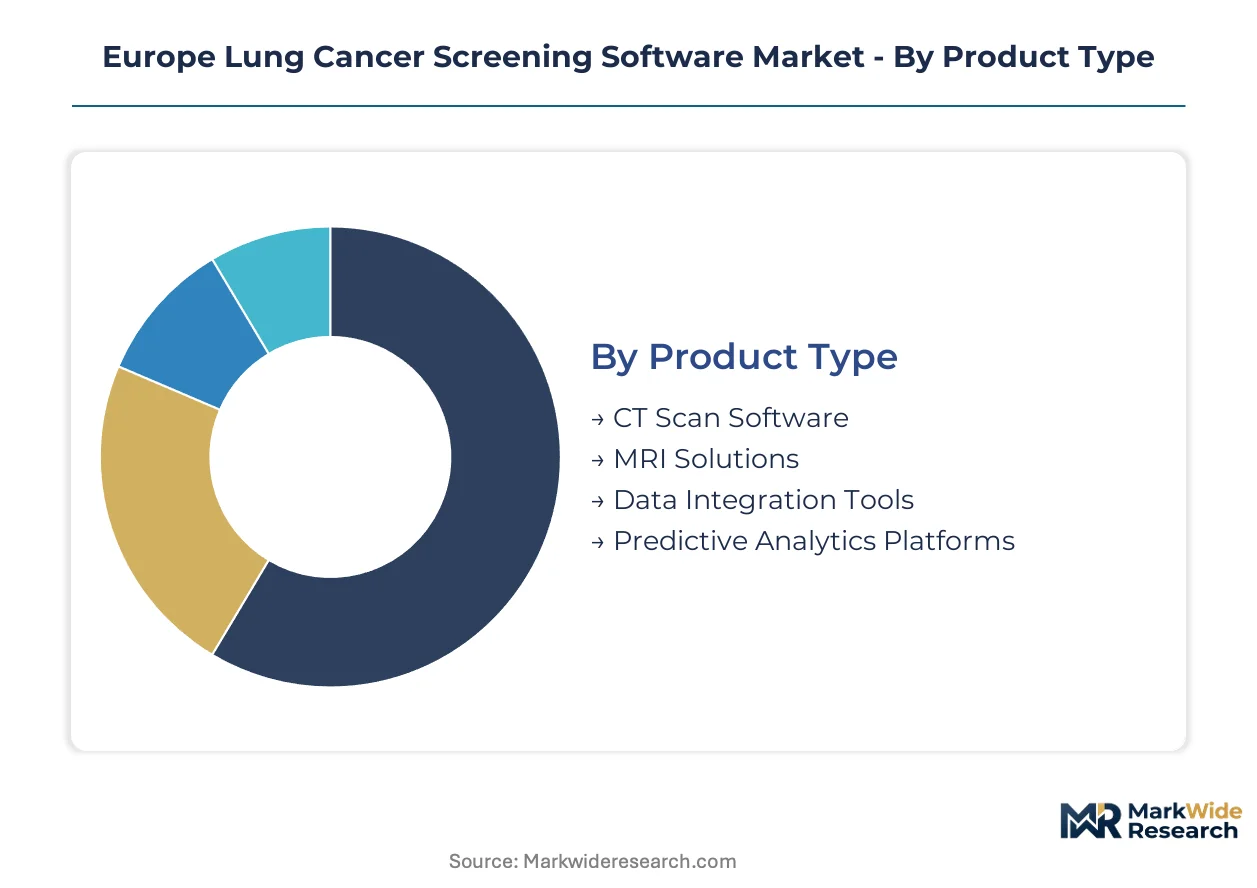
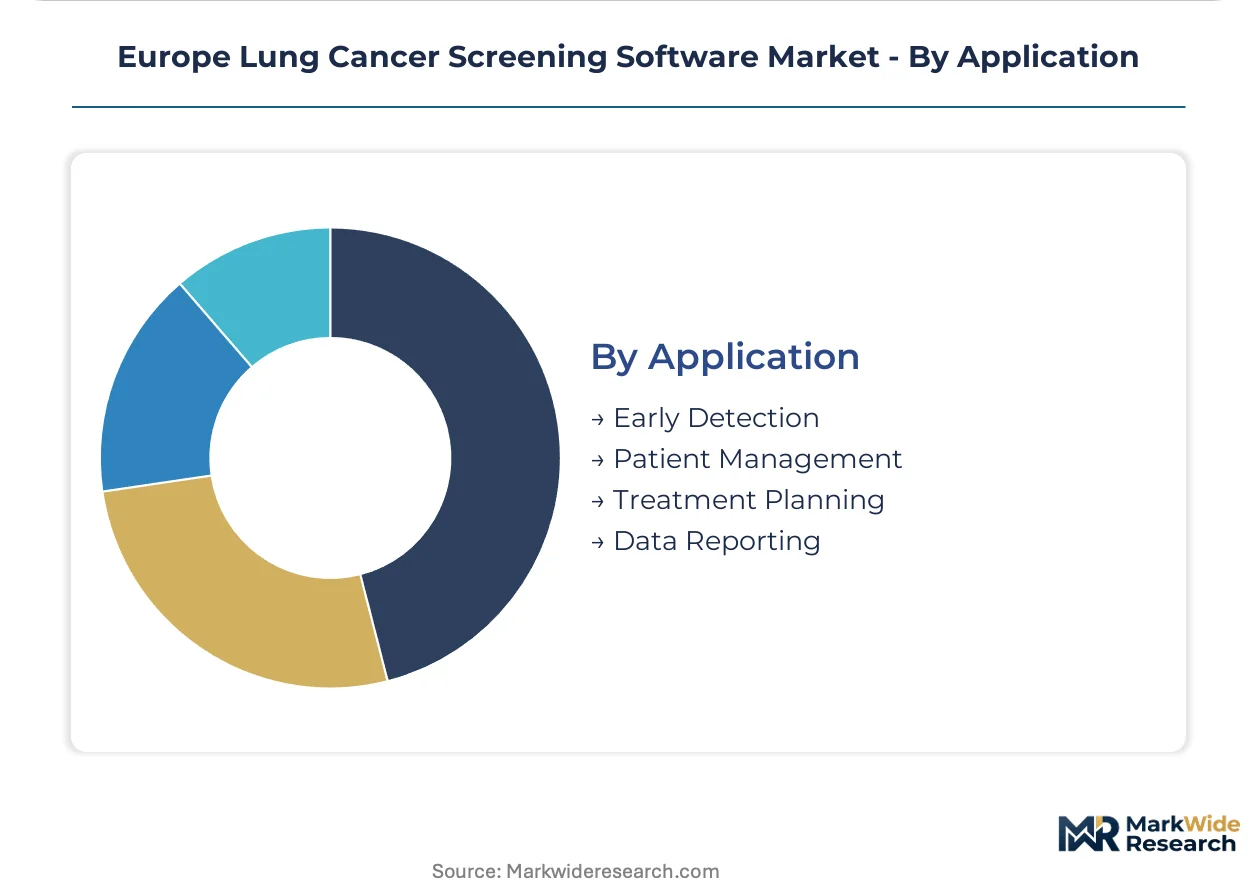
Segmentation in Europe lung cancer screening software reveals how procurement priorities diverge across hospital IT architectures, clinical workflows, and reimbursement pathways. Each dimension shapes vendor R&D allocation and go-to-market positioning differently.
Product Type:
Cost tier stratification separates high-investment algorithmic platforms from infrastructure-light integration tools, with procurement budgets clustering around validated clinical decision support.
- CT Scan Software:Processes thoracic CT volumes at 1.0–1.25 millimeter slice thickness thresholds with DICOM-structured reporting for longitudinal nodule comparison. German university hospitals in Heidelberg and Munich anchor demand through national screening pilot procurement, driven by BfArM certification requirements for low-dose protocols.
- Predictive Analytics Platforms:Deploy risk stratification models combining volumetric growth rates with smoking history biomarkers. French hospital groups in Île-de-France are piloting standalone evaluation processes for these tools, motivated by reimbursement code expansion for diagnostic staging applications.
- MRI Solutions:Magnetic resonance-based nodule characterization serves contraindicated patient cohorts where radiation exposure must be minimized.
- Data Integration Tools:HL7 FHIR connectivity modules bridge AI screening outputs to electronic health record systems from incumbent vendors.
CT scan software holds installed capacity. Predictive analytics platforms are rotating up the share rankings.
Deployment:
Volume concentration across hospital network footprints determines whether centralized cloud architectures or localized on-premise installations dominate procurement specifications.
- On-Premise:Local server installations maintaining full data residency within hospital firewalls, mandatory under GDPR Article 9 health data provisions and national data localization statutes. German and French public hospitals sustain dominance here, constrained by cybersecurity audit requirements for cross-border patient data.
- Cloud-Based:Centralized algorithm update models reducing per-site IT overhead through subscription licensing. Scandinavian multi-site networks in Sweden and Denmark are expanding fastest, attracted by DICOM-structured reporting compatibility without hardware refresh cycles.
- Hybrid:Split architectures processing sensitive patient data on-premise while pushing anonymized training volumes to cloud model refinement pipelines.
- Mobile Solutions:Tablet-based radiologist review interfaces for point-of-care nodule confirmation in outpatient settings.
On-premise deployment holds installed capacity. Cloud-based solutions are rotating up the share rankings.
End User:
Customer type fragmentation reflects divergent IT sophistication, with procurement authority concentrating in integrated delivery networks versus distributed clinic purchasing.
- Hospitals:Enterprise contract negotiations bundling AI screening modules with CT hardware procurement, governed by dedicated AI validation labs for independent performance benchmarking. German university hospital procurement offices lead adoption, pressured by MDR Class IIa and IIb device classification deadlines.
- Diagnostic Centers:Standalone imaging facilities prioritizing workflow efficiency metrics and rapid report turnaround times.
- Research Institutions:Academic medical centers requiring quantitative imaging analysis for longitudinal cohort studies exceeding 50,000 participants.
- Outpatient Clinics:Primary care gatekeepers with limited PACS infrastructure seeking lightweight screening decision support.
Hospitals hold installed capacity. Diagnostic centers are rotating up the share rankings.
Application:
Application maturity tracks reimbursement pathway development, with operational funding availability determining whether tools remain pilot-funded or achieve sustainable procurement.
- Early Detection:Algorithmic nodule detection and classification at initial screening encounter, displacing threshold-based diameter measurements with volumetric growth rate analysis. German BfArM reference sites drive demand, constrained by radiologist workflow integration friction averaging 8-14 months in university settings.
- Patient Management:Longitudinal tracking protocols automating recall scheduling and interval CT timing based on risk scores.
- Treatment Planning:Integration with surgical navigation systems and radiation oncology contouring workflows.
- Data Reporting:Structured output generation for national screening registries and health technology assessment submissions.
Early detection holds installed capacity. Patient management applications are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The BfArM anchors procurement standards across Europe through its reference site certification program for lung cancer screening pilots. German university hospitals in Heidelberg and Munich generate workflow templates that Dutch and French networks adopt. National reimbursement decisions by health technology assessment bodies will determine whether AI-assisted screening transitions from pilot budgets to sustainable operational funding.
Germany
Heidelberg and Munich university hospitals drive procurement volumes through BfArM-certified reference sites exceeding 50,000 participant cohorts. The MDR Class IIa and IIb device classifications compress vendor timelines for clinical validation before CE marking renewal deadlines. Siemens Healthineers leverages its installed CT base to anchor software attach rates across Baden-Württemberg and Bavaria.
France
Île-de-France public hospital groups pilot multi-vendor bake-offs separating imaging acquisition from AI interpretation workflows. ANSES coordinates with BfArM on harmonized documentation standards under the EU AI Act's high-risk system classification. Philips competes through integrated workflows linking nodule tracking to electronic health records in Parisian screening centers.
Netherlands
Dutch hospital networks seek proven AI-assisted nodule detection workflows from German reference sites for cross-border adoption. The country's national health technology assessment body evaluates AI-assisted screening tariff codes for sustainable procurement. University Medical Center Utrecht maintains dedicated AI validation labs for independent performance benchmarking.
Sweden
Scandinavian multi-site networks adopt centralized cloud algorithm update models reducing per-site IT overhead. GDPR Article 9 health data provisions constrain deployment architectures despite DICOM-structured reporting compatibility. Karolinska Institutet in Stockholm anchors research-intensive screening programs requiring quantitative imaging analysis.
Poland
Warsaw clinical centers present first-mover positioning for vendors with CE-marked tools and Polish-language interfaces. Underpenetrated screening infrastructure creates expansion opportunities as Eastern European markets mature. The country's national pharmaceutical regulator aligns device qualification requirements with MDR frameworks.
Europe Lung Cancer Screening Software Market Competitive Landscape
Imaging equipment incumbents and specialized software developers split the market between bundled hardware-software contracts and standalone algorithmic platforms. Siemens Healthineers and Philips anchor the integrated systems tier through CT installed base leverage, while MeVis Medical Solutions occupies the quantitative analysis niche. Market structure tilts toward enterprise procurement committees unbundling AI modules from equipment contracts. Dominant competitive moves include M&A for regulatory talent acquisition and strategic partnerships for PACS interoperability.
Among diversified health technology conglomerates, Siemens Healthineers AG and Koninklijke Philips N.V. exemplify the integrated imaging-to-AI workflow archetype, anchoring enterprise contract negotiations across German and French hospital networks. MeVis Medical Solutions AG represents the specialized quantitative imaging tier, occupying research-intensive screening program positioning. These three entities collectively illustrate the competitive spectrum from hardware-anchored bundling to standalone algorithmic specialization.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| Koninklijke Philips N.V |
| GE Healthcare |
| PenRad Technologies Inc. |
| Nuance Communications, Inc. |
| Canon Medical Systems Corporation |
| FUJIFILM Holdings Corporation |
| Medtronic |
| MeVis Medical Solutions AG |
| Others |
Supply & Pricing Matrix
Single-source dependency on MDR-notified body capacity for CE marking renewal compresses vendor timelines and widens pricing spreads between validated incumbents and unqualified challengers. This regulatory chokepoint shapes procurement tiering across German and French hospital networks while forcing supply chain consolidation around quality-assured component sourcing.
Pricing Analysis
The customization-premium spread separates configured-to-order algorithmic platforms from standard CT-integrated modules, with German university hospitals paying substantial premiums for BfArM-validated nodule detection workflows. Pricing stratifies across premium, standard, and economy tiers based on CE marking tier and algorithmic performance benchmarking. Cost compression in the standard tier intensifies as cloud deployment models reduce per-site IT overhead. Diagnostic centers exhibit highest price sensitivity, while research-intensive screening programs prioritize performance over acquisition cost.
Supply Chain Analysis
Tariff exposure between component suppliers in Taiwan and assembly operations in Germany dominates supply chain risk planning for AI accelerator hardware. Software development draws from engineering talent pools in Germany, the Netherlands, and Poland, with model training infrastructure concentrated in Scandinavian cloud regions. Single-source vulnerability in GPU compute supply creates procurement bottlenecks for volumetric analysis platforms. Distribution runs through direct enterprise sales to hospital procurement committees and channel partnerships with imaging equipment vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of dual-qualified regulatory engineers with simultaneous ISO 13485 expertise and deep learning architecture skills constrains vendor scaling velocity. This talent gap shapes competitive positioning more than capital access or algorithmic performance alone.
For Market Incumbents: Entrench market position through backward integration into PACS interoperability middleware, eliminating the 12-18 month integration delays that plague third-party AI modules. Acquire regulatory affairs talent pools in Heidelberg and Munich to compress MDR validation timelines before CE marking renewal deadlines. Priority lever rests on securing exclusive hospital system partnerships that lock out standalone algorithmic competitors. For New Entrants and Emerging Players: Pursue white-space positioning in Polish and Czech clinical centers where CE-marked tools with localized interfaces face minimal incumbent saturation. Target diagnostic centers in Warsaw and Prague with lightweight cloud deployments that bypass the enterprise procurement complexity of German university hospitals. Go-to-market angle emphasizes rapid PACS integration through API-first architectures versus legacy HL7 FHIR project timelines. For Investors and Strategic Acquirers: The market sits at a regulatory-consolidation phase that favors acquirers with pre-existing MDR clinical evidence portfolios. Long-term viability hinges on sustainable reimbursement pathway development across French, Italian, and Spanish health technology assessment frameworks. Acquisition target archetype includes mid-cap software developers with validated nodule detection algorithms and incomplete European commercial infrastructure. Signal to watch is definitive AI-assisted screening tariff code issuance by national reimbursement bodies.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Class IIa and IIb device classifications compress vendor validation timelines before renewal deadlines. |
| Hospital System Partnership | Bundled enterprise contracts with German university hospitals anchor software attach rates across Baden-Württemberg. |
| Software Companion Development | HL7 FHIR connectivity modules bridge AI screening outputs to electronic health record systems from incumbent vendors. |
| Reimbursement Strategy | Health technology assessment body decisions in France and Italy determine sustainable operational funding transitions. |
| Geographic Expansion | Polish-language interfaces and CE-marked tools capture first-mover positioning in Warsaw clinical centers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, hospital procurement databases, and GPO contract disclosures. Interviews with radiology department heads, biomedical engineers, hospital purchasing committee members, and regulatory affairs leads at notified bodies inform qualitative assessments. Secondary validation draws from BfArM certification records, ANSES documentation standards, EU MDR guidance documents, and national health technology assessment publications. Bottom-up modeling of vendor shipments triangulates against top-down expenditure estimates from hospital IT budget allocations.
Forecast inputs incorporate deployment model adoption curves, reimbursement pathway development timelines, and radiologist workflow integration friction coefficients across the analysis window. Segmentation dimensions include product type, deployment architecture, end-user facility category, and application maturity. CAGRs derive from algorithmic performance benchmarking trajectories and cloud infrastructure cost decline curves. Industry-specific inputs capture MDR compliance cost escalation and EU AI Act conformity assessment overlap effects.
Sensitivities concentrate around reimbursement code issuance delays, MDR notified body capacity constraints, and legacy PACS interoperability resolution timelines. Forecasts reflect assumptions regarding pilot program budget sustainability and cross-border adoption velocity from German reference sites. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Solutions
Mobile Applications for Melanoma Detection Market
Diagnostic Solutions
Middle East and Africa Lung Cancer Screening Software Market
Diagnostic Solutions
Total Bile Acid Assay Kit Market
Diagnostic Solutions
Protein Assays Market
Diagnostic Solutions
Global Ioversol Market
Diagnostic Solutions
Near-Patient Molecular Solutions Market
Diagnostic Solutions
Oral Screening Systems Market
Diagnostic Solutions
Multiple Reaction Monitoring Assay Market
Diagnostic Solutions
Global Enzyme-Linked Immunosorbent Assay (ELISA) Market
Diagnostic Solutions
Hepatitis C Diagnosis and Treatment Market
Diagnostic Solutions
Global Lung Cancer Screening Software Market
Diagnostic Solutions
Global Upper Gastrointestinal (GI) Series Market
Diagnostic Solutions
Protein Detection and Quantification Market
Diagnostic Solutions
North America Lung Cancer Screening Software Market